
 MEMS Microdisplay Market | 2026-2036
MEMS Microdisplay Market Size, Share, and Industry Trends Forecast 2026-2036
MEMS Microdisplay Market Foresight
Software-defined brightness calibration and subscription-based color-profile management is repositioning how OEMs monetize MEMS microdisplay modules beyond hardware shipments. Sony Semiconductor Solutions leverages captive CMOS foundry capacity to sustain wafer-level integration advantages. Himax Technologies anchors its position through dedicated timing controller and driver IC co-design. Texas Instruments competes with mature DLP MEMS mirror arrays that dominate high-lumen projector channels.
A MEMS microdisplay is a compact electro-mechanical light-modulation device fabricated on silicon substrates, typically measuring under 25 millimeters diagonally with pixel pitches below 10 micrometers, engineered to project or directly emit images for near-eye and pico-projection systems. Micro OLED segments currently command premium pricing in military pilot visors and medical imaging headsets where luminance uniformity requirements are stringent. Digital Light Processing maintains volume leadership in portable projector applications, though MicroLED is displacing incumbent technologies in AR waveguide engines due to superior luminous efficiency. LCoS occupies a defensible niche in structured-light 3D sensing modules where cost sensitivity favors reflective liquid-crystal architectures.
The US FDA governs optical display performance in diagnostic and surgical visualization systems, while the FCC regulates electromagnetic emissions from wireless-connected AR headsets employing MEMS microdisplays. China's MIIT enforces GB standards for display energy consumption and eye-safety luminance thresholds that constrain module design parameters. REACH compliance in Europe restricts hazardous substances in semiconductor packaging materials, directly affecting foundry material selection. Stakeholders must track how divergent photobiological safety standards across FDA, ECHA, and MIIT jurisdictions will fragment certification pathways and reshape supplier qualification timelines.
Market Dynamics
Defense procurement of head-mounted AR training systems is pulling wafer-level MEMS capacity toward military-grade luminance specifications, compressing consumer headset supply timelines and forcing foundry allocation trade-offs between pilot visor and gaming headset customers.
Growth Catalysts
- EU F-Gas Regulation:Tightening fluorinated gas controls for display manufacturing equipment is accelerating domestic substitution investments in China and South Korea, creating captive supply chains for MEMS-based near-eye modules.
- Medical imaging headsets:Surgical visualization systems requiring stringent luminance uniformity are expanding procurement volumes for Micro OLED segments in diagnostic applications governed by FDA optical performance standards.
- Silicon photonics integration:Wafer-level bonding of MEMS mirrors with CMOS backplanes is reducing module thickness for AR waveguide engines, enabling lighter form factors in consumer headsets.
Market Restraints
- Fluorinated gas input volatility:Etching chemistries dependent on regulated perfluorocarbons face supply uncertainty under REACH and F-Gas frameworks, elevating foundry operating costs.
- Wafer concentration risk:Captive CMOS foundry capacity at Sony Semiconductor Solutions and TSMC concentrates advanced backplane supply in East Asian facilities, exposing procurement to geopolitical friction.
- MicroLED substitution pressure:Superior luminous efficiency in gallium nitride emitters is displacing incumbent DLP mirror arrays in premium AR waveguide engines, threatening volume leadership in high-brightness segments.
Strategic Opportunities
- India PLI scheme:Domestic panel assembly incentives under the Production Linked Incentive program are attracting MEMS module packaging investments for export-oriented consumer electronics manufacturing.
- Structured-light 3D sensing:Cost-sensitive industrial automation deployments are expanding addressable volume for LCoS architectures in factory-floor depth cameras.
- Software-defined calibration:Subscription-based color-profile management is creating recurring revenue streams beyond hardware shipments, repositioning OEM monetization models.
Industry Challenges
- Photobiological safety certification fragmentation:Divergent luminance threshold standards across FDA, ECHA, and MIIT jurisdictions are extending module qualification timelines by 6-12 months for multi-region launches.
- Wafer-level integration capex intensity:Bonding equipment for CMOS-MEMS heterogenous integration requires $40-60 million per fab line, constraining mid-tier foundry participation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | MEMS Microdisplay Market |
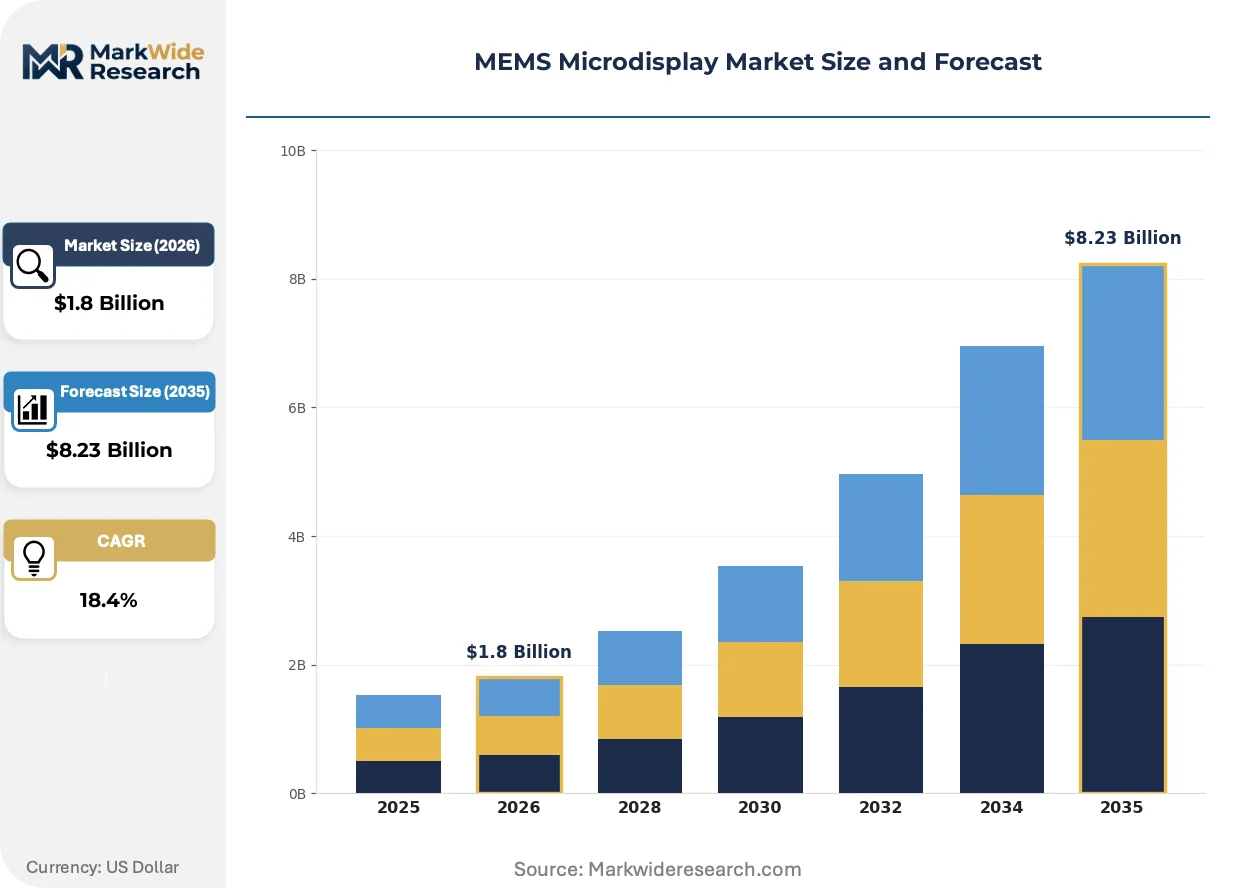
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $8.23 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
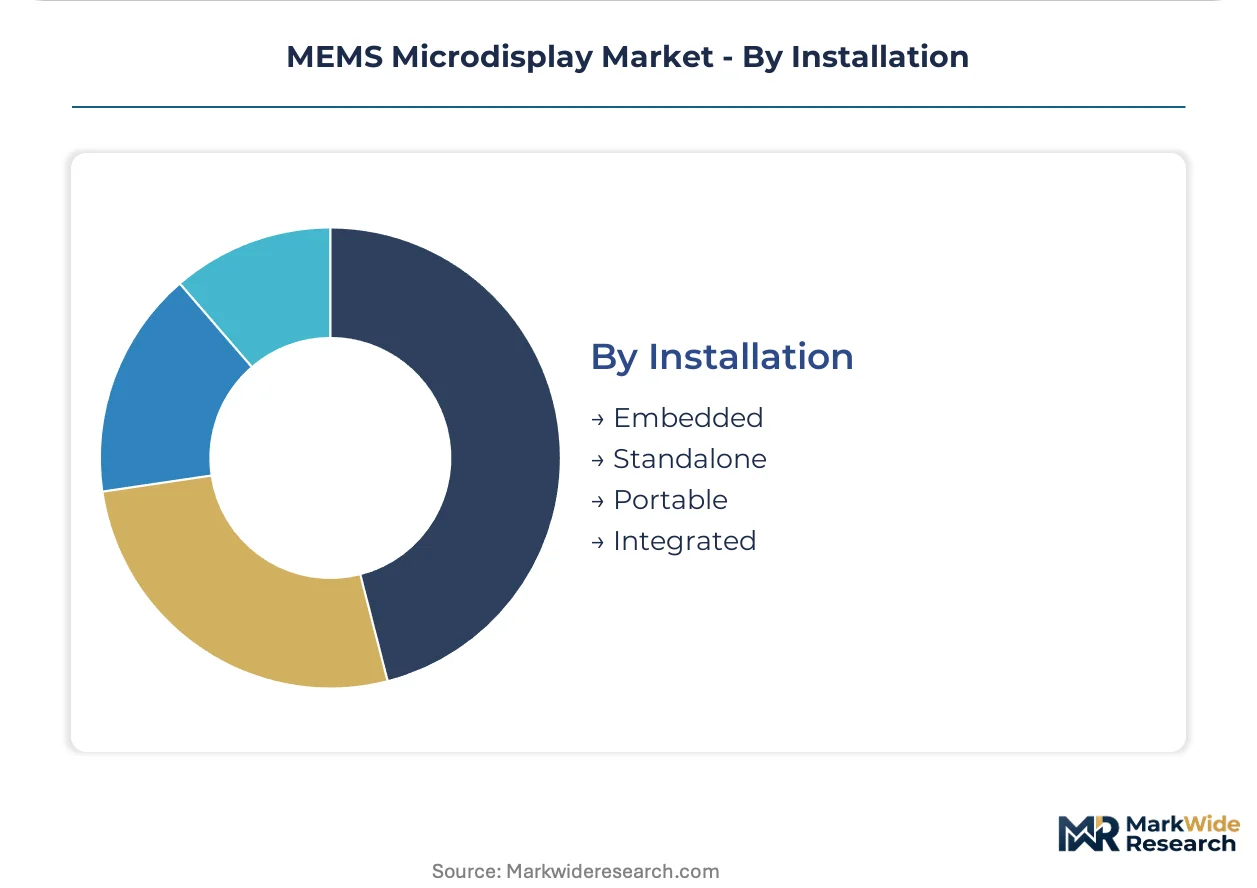
| Segmentation | Product Type: Micro OLED, LCoS, Digital Light Processing, MicroLED End User: Consumer Electronics, Defense, Automotive, Healthcare Technology: Display Technology, Projection Technology, Augmented Reality, Virtual Reality Installation: Embedded, Standalone, Portable, Integrated |
| Companies Covered | Sony Semiconductor Solutions, Kopin Corporation, Himax Technologies, MicroVision, Texas Instruments, Jade Bird Display, eMagin Corporation, Syndiant, Jasper Display Corp, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
MEMS Microdisplay Market Shifts & Advancements
Wafer-level integration architectures and software-defined display calibration are compressing traditional hardware-centric value capture, while regulatory divergence is fragmenting certification pathways across major demand centers.
Monolithic silicon photonics is expanding into MEMS microdisplay backplanes, enabling direct optical I/O between the light-modulation array and waveguide couplers. Defense contractors in the United States are qualifying these integrated engines for pilot helmet-mounted cueing systems. The technology is expanding into previously inaccessible form-factor constraints, compressing module thickness below 3 millimeters.
REACH compliance in Europe is restricting hazardous substances in semiconductor packaging materials, directly affecting foundry material selection for lead-free solder and mold compounds. Display module assemblers serving EU medical device OEMs are reformulating bill-of-materials to maintain CE marking eligibility. Micro OLED segments bound for surgical visualization systems face the most stringent substance documentation requirements.
Buyer concentration among Chinese domestic panel makers is forcing Western MEMS foundries to establish localized technical support and faster qualification cycles. Procurement teams at BOE and CSOT are demanding 48-hour failure analysis turnaround for production line stoppages. This behavioral shift is most visible in Shenzhen and Hefei display manufacturing clusters, where captive volume commitments now precede foundry capacity allocation.
MEMS Microdisplay Market Segmentation
MEMS microdisplay procurement patterns diverge sharply across end-use verticals, with defense pilot visors demanding military-grade luminance uniformity while consumer headsets prioritize wafer-thin form factors. Foundry allocation trade-offs between these segments directly constrain module availability and qualification timelines.
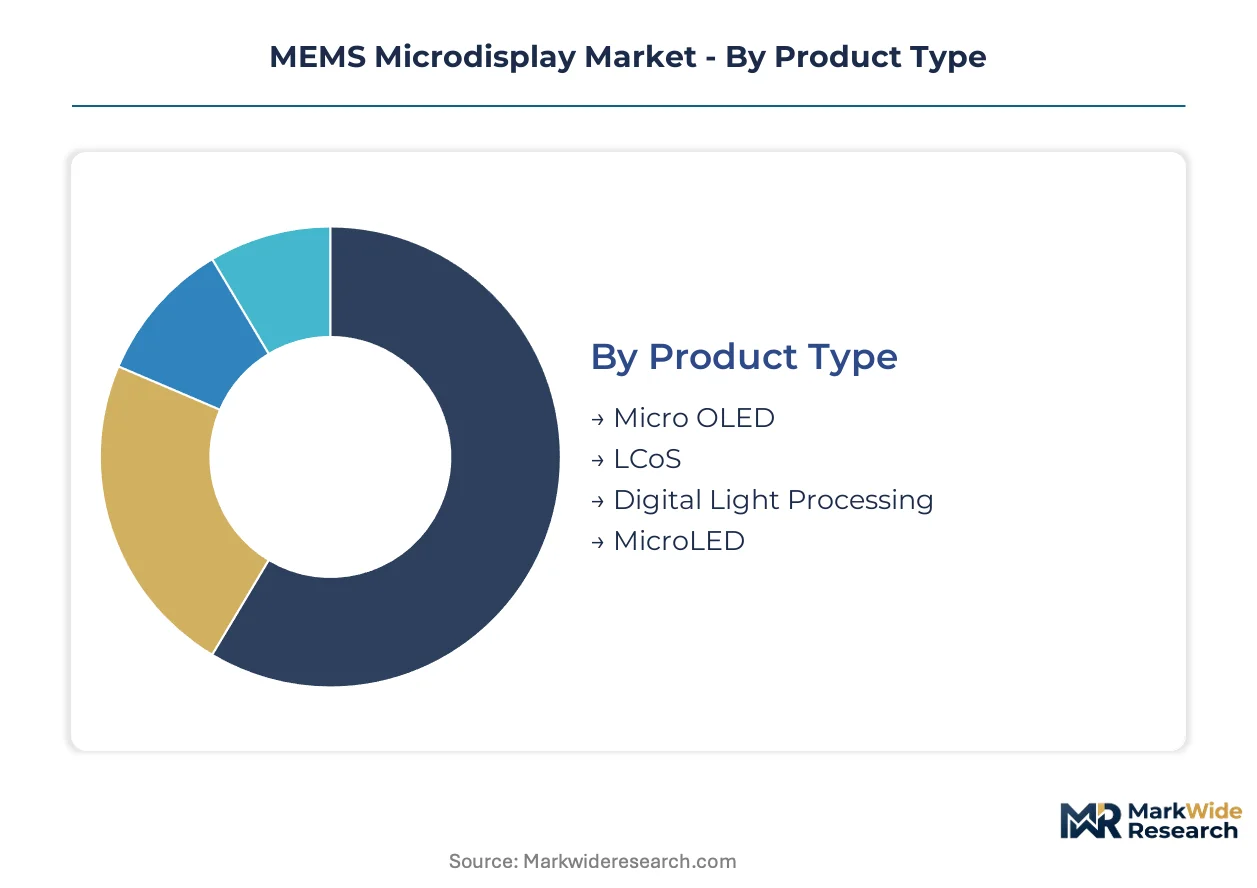
Product Type:
Upgrade cycles in near-eye display systems are compressing as gallium nitride emitters displace incumbent mirror architectures in premium AR waveguide engines.
- Micro OLED:Organic electroluminescent pixels deposited on silicon backplanes deliver sub-millisecond response times and infinite contrast ratios. Demand concentrates in surgical visualization headsets governed by FDA optical performance standards, where luminance uniformity requirements are most stringent.
- LCoS:Reflective liquid-crystal-on-silicon modulators use voltage-controlled birefringence to steer polarized light. Cost-sensitive industrial automation deployments in factory-floor depth cameras are expanding addressable volume for this architecture where structured-light 3D sensing dominates.
- Digital Light Processing:Micromirror arrays tilt ±12 degrees to modulate light direction with mature foundry processes.
- MicroLED:Gallium nitride emitters bonded directly to CMOS backplanes enable superior luminous efficiency.
Digital Light Processing sits at the top of the volume ranking, with MicroLED climbing the fastest.
End User:
Cost tier stratification separates military-grade qualification pathways from consumer headset procurement cycles.
- Consumer Electronics:Gaming headsets and smart glasses drive the largest absolute unit demand. Chinese domestic panel makers at BOE and CSOT are scaling MEMS-based near-eye display capacity, forcing Western foundries to establish localized technical support with 48-hour failure analysis turnaround.
- Defense:Pilot helmet-mounted cueing systems and AR training visors require military-grade luminance specifications. Wafer-level MEMS capacity is compressing consumer headset supply timelines as foundries trade off allocation between pilot visor and gaming headset customers.
- Automotive:Head-up display modules and augmented reality windshields are emerging applications.
- Healthcare:Diagnostic imaging headsets and surgical visualization systems face REACH substance documentation requirements.
Consumer Electronics captures the largest revenue base, with Defense expanding most quickly.
Technology:
Application-specific performance thresholds dictate whether direct-view or projection architectures prevail.
- Display Technology:Direct-emission or reflective light-modulation arrays for near-eye viewing. Medical imaging headsets in diagnostic applications governed by FDA standards are expanding procurement volumes where luminance uniformity requirements are most demanding.
- Projection Technology:Pico-projector engines using MEMS mirrors to steer light onto external surfaces. Portable projector channels maintain volume leadership for DLP mirror arrays despite MicroLED substitution pressure in premium segments.
- Augmented Reality:Waveguide-coupled microdisplays overlay digital information on physical environments.
- Virtual Reality:Immersive headsets with enclosed field-of-view dominate gaming applications.
Display Technology leads absolute module shipments, with Augmented Reality gaining share fastest.
Installation:
Supply concentration in East Asian packaging facilities favors embedded configurations over standalone alternatives.
- Embedded:Microdisplays integrated directly into host device motherboards with wafer-level bonding. Silicon photonics integration is reducing module thickness below 3 millimeters for AR waveguide engines, enabling lighter form factors in consumer headsets.
- Standalone:Self-contained display modules with independent power and thermal management. Defense contractors in the United States are qualifying monolithic silicon photonics engines for pilot helmet-mounted cueing systems.
- Portable:Battery-powered pico-projector units for mobile presentation and entertainment.
- Integrated:Factory-sealed optical engines with waveguide couplers pre-aligned.
Embedded configurations dominate production volume, with Integrated showing the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is redirecting MEMS microdisplay manufacturing investments toward jurisdictions with lower fluorinated gas compliance costs, while defense procurement and consumer electronics clusters concentrate capacity in specific national markets.
United States
Defense contractors are scaling pilot helmet-mounted cueing systems and AR training visors under FDA and FCC oversight. The Department of Defense procurement channels are pulling wafer-level MEMS capacity toward military-grade luminance specifications. Arizona and Texas semiconductor corridors host backplane integration facilities serving both defense and medical imaging OEMs.
China
Domestic panel makers at BOE and CSOT are expanding MEMS-based near-eye display capacity for consumer headsets under MIIT GB standards for energy consumption and eye-safety luminance. The EU F-Gas Regulation is accelerating domestic substitution investments in etching chemistry supply chains. Shenzhen and Hefei manufacturing clusters now demand 48-hour failure analysis turnaround from Western foundries.
South Korea
Captive CMOS foundry capacity at Samsung and SK Hynix is sustaining wafer-level integration advantages for Micro OLED segments bound for medical imaging headsets. The national response to EU fluorinated gas controls includes domestic etching equipment substitution programs. Seoul Capital Area packaging facilities are prioritizing embedded configurations for AR waveguide engines.
Germany
Automotive head-up display modules and industrial automation depth cameras are expanding LCoS architecture demand under REACH substance documentation requirements. ECHA restrictions on hazardous substances in semiconductor packaging are reformulating bill-of-materials for CE marking eligibility. Bavaria and Baden-Württemberg precision optics clusters are qualifying silicon photonics integration for thinner form factors.
Japan
CMOS backplane supply from Sony Semiconductor Solutions concentrates advanced foundry capacity under METI industrial policy guidance. Micro OLED segments for surgical visualization systems face stringent luminance uniformity requirements governed by PMDA standards. Kyushu and Tohoku semiconductor corridors maintain captive integration advantages for defense and medical applications.
MEMS Microdisplay Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with captive semiconductor divisions holding integration advantages in premium tiers while independent foundries serve cost-sensitive volume applications. The structure concentrates around three to four dominant backplane suppliers with heterogeneous integration capabilities. Strategic archetypes include CMOS-captive integrated device manufacturers, fabless MEMS design houses with foundry partnerships, and pure-play timing controller specialists. Competitive moves center on wafer-level bonding equipment investments and localized technical support deployments for Chinese panel maker procurement teams.
Among Asia-Pacific-based semiconductor divisions, Sony Semiconductor Solutions and Himax Technologies occupy positions at the integration-intensive end of the spectrum, while Texas Instruments represents the mature micromirror array segment. Sony exemplifies the CMOS-captive archetype through dedicated foundry capacity, Himax anchors the timing controller and driver IC co-design tier, and Texas Instruments sits within the established DLP volume leadership position for portable projector channels. These three entities collectively illustrate how vertical scope differentiation separates premium near-eye display suppliers from projection-focused competitors.
| Leading Market Players |
|---|
| Sony Semiconductor Solutions |
| Kopin Corporation |
| Himax Technologies |
| MicroVision |
| Texas Instruments |
| Jade Bird Display |
| eMagin Corporation |
| Syndiant |
| Jasper Display Corp |
| Others |
Supply & Pricing Matrix
Chinese panel makers' 48-hour failure analysis demands and captive volume commitments are forcing Western foundries to localize technical support teams, compressing margin structures as service intensity rises without proportional pricing recovery.
Pricing Analysis
Distributor margins for MEMS microdisplay modules compress as direct-to-OEM procurement channels expand. Three-tier pricing structure across defense-grade, medical-grade, and consumer-grade certification levels separates pilot visor specifications from gaming headset volumes. Cost compression in consumer tiers is intensifying because BOE and CSOT procurement teams negotiate consolidated annual commitments. Defense contractors show least price sensitivity due to military qualification barriers, while industrial automation buyers for LCoS depth cameras drive hardest bargain.
Supply Chain Analysis
Air freight premiums for wafer-level bonding equipment from Japan and Germany elevate total landed costs for new fab line installations. CMOS backplane supply concentrates in Taiwan, South Korea, and Japan, drawing from fluorinated etching chemistries, silicon-on-insulator substrates, and precision optical coatings. Single-source vulnerability runs through Sony Semiconductor Solutions' captive Kyushu foundry capacity. Distribution runs through Shenzhen and Hefei packaging clusters for Chinese domestic consumption, with Arizona and Texas corridors serving US defense and medical OEMs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Foundry investments are migrating toward jurisdictions with lower F-Gas compliance burdens, creating arbitrage between EU-regulated etching costs and South Korean domestic substitution incentives.
For Market Incumbents: To counter MicroLED substitution in premium AR waveguide engines, Sony Semiconductor Solutions and Himax Technologies should deepen captive CMOS-MEMS integration investments and accelerate silicon photonics qualification for sub-3-millimeter modules. Defense procurement pull toward military-grade luminance specifications demands dedicated capacity allocation protocols that preserve consumer headset supply timelines. For New Entrants and Emerging Players: Begin with India's PLI scheme for domestic panel assembly, where export-oriented consumer electronics manufacturing lacks embedded MEMS packaging depth. Structured-light 3D sensing for factory-floor automation offers penetrable volume for cost-sensitive LCoS architectures without competing against established DLP projector channels. Technical partnerships with Shenzhen-based procurement teams provide fastest qualification pathway. For Investors and Strategic Acquirers: Asymmetric upside sits with fabless MEMS design houses possessing foundry partnerships and software-defined calibration IP, as hardware margins commoditize. Long-term viability over the projection horizon rests on heterogenous integration capabilities rather than discrete component supply. Watch for wafer-level bonding equipment order backlogs as inflection signal for capacity expansion timing.| Strategic Initiative | Industry Significance |
|---|---|
| Wafer-Level Bonding Equipment Investment | Captive CMOS-MEMS integration at Sony and TSMC sustains premium positioning against fabless competitors. |
| Silicon Photonics Backplane Development | Monolithic optical I/O enables sub-3-millimeter modules for AR waveguide engines in pilot helmet systems. |
| Localized Technical Support Deployment | 48-hour failure analysis turnaround secures allocation priority with BOE and CSOT procurement teams. |
| Software-Defined Calibration Platform | Subscription-based color-profile management creates recurring revenue beyond hardware shipment cycles. |
| F-Gas Substitution Chemistry Qualification | Domestic etching supply chains in South Korea reduce REACH and EU regulatory compliance exposure. |
Research Methodology
Direct dialogue with MEMS foundry operations managers, display module procurement leads at BOE and CSOT, defense contractor systems engineers, and surgical visualization OEM regulatory affairs directors grounded qualitative assessment. Secondary validation drew from FDA 510(k) optical device filings, MIIT GB standard publications, ECHA REACH substance restriction updates, and SEMI equipment billings data. Bottom-up triangulation against top-down semiconductor capex forecasts ensured segmentation integrity.
Bottom-up modeling aggregated module shipments by product type, end-user vertical, and installation configuration across the analysis window. Top-down verification cross-checked foundry capacity announcements, defense procurement budget disclosures, and consumer electronics OEM display roadmap disclosures. CAGRs derived from wafer-level integration adoption curves, MicroLED displacement timelines, and regulatory compliance cost trajectories without assuming technology convergence.
Several conditions sit outside the modeled scope, including unannounced geopolitical export controls, breakthrough MicroLED transfer yield improvements, and harmonization of photobiological safety standards across FDA, ECHA, and MIIT jurisdictions. Forecasts reflect assumptions about fluorinated gas substitution timelines and defense procurement continuity. Stakeholders should weight assumptions against their own operating context and qualification backlog visibility.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Display Technologies
Display Material Market
Display Technologies
Tablets and Notebook Display Market
Display Technologies
Global LED Digital Signage Market
Display Technologies
Paper-Thin Display Market
Display Technologies
Gaming Monitors Market
Display Technologies
Multimedia Projectors Market
Display Technologies
Global UHD Display Market
Display Technologies
3D Display Module Market
Display Technologies
Masks for Display Panel Market
Display Technologies
Resistive Touchscreen Market
Display Technologies
Touch Screen Film Market
Display Technologies
Dot-Matrix LCD Modules Market
Display Technologies
Europe Computer Monitor Market
Display Technologies
Display Mask Market
Display Technologies
PMOLED Display Market
Display Technologies
Microdisplay Market