
 Global UHD Display Market | 2026-2036
Global UHD Display Market Size, Share, and Industry Trends Forecast 2026-2036
Global UHD Display Market Outlook
Modular panel bundling with integrated smart TV platforms is broadening buyer choice across price tiers. Samsung Display Co., Ltd. leverages its OLED vertical integration to capture premium positioning. BOE Technology Group Co., Ltd. anchors massive Gen 10.5 manufacturing scale in China. LG Display Co., Ltd. differentiates through white OLED evaporation technology for large-format screens.
UHD displays are flat-panel screens with pixel resolutions of 3840 × 2160 (4K) or 7680 × 4320 (8K), employing thin-film transistor backplanes to drive individual pixels at refresh rates up to 120 Hz for broadcast, digital signage, and consumer entertainment applications. OLED panels command the highest margin pools due to self-emissive architecture eliminating backlight assemblies. LED remains the volume leader in residential end user segments where cost sensitivity dominates procurement decisions. Gaming applications represent the fastest-growing technology segment as HDR and 120 Hz specifications become standard requirements.
The US FCC enforces energy consumption standards through ENERGY STAR certification programs that directly influence panel design requirements for North American market access. China's MIIT administers display industry standards under GB protocols while SAMR oversees market compliance for domestic manufacturers. The EU Ecodesign Directive and F-Gas Regulation constrain backlight refrigerant use and standby power thresholds across European imports. Stakeholders must monitor divergence between regional efficiency mandates and emerging MicroLED process scalability to align capital allocation with compliant production pathways.
Market Dynamics
Panel procurement patterns from streaming platforms and broadcasters are reshaping capacity allocation across Gen 8.5 and Gen 10.5 fabs, compressing lead times for premium OLED lots while stretching LCD delivery schedules.
Growth Catalysts
- China's dual carbon goals:Energy efficiency mandates under MEE protocols are accelerating fab retrofits toward low-temperature polysilicon processes, opening compliance-linked procurement windows for domestic manufacturers.
- Gaming segment specifications:HDR and 120 Hz requirements from esports broadcasters are pulling high-refresh panel volumes into premium residential channels.
- South Korea display cluster concentration:Proximity between Samsung and LG production complexes reduces logistics friction for bonded driver IC supply chains.
Market Restraints
- Input cost volatility:Rare earth dysprosium and europium prices for phosphor materials in LED backlights fluctuate with Chinese export quota adjustments.
- Supply concentration risk:Canon Tokki evaporation equipment for OLED deposition maintains single-source dependency from Japanese vendors.
- Technical limitation:White OLED color shift at high luminance constrains outdoor digital signage deployment without auxiliary thermal management.
Strategic Opportunities
- India residential underpenetration:Sub-15% UHD household penetration creates whitespace for 55-inch and 65-inch SKU expansion through e-commerce channels.
- EU F-Gas Regulation phase-down:Refrigerant constraints on conventional LED backlights incentivize transition to refrigerant-free OLED architectures for European imports.
- MicroLED-OLED convergence:Hybrid transfer processes combining pick-and-place precision with evaporation scalability promise cost reduction for sub-100-inch direct-view displays.
Industry Challenges
- Evaporation engineer scarcity:White OLED deposition expertise concentrates among veteran technicians at Korean and Japanese fabs, constraining capacity expansion timelines.
- ENERGY STAR certification latency:US DOE testing backlogs extend North American market entry timelines by four to six months for new panel form factors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global UHD Display Market |
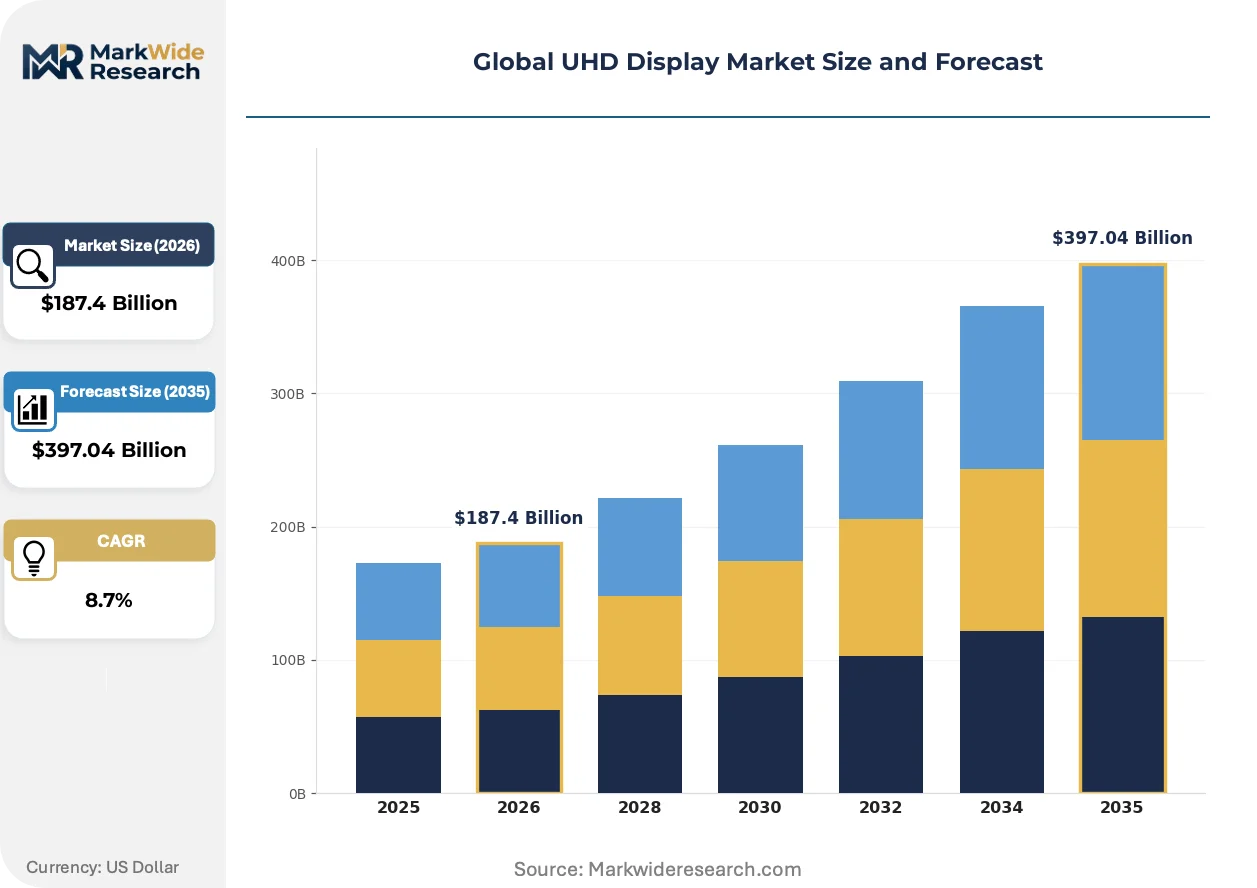
| Market Size in 2026 | $187.4 Billion |
| Market Size in 2035 | $397.04 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: LED, OLED, QLED, MicroLED End User: Residential, Commercial, Gaming, Education Size: 32 inch, 55 inch, 65 inch, 75 inch Technology: HDR, 4K, 8K, Smart TV |
| Companies Covered | Sharp Corporation, Innolux Corporation, Samsung Display Co., Ltd., TCL CSOT, Japan Display Inc., LG Display Co., Ltd., AU Optronics Corp., Samsung Electronics, BOE Technology Group Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global UHD Display Market Strategic Shifts
Manufacturing process convergence and regulatory efficiency mandates are compressing technology transition cycles, forcing simultaneous investment across multiple display architectures rather than sequential generational replacement.
MicroLED epitaxy and mass transfer processes are expanding into commercial signage and premium residential segments where burn-in risk and peak brightness requirements exceed OLED capabilities. Samsung and LG Display pilot lines in South Korea are qualifying 89-inch and 101-inch direct-view cabinets for corporate lobby installations. The technology is expanding into niches previously reserved for projection and fine-pitch LED walls, fragmenting the large-format premium category.
The EU Ecodesign Directive standby power thresholds and F-Gas refrigerant phase-down are forcing backlight redesigns for LED volumes bound for European ports. Panel makers are eliminating halogenated refrigerants in favor of solid-state thermal management or transitioning SKU allocation toward OLED for premium tiers. German and French importers now require supplier documentation tracing refrigerant content through GB standards-aligned supply chains.
Streaming platform procurement teams are consolidating panel purchasing through direct fab relationships, bypassing traditional OEM assembly tiers for original equipment specifications. Netflix and Disney content mastering divisions now issue reference display specifications that downstream TV manufacturers must certify against. This specification authority concentrates in Los Angeles and London post-production clusters, shifting pricing power toward content owners and away from hardware brands.
Global UHD Display Market Segmentation
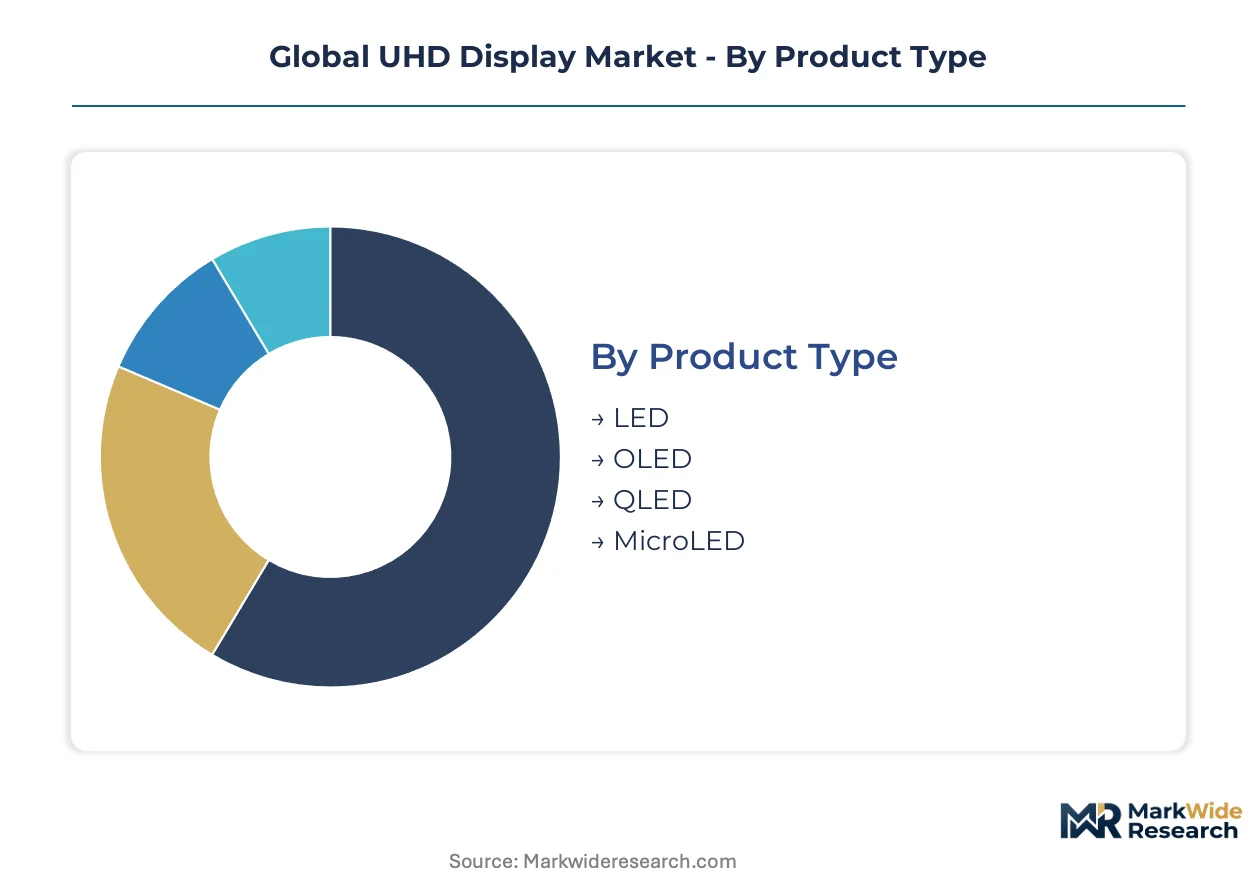
Panel architecture choices determine margin pools and compliance pathways across divergent regional efficiency mandates. Manufacturers allocate Gen 10.5 fab capacity based on segment-specific refresh rate and luminance requirements rather than uniform scaling.
Product Type:
Supply concentration in evaporation equipment and phosphor materials creates divergent expansion economics across display architectures.
- LED:LCD panels with edge-lit or direct-lit backlight assemblies dominate residential volume tiers where procurement teams prioritize unit cost over black-level performance. Chinese fabs in Hefei and Wuhan anchor global LED capacity under MIIT efficiency protocols.
- OLED:Self-emissive organic compounds eliminate backlight layers, enabling sub-3mm form factors and infinite contrast ratios. Samsung Display and LG Display complexes in South Korea concentrate white OLED expertise, constraining capacity expansion timelines due to veteran technician scarcity.
- QLED:Quantum dot enhancement films extend LED color gamut toward DCI-P3 coverage without evaporation process dependency. Samsung Electronics anchors QLED volume through in-house quantum dot inkjet production.
- MicroLED:Inorganic gallium nitride emitters enable 2000+ nit sustained brightness without burn-in risk for outdoor signage and corporate lobby installations. Samsung and LG pilot lines in South Korea are qualifying 89-inch and 101-inch direct-view cabinets.
LED absorbs the bulk of installed capacity; MicroLED is expanding most quickly among premium tiers.
End User:
Procurement authority is shifting from OEM brands toward content owners and platform operators with specification-setting power.
- Residential:Household replacement cycles drive 55-inch and 65-inch volume, with Indian e-commerce channels representing whitespace under 15% UHD penetration. ENERGY STAR certification latency extends North American entry timelines for new form factors.
- Commercial:Digital signage and corporate conferencing demand 24/7 durability and 700+ nit brightness for ambient light visibility. EU Ecodesign Directive standby thresholds force backlight redesigns for LED volumes bound for Rotterdam and Hamburg ports.
- Gaming:HDR and 120 Hz specifications from esports broadcasters pull high-refresh panels into premium residential channels. This segment climbs the fastest as tournament organizers standardize on 4K 144Hz reference displays.
- Education:Interactive whiteboard deployments prioritize 75-inch formats with anti-glare coatings for classroom visibility. Procurement concentrates through district-level bulk tenders in Texas, California, and Ontario.
Residential commands absolute volume; gaming claims the steepest expansion trajectory.
Size:
Gen 8.5 and Gen 10.5 fab economics favor specific diagonal ranges, compressing lead times for optimized mother glass cuts.
- 32 inch:Compact format serves secondary residential rooms and hospitality retrofit programs where space constraints override immersion priorities. BOE Technology Group anchors 32-inch volume through Beijing and Hefei line optimization.
- 55 inch:The volume anchor for global residential replacement, balancing panel yield rates against living room viewing distances. Chinese and Korean fabs allocate disproportionate mother glass to this diagonal.
- 65 inch:Premium residential threshold where OLED economics cross into mainstream affordability. Netflix and Disney content mastering divisions specify 65-inch as minimum reference size for HDR certification programs.
- 75 inch:Large-format residential and commercial standard requiring specialized logistics for last-mile delivery. White OLED color shift at high luminance constrains outdoor deployment without auxiliary thermal management.
55 inch captures the majority of fab output; 75 inch gains share fastest in North American and Middle Eastern premium channels.
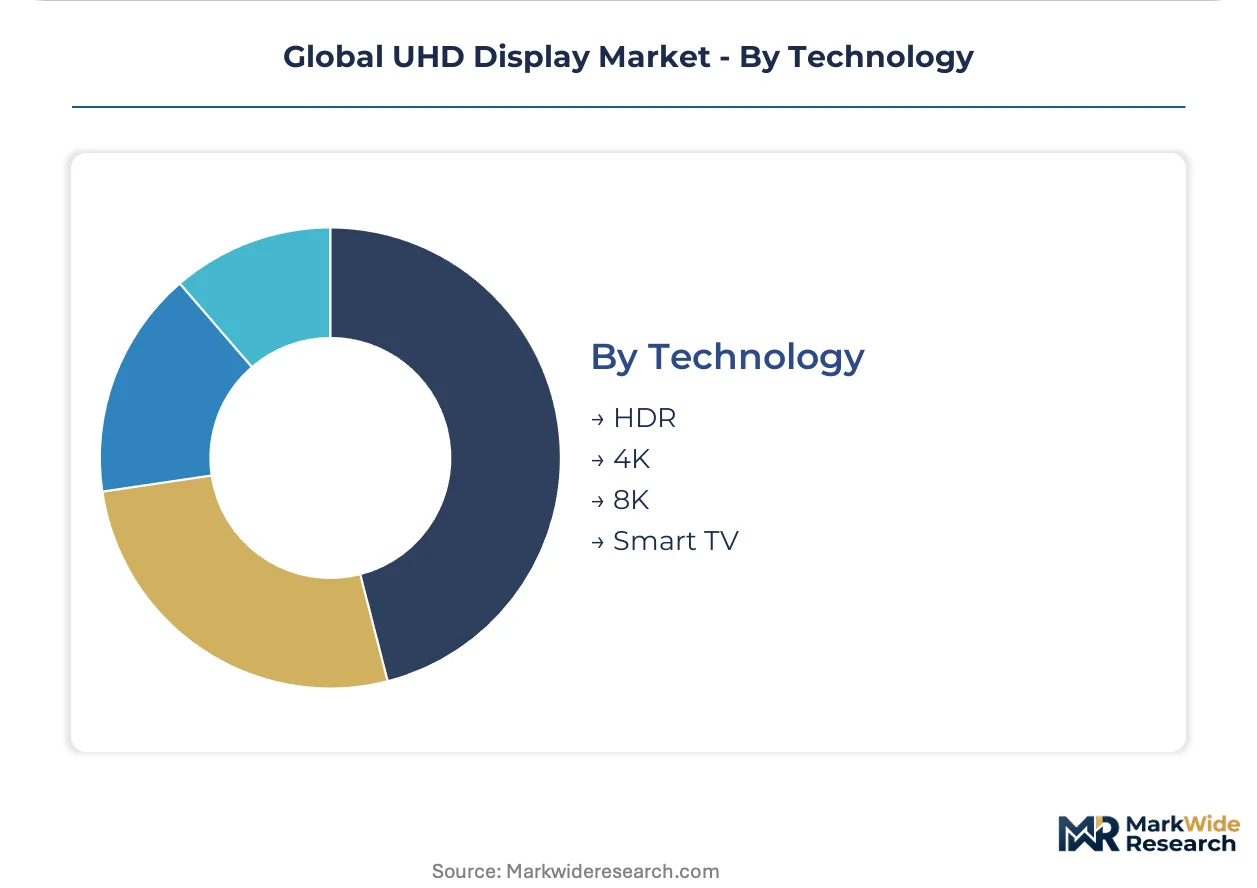
Technology:
Feature integration is compressing technology transition cycles, forcing simultaneous rather than sequential architecture investment.
- HDR:High dynamic range mastering requires 1000+ nit peak luminance and localized dimming zones for specular highlight reproduction. Streaming platform procurement teams now mandate HDR400 or HDR1000 certification for premium tier inclusion.
- 4K:3840 × 2160 resolution represents the current residential baseline, with panel yields mature across Gen 8.5 and Gen 10.5 fabs. 4K absorbs the bulk of streaming platform content delivery infrastructure.
- 8K:7680 × 4320 resolution enables immersive viewing at sub-2-meter distances for 85-inch+ formats. NHK broadcast trials and Japanese regulatory support accelerate 8K panel allocation despite limited native content libraries.
- Smart TV:Integrated processing platforms with streaming application ecosystems eliminate external device dependency. Roku, Tizen, and webOS licensing fees reshape margin structures for OEM assembly tiers.
4K holds the majority of installed base; 8K is expanding most quickly in Japanese and South Korean flagship retail channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
South Korea's free economic zones in Gyeonggi Province concentrate OLED evaporation expertise and bonded driver IC supply chains. China's Hefei and Wuhan industrial parks anchor Gen 10.5 LED capacity under MIIT efficiency protocols. Japan's Nagoya-Tokyo corridor sustains precision equipment manufacturing for deposition systems.
United States
Streaming platform procurement teams in Los Angeles and London post-production clusters now issue reference display specifications that TV manufacturers must certify against. The FCC enforces energy consumption standards through ENERGY STAR certification programs that directly influence panel design requirements. Texas and California district-level bulk tenders concentrate interactive whiteboard deployments for education end users.
China
BOE Technology Group anchors massive Gen 10.5 manufacturing scale in Beijing and Hefei fabs optimized for 32-inch volume production. MIIT administers display industry standards under GB protocols while SAMR oversees market compliance for domestic manufacturers. The Yangtze River Delta and Pearl River Delta clusters face accelerating fab retrofits toward low-temperature polysilicon processes under MEE dual carbon protocols.
South Korea
Samsung Display and LG Display production complexes in Gyeonggi Province reduce logistics friction for bonded driver IC supply chains. The country's display cluster concentrates white OLED expertise, constraining capacity expansion timelines due to veteran technician scarcity. Seoul Capital Area pilot lines are qualifying 89-inch and 101-inch MicroLED direct-view cabinets for corporate lobby installations.
Japan
NHK broadcast trials and METI regulatory support accelerate 8K panel allocation despite limited native content libraries. Canon Tokki maintains single-source dependency for evaporation equipment used in OLED deposition. The Nagoya-Tokyo corridor sustains precision manufacturing clusters supplying deposition and lithography systems to Korean and Chinese fabs.
Germany
German and French importers now require supplier documentation tracing refrigerant content through GB standards-aligned supply chains. The EU Ecodesign Directive standby power thresholds and F-Gas Regulation constrain backlight refrigerant use across European imports. Bavaria and North Rhine-Westphalia serve as distribution hubs for LED volumes bound for Rotterdam and Hamburg ports.
Global UHD Display Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across panel architecture tiers. The vendor base organizes around three strategic archetypes: Korean chaebol-affiliated display divisions with captive TV brand offtake, Chinese state-supported scale players with Gen 10.5 dominance, and Japanese precision equipment suppliers with deposition technology lock-in. Competitive moves concentrate on backward integration into driver IC supply and geographic expansion through Indian e-commerce channels.
Within the Korean chaebol tier, Samsung Display Co., Ltd. and LG Display Co., Ltd. occupy positions defined by OLED vertical integration and white OLED evaporation expertise respectively. BOE Technology Group Co., Ltd. exemplifies the Chinese scale-driven archetype with Beijing and Hefei fab concentration. Among Japanese precision specialists, Sharp Corporation represents legacy LCD optimization expertise.
| Leading Market Players |
|---|
| Sharp Corporation |
| Innolux Corporation |
| Samsung Display Co., Ltd. |
| TCL CSOT |
| Japan Display Inc. |
| LG Display Co., Ltd. |
| AU Optronics Corp. |
| Samsung Electronics |
| BOE Technology Group Co., Ltd. |
| Others |
Value Chain & Pricing Dynamics
Sovereign-backed producers in China's Yangtze River Delta anchor Gen 10.5 fab capacity, enabling aggressive unit pricing on 32-inch and 55-inch LED volumes while Korean chaebol-affiliated display divisions defend OLED premiums through captive driver IC supply and white OLED evaporation expertise. This ownership dichotomy compresses margin pools at the mid-tier while concentrating pricing power among vertically integrated specialists with in-house quantum dot or evaporation capabilities.
Pricing Analysis
Margin tightening in residential LED tiers reflects BOE Technology Group's Gen 10.5 scale economics and aggressive mother glass allocation to 55-inch formats. Three-tier pricing structure across premium OLED, standard QLED, and economy LED levels stratifies by certification grade and peak luminance performance. Cost compression accelerates in Indian e-commerce channels where sub-15% UHD household penetration intensifies price competition for 55-inch and 65-inch SKUs. Commercial digital signage buyers exhibit lowest price sensitivity, prioritizing 700+ nit brightness and 24/7 durability specifications over unit cost.
Supply Chain Analysis
Dual-sourcing requirements from Netflix and Disney procurement teams mandate qualified second-source validation for OLED evaporation equipment and bonded driver IC supply chains. Manufacturing concentrates in South Korea's Gyeonggi Province, China's Hefei-Wuhan corridor, and Japan's Nagoya-Tokyo equipment cluster. Raw material dependencies include rare earth dysprosium and europium for LED phosphors, gallium nitride substrates for MicroLED epitaxy, and specialized glass substrates from Corning and AGC. Single-source vulnerability persists for Canon Tokki evaporation systems. Distribution runs through bonded warehouse arrangements at Rotterdam, Hamburg, and Los Angeles ports for regional OEM assembly tiers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Competitive positioning in UHD displays hinges on backward integration into driver IC supply and evaporation equipment access, with Korean and Chinese players racing to secure captive semiconductor capacity.
For Market Incumbents: Hedge against MicroLED disruption by qualifying hybrid transfer processes at pilot lines in South Korea while locking long-term phosphor supply contracts with Chinese rare earth processors. Prioritize ENERGY STAR pre-certification investment to compress North American market entry timelines for new form factors. Defend OLED margin pools through exclusive Canon Tokki equipment allocation agreements and veteran technician retention programs. For New Entrants and Emerging Players: Capture whitespace in India's residential segment through 55-inch and 65-inch SKU launches via Flipkart and Amazon India channels, where UHD penetration remains below 15%. Target education procurement clusters in Texas, California, and Ontario with 75-inch interactive whiteboard formats featuring anti-glare coatings. Accelerate go-to-market velocity through white-label partnerships with established OEM assembly tiers rather than fab-scale capital deployment. For Investors and Strategic Acquirers: Distressed-cycle entries favor precision equipment specialists with evaporation technology lock-in and Chinese state-supported scale players with Gen 10.5 depreciation cycles maturing. Monitor Canon Tokki order backlogs and MIIT dual carbon retrofit compliance timelines as inflection indicators for capacity expansion viability. Long-term positioning requires exposure to both OLED premium-tier margin pools and MicroLED commercial signage adoption curves.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Driver IC Supply | Samsung Display's captive semiconductor production reduces logistics friction for bonded component delivery. |
| Gen 10.5 Fab Scale Expansion | BOE Technology Group's Beijing and Hefei lines anchor global LED volume through mother glass optimization. |
| White OLED Evaporation Expertise Acquisition | Veteran technician concentration at LG Display constrains competitor capacity expansion timelines. |
| MicroLED Pilot Line Qualification | Samsung and LG 89-inch and 101-inch direct-view cabinets target corporate lobby installations. |
| EU F-Gas Regulation Compliance Transition | OLED refrigerant-free architectures capture premium tier allocation for Rotterdam and Hamburg-bound volumes. |
Study Parameters
Independent corroboration across display fab utilization reports, streaming platform procurement disclosures, and regulatory filing databases underwrites the qualitative findings in this study. Primary interviews with panel procurement managers at Netflix and Disney content mastering divisions, fab operations directors at BOE and Samsung Display, and equipment sales executives at Canon Tokki supplied forward-looking capacity and technology roadmaps. Secondary validation drew from MIIT GB standard publications, US DOE ENERGY STAR certification databases, EU Ecodesign Directive implementation guidance, and SEC 10-K filings from listed display manufacturers. Bottom-up triangulation across mother glass input metrics and top-down reconciliation against end-user shipment data ensure internal consistency.
Rate-of-change decomposition across the projection horizon separates volume expansion from value migration effects, with segmentation modeling across product architecture, end-user application, diagonal size, and feature technology tiers. CAGRs derive from fitted growth curves calibrated to historical fab capacity ramp patterns and content platform procurement cycle timing. Industry-specific forecast inputs include Gen 8.5 and Gen 10.5 fab utilization rates, rare earth export quota adjustments from Chinese regulators, and ENERGY STAR certification backlog durations at US DOE testing facilities.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to MicroLED transfer process yield improvements and dual carbon protocol enforcement intensity from China's MEE. Deviation in Canon Tokki equipment delivery schedules or NHK 8K broadcast commitment levels would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Display Technologies
Quantum Dot Display Market
Display Technologies
Light Field Display Market
Display Technologies
Interferometric Modulator Display Market
Display Technologies
Interactive Display Market
Display Technologies
Multi-Function Display Market
Display Technologies
Graphic LCD Modules Market
Display Technologies
Global Display Panel Market
Display Technologies
Global Smartphone Display Panel Market
Display Technologies
Smartphone Display Market
Display Technologies
Display Mask Market
Display Technologies
Smart Display Market
Display Technologies
Global Monochrome Display Market
Display Technologies
Thin Display Technology Market
Display Technologies
DLP Projector Market
Display Technologies
4K Drawing Tablet with Screen Market
Display Technologies
Surface-Conduction Electron-Emitter Display (SED) Market