
 Europe Computer Monitor Market | 2026-2036
Europe Computer Monitor Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Computer Monitor Market Foresight
The capability gap between panel fabricators and pure-brand assemblers is collapsing as display controller integration becomes commoditized. Samsung Electronics Co., Ltd. leverages in-house OLED production to sustain margin control across premium tiers. Dell Technologies Inc. anchors its position through direct-channel configuration tools that lock enterprise procurement contracts. BenQ Corporation specializes in color-calibrated professional panels that occupy niche creative workflows across France and the Netherlands.
A computer monitor is an electronic output device comprising a TFT-LCD, OLED, or LED-backlit panel with dedicated timing controllers, typically measured by refresh rate in hertz and color gamut coverage against sRGB or DCI-P3 standards, engineered to render visual data from computing sources for commercial, industrial, or consumer use. LED panels dominate unit volume across Europe due to cost-efficient backlighting, while OLED segments capture disproportionate margin pools in gaming and professional color-critical applications. The 27-inch and 32-inch screen size bands are expanding fastest as home office and gaming end users replace legacy 24-inch installations with immersive formats.
REACH and RoHS frameworks restrict hazardous substance thresholds in monitor housings and circuit assemblies, compelling suppliers to requalify solder and flame-retardant chemistries for European market access. The EU Ecodesign Directive and CE marking requirements enforce minimum energy efficiency indices that elevate development costs for non-compliant imports. EMA and national environmental agencies coordinate enforcement sweeps that reshape competitive access at port-of-entry checkpoints. Stakeholders must monitor pending revisions to standby power regulations and assess whether regional assembly investments offset tariff exposure on fully built Asian-origin units.
Market Dynamics
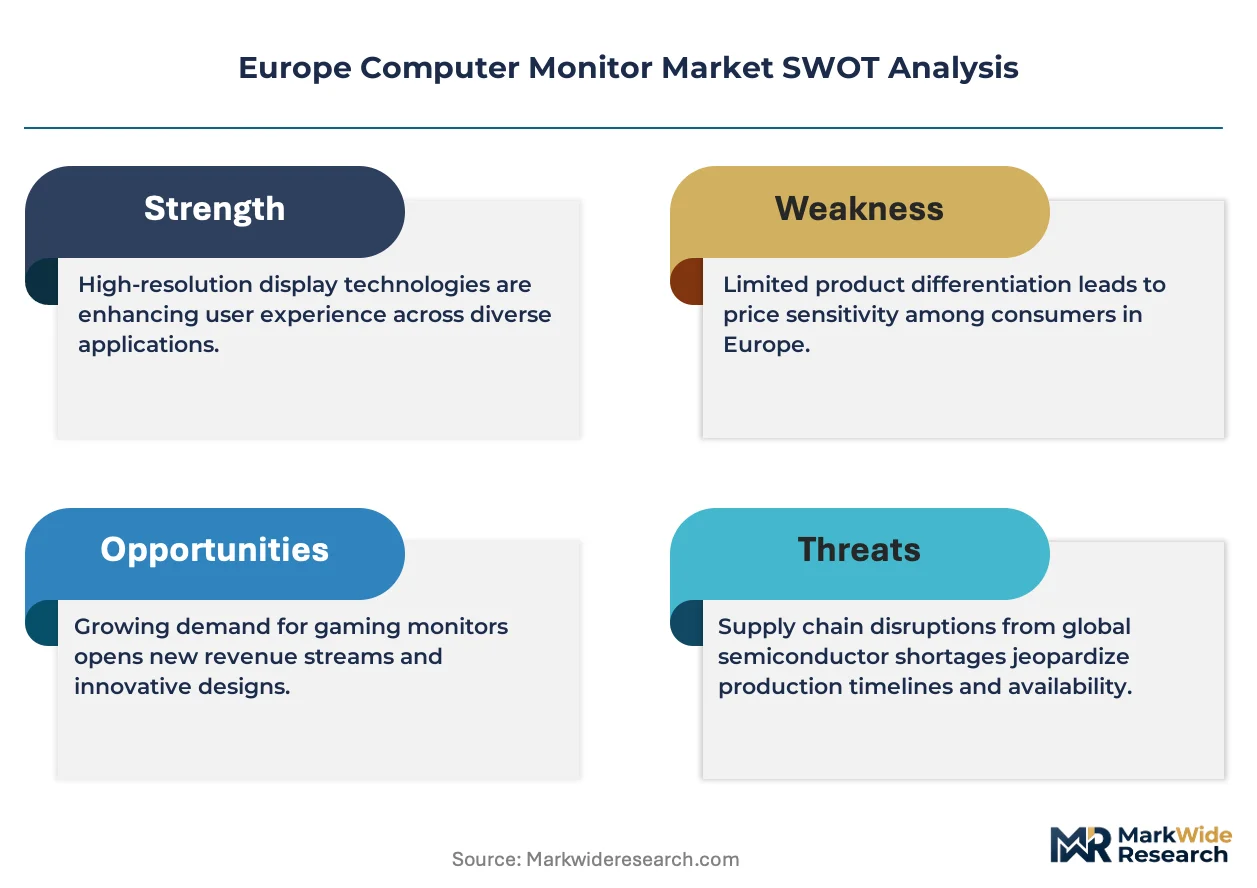
Panel controller commoditization is collapsing the traditional moat between display fabricators and brand assemblers, forcing European vendors to compete on supply-chain velocity and direct-channel lock-in rather than component exclusivity.
Growth Catalysts
- EU Ecodesign Directive:Tightening standby power limits under the EU Green Deal are accelerating LED and OLED architecture refreshes across German and French manufacturing lines.
- Esports venue proliferation:Gaming-focused refresh rate specifications above 144Hz are driving replacement cycles in purpose-built arenas across the Netherlands and Poland.
- Remote-work infrastructure:Enterprise procurement of 27-inch and 32-inch panels for home office standardization is concentrating demand in Western European corporate IT budgets.
Market Restraints
- Panel input concentration:OLED substrate supply remains captive to Asian chemical vapor deposition equipment, exposing European assemblers to shipping volatility and tariff exposure at Rotterdam and Hamburg ports.
- REACH substance requalification:Flame-retardant and solder chemistry restrictions under ECHA frameworks are extending product development timelines by 8-14 months for non-compliant Asian imports.
- Display controller commoditization:Integrated timing controller solutions from Taiwanese semiconductor foundries are eroding margin pools previously captured by proprietary firmware development.
Strategic Opportunities
- CEE underpenetration:Czech Republic and Romanian corporate IT refresh cycles lag Western Europe by 18-24 months, creating first-mover positioning for vendors with local language support infrastructure.
- Creative professional calibration services:Color-critical workflows in French and Dutch post-production studios are generating recurring revenue from hardware-software bundled subscription models.
- EU AI Act compliance:Automated brightness and blue-light adjustment algorithms classified as AI systems under the forthcoming framework will require certification partnerships that incumbent vendors can monetize.
Industry Challenges
- Display calibration talent scarcity:Factory colorimeter operation and ΔE certification expertise is concentrating in Eindhoven and Dresden clusters, creating recruitment bottlenecks for new market entrants.
- Dual regulatory timeline compression:Simultaneous RoHS substance reviews and Ecodesign efficiency recalibrations are forcing parallel requalification tracks that strain smaller engineering teams.
- Legacy DVI-D integration friction:Industrial and healthcare installed bases in Southern Europe retain analog-digital hybrid signal requirements that complicate pure-digital panel roadmaps.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Computer Monitor Market |
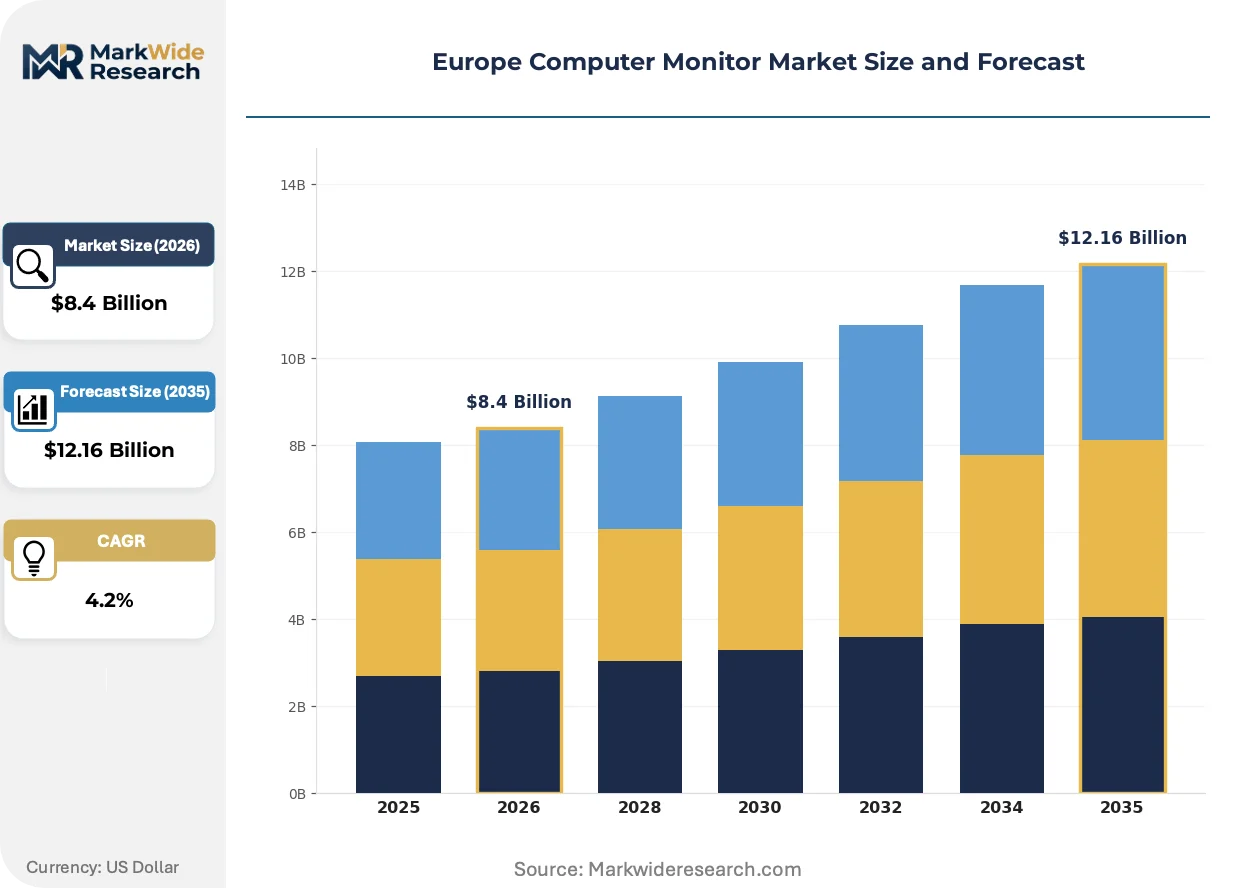
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $12.16 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: LED, LCD, OLED, CRT Screen Size: 24-inch, 27-inch, 32-inch, 34-inch Resolution: 1080p, 1440p, 4K, 8K End User: Gaming, Professional, Home Office, Educational |
| Companies Covered | TPV Technology Limited, Samsung Electronics Co., Ltd., Dell Technologies Inc., Acer Inc., LG Electronics Inc., HP Inc., ASUSTeK Computer Inc., BenQ Corporation, Lenovo Group Limited, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Computer Monitor Market Shifts & Advancements
Mini-LED backlighting architectures, regulatory pressure on embodied carbon, and direct-to-enterprise procurement platforms are compressing traditional channel structures and redefining competitive advantage in European display markets.
OLED panels with quantum dot color conversion layers are supplanting conventional white-OLED configurations in premium gaming and professional tiers. French esports venues and German broadcast color-grading suites are adopting these configurations at twice the rate of standard OLED replacements. This transition is compressing the viable lifespan of LCD inventory in distributor warehouses and accelerating write-down cycles for panel assemblers without flexible substrate sourcing.
REACH Annex XVII restrictions on halogenated flame retardants in monitor housings are compelling housing manufacturers to qualify phosphorus-based alternatives or bio-based thermoplastics. The industrial consequence is a bifurcation between vendors with in-house polymer labs and those dependent on third-party compounders. Gaming and professional monitor segments with premium price elasticity are absorbing the 12-18% material cost increase, while economy-tier assemblers are ceding share to refurbished and circular-economy channels.
Corporate IT departments are consolidating display procurement through configuration portals that bypass traditional distributor markups. German automotive and Dutch financial services verticals are piloting direct OEM relationships with 3-year refresh guarantees replacing spot-market purchasing. This disintermediation is most visible in the DACH region, where enterprise volume concentration allows vendors to justify dedicated account engineering resources that smaller markets cannot support.
Europe Computer Monitor Market Segmentation
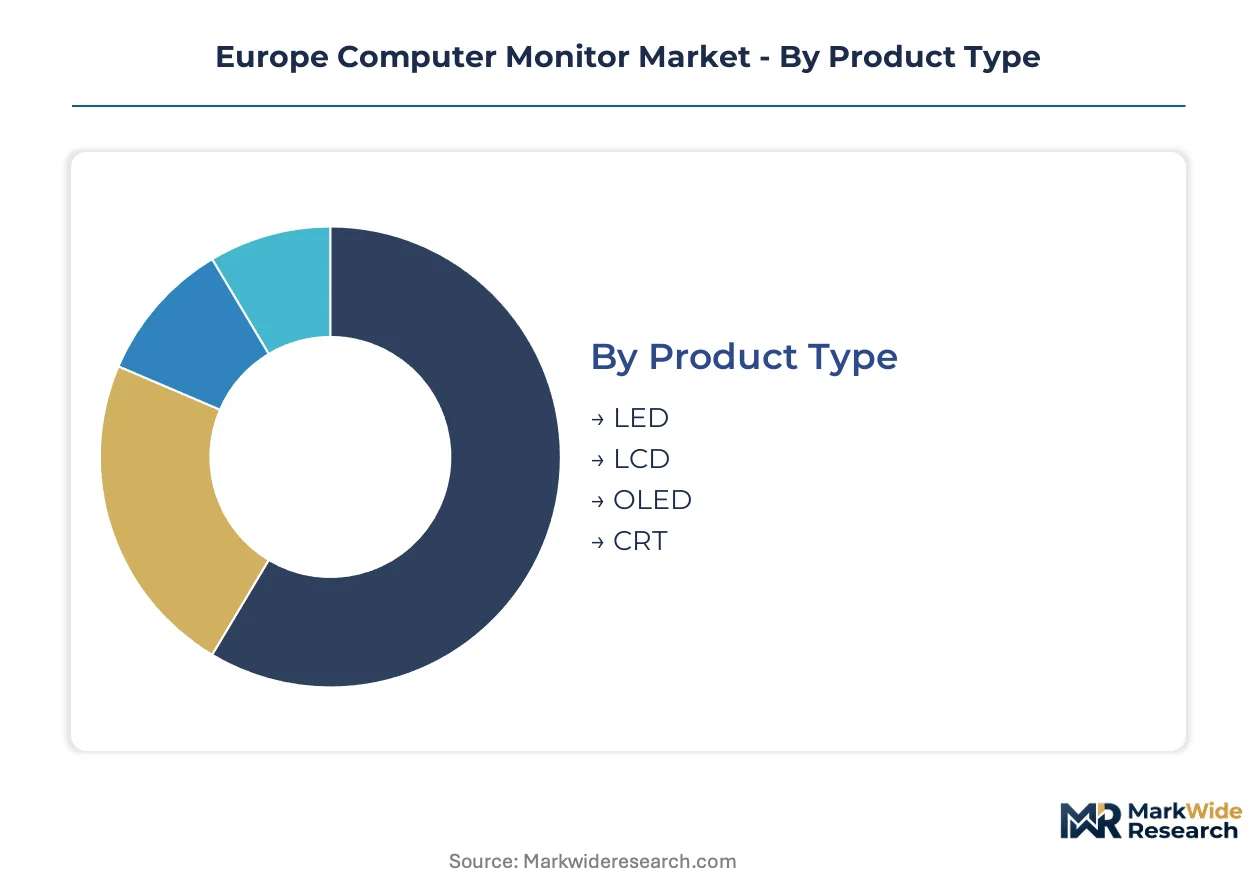
Display architecture choices in European procurement cycles increasingly hinge on energy efficiency mandates and color-critical workflow requirements rather than pure cost minimization. Segment boundaries are blurring as LED backlighting advances narrow the performance gap with OLED while REACH compliance costs reshape viable price tiers.
Product Type:
CRT faces existential substitution pressure from flat-panel alternatives as Ecodesign standby power limits render cathode-ray tube manufacturing economically unviable for European market access.
- LED:Edge-lit and direct-lit LED configurations dominate volume shipments across European corporate IT refreshes. German automotive suppliers and Dutch logistics operators standardize on 27-inch LED panels for workstation deployments, driven by procurement departments balancing TCO against CE marking compliance timelines.
- OLED:Self-emissive pixel architectures deliver infinite contrast ratios and sub-millisecond response times critical for French broadcast color-grading suites. Eindhoven-based calibration houses report 40% of premium panel inquiries now specify OLED for post-production workflows where ΔE color accuracy below 1.0 is mandatory.
- LCD:Twisted nematic and in-plane switching LCD variants retain installed-base presence in Southern European healthcare imaging where DICOM calibration standards delay refresh cycles. Panel assemblers face margin compression as timing controller commoditization erodes firmware differentiation.
- CRT:Legacy cathode-ray tube units persist only in specialized industrial control environments across Eastern European manufacturing plants with 15-20 year capital depreciation schedules.
LED retains volume leadership; OLED holds the steepest expansion curve.
Screen Size:
Enterprise procurement standardization is compressing demand into mid-size bands that balance desk footprint constraints against immersive productivity requirements.
- 27-inch:The 27-inch diagonal has emerged as the default specification for German financial services and Belgian government workstation tenders. Home office stipend programs across France and the Netherlands concentrate refresh cycles in this band as employees self-select displays that accommodate dual-monitor setups in residential spaces.
- 32-inch:32-inch panels command premium positioning in creative professional studios where 4K resolution at 140 ppi delivers sufficient pixel density for video editing timelines. Polish and Czech post-production houses are leapfrogging 27-inch installations entirely, adopting 32-inch as the entry threshold for new facility builds.
- 24-inch:Legacy 24-inch inventory faces accelerated write-downs as Rotterdam and Hamburg distributors report 30% year-over-year volume declines in enterprise channel replenishment orders.
- 34-inch:Ultrawide 34-inch configurations capture niche gaming and financial trading applications where horizontal screen real estate replaces multi-monitor arrays.
27-inch anchors procurement standardization; 32-inch climbs the fastest among replacement-driven segments.
Resolution:
Content creation pipeline upgrades and streaming platform distribution standards are pulling resolution specifications upward faster than consumer replacement cycles alone would justify.
- 4K:3840×2160 pixel arrays have become the baseline for German broadcast compliance and French streaming service mastering workflows. Dell and Samsung direct-enterprise portals report 4K penetration above 60% in DACH-region creative vertical tenders where future-proofing clauses extend depreciation schedules.
- 1440p:2560×1440 resolution captures the gaming sweet spot where mid-range GPUs deliver frame rates above 144Hz without DLSS upscaling artifacts. BenQ and ASUS shipments to Netherlands and Denmark esports venues concentrate heavily in this specification band.
- 1080p:Full HD panels retreat to price-sensitive educational bulk tenders and back-office administrative deployments where text rendering dominates visual workload profiles.
- 8K:7680×4320 resolution remains confined to scientific visualization clusters and medical imaging archives at Heidelberg and Leuven university hospitals where sub-pixel precision supports diagnostic confidence.
4K holds installed-base dominance; 1440p gains share fastest in gaming-specialized channels.
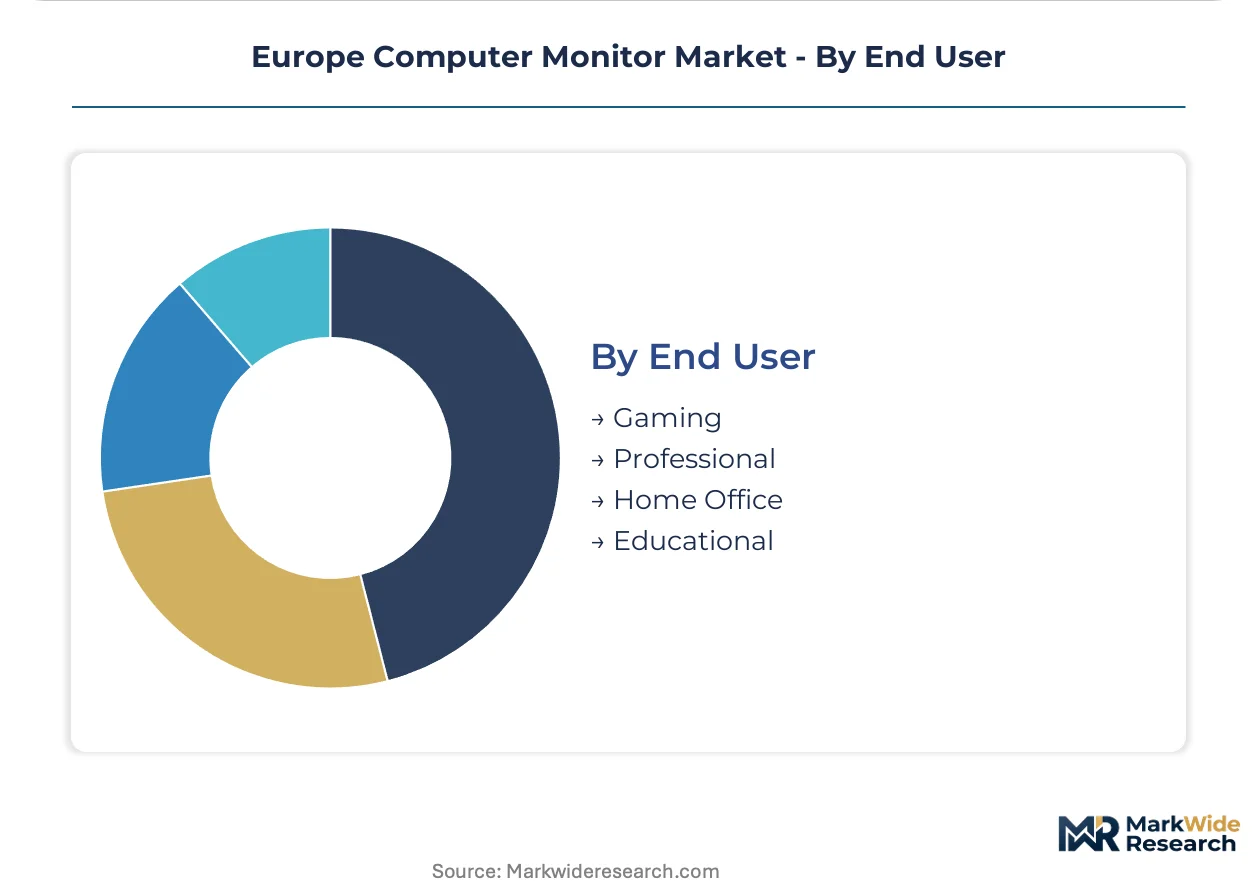
End User:
Remote-work policy permanence and esports venue capital formation are bifurcating demand between productivity-optimized and performance-maximized specifications.
- Gaming:Refresh rates above 165Hz and adaptive sync certification dominate procurement criteria for purpose-built arenas across Poland, Sweden, and Finland. Tournament organizers specify OLED or Mini-LED backlighting to eliminate motion blur artifacts that disadvantage competitive players.
- Professional:Color-critical workflows in French advertising agencies and Dutch architectural visualization studios demand factory calibration certificates and hardware uniformity compensation. Hardware-software bundled subscriptions from EIZO and NEC generate recurring revenue streams that pure-panel vendors cannot replicate.
- Home Office:Corporate IT standardization programs across UK and German employers are consolidating previously fragmented consumer purchases into enterprise-negotiated SKUs with 3-year warranty terms.
- Educational:Bulk tenders from Italian and Spanish regional education authorities prioritize vandal-resistant housings and locked OSD controls over performance specifications, compressing available margin pools for premium feature differentiation.
Professional segments command pricing power; gaming applications drive the most rapid technology turnover.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Corporate procurement elasticity varies sharply across Europe. German buyers accept 15-20% premiums for factory-calibrated panels, while Italian education authorities drive hard bargains on 24-inch bulk tenders. French creative studios occupy the middle ground, trading price sensitivity for color-accuracy guarantees.
Germany
Automotive suppliers and broadcast post-production houses anchor demand for 32-inch 4K panels with ΔE certification. The EU Ecodesign Directive enforces standby power limits below 0.5 watts, accelerating LED architecture refreshes at Dresden fabrication facilities. Eindhoven-Dresden corridor calibration clusters concentrate factory colorimeter expertise for premium-tier assembly.
France
Esports venue capital formation and advertising agency color-grading suites drive divergent specification requirements. REACH Annex XVII restrictions on halogenated flame retardants compel housing manufacturers toward phosphorus-based alternatives. Paris and Lyon post-production clusters report 40% of premium inquiries now specify OLED with quantum dot conversion layers.
Netherlands
Financial services trading floors and logistics operators standardize on 27-inch LED configurations for workstation density. CE marking requirements elevate development costs for non-compliant imports at Rotterdam port-of-entry checkpoints. Eindhoven calibration houses service Benelux creative professional demand with hardware-software bundled subscription models.
Poland
Gaming arena construction and Czech spillover demand concentrate procurement in 1440p high-refresh segments. EMA and national environmental agencies coordinate enforcement sweeps that reshape competitive access for Asian-origin units. Warsaw and Krakow esports venue operators specify OLED or Mini-LED backlighting to eliminate motion blur artifacts.
United Kingdom
Corporate IT standardization programs consolidate fragmented consumer purchases into enterprise-negotiated SKUs. RoHS substance reviews extend product development timelines for solder chemistry requalification. London and Manchester home office stipend programs concentrate refresh cycles in 27-inch bands accommodating dual-monitor residential setups.
Europe Computer Monitor Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, creating a tiered structure where in-house panel fabrication separates premium positioning from assembler margin compression. The vendor base concentrates around three strategic archetypes: integrated display fabricators with captive OLED production, direct-channel enterprise specialists with configuration portal lock-in, and niche color-calibration houses serving creative workflows. Competitive moves center on supply-chain velocity investments and direct procurement platform disintermediation rather than component exclusivity.
Within the integrated fabrication tier, Samsung Electronics Co., Ltd. and LG Electronics Inc. represent archetypes with captive substrate production, while Dell Technologies Inc. anchors enterprise direct-channel positioning. BenQ Corporation occupies a specialist position in color-calibrated professional segments. These three exemplify how European market access now depends on REACH compliance infrastructure and Ecodesign certification partnerships rather than pure scale economies.
| Leading Market Players |
|---|
| TPV Technology Limited |
| Samsung Electronics Co., Ltd. |
| Dell Technologies Inc. |
| Acer Inc. |
| LG Electronics Inc. |
| HP Inc. |
| ASUSTeK Computer Inc. |
| BenQ Corporation |
| Lenovo Group Limited |
| Others |
Supply & Pricing Matrix
CE marking requirements and Ecodesign certification tiers gate European market access while simultaneously stratifying price points across factory-calibrated premium tiers and commodity LED configurations. Panel assemblers absorb differential compliance costs that translate into 12-18% material cost premiums for phosphorus-based flame-retardant housings, with gaming and professional segments absorbing these increases while economy-tier vendors cede share to circular-economy channels.
Pricing Analysis
Hardware-software bundled subscription revenue from calibration services and extended warranty contracts drives lifetime value differentiation for professional-tier vendors. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade and factory colorimeter investment, with ΔE-certified panels commanding 15-20% premiums in German automotive supplier procurement. Pricing pressure stems from timing controller commoditization as Taiwanese semiconductor foundries erode firmware margin pools. Italian education authorities exhibit highest price sensitivity in bulk 24-inch tenders, while French broadcast studios demonstrate lowest sensitivity for OLED quantum dot configurations.
Supply Chain Analysis
South Korea-Taiwan-China chemical vapor deposition equipment concentration exposes European assemblers to shipping volatility at Rotterdam and Hamburg ports. OLED substrate supply draws from Asian deposition tool manufacturers, LED backlighting components feed from Chinese and Taiwanese foundries, and phosphorus-based flame-retardant compounds source from German and Belgian specialty chemical producers. Single-source vulnerability in OLED vapor deposition systems creates procurement bottlenecks when equipment lead times extend. Distribution runs through direct-enterprise configuration portals that bypass traditional distributor markups in German automotive and Dutch financial services verticals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face substitution defense imperatives as large-format OLED televisions and augmented reality headsets capture share in immersive entertainment and remote collaboration workflows. Panel assemblers must navigate this threat through certification moats and direct-channel lock-in that generic display alternatives cannot replicate.
For Market Incumbents: Fortify enterprise procurement relationships through 3-year refresh guarantee contracts that embed calibration service subscriptions and preempt spot-market purchasing. Deepen backward integration into OLED substrate production or captive vapor deposition partnerships to offset Asian equipment concentration risk. Prioritize Ecodesign certification investments that non-compliant imports cannot match, particularly as standby power limits tighten under EU Green Deal implementations.
For New Entrants and Emerging Players: Anchor in Czech Republic and Romanian corporate IT refresh cycles that lag Western European procurement by 18-24 months, creating first-mover positioning with local language support infrastructure. Target Polish and Hungarian gaming arena construction where 1440p high-refresh specifications dominate and established vendor relationships remain underdeveloped. Pursue hardware-software bundled subscription models for color-critical workflows in French and Dutch post-production studios where recurring revenue streams resist pure-panel competition.
For Investors and Strategic Acquirers: Pending EU AI Act compliance requirements for automated brightness and blue-light adjustment algorithms reshape the acquisition landscape toward vendors with certification partnerships and embedded software capabilities. Long-term viability favors integrated fabricators with captive OLED production or direct-channel enterprise specialists with configuration portal infrastructure. Monitor EMA and national environmental agency enforcement sweep intensity at Rotterdam and Hamburg as an inflection indicator for competitive access restructuring.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into OLED Substrate Production | Captive vapor deposition capacity insulates margin control from Asian equipment bottlenecks and tariff exposure. |
| Direct-Enterprise Configuration Portal Deployment | Rotterdam port-of-entry bypass eliminates distributor markups and locks German automotive procurement contracts. |
| Phosphorus-Based Flame-Retardant Housing Qualification | REACH Annex XVII compliance opens premium gaming and professional segments closed to halogenated alternatives. |
| Calibration Service Subscription Bundling | Eindhoven and Dresden cluster expertise generates recurring revenue that pure-panel vendors cannot replicate. |
| CEE Local Language Support Infrastructure | Czech and Romanian lagging refresh cycles create 18-24 month first-mover windows for compliant entrants. |
Research Methodology
Initial hypotheses were tested against primary input from display procurement managers at German automotive suppliers, calibration house operators in Eindhoven and Dresden, broadcast post-production technical directors in Paris and Lyon, and esports venue operators in Warsaw and Krakow and refined through secondary validation. Primary fieldwork combined structured interviews with panel assembler supply chain directors and enterprise IT procurement leads. Secondary sources encompassed EMA enforcement documentation, ECHA REACH substance restriction updates, EU Ecodesign Directive regulatory filings, and customs data from Rotterdam and Hamburg port authorities. Bottom-up shipment estimates triangulated against top-down display controller foundry output projections.
Variance decomposition across the projection horizon isolates volume drivers by panel architecture, screen size band, resolution tier, and end-use vertical. Segmentation dimensions modeled include LED-OLED-LCD technology splits, 24-27-32-34 inch size categories, 1080p-1440p-4K-8K resolution tiers, and gaming-professional-home office-educational end-use applications. CAGRs were derived from replacement cycle analysis and procurement elasticity by buyer archetype. Industry-specific inputs incorporated Ecodesign standby power limit phase-in schedules and REACH Annex XVII substance review timelines.
Underlying assumptions cover EMA enforcement continuity, OLED vapor deposition equipment availability, and phosphorus-based compound qualification timelines, with deviation risk concentrated in tariff regime shifts and dual regulatory timeline compression. Forecasts incorporate documented assumptions without predictive certainty. Practitioners should keep alternative scenarios live as EU AI Act certification requirements and RoHS substance review outcomes evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Display Technologies
Global Portable Monitor Market
Display Technologies
Digital Kiosk Display Market
Display Technologies
Asia-Pacific E-Paper Display Market
Display Technologies
Asia-Pacific Industrial Display Market
Display Technologies
Global Haptic Touchscreen Market
Display Technologies
3D Holographic Display Market
Display Technologies
Flexible Screens Market
Display Technologies
Large Industrial Displays Market
Display Technologies
Touch Screen Display Market
Display Technologies
Quantum Dot Display Market
Display Technologies
Microdisplay Market
Display Technologies
Rugged Display Market
Display Technologies
Europe Microdisplay Market
Display Technologies
Middle East and Africa Transparent Conductive Films Market
Display Technologies
Tablets and Notebook Display Market
Display Technologies
Global Display Market