
 Masks for Display Panel Market | 2026-2036
Masks for Display Panel Market Size, Share, and Industry Trends Forecast 2026-2036
Masks for Display Panel Market Insights
A shift from single-source photomask procurement to dual-qualified supply arrangements is realigning how display panel makers secure critical lithography tooling. Photronics Inc. leverages its captive manufacturing footprint across multiple geographies to sustain delivery reliability for OLED mask customers. Dai Nippon Printing Co., Ltd. anchors high-end mask production through proprietary patterning expertise that commands premium positioning in smartphone supply chains. Hoya Corporation competes on substrate material purity, extending its optical glass leadership into display-grade quartz blank supply.
Masks for Display Panel are precision-patterned quartz substrates with chrome or molybdenum-silicon absorber layers, manufactured via electron-beam lithography to sub-micron tolerances for transferring circuit geometries onto TFT backplanes. Their primary purpose is enabling high-resolution patterning of thin-film transistor arrays that drive pixel switching in flat-panel displays. OLED Masks command the dominant share of value as foldable and high-refresh-rate panels proliferate, while MicroLED-oriented mask sets represent the fastest-expanding technology tier due to chiplet-scale transfer requirements. Automotive Displays as an application segment is drawing disproportionate investment as tier-one panel makers adapt mask designs for wide-temperature and long-lifetime specifications.
Japan's METI oversees domestic mask industry consolidation through semiconductor and display technology roadmaps that prioritize supply security. South Korea's MFDS and industrial standards bodies enforce contamination controls that shape mask qualification protocols for OLED fabs near Seoul and Gumi. Taiwan's CEA-aligned regulations on hazardous material handling in precision manufacturing affect mask cleaning and recycling operations. Stakeholders must monitor how divergent regional certification timelines for next-generation display nodes reshape vendor eligibility across major panel production clusters.
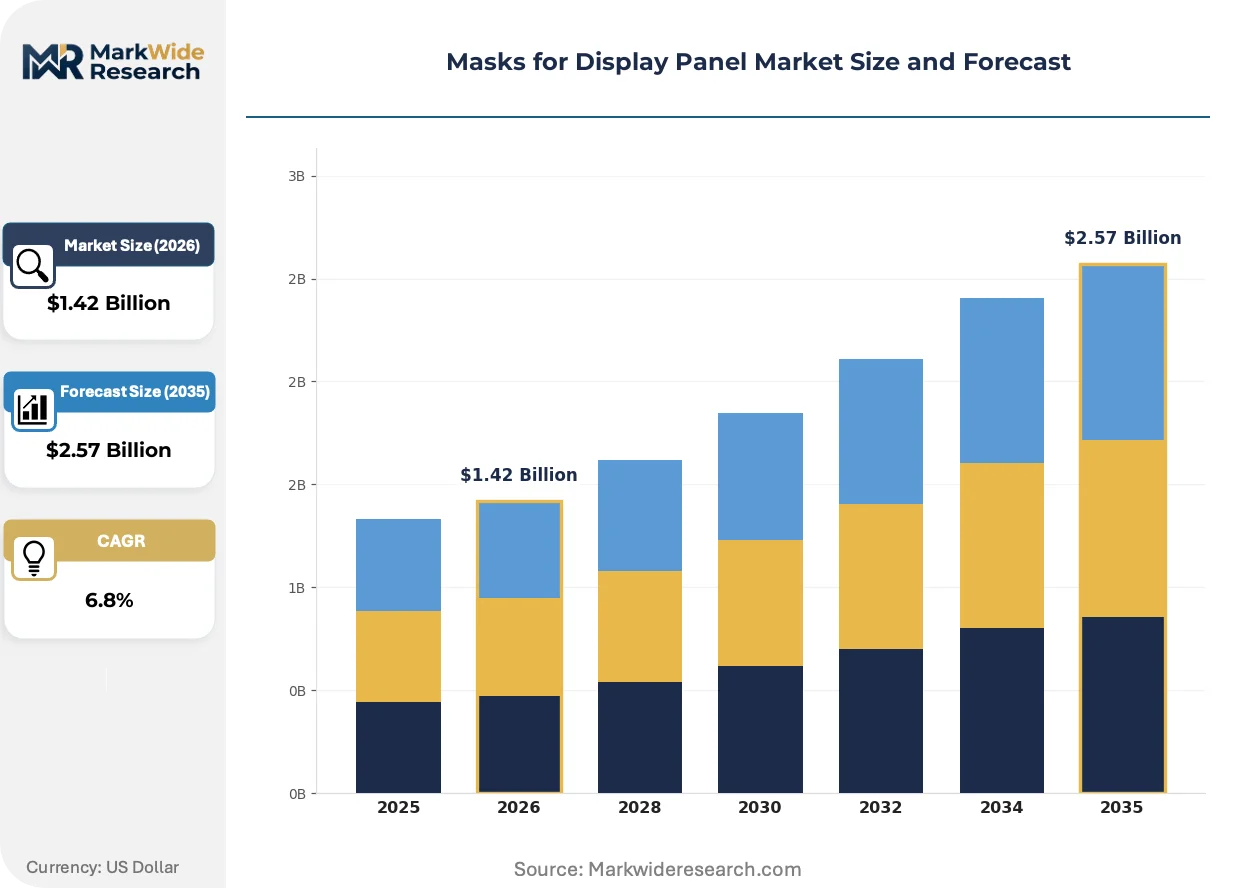
Market Dynamics
Display panel photomask procurement is pivoting from single-source dependency toward dual-qualified supply architectures as resolution roadmaps tighten and geopolitical risk reshapes vendor selection criteria across major fabrication clusters.
Growth Catalysts
- OLED Resolution Escalation:Smartphone manufacturers are mandating sub-micron pattern fidelity for foldable and high-refresh-rate panels, pulling advanced multi-layer mask sets into standard procurement bundles.
- South Korea's Supply Chain Resilience Mandate:Domestic panel makers under METI-aligned technology roadmaps are qualifying second-source mask vendors to reduce exposure to concentrated supplier geographies.
- Automotive Display Specification Tier:Wide-temperature and long-lifetime requirements for cockpit panels are creating dedicated mask design categories with distinct qualification protocols.
Market Restraints
- Quartz Substrate Supply Concentration:High-purity synthetic quartz blank production clusters in limited geographic zones, creating input bottlenecks when fab capacity expands.
- Electron-Beam Lithography Equipment Lead Times:Mask patterning tool availability constrains capacity expansion at independent mask shops regardless of downstream demand signals.
- Contamination Control Infrastructure Costs:Class 1 cleanroom requirements for OLED-grade masks impose capital intensity that limits new entrant participation.
Strategic Opportunities
- MicroLED Chiplet Transfer Masks:Mass transfer architectures for micro-LED displays require novel stencil designs with asymmetric aperture geometries that incumbent mask makers are positioned to capture.
- Taiwan CEA Hazardous Material Handling Incentives:Regulatory frameworks supporting precision manufacturing recycling operations create cost advantages for mask cleaning and substrate reclamation services.
- India Display Manufacturing Corridor:Emerging panel fabrication investments under PLI scheme structures will require localized mask qualification and logistics capabilities.
Industry Challenges
- Patterning Engineer Talent Scarcity:Electron-beam lithography operation and defect metrology expertise concentrates at incumbent vendors, constraining capacity scaling.
- Multi-Node Qualification Overlap:Mask shops must maintain parallel qualification streams for legacy LCD, current OLED, and emerging MicroLED nodes simultaneously.
- Substrate-to-Fab Logistics Integrity:Quartz mask blanks require vibration-controlled transport with environmental monitoring, complicating geographic diversification strategies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Masks for Display Panel Market |
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $2.57 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: LCD Masks, OLED Masks, LED Masks, QLED Masks Application: Smartphones, Televisions, Monitors, Automotive Displays Technology: Thin Film Transistors, Flexible Displays, Touchscreen, MicroLED End User: Consumer Electronics, Industrial Devices, Healthcare Equipment, Retail Displays |
| Companies Covered | Photronics Inc., Dai Nippon Printing Co., Ltd., Hoya Corporation, Toppan Photomasks Inc., LG Innotek Co., Ltd., SK-Electronics Co., Ltd., Taiwan Mask Corporation, Shenzhen Qingyi Photomask Ltd., Darwin Microelectronic Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Masks for Display Panel Market Trends and Innovations
Photomask technology trajectories are diverging across display generations as OLED refinement, MicroLED emergence, and automotive qualification requirements create parallel development tracks with distinct technical specifications.
Multi-layer phase-shift masks are expanding into high-resolution OLED production as panel makers pursue 500+ ppi densities for virtual reality headsets and premium smartphone form factors. Samsung Display and LG Display are accelerating adoption of attenuated phase-shift architectures that extend 193nm optical lithography resolution without requiring equipment replacement. This technology is expanding into standard procurement specifications that independent mask shops must meet to retain qualified vendor status.
Japan's METI semiconductor and display technology roadmaps are consolidating domestic mask industry capabilities through targeted R&D subsidies and qualification standard harmonization. The framework prioritizes supply security for critical lithography tooling by incentivizing captive production investments and cross-vendor technology sharing agreements. Domestic panel makers and mask suppliers are responding with coordinated roadmapping that aligns node transitions with indigenous equipment availability timelines.
Dual-source contracting is replacing sole-source arrangements as tier-one panel makers demand geographic and vendor diversification for mask supply continuity. Procurement teams at major OLED fabs are splitting volumes across qualified suppliers to mitigate disruption risk from single-point failures. South Korea's display ecosystem near Seoul and Gumi exhibits the most advanced implementation of this model, with formal second-source qualification timelines now embedded in vendor scorecards.
Masks for Display Panel Market Segmentation
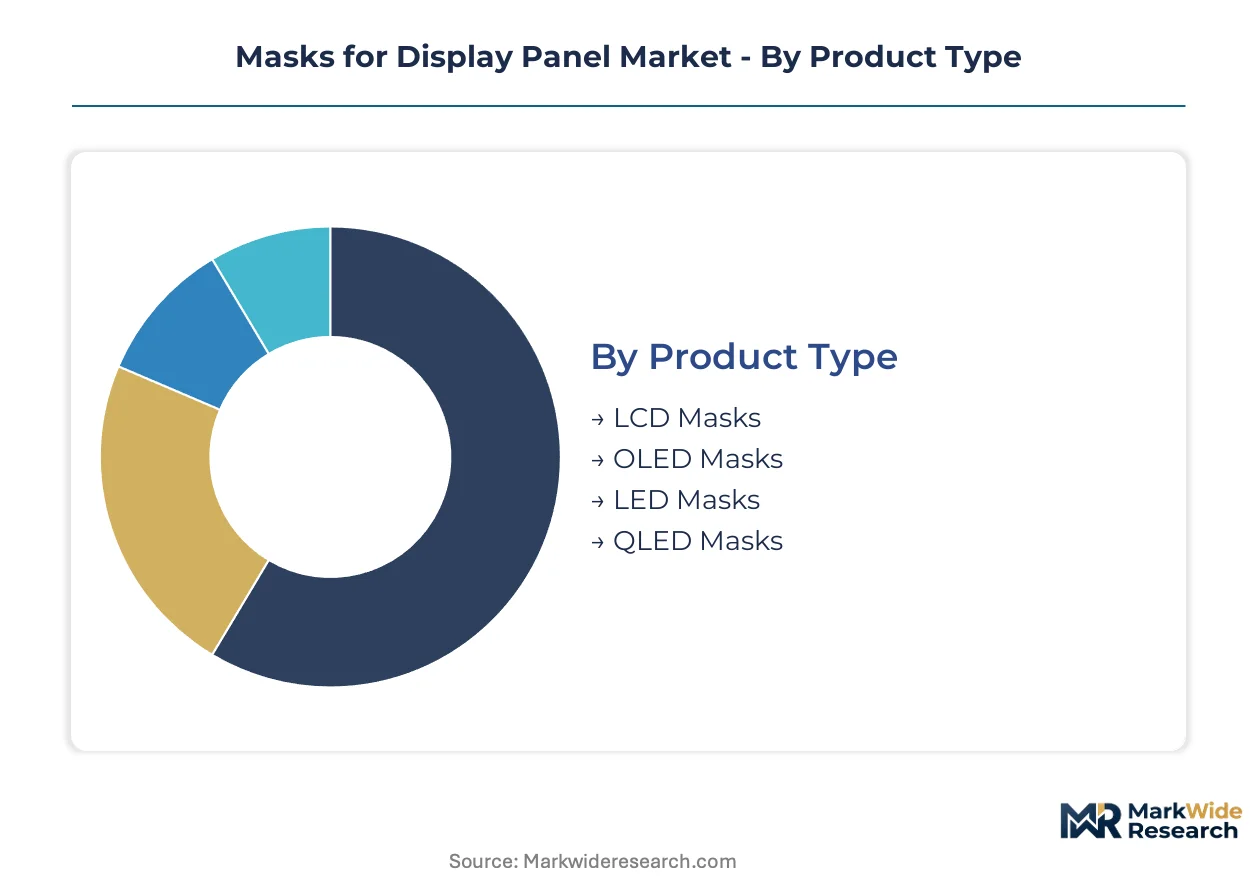
Photomask procurement strategies diverge sharply across display technologies and end-use specifications, forcing suppliers to maintain parallel qualification tracks for legacy LCD nodes alongside emerging MicroLED architectures. Understanding segment-level technical requirements illuminates where capital deployment and patterning expertise concentrate.
Product Type:
Standardization dominates commodity LCD mask production, while OLED and MicroLED categories demand extensive customization for multi-layer patterning and chiplet-scale geometries.
- OLED Masks:Multi-layer quartz substrates with chrome or molybdenum-silicon absorber stacks enable sub-micron pattern fidelity for foldable and high-refresh-rate panels. Samsung Display and LG Display near Seoul and Gumi concentrate procurement of attenuated phase-shift architectures as 500+ ppi density requirements tighten.
- LCD Masks:Single-layer chrome-on-quartz designs serve mature TFT backplane production with established patterning protocols and shorter qualification cycles. Volume demand clusters in China's panel manufacturing corridors where cost optimization overrides technical differentiation.
- LED Masks:Large-format patterning for direct-view LED video walls requires specialized aperture geometries distinct from pixel-array TFT masks.
- QLED Masks:Quantum dot color conversion layers demand intermediate precision between LCD and OLED specifications, with Samsung Display anchoring development investment.
Leading the category by volume: LCD Masks. Growing fastest: OLED Masks.
Application:
Automotive qualification timelines stretch 18-24 months longer than consumer electronics, creating distinct margin tiers across application segments.
- Smartphones:Foldable form factors and 120Hz+ refresh rates mandate sub-micron pattern fidelity that multi-layer phase-shift masks deliver. Procurement concentrates among South Korean and Chinese panel makers supplying Apple, Samsung Electronics, and domestic handset brands.
- Automotive Displays:Wide-temperature operation (-40°C to 85°C) and 15-year lifetime specifications require dedicated mask design categories with contamination protocols exceeding consumer-grade standards. German tier-one suppliers and Japanese automakers drive qualification requirements.
- Televisions:8K resolution roadmaps pull advanced mask sets into mainstream procurement for 65-inch+ panel formats.
- Monitors:Gaming-oriented high refresh rates overlap smartphone technical requirements at lower pattern density thresholds.
Highest margin capture: Automotive Displays. Steepest volume expansion: Smartphones.
Technology:
Equipment utilization rates diverge across technology tiers as electron-beam lithography capacity reallocates from mature nodes to emerging architectures.
- MicroLED:Chiplet-scale mass transfer demands stencil masks with asymmetric aperture geometries and sub-micron positional accuracy that incumbent suppliers are positioned to capture. Apple and Samsung Electronics investment timelines concentrate development resources.
- Flexible Displays:Polyimide substrate compatibility requires modified thermal expansion coefficients in mask blank specifications, constraining qualified supplier pools.
- Thin Film Transistors:Established amorphous and oxide semiconductor backplanes anchor volume production with standardized mask requirements.
- Touchscreen:In-cell and on-cell integration patterns add mask layers without fundamentally altering patterning equipment requirements.
Dominant volume position: Thin Film Transistors. Most rapid technology transition: MicroLED.
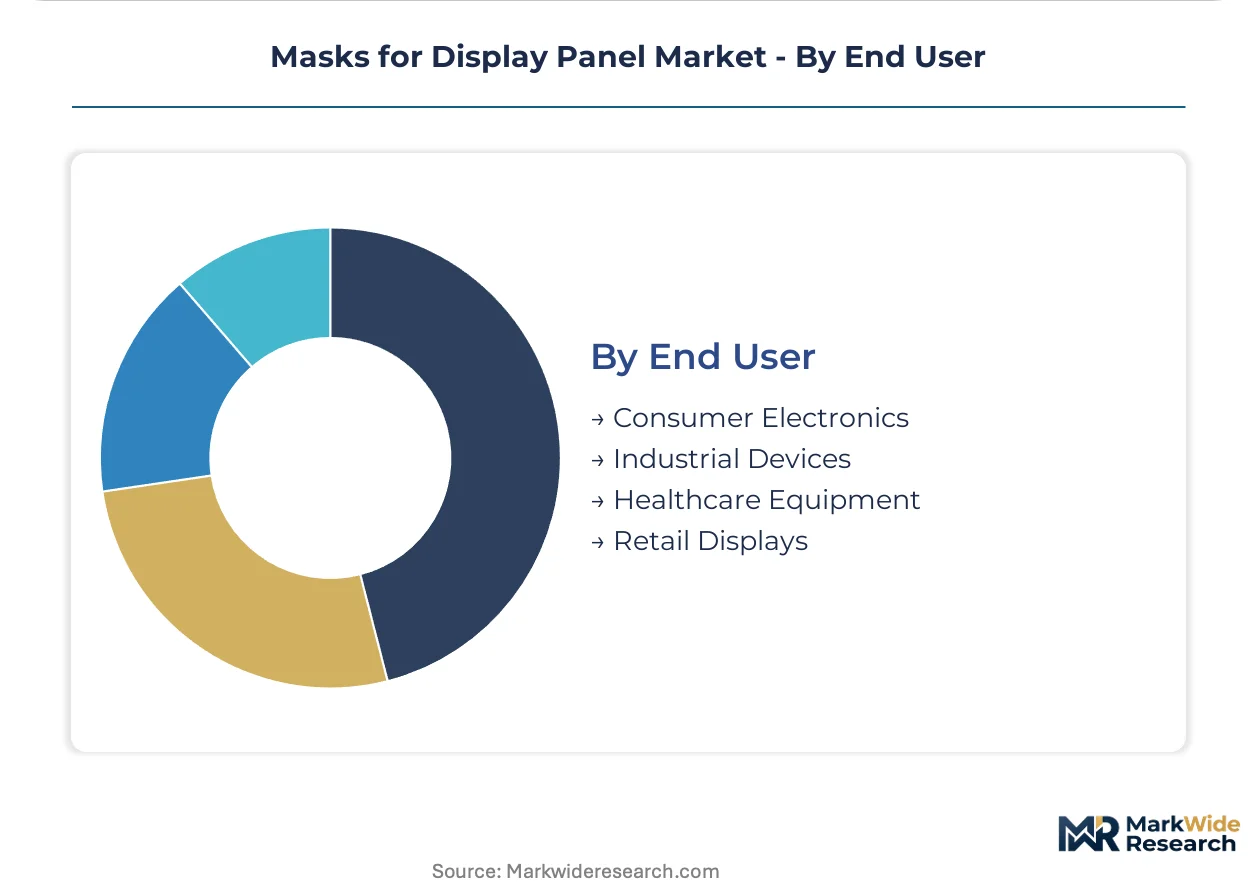
End User:
Certification burden and qualification protocol intensity separate industrial and healthcare segments from high-volume consumer electronics procurement.
- Consumer Electronics:Annual product cycles compress mask qualification timelines to 6-12 months, prioritizing supplier responsiveness over absolute defect density minima. South Korean and Chinese panel makers dominate procurement concentration.
- Healthcare Equipment:Diagnostic imaging displays require IEC 60601-1 electromagnetic compatibility compliance that extends mask qualification through system-level integration testing. Siemens Healthineers and Philips Medical Systems anchor specification development.
- Industrial Devices:Extended operating lifetime requirements (50,000+ hours) align mask specifications closer to automotive than consumer tiers.
- Retail Displays:High-brightness outdoor applications drive distinct aperture ratio optimization for sunlight readability.
Peak volume concentration: Consumer Electronics. Most stringent qualification barriers: Healthcare Equipment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
High-purity synthetic quartz blank production clusters in Japan's Hokkaido and Kyushu regions anchor the upstream material base for precision photomask manufacturing. Geographic concentration of electron-beam lithography equipment and Class 1 cleanroom infrastructure shapes competitive positioning across East Asian fabrication zones.
South Korea
Samsung Display and LG Display near Seoul and Gumi drive procurement of multi-layer phase-shift masks for foldable OLED panels. The country's MFDS enforces contamination control protocols that extend mask qualification timelines for automotive-grade specifications. Gumi's display cluster concentrates second-source vendor qualification activity under domestic supply chain resilience mandates.
Japan
METI technology roadmaps consolidate domestic mask industry capabilities through R&D subsidies targeting 500+ ppi density requirements. JIS standards harmonize qualification protocols across quartz substrate suppliers and patterning equipment makers. Hokkaido's synthetic quartz production facilities supply blank material to mask shops in Kyushu's semiconductor corridor.
China
Panel manufacturing corridors in Shenzhen and Beijing-Tianjin-Hebei pull LCD mask demand at cost-optimized specifications. MIIT industrial policies support localization of photomask supply chains for domestic display fabs. Shenzhen Qingyi Photomask anchors independent mask shop capacity serving tier-two panel makers.
Taiwan
CEA hazardous material handling regulations shape mask cleaning and substrate reclamation operations at precision manufacturing facilities. Taiwan Mask Corporation serves the island's TFT-LCD and touch sensor panel clusters. Kaohsiung's industrial zone concentrates environmental compliance infrastructure for quartz blank recycling services.
United States
Photronics Inc. maintains captive manufacturing footprints across multiple states to sustain delivery reliability for OLED mask customers. OSHA workplace safety standards intersect with semiconductor equipment handling protocols at electron-beam lithography facilities. Arizona and Texas host mask patterning operations serving North American display equipment OEMs.
Masks for Display Panel Market Competitive Landscape
Global majors compete with regional champions across patterning expertise and captive quartz blank supply. The vendor base organizes around three tiers: integrated photomask specialists with electron-beam lithography ownership, display-dedicated mask shops with OLED qualification depth, and emerging regional fabricators serving cost-sensitive LCD procurement. Strategic moves concentrate on dual-source qualification partnerships and multi-node capacity allocation.
Among Japan-based precision manufacturers, Dai Nippon Printing Co., Ltd. and Hoya Corporation exemplify the integrated specialist archetype combining proprietary patterning with substrate material control. Photronics Inc. represents the geographic diversification model with manufacturing presence across multiple continents. Taiwan Mask Corporation and Shenzhen Qingyi Photomask Ltd. occupy positions within the Asia-Pacific regional champion tier serving proximity-dependent procurement relationships.
| Leading Market Players |
|---|
| Photronics Inc. |
| Dai Nippon Printing Co., Ltd. |
| Hoya Corporation |
| Toppan Photomasks Inc. |
| LG Innotek Co., Ltd. |
| SK-Electronics Co., Ltd. |
| Taiwan Mask Corporation |
| Shenzhen Qingyi Photomask Ltd. |
| Darwin Microelectronic Co., Ltd. |
| Others |
Pricing and Supply Chain Analysis
Electron-beam lithography specialist concentration in Japan's Kyushu corridor and South Korea's Gumi cluster feeds labor-cost differentials that widen spreads between premium multi-layer phase-shift masks and economy-grade LCD alternatives. Buyers absorb these tier gaps through bundled qualification services that compress total cost of ownership for automotive and OLED-grade procurement.
Pricing Analysis
Warranty and metrology service bundling separates premium OLED mask vendors from unbundled commodity LCD suppliers. Three-tier pricing structure across premium, standard, and economy levels tracks certification grade and contamination protocol intensity. Cost compression in standard-tier LCD masks is intensifying because Chinese panel makers prioritize unit economics over pattern fidelity. Automotive display manufacturers exhibit the lowest price sensitivity due to 18-24 month qualification lock-in, while tier-two LCD fabs in Shenzhen corridors drive aggressive procurement negotiations.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale demand from Samsung Display and LG Display, while independent mask shops serve tier-two panel makers through distributor-mediated procurement. High-purity synthetic quartz blank production clusters in Japan's Hokkaido and Kyushu regions, with patterning equipment concentrated in South Korea and Taiwan. The supply chain draws from chrome and molybdenum-silicon absorber materials, photoresist chemistries, and electron-beam lithography systems. Single-source vulnerability in electron-beam tool supply creates capacity expansion bottlenecks regardless of downstream demand signals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a cost-of-compliance story where South Korea's MFDS contamination protocols and Japan's METI technology roadmaps erect barrier-to-entry moats that protect qualified incumbents from unqualified challengers.
For Market Incumbents: Extend captive quartz blank supply through backward integration into Hokkaido-region synthetic quartz production, securing substrate purity advantages as OLED resolution roadmaps tighten. Deepen second-source qualification partnerships with Gumi-based panel makers to defend against emerging Chinese mask shops exploiting MIIT localization subsidies. Electron-beam lithography talent scarcity represents the primary threat to capacity scaling. For New Entrants and Emerging Players: MicroLED chiplet transfer mask architectures offer a technology-first wedge into display supply chains where incumbent qualification depth remains underdeveloped. Target India's PLI-supported display manufacturing corridor for localized mask qualification before established vendors consolidate logistics capabilities. Lead with stencil design expertise for asymmetric aperture geometries rather than competing head-to-head in saturated OLED multi-layer segments. For Investors and Strategic Acquirers: Re-rating potential sits with independent mask shops possessing electron-beam lithography ownership and automotive-grade qualification depth given procurement's pivot toward dual-source contracting. Long-term viability favors vendors with demonstrated multi-node qualification overlap spanning legacy LCD, current OLED, and emerging MicroLED architectures. Watch South Korea's domestic supply chain resilience mandates as an inflection signal for second-source vendor volume allocation.| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Layer Phase-Shift Mask Qualification | Attenuated phase-shift architectures enable 500+ ppi densities for Samsung Display and LG Display roadmaps. |
| Second-Source Vendor Certification | Dual-qualified supply arrangements reduce disruption risk under South Korea's MFDS contamination protocols. |
| MicroLED Stencil Development | Asymmetric aperture geometries for chiplet mass transfer capture Apple and Samsung Electronics investment timelines. |
| Automotive Display Qualification | Wide-temperature specifications align mask vendors with German tier-one cockpit panel procurement. |
| Quartz Blank Backward Integration | Hokkaido-region synthetic quartz captive supply secures substrate purity for OLED-grade mask production. |
Research Methodology
Independent corroboration across mask shop operations directors, panel maker procurement leads, and electron-beam lithography equipment specialists underwrites the qualitative findings. Primary interviews with OLED fab qualification managers, automotive display specification engineers, and quartz substrate technical directors combined with secondary validation from MIIT industrial policy filings, METI technology roadmap disclosures, and MFDS contamination protocol documentation. Bottom-up mask production capacity modeling and top-down panel fabrication demand triangulation anchored volume estimates.
Historical reference periods spanning pre-pandemic baseline through post-supply-shock recovery established the forecast anchor for projection horizon calibration. Segmentation modeling across product type, application, technology, and end user dimensions incorporated node transition timelines and qualification protocol intensity differentials. CAGRs derived from equipment utilization rate trajectories and electron-beam lithography capacity expansion constraints. Industry-specific inputs included photomask layer counts per display generation and substrate reclamation yield rates.
Several conditions sit outside the modeled scope, including geopolitical trade restriction escalations, breakthrough lithography technology displacements, and synthetic quartz raw material supply disruptions. Forecasts reflect assumptions regarding node transition pacing and dual-source procurement adoption rates. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Display Technologies
Smart Privacy Glass Market
Display Technologies
Foldable Display Market
Display Technologies
Projector Screen Market
Display Technologies
Electronic Paper Display (EPD) Market
Display Technologies
PMOLED Display Market
Display Technologies
Global Medical Display Market
Display Technologies
4K Technology Market
Display Technologies
TFT LCD Panel Market
Display Technologies
Light Field Display Market
Display Technologies
Display Fingerprint Technology Market
Display Technologies
OLED Laptops Market
Display Technologies
Phosphor Screen Market
Display Technologies
Global 5K Display Resolution Market
Display Technologies
Advanced (3D/4D) Visualization Systems Market
Display Technologies
Global Display Controllers Market
Display Technologies
Electrochromic Window Market