
 PMOLED Display Market | 2026-2036
PMOLED Display Market Size, Share, and Industry Trends Forecast 2026-2036
PMOLED Display Market Analytics
High-brightness specification tiers is unwinding across the PMOLED Display Market as buyers in automotive and industrial segments reject legacy luminance thresholds. Samsung Electronics leverages its captive OLED material supply chain to dominate premium monochrome panel output for dashboard clusters. Visionox anchors China's domestic PMOLED capacity through specialized Gen-2.5 fabrication lines serving wearable OEMs.
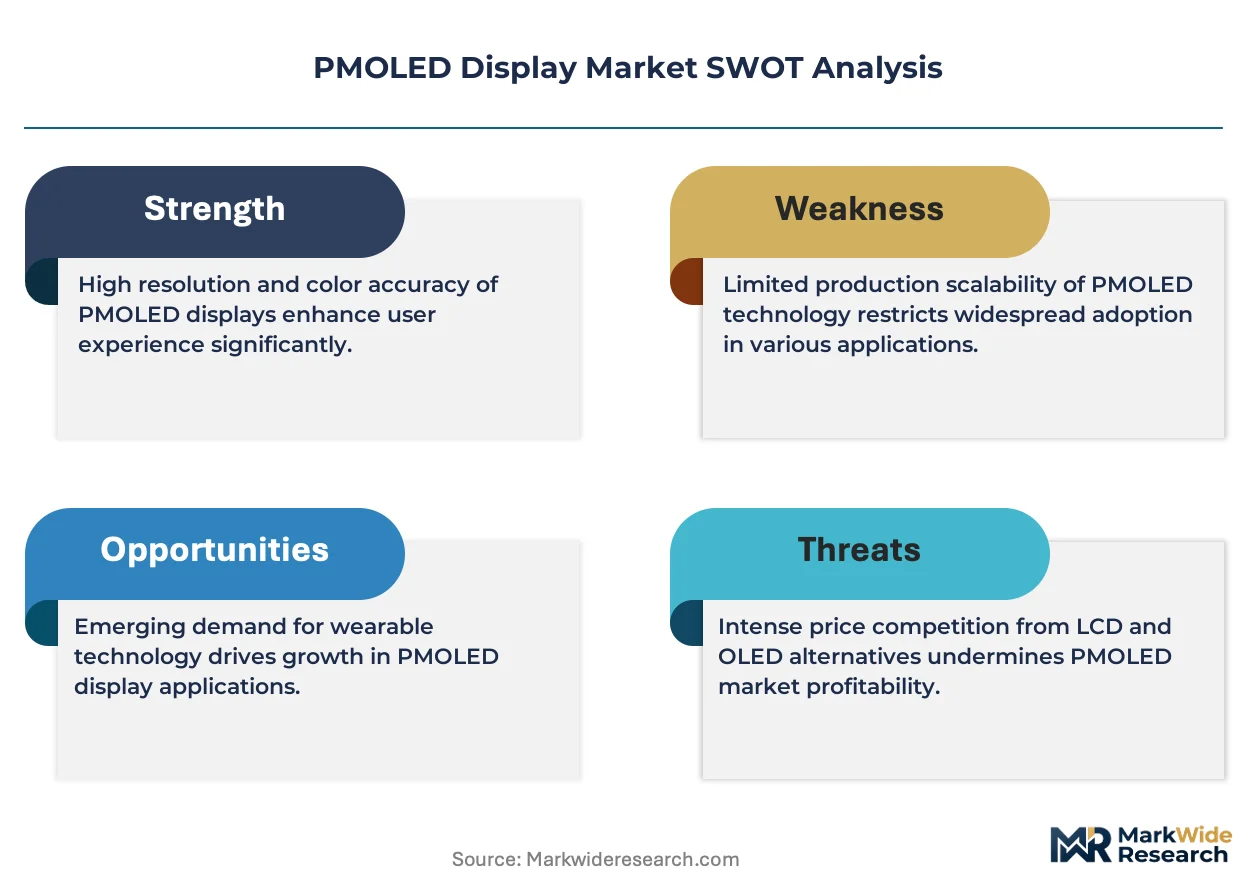
PMOLED displays employ organic electroluminescent layers arranged in a passive matrix configuration, with each pixel addressed by intersecting row and column electrodes rather than individual thin-film transistors, enabling sub-millimeter thickness and sub-milliwatt static power draw ideal for always-on secondary screens. The technology segment splits sharply: passive matrix architectures retain cost advantages in low-resolution status indicators, while thin-film encapsulation variants capture margin pools in medical and military applications requiring hermetic sealing. Flexible product types are expanding fastest as rollable deposition techniques mature, though transparent variants remain confined to novelty signage due to luminance trade-offs.
RoHS and REACH compliance in Europe restricts cadmium-based phosphorescent dopants, redirecting R&D toward thermally activated delayed fluorescence emitters. The EPA's emerging e-waste rules for display modules in the United States are pressuring brands to design for disassembly. China's GB standards on display energy efficiency, enforced by SAMR, shape product qualification for domestic procurement tenders. Stakeholders must track which regulatory jurisdiction moves first on mandating recycled substrate content, as this will reshape supplier qualification timelines and captive recycling investments.
Market Dynamics
Passive matrix OLED manufacturing is bifurcating between high-volume commodity production in East Asian clusters and precision medical-grade fabrication requiring hermetic thin-film encapsulation, with China's MIIT efficiency mandates accelerating this structural split.
Growth Catalysts
- Wearable Integration:Fitness bands and smartwatches demand sub-millimeter thickness profiles that only organic electroluminescent layers can deliver. Panel makers report order backlogs from health-monitoring device OEMs.
- RoHS Compliance:Europe's restriction on cadmium-based phosphorescent dopants redirects R&D budgets toward thermally activated delayed fluorescence emitters. Material suppliers are scaling TADF production lines.
- Automotive Dashboard Refresh:Tier-1 suppliers specify high-brightness monochrome panels for instrument clusters. South Korean fabs have dedicated Gen-2.5 lines to serve this qualified supplier base.
Market Restraints
- Input Concentration:High-purity organic vapor deposition precursors source from a narrow German and Japanese chemical supplier base. Price volatility in indium tin oxide targets constrains electrode cost forecasting.
- Technical Ceiling:Passive matrix addressing limits resolution scalability above 128x64 pixels without unacceptable crosstalk. Active matrix alternatives capture applications requiring finer pitch.
- Substitution Pressure:Reflective LCD and memory-in-pixel technologies improve sunlight readability. Outdoor signage buyers increasingly specify these alternatives despite power trade-offs.
Strategic Opportunities
- Medical Hermetic Sealing:Implantable and sterilizable display applications require thin-film encapsulation variants that command 3-4x standard panel margins. FDA qualification pathways for biocompatible substrates remain underpenetrated.
- India PLI Scheme:The country's production-linked incentive framework for electronic components subsidizes display module assembly. Contract manufacturers are qualifying local supply chains for wearable OEM export programs.
- Transparent Deposition:Roll-to-roll manufacturing of see-through PMOLED substrates enables automotive HUD integration. German Tier-1s are prototyping windshield-embedded indicator layers.
Industry Challenges
- Thin-Film Encapsulation Talent:Atomic layer deposition specialists command premium compensation. Fabs in Taiwan and South Korea compete for the limited pool of barrier-layer process engineers.
- Multi-Jurisdiction Certification:Medical displays require simultaneous FDA 510(k), MDR CE marking, and NMPA registration. Parallel submission timelines extend product launch windows by 14-18 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | PMOLED Display Market |
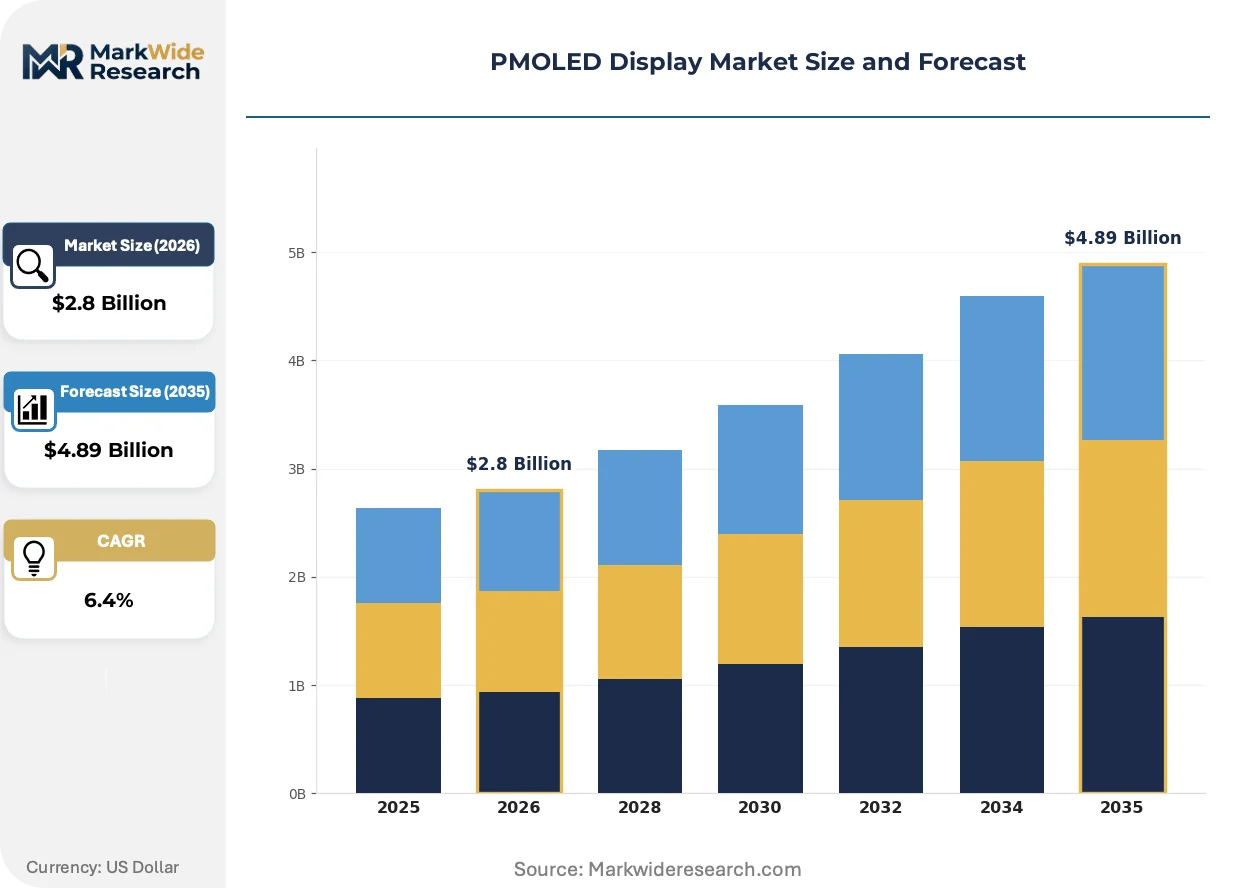
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.89 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Monochrome, Color, Transparent, Flexible Technology: Passive Matrix, Active Matrix, Organic Light Emitting Diode, Thin Film End User: Consumer Electronics, Automotive Displays, Wearable Devices, Industrial Equipment Application: Smartphones, Televisions, Digital Signage, Smart Wearables |
| Companies Covered | Samsung Electronics, Visionox, Sony Corporation, Panasonic, LG Display, US Micro Products, Japan Display, RaystarOptronics, Accelopment, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
PMOLED Display Market Evolving Landscape
Organic vapor deposition techniques are maturing toward rollable formats, while regulatory pressure on hazardous substances and buyer consolidation in automotive are compressing supplier qualification timelines.
Thermally activated delayed fluorescence emitter chemistry is bifurcating the material supply base. Automotive and medical buyers specify TADF-based panels for their extended operational lifespans without rare-earth dopants. This chemistry is displacing phosphorescent alternatives in premium monochrome segments and compressing margins for legacy material suppliers.
China's GB display energy efficiency standards, enforced by SAMR, now mandate power-draw testing for panels above 1-inch diagonal. Domestic procurement tenders disqualify non-compliant suppliers. Korean and Taiwanese exporters are redesigning driver IC architectures to meet these thresholds for government wearable contracts.
Automotive OEMs now require 10-year supply guarantees for dashboard components. This procurement pattern concentrates panel awards among fabs with captive substrate production and multi-year material stockpiling programs. German and Japanese automakers are most aggressive in enforcing these qualification requirements.
PMOLED Display Market Segmentation
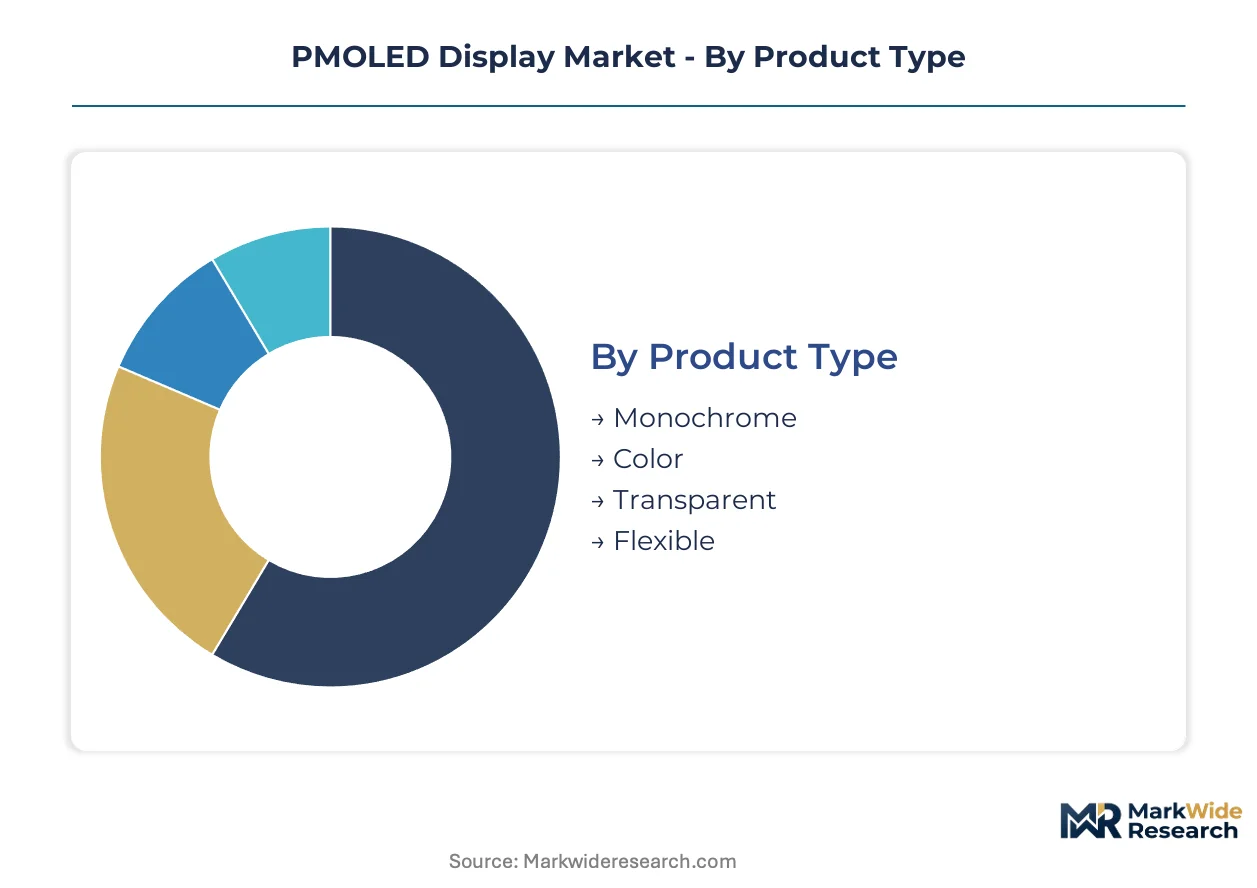
PMOLED display procurement channels diverge sharply by segment. Medical and military buyers source through qualified supplier programs with multi-year qualification timelines, while consumer electronics OEMs leverage contract manufacturers for high-volume commodity panels.
Product Type:
Channel mix varies dramatically across product types. Monochrome panels flow through automotive Tier-1 supplier networks with strict qualification protocols. Flexible variants route through medical device OEMs and specialized wearable manufacturers requiring custom form factors.
- Monochrome:Single-color organic electroluminescent layers dominate automotive instrument clusters and industrial status indicators. South Korean fabs capture the bulk of Tier-1 automotive procurement through dedicated Gen-2.5 production lines. Demand concentrates in dashboard refresh programs where 10-year supply guarantees are now standard.
- Flexible:Rollable deposition techniques enable sub-millimeter bend radii for fitness bands and curved medical interfaces. Wearable OEMs in Taiwan and South Korea drive order backlogs as health-monitoring device specifications tighten thickness requirements. TADF emitter chemistry extends operational lifespan for premium wearable contracts.
- Color:RGB pixel arrangements serve novelty signage and consumer secondary displays with limited resolution scalability.
- Transparent:See-through substrates remain confined to automotive HUD prototyping and architectural installations due to luminance trade-offs in daylight conditions.
By volume, Monochrome leads. By growth pace, Flexible is expanding most quickly.
Technology:
Cost tiers separate technology adoption. Passive matrix architectures occupy the economy tier for low-resolution applications. Thin-film encapsulation variants command premium pricing for hermetic sealing requirements in implantable medical devices.
- Passive Matrix:Intersecting row and column electrodes address pixels without individual thin-film transistors, minimizing cost and power draw for always-on secondary screens. Consumer electronics OEMs specify these for basic status indicators in appliances and low-end wearables. MIIT efficiency standards in China are pushing manufacturers toward higher-yield organic vapor deposition processes for this segment.
- Thin Film:Atomic layer deposition creates hermetic barrier layers enabling sterilizable and implantable display applications. Medical device manufacturers pay 3-4x standard panel margins for FDA-qualifiable biocompatible substrates. Taiwan and South Korean fabs compete aggressively for the limited pool of barrier-layer process engineers.
- Active Matrix:Individual TFT addressing enables higher resolution but at cost points that push applications toward AMOLED alternatives.
- Organic Light Emitting Diode:The foundational electroluminescent technology spans all PMOLED architectures, with material chemistry bifurcating between phosphorescent legacy supply and TADF-based premium segments.
Passive Matrix captures the highest shipment volumes. Thin Film delivers the steepest margin expansion trajectory.
End User:
Application requirements dictate customer type concentration. Automotive and medical buyers enforce the longest qualification timelines. Industrial equipment purchasers prioritize supply continuity over technical advancement.
- Automotive Displays:Dashboard cluster specifications demand high-brightness monochrome panels with decade-long supply guarantees. German and Japanese automakers enforce the most aggressive qualification requirements, concentrating awards among fabs with captive substrate production. SAMR energy efficiency standards in China now shape procurement for government fleet contracts.
- Wearable Devices:Fitness bands and smartwatches require sub-millimeter thickness profiles that only organic electroluminescent layers deliver. Health-monitoring device OEMs report order backlogs as brands integrate always-on secondary screens. Visionox anchors domestic Chinese capacity through specialized Gen-2.5 fabrication lines.
- Consumer Electronics:Appliance and peripheral manufacturers specify basic PMOLED indicators for power and connectivity status.
- Industrial Equipment:Manufacturing and instrumentation buyers favor proven passive matrix architectures for reliability in harsh operating environments.
Automotive Displays generate the largest contract values. Wearable Devices are climbing the fastest as health-monitoring adoption accelerates.
Application:
Volume scale separates application tiers. Smartphones and televisions represent massive unit opportunities but face active matrix substitution pressure. Digital signage and smart wearables occupy specialized niches with distinct technical requirements.
- Smart Wearables:Fitness bands and smartwatches drive the most intense demand for flexible, low-power secondary displays. Panel makers report qualified supplier status with major wearable OEMs requires 18-24 month certification cycles. India's PLI scheme for electronic components is subsidizing local assembly capacity for export programs.
- Digital Signage:Indoor and semi-outdoor installations specify PMOLED for thin profiles and wide viewing angles. Transparent variants serve novelty architectural applications despite sunlight readability limitations. Reflective LCD alternatives capture outdoor signage buyers despite power trade-offs.
- Smartphones:Secondary notification displays and foldable cover screens represent limited PMOLED penetration against AMOLED dominance.
- Televisions:Near-zero PMOLED presence due to resolution and brightness requirements favoring active matrix alternatives.
Smart Wearables lead by volume momentum. Digital Signage offers the most stable margin profile for qualified suppliers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Panel fabrication ecosystems concentrate in East Asian manufacturing clusters, with South Korean and Taiwanese fabs commanding qualified supplier status for automotive and medical applications. China's domestic capacity expansion reshapes procurement patterns for wearable OEMs.
South Korea
Samsung Electronics dominates premium monochrome panel output for automotive dashboard clusters through captive OLED material supply chains. The country's national technology regulator enforces display efficiency benchmarks that align with MIIT standards. Seoul Capital Area fabrication lines dedicate Gen-2.5 capacity to serve German and Japanese automaker qualification programs.
Taiwan
Specialized foundries compete aggressively for thin-film encapsulation process engineers supporting medical-grade hermetic sealing applications. The island's industrial development authority subsidizes barrier-layer R&D for implantable display substrates. Hsinchu Science Park anchors precision fabrication capacity serving FDA-qualifiable biocompatible panel demand.
China
Visionox anchors domestic PMOLED capacity through specialized Gen-2.5 fabrication lines targeting wearable OEM export programs. SAMR enforces GB standards on display energy efficiency that disqualify non-compliant suppliers from government procurement tenders. Yangtze River Delta manufacturing clusters scale TADF emitter production lines to meet RoHS-aligned material requirements.
Japan
Panasonic and Japan Display occupy positions in industrial and medical display segments requiring extended operational lifespans. METI efficiency mandates shape domestic procurement for automotive and instrumentation applications. Kyushu fabrication facilities concentrate on high-reliability passive matrix architectures for harsh environment deployments.
United States
US Micro Products represents domestic assembly capacity for specialized industrial and military display applications. EPA emerging e-waste rules pressure brands to design for disassembly in display modules. California-based health-monitoring device OEMs drive order backlogs for sub-millimeter flexible panel specifications.
PMOLED Display Market Competitive Landscape
Concentration sits with diversified electronics conglomerates possessing captive material supply chains and multi-year substrate stockpiling programs. The competitive structure splits between high-volume commodity producers serving consumer electronics and precision fabricators qualified for medical hermetic sealing. Three archetypes dominate: vertically integrated display divisions of Korean chaebol, Chinese state-supported panel specialists, and Japanese industrial electronics conglomerates. Capacity expansion and strategic partnerships constitute the dominant competitive moves, with automotive 10-year supply guarantee requirements favoring fabs with in-house substrate production.
Among Korean-based fabricators, Samsung Electronics exemplifies the diversified conglomerate archetype through its integrated OLED material operations. Visionox occupies a position within the state-supported specialist tier serving domestic wearable OEM demand. Japanese industrial conglomerates Panasonic and Japan Display represent the precision fabrication archetype for medical and instrumentation segments. Sony Corporation anchors the premium consumer electronics vector despite limited PMOLED-specific exposure.
| Leading Market Players |
|---|
| Samsung Electronics |
| Visionox |
| Sony Corporation |
| Panasonic |
| LG Display |
| US Micro Products |
| Japan Display |
| RaystarOptronics |
| Accelopment |
| Others |
Value Network & Pricing Analysis
GB standards on display energy efficiency enforced by SAMR gate both supplier qualification and price differentiation simultaneously, compressing margin pools for non-compliant producers while rewarding fabs with in-house TADF emitter chemistry. Automotive OEMs now enforce 10-year supply guarantees that concentrate procurement awards among vertically integrated manufacturers with multi-year substrate stockpiling programs.
Pricing Analysis
GB standards dictate the pricing tier structure across the PMOLED Display Market, separating qualified suppliers for government procurement from commodity producers serving consumer electronics. Pricing stratifies across medical hermetic sealing, automotive high-brightness monochrome, and economy passive matrix tiers. Cost compression in standard monochrome panels is intensifying because Korean and Taiwanese fabs compete for limited automotive qualification slots. Consumer electronics OEMs exhibit the highest price sensitivity, while medical device manufacturers accept 3-4x premiums for FDA-qualifiable biocompatible substrates.
Supply Chain Analysis
Taiwan and South Korea anchor precision fabrication for thin-film encapsulation and automotive-grade monochrome output. German and Japanese chemical suppliers dominate high-purity organic vapor deposition precursors. Indium tin oxide targets for electrodes draw from concentrated East Asian sputtering operations. Single-source vulnerability in TADF emitter chemistry creates exposure as RoHS compliance redirects material demand. Distribution runs through automotive Tier-1 supplier networks for qualified panels and contract manufacturers for wearable commodity volumes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among automotive OEMs and medical device manufacturers, with procurement consolidation around decade-long supply guarantees and multi-jurisdiction certification requirements reshaping supplier viability thresholds.
For Market Incumbents: Shield qualification status by deepening captive OLED material supply chains and securing atomic layer deposition talent pools before Taiwan and South Korean fabs exhaust the limited barrier-layer engineer base. Defend against reflective LCD substitution in outdoor signage by accelerating TADF chemistry roadmaps for extended operational lifespan guarantees. Prioritize SAMR pre-certification for GB energy efficiency standards to maintain access to Chinese government wearable procurement. For New Entrants and Emerging Players: Anchor in India's PLI-subsidized electronic component assembly corridors to serve wearable OEM export programs with lower qualification barriers than automotive or medical tiers. Target transparent deposition prototyping for automotive HUD integration where German Tier-1s seek alternative suppliers beyond established Korean relationships. Pursue sterilizable thin-film encapsulation for implantable medical applications as the most penetrable premium segment with underdeveloped FDA qualification pathways. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across thin-film encapsulation variants as atomic layer deposition equipment and barrier-layer R&D consume disproportionate cash flow versus commodity passive matrix output. Favor acquisition targets with existing FDA 510(k) submission experience and SAMR GB standard compliance to compress 14-18 month multi-jurisdiction certification timelines. Watch for MIIT efficiency mandate acceleration as the signal indicating which material chemistry investments will capture displaced phosphorescent dopant demand.| Strategic Initiative | Industry Significance |
|---|---|
| TADF Emitter Production Scale-Up | RoHS-aligned chemistry redirects R&D budgets away from cadmium-based phosphorescent dopants toward thermally activated delayed fluorescence lines. |
| Thin-Film Encapsulation Talent Acquisition | Barrier-layer process engineers command premium compensation as Taiwan and South Korean fabs compete for atomic layer deposition specialists. |
| Automotive Qualification Program Investment | Gen-2.5 fabrication lines dedicated to German and Japanese OEM requirements capture decade-long supply guarantee contracts. |
| India PLI Scheme Localization | Production-linked incentive frameworks subsidize display module assembly for wearable OEM export programs. |
| GB Standard Pre-Certification | SAMR energy efficiency testing mandates for panels above 1-inch diagonal shape procurement eligibility for government tenders. |
Research Methodology
Desk research of customs trade data, SEC filings from diversified electronics conglomerates, and MIIT efficiency standard documentation preceded structured interviews with panel fabrication executives, automotive Tier-1 procurement leads, medical device regulatory affairs directors, and TADF material supplier technical R&D heads. Primary fieldwork combined with secondary validation from SAMR enforcement bulletins and FDA 510(k) submission databases. Bottom-up shipment estimates by product type and technology tier underwent triangulation against top-down value projections derived from automotive contract value disclosures.
Variance decomposition across the projection horizon isolates volume, price, and mix contributions to value expansion. Segmentation dimensions modeled include product type flexibility, encapsulation technology tier, end-use application requirements, and regional regulatory cluster alignment. CAGRs emerged from logistic diffusion curves fitted to wearable integration adoption patterns and automotive dashboard refresh cycles. Industry-specific forecast inputs incorporate TADF chemistry yield improvements and MIIT efficiency threshold enforcement timelines.
Decision-makers should treat outputs as directional under assumptions of sustained automotive 10-year supply guarantee requirements and stable RoHS enforcement trajectories; material deviation in indium tin oxide price volatility or REACH expansion to additional dopant classes would warrant model refresh. Recalibration cycles align with material shifts in SAMR GB standard revision schedules and FDA biocompatible substrate guidance updates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Display Technologies
Next Generation 3D Display Market
Display Technologies
Flat Panel Display (FPD) Market
Display Technologies
Head Up Display Market
Display Technologies
OLED Microdisplay Market
Display Technologies
Large Industrial Displays Market
Display Technologies
Global Medical Display Market
Display Technologies
Holographic Display Market
Display Technologies
Industrial Display Market
Display Technologies
Flexible Display Market
Display Technologies
Wireless Display Market
Display Technologies
Touch Screen Module Market
Display Technologies
AMOLED Display Market
Display Technologies
Global OLED Market
Display Technologies
Plasma Display Module Market
Display Technologies
Phosphor Screen Market
Display Technologies
Global Display Market