
 Resistive Touchscreen Market | 2026-2036
Resistive Touchscreen Market Size, Share, and Industry Trends Forecast 2026-2036
Resistive Touchscreen Market Insights
Southeast Asia is reconfiguring its role in resistive touchscreen supply chains as Vietnam and Thailand expand cleanroom assembly capacity for industrial-grade panels. Fujitsu sustains its technology leadership in analog resistive architectures for medical equipment interfaces. Elo Touch Solutions dominates the North American point-of-sale channel through specialized distribution partnerships. SCHURTER anchors European demand with precision-engineered industrial control panels certified to IEC standards.
A resistive touchscreen registers input through mechanical pressure that compresses two conductive layers—typically indium tin oxide-coated polyester and glass substrates separated by micro-dot spacers—completing a circuit at the contact point to deliver coordinate data to a controller. This architecture tolerates gloved operation, moisture exposure, and stylus precision, making it indispensable for factory floors, healthcare settings, and outdoor kiosks where capacitive alternatives fail. Industrial Panels command the deepest margin pools due to extended qualification cycles and long-term supply agreements, while Medical Devices represents the fastest-growing end-user category as diagnostic equipment manufacturers replace mechanical switches with sealed touch interfaces. Analog Resistive technology still occupies the largest volume share, though Digital Resistive variants are gaining traction in gaming machine applications requiring faster response times.
The US FDA regulates touchscreen interfaces in medical devices through 510(k) clearance pathways that validate biocompatibility and electromagnetic compatibility, while the EU MDR imposes stricter clinical evidence requirements on patient-facing touch controls. China's GB standards mandate electromagnetic interference testing for industrial panel imports, creating compliance friction for non-domestic suppliers. Stakeholders must monitor how RoHS exemptions for legacy industrial equipment reshape material substitution timelines and sourcing strategies.
Market Dynamics
Industrial automation buyers in Germany and Japan are expanding orders for analog resistive panels, tightening supply for qualified suppliers while REACH compliance in the European Union forces material disclosure revisions across conductive coating formulations.
Growth Catalysts
- Industrial automation expansion:Factory floor digitization in Germany and Japan sustains demand for gloved-operation panels. Automotive assembly lines specify resistive interfaces for paint-shop environments.
- EU MDR compliance pathways:Stricter clinical evidence requirements on patient-facing touch controls accelerate replacement of mechanical switches with sealed resistive interfaces in diagnostic equipment.
- East Asian manufacturing concentration:Shenzhen and Taipei clusters achieve scale economies in cleanroom assembly, lowering unit costs for industrial-grade panels exported to North American and European OEMs.
Market Restraints
- Indium supply concentration:Indium tin oxide coatings depend on refining capacity concentrated in Chinese state-controlled enterprises, exposing panel makers to input volatility and export license friction.
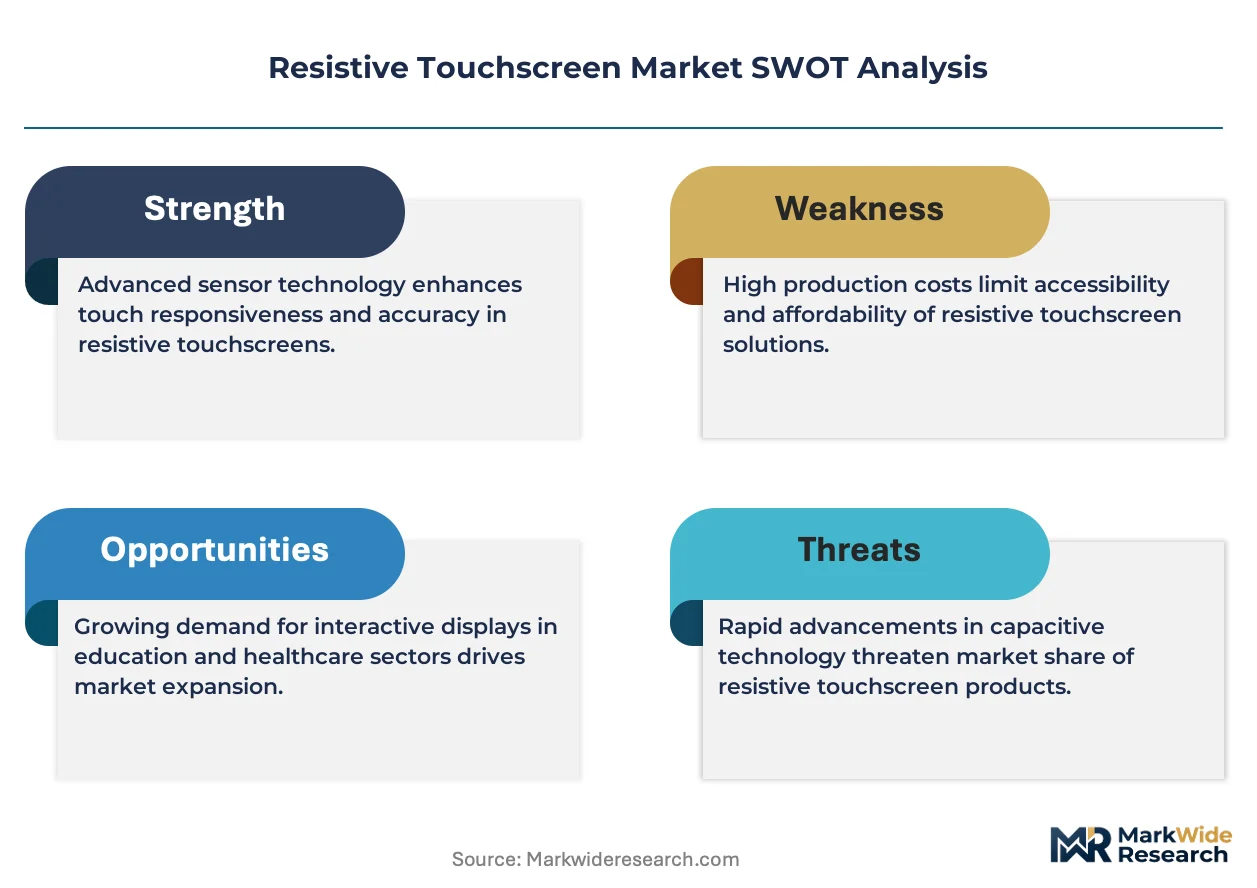
- Capacitive substitution in consumer segments:Projected capacitive touch modules erode resistive share in retail kiosks and hospitality terminals where glove compatibility is non-critical.
- RoHS exemption uncertainty:Pending European Commission decisions on legacy industrial equipment exemptions force premature material substitution investments before regulatory clarity emerges.
Strategic Opportunities
- Vietnam and Thailand cleanroom expansion:Southeast Asian governments offer tax holidays for precision assembly investments, enabling tariff-advantaged export platforms for US and EU industrial customers.
- Digital resistive gaming applications:Casino and amusement machine manufacturers specify faster-response digital variants for high-frequency touch environments, opening premium pricing tiers.
- China GB standard alignment:Electromagnetic interference certification for industrial panel imports creates first-mover advantage for suppliers achieving dual IEC-GB compliance.
Industry Challenges
- Controller firmware integration:Legacy PLC systems in installed industrial bases require custom driver development, extending sales cycles and straining application engineering teams.
- Micro-dot spacer precision:Sub-50-micron tolerance control in polyester-glass lamination demands capital-intensive optical inspection equipment that mid-tier assemblers struggle to finance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Resistive Touchscreen Market |
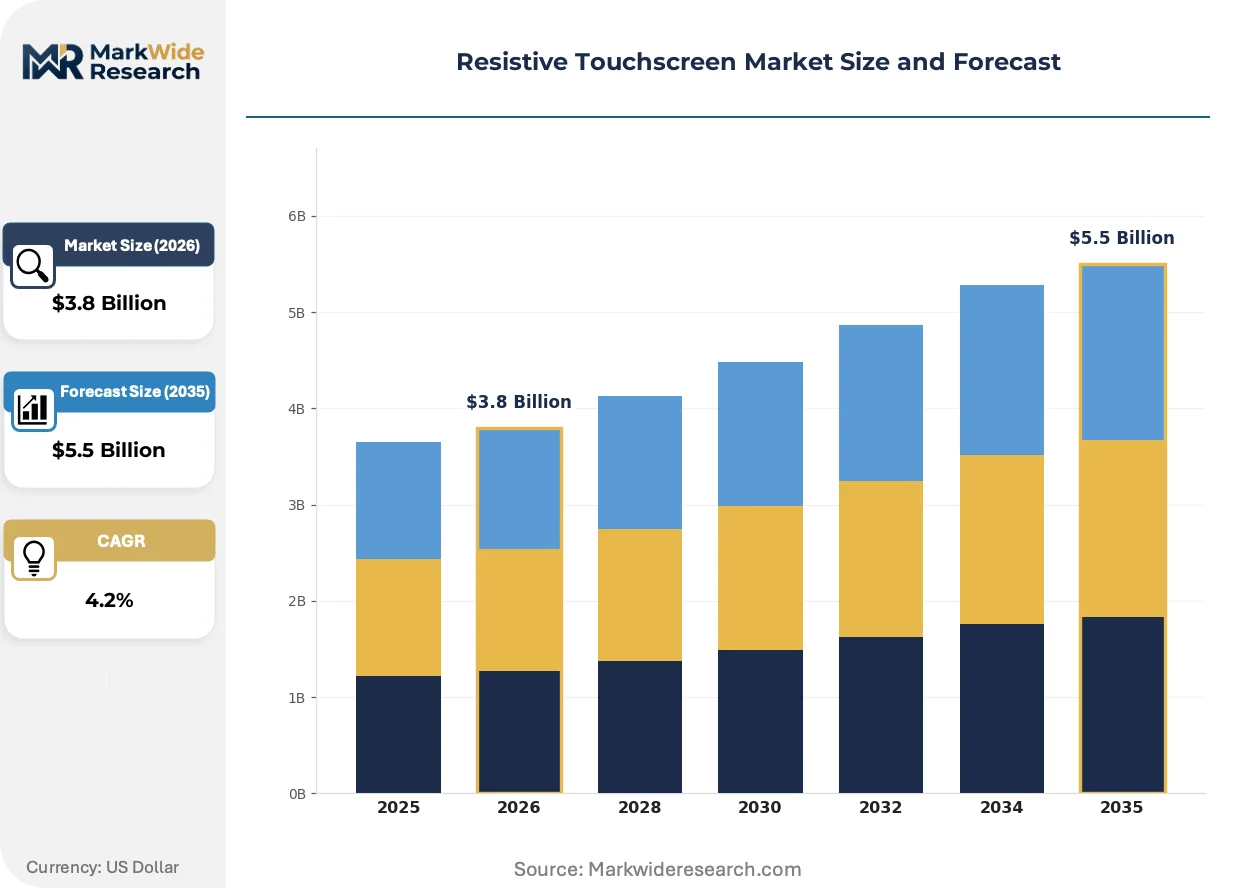
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.5 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Embedded Touchscreens, Custom Displays, Medical Devices, Industrial Panels Technology: Analog Resistive, Digital Resistive, Multi-Touch, Single-Touch End User: Consumer Electronics, Healthcare Equipment, Automotive, Industrial Automation Application: Point of Sale, Kiosks, Gaming Machines, Home Appliances |
| Companies Covered | AMT, MILDEX OPTICAL INC, Fujitsu, 3M Company, Elo Touch Solutions, STMicroelectronics, SCHURTER, Touch International, Rohm Semiconductor, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Resistive Touchscreen Market Trends and Innovations
Resistive touchscreen architecture is bifurcating into precision industrial variants and cost-optimized commercial tiers, with manufacturing process innovation and regulatory pressure as the dominant change vectors.
Multi-layer digital resistive stacks are digitizing coordinate detection through matrix-based scanning rather than analog voltage gradient measurement. Gaming machine OEMs in Nevada and Macau specify these variants for sub-10-millisecond response requirements. The technology is digitizing performance benchmarks that analog architectures cannot meet, compressing analog share to price-sensitive utility applications.
REACH Article 33 disclosure obligations are tightening supply chain documentation burdens for conductive coating suppliers. ECHA enforcement actions against incomplete SVHC declarations have triggered third-party audit requirements. Medical device contract manufacturers in Ireland and the Netherlands are responding by qualifying alternative silver nanowire formulations that reduce indium dependence.
Buyers in North American point-of-sale channels are consolidating vendor relationships around distributors offering bonded inventory and same-day replacement programs. Specialized channel partners with in-house controller programming capabilities are displacing direct procurement from panel manufacturers. This consolidation is most visible among quick-service restaurant chains upgrading drive-thru kiosks across the US Southeast and Midwest.
Resistive Touchscreen Market Segmentation
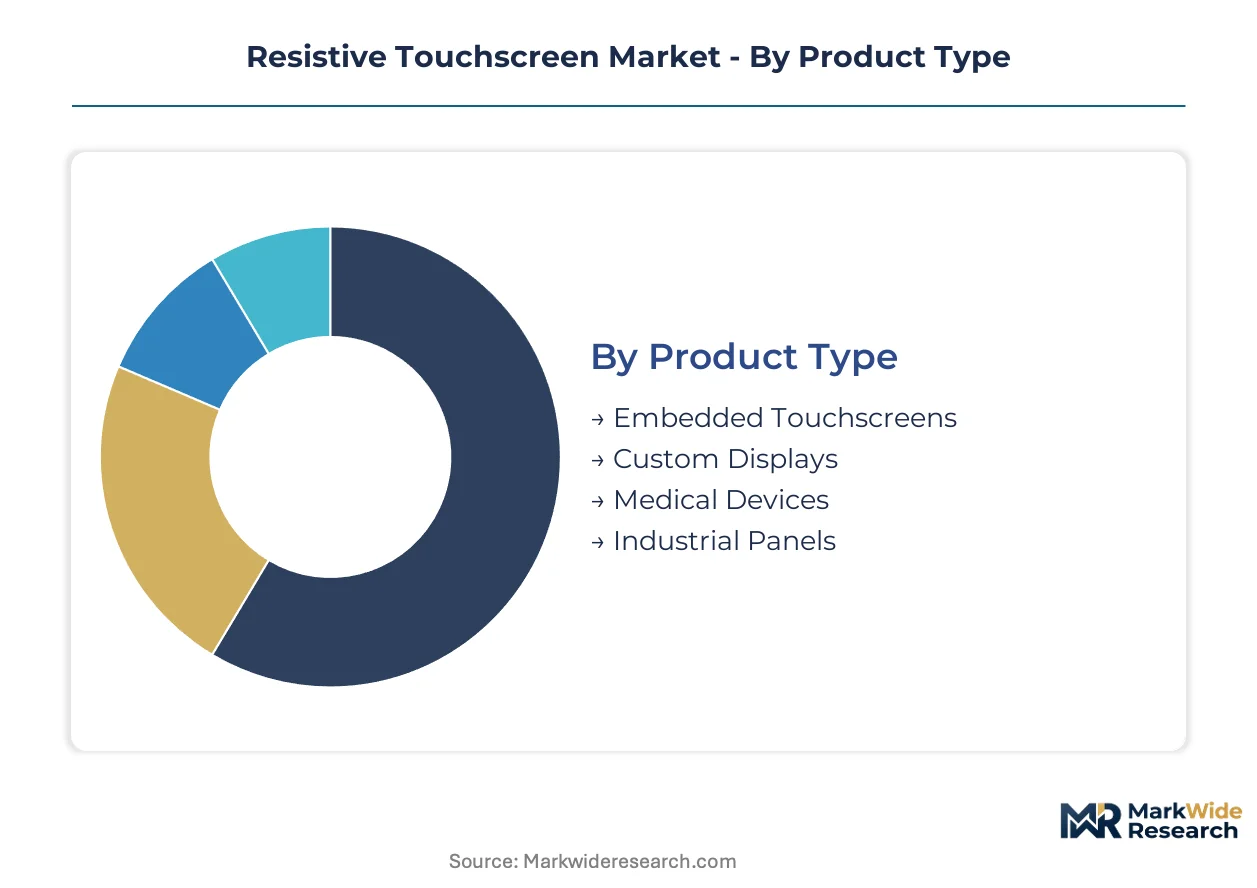
Resistive touchscreen segmentation reveals how pressure-sensitive input architectures diverge across precision requirements, regulatory exposure, and operational environments. Product maturity varies sharply between legacy analog formats and emerging digital variants, with end-use certification demands reshaping supplier portfolios.
Product Type:
Mature industrial formats coexist with emerging medical specializations as qualification cycles and margin structures diverge across application tiers.
- Industrial Panels:Ruggedized polyester-glass laminates withstand chemical exposure, vibration, and temperature cycling in factory automation environments. German and Japanese automotive paint shops specify these interfaces for gloved-operator compatibility, locking in multi-year supply agreements with extended qualification timelines.
- Medical Devices:Sealed resistive architectures replace mechanical switches in diagnostic equipment, driven by EU MDR clinical evidence requirements for patient-facing controls. Irish and Dutch contract manufacturers are qualifying silver nanowire formulations to reduce indium dependence while maintaining biocompatibility.
- Embedded Touchscreens:Integrated controller-processor combinations streamline OEM integration for mid-volume equipment builders.
- Custom Displays:Bespoke form factors serve specialized industrial machinery with non-standard aspect ratios or mounting configurations.
Industrial Panels handle the majority of throughput; Medical Devices is expanding most quickly on share.
Technology:
Cost tier separation between established voltage-gradient measurement and premium matrix-scanning architectures reflects response-time demands across customer segments.
- Analog Resistive:Voltage gradient detection across ITO-coated substrates delivers coordinate data through mechanical pressure compression. Factory floors in Germany and Japan sustain demand for this mature architecture, though indium supply concentration in Chinese state-controlled refiners creates input volatility exposure.
- Digital Resistive:Matrix-based scanning digitizes coordinate detection for sub-10-millisecond response requirements. Gaming machine OEMs in Nevada and Macau specify these variants for high-frequency touch environments, commanding premium pricing tiers unavailable to analog suppliers.
- Single-Touch:Basic pressure-activated input serves cost-optimized commercial applications where multi-point detection is unnecessary.
- Multi-Touch:Two-point detection capability addresses limited gesture requirements in industrial human-machine interfaces.
Analog Resistive dominates current volume; Digital Resistive is gaining share fastest in premium segments.
End User:
Application concentration varies by customer type, with healthcare procurement patterns diverging sharply from industrial automation purchasing behavior.
- Industrial Automation:Gloved-operation panels integrate with legacy PLC systems on automotive assembly lines and process control environments. Controller firmware integration challenges extend sales cycles, but long-term agreements with German and Japanese buyers protect margin pools.
- Healthcare Equipment:Diagnostic device manufacturers replace mechanical switches with sealed touch interfaces to satisfy FDA 510(k) biocompatibility and electromagnetic compatibility pathways. EU MDR stricter clinical evidence requirements accelerate this substitution in European markets.
- Consumer Electronics:Limited resistive penetration as capacitive alternatives dominate handheld and portable applications.
- Automotive:Paint-shop and assembly-line environments specify resistive interfaces where moisture and chemical exposure would compromise capacitive performance.
Industrial Automation commands the deepest margin pools; Healthcare Equipment shows the steepest expansion trajectory.
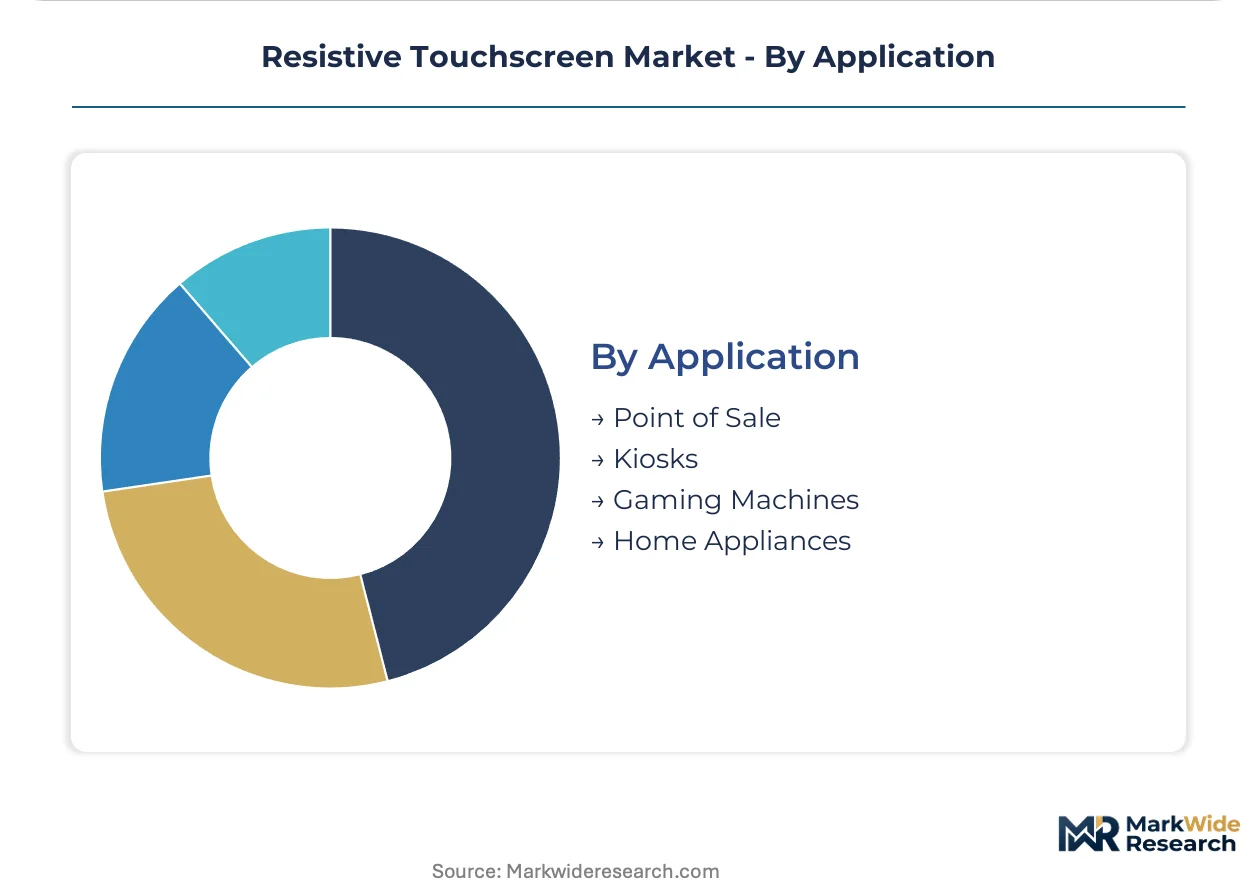
Application:
Geography and channel structure differentiate application segments, with North American point-of-sale consolidation contrasting Asian manufacturing concentration.
- Point of Sale:Quick-service restaurant drive-thru kiosks across the US Southeast and Midwest consolidate vendor relationships around distributors offering bonded inventory and same-day replacement programs. Elo Touch Solutions dominates this channel through specialized partnerships with in-house controller programming capabilities.
- Gaming Machines:Casino and amusement equipment in Nevada and Macau specifies digital resistive variants for high-frequency touch environments. Sub-10-millisecond response requirements exclude analog architectures from this premium tier.
- Kiosks:Outdoor and semi-outdoor self-service terminals leverage resistive moisture tolerance where capacitive alternatives fail.
- Home Appliances:Cost-optimized resistive panels serve white-goods interfaces where glove compatibility and stylus precision are non-critical.
Point of Sale anchors established revenue; Gaming Machines is climbing the fastest on share.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German automotive paint shops demand gloved-operation panels for chemical-exposed assembly lines, while Chinese cleanroom clusters export cost-optimized industrial units to North American OEMs, creating a consumption mix split between precision-driven European automation and scale-driven Asian manufacturing.
Germany
Automotive assembly lines in Bavaria and Baden-Württemberg specify resistive interfaces for paint-shop environments where chemical exposure and gloved operation are mandatory. KBA vehicle safety standards influence control panel certification requirements for industrial equipment integration. Stuttgart and Munich industrial clusters host precision-engineered panel suppliers serving multi-year supply agreements with extended qualification timelines.
China
GB standards mandate electromagnetic interference testing for industrial panel imports, creating compliance friction for non-domestic suppliers while domestic cleanroom assemblers capture scale economies. Shenzhen and Taipei manufacturing clusters achieve cost advantages in bonded-inventory export platforms serving North American point-of-sale channels. Pearl River Delta facilities concentrate indium tin oxide coating capacity within state-controlled refiner supply chains.
Japan
METI industrial digitization programs sustain factory floor demand for analog resistive architectures compatible with legacy PLC systems. JIS standards govern precision tolerance requirements for polyester-glass lamination in medical device interfaces. Nagoya and Osaka industrial corridors anchor automotive and healthcare equipment procurement with long-term supplier relationships.
United States
FDA 510(k) clearance pathways for medical device touch interfaces validate biocompatibility and electromagnetic compatibility requirements for diagnostic equipment manufacturers. Nevada gaming machine OEMs specify digital resistive variants for sub-10-millisecond response requirements in casino environments. Quick-service restaurant chains across the Southeast and Midwest consolidate vendor relationships around distributor partnerships with controller programming capabilities.
Vietnam
Thai and Vietnamese governments offer tax holidays for precision assembly investments, enabling tariff-advantaged export platforms for US and EU industrial customers. Cleanroom capacity expansion in Ho Chi Minh City and Bangkok industrial zones targets industrial-grade panel assembly for automotive and healthcare OEMs. Southeast Asian manufacturing is reconfiguring supply chain roles as alternative sourcing bases to Chinese concentration.
Resistive Touchscreen Market Competitive Landscape
Capability concentration sits with precision-engineered specialists certified to IEC and FDA pathways; scale advantage sits with high-volume assemblers serving cost-optimized commercial tiers. The vendor base separates into three strategic archetypes: analog resistive specialists serving legacy industrial automation, digital resistive developers targeting gaming and medical response-time requirements, and integrated controller-panel combination suppliers streamlining OEM procurement. Dominant competitive moves include cleanroom capacity expansion in Vietnam and Thailand for tariff-advantaged export positioning, and qualification of silver nanowire formulations to reduce indium supply dependence under REACH disclosure pressure.
Within the precision-certified tier, Fujitsu exemplifies technology leadership in analog resistive architectures for medical equipment interfaces, while SCHURTER anchors European demand with IEC-standard industrial control panels. Elo Touch Solutions occupies a position in North American point-of-sale channels through specialized distribution partnerships with in-house controller programming capabilities. These three companies represent distinct competitive positioning vectors: Japanese medical precision, Swiss-German industrial certification, and US channel-integrated scale.
| Leading Market Players |
|---|
| AMT |
| MILDEX OPTICAL INC |
| Fujitsu |
| 3M Company |
| Elo Touch Solutions |
| STMicroelectronics |
| SCHURTER |
| Touch International |
| Rohm Semiconductor |
| Others |
Pricing and Supply Chain Analysis
Indium tin oxide coating capacity concentrated in Chinese state-controlled refiners feeds directly into margin pools captured by industrial panel specialists serving German and Japanese automotive buyers. Long-term offtake agreements for qualified medical-grade panels lock in premium pricing tiers, while spot-market sourcing for commercial-grade commercial displays faces persistent cost compression.
Pricing Analysis
Long-term offtake contracts dominate procurement for industrial automation and medical device segments, insulating qualified suppliers from spot volatility. Three-tier pricing structure across precision-certified, standard industrial, and economy commercial levels reflects certification grade and volume scale differentiation. Cost compression in economy tiers intensifies as Vietnamese and Thai assemblers expand bonded-inventory export platforms. Healthcare equipment buyers show least price sensitivity due to extended qualification cycles and regulatory compliance requirements, while point-of-sale channel consolidators drive hardest bargain terms.
Supply Chain Analysis
Export license controls on advanced coating technologies limit indium tin oxide precursor flows from Chinese state-controlled refiners to non-domestic panel makers. Manufacturing concentrates in China, Vietnam, and Thailand, with cleanroom assembly capacity expanding fastest in Southeast Asian tax-advantaged zones. Raw material dependencies center on indium tin oxide coatings, silver nanowire alternatives, and micro-dot spacer substrates. Single-source vulnerability around Chinese indium refining creates input volatility exposure. Distribution runs through specialized channel partners with in-house controller programming capabilities serving North American point-of-sale consolidation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Resistive touchscreen demand follows industrial capital expenditure cycles, with German and Japanese automotive paint-shop digitization programs signaling current upswing phase.
For Market Incumbents: Insulate margin pools by deepening backward integration into indium tin oxide coating capacity or qualifying silver nanowire formulations to reduce Chinese supply dependence. Extend certification investments for dual IEC-GB compliance to capture first-mover advantage in electromagnetic interference testing pathways. Channel control through distributor partnerships with bonded inventory programs defends against Southeast Asian tariff-advantaged entrants. For New Entrants and Emerging Players: Pursue white-space opportunities in Vietnam and Thailand cleanroom assembly for US and EU industrial customers seeking tariff-advantaged sourcing. Digital resistive variants for Nevada and Macau gaming machine OEMs represent most penetrable premium segment given sub-10-millisecond response requirements excluding analog competition. Go-to-market through specialized distributors with controller firmware integration capabilities accelerates customer acquisition. For Investors and Strategic Acquirers: Capital is best deployed toward precision-certified specialists with FDA 510(k) and EU MDR pathway experience, as regulatory moats sustain pricing power across multi-year horizons. Acquisition targets should demonstrate established relationships with German automotive or Japanese healthcare equipment OEMs. Signal to watch: REACH enforcement actions triggering accelerated silver nanowire qualification timelines among Irish and Dutch contract manufacturers.| Strategic Initiative | Industry Significance |
|---|---|
| Cleanroom Capacity Expansion | Vietnam and Thailand tax holidays enable tariff-advantaged export platforms for industrial panel assembly. |
| Alternative Material Qualification | Silver nanowire formulations reduce indium dependence while satisfying REACH Article 33 disclosure obligations. |
| Dual Certification Investment | Simultaneous IEC and GB standard alignment captures Chinese import compliance for electromagnetic interference testing. |
| Channel Partnership Consolidation | Distributor relationships with in-house controller programming displace direct procurement in North American point-of-sale. |
| Digital Resistive Development | Matrix-scanning architectures address Nevada and Macau gaming OEM sub-10-millisecond response requirements. |
Research Methodology
Desk research of trade customs data, SEC filings from publicly listed component suppliers, and ECHA REACH enforcement records preceded structured interviews with industrial automation procurement directors, medical device contract manufacturing executives, and specialized distributor channel partners. Primary fieldwork with factory floor engineers and diagnostic equipment designers validated secondary findings on qualification cycle duration and regulatory pathway complexity. Bottom-up unit demand estimates triangulated against top-down industrial automation capital expenditure projections.
Assumptions held fixed include continued RoHS exemption timelines for legacy industrial equipment and sustained Chinese indium refining capacity availability, while variables tested included Southeast Asian cleanroom expansion rates and EU MDR enforcement intensity. Segmentation modeling spanned product type, technology architecture, end-user industry, and geographic manufacturing cluster dimensions. CAGRs derived from regression analysis of historical industrial panel shipment volumes against automotive production and healthcare equipment installation trends.
Sensitivities concentrate around REACH enforcement escalation, Chinese export license restrictions on indium precursors, and EU MDR clinical evidence requirement implementation pace. Forecasts reflect documented assumptions on regulatory timeline stability and raw material supply continuity. Material shifts in RoHS exemption decisions or indium supply concentration would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Display Technologies
Global Ultra Wide Temperature TFT Display Market
Display Technologies
Polarizing Film for Displays Market
Display Technologies
Europe Computer Monitor Market
Display Technologies
Flexible OLED Market
Display Technologies
Screenless Display Market
Display Technologies
Display Fingerprint Technology Market
Display Technologies
Interactive Display Market
Display Technologies
Cathode Ray Tube Display Market
Display Technologies
Dot Matrix Display Market
Display Technologies
Computer Monitor Market
Display Technologies
OLED Microdisplay Market
Display Technologies
Europe E-Paper Display Market
Display Technologies
Flexible Screens Market
Display Technologies
North America Head-Up Display Market
Display Technologies
Smartwatch Display Panel Market
Display Technologies
Commercial Touch Display Market