
 Medical Respiratory Protective Equipment Market | 2026-2036
Medical Respiratory Protective Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Medical Respiratory Protective Equipment Market Intelligence
Silicone elastomer is expanding its share in full-face respirator seals as manufacturers seek alternatives to natural rubber latex that trigger Type I hypersensitivity reactions in clinical settings. 3M Company leverages backward integration into electrostatic filter media production to sustain margin control across its N95 portfolio. Honeywell International dominates North American hospital procurement through long-term vendor-managed inventory contracts with integrated delivery networks.
Medical respiratory protective equipment encompasses devices engineered to filter airborne particulates, biological aerosols, and chemical vapors through mechanical filtration layers rated at N95 equivalence or higher, with exhalation valves and face-seal interfaces designed to achieve fit factors exceeding 100. These systems protect healthcare workers during aerosol-generating procedures, hazardous drug compounding, and outbreak response in clinical environments. N95 respirators command the largest revenue pool among product types due to pandemic-era stockpiling mandates and OSHA compliance requirements, while powered air-purifying respirators represent the fastest-expanding category as oncology units adopt loose-fitting hood systems for chemotherapy handling. Surgical masks occupy a mature, price-compressed segment where differentiation hinges on ASTM F2100 Level 3 certification rather than brand premium.
The FDA enforces 21 CFR 878.4040 for surgical masks and NIOSH certification for respirators under 42 CFR 84, creating a dual-track compliance burden that filters out marginal suppliers. The EU Medical Device Regulation and REACH restrictions on phthalate plasticizers in facepiece materials are forcing European manufacturers to reformulate elastomer compounds and resubmit technical documentation. Stakeholders must monitor how the EPA's emerging per- and polyfluoroalkyl substance restrictions will affect melt-blown polypropylene treatments currently used to enhance hydrophobic filtration performance.
Market Dynamics
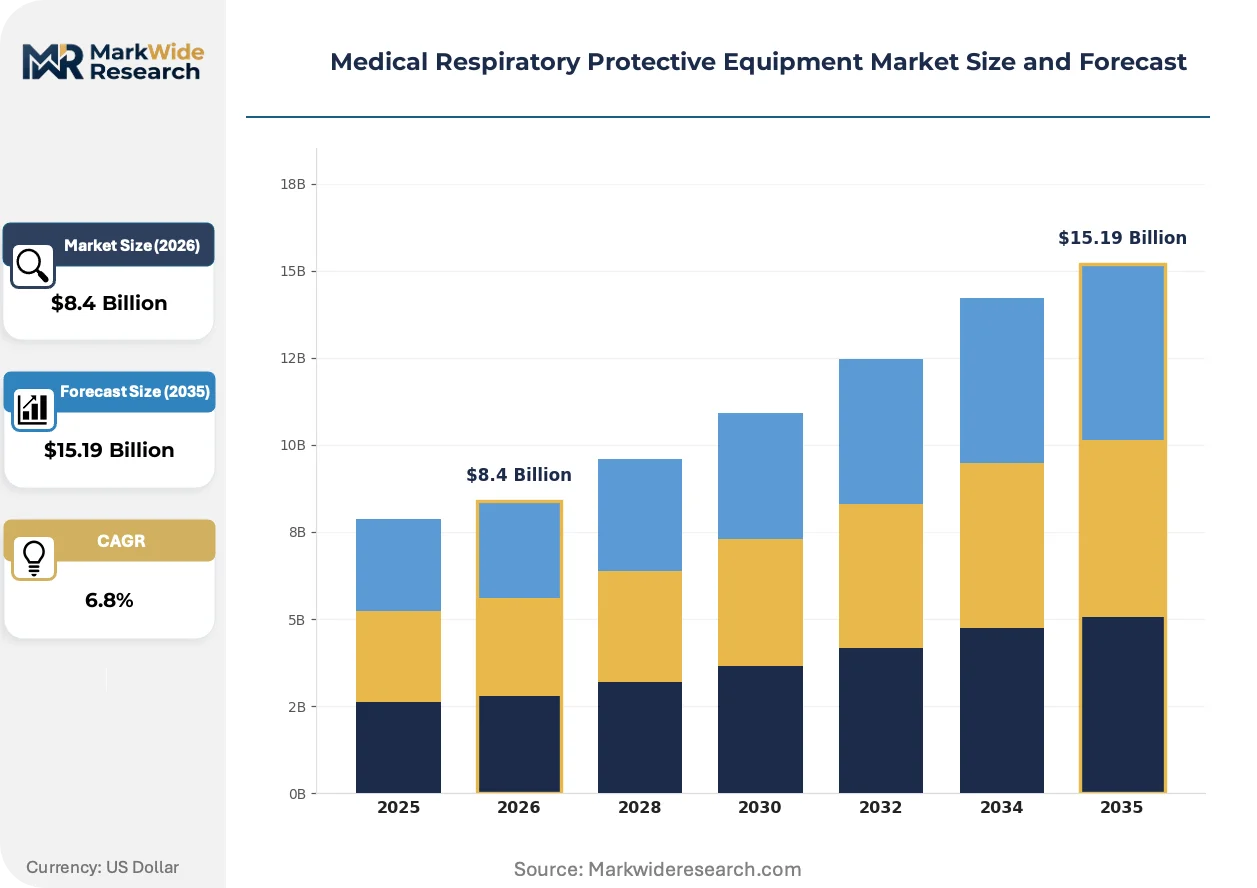
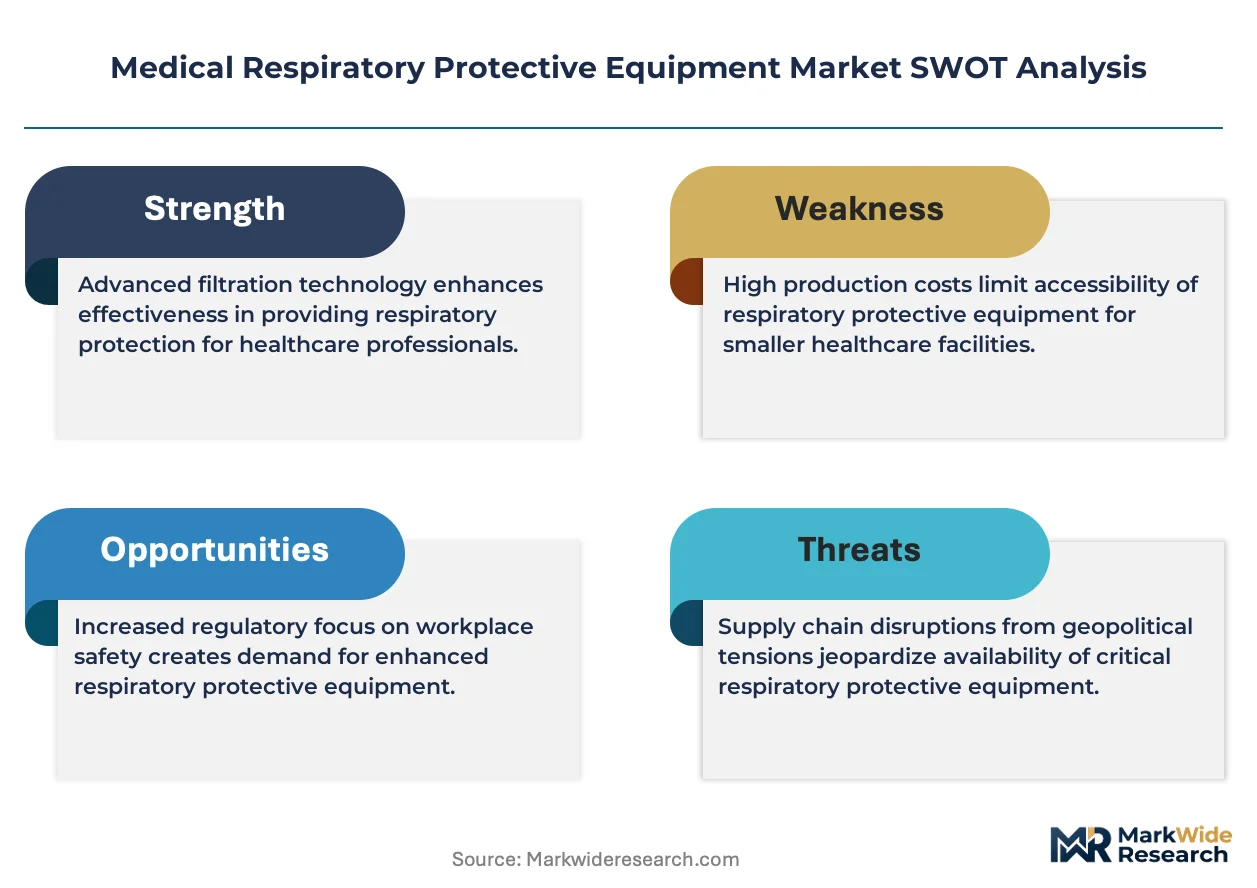
Post-pandemic stockpiling mandates across North American and European hospital systems are creating a structural demand floor that insulates N95 respirator volumes from normal cyclicality, while simultaneously compressing margins through bulk procurement terms and multi-year vendor-managed inventory contracts.
Growth Catalysts
- OSHA compliance mandates:US hospital systems face enforcement of updated respiratory protection standards requiring fit-testing documentation and annual training programs, institutionalizing recurring equipment refresh cycles.
- Oncology unit expansion:Loose-fitting powered air-purifying respirator hoods are displacing tight-fitting elastomeric masks in chemotherapy compounding pharmacies due to superior comfort during extended wear periods.
- Silicone elastomer substitution:Manufacturers are reformulating full-face respirator seals to eliminate natural rubber latex and capture clinical settings with strict Type I hypersensitivity protocols.
Market Restraints
- Melt-blown polypropylene concentration:Electrostatic filter media production clusters in East Asian manufacturing zones, exposing supply chains to shipping cost volatility and tariff exposure.
- Dual-track certification burden:The FDA's 21 CFR 878.4040 surgical mask pathway and NIOSH's 42 CFR 84 respirator pathway force parallel testing regimes that filter out marginal suppliers.
- Phthalate plasticizer restrictions:REACH compliance in European markets requires complete elastomer compound reformulation and technical documentation resubmission, extending time-to-market.
Strategic Opportunities
- Per- and polyfluoroalkyl substance alternatives:EPA emerging restrictions on PFAS treatments for hydrophobic filtration performance create first-mover advantage for fluorine-free surface modification technologies.
- Home healthcare respiratory protection:Post-acute care settings and palliative home nursing represent underpenetrated channels with distinct fit-testing and training requirements.
- EU Medical Device Regulation harmonization:MDR technical documentation centralization enables cross-border tender participation for certified manufacturers in Germany, France, and Benelux markets.
Industry Challenges
- Fit-testing technician scarcity:Hospital systems struggle to maintain qualified staff for quantitative fit-testing protocols required under OSHA's respiratory protection standard, creating compliance gaps.
- Legacy inventory integration:Multi-year stockpiles of pandemic-era N95 respirators with degraded headband elasticity complicate rotation protocols and expiration date management.
- NIOSH certification backlog:Respirator approval timelines stretch 12-18 months, delaying product launches and locking designs that may become obsolete during review.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Medical Respiratory Protective Equipment Market |
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $15.19 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Surgical Masks, N95 Respirators, Face Shields, Powered Air-Purifying Respirators End User: Hospitals, Clinics, Laboratories, Emergency Services Application: Infection Control, Hazardous Material Handling, Surgery, Respiratory Protection Distribution Channel: Direct Sales, Online Retail, Medical Supply Distributors, Wholesalers |
| Companies Covered | 3M Company, Honeywell International Inc., DuPont de Nemours Inc., MSA Safety Incorporated, Ansell Ltd., Bullard Company, Drägerwerk AG & Co. KGaA, Kimberly-Clark Corporation, Alpha Pro Tech Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Medical Respiratory Protective Equipment Market Strategic Shifts & Innovations
Electrostatic filtration media manufacturing, regulatory chemistry restrictions, and procurement centralization are converging to reshape competitive positioning and supply chain configuration across medical respiratory protective equipment categories.
Reusable elastomeric respirator platforms with cartridge-based filtration are decentralizing demand away from disposable N95 disposables in high-frequency use settings. Ambulatory surgery centers and dental clinics are adopting half-mask designs with P100 cartridges to reduce per-procedure costs and waste volume. This technology is decentralizing purchasing authority from central supply departments to individual clinical units with distinct usage patterns.
REACH restrictions on phthalate plasticizers in facepiece materials are forcing European manufacturers to reformulate silicone and thermoplastic elastomer compounds. The industrial consequence is a 12-18 month technical documentation resubmission cycle that advantages incumbent suppliers with established regulatory affairs capacity. German and French hospital procurement consortia are responding by consolidating vendor lists to suppliers with proven MDR compliance histories.
Integrated delivery networks are consolidating respiratory protection procurement under vendor-managed inventory contracts that shift inventory carrying costs to manufacturers. Group purchasing organizations are displacing individual hospital contracting for N95 respirators and surgical masks, compressing price realization. This concentration is most visible in North American health systems where three-year sole-source agreements now dominate high-volume categories.
Medical Respiratory Protective Equipment Market Segmentation
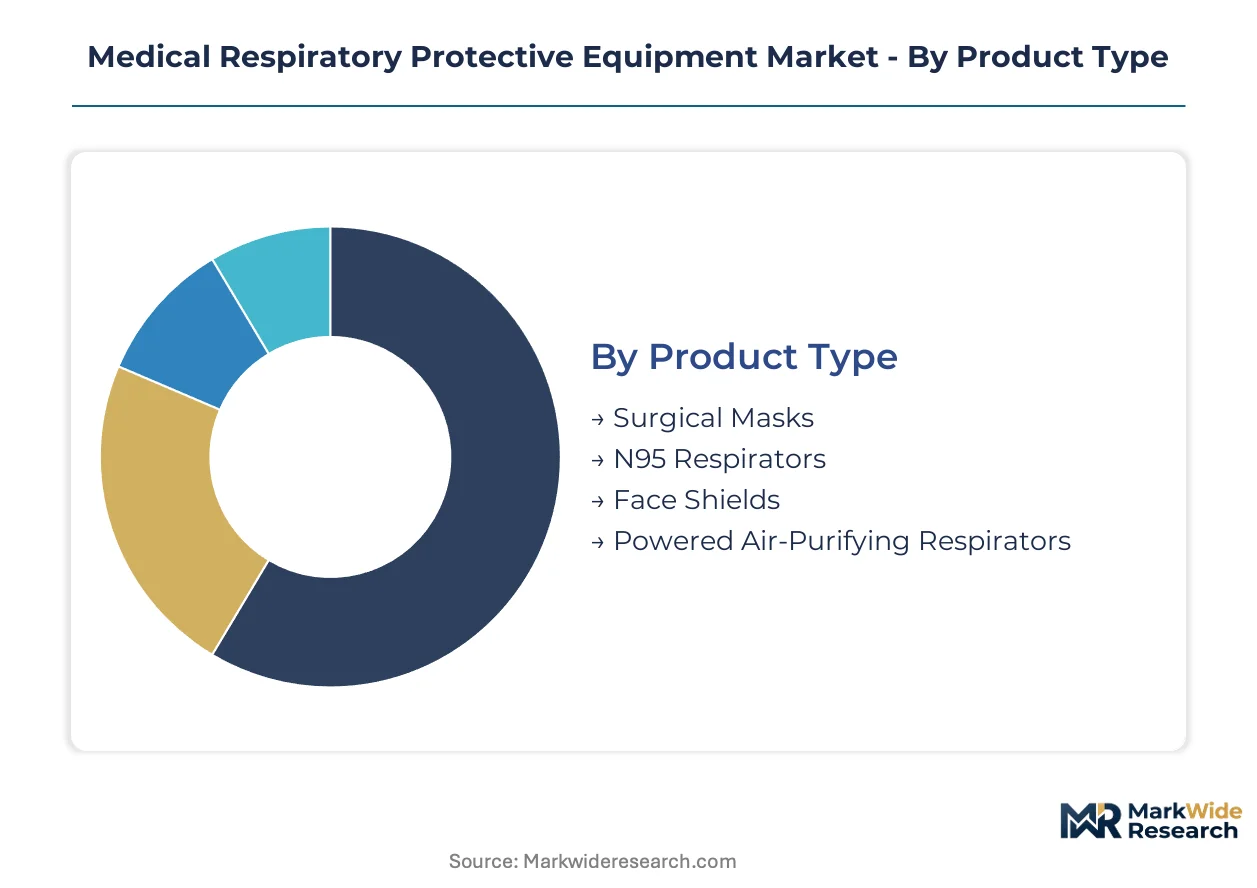
Segmentation in medical respiratory protective equipment reveals how procurement authority, regulatory pathways, and clinical workflows fragment demand across incompatible product specifications. Understanding these divisions exposes where margin pools concentrate and which certification requirements create defensible supplier positions.
Product Type:
Supply concentration in electrostatic filter media manufacturing clusters procurement leverage around N95 respirators and shapes competitive dynamics across adjacent categories.
- N95 Respirators:Mechanical filtration devices rated to capture 95% of 0.3-micron particles through melt-blown polypropylene layers with electrostatic charge enhancement. Hospital systems in Germany and the United States anchor procurement volume through multi-year stockpiling mandates tied to federal strategic reserve protocols.
- Powered Air-Purifying Respirators:Battery-driven blower units that force ambient air through HEPA filtration into loose-fitting hoods or tight-fitting facepieces. Oncology units in North American hospital systems are driving adoption for chemotherapy compounding due to extended-wear comfort requirements that tight-fitting elastomeric masks cannot satisfy.
- Surgical Masks:Three-ply barrier devices meeting ASTM F2100 filtration standards without seal requirements. Differentiation hinges on Level 3 fluid resistance certification rather than brand premium, compressing margins in commoditized hospital procurement.
- Face Shields:Polycarbonate or polyethylene terephthalate glycol barriers providing splash protection without respiratory filtration. Demand concentrates in dental clinics and ambulatory surgery centers seeking disposable eye and face coverage for aerosol-generating procedures.
Today's leader: N95 Respirators. Tomorrow's challenger: Powered Air-Purifying Respirators.
End User:
Cost tier stratification separates capital-intensive hospital procurement from price-sensitive clinic purchasing, fragmenting vendor strategies across incompatible contract structures.
- Hospitals:Integrated delivery networks with vendor-managed inventory contracts and centralized respiratory protection programs. OSHA compliance mandates for fit-testing documentation and annual training institutionalize recurring equipment refresh cycles across acute care facilities.
- Emergency Services:Fire departments and ambulance systems requiring rapid-donning equipment for unknown respiratory hazards. Federal stockpiling mandates in the United States sustain demand for N95 respirators and elastomeric platforms with standardized cartridge interfaces.
- Clinics:Outpatient facilities with decentralized purchasing authority and volume constraints that favor disposable surgical masks over capital-intensive reusable systems.
- Laboratories:Research and diagnostic facilities handling biological safety level 2 and 3 agents, where biosafety cabinet integration and negative pressure protocols determine respiratory protection specifications.
Volume concentrates in Hospitals. Margin expansion potential sits with Emergency Services.
Application:
Application-specific regulatory requirements create divergent certification burdens that filter suppliers across incompatible market entry costs.
- Infection Control:Barrier protection for aerosol-generating procedures in isolation rooms and outbreak response settings. FDA enforcement of 21 CFR 878.4040 for surgical masks and NIOSH 42 CFR 84 for respirators creates dual-track compliance that advantages established manufacturers with regulatory affairs capacity.
- Hazardous Material Handling:Protection against chemical vapors and particulate mixtures in pharmacy compounding and industrial hygiene contexts. OSHA permissible exposure limits for antineoplastic drugs drive adoption of loose-fitting powered air-purifying respirator hoods in oncology units.
- Surgery:Sterile field maintenance requiring fluid resistance and bacterial filtration efficiency without respiratory seal performance. ASTM F2100 Level 3 certification serves as the primary procurement filter in this mature segment.
- Respiratory Protection:General occupational safety applications spanning construction, manufacturing, and healthcare maintenance where fit-testing protocols and cartridge compatibility determine equipment selection.
Regulatory complexity peaks in Infection Control. Technology substitution accelerates in Hazardous Material Handling.
Distribution Channel:
Customer type fragmentation between institutional procurement and individual purchasing reshapes inventory carrying costs and pricing transparency across channel structures.
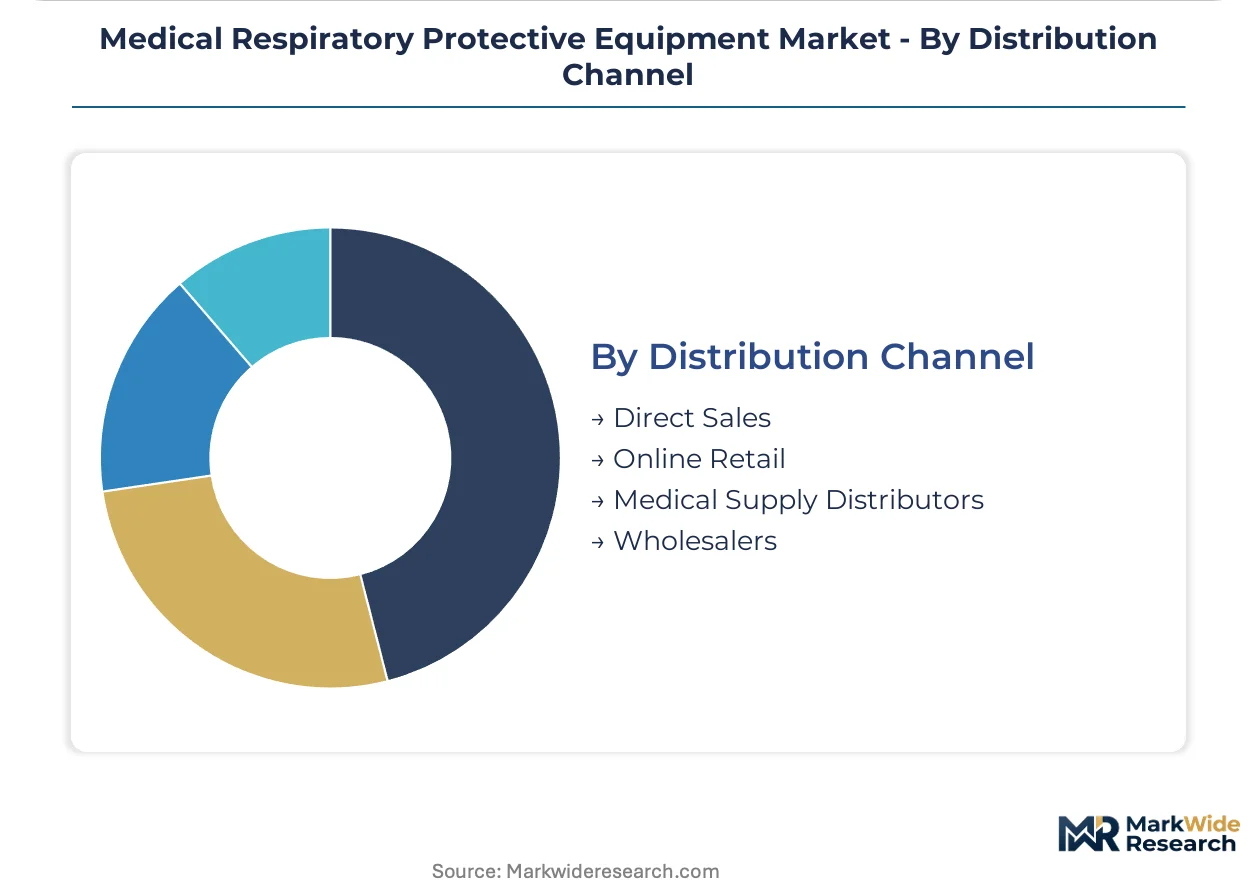
- Medical Supply Distributors:Regional and national intermediaries with GPO contract participation and logistics networks serving hospital systems. Group purchasing organization consolidation is displacing individual hospital contracting, compressing price realization for high-volume categories.
- Direct Sales:Manufacturer-led contracting with integrated delivery networks and federal procurement programs. Vendor-managed inventory agreements shift carrying costs to suppliers while locking in multi-year sole-source relationships.
- Online Retail:E-commerce platforms serving smaller clinical units, dental practices, and individual healthcare workers with transactional purchasing and limited technical support.
- Wholesalers:Bulk intermediaries handling generic surgical masks and commodity respirators with minimal value-added services and price-driven selection criteria.
Contract value concentrates in Direct Sales. Channel conflict intensifies between Medical Supply Distributors and Online Retail.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German industrial clusters in North Rhine-Westphalia and Bavaria anchor European production capacity for medical respiratory protective equipment, with federal strategic reserve procurement sustaining demand volumes that exceed clinical consumption alone.
United States
Hospital systems and integrated delivery networks drive procurement through vendor-managed inventory contracts with multi-year terms. OSHA enforcement of updated respiratory protection standards mandates fit-testing documentation and annual training programs. The Midwest manufacturing corridor, particularly around Minneapolis-St. Paul, concentrates domestic N95 respirator production capacity.
Germany
Federal stockpiling mandates for strategic reserves sustain demand volumes independent of hospital utilization rates. EU Medical Device Regulation and REACH restrictions on phthalate plasticizers force complete elastomer compound reformulation. The Ruhr industrial region hosts specialized filtration media production facilities serving both domestic hospital systems and export markets.
China
Electrostatic melt-blown polypropylene manufacturing clusters in Yangtze River Delta supply filter media to global respirator assemblers. NMPA certification requirements and GB standards for medical device registration create parallel compliance tracks for domestic and export production. Zhejiang province concentrates surgical mask fabrication capacity with cost structures that pressure global pricing.
Japan
Oncology unit expansion in metropolitan hospital systems drives adoption of powered air-purifying respirator hoods for chemotherapy compounding. PMDA medical device registration and JIS standards for respiratory protection equipment enforce rigorous quality documentation. The Kansai region around Osaka maintains specialized elastomer formulation capabilities for full-face respirator seals.
India
Domestic hospital procurement is shifting from imported N95 respirators to locally manufactured alternatives under CDSCO medical device rules. BIS certification requirements for surgical masks and respirators are filtering out unorganized sector suppliers. The Pune-Ahmedabad industrial corridor is emerging as a concentration point for disposable respirator assembly operations.
Medical Respiratory Protective Equipment Market Key Industry Players
Capacity expansion dominates the current landscape as manufacturers respond to post-pandemic stockpiling mandates and federal strategic reserve procurement. The vendor base fragments across three tiers: diversified industrial conglomerates with backward integration into filter media, specialized respiratory protection manufacturers with deep regulatory affairs capacity, and regional disposable mask assemblers competing on price. Strategic archetypes include integrated materials-to-device producers, regulatory-compliance specialists, and scale-driven commodity suppliers. Parallel competitive moves center on geographic production diversification to reduce East Asian supply chain exposure and portfolio expansion into powered air-purifying systems.
Among diversified industrial conglomerates, 3M Company exemplifies the integrated materials-to-device archetype through captive electrostatic filter media production. Honeywell International occupies a position within the regulatory-compliance specialist tier, anchored by long-term vendor-managed inventory relationships with North American hospital systems. Drägerwerk AG & Co. KGaA represents the European regulatory-specialist archetype, with technical documentation capacity that satisfies EU Medical Device Regulation harmonization requirements.
| Leading Market Players |
|---|
| 3M Company |
| Honeywell International Inc. |
| DuPont de Nemours Inc. |
| MSA Safety Incorporated |
| Ansell Ltd. |
| Bullard Company |
| Drägerwerk AG & Co. KGaA |
| Kimberly-Clark Corporation |
| Alpha Pro Tech Ltd. |
| Others |
Cost & Logistics Intelligence
Electrostatic filter media engineers in the Yangtze River Delta command wage premiums that compress manufacturing margins, widening the spread between commodity surgical masks and certified N95 respirators across North American and European procurement tiers.
Pricing Analysis
Input-cost pass-through from melt-blown polypropylene resin and electrostatic charge enhancement chemicals shapes contract pricing for N95 respirators, with three-tier pricing structure across premium, standard, and economy levels separating NIOSH-certified hospital-grade units from industrial variants and unbranded disposable masks. Certification grade under FDA 21 CFR 878.4040 and NIOSH 42 CFR 84 pathways creates the primary price differentiation, while volume scale through group purchasing organization consolidation intensifies cost compression in the standard tier. Pricing pressure stems from multi-year vendor-managed inventory contracts that shift carrying costs to manufacturers. Clinics and outpatient facilities exhibit highest price sensitivity, whereas integrated delivery networks prioritize compliance documentation over unit cost.
Supply Chain Analysis
Direct-to-hospital channels handle high-volume demand from integrated delivery networks, while medical supply distributors serve mid-tier regional systems with GPO contract participation. Geographic supply concentration centers on China for electrostatic filter media and melt-blown polypropylene, Germany for elastomer formulation and full-face respirator assembly, and the United States for N95 finished goods. Raw material dependencies include polypropylene resin, silicone elastomer compounds, and lithium-ion battery cells for powered air-purifying respirator units. Single-source vulnerability in East Asian filter media production exposes assemblers to shipping cost volatility and tariff exposure. Distribution runs through vendor-managed inventory agreements with three to five-year terms dominating North American hospital procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in medical respiratory protective equipment rests on silicone elastomer substitution eliminating natural rubber latex from full-face respirator seals, reducing allergen liability costs while capturing premium positioning in hypersensitivity-protocol clinical settings.
For Market Incumbents: Anchor defensive positioning through backward integration into electrostatic filter media production and captive silicone elastomer compounding capacity in Germany or the United States. Consolidate vendor-managed inventory relationships with integrated delivery networks before group purchasing organization consolidation displaces individual hospital contracting. Invest in EU Medical Device Regulation technical documentation capacity to defend against REACH-driven supplier attrition. For New Entrants and Emerging Players: EPA emerging restrictions on per- and polyfluoroalkyl substances in the United States open a window for fluorine-free surface modification technologies to capture first-mover advantage in hydrophobic filtration performance. Target home healthcare respiratory protection as the most penetrable channel, where post-acute care settings lack established fit-testing infrastructure. Pursue oncology unit partnerships for loose-fitting powered air-purifying respirator hoods as the go-to-market angle. For Investors and Strategic Acquirers: Valuations sit cheapest among regional disposable mask assemblers facing dual-track FDA-NIOSH certification burdens that filter out marginal competitors. Long-term viability over the next decade favors manufacturers with demonstrated regulatory affairs capacity and established hospital system relationships. Watch NIOSH certification backlog duration as the signal for competitive entry timing—approval timeline compression indicates window narrowing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Filter Media | Captive electrostatic melt-blown polypropylene production insulates margin control from Yangtze River Delta supply volatility. |
| Silicone Elastomer Reformulation | Eliminating natural rubber latex captures hospital systems with strict Type I hypersensitivity protocols in Germany and the United States. |
| Vendor-Managed Inventory Expansion | Three to five-year sole-source agreements with integrated delivery networks lock out competitors in North American hospital procurement. |
| Fluorine-Free Surface Modification | EPA restrictions on per- and polyfluoroalkyl substances create replacement demand for hydrophobic filtration treatments. |
| EU MDR Technical Documentation Investment | Centralized documentation enables cross-border tender participation in German, French, and Benelux hospital procurement consortia. |
Research Approach
Multiple input streams — primary interviews with hospital procurement managers, biomedical engineers, and GPO contracts specialists; secondary validation through FDA 510(k) filings, NIOSH certification databases, and hospital supply chain disclosures; and customs trade data on melt-blown polypropylene imports — were reconciled through bottom-up and top-down triangulation to construct market estimates.
Historical volume trajectories were cross-referenced against panel input from respiratory protection manufacturers and integrated delivery network supply chain directors to model growth across product type, end user, application, and distribution channel dimensions over the projection horizon. CAGRs were derived from segmented demand build-ups incorporating OSHA enforcement intensity, federal stockpiling mandate renewal schedules, and oncology unit expansion rates as industry-specific forecast inputs.
Revisions become necessary when EPA finalizes per- and polyfluoroalkyl substance restrictions, when NIOSH certification timelines shift materially, or when federal strategic reserve procurement volumes deviate from mandated targets. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Safety Equipment and Personal Protective Equipment (PPE)
Global Protective Gloves Market
Safety Equipment and Personal Protective Equipment (PPE)
Smart Barrier Gate Market
Safety Equipment and Personal Protective Equipment (PPE)
Safety Cones Market
Safety Equipment and Personal Protective Equipment (PPE)
Supplied Air Respirators Market
Safety Equipment and Personal Protective Equipment (PPE)
Drone Safety Solutions Market
Safety Equipment and Personal Protective Equipment (PPE)
Intrinsically Safe Lighting Market
Safety Equipment and Personal Protective Equipment (PPE)
Global Explosion Proof Equipment Market
Safety Equipment and Personal Protective Equipment (PPE)
Asia-Pacific Riot Control Equipment Market
Safety Equipment and Personal Protective Equipment (PPE)
Fall Protection Equipment Market
Safety Equipment and Personal Protective Equipment (PPE)
US Personal Protective Equipment Market
Safety Equipment and Personal Protective Equipment (PPE)
Plastics in Personal Protective Equipment Market
Safety Equipment and Personal Protective Equipment (PPE)
Alarm Management System Market
Safety Equipment and Personal Protective Equipment (PPE)
Europe Safes and Vaults Market
Safety Equipment and Personal Protective Equipment (PPE)
Industrial Machine Guarding Fence Market
Safety Equipment and Personal Protective Equipment (PPE)
Global Respirator Filter Market
Safety Equipment and Personal Protective Equipment (PPE)
North America Respiratory Protective Equipment (RPE) Market