
 Safety Cones Market | 2026-2036
Safety Cones Market Size, Share, and Industry Trends Forecast 2026-2036
Safety Cones Market Analytics
A shift from single-source municipal contracts toward multi-source procurement frameworks is repositioning how safety cone vendors secure long-term supply agreements. TrafFix Devices leverages its manufacturing scale to dominate state-level DOT bidding pools across the American Southwest. 3M anchors premium positioning through proprietary reflective sheeting technology integrated into cone collars. JBC Safety Plastic, Inc. competes on cost-efficient polyethylene molding for high-volume construction site orders.
Safety cones are temporary traffic control devices typically manufactured through rotational or injection molding of polyethylene, PVC, or rubber compounds, engineered with retroreflective bands to meet minimum luminance coefficients for nighttime visibility. Their primary purpose is to channel vehicle and pedestrian flow around hazards, work zones, or emergency scenes. Traffic cones occupy the largest volume share within the type dimension, though delineator posts capture higher per-unit margins from highway agencies specifying enhanced stability. Composite materials represent the fastest-expanding material category as agencies seek alternatives to pure PVC amid evolving environmental compliance frameworks.
Federal Highway Administration MUTCD standards, OSHA 29 CFR workplace safety provisions, and state DOT specifications collectively mandate minimum cone height, weight, and retroreflectivity thresholds that determine product eligibility for public procurement. The EPA's emerging scrutiny of PVC additive formulations is pressuring manufacturers to validate alternative polymer recipes without sacrificing impact resistance. Stakeholders must monitor how pending infrastructure appropriations reshape specification tiers before committing to capacity expansion or material platform transitions.
Market Dynamics
Municipal procurement departments are consolidating safety cone purchases into multi-year framework agreements, compressing vendor margins while elevating compliance thresholds for retroreflective performance and material traceability.
Growth Catalysts
- MUTCD federal highway standards:The Federal Highway Administration's updated visibility mandates for temporary traffic control devices are forcing state DOTs to refresh aging cone inventories, creating replacement demand across California, Texas, and Florida highway programs.
- Composite material innovation:Recycled rubber-polyethylene blends are displacing virgin PVC in highway agency specifications, opening procurement eligibility for manufacturers with validated circular supply chains.
- Construction sector concentration:Large infrastructure contractors are standardizing cone fleets across multi-state projects, concentrating volume with suppliers offering national distribution networks and color-coded inventory management systems.
Market Restraints
- Petrochemical input volatility:Linear low-density polyethylene resin prices fluctuate with ethylene feedstock costs, squeezing molding margins for high-volume construction-grade cone producers.
- Single-source retroreflective sheeting dependency:Domestic cone manufacturers rely on concentrated supply of microprismatic collar materials, creating vulnerability to allocation constraints during highway construction season peaks.
- OSHA 29 CFR compliance friction:Workplace safety provisions mandate specific cone weight-to-height ratios that conflict with lightweight shipping preferences, forcing manufacturers to maintain dual product lines.
Strategic Opportunities
- Smart city infrastructure integration:Bluetooth-enabled cones with GPS tracking are converging with municipal asset management platforms, creating data-service revenue streams beyond hardware sales.
- Emergency response standardization:Federal emergency management frameworks are mandating interoperable traffic control kits, opening specification windows for vendors with NFPA-certified product bundles.
- Direct-to-contractor e-commerce channels:Digital procurement platforms are disintermediating traditional distribution, allowing manufacturers to capture margin previously allocated to regional safety equipment distributors.
Industry Challenges
- Retroreflectivity certification backlog:Third-party testing laboratories face six-month queues for luminance coefficient validation, delaying product launches for manufacturers with new collar formulations.
- Skilled rotational molding technician scarcity:Experienced operators who can maintain wall-thickness consistency in high-density polyethylene cones command wage premiums that erode cost competitiveness against injection-molded alternatives.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Safety Cones Market |
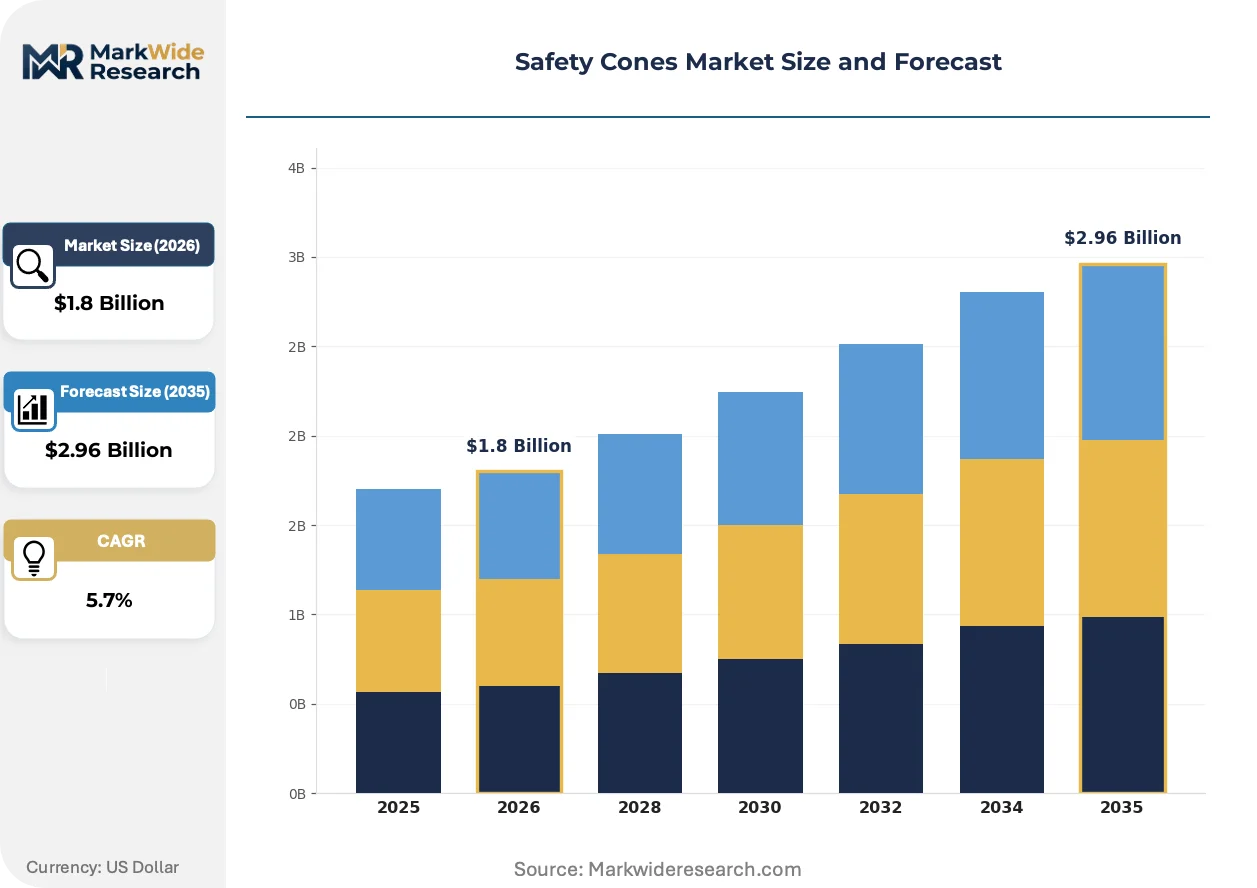
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Traffic Cones, Road Cones, Safety Barriers, Delineator Posts Material: Polyethylene, PVC, Rubber, Composite Application: Construction Sites, Emergency Services, Road Maintenance, Event Management Size: Standard, Mini, Tall, Custom |
| Companies Covered | OPTSIGNS (Optraffic Brand), Lakeside Plastics, Inc., TrafFix Devices, JBC Safety Plastic, Inc., Tolco Corporation, Cortina Companies, Honeywell, 3M, Melba Swintex, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Safety Cones Market Evolving Landscape
Material science advances and digital asset tracking are restructuring how safety cones are specified, procured, and deployed across infrastructure and industrial applications.
Photoluminescent pigment infusion is converging with traditional retroreflective banding to create hybrid visibility systems. State DOTs in Arizona and Nevada are piloting these dual-mode cones for unlit rural work zones where electrical power is unavailable. The technology is converging with solar-powered LED strobe integration, compressing the addressable market for pure retroreflective products in high-risk highway segments.
EPA scrutiny of phthalate plasticizer formulations in PVC traffic control devices is tightening additive disclosure requirements. Manufacturers must now submit full material safety data sheets for cone compounds to qualify for federal-aid highway project procurement. California Department of Transportation specifications are most affected, with Caltrans accelerating its transition to specified polyethylene alternatives ahead of federal mandate timelines.
Rental and leasing models are displacing outright purchase for large infrastructure contractors. Turner Construction and Bechtel are consolidating cone fleets through third-party logistics providers that handle inventory rotation, cleaning, and compliance verification. This shift is most visible in Texas urban corridor projects where contractor mobility requirements exceed storage capacity at temporary job sites.
Safety Cones Market Segmentation
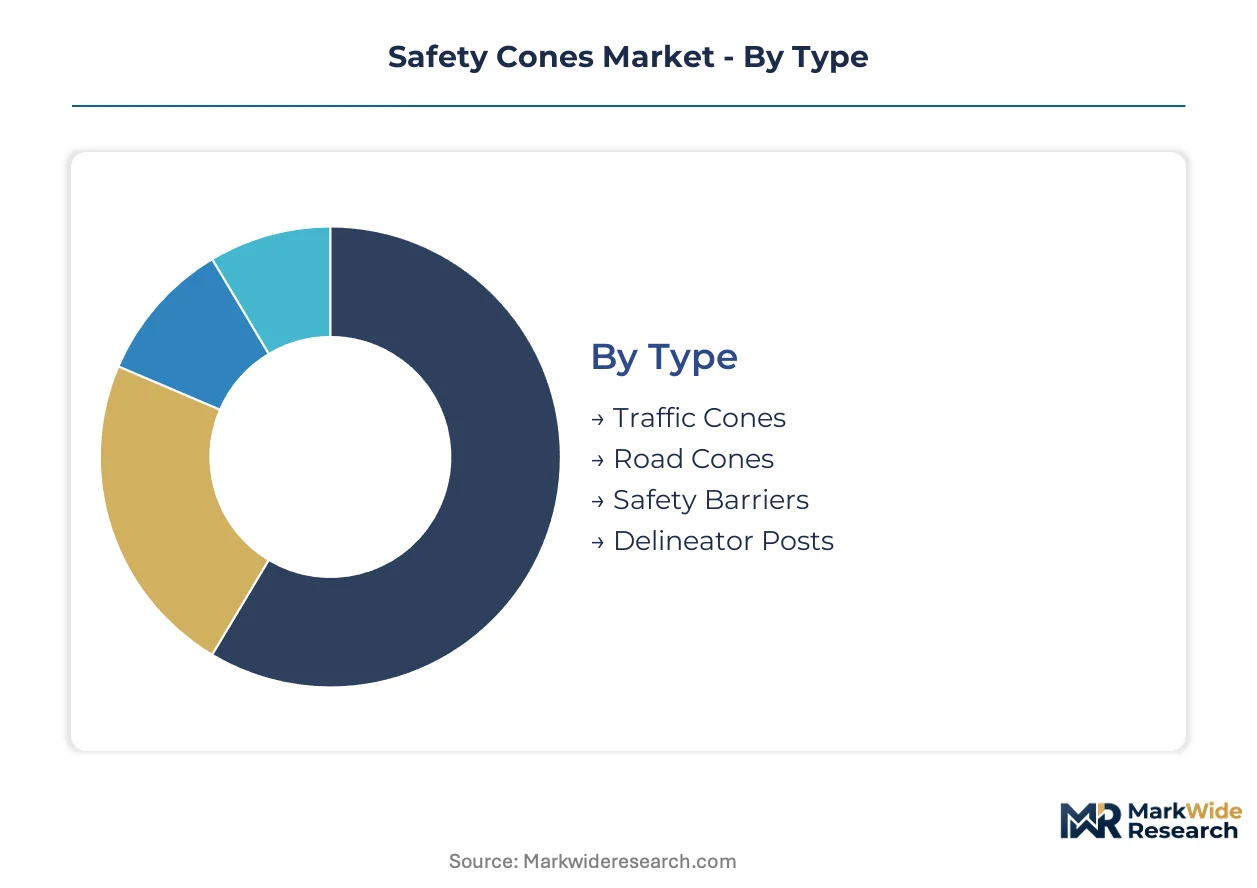
Safety cone procurement patterns diverge sharply between high-volume municipal road programs and specialized emergency response deployments. Specification tiers across type, material, and application dimensions determine vendor eligibility for federal-aid highway contracts and industrial safety mandates.
Type:
Volume concentration favors collapsible, stackable designs for construction logistics, while premium margins attach to stability-engineered highway configurations.
- Traffic Cones:Rotational-molded polyethylene shells with retroreflective collar bands dominate state DOT procurement. California, Texas, and Florida highway maintenance programs specify 28-inch and 36-inch heights for lane closure protocols, with weight requirements that resist wind displacement on elevated roadways.
- Delineator Posts:Flexible polyurethane or rubber composite shafts with surface-mounted reflectors command higher per-unit pricing from agencies prioritizing post-impact recovery. Arizona and Nevada rural highway divisions specify these for unlit corridor marking where vehicle strikes are frequent.
- Road Cones:Injection-molded variants serve temporary parking control and short-duration work zones with lighter base configurations.
- Safety Barriers:Expandable plastic accordion systems channel pedestrian flow at event venues and retail construction fronts.
Mature deployment sits with Traffic Cones. Newer deployment is concentrated in Delineator Posts.
Material:
Environmental compliance timelines are accelerating substitution away from legacy polymer platforms toward validated alternatives.
- Polyethylene:Linear low-density and high-density grades dominate rotational molding for traffic cone bodies. Caltrans specifications now require minimum recycled content thresholds, pressuring molders to secure post-industrial scrap streams.
- Composite:Recycled rubber-polyethylene blends and bio-based fillers are expanding fastest as EPA scrutiny of PVC additives tightens. Manufacturers with verified circular supply chains gain procurement eligibility under emerging federal-aid highway sustainability criteria.
- PVC:Legacy formulations face phthalate plasticizer disclosure mandates; remaining applications concentrate in low-cost construction site orders.
- Rubber:Heavy-base applications for high-wind environments and railroad crossing deployments.
Volume leadership rests with Polyethylene. Composite platforms are climbing the fastest as compliance windows narrow.
Application:
End-use specification intensity varies from prescriptive federal highway standards to discretionary contractor purchasing.
- Road Maintenance:State DOT programs in California, Texas, and Florida mandate MUTCD-compliant retroreflectivity, base weight, and material traceability. Multi-year framework agreements consolidate volume with vendors offering color-coded inventory systems.
- Construction Sites:Large infrastructure contractors standardize cone fleets across multi-state projects, concentrating procurement with national distribution networks. Turner Construction and Bechtel utilize third-party logistics for fleet rotation and compliance verification.
- Emergency Services:NFPA-certified interoperable traffic control kits are gaining federal emergency management framework traction.
- Event Management:Lightweight, stackable configurations prioritize rapid deployment and storage efficiency over durability specifications.
Procurement formalization is deepest in Road Maintenance. Specification flexibility remains widest in Event Management.
Size:
Height and base diameter combinations map directly to regulatory tier and corresponding price bands.
- Standard:28-inch and 36-inch heights satisfy OSHA 29 CFR workplace provisions and MUTCD federal highway standards for lane closure visibility. State DOTs specify these for daytime and nighttime work zone protection.
- Tall:42-inch configurations address high-speed rural highway segments and elevated roadway applications where enhanced sight distance is critical.
- Mini:12-inch and 18-inch variants serve indoor facility marking and pedestrian channeling where vehicle impact risk is minimal.
- Custom:Specialty heights and base configurations accommodate airport tarmac protocols, railroad maintenance, and military base specifications.
Regulatory anchoring is strongest in Standard sizes. Differentiation opportunity concentrates in Custom specifications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for safety cones concentrates in the United States, where state DOT procurement programs and federal highway maintenance mandates drive replacement cycles. Municipal road departments in California, Texas, and Florida account for the dominant share of public-sector volume.
United States
State DOT programs in California, Texas, and Florida are refreshing aging cone inventories under tightened MUTCD visibility mandates. The Federal Highway Administration's updated standards force compliance upgrades across federal-aid highway projects. Los Angeles County and Houston metropolitan corridor maintenance divisions are consolidating multi-year framework agreements with vendors offering color-coded inventory systems.
Germany
Autobahn maintenance authorities are specifying enhanced retroreflective performance for nighttime work zone protection. The country's national road safety regulator enforces strict visibility coefficient thresholds under EU directive harmonization. Bavaria and North Rhine-Westphalia highway agencies are piloting composite material cones with recycled rubber content in rural construction zones.
China
Provincial transportation bureaus are expanding procurement of delineator posts for expressway expansion projects in western regions. The Ministry of Transport's GB standards mandate minimum cone height and base weight specifications for national highway maintenance. Yangtze River Delta infrastructure contractors are standardizing cone fleets across multi-province high-speed rail corridor projects.
India
National highway development programs under the Ministry of Road Transport and Highways are driving volume procurement for four-lane expansion projects. The Bureau of Indian Standards is drafting visibility specifications for temporary traffic control devices on federal road networks. Maharashtra and Karnataka state public works departments are consolidating safety equipment purchases through centralized e-procurement portals.
United Arab Emirates
Dubai and Abu Dhabi municipal infrastructure departments are specifying premium-grade cones for smart city corridor development. The country's federal transport authority mandates EN 13422 compliance for road maintenance equipment on federal highway projects. Sharjah's logistics hub operators are deploying Bluetooth-enabled cones with GPS tracking for port and free zone traffic management.
Safety Cones Market Competitive Landscape
Multi-year framework agreement bidding dominates the current landscape as municipal procurement departments consolidate vendor relationships. The market structures around three tiers: large-scale rotational molders serving state DOT programs, specialized manufacturers of delineator posts for highway agencies, and regional suppliers filling construction site orders. Strategic archetypes include compliance-focused specification leaders, cost-efficient volume producers, and technology-integrated solution providers. Capacity expansion and material platform transitions represent the dominant competitive moves as EPA scrutiny of PVC additives accelerates.
Among American manufacturers, TrafFix Devices and JBC Safety Plastic, Inc. exemplify contrasting scale archetypes in state-level DOT procurement. 3M occupies a position anchoring premium-tier positioning through proprietary reflective sheeting supply to cone collar integrators. OPTSIGNS represents the specialized manufacturer archetype with its Optraffic-branded focus on traffic control equipment for international distribution networks.
| Leading Market Players |
|---|
| OPTSIGNS (Optraffic Brand) |
| Lakeside Plastics, Inc. |
| TrafFix Devices |
| JBC Safety Plastic, Inc. |
| Tolco Corporation |
| Cortina Companies |
| Honeywell |
| 3M |
| Melba Swintex |
| Others |
Value Network & Pricing Analysis
MUTCD certification tiers split the market into specification-locked highway contracts and discretionary construction orders, with this divergence mapping to distinct supply chain footprints: DOT-qualified producers maintain captive reflective sheeting inventories and regional distribution centers, while commodity molders rely on spot resin purchasing and third-party logistics.
Pricing Analysis
Volume-margins concentrate in divergent tiers. Three-tier pricing structure across premium, standard, and economy levels separates 3M-collared highway cones from Caltrans-specified polyethylene bodies and unbranded construction site orders. Price differentiation hinges on retroreflective certification grade and base weight compliance. Cost compression in economy tiers is intensifying because of LLDPE resin volatility. Municipal procurement departments show lowest price sensitivity; event management buyers exhibit highest.
Supply Chain Analysis
Regional distribution centers in Texas, California, and Ohio anchor hub-and-spoke patterns serving state DOT maintenance yards. Manufacturing concentrates in the United States, Mexico, and China. Raw material inputs draw from ethylene feedstock streams, microprismatic sheeting films, and recycled rubber crumb. Single-source retroreflective sheeting vulnerability creates allocation risk during highway construction peaks. Distribution runs through third-party logistics providers handling fleet rotation and compliance verification.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a cost-of-compliance arena where MUTCD retroreflectivity mandates erect barrier-to-entry moats favoring incumbents with validated testing relationships and certified collar formulations.
For Market Incumbents: Anticipate EPA phthalate disclosure mandates by accelerating polyethylene platform transitions ahead of federal-aid highway sustainability criteria. Secure backward integration into post-industrial scrap streams to defend margin position against recycled content thresholds. Prioritize rotational molding technician retention programs to offset wage premiums eroding cost competitiveness against injection-molded alternatives. For New Entrants and Emerging Players: Begin with Bluetooth-enabled cone development for smart city asset management platforms, where data-service revenue streams remain uncontested by legacy hardware vendors. Target emergency response standardization under federal frameworks mandating NFPA-certified interoperable traffic control kits. Deploy direct-to-contractor e-commerce channels to disintermediate regional safety equipment distributors capturing 15-20 point margin spreads. For Investors and Strategic Acquirers: Re-rating potential sits with composite material specialists given EPA scrutiny of PVC additives accelerating specification windows for validated circular supply chains. Long-term viability favors manufacturers with dual-platform flexibility across polyethylene and rubber-polyethylene blends. Monitor Caltrans procurement bulletins as inflection signal for federal-aid highway sustainability criteria adoption timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Composite Material Platform Transition | EPA phthalate scrutiny positions recycled rubber-polyethylene blends for federal-aid highway eligibility. |
| Retroreflective Sheeting Backward Integration | Captive microprismatic collar supply insulates against allocation constraints during construction season peaks. |
| Smart City Technology Partnership | Bluetooth-enabled GPS tracking converges with municipal asset management platforms for recurring revenue. |
| Multi-Year Framework Agreement Bidding | Color-coded inventory systems secure volume consolidation with California, Texas, and Florida DOT programs. |
| Third-Party Logistics Fleet Consolidation | Turner Construction and Bechtel utilization signals rental model displacement of outright purchase. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, cross-referenced with primary interviews involving state DOT procurement officers, rotational molding plant managers, infrastructure contractor safety directors, and third-party logistics providers. Federal Highway Administration MUTCD documentation, OSHA 29 CFR workplace safety provisions, EPA material safety data sheet repositories, and state DOT specification bulletins supplied validation layers. Bottom-up segment sizing reconciled against top-down market triangulation.
Data-stream reconciliation across shipment volumes, resin pricing indices, and procurement contract values structured the analytical framework. Segmentation dimensions spanned cone type, material platform, application intensity, and height specification tier across the analysis window. CAGRs derived from regression against infrastructure appropriation trajectories and replacement cycle assumptions. Retroreflectivity certification timelines and skilled technician wage trends informed industry-specific forecast inputs.
Underlying measurement precision varies by segment; DOT-qualified highway contracts carry tighter precision than discretionary event management estimates. Forecasts reflect documented assumptions regarding MUTCD compliance timelines, EPA regulatory finalization, and infrastructure appropriation levels. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Safety Equipment and Personal Protective Equipment (PPE)
Riot Gear Market
Safety Equipment and Personal Protective Equipment (PPE)
Healthcare Personal Protective Equipment (PPE) Market
Safety Equipment and Personal Protective Equipment (PPE)
Hearing Protection Devices Market
Safety Equipment and Personal Protective Equipment (PPE)
US Safety Helmet Market
Safety Equipment and Personal Protective Equipment (PPE)
Passenger Security Equipment Market
Safety Equipment and Personal Protective Equipment (PPE)
Saudi Arabia Personal Protective Equipment Market
Safety Equipment and Personal Protective Equipment (PPE)
Spill Kits Market
Safety Equipment and Personal Protective Equipment (PPE)
Bulletproof Helmet Market
Safety Equipment and Personal Protective Equipment (PPE)
Cut Resistant Gloves Market
Safety Equipment and Personal Protective Equipment (PPE)
Drone Safety Systems Market
Safety Equipment and Personal Protective Equipment (PPE)
Crash Barrier Systems Market
Safety Equipment and Personal Protective Equipment (PPE)
Human Airbag Wearable Market
Safety Equipment and Personal Protective Equipment (PPE)
Smart Barrier Gate Market
Safety Equipment and Personal Protective Equipment (PPE)
Protective Gowns Market
Safety Equipment and Personal Protective Equipment (PPE)
Global Protective Gloves Market
Safety Equipment and Personal Protective Equipment (PPE)
Anti-Static Safety Clothing Market