
 Global Protective Gloves Market | 2026-2036
Global Protective Gloves Market Size, Share, and Industry Trends Forecast 2026-2036
Global Protective Gloves Market Outlook
Subscription-based glove replenishment programs for industrial facilities is expanding as buyers shift from spot purchasing to contracted consumption models. Ansell Limited leverages direct distribution networks to secure multi-year supply agreements with automotive manufacturers. Top Glove Corporation Bhd sustains cost leadership through integrated latex sourcing and plantation-to-factory production control. Honeywell International Inc. differentiates via connected safety platforms that embed glove-wear sensors into broader personal protective equipment ecosystems.
Protective gloves are engineered barriers worn on the hands to shield against mechanical, chemical, thermal, or biological hazards, typically constructed from nitrile, natural rubber latex, neoprene, or aramid fibers with thickness specifications ranging from 3 mil for medical disposables to 22 mil for heavy industrial cut-resistant variants. Their primary purpose is to prevent occupational injury, cross-contamination, and dermatological exposure across regulated work environments. The disposable segment dominates volume due to healthcare and food service consumption patterns, while chemical-resistant gloves command premium pricing in petrochemical and laboratory settings. Nitrile material demand is accelerating fastest as latex allergy concerns and oil-based chemical protection requirements displace natural rubber across European and North American industrial buyers.
The U.S. Occupational Safety and Health Administration mandates hand-protection assessments under 29 CFR 1910.138, while the European Union enforces CE marking and conformity to EN ISO 374 chemical-permeation standards through the PPE Regulation. India's Bureau of Indian Standards has progressively tightened IS 6994 specifications for industrial leather and cotton gloves, compelling domestic manufacturers to upgrade testing infrastructure. Stakeholders must monitor evolving bio-based polymer certifications and regional carbon-border adjustments that will reshape material sourcing decisions and factory location strategies.
Market Dynamics
The protective gloves market is being fundamentally reshaped by nitrile's displacement of natural rubber latex across industrial and medical applications, driven by allergy mitigation and superior chemical resistance against petroleum-based solvents.
Growth Catalysts
- OSHA 29 CFR 1910.138 enforcement:United States workplace safety inspections are mandating documented hand-hazard assessments, compelling manufacturing facilities to standardize glove procurement and increase consumption volumes across metal fabrication and chemical processing plants.
- EU PPE Regulation (EU) 2016/425:CE marking requirements and EN ISO 374 chemical-permeation testing are elevating certification barriers, filtering out uncertified suppliers and consolidating demand toward compliant manufacturers serving laboratory and petrochemical end-users.
- Southeast Asia healthcare procurement:Government hospital expansion programs in Thailand, Vietnam, and Indonesia are scaling nitrile examination glove tenders, with public health ministries centralizing purchasing to secure pandemic-resilient supply chains.
Market Restraints
- Acrylonitrile butadiene price volatility:Nitrile glove production depends on petrochemical feedstock costs that track crude oil and natural gas fluctuations, compressing margins during energy price spikes without corresponding pricing power.
- Malaysian production concentration:Over 60% of global nitrile glove capacity remains clustered in Malaysian industrial zones, creating geographic supply vulnerability to flooding, labor disruptions, or export licensing changes.
- Biodegradability limitations:Synthetic nitrile polymers resist microbial decomposition, exposing users to rising landfill restrictions and extended producer responsibility frameworks in Germany and France.
Strategic Opportunities
- India industrial safety enforcement:State-level factory inspectorates are implementing BIS IS 6994 compliance deadlines, creating first-time demand for certified industrial gloves among small and medium manufacturing enterprises previously operating unprotected.
- Connected PPE ecosystems:Integration of glove-wear sensors with industrial IoT platforms enables real-time tear detection and usage analytics, opening premium service contracts with automotive and aerospace assembly operations.
- Bio-based polymer certifications:Emerging standards for renewable-content verification position early adopters to capture sustainability-driven procurement mandates from European healthcare systems and food processors.
Industry Challenges
- EN ISO 374-1:2016 type-testing backlog:Chemical-resistance certification requires extended permeation testing cycles, delaying new product launches and trapping inventory in pre-market approval queues.
- Multi-material formulation expertise:Developing gloves combining cut-resistant aramid liners with chemical-resistant nitrile coatings demands polymer science talent scarce outside established industrial hubs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Protective Gloves Market |
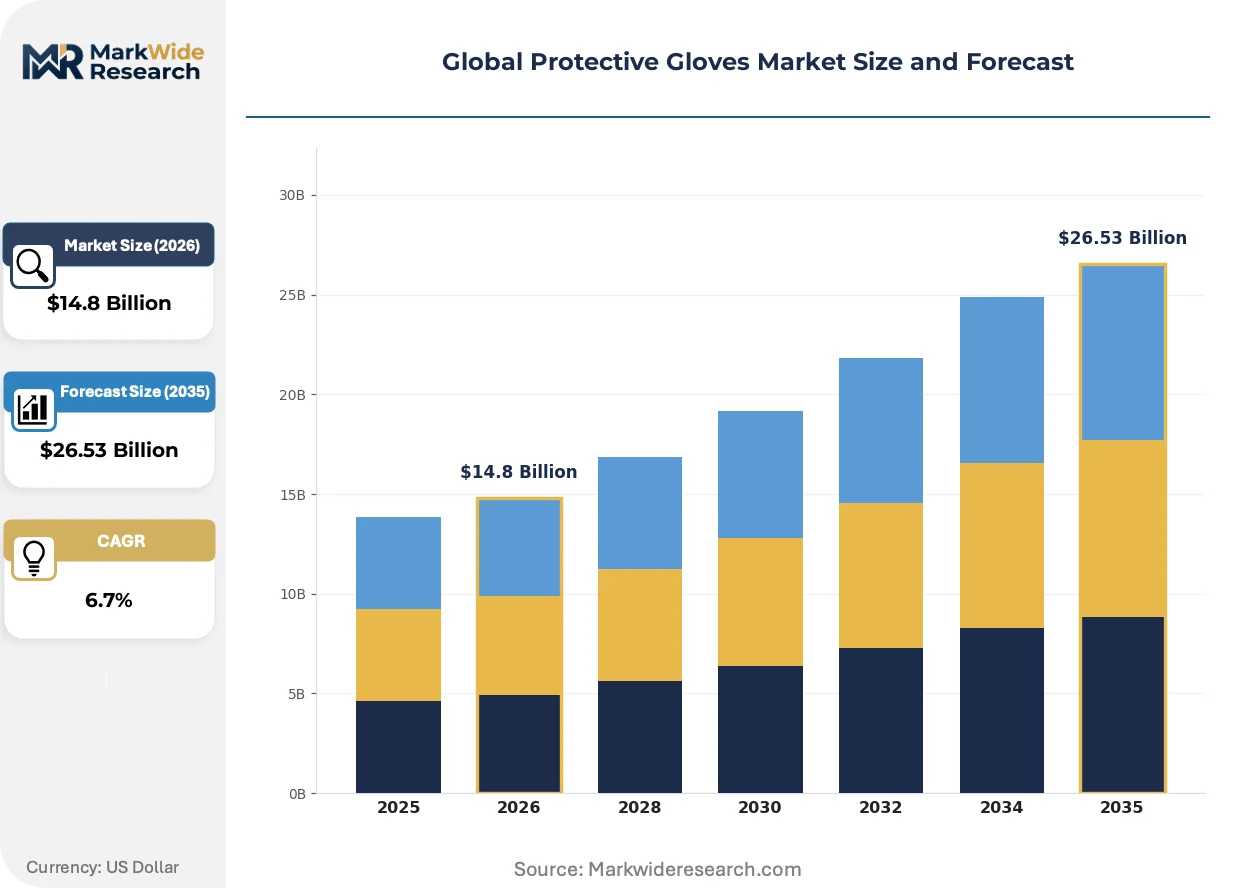
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $26.53 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Disposable, Reusable, Chemical-Resistant, Heat-Resistant Material: Latex, Nitrile, Vinyl, Rubber End User: Healthcare, Food Service, Industrial, Laboratory Application: Medical, Construction, Food Processing, Automotive |
| Companies Covered | Top Glove Corporation Bhd, Lakeland Industries, 3M, Mallcom, Superior Glove Works Limited, Ansell Limited, Delta Plus Group, Radians Inc., Honeywell International Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Protective Gloves Market Strategic Shifts
Material science breakthroughs and digital integration are compressing product lifecycles while elevating performance thresholds, with regulatory stringency acting as the primary accelerant for technology adoption across manufacturing and healthcare.
Smart glove technology embedding force-sensitive resistors and near-field communication tags is converging with industrial safety management platforms, enabling real-time grip-force monitoring and automatic replacement alerts. Automotive manufacturers in Germany and Japan are piloting these systems to reduce repetitive strain injuries and optimize inventory replenishment. The structural consequence is a shift from commodity volume sales toward integrated safety-as-a-service contracts bundling hardware, software, and maintenance.
REACH Annex XVII restrictions on polycyclic aromatic hydrocarbons in extender oils are forcing reformulation of nitrile compounds used in heavy industrial gloves, with ECHA compliance deadlines compressing supplier qualification timelines. Compounders serving petrochemical and mining sectors must retest entire product lines against revised migration limits. German TÜV and DEKRA certification bodies are reporting 40% increases in glove resubmission volumes as manufacturers race to maintain market access.
Subscription replenishment programs are displacing spot purchasing among North American food processing and pharmaceutical manufacturers, with buyers locking multi-year unit-price agreements against guaranteed volume commitments. Distributors are consolidating supplier relationships to offer single-source managed inventory services. This pattern is most pronounced in California and Illinois, where large-scale protein processing facilities and generic drug manufacturers prioritize supply continuity over per-unit cost minimization.
Global Protective Gloves Market Segmentation
Protective glove procurement decisions hinge on hazard specificity, regulatory compliance tiers, and total cost of ownership calculations across disposable and durable categories. Material chemistry and end-use certification requirements create distinct supply chains that rarely overlap.
Product Type:
Supply concentration clusters around high-volume disposable lines where Malaysian and Thai manufacturers dominate nitrile capacity.
- Disposable:Single-use nitrile and latex barriers engineered for 3-8 mil thickness specifications. Demand concentrates in U.S. healthcare systems consolidating procurement through group purchasing organizations to meet OSHA bloodborne pathogen standards.
- Reusable:Multi-shift leather, cotton, and synthetic blends with 30-60 wash cycle durability. German automotive assembly plants and Japanese precision manufacturing facilities drive specification tightening for cut-resistant woven liners.
- Chemical-Resistant:Neoprene and butyl rubber compounds exceeding 15 mil thickness for petrochemical handling. EN ISO 374-1:2016 Type A certification requirements filter supplier pools serving ECHA-regulated European laboratories.
- Heat-Resistant:Aramid fiber and aluminized fabric constructions rated to 500°C for foundry and welding applications. Demand localizes near steel production clusters in India and China.
Today's leader: Disposable. Tomorrow's challenger: Chemical-Resistant.
Material:
Cost tier stratification separates premium nitrile formulations from commodity vinyl alternatives.
- Latex:Natural rubber hevea brasiliensis derivatives with superior elasticity and tactile sensitivity. Allergy prevalence in U.S. and European healthcare workforces accelerates displacement by synthetic alternatives.
- Nitrile:Acrylonitrile butadiene copolymers delivering petroleum solvent resistance and puncture durability. Southeast Asian plantation-to-factory integration secures cost advantage for Malaysian producers serving FDA-regulated medical device channels.
- Vinyl:Polyvinyl chloride plastisol formulations at 30-40% cost discount to nitrile. Food service and janitorial applications in price-sensitive emerging markets sustain volume despite inferior chemical resistance.
- Rubber:Neoprene, butyl, and natural rubber heavy industrial compounds. Petrochemical and mining operations in Alberta and Texas specify these for extended immersion protection against aromatic solvents.
Today's leader: Nitrile. Tomorrow's challenger: Latex (in specialized surgical micro-thin variants).
End User:
Application-driven volume distribution concentrates procurement authority in distinct buyer archetypes.
- Healthcare:Hospitals, clinics, and long-term care facilities governed by CDC hand hygiene protocols and FDA medical device classification. U.S. acute care systems standardize on cobalt-blue nitrile examination gloves for bloodborne pathogen compliance.
- Food Service:Commercial kitchens and protein processing plants requiring HACCP-aligned color-coded glove programs. USDA-FSIS inspected facilities mandate single-use barriers for raw meat handling.
- Industrial:Manufacturing, construction, and logistics operations subject to OSHA 29 CFR 1910.138 hazard assessments. Metal fabrication and chemical processing plants drive specification diversity.
- Laboratory:Research institutions and diagnostic facilities requiring chemical permeation resistance and particulate control. EN ISO 374 compliance dominates European academic and pharmaceutical R&D procurement.
Today's leader: Healthcare. Tomorrow's challenger: Industrial (as India's BIS enforcement expands).
Application:
Geographic production clusters align with end-use certification requirements and regional regulatory stringency.
- Medical:Examination, surgical, and emergency response applications requiring FDA 510(k) or CE-MDR conformity. Thai and Malaysian exporters dominate sterile and non-sterile supply to U.S. and EU distribution channels.
- Construction:Cut-resistant and impact-protection gloves for framing, concrete work, and heavy equipment operation. German BauBG safety regulations and U.S. OSHA construction standards drive specification convergence.
- Food Processing:High-volume protein, dairy, and produce handling with allergen control and metal detectability requirements. Illinois and California processing facilities lead North American subscription replenishment adoption.
- Automotive:Precision assembly, paint shop, and battery manufacturing with ESD and chemical resistance specifications. German OEMs and Japanese tier-1 suppliers specify connected PPE integration trials.
Today's leader: Medical. Tomorrow's challenger: Automotive (via smart glove platform bundling).
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States healthcare systems consume cobalt-blue nitrile examination gloves at volumes exceeding German industrial procurement, while Malaysian factory zones supply both markets through divergent certification pathways. Regulatory stringency and end-use specialization create distinct demand profiles across major economies.
United States
OSHA 29 CFR 1910.138 workplace inspections are compelling metal fabrication and chemical processing plants to standardize documented hand-hazard assessments. FDA 510(k) medical device classification governs hospital procurement through group purchasing organizations. Illinois and California protein processing facilities lead subscription-based replenishment adoption for supply continuity.
Germany
Automotive OEMs in Bavaria and Baden-Württemberg are piloting smart glove platforms with embedded force-sensitive resistors for real-time grip monitoring. ECHA REACH Annex XVII restrictions on polycyclic aromatic hydrocarbons are forcing nitrile compound reformulation for heavy industrial lines. TÜV and DEKRA certification bodies report surging resubmission volumes as manufacturers race to maintain market access.
India
BIS IS 6994 compliance deadlines for industrial leather and cotton gloves are creating first-time certified demand among small and medium manufacturing enterprises. State-level factory inspectorates in Maharashtra and Gujarat are tightening enforcement. Tamil Nadu and Karnataka industrial clusters are upgrading testing infrastructure to meet specification requirements.
Malaysia
Integrated plantation-to-factory production control sustains cost leadership in nitrile examination glove supply. Over 60% of global nitrile glove capacity concentrates in Malaysian industrial zones, creating geographic vulnerability to flooding or labor disruptions. Thai and Malaysian exporters dominate sterile and non-sterile supply to U.S. and EU distribution channels.
Japan
Precision manufacturing facilities in the Chubu region around Nagoya are driving specification tightening for cut-resistant woven liners. METI industrial safety guidelines are elevating performance thresholds for multi-shift reusable gloves. Automotive tier-1 suppliers are specifying connected PPE integration trials for assembly line optimization.
Global Protective Gloves Market Competitive Environment
Top-tier vendors anchor premium certification tiers, while mid-scale fabricators compete on volume throughput and regional logistics. The protective gloves market structures around three distinct archetypes: integrated petrochemical-to-glove producers controlling acrylonitrile butadiene feedstock, specialized safety distributors bundling multi-category PPE portfolios, and technology-forward developers embedding sensors into wearable barriers. Capacity expansion and backward integration into raw polymer supply represent the dominant competitive moves as margin pressure intensifies.
Within the integrated production archetype, Top Glove Corporation Bhd exemplifies plantation-to-factory vertical control, while Ansell Limited and Honeywell International Inc. occupy positions bridging industrial distribution with technology-enabled safety ecosystems. These three entities represent contrasting strategic postures: feedstock-captive manufacturing, direct distribution network leverage, and connected platform bundling respectively.
| Leading Market Players |
|---|
| Top Glove Corporation Bhd |
| Lakeland Industries |
| 3M |
| Mallcom |
| Superior Glove Works Limited |
| Ansell Limited |
| Delta Plus Group |
| Radians Inc. |
| Honeywell International Inc. |
| Others |
Value Chain & Pricing Dynamics
Subscription replenishment programs among North American food processing and pharmaceutical manufacturers are compressing spot-market liquidity and forcing suppliers toward multi-year unit-price agreements with guaranteed volume commitments.
Pricing Analysis
Capacity additions in Vietnam and Thailand are reshaping price floors for nitrile examination gloves, eroding Malaysian cost premiums. Three-tier pricing structure across FDA-cleared medical grade, industrial certified, and economy vinyl tiers separates premium from standard from economy offerings. Pricing pressure stems from acrylonitrile butadiene feedstock volatility tracking crude oil fluctuations. Food service buyers exhibit highest price sensitivity, while laboratory and petrochemical procurement prioritizes EN ISO 374 certification over per-unit cost.
Supply Chain Analysis
Regional distribution centers in Rotterdam, Singapore, and Los Angeles anchor hub-and-spoke patterns serving European, Asian, and North American demand clusters. Manufacturing concentrates in Malaysia, Thailand, and Vietnam, with acrylonitrile butadiene rubber, natural rubber latex, and aramid fibers as critical inputs. Single-source vulnerability to Malaysian flooding and labor disruptions creates structural risk. Distribution runs through specialized safety distributors and integrated PPE platforms rather than commodity wholesale channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder, with OSHA 29 CFR 1910.138 enforcement in the United States and EU PPE Regulation (EU) 2016/425 compliance deadlines systematically expanding mandated consumption volumes across industrial and healthcare sectors.
For Market Incumbents: Deepen backward integration into acrylonitrile butadiene feedstock to defend margin position against petrochemical price volatility. Expand certified production capacity in India ahead of BIS IS 6994 enforcement deadlines. Prioritize EN ISO 374-1:2016 Type A certification investment to filter out uncertified competitors serving European laboratory markets.
For New Entrants and Emerging Players: Begin with India's small and medium manufacturing enterprises in Maharashtra and Gujarat, where first-time certified glove demand is emerging from previously unprotected operations. Target chemical-resistant glove segments where permeation-testing backlogs delay incumbent product launches. Pursue direct relationships with state-level factory inspectorates as a go-to-market angle.
For Investors and Strategic Acquirers: Asymmetric upside sits with integrated plantation-to-factory producers controlling natural rubber latex supply and nitrile compound formulation expertise. Five-to-ten-year viability favors feedstock-captive manufacturing archetypes over pure-play distributors. Watch for bio-based polymer certification standards as an inflection indicator for sustainability-driven procurement mandates.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Feedstock | Captive acrylonitrile butadiene supply insulates margins from crude oil volatility. |
| Smart Glove Platform Development | Embedded sensors enable automotive OEMs to optimize assembly line safety protocols. |
| India Manufacturing Footprint Expansion | BIS IS 6994 compliance deadlines create first-time certified demand among SMEs. |
| Bio-Based Polymer Certification | Renewable-content verification positions suppliers for European sustainability mandates. |
| Multi-Year Supply Agreements | Subscription models lock in volume commitments from food processing and pharmaceutical buyers. |
Study Parameters
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each region combined with secondary validation. Interviews with plant safety managers, procurement leads at automotive OEMs, hospital GPO contract managers, and nitrile compound R&D directors informed demand-side assessments. Secondary sources include OSHA enforcement data, EU PPE Regulation compliance filings, FDA 510(k) clearances, and customs trade records. Bottom-up volume modeling and top-down market sizing were triangulated to derive segment-level outputs.
Granularity extends to product type, material chemistry, end-user industry, and application across the projection horizon. Segmentation dimensions include disposable versus reusable categories, nitrile versus latex versus vinyl formulations, and healthcare versus industrial versus food service end-use. CAGRs were derived from regression analysis against regulatory enforcement timelines and procurement pattern shifts. Forecast inputs incorporated OSHA inspection frequency data and BIS compliance deadline schedules.
Several conditions sit outside the modeled scope, including abrupt changes to Malaysian export licensing, extreme weather disruptions to plantation operations, and unanticipated REACH Annex XVII chemical restrictions. Forecasts reflect assumptions about regulatory enforcement continuity and feedstock price correlation patterns. Stakeholders should weight assumptions against their own operating context and regional supply chain exposures.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Safety Equipment and Personal Protective Equipment (PPE)
Disposable Respirator Market
Safety Equipment and Personal Protective Equipment (PPE)
Drone Safety Systems Market
Safety Equipment and Personal Protective Equipment (PPE)
Safety Mirrors Market
Safety Equipment and Personal Protective Equipment (PPE)
Americas Reusable Gloves Market
Safety Equipment and Personal Protective Equipment (PPE)
Ship Life-Saving Equipment Market
Safety Equipment and Personal Protective Equipment (PPE)
Tourniquet Cuffs Market
Safety Equipment and Personal Protective Equipment (PPE)
Personal Protective Equipment Packaging Market
Safety Equipment and Personal Protective Equipment (PPE)
Hand Sanitizer Spray Pen Market
Safety Equipment and Personal Protective Equipment (PPE)
Global Personal Protective Equipment Kit Market
Safety Equipment and Personal Protective Equipment (PPE)
US Safety Helmet Market
Safety Equipment and Personal Protective Equipment (PPE)
Smart Seat Belt Technology Market
Safety Equipment and Personal Protective Equipment (PPE)
Armoured Thermocouple Market
Safety Equipment and Personal Protective Equipment (PPE)
Protective Eye Wear Market
Safety Equipment and Personal Protective Equipment (PPE)
Safety Light Curtains Market
Safety Equipment and Personal Protective Equipment (PPE)
Household Smart Safe Market
Safety Equipment and Personal Protective Equipment (PPE)
Human Airbag Wearable Market