
 Fall Protection Equipment Market | 2026-2036
Fall Protection Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Fall Protection Equipment Market Intelligence
Chinese textile and hardware manufacturers is broadening the supply base for webbing and alloy hardware used in harness assemblies. WernerCo leverages its vertical integration across ladder and climbing systems to extend into fall protection kits. 3M Company sustains R&D intensity in self-retracting device engineering through its industrial safety division. Honeywell International Inc. anchors its position via channel control through safety distribution networks serving oil and gas contractors.
Fall protection equipment encompasses body-worn systems and engineered anchorage designed to arrest or eliminate falls from elevated work positions, typically constructed from high-tenacity polyester webbing rated above 5,000 pounds tensile strength and aluminum or steel alloy hardware meeting ANSI Z359.12 connector specifications. These systems serve the primary commercial purpose of preventing fatal and lost-time injuries in environments where workers operate at heights exceeding four feet without continuous guardrail protection. Harnesses and self-retracting devices command the largest share of product-type revenue pools, while wind energy installations represent the fastest-growing application segment as turbine tower heights exceed 150 meters and maintenance access protocols intensify. Deployment preferences are shifting toward integrated systems that combine fixed anchor networks with portable rescue capabilities, particularly in telecommunications and warehousing environments where work locations change frequently.
OSHA enforces 29 CFR 1926.501 for construction fall protection and 29 CFR 1910.140 for general industry, mandating body harness use rather than body belts and triggering equipment replacement after arrested falls. The EU's PPE Regulation 2016/425 requires Module B+C2 or D conformity assessment for Category III fall arrest equipment, creating compliance cost barriers for non-European manufacturers seeking CE marking. China's GB 24542 and GB 24543 national standards govern fall arrest and restraint systems through the country's standardization administration. Stakeholders must monitor regulatory divergence between ANSI Z359 harmonization efforts and emerging market-specific certification requirements as procurement specifications increasingly specify multi-standard compliance.
Market Dynamics
OSHA's 29 CFR 1926.501 mandate eliminating body belts in favor of full-body harnesses has compressed replacement cycles and forced distributors to clear legacy inventory, reshaping procurement patterns across North American construction and energy maintenance operations.
Growth Catalysts
- EU PPE Regulation 2016/425:Category III conformity assessment requirements for fall arrest equipment are filtering out uncertified suppliers and consolidating demand around tested manufacturers serving European wind energy contractors.
- Wind turbine height escalation:Towers exceeding 150 meters require specialized self-retracting lifelines and guided fall arrest systems, expanding equipment specifications for offshore and onshore maintenance crews.
- Polyester webbing supply base:Chinese textile manufacturers are scaling high-tenacity fiber production, reducing raw material lead times for harness assemblers serving infrastructure projects.
Market Restraints
- Aluminum alloy price volatility:Connector and carabiner hardware faces input cost pressure from energy-intensive smelting operations concentrated in specific production zones.
- CE marking compliance costs:Module B+C2 or D assessment pathways create capital barriers for non-European manufacturers seeking European market access.
- Inspection and recertification burden:Post-arrest equipment replacement mandates under OSHA 1926.501 inflate total cost of ownership for high-frequency use environments.
Strategic Opportunities
- Telecommunications infrastructure:5G small-cell deployment and tower densification create demand for portable anchor systems in urban and suburban maintenance settings.
- Integrated rescue capability:Convergence of fixed anchor networks with descent devices addresses warehousing and logistics verticals where work locations shift daily.
- India's construction safety enforcement:Strengthened building code implementation at state level is creating first-time harness demand among informal sector contractors.
Industry Challenges
- Competent person training gaps:Qualified harness inspectors and rescue planners remain scarce in secondary construction markets, limiting safe deployment scale.
- Multi-standard certification complexity:Simultaneous ANSI Z359, EN 360, and GB 24542 compliance requirements extend product development timelines and testing expenditures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fall Protection Equipment Market |
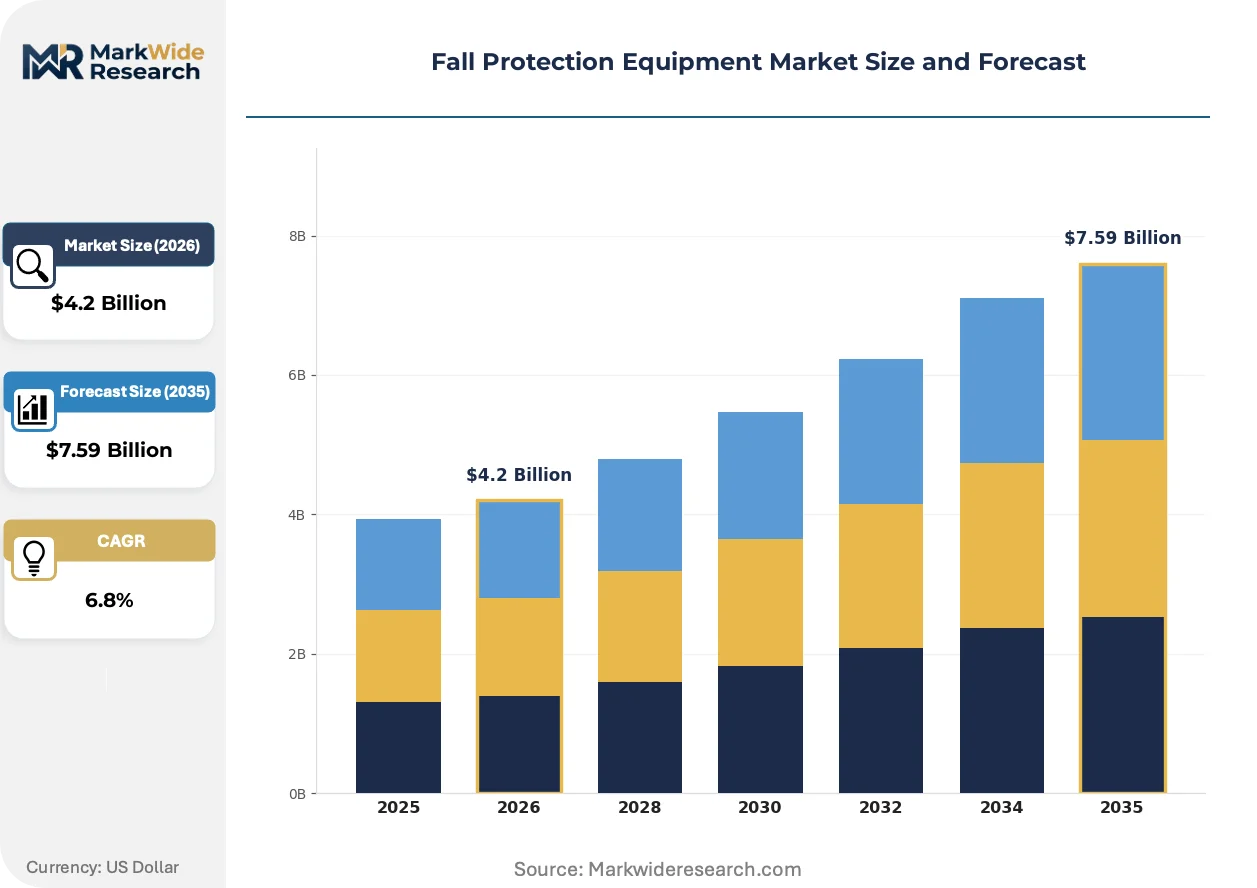
| Market Size in 2026 | $4.2 Billion |
| Market Size in 2035 | $7.59 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Harnesses, Lanyards, Lifelines, Anchor Points, Self-Retracting Devices, Fall Arresters Application: Construction, Oil & Gas Platforms, Telecommunications Towers, Wind Energy Installations, Warehousing, Mining End User: Contractors, Maintenance Personnel, Safety Inspectors, Equipment Operators, Facility Managers Deployment Type: Fixed Systems, Portable Systems, Temporary Systems, Integrated Systems, Mobile Platforms |
| Companies Covered | WernerCo, SKYLOTEC GmbH, 3M Company, Guardian Fall Protection, Petzl Group, Honeywell International Inc., FallTech, Kee Safety Inc., MSA Safety Incorporated, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fall Protection Equipment Market Strategic Shifts & Innovations
Connected safety systems and advanced materials are compressing the gap between passive protection and active hazard monitoring, with equipment vendors embedding sensors directly into load-bearing components.
Self-retracting devices with integrated load-indicating swivels are overtaking conventional shock-absorbing lanyards in oil and gas platform maintenance. Offshore contractors in the Gulf of Mexico are specifying these units for 100% tie-off protocols. The technology is overtaking legacy lanyard configurations by eliminating pendulum swing hazards and reducing clearance requirements in confined derrick structures.
REACH substance restrictions on chromate conversion coatings are forcing hardware manufacturers toward trivalent chromium and zinc-nickel plating alternatives. Surface treatment suppliers serving fall protection OEMs have reformulated pretreatment lines to maintain corrosion resistance ratings. European distributors now require coating compliance documentation before stocking alloy connectors and anchor components.
Rental and leasing models for high-value self-retracting lifelines are displacing outright purchase in seasonal construction and turnaround maintenance sectors. Equipment service providers in Texas and Alberta are building captive inspection and recertification capabilities to support recurring revenue streams. This pattern concentrates most visibly in energy sector contracting where project duration uncertainty discourages capital equipment commitment.
Fall Protection Equipment Market Segmentation
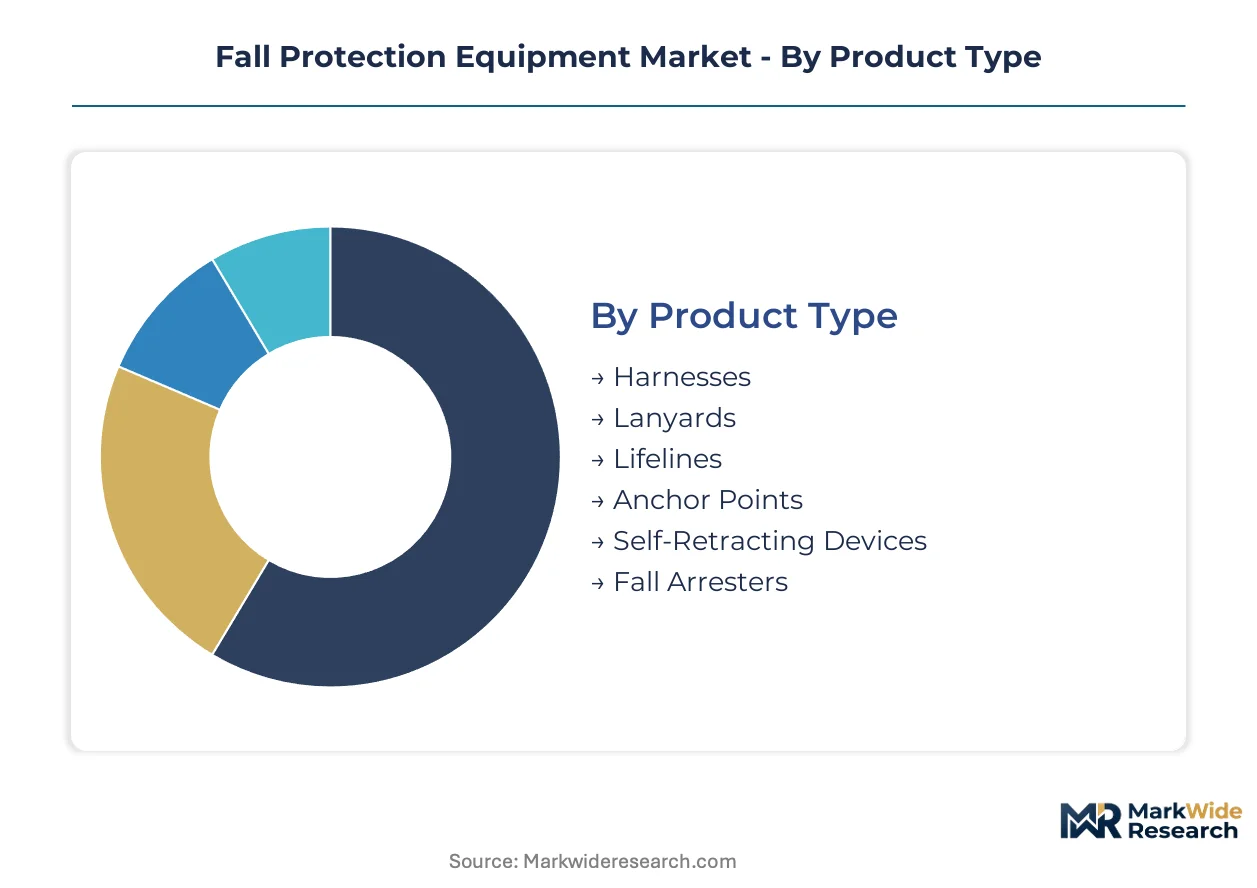
Segmentation in fall protection equipment reveals how certification requirements, deployment complexity, and end-user sophistication create distinct procurement patterns. Manufacturers configure product portfolios around specific hazard profiles rather than pursuing undifferentiated coverage.
Product Type:
ANSI Z359.11 governs full-body harnesses while EN 360 and EN 795 apply to self-retracting devices and anchor devices respectively, creating divergent testing burdens across segments.
- Harnesses:Full-body configurations constructed from high-tenacity polyester webbing rated above 5,000 pounds tensile strength dominate contractor procurement in the United States. OSHA's 29 CFR 1926.501 mandate eliminating body belts has compressed replacement cycles across North American construction sites.
- Self-Retracting Devices:These units integrate centrifugal braking mechanisms with load-indicating swivels to eliminate pendulum swing hazards. Gulf of Mexico offshore contractors specify these for 100% tie-off protocols in confined derrick structures where clearance is minimal.
- Lanyards:Shock-absorbing configurations remain common in general industry applications with lower frequency of use.
- Lifelines:Horizontal and vertical systems serve fixed installation requirements in wind turbine towers exceeding 150 meters.
- Anchor Points:Permanent and temporary anchorage devices must meet EN 795 Class A or B specifications for European wind energy deployment.
- Fall Arresters:Guided type fall arresters on rigid rails address specialized climbing applications in telecommunications infrastructure.
Harnesses sit at the top of the volume ranking, with self-retracting devices climbing the fastest.
Application:
Cost tier stratification separates capital-intensive permanent installations from consumable personal equipment in project-based contracting.
- Construction:General contractors face the steepest compliance burden under OSHA 1926.501, driving recurring harness replacement after arrested falls. Residential and commercial building activity in the United States and Germany concentrates demand for standard-duty full-body harnesses.
- Wind Energy Installations:Turbine tower heights exceeding 150 meters require specialized self-retracting lifelines and guided fall arrest systems. Offshore and onshore maintenance crews in Northern Europe and China specify equipment meeting both EN and GB standards.
- Oil & Gas Platforms:North Sea and Gulf of Mexico operators mandate 100% tie-off with integrated rescue capability.
- Telecommunications Towers:5G small-cell deployment creates demand for portable anchor systems in urban maintenance settings.
- Warehousing:E-commerce fulfillment centers specify integrated systems combining fixed anchor networks with descent devices.
- Mining:Underground and surface operations in Australia and South Africa require flame-resistant harness materials.
Construction commands the largest installed base, while wind energy installations expand most quickly.
End User:
Competent person training gaps fragment the customer base between qualified safety professionals and informal sector contractors lacking inspection capability.
- Contractors:Construction and energy sector contractors in the United States, Germany, and China drive volume procurement through distributor relationships. These buyers prioritize ANSI Z359 and EN 363 compliance documentation for liability protection.
- Maintenance Personnel:Wind turbine technicians and telecommunications tower climbers require specialized training in rescue planning and equipment inspection.
- Safety Inspectors:Qualified inspectors enforce recertification schedules and post-arrest equipment replacement mandates.
- Equipment Operators:Crane and aerial lift operators need restraint systems rather than full arrest configurations.
- Facility Managers:Warehousing and manufacturing facilities specify fixed systems with integrated rescue for multi-user environments.
Contractors represent the dominant procurement channel, with maintenance personnel gaining share fastest.
Deployment Type:
Supply concentration in Chinese textile and alloy hardware manufacturing favors integrated system assemblers with captive sourcing relationships.
- Integrated Systems:Convergence of fixed anchor networks with portable rescue capabilities addresses telecommunications and warehousing verticals where work locations shift daily. These configurations command premium positioning through reduced total cost of ownership.
- Fixed Systems:Permanent installations in wind turbines and oil platforms require EN 795-compliant anchor devices with 30-year design life.
- Portable Systems:Temporary anchorage devices serve 5G small-cell deployment and urban telecommunications maintenance.
- Temporary Systems:Construction sites specify reusable horizontal lifelines for phase-specific protection.
- Mobile Platforms:Aerial work platforms with integrated guardrail and harness attachment points reduce fall exposure in warehousing.
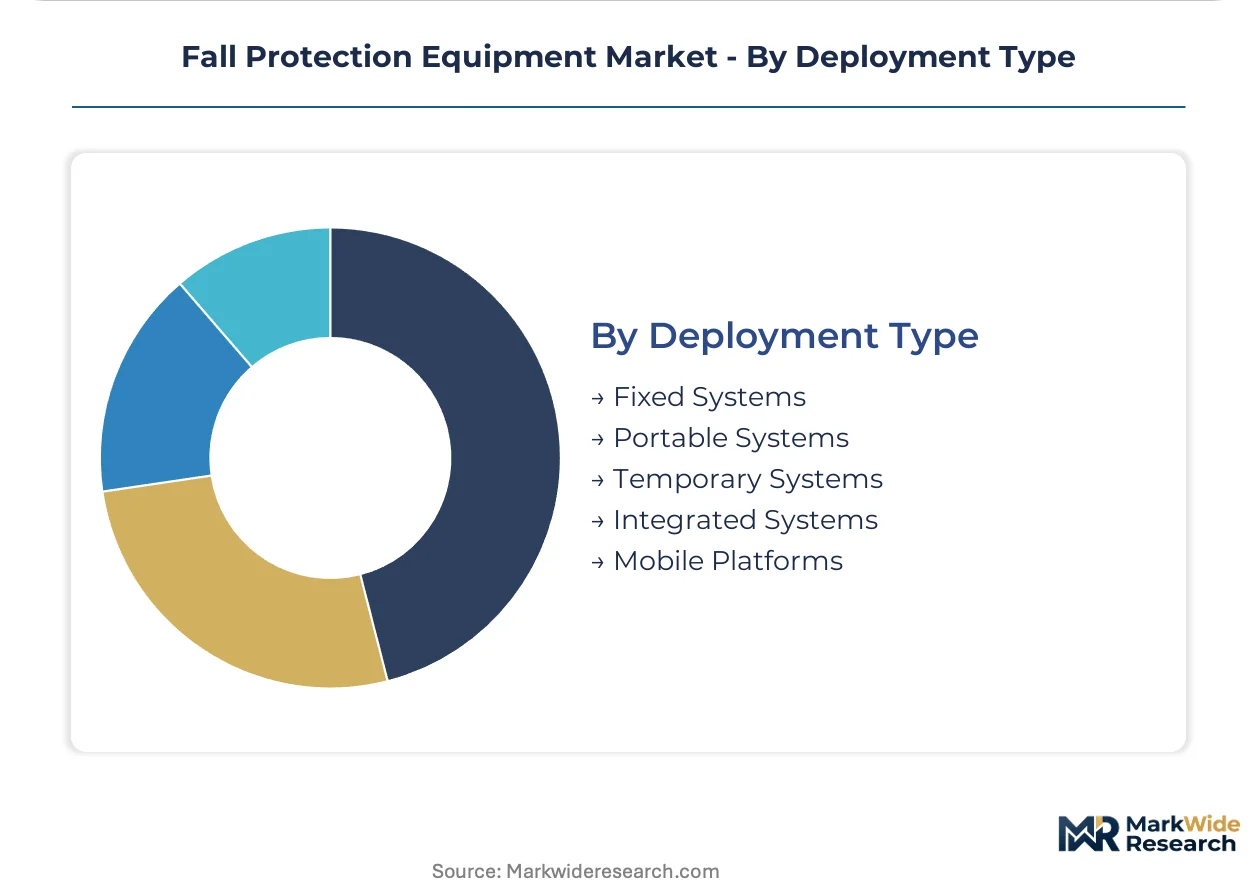
Fixed systems retain the largest installed base, with integrated systems gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany enforces stricter PPE conformity assessments than the United States, while China operates the world's largest polyester webbing supply base for harness manufacturing. These divergent regulatory and production environments create distinct procurement patterns across major demand centers.
United States
Construction spending and energy sector maintenance cycles drive harness procurement across Texas and the Gulf Coast. OSHA enforces 29 CFR 1926.501 mandating full-body harnesses over body belts, accelerating equipment replacement cycles. Houston anchors offshore oil platform demand where 100% tie-off protocols dominate contractor specifications.
Germany
Wind turbine tower heights exceeding 150 meters require specialized self-retracting lifelines for onshore and offshore maintenance crews. The EU PPE Regulation 2016/425 imposes Module B+C2 or D conformity assessment for Category III fall arrest equipment. Northern port cities concentrate equipment distribution networks serving North Sea offshore installations.
China
Infrastructure investment and energy sector expansion generate volume demand for standard-duty harnesses. GB 24542 and GB 24543 national standards govern fall arrest and restraint systems through the Standardization Administration. Yangtze River Delta textile manufacturers scale high-tenacity polyester fiber production for domestic and export harness assemblers.
India
State-level building code enforcement creates first-time harness demand among informal construction contractors. The Bureau of Indian Standards mandates product certification for safety equipment in commercial building projects. Maharashtra and Gujarat industrial corridors concentrate contractor procurement through emerging safety distribution networks.
United Kingdom
Telecommunications infrastructure for 5G small-cell deployment drives portable anchor system demand in urban maintenance settings. HSE guidelines align with EN 360 and EN 795 specifications for self-retracting devices and anchor devices. London and Southeast England concentrate tower climbing contractor activity with specialized rescue planning requirements.
Fall Protection Equipment Market Key Industry Players
United States producers anchor one tier; European specialists hold certification-intensive positions for wind energy applications. The vendor structure splits between diversified industrial safety conglomerates and focused harness manufacturers. Three archetypes dominate: vertically integrated ladder-to-harness system providers, channel-controlled safety distributors, and textile-to-hardware captive producers. Consolidation through distributor acquisition and backward integration into webbing supply represent the primary competitive vectors.
Among diversified industrial safety providers, 3M Company and Honeywell International Inc. occupy positions exemplifying channel control through safety distribution networks. WernerCo represents vertical integration across climbing systems extending into fall protection kits. SKYLOTEC GmbH anchors the specialist tier with German-engineered positioning for European wind energy compliance requirements.
| Leading Market Players |
|---|
| WernerCo |
| SKYLOTEC GmbH |
| 3M Company |
| Guardian Fall Protection |
| Petzl Group |
| Honeywell International Inc. |
| FallTech |
| Kee Safety Inc. |
| MSA Safety Incorporated |
| Others |
Cost & Logistics Intelligence
OSHA's 29 CFR 1926.501 mandate eliminating body belts in favor of full-body harnesses has compressed replacement cycles and forced distributors to clear legacy inventory, reshaping procurement patterns across North American construction and energy maintenance operations. This specification shift concentrates demand around ANSI Z359.11-certified harnesses and self-retracting devices, elevating pricing power for manufacturers with verified compliance documentation while pressuring uncertified suppliers to discount or exit.
Pricing Analysis
Distributor margins of 25-35 percent separate manufacturer cost from end-user price in the contractor channel, with direct-to-OEM arrangements commanding steeper discounts for volume commitments. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation, with CE-marked and ANSI Z359 dual-certified products commanding 15-20 percent premiums over single-standard alternatives. Cost compression in the economy tier is intensifying because Chinese textile manufacturers are scaling polyester webbing supply, yet price-insensitive wind energy contractors in Northern Europe prioritize rescue-integrated systems over unit cost.
Supply Chain Analysis
CE marking and ANSI Z359.12 connector qualification requirements gate market access, filtering out uncertified hardware suppliers and consolidating procurement around tested assemblers with documented conformity assessment. Polyester webbing production concentrates in China's Yangtze River Delta, aluminum alloy hardware feeds from domestic Chinese smelters and German specialty metalworks, and final assembly distributes across Vietnam and Mexico for tariff-advantaged access to North American markets. Single-source vulnerability in high-tenacity fiber supply creates exposure if Chinese environmental enforcement disrupts textile output. Distribution runs through safety equipment specialists like Grainger and W.W. Grainger rather than general industrial distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The fall protection equipment market functions as a stable compounder anchored by non-discretionary regulatory compliance mandates that perpetually refresh installed base demand regardless of construction cycle volatility.
For Market Incumbents: Extend certification coverage to capture multi-standard procurement specifications by investing in simultaneous ANSI Z359, EN 360, and GB 24542 testing protocols. Deepen backward integration into polyester webbing supply to defend margin position against raw material volatility. Channel control through safety distribution networks serving oil and gas contractors remains the priority defensive lever against emerging Asian assemblers. For New Entrants and Emerging Players: Begin with India's state-level building code enforcement creating first-time harness demand among informal construction contractors in Maharashtra and Gujarat. Target portable anchor systems for 5G telecommunications infrastructure where work location fluidity favors integrated rescue capability over fixed installations. A rental and leasing service model with captive inspection capabilities bypasses capital equipment purchase barriers in seasonal energy sector contracting. For Investors and Strategic Acquirers: Asymmetric upside sits with mid-cap specialists possessing captive textile-to-hardware integration and established CE marking pathways for European wind energy access. The five-to-ten-year viability window favors assemblers with demonstrated Module B+C2 conformity assessment completion over pure distributors. Watch for OSHA enforcement intensity in residential construction as the signal indicating replacement cycle acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Webbing Supply | Captive polyester fiber production insulates margin from Chinese textile price volatility. |
| Multi-Standard Certification Investment | Simultaneous ANSI Z359 and EN 360 compliance unlocks procurement specifications from multinational contractors. |
| Rescue Capability Integration | Convergence of fixed anchor networks with descent devices addresses warehousing verticals with shifting work locations. |
| Rental and Leasing Model Deployment | Inspection and recertification services generate recurring revenue from energy sector project contractors. |
| Distribution Network Acquisition | Channel control through safety specialists serving oil and gas platforms anchors defensive positioning. |
Research Approach
Direct dialogue with safety equipment distributors, wind turbine maintenance contractors, construction procurement managers, and OSHA compliance officers grounded qualitative assessment in operational reality. Secondary validation drew from OSHA enforcement data, EU PPE Regulation 2016/425 conformity assessment databases, Chinese GB standard filings, and customs records of polyester webbing and aluminum alloy hardware trade flows. Bottom-up and top-down triangulation reconciled equipment shipment volumes with end-use industry employment and regulatory mandate coverage rates.
Bottom-up modeling segmented demand across harnesses, self-retracting devices, lanyards, lifelines, and anchor points, further disaggregated by construction, wind energy, oil and gas, telecommunications, warehousing, and mining applications. Top-down verification cross-checked aggregate manufacturer revenue disclosures against derived market size estimates across the analysis window. CAGRs were derived from equipment replacement cycle analysis tied to OSHA 1926.501 post-arrest mandates and wind turbine installation growth trajectories. Key forecast inputs included infrastructure spending commitments in the United States and Germany, and textile production capacity expansion in China's Yangtze River Delta.
Several conditions sit outside the modeled scope, including potential harmonization between ANSI Z359 and EN standards that could collapse multi-certification premiums, and breakthrough advances in drone-based turbine maintenance that could reduce technician climb frequency. Forecasts reflect assumptions about continued regulatory enforcement intensity and no relaxation of body belt prohibitions. A model refresh is warranted upon material change in OSHA inspection staffing levels or EU PPE Regulation conformity assessment fee structures.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Safety Equipment and Personal Protective Equipment (PPE)
Africa Riot Control Equipment Market
Safety Equipment and Personal Protective Equipment (PPE)
Global Face Shield Market
Safety Equipment and Personal Protective Equipment (PPE)
Medical Respiratory Protective Equipment Market
Safety Equipment and Personal Protective Equipment (PPE)
N95 Grade Medical Protective Mask Market
Safety Equipment and Personal Protective Equipment (PPE)
Explosion Proof Devices Market
Safety Equipment and Personal Protective Equipment (PPE)
Booster Seat Type Child Safety Seats Market
Safety Equipment and Personal Protective Equipment (PPE)
PPE Detection Market
Safety Equipment and Personal Protective Equipment (PPE)
Personal Protective Equipment (PPE) Market
Safety Equipment and Personal Protective Equipment (PPE)
Active Hearing Protection Market
Safety Equipment and Personal Protective Equipment (PPE)
Disposable Protective Apparel Market
Safety Equipment and Personal Protective Equipment (PPE)
Protective Snowmobile Gear Market
Safety Equipment and Personal Protective Equipment (PPE)
Particulate Respirators Market
Safety Equipment and Personal Protective Equipment (PPE)
US Law Enforcement PPE Market
Safety Equipment and Personal Protective Equipment (PPE)
North America Respiratory Protective Equipment (RPE) Market
Safety Equipment and Personal Protective Equipment (PPE)
Anti-Fatigue Mats Market
Safety Equipment and Personal Protective Equipment (PPE)
Driving Protection Gear Market