
 Particulate Respirators Market | 2026-2036
Particulate Respirators Market Size, Share, and Industry Trends Forecast 2026-2036
Particulate Respirators Market Outlook
Healthcare procurement is hardening across North American and European hospital networks as institutions normalize pandemic-era inventory buffers into permanent supply-chain policy. 3M leverages its dual presence in filtration media and finished respirator assembly to control upstream material flows. Honeywell International sustains defense and industrial contracts that anchor long-term offtake volumes. Drägerwerk AG & Co. KGaA specializes in full-face systems for chemical handling applications where regulatory complexity creates premium positioning.
Particulate respirators are tight-fitting respiratory protective devices that filter airborne particles through electrostatically charged polypropylene microfiber media, with N95-rated units capturing at least 95% of 0.3-micron test aerosols under NIOSH 42 CFR 84 protocols. These devices serve primarily to prevent occupational lung disease and infectious aerosol transmission in workplaces where engineering controls prove insufficient. N95 disposables dominate volume across healthcare and light industrial channels, while P100 configurations with integrated organic vapor cartridges command margin pools in asbestos abatement and chemical remediation. Full-face elastomeric designs are displacing half-face units in oil and gas applications as employers prioritize eye protection integration and reduced per-use costs through cartridge reuse.
NIOSH certification requirements under 42 CFR 84 govern filtration efficiency and exhalation valve performance for respirators sold in the United States, while the EU MDR and CE marking framework enforce biocompatibility and clinical validation standards for medical-grade devices distributed in Europe. OSHA's Respiratory Protection Standard (29 CFR 1910.134) mandates annual fit testing, medical evaluation, and documented training cycles that sustain replacement demand and disqualify non-compliant suppliers from institutional procurement. Stakeholders must monitor how FDA emergency use authorization precedents reshape permanent regulatory pathways for novel filtration substrates and connected fit-monitoring technologies.
Market Dynamics
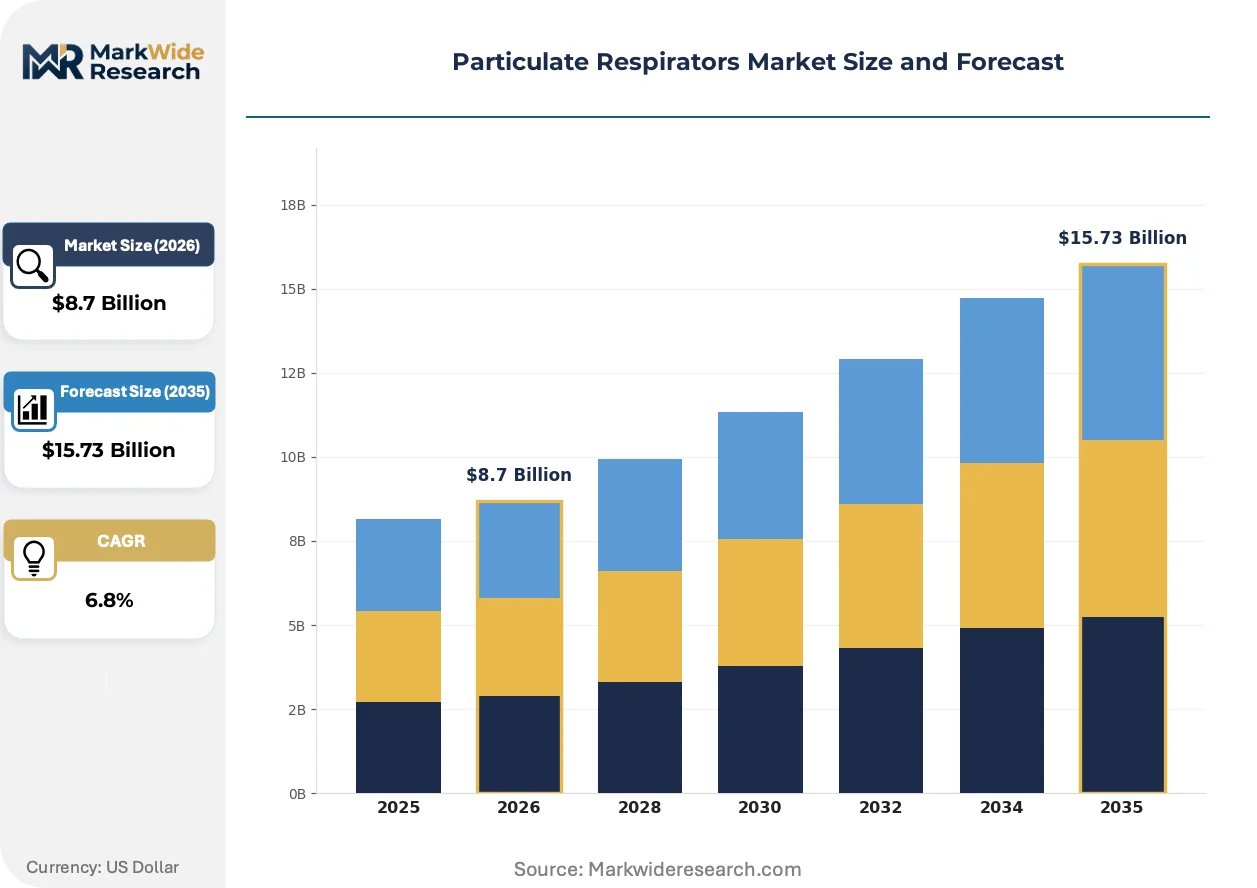
Hospital systems are hardening pandemic-era stockpiles into permanent supply-chain policy, while OSHA's tightened fit-testing mandates compress replacement cycles and disqualify non-compliant suppliers from institutional procurement.
Growth Catalysts
- OSHA Respiratory Protection Standard (29 CFR 1910.134):Annual fit-testing mandates and documented training cycles sustain replacement demand across US healthcare and industrial employers.
- Polypropylene microfiber media:Electrostatic charging advances improve filtration efficiency without breathing resistance penalties, expanding adoption into extended-wear healthcare settings.
- China:Domestic manufacturing scale and government stockpiling programs expand coverage to industrial and medical channels, concentrating volume growth.
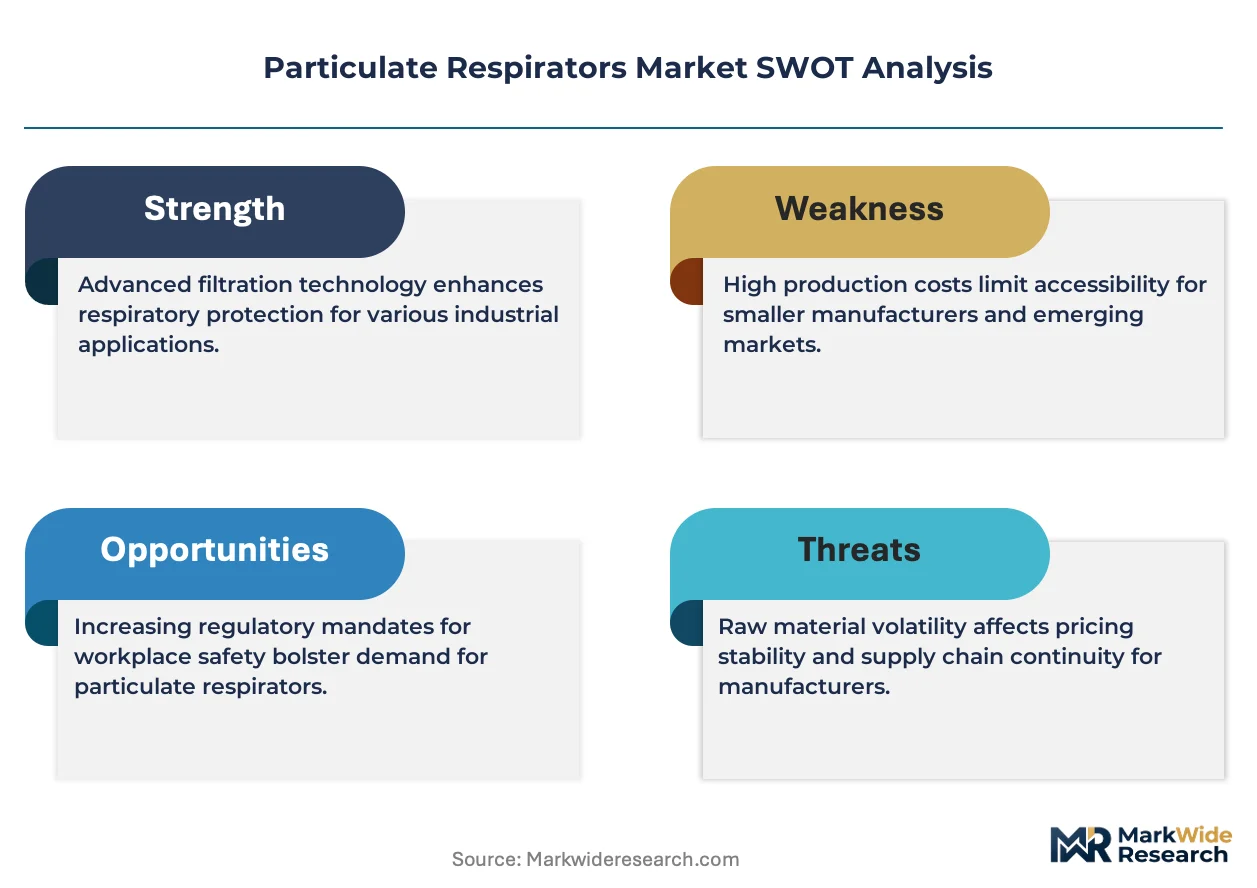
Market Restraints
- Meltblown polypropylene supply:Feedstock concentration among petrochemical complexes creates input cost volatility and margin compression for finished respirator assemblers.
- NIOSH certification timelines:Extended validation protocols under 42 CFR 84 delay market entry for novel filtration substrates and connected monitoring technologies.
- Elastomeric half-face units:Lower per-use costs through cartridge reuse threaten disposable N95 volume in industrial maintenance and manufacturing channels.
Strategic Opportunities
- Connected fit-monitoring:Real-time seal verification sensors converge with Bluetooth-enabled respiratory protection, opening premium positioning in high-exposure healthcare and chemical handling.
- India:Underpenetrated industrial hygiene enforcement and expanding pharmaceutical manufacturing create white space for certified respirator penetration.
- EU MDR medical-grade pathway:Biocompatibility and clinical validation standards for CE-marked devices enable margin capture in European surgical and infection-control applications.
Industry Challenges
- Respiratory protection program administration:Medical evaluation coordination and fit-test documentation burden strain occupational health departments in mid-sized manufacturing facilities.
- Legacy inventory integration:Pandemic-era stockpiles with approaching expiration dates complicate rotation protocols and working capital management for hospital supply chains.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Particulate Respirators Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: N95, P100, Half-Face, Full-Face End User: Healthcare, Construction, Manufacturing, Oil & Gas Application: Dust Protection, Chemical Handling, Infectious Disease Control, Asbestos Removal Distribution Channel: Online Retail, Wholesale, Specialty Stores, Direct Sales |
| Companies Covered | 3M, Honeywell International, Moldex-Metric, Inc., Drägerwerk AG & Co. KGaA, Crosstex International, Inc., Mine Safety Appliances (MSA) Company, Halyard Health, Inc., Uvex Group, Bullard, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Particulate Respirators Market Strategic Shifts
Electrostatic filtration media, regulatory digitization, and procurement centralization are actively compressing product lifecycles and reshaping competitive positioning in respiratory protection.
Elastomeric respirator platforms with swappable cartridge interfaces are modularizing across oil and gas and chemical manufacturing sectors. Employers in these industries prioritize eye protection integration and reduced per-use costs through component reuse. This architecture is modularizing supplier relationships, as end-users mix cartridge chemistries from specialized vendors with facepiece hardware from industrial safety distributors.
EU MDR biocompatibility requirements and ISO 18562 testing protocols for breathing gas pathways are tightening material qualification standards for medical-grade devices distributed in Europe. Manufacturers must document cytotoxicity, sensitization, and irritation profiles for all polypropylene and silicone components. Full-face systems for surgical and high-acuity care are most affected, with suppliers extending development timelines to secure notified body approval.
Hospital network procurement consolidation is compressing vendor panels and unbundling after-sales respiratory program services. Group purchasing organizations now mandate documented fit-test compliance dashboards as a condition of contract renewal. This concentration is most visible in the United States, where multi-hospital systems centralize respiratory protection standardization to reduce administrative overhead and liability exposure.
Particulate Respirators Market Segmentation
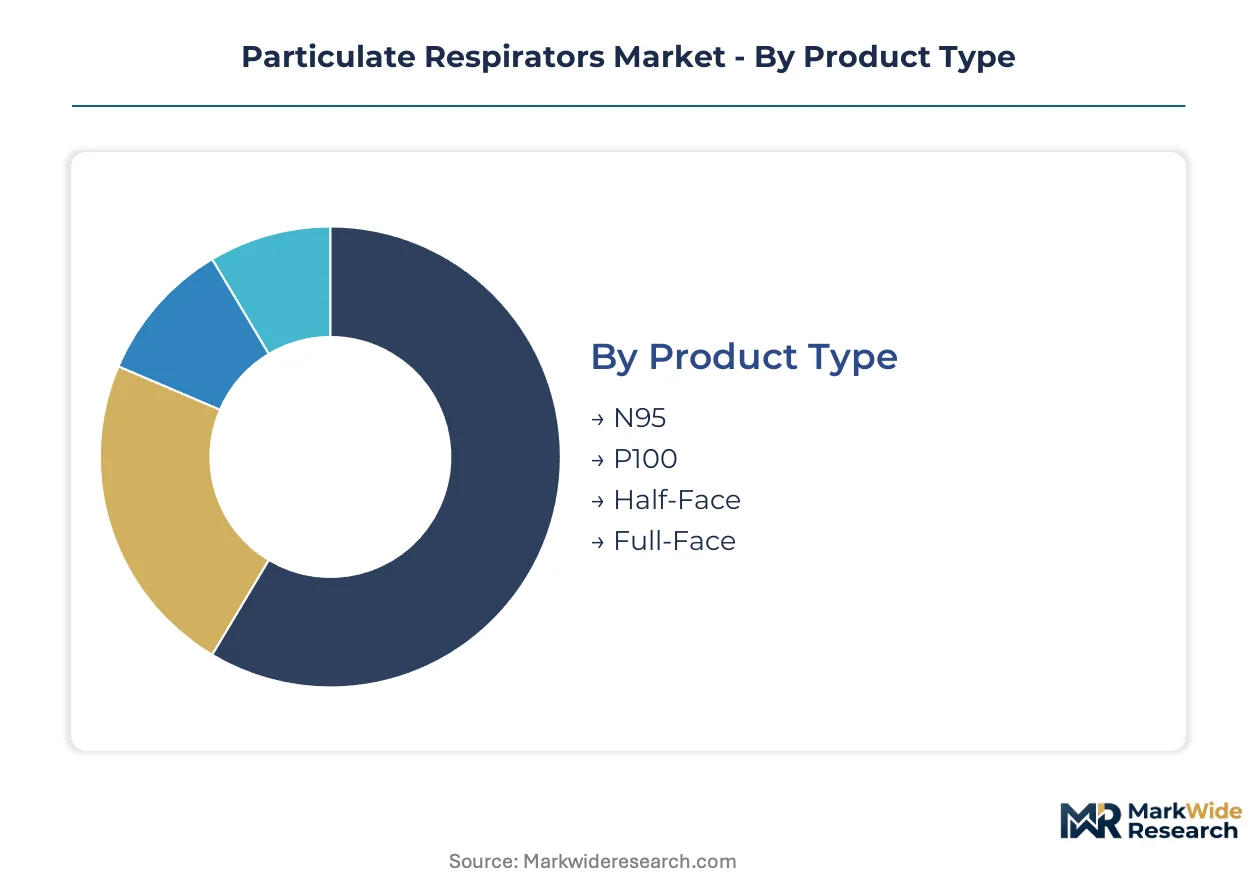
Respiratory protection procurement splits across technical specification, exposure environment, and supply chain configuration. Each segmentation axis carries distinct margin profiles and regulatory compliance burdens that reshape vendor positioning.
Product Type:
Filtration efficiency ratings and facepiece architecture determine unit economics and replacement cadence.
- N95:Electrostatically charged polypropylene microfiber media captures 95% of 0.3-micron particles per NIOSH 42 CFR 84 protocols. Hospital systems in the United States normalize pandemic-era stockpiles into permanent inventory policy, sustaining volume through fit-testing mandates.
- P100:99.97% filtration efficiency with integrated organic vapor cartridges commands premium positioning in asbestos abatement and chemical remediation where OSHA respiratory protection standards enforce cartridge-based systems.
- Half-Face:Elastomeric designs with swappable cartridges reduce per-use costs in manufacturing maintenance cycles.
- Full-Face:Integrated eye protection displaces half-face units in oil and gas applications prioritizing seal verification and component reuse.
Mature deployment sits with N95 disposables across healthcare and light industrial channels. Newer deployment is concentrated in full-face elastomeric systems gaining share fastest in high-exposure chemical handling.
End User:
Occupational exposure profiles and regulatory enforcement intensity vary sharply across employer categories.
- Healthcare:Annual fit-testing mandates under OSHA 29 CFR 1910.134 sustain replacement demand. Group purchasing organizations now require documented compliance dashboards as contract conditions.
- Construction:Dust protection applications in silica-generating activities face heightened enforcement, though program administration burdens strain mid-sized contractors.
- Manufacturing:Elastomeric cartridge reuse threatens disposable volume in maintenance departments prioritizing per-use cost reduction.
- Oil & Gas:Full-face systems with modular cartridge interfaces dominate where employers prioritize eye protection integration and reduced liability exposure.
Procurement concentration is most advanced in healthcare. Regulatory enforcement gaps persist in construction.
Application:
Exposure type dictates filtration substrate selection and certification pathway complexity.
- Dust Protection:Silica and general particulate applications in construction and manufacturing drive volume through N95 and P100 disposables.
- Chemical Handling:Organic vapor and acid gas exposures require cartridge-integrated systems with specialized sorbent media, extending development timelines for EU MDR biocompatibility compliance.
- Infectious Disease Control:Healthcare settings demand medical-grade devices with documented breathing gas pathway testing under ISO 18562 protocols.
- Asbestos Removal:Regulatory complexity creates premium positioning for P100 configurations with tight-fitting elastomeric seals and negative-pressure verification.
Standardized deployment dominates dust protection. Connected fit-monitoring sensors are penetrating infectious disease control fastest.
Distribution Channel:
Supply chain configuration determines service attachment and compliance documentation capabilities.
- Online Retail:Volume concentration in individual and small-employer procurement with limited fit-testing service attachment.
- Wholesale:Industrial safety distributors anchor long-term offtake through respiratory protection program administration and cartridge chemistry mixing.
- Specialty Stores:Regional presence in construction and manufacturing clusters with hands-on fit-testing capabilities.
- Direct Sales:Hospital network procurement consolidation compresses vendor panels and unbundles after-sales services to dedicated compliance platforms.
Wholesale channels retain industrial anchor accounts. Direct sales is climbing fastest in healthcare system centralization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Free trade zones in Southeast Asia and China's coastal special economic zones concentrate filter media finishing capacity. Industrial safety procurement centralizes near petrochemical clusters and pharmaceutical manufacturing corridors. Regulatory divergence between NIOSH, CE marking, and GB standards fragments certification pathways.
United States
Hospital network consolidation drives procurement centralization through group purchasing organizations. OSHA's 29 CFR 1910.134 mandates annual fit-testing and medical evaluation documentation that sustain replacement cycles. Houston's petrochemical corridor anchors industrial demand for elastomeric systems with organic vapor protection.
China
Government stockpiling programs expand from medical to industrial channels as domestic meltblown capacity scales. GB 2626-2019 standards govern KN95 certification while SAMR tightens quality enforcement. Yangtze River Delta manufacturers dominate export assembly for European and Southeast Asian markets.
Germany
Chemical manufacturing clusters in North Rhine-Westphalia sustain demand for full-face elastomeric systems with modular cartridge interfaces. EU MDR biocompatibility requirements and ISO 18562 breathing gas pathway testing extend development timelines for medical-grade devices. BASF's Ludwigshafen complex anchors regional procurement for integrated respiratory protection programs.
India
Pharmaceutical manufacturing expansion in Maharashtra and Gujarat creates white space for certified respirator penetration. BIS certification requirements and DGFT import regulations shape competitive entry. Hyderabad's vaccine production corridor drives medical-grade N95 procurement as CDSCO tightens device registration.
Japan
Precision manufacturing in Aichi Prefecture and automotive assembly in Kanagawa sustain industrial hygiene enforcement. METI industrial safety guidelines and JIS T 8151 standards govern disposable and reusable respirator specifications. Osaka's chemical handling sector prioritizes connected fit-monitoring integration for high-exposure applications.
Particulate Respirators Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with filtration media suppliers capturing upstream margin and finished device assemblers competing on certification speed and program administration. The vendor base organizes into three tiers: integrated material-to-device conglomerates, respiratory protection specialists with regulatory depth, and regional fabricators serving price-sensitive industrial channels. M&A activity concentrates on cartridge chemistry capabilities and connected monitoring technologies. Capacity expansion targets meltblown polypropylene backward integration to secure input cost stability.
Among diversified industrial conglomerates, 3M and Honeywell International occupy positions spanning filtration media through finished respirator assembly. Drägerwerk AG & Co. KGaA exemplifies the specialist archetype with concentration in full-face systems for chemical handling applications. These three anchors represent distinct competitive vectors: upstream material control, defense and industrial contract anchoring, and premium regulatory-complexity positioning respectively.
| Leading Market Players |
|---|
| 3M |
| Honeywell International |
| Moldex-Metric, Inc. |
| Drägerwerk AG & Co. KGaA |
| Crosstex International, Inc. |
| Mine Safety Appliances (MSA) Company |
| Halyard Health, Inc. |
| Uvex Group |
| Bullard |
| Others |
Value Chain & Pricing Dynamics
Family-owned mid-cap specialists in Yangtze River Delta filtration media production anchor supply discipline through captive meltblown capacity, translating input cost stability into pricing power against contract assemblers dependent on spot polypropylene markets. This ownership pattern concentrates margin capture upstream while finished device manufacturers absorb volatility through inventory buffers or pass-through clauses in hospital procurement contracts.
Pricing Analysis
Short lead-time premiums command pricing separation from standard-cycle contract volumes, with hospital systems paying elevated unit costs for emergency replenishment outside group purchasing organization terms. Pricing stratifies across NIOSH-certified premium tiers, EU MDR medical-grade validation levels, and unbranded industrial economy segments, with certification grade and volume scale as primary differentiation drivers. Cost compression in economy-tier disposables is intensifying because Chinese domestic capacity expansion outpaces branded stockpile demand. Mid-sized manufacturing facilities exhibit highest price sensitivity due to unbundled respiratory program administration costs, while integrated oil and gas operators prioritize total cost of ownership over per-unit pricing.
Supply Chain Analysis
Dual-sourcing qualification mandates from US hospital networks and European pharmaceutical manufacturers require validated secondary suppliers for meltblown media and elastomeric facepiece components, extending procurement timelines but reducing single-source vulnerability. Geographic concentration centers on China for polypropylene microfiber finishing, Germany for precision elastomer molding, and the United States for NIOSH-certified assembly. Raw material dependencies rest on petrochemical-grade polypropylene resin, electrostatic charging additives, and silicone facepiece compounds. Tariff exposure on Chinese-origin filtration media creates structural risk for US-based finished device assemblers. Distribution runs through industrial safety distributors with respiratory program administration capabilities, hospital network direct procurement portals, and construction channel specialty retailers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The particulate respirators market sits in a technology-transition phase as connected fit-monitoring sensors displace passive seal verification across high-exposure healthcare and chemical handling applications.
For Market Incumbents: Cement upstream filtration media control through backward integration into meltblown polypropylene production or long-term offtake agreements with Yangtze River Delta suppliers, defending against margin erosion from Chinese domestic manufacturers expanding into export markets. Accelerate NIOSH certification investment for Bluetooth-enabled respiratory protection platforms to capture replacement demand from OSHA's digitized fit-testing mandate enforcement. For New Entrants and Emerging Players: Capture white space in India's pharmaceutical manufacturing corridor and construction dust protection segments where BIS certification requirements and fragmented contractor procurement create entry pathways for certified respirator specialists. Target modular cartridge chemistry partnerships with established elastomeric facepiece distributors as the most penetrable go-to-market angle, avoiding direct competition with integrated conglomerates in hospital network procurement. For Investors and Strategic Acquirers: Distressed-cycle entries favor cartridge chemistry specialists with EU MDR notified body relationships in Germany and connected sensor technology developers in Japan's precision manufacturing clusters, positioned for long-term viability as regulatory digitization and biocompatibility standards reshape competitive moats. Watch NIOSH validation timeline compression for novel filtration substrates as the inflection indicator signaling technology transition maturation.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Meltblown Media | Captive polypropylene supply secures margin stability against petrochemical volatility in Yangtze River Delta. |
| Connected Sensor Platform Development | Bluetooth-enabled seal verification meets OSHA digitization mandates in Houston petrochemical corridor. |
| EU MDR Notified Body Certification | Biocompatibility documentation opens premium positioning in German chemical manufacturing clusters. |
| India BIS Certification Investment | Regulatory compliance unlocks pharmaceutical manufacturing demand in Maharashtra and Gujarat corridors. |
| Hospital GPO Compliance Dashboard Integration | Documented fit-test data streams satisfy group purchasing organization contract renewal conditions. |
Study Parameters
Multi-period observation of NIOSH certification pipeline volumes, OSHA enforcement action frequencies, and hospital procurement contract durations anchored the trend analysis, supplemented by interviews with respiratory protection program administrators, industrial safety distributors, elastomeric facepiece engineers, and group purchasing organization contract managers. Secondary validation drew from FDA 510(k) filings, EU MDR notified body decision databases, SAMR quality enforcement disclosures, customs trade data for filtration media imports, and SEC 10-K respiratory segment disclosures. Bottom-up demand modeling across end-user segments triangulated against top-down macroeconomic indicators and regulatory timeline projections.
Input-output matrices mapped polypropylene resin costs through meltblown media production to finished respirator assembly, with volume and value outputs derived across product type, end-user industry, application exposure profile, and distribution channel configuration over the projection horizon. Segmentation dimensions modeled included filtration efficiency rating, facepiece architecture, occupational exposure category, and regional regulatory cluster. CAGRs were synthesized from replacement cycle frequencies under OSHA 29 CFR 1910.134, hospital stockpile normalization trajectories, and industrial hygiene enforcement intensity indices. Industry-specific forecast inputs incorporated elastomeric cartridge reuse rates and connected fit-monitoring sensor adoption curves.
The model holds under stable OSHA enforcement intensity and continued hospital network procurement consolidation; deviation in NIOSH certification timeline delays or Chinese export restriction policies would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Safety Equipment and Personal Protective Equipment (PPE)
Pest Control Devices Market
Safety Equipment and Personal Protective Equipment (PPE)
Africa Riot Control Equipment Market
Safety Equipment and Personal Protective Equipment (PPE)
Anti-Shock Trouser Market
Safety Equipment and Personal Protective Equipment (PPE)
Global Surgical Mask and Respirators Market
Safety Equipment and Personal Protective Equipment (PPE)
Global Safety and Eyewash Shower Market
Safety Equipment and Personal Protective Equipment (PPE)
Middle East and Africa Process Safety Services Market
Safety Equipment and Personal Protective Equipment (PPE)
North America Respiratory Protective Equipment (RPE) Market
Safety Equipment and Personal Protective Equipment (PPE)
Global above the Waist PPE Market
Safety Equipment and Personal Protective Equipment (PPE)
APAC Safety Instrumented Systems Market
Safety Equipment and Personal Protective Equipment (PPE)
Diving and Survival Equipment Market
Safety Equipment and Personal Protective Equipment (PPE)
Booster Seat Type Child Safety Seats Market
Safety Equipment and Personal Protective Equipment (PPE)
Electronic Siren Systems Market
Safety Equipment and Personal Protective Equipment (PPE)
Global Respirator Filter Market
Safety Equipment and Personal Protective Equipment (PPE)
Steel Smart Locker Market
Safety Equipment and Personal Protective Equipment (PPE)
Safety IO Modules Market
Safety Equipment and Personal Protective Equipment (PPE)
Non Ionizing Radiation/EMF Detection, Measurement, and Safety Market