
 Alarm Management System Market | 2026-2036
Alarm Management System Market Size, Share, and Industry Trends Forecast 2026-2036
Alarm Management System Market Outlook
Direct sales through system integrators is fragmenting as cloud deployment options and API-based procurement open alternative paths to end users. Johnson Controls leverages its building automation footprint to bundle alarm management into broader facility contracts. Siemens competes through deep specialization in process industries, anchoring its position with IEC-compliant engineering services. Honeywell differentiates by extending its distributed control system architecture into native alarm analytics.
An alarm management system comprises hardware sensors, software platforms, and integration services designed to prioritize, suppress, and document industrial alerts based on severity and operator response requirements. These systems employ configurable alarm suppression algorithms and state-based rationalization to prevent flood conditions that desensitize control room personnel. Software and services segments capture expanding margin pools as utilities and healthcare facilities shift from on-premise installations toward subscription-based cloud platforms. Hardware retains dominance in oil and gas and manufacturing plants where hardwired safety instrumented systems remain mandatory under process safety regulations.
FDA 21 CFR Part 820 quality system requirements shape alarm management design in medical device manufacturing, while OSHA process safety management standards enforce alarm documentation in chemical facilities. ISA-18.2 and IEC 62682 provide the technical frameworks that determine product certification eligibility across North American and European procurement cycles. Stakeholders must monitor how API-based integration standards evolve to determine whether standalone alarm platforms or embedded modules within broader control architectures will command preferred vendor status.
Market Dynamics
Cloud-native alarm management platforms are compressing deployment cycles from months to weeks, forcing legacy on-premise vendors to rearchitect their delivery models or lose procurement cycles to API-first competitors.
Growth Catalysts
- IEC 62682 compliance deadlines:European process facilities face mandatory alarm rationalization audits, driving replacement of legacy suppression systems with certified platforms.
- Operator fatigue reduction mandates:OSHA process safety management standards in the United States now explicitly reference alarm flooding as a documented hazard, compelling chemical plants to upgrade.
- Digital twin integration:Oil and gas operators are embedding alarm analytics into virtual facility replicas to pre-emptively model failure scenarios before physical deployment.
Market Restraints
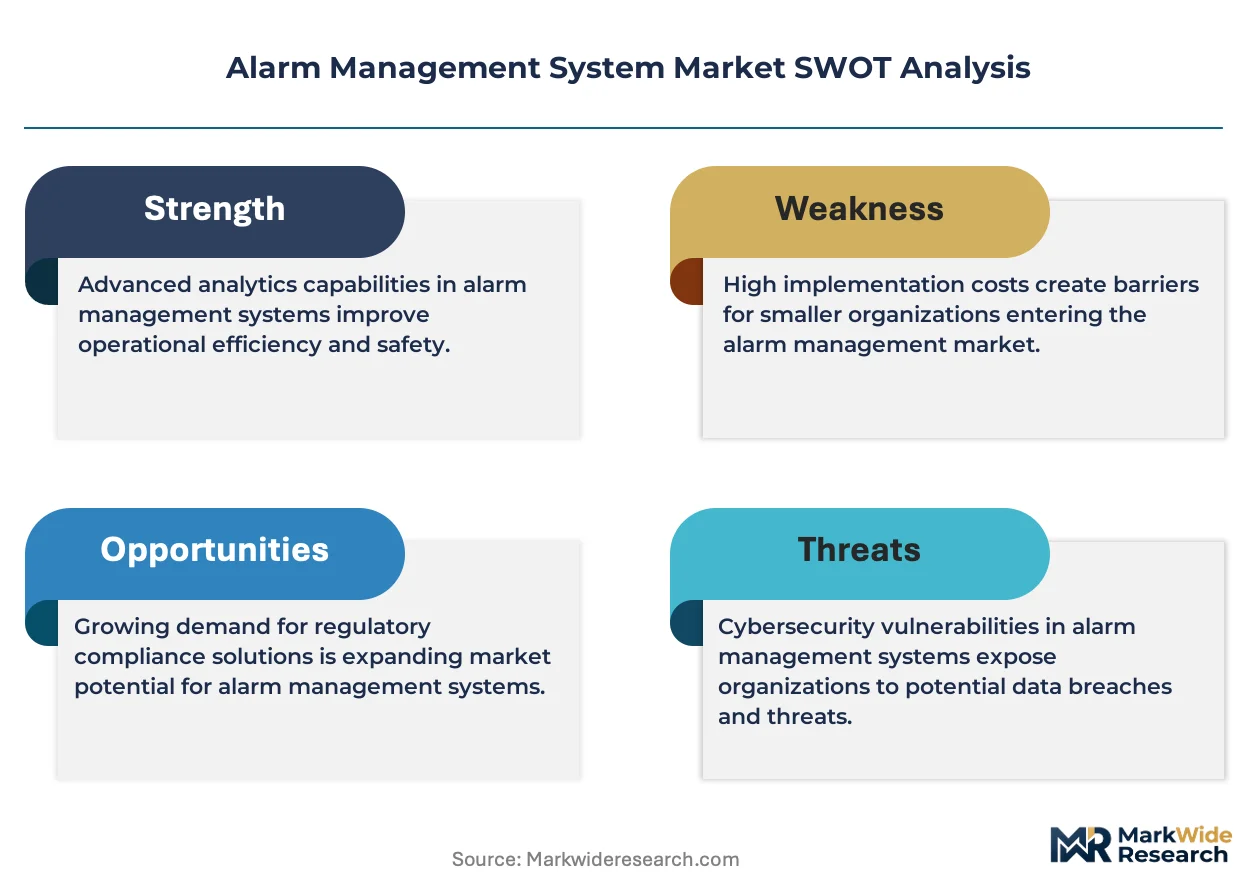
- Semiconductor supply concentration:Safety instrumented system hardware depends on specialized industrial microcontrollers sourced primarily from East Asian foundries, creating 18-24 month lead time volatility.
- ISA-18.2 certification friction:The multi-stage third-party validation process adds 8-14 months to product release timelines, delaying revenue recognition for platform developers.
- Substitute alert channels:Mobile push notification systems and wearable haptic devices are capturing low-severity alert traffic that previously flowed to centralized alarm consoles.
Strategic Opportunities
- Healthcare facility underpenetration:Hospital operating rooms and pharmaceutical cleanrooms in Germany remain largely unserved by IEC-compliant alarm rationalization tools.
- API marketplace distribution:Industrial software exchanges are enabling direct procurement of alarm management modules without system integrator intermediaries.
- EU AI Act alignment:Automated alarm prioritization algorithms classified as high-risk AI systems create certified-provider advantages for vendors with documented explainability frameworks.
Industry Challenges
- Control systems engineering talent scarcity:Proficiency in both ISA-18.2 rationalization methodology and modern cloud architecture is concentrated among a narrow cohort of specialists.
- Legacy DCS integration complexity:Proprietary communication protocols from 1990s-era distributed control systems require custom gateway development for each installation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Alarm Management System Market |
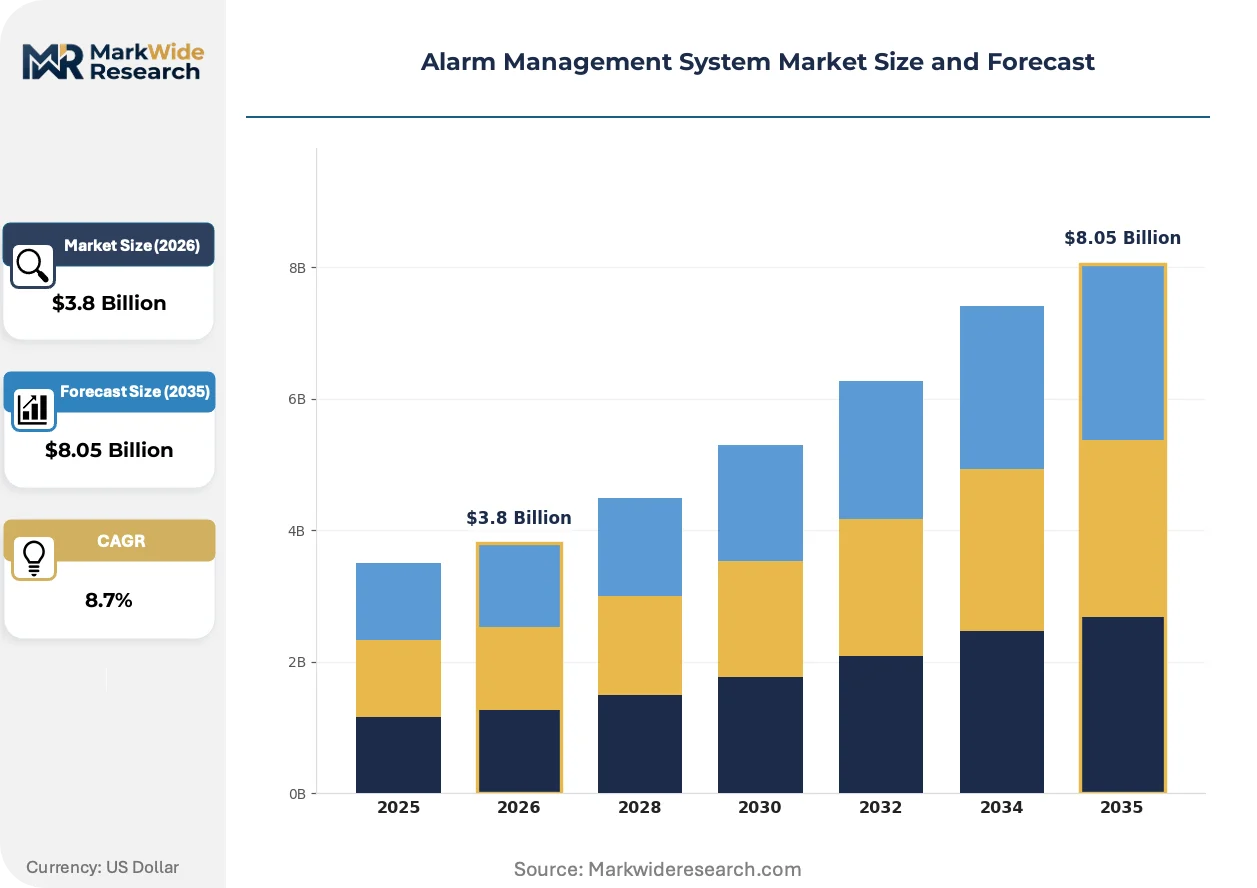
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hardware, Software, Services, Integration End User: Healthcare Facilities, Oil & Gas Industry, Manufacturing Plants, Utilities Deployment: On-Premise, Cloud-Based, Hybrid, Mobile Integration Level: Standalone, System Integrated, API-Based, Custom Solutions |
| Companies Covered | Carrier Edwards, SimpliSafe, Johnson Controls, Vivint, ADT, Honeywell, Bosch, Frontpoint, Siemens, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Alarm Management System Market Strategic Shifts
Software-defined alarm processing is displacing hardware-centric architectures, compressing capital requirements while expanding configurability for multi-site operators managing heterogeneous control environments.
Edge computing nodes with embedded alarm analytics are virtualizing the traditional control room workstation, enabling distributed decision-making at refinery process units and offshore platforms. Midstream oil and gas operators are deploying these devices at wellpad clusters to suppress nuisance alarms before transmission to central SCADA systems. This architecture is virtualizing the physical boundary between field operations and control center oversight.
REACH chemical substance restrictions are accelerating substitution of legacy brominated flame retardants in alarm annunciator housings, forcing enclosure manufacturers to requalify materials for hazardous area certifications. The industrial consequence extends product development timelines by 6-9 months for ATEX-rated hardware. European chemical facilities are responding by extending service contracts on existing certified equipment rather than accepting unproven replacement materials.
Subscription-based alarm analytics procurement is consolidating purchasing authority within corporate digital transformation offices, bypassing traditional plant engineering departments that historically specified control systems. System integrators in the United States are losing specification influence as end users procure cloud alarm platforms through enterprise software marketplaces. This shift is most visible among Fortune 500 manufacturers with centralized IT governance and multi-plant standardization mandates.
Alarm Management System Market Segmentation
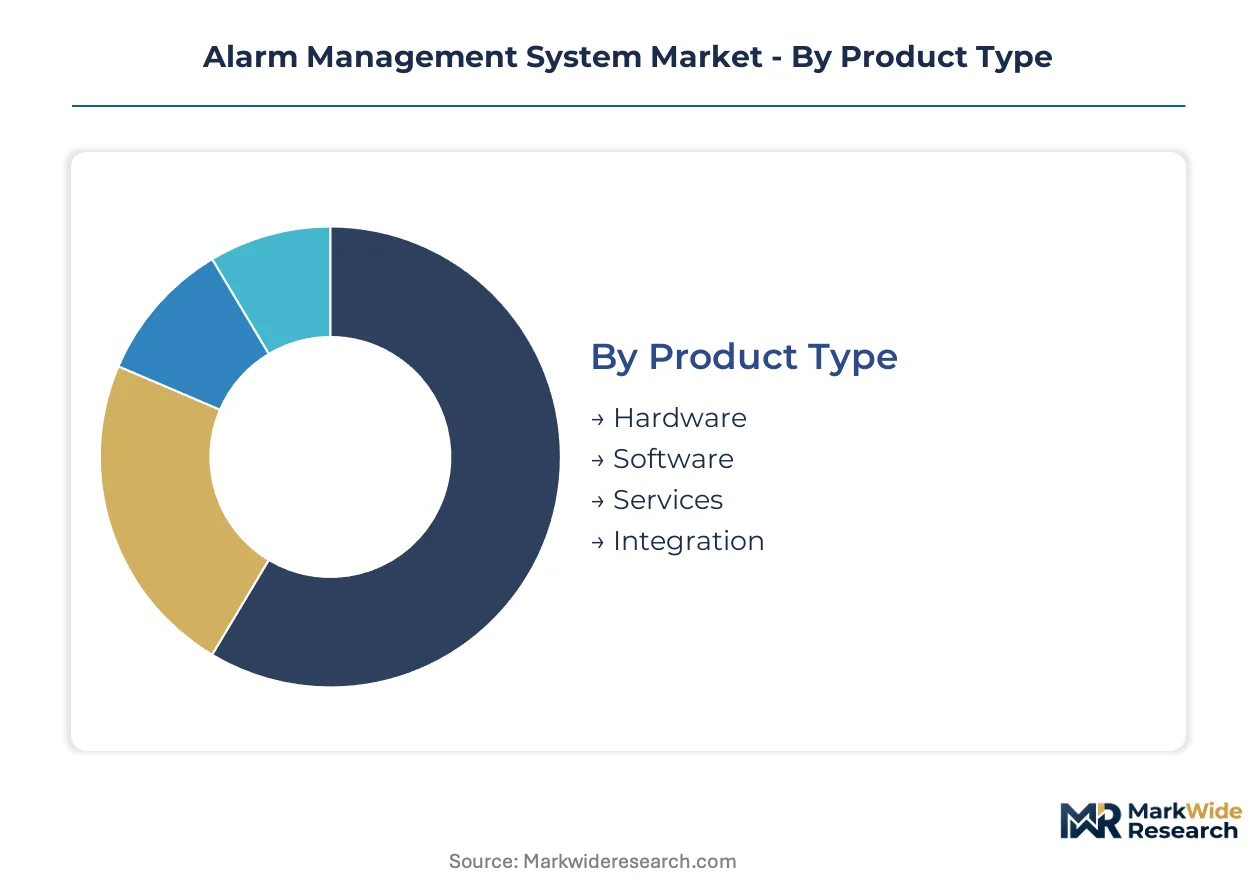
Alarm management system procurement patterns diverge sharply across deployment models and integration architectures. Segmentation reveals where capital budgets concentrate versus where subscription revenue pools are forming fastest.
Product Type:
Hardware sensors and annunciators turn over on 7-10 year replacement cycles tied to safety instrumented system recertification, while software platforms refresh annually through subscription renewals. Services revenue exhibits the most volatile cadence, spiking during compliance audit windows.
- Hardware:Encompasses alarm annunciators, industrial microcontrollers, and safety-rated enclosures engineered for hazardous area certifications. Oil and gas facilities in the United States drive replacement demand as OSHA process safety management audits force upgrades of legacy suppression systems. REACH chemical substance restrictions in Europe are extending hardware replacement timelines as manufacturers requalify flame-retardant materials.
- Software:Delivers configurable alarm rationalization algorithms, state-based suppression logic, and operator interface dashboards. Utilities in Germany are migrating toward cloud-native platforms that compress deployment cycles from months to weeks. FDA 21 CFR Part 820 requirements shape development roadmaps for medical device manufacturing applications.
- Services:Includes IEC 62682 compliance auditing, alarm flood analysis, and operator training programs. Demand concentrates during mandatory rationalization audit windows.
- Integration:Covers gateway development for legacy DCS protocol translation and multi-site standardization projects. Chemical facilities with 1990s-era distributed control systems require custom engineering for each installation.
Hardware anchors the volume base while software gains share at the steepest rate.
End User:
Capital intensity and regulatory enforcement intensity vary dramatically across end-use verticals, with process safety mandates in hydrocarbon processing contrasting against quality system requirements in medical manufacturing.
- Healthcare Facilities:Hospital operating rooms and pharmaceutical cleanrooms deploy alarm management for patient safety monitoring and environmental control alerts. German healthcare facilities remain largely unserved by IEC-compliant rationalization tools, creating whitespace for certified platform vendors.
- Oil & Gas Industry:Upstream, midstream, and downstream operators employ alarm analytics to reduce operator fatigue and pre-emptively model failure scenarios through digital twin integration. Edge computing nodes at wellpad clusters suppress nuisance alarms before SCADA transmission.
- Manufacturing Plants:Discrete and process manufacturers balance hardwired safety systems with configurable software platforms. FDA quality system requirements govern medical device manufacturing alarm design.
- Utilities:Power generation and water treatment operators are consolidating purchasing authority within corporate digital transformation offices, bypassing traditional plant engineering departments for cloud platform procurement.
Oil and gas anchors the volume base while healthcare facilities gain share at the steepest rate.
Deployment:
Procurement authority is migrating from plant engineering to enterprise IT functions as subscription models displace capital expenditure approval workflows.
- On-Premise:Traditional perpetual-license installations on facility-owned servers remain mandatory where hardwired safety instrumented systems predominate. Chemical plants under OSHA process safety management standards favor this architecture for audit documentation control.
- Cloud-Based:SaaS platforms deliver alarm analytics through browser interfaces with API-based integration to existing control systems. Fortune 500 manufacturers with centralized IT governance are procuring through enterprise software marketplaces.
- Hybrid:Combines on-premise safety-critical alarm processing with cloud-based analytics and reporting layers. Midstream operators use this architecture to balance regulatory documentation requirements with predictive maintenance capabilities.
- Mobile:Tablet and smartphone interfaces extend alarm acknowledgment and escalation to field personnel. Haptic wearable devices are capturing low-severity alert traffic that previously flowed to centralized consoles.
On-premise anchors the volume base while cloud-based deployment gains share at the steepest rate.
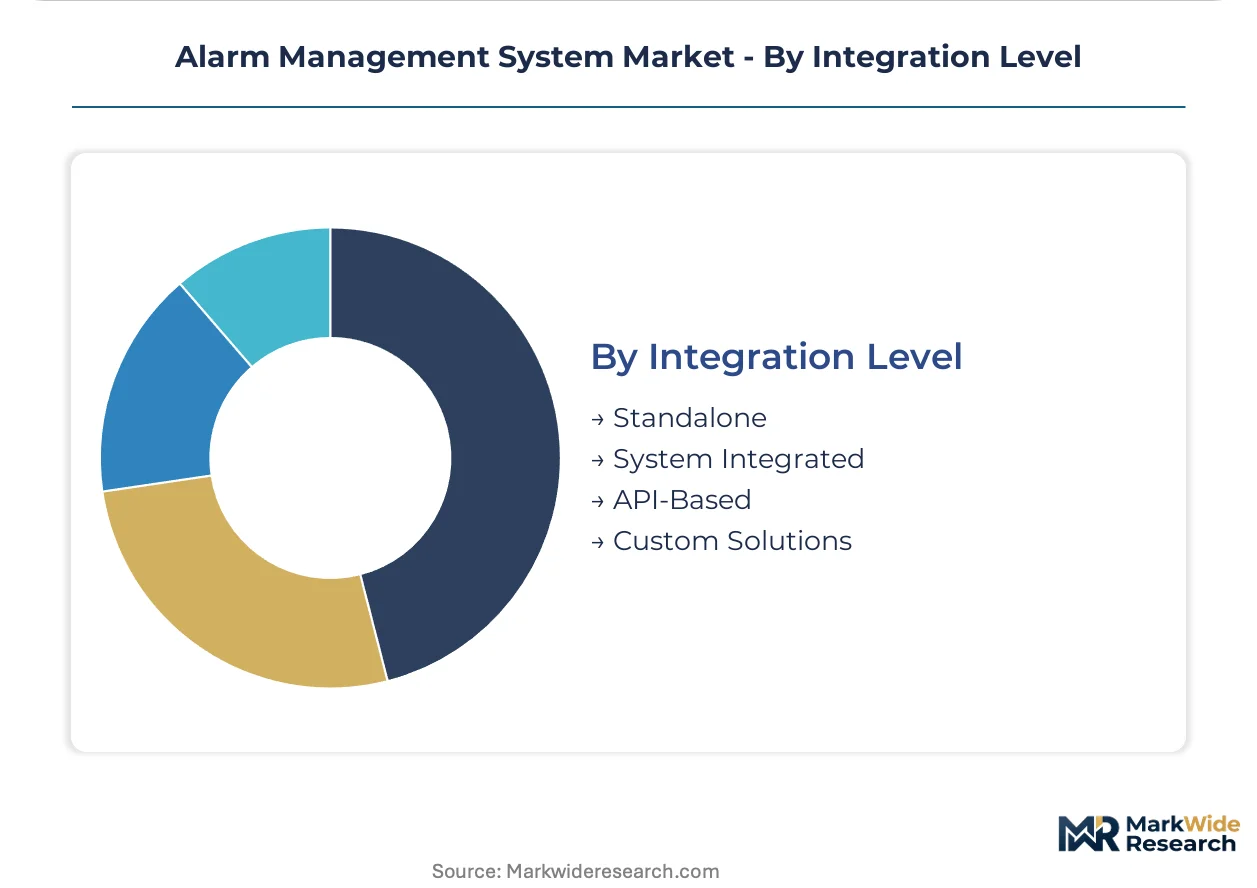
Integration Level:
Technical architecture choices determine whether alarm management functions as a standalone platform or embeds within broader control system ecosystems, with significant implications for vendor lock-in and switching costs.
- Standalone:Dedicated alarm management platforms operating independently of distributed control systems through OPC or proprietary gateways. Facilities with heterogeneous control environments favor this approach for multi-vendor flexibility.
- System Integrated:Native alarm analytics modules embedded within DCS or SCADA architectures from incumbent automation vendors. Siemens anchors this segment with IEC-compliant engineering services bundled into process industry contracts.
- API-Based:Microservice architectures enabling direct procurement of alarm management functions through industrial software exchanges. System integrators in the United States are losing specification influence as end users bypass intermediaries.
- Custom Solutions:Bespoke engineering for legacy protocol translation and specialized suppression logic. 1990s-era distributed control systems require custom gateway development for each installation.
System integrated solutions anchor the volume base while API-based integration gains share at the steepest rate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Gulf Coast petrochemical corridor underwrites United States demand for alarm management infrastructure, with refineries and LNG export terminals driving continuous control system investment. Pipeline interconnects to Canada and Mexico extend procurement influence across North American process safety networks.
United States
OSHA process safety management audits at Gulf Coast refineries are forcing replacement of legacy suppression systems. The EPA enforces risk management plan requirements that mandate documented alarm rationalization. Houston's Energy Corridor hosts engineering procurement offices for Chevron and ExxonMobil that specify IEC-compliant platforms for domestic and international deployment.
Germany
Chemical complexes along the Rhine-Ruhr industrial belt require state-based alarm rationalization to meet ECHA enforcement timelines. The EU AI Act classifies automated alarm prioritization as high-risk, demanding certified explainability frameworks. BASF's Ludwigshafen headquarters coordinates group-wide standardization on cloud-native platforms across European manufacturing assets.
China
State-owned oil majors Sinopec and PetroChina are digitizing control rooms at Yangtze River Delta refineries under MIIT smart manufacturing mandates. GB standards for process safety are converging toward IEC 62682 technical frameworks. The Ningbo-Zhoushan petrochemical zone is deploying edge computing nodes to suppress nuisance alarms at wellpad clusters before SCADA transmission.
Saudi Arabia
Aramco's Abqaiq processing facility and Jubail industrial city are expanding alarm analytics to reduce operator fatigue across downstream operations. SAMR technical regulations for safety instrumented systems are tightening compliance documentation requirements. The King Salman Energy Park in Eastern Province is attracting system integrators to serve regional oilfield service demand.
India
Reliance Industries' Jamnagar refinery complex is rationalizing alarm hierarchies under Petroleum and Natural Gas Regulatory Board safety audits. BIS adoption of IEC standards is accelerating certification requirements for imported control systems. The Gujarat State Petrochemicals cluster in Vadodara represents the densest concentration of process industry alarm management procurement in South Asia.
Alarm Management System Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream with sensors, annunciators, and safety-rated enclosures. The vendor base organizes into three functional layers: building automation conglomerates bundling alarm management into facility contracts, process industry specialists anchoring positions with IEC-compliant engineering services, and cloud-native entrants compressing deployment cycles through API-first architectures. Consolidation pressure is intensifying as subscription models bypass traditional system integrator intermediaries, while semiconductor supply constraints are forcing hardware vendors toward captive foundry arrangements.
Among diversified automation conglomerates, Johnson Controls leverages its building systems footprint to bundle alarm management into broader facility contracts, while Siemens anchors the process industry tier with deep specialization in IEC-compliant engineering services. Honeywell occupies a position extending distributed control system architectures into native alarm analytics. These three exemplify the dominant competitive archetypes: facility-scale bundlers, process-specialized engineering houses, and control-system-integrated analytics providers.
| Leading Market Players |
|---|
| Carrier Edwards |
| SimpliSafe |
| Johnson Controls |
| Vivint |
| ADT |
| Honeywell |
| Bosch |
| Frontpoint |
| Siemens |
| Others |
Value Chain & Pricing Dynamics
East Asian foundry concentration for industrial microcontrollers concentrates margin capture at the safety instrumented system hardware tier, while software vendors extract recurring value through SaaS tiers decoupled from silicon cost cycles.
Pricing Analysis
Volume-discount tiering structures separate enterprise multi-plant deployments from mid-market single-facility installations. Three-tier pricing stratification across premium IEC-certified, standard ISA-compliant, and economy non-certified levels reflects after-sales engineering bundling and audit documentation depth. Pricing pressure stems from API-first entrants compressing deployment margins. Chemical plants under OSHA mandates exhibit lowest price sensitivity due to compliance liability exposure, while discrete manufacturers prioritize capital efficiency.
Supply Chain Analysis
Tariff exposure between East Asian semiconductor sources and North American system integrators dominates supply chain risk calculus. Safety instrumented system hardware draws from Taiwan, South Korea, and Japan for specialized industrial microcontrollers. Brominated flame retardant enclosures and ATEX-rated housing materials face REACH substitution timelines. Single-source vulnerability concentrates at the foundry tier for automotive-grade silicon. Distribution runs through system integrator channels though API marketplaces are disintermediating procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics inflection is restructuring vendor capture as API-based procurement and cloud-native delivery dissolve traditional system integrator gatekeeping, with interoperability standards determining which architectures achieve preferred status.
For Market Incumbents: Pre-empt API-first disintermediation by embedding alarm analytics natively into distributed control system architectures. Consolidate specification influence through IEC-compliant engineering services bundled into multi-year facility contracts. Certification investment in EU AI Act explainability frameworks creates defensive moats against cloud-native entrants targeting automated prioritization. For New Entrants and Emerging Players: Build out healthcare facility penetration in German hospital operating rooms and pharmaceutical cleanrooms where IEC-compliant rationalization tools remain undersupplied. Target mid-market utilities with centralized IT governance mandating multi-plant standardization. SaaS procurement through enterprise software marketplaces offers the most penetrable go-to-market angle. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed industrial software platforms consolidating fragmented alarm management modules. Long-term viability hinges on API ecosystem positioning and cloud-native architecture migration. Acquisition targets should demonstrate explainability framework documentation for EU AI Act alignment. The signal to watch is procurement authority migration from plant engineering to enterprise digital transformation offices.| Strategic Initiative | Industry Significance |
|---|---|
| API Marketplace Integration | Direct procurement bypasses system integrators for Fortune 500 manufacturers. |
| EU AI Act Certification | Explainability frameworks create certified-provider advantages in automated prioritization. |
| Healthcare Vertical Expansion | German hospital whitespace offers first-mover positioning in patient safety monitoring. |
| Edge Computing Deployment | Wellpad cluster virtualization suppresses nuisance alarms before SCADA transmission. |
| Legacy DCS Gateway Development | 1990s-era protocol translation captures replacement cycles at chemical facilities. |
Study Parameters
Operator-level perspectives from control room supervisors, process safety engineers, alarm rationalization consultants, and plant engineering directors anchored the qualitative base. Primary fieldwork combined structured interviews with secondary validation against IEC 62682 audit documentation, ISA-18.2 certification records, and OSHA process safety management inspection data. SEC filings from automation conglomerates, customs records for safety instrumented system hardware, and hyperscaler cloud platform disclosures provided triangulation anchors. Bottom-up facility counts and top-down industrial automation spend estimates converged through iterative reconciliation.
Scenario-bracketing framed demand projections across the analysis window, with segmentation modeling across deployment architecture, end-use vertical, integration level, and regional regulatory enforcement intensity. CAGRs derived from facility replacement cycle analysis and compliance audit window timing. Cloud adoption curves and API procurement penetration served as industry-specific forecast inputs alongside safety instrumented system recertification mandates.
Stress conditions across semiconductor lead time volatility, REACH chemical substitution timelines, and EU AI Act implementation pacing were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding standard convergence and procurement authority migration. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Safety Equipment and Personal Protective Equipment (PPE)
Bulletproof Gear Market
Safety Equipment and Personal Protective Equipment (PPE)
Wearable Airbag Belt Market
Safety Equipment and Personal Protective Equipment (PPE)
Military Protection Glasses Market
Safety Equipment and Personal Protective Equipment (PPE)
United States Safes and Vaults Market
Safety Equipment and Personal Protective Equipment (PPE)
Europe N95 Mask Market
Safety Equipment and Personal Protective Equipment (PPE)
Driving Protection Gear Market
Safety Equipment and Personal Protective Equipment (PPE)
Public Address and Voice Alarm Systems Market
Safety Equipment and Personal Protective Equipment (PPE)
Industrial Machine Guarding Fence Market
Safety Equipment and Personal Protective Equipment (PPE)
Active Seat Belt System Market
Safety Equipment and Personal Protective Equipment (PPE)
Gas Detection Equipment Market
Safety Equipment and Personal Protective Equipment (PPE)
PPE Detection Market
Safety Equipment and Personal Protective Equipment (PPE)
Global Law Enforcement Personal Protective Equipment Market
Safety Equipment and Personal Protective Equipment (PPE)
Hearing Protection Equipment Market
Safety Equipment and Personal Protective Equipment (PPE)
APAC Safety Instrumented Systems Market
Safety Equipment and Personal Protective Equipment (PPE)
Middle East and Africa Intrinsically Safe Equipment Market
Safety Equipment and Personal Protective Equipment (PPE)
Hand Protection Equipment Market