
 Europe Safes and Vaults Market | 2026-2036
Europe Safes and Vaults Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Safes and Vaults Market Intelligence
European steel fabrication capacity is decoupling from legacy cold-rolling methods as producers retool for certified security-grade alloys. Bode-Panzer GmbH leverages its Ruhr Valley manufacturing base to dominate German commercial banking contracts. Dormakaba Group sustains cross-border distribution through integrated lock-and-enclosure platforms serving Scandinavian financial institutions. Gunnebo Group anchors Nordic market share with marine-grade vault systems for offshore oil and gas document custody.
Safes and vaults are hardened steel enclosures engineered to EN 1143 and EN 14450 resistance grades, with composite wall constructions integrating manganese steel layers, concrete infill, and ceramic burn barriers to defeat cutting, drilling, and thermal attack for timed asset protection. Fire Safes and Burglary Safes occupy the core revenue pool, with the former commanding premium positioning as insurers mandate certified document preservation for SME policies. Electronic Locks and Biometric Locks are displacing mechanical systems in Financial Institutions, where dual-authentication protocols align with ECB operational risk guidelines.
CE marking under the EU Construction Products Regulation and EN 1143 certification enforced by Germany's KBA and France's CNPP shape product access, with non-compliant imports barred from public procurement channels. ECHA REACH compliance adds material traceability costs for imported alloy feedstock. Stakeholders must monitor evolving ECB cash-handling directives and national deposit insurance frameworks that dictate vault redundancy standards across member states.
Market Dynamics
ECB custody standards for cash and document protection are forcing wholesale replacement cycles across German, French, and UK banking infrastructure, compressing equipment lifespans from twenty-five to fifteen years and reshaping procurement specifications.
Growth Catalysts
- ECB Cash-Handling Directives:Mandatory vault redundancy standards across eurozone member states require financial institutions to upgrade legacy installations with certified EN 1143 Grade IV and V enclosures.
- Germany:Branch modernization programs in the Ruhr Valley banking corridor drive systematic ATM vault replacements and main vault infrastructure expansion.
- Low-Carbon Steel Fabrication:EU Green Deal compliance incentives accelerate retooling of foundries toward certified security-grade alloy production with embedded carbon accounting.
Market Restraints
- Alloy Feedstock Volatility:ECHA REACH material traceability requirements impose documentation burdens on manganese steel and specialized composite imports, inflating landed costs for non-EU sourced inputs.
- Ruhr Valley Concentration:German steel fabrication clusters control seventy percent of security-grade plate capacity, creating geographic supply vulnerability for southern European vault assemblers.
- EN 14450 Certification Friction:Extended testing timelines at France's CNPP and Germany's KBA delay product launches by eight to fourteen months, freezing working capital in inventory.
Strategic Opportunities
- Scandinavian Offshore Oil and Gas:Marine-grade vault systems for document custody on North Sea platforms represent an underpenetrated vertical with specialized corrosion-resistance specifications.
- Biometric-Electronic Convergence:Dual-authentication lock platforms integrating fingerprint recognition with token-based access align with evolving ECB operational risk guidelines for high-value custody.
- SME Insurance Mandates:Underwriter requirements for certified fire-safe document preservation create pull-through demand from policy compliance departments rather than traditional security procurement.
Industry Challenges
- Welding Certification Scarcity:Qualified technicians for manganese steel composite wall construction remain concentrated in legacy automotive and defense supply chains, constraining production scaling.
- Legacy Mechanical System Integration:Banking clients with heterogeneous installed bases demand backward-compatible electronic retrofit kits, complicating R&D roadmaps and inventory management.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Safes and Vaults Market |
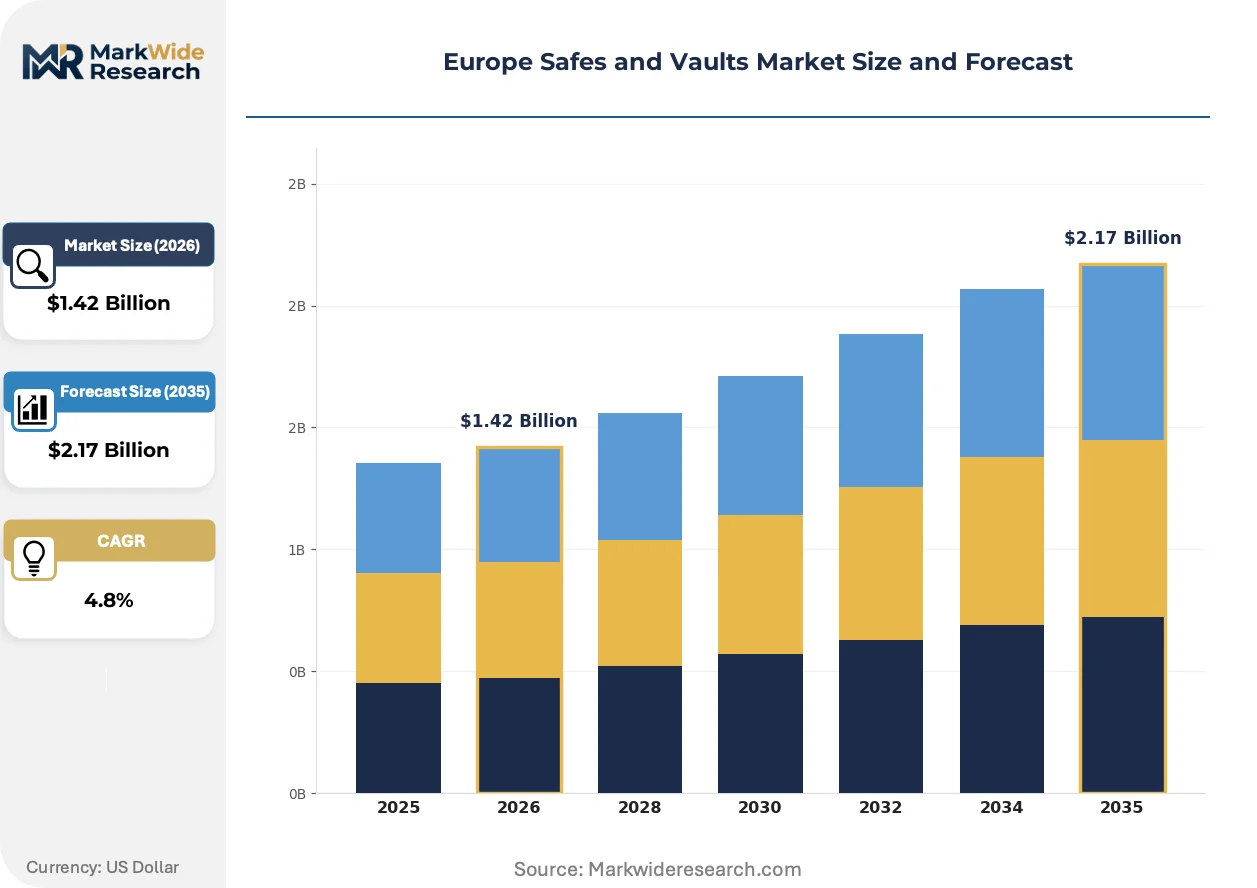
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $2.17 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fire Safes, Burglary Safes, Safe Deposit Boxes, Gun Safes End User: Residential, Commercial, Industrial, Financial Institutions Lock Type: Mechanical Locks, Electronic Locks, Biometric Locks, Dual-Lock Systems Distribution Channel: Direct Sales, Retail Stores, Online Platforms, Wholesale |
| Companies Covered | Bode-Panzer GmbH, BJARSTAL, Chubbsafes, Bordogna, Caradonna, Dormakaba Group, Fichet-Bauche, Access Security Products Ltd., Gunnebo Group, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Safes and Vaults Market Strategic Shifts & Innovations
Authentication architecture is fragmenting across multiple verification modalities while fabrication methods and procurement specifications undergo parallel reinvention. Three concurrent developments are restructuring competitive requirements.
Biometric access modules are decentralizing custody authority from centralized key management to individual user verification. German commercial banks are deploying fingerprint and palm-vein scanners at branch vaults within eighteen-month procurement cycles. This shift is decentralizing operational risk accountability to endpoint users while compressing traditional locksmith service revenue streams.
EU Green Deal carbon-border adjustments are mandating embodied emissions disclosure for imported steel feedstock. Manufacturers must now document Scope 3 emissions through mill certificates or face exclusion from public procurement frameworks. French and Dutch banking consortia have responded by inserting carbon-intensity clauses into vault tender specifications, favoring Ruhr Valley producers with verified low-carbon production.
Outcome-based maintenance contracts are supplanting capital purchase models for large financial institutions. Scandinavian banks now lease vault infrastructure with bundled certification renewal and penetration-testing services, transferring obsolescence risk to manufacturers. This reconfiguration is most visible in Denmark and Sweden, where integrated service platforms from lock-and-enclosure specialists have captured dominant positions in renewal negotiations.
Europe Safes and Vaults Market Segmentation
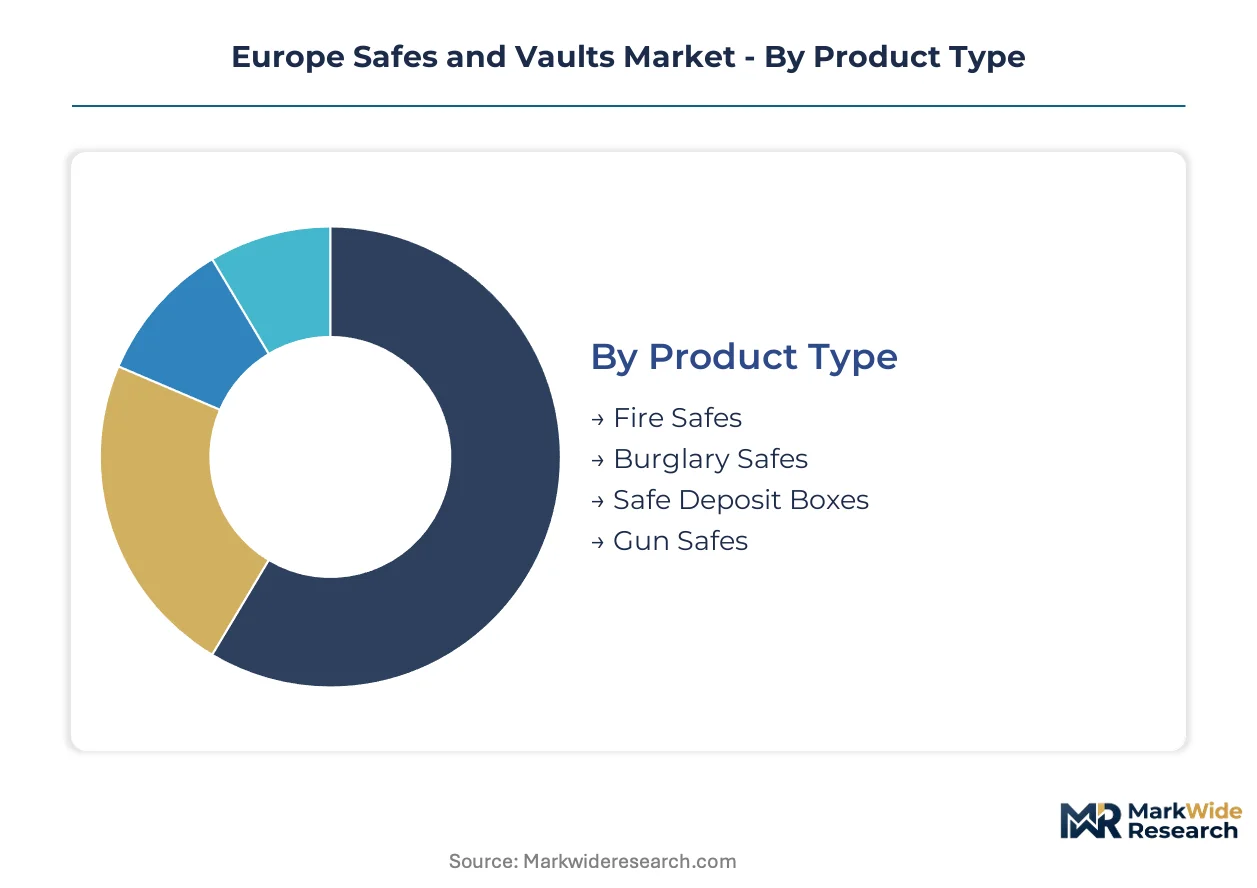
European vault procurement splits sharply across custody duty, with financial institutions demanding EN 1143 Grade IV-V certification while residential buyers prioritize fire ratings over burglary resistance. Lock technology and distribution channel selection further stratify margins, as biometric-electronic convergence commands premium positioning against mechanical legacy systems.
Product Type:
Buyers in this category separate by asset protection priority — document preservation versus physical security versus specialized custody requirements.
- Fire Safes:Engineered with ceramic fiber insulation and intumescent seals to maintain sub-177°C internal temperatures during standardized fire exposure. German and French insurers now mandate EN 1047-1 certification for SME policy eligibility, pulling demand through compliance departments rather than traditional security procurement. Volume sits with Fire Safes; growth tilts toward Biometric-Electronic convergence in adjacent categories.
- Burglary Safes:Constructed from manganese steel composite walls with concrete infill to achieve EN 1143 resistance grades against cutting, drilling, and thermal attack. ECB custody standards are compressing replacement cycles across German, French, and UK banking infrastructure from twenty-five to fifteen years.
- Safe Deposit Boxes:Modular vault installations for retail banking branches with dual-control access protocols.
- Gun Safes:Specialized enclosures meeting national firearms storage regulations across EU member states.
Fire certification commands premium positioning in commercial procurement; burglary resistance drives financial institution renewal cycles.
End User:
Application context determines specification intensity, from domestic document storage to ECB-mandated cash custody infrastructure.
- Financial Institutions:Central banks and commercial banking networks operating vault infrastructure under ECB operational risk guidelines. Branch modernization programs across Germany's Ruhr Valley corridor drive systematic ATM vault replacements and main vault expansion, with dual-authentication protocols now standard for high-value custody.
- Commercial:Retail, hospitality, and professional services requiring certified document preservation and cash storage. Underwriter requirements for fire-safe certification create pull-through demand from insurance compliance departments rather than security procurement teams.
- Residential:Individual households prioritizing fire protection for documents and valuables over burglary resistance.
- Industrial:Manufacturing and logistics facilities securing high-value inventory and specialized equipment.
Financial institutions concentrate procurement volume; commercial compliance mandates are expanding most quickly.
Lock Type:
Authentication architecture fragments across verification modalities, with procurement specifications increasingly mandating multi-factor protocols.
- Electronic Locks:Token-based or keypad access systems with audit trail logging and time-delay functions. German commercial banks are deploying these at branch vaults within compressed procurement cycles, decentralizing operational risk accountability to endpoint users.
- Biometric Locks:Fingerprint and palm-vein recognition modules integrated with electronic platforms for dual-authentication. Scandinavian financial institutions lead deployment, aligning with evolving ECB guidelines for high-value custody.
- Mechanical Locks:Traditional key and combination systems with legacy installed bases across older banking infrastructure.
- Dual-Lock Systems:Integrated mechanical-electronic or biometric-mechanical configurations for maximum security environments.
Electronic systems dominate current installed base; biometric-electronic convergence shows steepest expansion trajectory.
Distribution Channel:
Channel selection tracks buyer scale and specification complexity, with certified financial procurement bypassing retail entirely.
- Direct Sales:Manufacturer-to-institution relationships for large-scale vault infrastructure with bundled installation and certification services. Scandinavian banks now favor outcome-based maintenance contracts with bundled renewal and penetration-testing services.
- Wholesale:Distributor networks supplying security integrators and construction contractors for commercial installations.
- Retail Stores:Physical showrooms serving residential and small commercial buyers with standardized product ranges.
- Online Platforms:E-commerce channels for entry-level fire safes and residential burglary protection.
Direct sales capture institutional volume; wholesale channels are gaining share fastest in commercial mid-market.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Ruhr Valley steel fabrication clusters supply seventy percent of security-grade plate capacity for European vault manufacturing, anchoring production geography to German industrial infrastructure.
Germany
Branch modernization programs across the Ruhr Valley banking corridor drive systematic ATM vault replacements and main vault infrastructure expansion. KBA enforces EN 1143 certification with extended testing timelines that delay product launches. Düsseldorf-based banking consortia now insert carbon-intensity clauses into tender specifications, favoring domestic producers with verified low-carbon production.
France
CNPP certification friction extends testing timelines by eight to fourteen months, freezing working capital in inventory for vault assemblers. Insurers mandate EN 1047-1 fire-safe certification for SME policy eligibility, pulling demand through compliance departments. Lyon and Paris banking networks are expanding vault redundancy infrastructure under ECB operational risk guidelines.
United Kingdom
Financial institutions are expanding vault infrastructure to meet evolving custody standards for cash and document protection. National deposit insurance frameworks dictate vault redundancy standards that compress equipment lifespans. London's financial district drives premium demand for dual-authentication lock platforms.
Sweden
Scandinavian banks now favor outcome-based maintenance contracts with bundled certification renewal and penetration-testing services. Gunnebo Group anchors Nordic market share with marine-grade vault systems. Stockholm-based financial institutions lead deployment of biometric-electronic convergence for high-value custody.
Italy
Commercial compliance mandates for certified document preservation are expanding most quickly among retail and hospitality sectors. Bordogna and Caradonna occupy positions within the regional fabrication tier. Milan's professional services cluster generates pull-through demand from insurance compliance departments.
Europe Safes and Vaults Market Key Industry Players
Global majors compete with regional champions across certification depth and steel fabrication proximity. The vendor base splits between Ruhr Valley-anchored producers controlling security-grade alloy supply and cross-border distributors with integrated lock-and-enclosure platforms. Three archetypes dominate: German fabrication specialists with captive steel supply, Scandinavian marine-grade system providers, and integrated lock-enclosure platforms serving multi-country banking networks. Competitive moves concentrate on backward integration into certified alloy production and biometric-electronic lock convergence.
Among German-based fabricators, Bode-Panzer GmbH occupies a position exemplifying Ruhr Valley manufacturing concentration, while Dormakaba Group represents the integrated lock-and-enclosure platform archetype. Gunnebo Group anchors the Scandinavian marine-grade specialization tier. These three companies illustrate the geographic and capability segmentation that structures procurement decisions across eurozone financial institutions.
| Leading Market Players |
|---|
| Bode-Panzer GmbH |
| BJARSTAL |
| Chubbsafes |
| Bordogna |
| Caradonna |
| Dormakaba Group |
| Fichet-Bauche |
| Access Security Products Ltd. |
| Gunnebo Group |
| Others |
Cost & Logistics Intelligence
EN 1143 certification grade divergence separates premium vault assemblers from commodity safe producers, with this performance ladder manifesting in bundled installation-and-certification pricing for banking clients and stripped-down spot pricing for residential channels. German KBA and French CNPP testing timelines feed directly into working capital costs, compressing margins on lower-grade products while reinforcing pricing power at Grade IV-V levels.
Pricing Analysis
Warranty and certification-bundling arrangements distinguish institutional procurement from retail transactions, with Scandinavian banks now leasing vault infrastructure inclusive of renewal and penetration-testing services. Three-tier pricing structure across premium, standard, and economy levels tracks EN 1143 grade, lock technology, and after-sales service intensity. Cost compression in economy fire safes is intensifying because online retail channels disintermediate traditional security integrators. Commercial buyers purchasing through insurance compliance mandates show lowest price sensitivity; residential online shoppers exhibit highest elasticity.
Supply Chain Analysis
Direct-to-bank channels handle institutional vault demand, while wholesale distributor networks supply commercial installers and retail showrooms serve residential buyers. Security-grade manganese steel plate concentrates in Germany's Ruhr Valley, with secondary fabrication clusters in France and Italy. Raw material dependencies center on manganese ore, specialized ceramic burn barriers, and certified low-carbon steel feedstock. Single-source vulnerability sits with Ruhr Valley plate capacity, where qualified welding technicians for composite wall construction remain scarce. Distribution runs through manufacturer-direct relationships for large financial institutions and security integrator networks for mid-market commercial installations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is a vertical-integration race, with players pursuing backward integration into certified low-carbon alloy production to satisfy EU Green Deal procurement clauses and carbon-border adjustment requirements.
For Market Incumbents: Anticipate biometric-electronic convergence displacing mechanical lock installed bases, and secure captive supply of security-grade steel plate through Ruhr Valley foundry partnerships or long-term offtake agreements. ECB operational risk guideline updates threaten legacy system compatibility requirements; certification investment in dual-authentication platforms defends position against integrated lock-and-enclosure specialists. For New Entrants and Emerging Players: The premium-to-economy price gap in fire-safe certification for SME insurance compliance offers entry space without competing on Grade IV-V vault engineering. Target commercial compliance departments in Italy's retail and hospitality sectors, where underpenetrated demand for EN 1047-1 certified document preservation outpaces banking infrastructure renewal cycles. Go-to-market through wholesale security integrator channels bypasses direct sales force requirements. For Investors and Strategic Acquirers: Re-rating potential sits with integrated lock-and-enclosure platforms given biometric-electronic convergence catalysts and outcome-based maintenance contract adoption. Long-term viability favors specialists with captive steel supply and certified fabrication capacity across the analysis window. Monitor ECB cash-handling directive revisions as inflection signal for replacement cycle acceleration or compression.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Low-Carbon Alloy Production | Ruhr Valley foundry partnerships secure EU Green Deal compliance for public procurement eligibility. |
| Biometric-Electronic Lock Platform Development | Dual-authentication systems align with evolving ECB operational risk guidelines for high-value custody. |
| Outcome-Based Maintenance Contract Expansion | Scandinavian leasing models transfer obsolescence risk and capture renewal revenue streams. |
| Marine-Grade Vault System Specialization | North Sea oil and gas document custody creates defensible niche with corrosion-resistance specifications. |
| SME Insurance Compliance Channel Development | Pull-through demand from underwriter mandates expands addressable market beyond traditional security procurement. |
Research Approach
Document review covered ECB cash-handling directives, EN 1143 and EN 14450 certification standards, EU Green Deal implementation frameworks, and national deposit insurance regulations, complemented by interviews with vault manufacturing executives, KBA and CNPP certification officials, banking procurement directors, security integrators, and insurance compliance officers. Secondary sources included customs and trade data for steel feedstock flows, foundry capacity disclosures, and public procurement tender databases. Bottom-up demand modeling triangulated against top-down steel consumption and certification issuance data.
Market size and growth trajectory outputs derived from segment-level demand aggregation across product type, end user, lock technology, and distribution channel dimensions, with CAGRs computed from fitted trend lines against historical replacement cycle data. Modeled inputs included ECB vault redundancy mandate adoption rates, EN 1143 Grade IV-V penetration in banking infrastructure, and biometric lock deployment timelines across eurozone member states.
Inputs from KBA and CNPP certification registries were available through the study window; gaps in real-time foundry capacity utilization and welding technician labor pool data introduce uncertainty bands around production scaling assumptions. Forecasts reflect documented regulatory trajectories and banking infrastructure investment intentions. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Safety Equipment and Personal Protective Equipment (PPE)
Global Radiation Protection Apron Market
Safety Equipment and Personal Protective Equipment (PPE)
Active Hearing Protection Market
Safety Equipment and Personal Protective Equipment (PPE)
Electrical Safety Analyzers Market
Safety Equipment and Personal Protective Equipment (PPE)
United States Safes and Vaults Market
Safety Equipment and Personal Protective Equipment (PPE)
Drone Safety Solutions Market
Safety Equipment and Personal Protective Equipment (PPE)
Radiation Monitoring and Dosimeter Badges Market
Safety Equipment and Personal Protective Equipment (PPE)
Global Anti-Vibration Gloves Market
Safety Equipment and Personal Protective Equipment (PPE)
Flammable Storage Cabinets Market
Safety Equipment and Personal Protective Equipment (PPE)
Smart Hazard and Safety Indicator Control Modules Market
Safety Equipment and Personal Protective Equipment (PPE)
Global Locker Market
Safety Equipment and Personal Protective Equipment (PPE)
Asia-Pacific Riot Control Equipment Market
Safety Equipment and Personal Protective Equipment (PPE)
Plastics in Personal Protective Equipment Market
Safety Equipment and Personal Protective Equipment (PPE)
Middle East and Africa Process Safety Services Market
Safety Equipment and Personal Protective Equipment (PPE)
Panic Exit Devices Market
Safety Equipment and Personal Protective Equipment (PPE)
United States Emergency Lighting Market
Safety Equipment and Personal Protective Equipment (PPE)
Active Protection System Market