
 Respiratory Protective Equipment Market | 2026-2036
Respiratory Protective Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Respiratory Protective Equipment Market Analysis
China's manufacturing expansion in polymer filtration media is reshaping upstream supply dynamics for respiratory protective equipment. 3M leverages its integrated electret media production to sustain margin advantages across North American healthcare channels. MSA Safety Incorporated anchors its position through fixed gas detection combined with respiratory system bundling for oil and gas clients.
Respiratory protective equipment encompasses tight-fitting facepieces, loose-fitting hoods, and powered systems engineered to filter airborne particulates, gases, or vapors through mechanical or electrostatic capture media with assigned protection factors ranging from ten to one thousand. These devices serve primarily to prevent occupational lung disease, acute chemical injury, and infectious aerosol transmission in hazardous atmosphere workplaces. N95 respirators and powered air-purifying respirators command the fastest expansion trajectories as healthcare and heavy industry upgrade from basic dust masks to higher-assignment-protection-factor systems. Full face masks retain premium positioning in chemical exposure applications where eye protection integration justifies unit price multiples over half-mask alternatives.
OSHA enforces permissible exposure limits that mandate employer-supplied respiratory protection across construction and manufacturing settings, while the FDA regulates surgical N95 respirators as medical devices requiring 510(k) clearance for fluid resistance claims. The EU AI Act and MDR frameworks are beginning to influence smart respirator development pathways, particularly for connected fit-monitoring systems. Stakeholders must track how converging occupational safety and medical device regulatory scopes will reshape product development roadmaps and certification investment requirements.
Market Dynamics
Electret filtration media production is consolidating among polymer specialists with captive meltblown capacity, compressing margin structures for respirator assemblers dependent on merchant supply. This upstream concentration is redistributing value capture toward integrated compounders and forcing downstream players toward backward integration or long-term offtake commitments.
Growth Catalysts
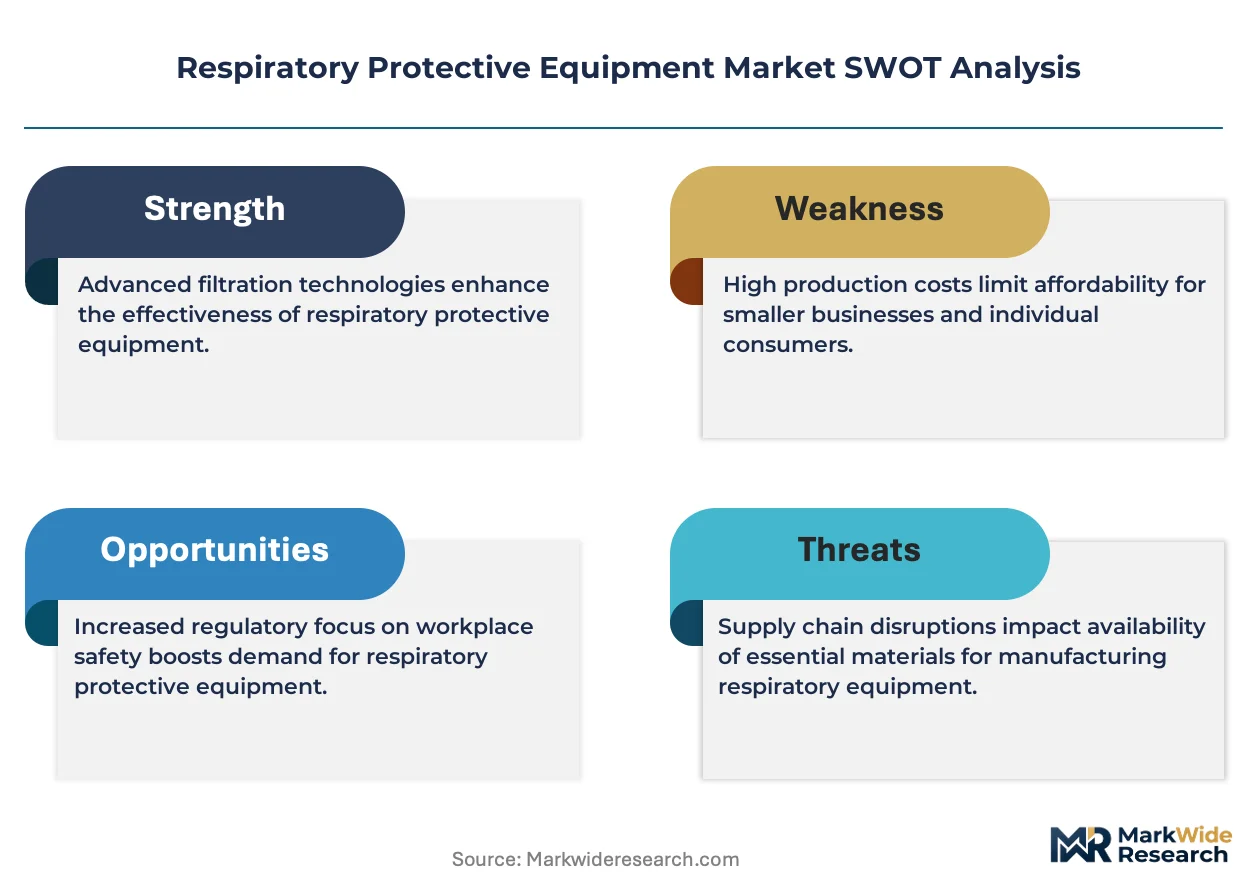
- OSHA permissible exposure limit enforcement:US construction and manufacturing employers must maintain employer-supplied respiratory protection programs, mandating fit testing and documented respirator assignments.
- EU PPE Regulation 2016/425 certification upgrades:European supply chains are accelerating filtration technology investments to meet tightened module B+C2 conformity assessment routes for category III devices.
- India's industrial corridor expansion:Construction and manufacturing activity across Gujarat, Maharashtra, and Tamil Nadu is driving procurement of half-mask and powered air-purifying respirator systems.
Market Restraints
- Polypropylene resin price volatility:Electret-grade meltblown media depends on specialized polymer feedstocks subject to petrochemical cycle swings and freight cost spikes.
- Single-source electret treatment equipment:Corona and tribocharging machinery for permanent charge implantation concentrates among German and Japanese capital equipment suppliers.
- Fit testing protocol complexity:OSHA quantitative fit testing requirements using ambient aerosol or controlled negative pressure methods impose recurring operational burdens on smaller employers.
Strategic Opportunities
- Connected fit-monitoring systems:Bluetooth-enabled respirators with real-time seal verification align with EU AI Act and MDR frameworks for smart PPE.
- Reusable elastomeric platforms:Healthcare systems seeking stockpile resilience are evaluating cartridge-based half-masks as alternatives to disposable N95 supply chains.
- Industrial distributor direct sourcing:Bypassing traditional medical supply intermediaries allows manufacturers to capture margin and establish service relationships with safety managers.
Industry Challenges
- 510(k) clearance timelines:FDA review of surgical N95 fluid resistance claims creates extended commercialization windows for novel filter media formulations.
- Legacy fit testing infrastructure:PortaCount and controlled negative pressure systems require specialized technician training and calibration maintenance that strains occupational health departments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Respiratory Protective Equipment Market |
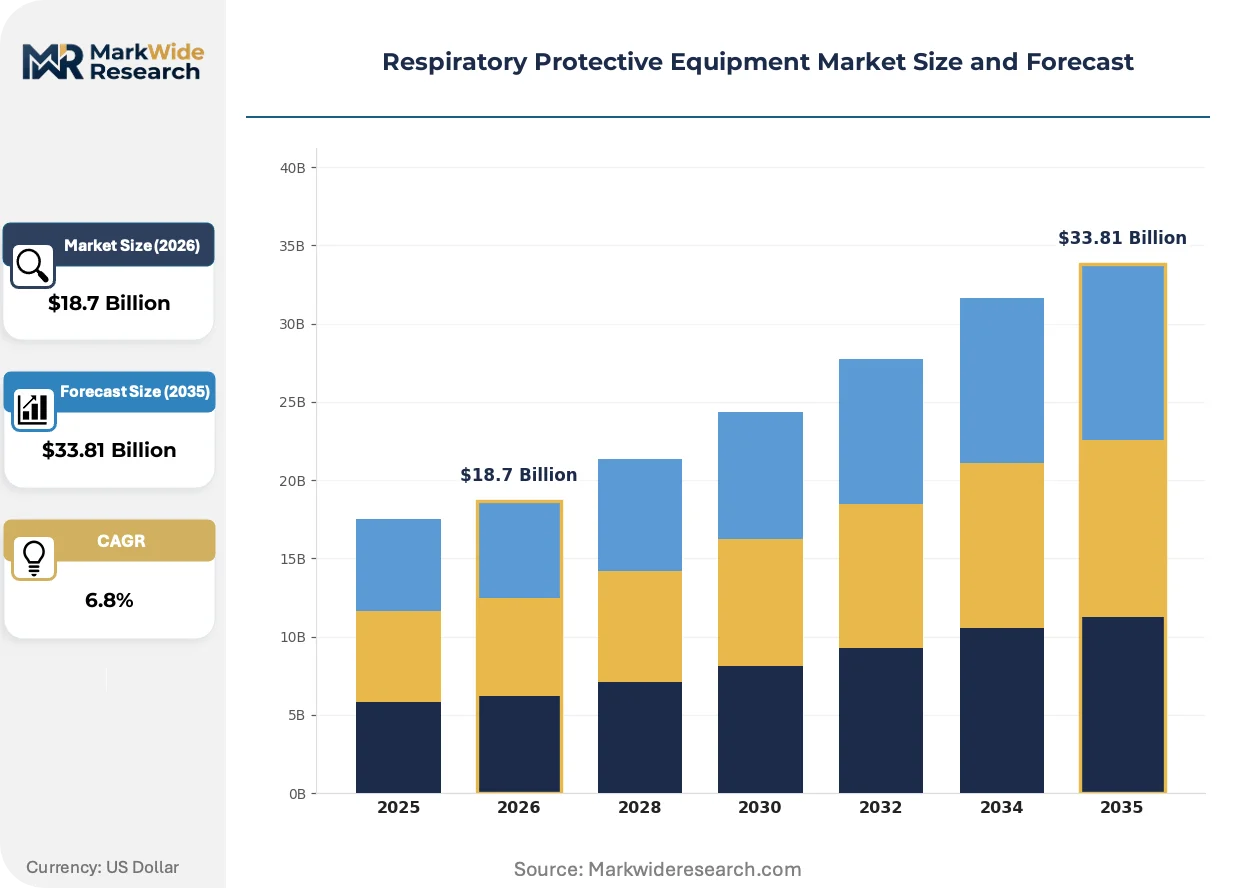
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: N95 Respirators, Full Face Masks, Half Masks, Powered Air-Purifying Respirators End User: Construction, Healthcare, Oil & Gas, Manufacturing Application: Dust Protection, Chemical Exposure, Infection Control, Pandemic Response Distribution Channel: Offline Retail, Online Platforms, Direct Sales, Wholesalers |
| Companies Covered | 3M, Honeywell International Inc., MSA Safety Incorporated, Drägerwerk AG & Co. KGaA, Alpha Pro Tech, Bullard, Avon Protection, Moldex-Metric, Gentex Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Respiratory Protective Equipment Market Emerging Trajectories
Filtration science and digital integration are converging to redefine respiratory protection performance metrics and procurement criteria. The market is witnessing simultaneous compression in traditional supply chains and emergence of connected device categories.
Electret nanofiber composites are collapsing the performance gap between mechanical and electrostatic capture mechanisms. Heavy industry safety managers are specifying these media for oil mist environments previously requiring P100 cartridges. The technology is collapsing the historical trade-off between breathing resistance and filtration efficiency that constrained half-mask comfort ratings.
EU AI Act risk classification rules are reshaping development roadmaps for connected respirators. Manufacturers must document algorithmic transparency and human oversight protocols for real-time fit monitoring systems. North American healthcare channels are delaying smart respirator launches until CE marking under MDR Article 10 establishes precedent for FDA 510(k) predicate alignment.
Hospital system procurement committees are consolidating vendor relationships around full-service respiratory protection programs. Group purchasing organizations are unbundling fit testing services from device supply contracts and awarding multi-year managed service agreements to integrated safety providers. This consolidation is most visible across US integrated delivery networks seeking pandemic stockpile standardization.
Respiratory Protective Equipment Market Segmentation
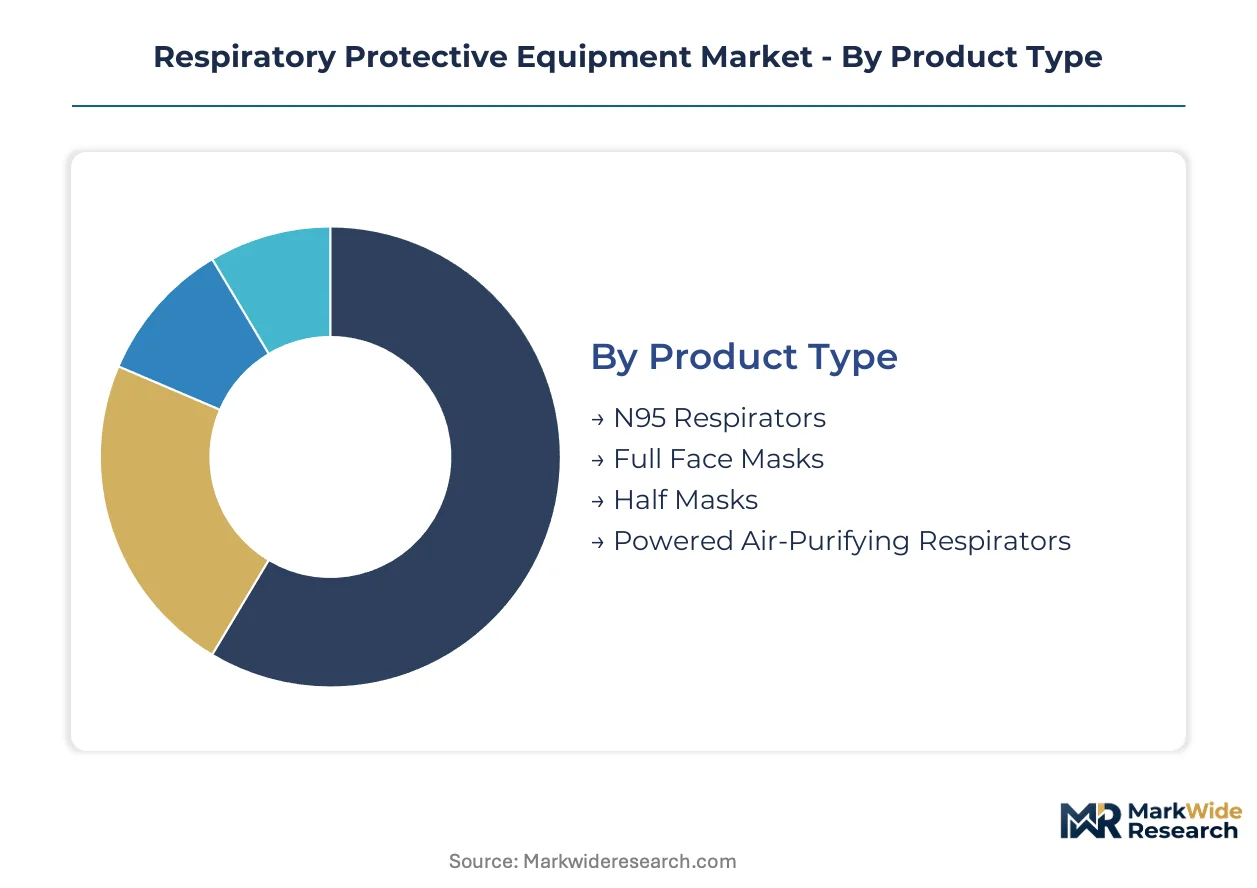
Respiratory protective equipment procurement follows distinct technical and commercial logics across product architectures, end-use environments, and supply channels. Understanding these segment boundaries clarifies where filtration technology investments concentrate and how regulatory scopes reshape vendor positioning.
Product Type:
Mature tight-fitting designs dominate current procurement volumes while emerging powered systems capture specification upgrades in high-exposure settings.
- N95 Respirators:Disposable cup-shaped or flat-fold devices with electret polypropylene media achieving 95% filtration efficiency against 0.3-micron particles. OSHA enforcement across US construction and manufacturing drives fit-testing program standardization. FDA 510(k) clearance requirements for surgical variants extend commercialization timelines for novel media formulations.
- Powered Air-Purifying Respirators:Battery-driven blower units delivering filtered air through loose-fitting hoods or tight-fitting facepieces with assigned protection factors up to 1,000. India's industrial corridors in Gujarat and Maharashtra specify these systems for foundry and chemical processing environments where half-mask protection proves insufficient.
- Full Face Masks:Elastomeric designs integrating eye protection with dual-cartridge filtration for chemical vapor and particulate combinations.
- Half Masks:Reusable elastomeric platforms with replaceable mechanical or combination cartridges, gaining traction in healthcare stockpile resilience planning.
N95 respirators handle the majority of throughput; powered air-purifying respirators are expanding most quickly on specification share.
End User:
Cost tier differentiation separates premium-specification healthcare and oil and gas procurement from volume-driven construction and manufacturing segments.
- Construction:Dust and silica exposure drives half-mask and disposable respirator procurement across residential and infrastructure projects. OSHA permissible exposure limit enforcement mandates employer-supplied programs with documented fit testing.
- Healthcare:Surgical N95 and elastomeric alternatives serve infectious aerosol protection and pandemic stockpile requirements. US integrated delivery networks consolidate vendor relationships around full-service respiratory protection programs with unbundled fit testing services.
- Oil & Gas:Hydrogen sulfide and volatile organic compound exposure necessitates full-face and powered systems with fixed gas detection integration.
- Manufacturing:Metalworking, pharmaceutical, and food processing applications span the product type spectrum based on contaminant characteristics and exposure duration.
Construction absorbs the highest unit volumes; healthcare commands the steepest price premiums per unit.
Application:
Volume concentration clusters in dust protection while margin capture concentrates in chemical exposure and infection control specifications.
- Dust Protection:Mechanical filtration against silica, coal dust, and nuisance particulates in mining, construction, and agricultural operations. N95 and P100 disposable respirators dominate with electret media providing electrostatic enhancement to mechanical capture.
- Chemical Exposure:Organic vapor, acid gas, and ammonia protection through activated carbon and multi-gas cartridges in chemical manufacturing and petrochemical operations. Full face masks retain premium positioning where eye protection integration justifies unit price multiples.
- Infection Control:Surgical N95 respirators with fluid resistance claims for operating room and isolation environments.
- Pandemic Response:Strategic stockpile procurement of disposable and elastomeric platforms for surge capacity.
Dust protection handles the majority of throughput; infection control specifications are gaining share fastest on margin contribution.
Distribution Channel:
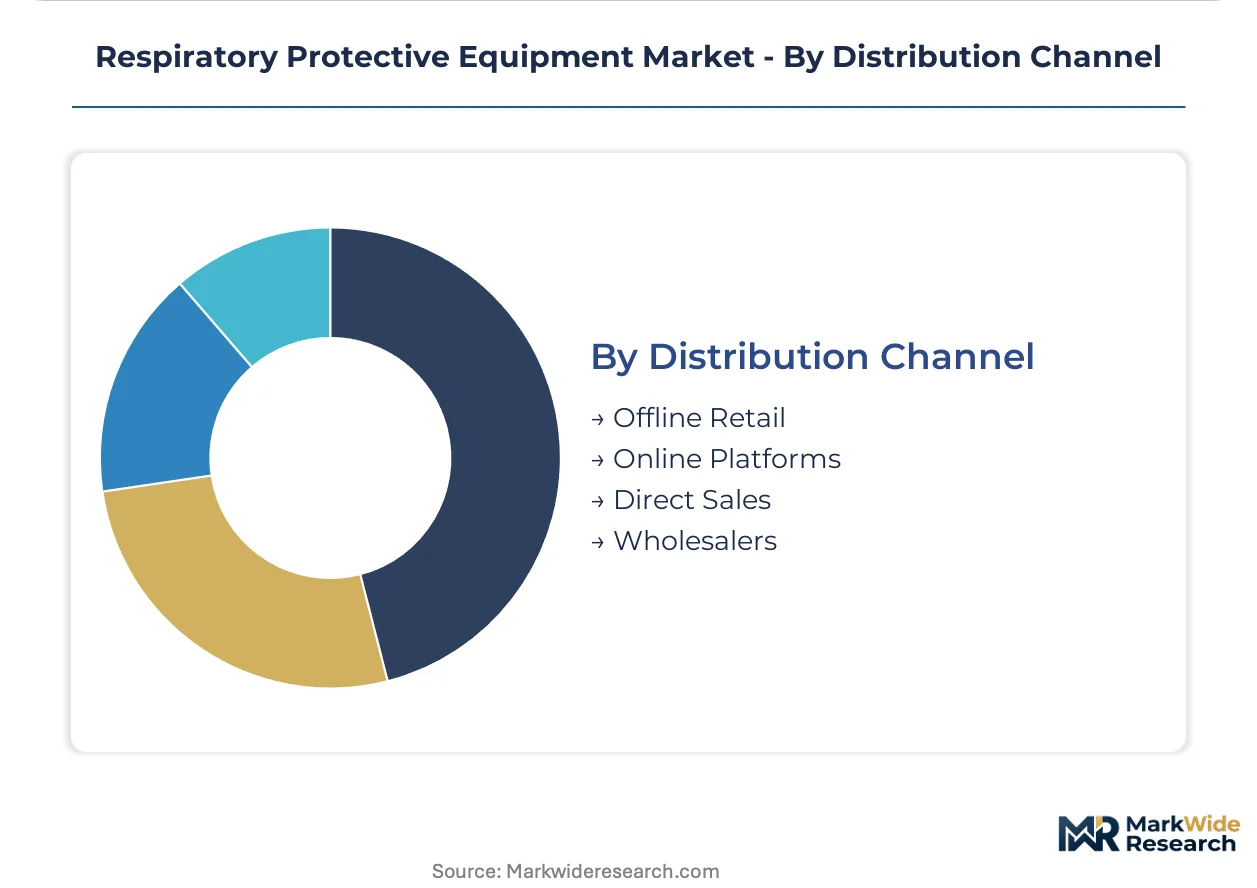
Customer type fragmentation separates price-sensitive small employer procurement through wholesalers from integrated safety programs sold direct to enterprise safety managers.
- Direct Sales:Manufacturer relationships with integrated delivery networks and industrial safety managers for managed respiratory protection programs. Multi-year service agreements bundle fit testing, training, and device supply.
- Wholesalers:Industrial distributors serving mid-sized construction and manufacturing employers with transactional respirator and cartridge replenishment.
- Offline Retail:Hardware and safety supply stores for small contractor and consumer DIY respirator purchases.
- Online Platforms:E-commerce channels for standardized N95 and half-mask cartridge procurement, constrained by fit testing protocol requirements that favor established distributor relationships.
Direct sales capture the highest service-attach revenue; online platforms are climbing fastest on convenience-driven small employer adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
OSHA workplace exposure mandates anchor procurement volumes in the United States, while EU PPE Regulation 2016/425 and India's industrial corridor expansion reshape supply chain investments across distinct regulatory environments.
United States
Healthcare systems in Texas and California are expanding N95 stockpile programs following OSHA permissible exposure limit enforcement. FDA 510(k) clearance requirements for surgical respirators extend commercialization timelines for novel filter media. Construction activity across the Sun Belt drives fit-testing program standardization among mid-sized contractors.
Germany
Chemical manufacturing clusters along the Rhine-Main corridor specify full-face masks with integrated eye protection for organic vapor exposure. EU PPE Regulation 2016/425 module B+C2 conformity assessment routes accelerate filtration technology upgrades. Bavarian automotive suppliers are bundling powered air-purifying respirators with fixed gas detection systems.
China
Polymer filtration media manufacturing concentrates in Zhejiang and Jiangsu provinces, consolidating electret meltblown supply for downstream assemblers. The national standardization administration enforces GB 2626-2019 respiratory protection requirements. Yangtze River Delta industrial zones are absorbing capacity expansion from integrated compounders with captive production lines.
India
Construction and manufacturing corridors in Gujarat, Maharashtra, and Tamil Nadu drive half-mask and powered air-purifying respirator procurement. Bureau of Indian Standards certification requirements are tightening for category III PPE imports. Mundra and Hazira port zones are becoming distribution hubs for industrial safety equipment serving western Indian manufacturing belts.
Japan
Precision manufacturing in Aichi and Osaka prefectures maintains demand for compact half-mask designs with low breathing resistance. METI industrial safety guidelines emphasize quantitative fit testing protocol adoption. Kanto region healthcare networks are evaluating reusable elastomeric platforms as pandemic stockpile alternatives.
Respiratory Protective Equipment Market Vendor Landscape
Capability concentration sits with integrated polymer specialists controlling electret media production; scale advantage sits with diversified safety conglomerates distributing across multiple industrial channels. The market structures around three tiers: captive filtration media producers, full-service respiratory protection program providers, and regional assemblers dependent on merchant supply. Dominant competitive moves include backward integration into meltblown capacity and long-term offtake commitments securing feedstock access.
Among integrated North American safety conglomerates, 3M and MSA Safety Incorporated exemplify divergent strategic positions—one anchoring margin capture through captive electret media production, the other bundling respiratory systems with fixed gas detection for oil and gas verticals. Honeywell International Inc. occupies a position spanning industrial automation and personal protective equipment distribution. German specialist Drägerwerk AG & Co. KGaA represents the premium-tier full-face mask archetype with chemical exposure integration.
| Leading Market Players |
|---|
| 3M |
| Honeywell International Inc. |
| MSA Safety Incorporated |
| Drägerwerk AG & Co. KGaA |
| Alpha Pro Tech |
| Bullard |
| Avon Protection |
| Moldex-Metric |
| Gentex Corporation |
| Others |
Supply Flow & Price Mechanics
Zhejiang and Jiangsu provinces anchor global electret meltblown media capacity, concentrating upstream filtration supply among integrated polymer compounders who capture margin structures that downstream respirator assemblers struggle to reclaim. This geographic concentration of specialized feedstock production translates directly into pricing power asymmetries across North American and European procurement channels.
Pricing Analysis
Geographic price spreads between electret-grade polypropylene resin in Asia and finished N95 respirators in North America exceed threefold multiples when freight and tariff layers accumulate. Three-tier pricing structure across premium, standard, and economy levels separates FDA-cleared surgical N95s from industrial-grade disposables and unbranded commodity masks. Pricing pressure stems from merchant supply dependency as captive producers force long-term offtake commitments. Small construction contractors exhibit highest price sensitivity; oil and gas safety managers show lowest, prioritizing assigned protection factor ratings over unit cost.
Supply Chain Analysis
German and Japanese export-control regimes restrict corona and tribocharging equipment for permanent charge implantation, limiting electret treatment capacity expansion outside integrated compounders. Electret media production concentrates in China, South Korea, and Germany; respirator assembly spreads across Mexico, Malaysia, and the United States. Raw material flows draw from polypropylene resin, activated carbon substrates, and elastomer compounds. Single-source vulnerability in electret machinery creates chokepoint risk. Distribution runs through industrial safety distributors and direct sales to integrated delivery networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Reusable elastomeric platforms threaten disposable N95 incumbents as healthcare systems prioritize stockpile resilience over supply chain fragility. Incumbents must navigate this substitution dynamic while defending established certification positions.
For Market Incumbents: Build captive electret media moats through backward integration into Zhejiang and Jiangsu meltblown capacity or binding offtake agreements with polymer specialists. Defend FDA 510(k) clearance positions against emerging cartridge-based alternatives by accelerating surgical N95 fluid resistance claims. Channel control through direct safety manager relationships offers defensive leverage against distributor disintermediation.
For New Entrants and Emerging Players: Pursue connected fit-monitoring white space where EU AI Act and MDR frameworks have delayed incumbent launches awaiting CE marking precedent. Target India's Gujarat and Maharashtra industrial corridors with powered air-purifying respirator systems specified for foundry environments. Go-to-market through industrial distributor partnerships bypasses entrenched medical supply intermediaries.
For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-capture play because OSHA enforcement and EU PPE Regulation 2016/425 module B+C2 routes concentrate value with certified incumbents. Acquisition targets include electret media specialists with captive meltblown lines and service-attach distributors managing multi-year respiratory protection programs. Watch for BIS certification tightening in India as inflection signal for import substitution opportunities.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Electret Media | Captive meltblown production insulates margin from polypropylene volatility and merchant supply squeezes. |
| CE Marking for Connected Respirators | MDR Article 10 compliance establishes predicate pathway for FDA 510(k) alignment on smart fit-monitoring systems. |
| Direct Safety Manager Relationships | Bypassing medical supply intermediaries captures service-attach revenue and locks in multi-year program contracts. |
| Reusable Elastomeric Platform Development | Cartridge-based half-masks address healthcare stockpile resilience requirements displacing disposable N95 dependency. |
| India Industrial Corridor Expansion | Bureau of Indian Standards certification investments position for construction and manufacturing procurement surges in Gujarat and Maharashtra. |
Methodological Framework
Cross-validation between OSHA enforcement documentation and EU PPE Regulation 2016/425 conformity assessment records anchors the qualitative findings on certification pathway evolution. Primary interviews with respiratory protection program managers, industrial safety distributors, polymer compounder procurement leads, and hospital GPO contracts managers combined with secondary validation from FDA 510(k) filings, BIS certification databases, and customs trade records. Bottom-up respirator shipment data and top-down industrial safety spending estimates triangulate market sizing.
Calibration against historical OSHA citation patterns and EU notified body approval timelines refined the analytical framework across the projection horizon. Segmentation dimensions modeled include product architecture, end-use environment, application contaminant type, and distribution channel complexity. CAGRs derived from weighted average of demand elasticity estimates and supply capacity expansion schedules. Electret media capacity utilization and fit-testing program penetration served as industry-specific forecast inputs.
Macroeconomic conditions sit as an overlay; deviation in petrochemical cycle timing and freight cost indices would shift the trajectory. Forecasts reflect documented assumptions on regulatory enforcement intensity and certification timeline stability. Material shifts in EU AI Act risk classification implementation or BIS import restriction severity would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Safety Equipment and Personal Protective Equipment (PPE)
North America Self-Contained Breathing Apparatus Market
Safety Equipment and Personal Protective Equipment (PPE)
Europe Safety Switches Market
Safety Equipment and Personal Protective Equipment (PPE)
Earmuffs Market
Safety Equipment and Personal Protective Equipment (PPE)
Safety IO Modules Market
Safety Equipment and Personal Protective Equipment (PPE)
Smart Helmet Market
Safety Equipment and Personal Protective Equipment (PPE)
Armoured Thermocouple Market
Safety Equipment and Personal Protective Equipment (PPE)
Passenger Security Equipment Market
Safety Equipment and Personal Protective Equipment (PPE)
Traffic Baton Market
Safety Equipment and Personal Protective Equipment (PPE)
Global Radiation Protection Apron Market
Safety Equipment and Personal Protective Equipment (PPE)
Active Protection System Market
Safety Equipment and Personal Protective Equipment (PPE)
Respirator Fit Tester Market
Safety Equipment and Personal Protective Equipment (PPE)
Global Machine Safeguarding Solution Market
Safety Equipment and Personal Protective Equipment (PPE)
Steel Smart Locker Market
Safety Equipment and Personal Protective Equipment (PPE)
Industrial Fall Protection Equipment Market
Safety Equipment and Personal Protective Equipment (PPE)
APAC Safety Instrumented Systems Market
Safety Equipment and Personal Protective Equipment (PPE)
Africa Riot Control Equipment Market