
 Asia-Pacific Riot Control Equipment Market | 2026-2036
Asia-Pacific Riot Control Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Riot Control Equipment Market Outlook
South Korea is rewriting regional supply dynamics through expanded chemical irritant manufacturing capacity near Daegu. Rheinmetall AG leverages its European engineering base to compete for tender contracts across Southeast Asian defense ministries. Safariland LLC anchors its position through specialized protective gear distribution channels reaching Australian and Japanese law enforcement agencies. PT Pindad dominates domestic Indonesian procurement with in-house production of tear gas and smoke grenades for military applications.
Asia-Pacific riot control equipment encompasses non-lethal systems designed to disperse, deter, or contain civilian crowds during civil unrest, public demonstrations, or security incidents, typically employing chemical agents with defined concentration thresholds, kinetic impact projectiles with calibrated energy limits, or pressurized water streams exceeding 200 psi. These systems serve law enforcement, military, and private security operators requiring graduated force options below lethal engagement thresholds. Protective gear occupies the largest value pool due to mandatory replacement cycles and multi-layer ballistic fabric specifications, while tear gas formulations represent the fastest-growing product category as regional militaries modernize stockpiles with CS-based alternatives. Deployment across urban areas generates the highest service attachment rates, particularly for training and equipment leasing contracts tied to metropolitan police forces.
India's BIS standards and Australia's TGA-equivalent chemical safety frameworks shape product compliance costs and certification timelines for foreign suppliers entering these markets. Japan's METI export control regulations restrict technology transfer for advanced crowd dispersal systems, creating segmented market access conditions across Northeast Asia. Stakeholders must monitor evolving national security procurement policies and local content requirements that increasingly favor domestic manufacturing partnerships over direct equipment imports.
Market Dynamics
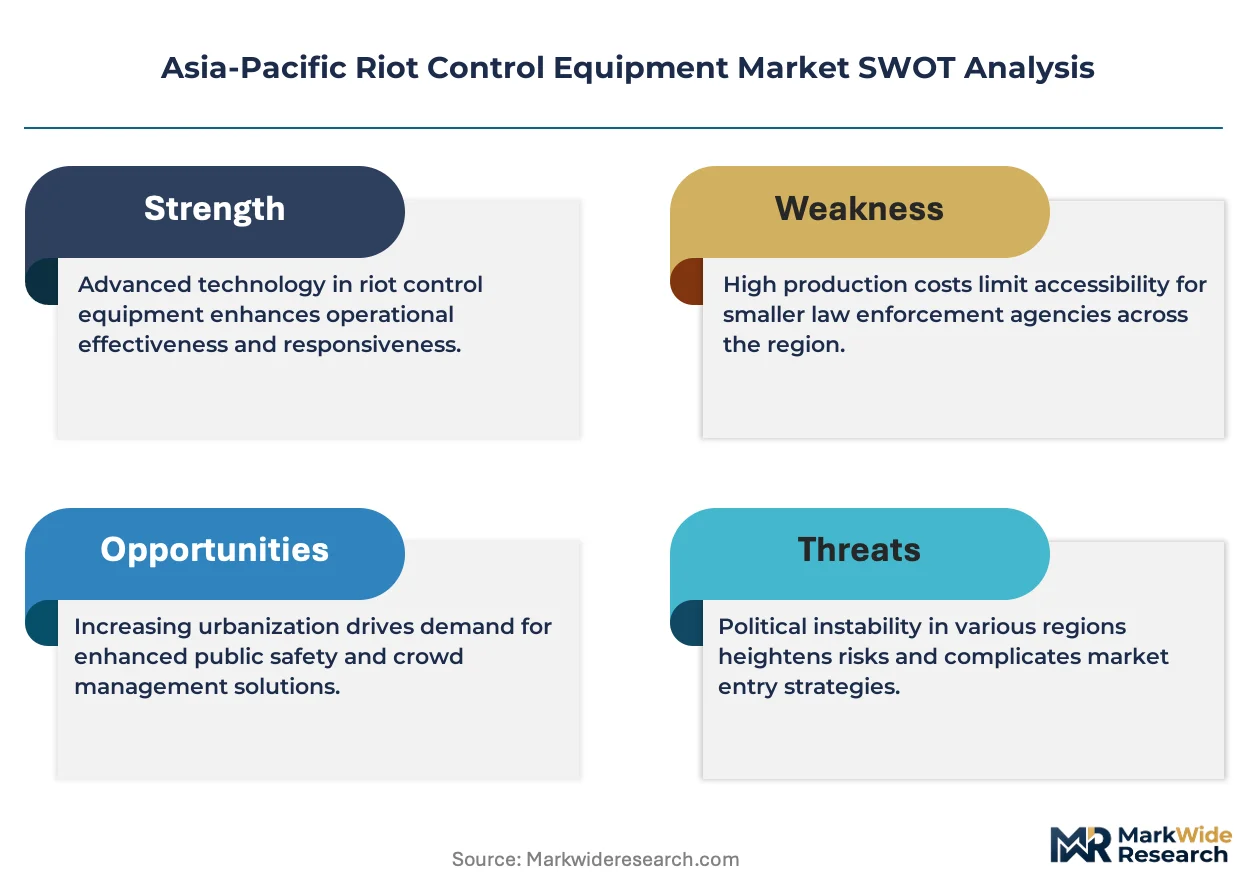
India's BIS certification tightening for protective gear is compressing foreign supplier timelines while accelerating domestic manufacturing partnerships across the Asia-Pacific riot control equipment landscape.
Growth Catalysts
- Urbanization-driven procurement:Metropolitan police forces in Indonesia, Vietnam, and the Philippines are expanding non-lethal crowd control arsenals to manage denser population concentrations.
- CS-based tear gas modernization:Regional militaries are replacing legacy CN formulations with refined CS variants offering improved safety profiles and faster dispersal characteristics.
- Dual-use manufacturing infrastructure:Indonesia's PT Pindad leverages military production lines to supply domestic police agencies, reducing import dependency.
Market Restraints
- Multi-layer ballistic fabric input costs:Aramid and ultra-high-molecular-weight polyethylene prices fluctuate with petrochemical feedstock volatility, squeezing protective gear margins.
- Daegu chemical cluster concentration:South Korea's irritant manufacturing dominance creates single-point vulnerability for regional tear gas supply security.
- METI export control friction:Japan's technology transfer restrictions block advanced crowd dispersal system sales to specific Asia-Pacific defense ministries.
Strategic Opportunities
- Vietnam's underpenetrated police modernization:Provincial law enforcement agencies lack standardized non-lethal equipment, creating first-mover advantage for certified suppliers.
- Training-service bundling:Australian and Japanese metropolitan forces are unbundling equipment purchases from multi-year operator certification contracts.
- India's PLI scheme alignment:Local content incentives for protective gear manufacturing reward joint ventures with domestic textile and chemical processors.
Industry Challenges
- BIS certification timeline compression:Foreign protective gear suppliers face 18-24 month approval cycles that misalign with urgent procurement schedules.
- Legacy smoke grenade inventory integration:Militaries seeking CS-based upgrades must safely dispose of obsolete stockpiles before new system deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Riot Control Equipment Market |
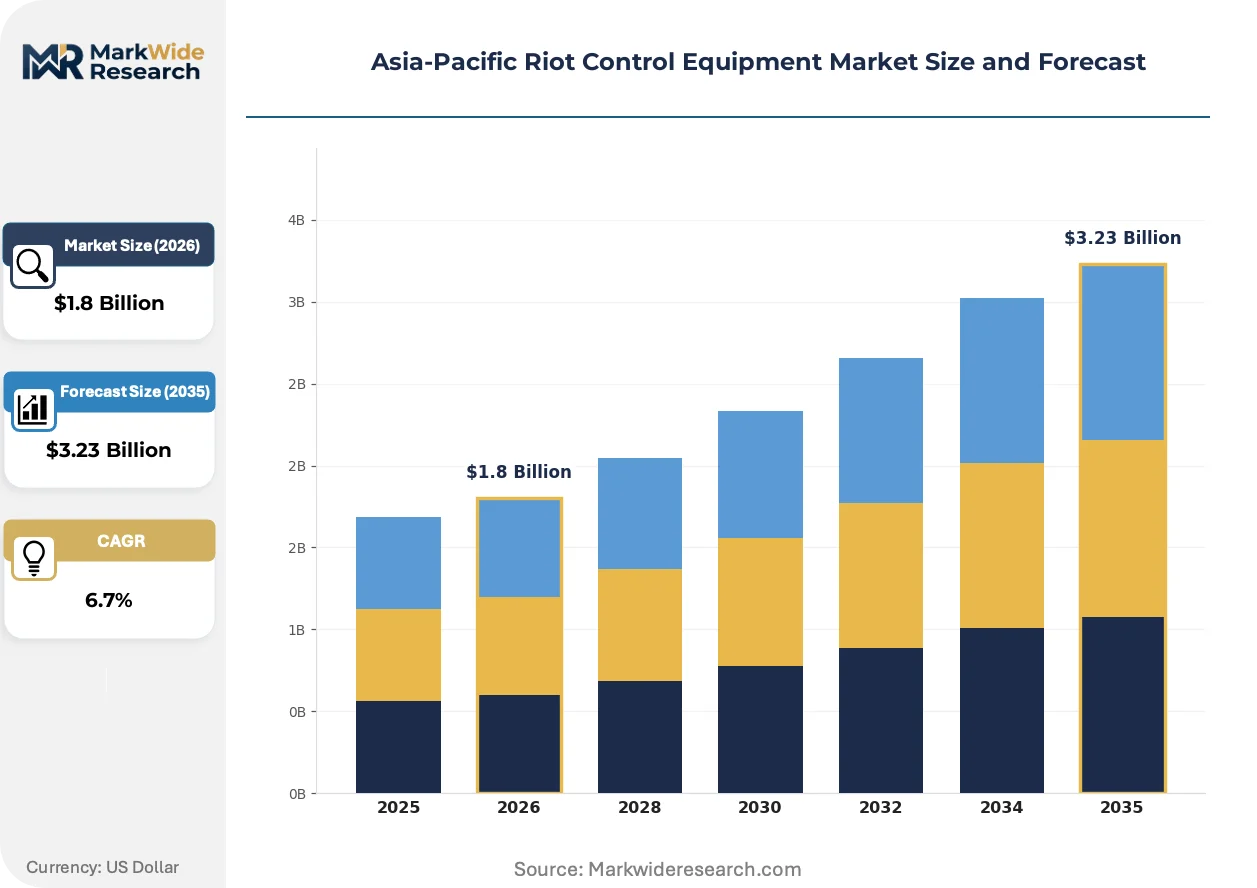
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Protective Gear, Smoke Grenades, Water Cannons, Tear Gas End User: Law Enforcement, Military, Private Security, Government Agencies Deployment: Urban Areas, Rural Areas, Event Venues, Transportation Hubs Service Type: Maintenance, Training, Consultation, Equipment Leasing |
| Companies Covered | Rheinmetall AG, Safariland LLC, Combined Systems Inc, Axon Enterprise Inc, NonLethal Technologies Inc, Genasys Inc, PT Pindad, Dae Kwang Chemical Corporation, Security Devices International Inc, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Riot Control Equipment Market Strategic Shifts
Electrified dispersion systems and smart-targeting payloads are redefining force-calibration standards across Asia-Pacific security agencies, while regulatory fragmentation accelerates product specialization.
Directed-energy acoustic deterrents operating at precise frequency ranges are entering field trials with South Korean and Australian riot police units. These systems deliver localized discomfort without residual chemical contamination. Metropolitan forces in Seoul and Sydney are piloting deployments ahead of mass procurement decisions. Thermal and kinetic dispersion methods are rendering obsolete for enclosed-space operations where ventilation constraints limit traditional agent effectiveness.
Australia's TGA-equivalent chemical safety frameworks are tightening concentration thresholds for imported irritant formulations. Foreign suppliers must reformulate products or establish local blending facilities to maintain market access. Japanese and Australian law enforcement agencies are prioritizing domestically certified alternatives, reshaping procurement qualification criteria.
Leasing arrangements for protective gear and dispersal systems are displacing outright purchase models among budget-constrained provincial police forces. Equipment providers retain ownership responsibility for maintenance, replacement, and certification compliance. Indonesian and Philippine municipal agencies are adopting this structure most aggressively to circumvent capital appropriation delays.
Asia-Pacific Riot Control Equipment Market Segmentation
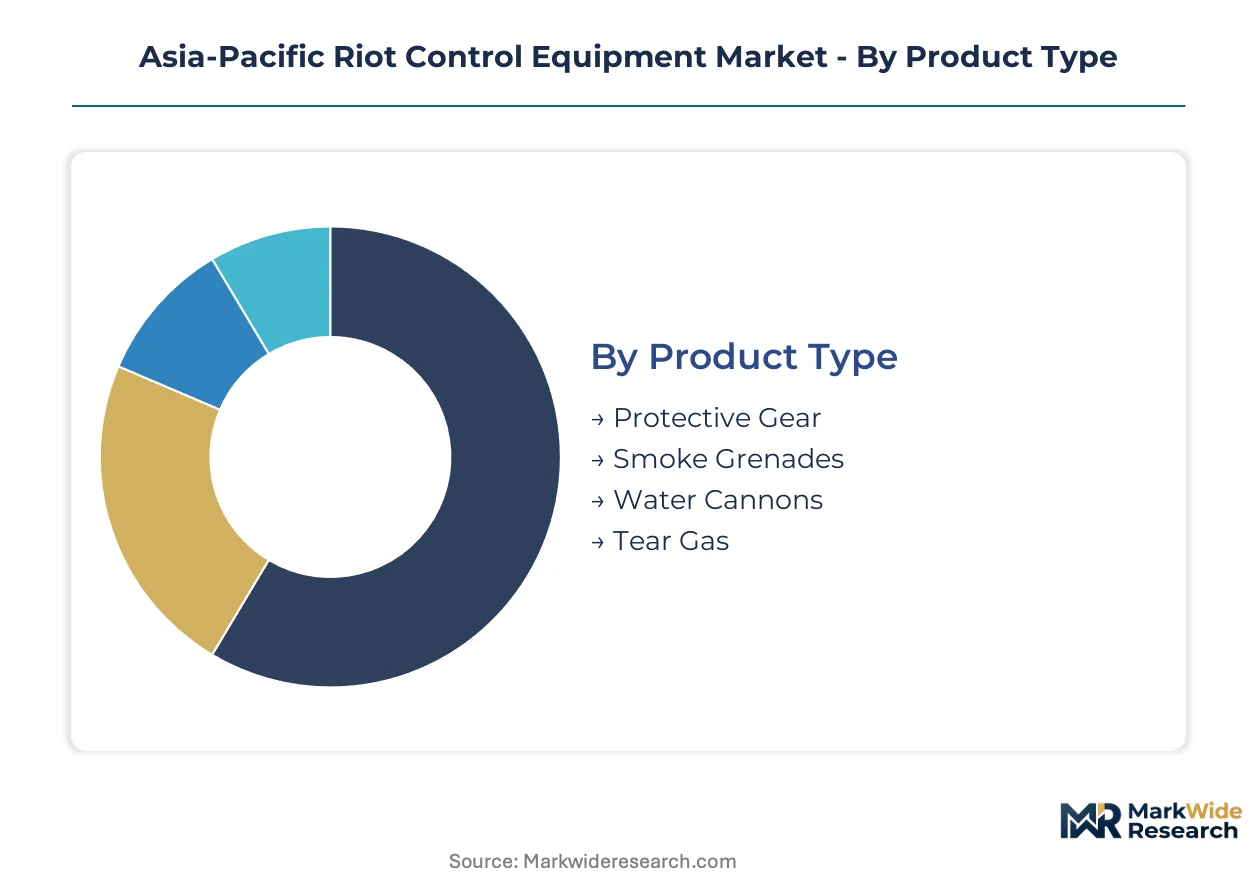
Segmentation across the Asia-Pacific riot control equipment market reveals divergent service intensity patterns, with protective gear demanding continuous recertification support while chemical agents require specialized disposal logistics. Procurement officers weigh replacement cycles against operator training burdens when allocating budgets across product categories.
Product Type:
After-sales service intensity varies sharply across equipment categories, with multi-layer ballistic fabrics requiring scheduled fiber integrity testing and chemical formulations needing stability monitoring under tropical storage conditions.
- Protective Gear:Multi-layer aramid and ultra-high-molecular-weight polyethylene assemblies with defined ballistic resistance ratings. Metropolitan police forces in Jakarta, Sydney, and Tokyo drive procurement through mandatory replacement cycles tied to fabric degradation protocols.
- Tear Gas:CS-based irritant formulations with calibrated concentration thresholds and dispersal velocity specifications. Regional militaries in Indonesia and South Korea are modernizing stockpiles to replace legacy CN variants, creating sustained order flow for refined chemical production.
- Smoke Grenades:Pyrotechnic obscurant devices with controlled burn rates and visibility reduction coefficients.
- Water Cannons:Pressurized dispersion systems exceeding 200 psi with adjustable stream patterns for graduated force application.
Protective gear holds the largest share; momentum sits with tear gas as militaries accelerate CS-based modernization programs.
End User:
Cost tier differentiation separates capital-rich military procurement from budget-constrained municipal police forces, with private security operators occupying a mid-tier equipment specification band.
- Law Enforcement:Metropolitan and provincial police agencies requiring graduated force options for crowd management. Australian and Japanese forces are unbundling equipment purchases from multi-year operator certification contracts, elevating training-service attachment rates.
- Military:Defense ministries with dedicated riot control units and civil disturbance response mandates. Indonesia's PT Pindad serves this segment through domestic production lines that reduce import dependency for tear gas and smoke grenades.
- Private Security:Corporate and facility protection operators with limited authorization for chemical agent deployment.
- Government Agencies:Border control, prison administration, and critical infrastructure protection units with specialized equipment requirements.
Law enforcement commands the dominant procurement volume; military segments are expanding most quickly as defense ministries formalize dedicated crowd control capabilities.
Deployment:
Application context dictates equipment specification, with enclosed-space operations in transportation hubs demanding non-residual dispersion methods while open urban environments accommodate broader chemical agent use.
- Urban Areas:Dense population centers with ventilation-constrained infrastructure and elevated collateral damage risks. Seoul and Sydney metropolitan forces are piloting directed-energy acoustic deterrents to address enclosed-space limitations of traditional thermal and kinetic methods.
- Event Venues:Temporary gathering spaces requiring rapid deployment and removal of crowd control infrastructure. Leasing arrangements for protective gear and dispersal systems are displacing outright purchase models among budget-constrained provincial agencies in Indonesia and the Philippines.
- Rural Areas:Dispersed populations with extended logistics chains and reduced immediate backup availability.
- Transportation Hubs:Airports, rail terminals, and ports with strict chemical contamination protocols and high-visibility security requirements.
Urban deployment generates the highest service attachment rates; event venues are gaining share fastest through equipment leasing adoption.
Service Type:
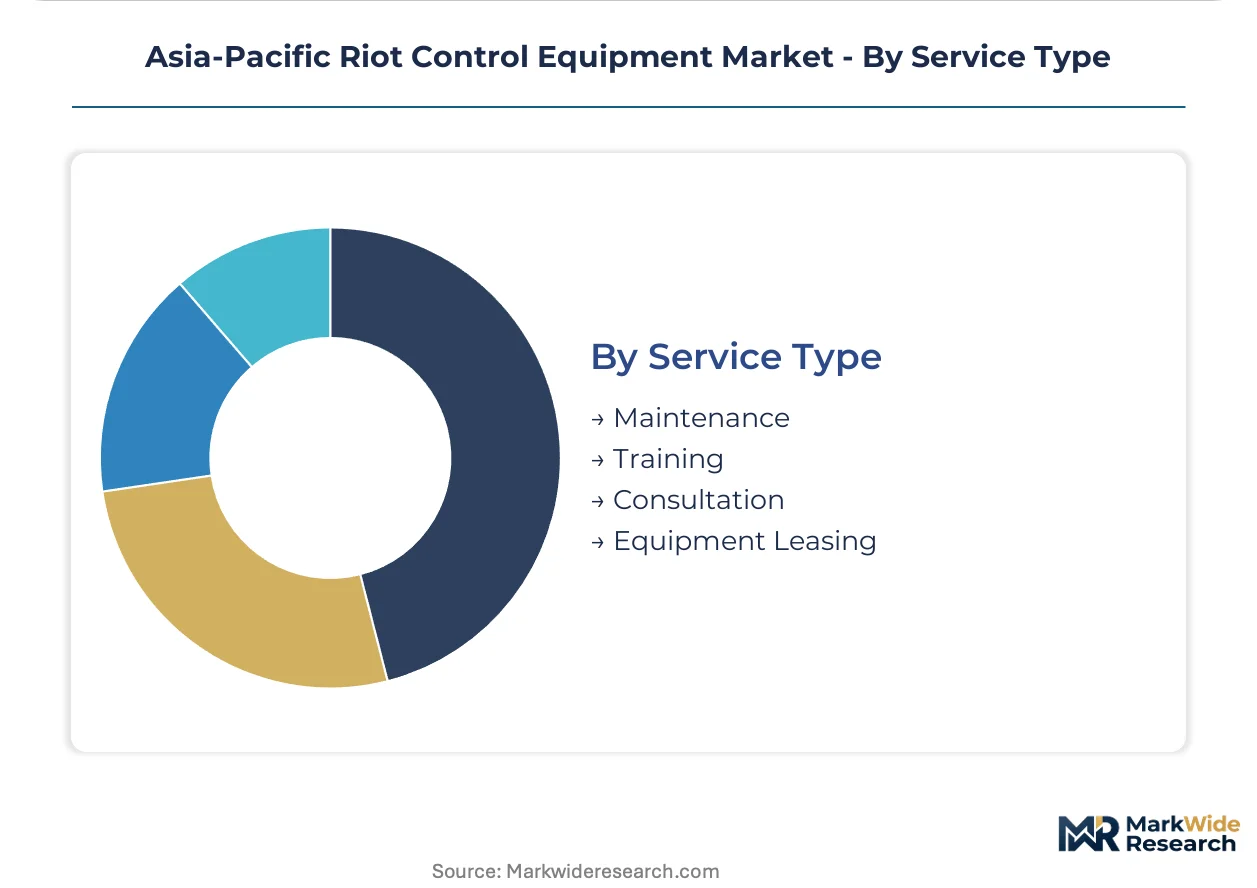
Customer type stratification separates integrated full-service providers from equipment-only vendors, with provincial agencies prioritizing bundled maintenance and training to circumvent technical certification burdens.
- Training:Operator certification programs covering chemical agent handling, protective gear donning protocols, and escalation decision frameworks. Australian and Japanese metropolitan forces are expanding multi-year training contracts independent of equipment procurement.
- Equipment Leasing:Ownership-retention models where providers assume maintenance, replacement, and certification compliance responsibilities. Indonesian and Philippine municipal agencies are adopting this structure aggressively to bypass capital appropriation delays.
- Maintenance:Scheduled inspection, repair, and recertification services for protective gear and dispersion systems.
- Consultation:Threat assessment, deployment strategy, and regulatory compliance advisory for procurement planning.
Training services capture the largest revenue pool; equipment leasing is climbing the fastest as municipal budget constraints reshape procurement structures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Indonesia's military-police dual-use procurement diverges sharply from Australia's unbundled service contracting, creating distinct consumption archetypes across the region. South Korea's chemical cluster concentration supplies tear gas stockpiles to multiple defense ministries. India's BIS certification timeline compression is accelerating domestic manufacturing partnerships.
Indonesia
Domestic production capabilities at PT Pindad serve both military and police end users, reducing import dependency for tear gas and smoke grenades. The Ministry of Defense prioritizes local content requirements in tender specifications. Bandung's defense manufacturing corridor anchors production of pyrotechnic obscurant devices for regional distribution.
South Korea
Metropolitan police forces in Seoul pilot directed-energy acoustic deterrents for enclosed-space operations where chemical agents face ventilation constraints. MFDS chemical safety frameworks regulate irritant concentration thresholds for domestic use. Daegu's chemical manufacturing cluster supplies CS-based formulations to defense ministries across Northeast Asia.
India
Provincial law enforcement agencies lack standardized non-lethal equipment, creating procurement gaps for certified suppliers. BIS certification requirements for protective gear compress foreign supplier timelines to 18-24 months. Tamil Nadu and Maharashtra textile corridors are absorbing PLI scheme incentives for domestic ballistic fabric production.
Australia
Metropolitan forces in Sydney unbundle equipment purchases from multi-year operator certification contracts, elevating training-service attachment rates. TGA-equivalent chemical safety frameworks tighten concentration thresholds for imported irritant formulations. Victoria and New South Wales police agencies drive protective gear procurement through mandatory replacement cycles.
Japan
Defense ministries face METI export control restrictions blocking advanced crowd dispersal system acquisitions from specific regional partners. JIS standards govern protective gear specifications for domestic law enforcement. Tokyo metropolitan police anchor demand for domestically certified alternatives, reshaping procurement qualification criteria.
Asia-Pacific Riot Control Equipment Market Competitive Environment
Capability concentration sits with domestic defense manufacturers; scale advantage sits with multinational industrial conglomerates. The market structures around three tiers: state-linked producers with captive local demand, European engineering specialists competing for tender contracts, and North American protective gear distributors with established certification pathways. Strategic moves center on joint ventures to satisfy local content requirements and leasing models to bypass municipal capital constraints.
Among Asia-Pacific-based producers, PT Pindad exemplifies the state-integrated archetype with in-house chemical production serving domestic security agencies. Rheinmetall AG occupies a position as the European engineering specialist leveraging tender access across Southeast Asian defense ministries. Safariland LLC represents the North American protective gear tier, anchoring distribution channels reaching Australian and Japanese law enforcement certification frameworks.
| Leading Market Players |
|---|
| Rheinmetall AG |
| Safariland LLC |
| Combined Systems Inc |
| Axon Enterprise Inc |
| NonLethal Technologies Inc |
| Genasys Inc |
| PT Pindad |
| Dae Kwang Chemical Corporation |
| Security Devices International Inc |
| Others |
Value Chain & Pricing Dynamics
Freight corridors connecting Busan to Jakarta determine landed cost spreads for CS-based irritant formulations, compressing margins for suppliers lacking regional blending facilities while amplifying price differentiation between certified and uncertified protective gear tiers.
Pricing Analysis
Geographic price spreads of 15-25% separate Australian metropolitan procurement from Indonesian provincial tenders, reflecting certification burden differentials under TGA-equivalent versus domestic frameworks. Three-tier pricing structure across premium, standard, and economy levels stratifies by BIS certification status and after-sales service bundling. Cost compression in economy-tier protective gear intensifies as Tamil Nadu textile corridors absorb PLI scheme incentives, eroding import-dependent supplier margins. Provincial police forces in the Philippines exhibit highest price sensitivity; Japanese defense ministries show least, prioritizing METI-compliant domestic alternatives regardless of premium.
Supply Chain Analysis
Japan's METI export control restrictions on advanced crowd dispersal technologies fragment regional equipment flows, forcing defense ministries toward alternative sourcing channels. Manufacturing concentrates in South Korea for chemical irritants, Indonesia for pyrotechnic devices, and India for ballistic fabrics under BIS standards. Raw material dependencies center on Chinese aramid fiber feedstocks, Saudi petrochemical precursors for CS synthesis, and Australian ultra-high-molecular-weight polyethylene. Single-source vulnerability runs through Daegu's chemical cluster concentration for regional tear gas supply security. Distribution runs through state-linked defense contractors in Indonesia, specialized law enforcement distributors in Australia and Japan, and direct tender participation by European engineering specialists elsewhere.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among Australian and Japanese metropolitan forces unbundling equipment from multi-year service contracts, while Indonesian provincial agencies fragment procurement through leasing adoption.
For Market Incumbents: Pre-empt margin erosion in protective gear by securing backward integration into Tamil Nadu and Maharashtra textile corridors before PLI scheme incentives attract new domestic competitors. Anchor channel control through exclusive operator certification contracts with Australian and Japanese metropolitan police, raising switching costs for rivals lacking established training infrastructure. For New Entrants and Emerging Players: Pursue Vietnam's underpenetrated provincial law enforcement agencies lacking standardized non-lethal equipment, where first-mover certification advantage outweighs established brand recognition. Target equipment leasing structures for Indonesian and Philippine municipal forces circumventing capital appropriation delays, paired with bundled maintenance offerings that incumbent distributors underserve. For Investors and Strategic Acquirers: Carve-out targets emerge from European industrial conglomerates divesting non-core riot control divisions amid defense portfolio rebalancing. Long-term viability hinges on regulatory certification moats rather than manufacturing scale alone. Watch for BIS timeline compression triggering distressed asset availability among foreign protective gear suppliers facing 18-24 month approval cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Joint Venture with Domestic Textile Producer | PLI scheme alignment in India accelerates BIS certification pathways for foreign suppliers. |
| Regional Blending Facility Establishment | TGA-equivalent compliance in Australia tightens concentration thresholds for imported irritant formulations. |
| Multi-Year Training Contract Unbundling | Metropolitan forces in Sydney and Tokyo separate equipment procurement from operator certification services. |
| Leasing Model Deployment | Budget-constrained provincial agencies in Indonesia bypass capital appropriation delays through ownership-retention structures. |
| Directed-Energy Acoustic System Field Trials | Seoul metropolitan police pilot non-chemical alternatives for enclosed-space operations ahead of mass procurement. |
Study Parameters
Cross-validation between procurement officer interviews at Indonesian and Vietnamese defense ministries and secondary customs data anchors the qualitative findings on import dependency patterns. Primary fieldwork engaged riot control equipment procurement leads, BIS certification consultants, chemical manufacturing plant managers, and law enforcement training directors. Secondary sources encompassed MFDS chemical safety filings, Australian TGA-equivalent regulatory updates, Indian PLI scheme disbursement records, and SEC disclosures from listed defense contractors. Bottom-up segment sizing triangulated against top-down defense budget allocation analysis.
Calibration against historical procurement cycles and announced modernization programs shaped the analytical framework across the analysis window. Segmentation modeling incorporated product type, end user tier, deployment context, and service attachment intensity. CAGRs derived from weighted average of announced tender volumes, replacement cycle assumptions, and regulatory-driven compliance cost escalations. Forecast inputs included BIS certification timeline compression effects and CS-based tear gas modernization program announcements.
Macroeconomic conditions sit as an overlay; deviation in petrochemical feedstock volatility or regional defense budget prioritization would shift the trajectory. Forecasts reflect assumptions on regulatory stability and continued local content incentive schemes. Material shifts in METI export control scope or BIS protective gear standard revisions would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Safety Equipment and Personal Protective Equipment (PPE)
Fall Protection Equipment Market
Safety Equipment and Personal Protective Equipment (PPE)
Process Safety System Market
Safety Equipment and Personal Protective Equipment (PPE)
Respiratory Protective Equipment Market
Safety Equipment and Personal Protective Equipment (PPE)
Europe N95 Mask Market
Safety Equipment and Personal Protective Equipment (PPE)
Global Safes and Vaults Market
Safety Equipment and Personal Protective Equipment (PPE)
Edge Protector Market
Safety Equipment and Personal Protective Equipment (PPE)
Supplementary Protectors Market
Safety Equipment and Personal Protective Equipment (PPE)
Electrical Safety Products Market
Safety Equipment and Personal Protective Equipment (PPE)
Steel Smart Locker Market
Safety Equipment and Personal Protective Equipment (PPE)
Europe Safes and Vaults Market
Safety Equipment and Personal Protective Equipment (PPE)
Hearing Protection Products Market
Safety Equipment and Personal Protective Equipment (PPE)
Household Smart Safe Market
Safety Equipment and Personal Protective Equipment (PPE)
Bulletproof Gear Market
Safety Equipment and Personal Protective Equipment (PPE)
Wearable Airbag Belt Market
Safety Equipment and Personal Protective Equipment (PPE)
Global Anti-Vibration Gloves Market
Safety Equipment and Personal Protective Equipment (PPE)
Global Surgical Mask and Respirators Market