
 Drone Safety Solutions Market | 2026-2036
Drone Safety Solutions Market Size, Share, and Industry Trends Forecast 2026-2036
Drone Safety Solutions Market Insights
Modular platform bundling is consolidating buyer choice around integrated detection-jamming-kill chains rather than point solutions. Thales Group leverages its radar heritage to anchor European defense contracts. Dedrone Holdings, Inc. specializes in sensor fusion architectures for urban airspace monitoring. Lockheed Martin Corporation dominates government-grade counter-UAS programs through its advanced directed-energy partnerships.
Drone safety solutions encompass hardware and software systems designed to prevent unauthorized drone incursions, ensure compliant flight operations, and protect critical airspace, typically integrating multi-spectral sensors with real-time kinematic positioning achieving centimeter-level accuracy. These systems serve military, commercial, and civilian infrastructure operators requiring assured airspace sovereignty. Collision avoidance systems lead product type demand as autonomous flight density rises in urban corridors. Computer vision segments within technology are expanding fastest due to falling GPU costs and edge-AI deployment. Law enforcement agencies represent the deepest margin pool among end users given classified procurement budgets and long-term service contracts.
The FAA's Remote ID rule and EASA's drone regulation framework mandate broadcast capabilities that reshape product design requirements across manufacturers. China's CAAC and NMPA coordinate GB standards for civilian drone certification, creating parallel compliance tracks for exporters. Stakeholders must monitor divergence between sovereign encryption requirements and international interoperability standards as procurement specifications fragment across defense ministries.
Market Dynamics
Modular counter-drone architectures are consolidating procurement decisions around integrated detection-jamming-kill chains, pressuring point-solution vendors to bundle or exit. Defense ministries now mandate interoperable platforms that federate radar, RF, and optical sensors through common command interfaces.
Growth Catalysts
- FAA Remote ID Mandate:Broadcast requirements for all drones above 250 grams force hardware retrofits and software upgrades across commercial fleets in the United States.
- Urban Air Mobility Corridors:Autonomous cargo and passenger drone routes in Germany and China create persistent demand for collision avoidance and geofencing infrastructure.
- Directed-Energy Maturation:Solid-state laser and high-power microwave systems are achieving tactically relevant power-to-weight ratios for mobile counter-UAS deployment.
Market Restraints
- Gallium Nitride Supply Concentration:RF power amplifier substrates face single-source dependency from Chinese foundries, creating vulnerability for jamming system manufacturers.
- Sovereign Encryption Divergence:Defense ministries in the United States, France, and China impose incompatible classified waveform standards, fragmenting R&D and blocking economies of scale.
- Spectrum Licensing Friction:Counter-drone jamming operations require coordinated frequency clearances that national telecom regulators delay or deny for civilian airspace.
Strategic Opportunities
- India Civil Aviation Market:DGCA drone rules and PLI scheme incentives create a compliance-driven hardware replacement cycle for imported Chinese systems.
- AI-Edge Sensor Fusion:Converging computer vision with onboard radar processing enables standalone detection nodes without centralized server dependency.
- Critical Infrastructure as-a-Service:Power utilities and petrochemical operators in Germany are contracting managed airspace protection rather than capital purchases.
Industry Challenges
- RF Engineer Scarcity:Phased-array radar and adaptive jamming algorithm development requires specialized talent concentrated in defense contracting hubs.
- Type Certification Timelines:EASA's Specific Category operational authorization process extends 18-24 months for new counter-drone platforms, freezing product launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Drone Safety Solutions Market |
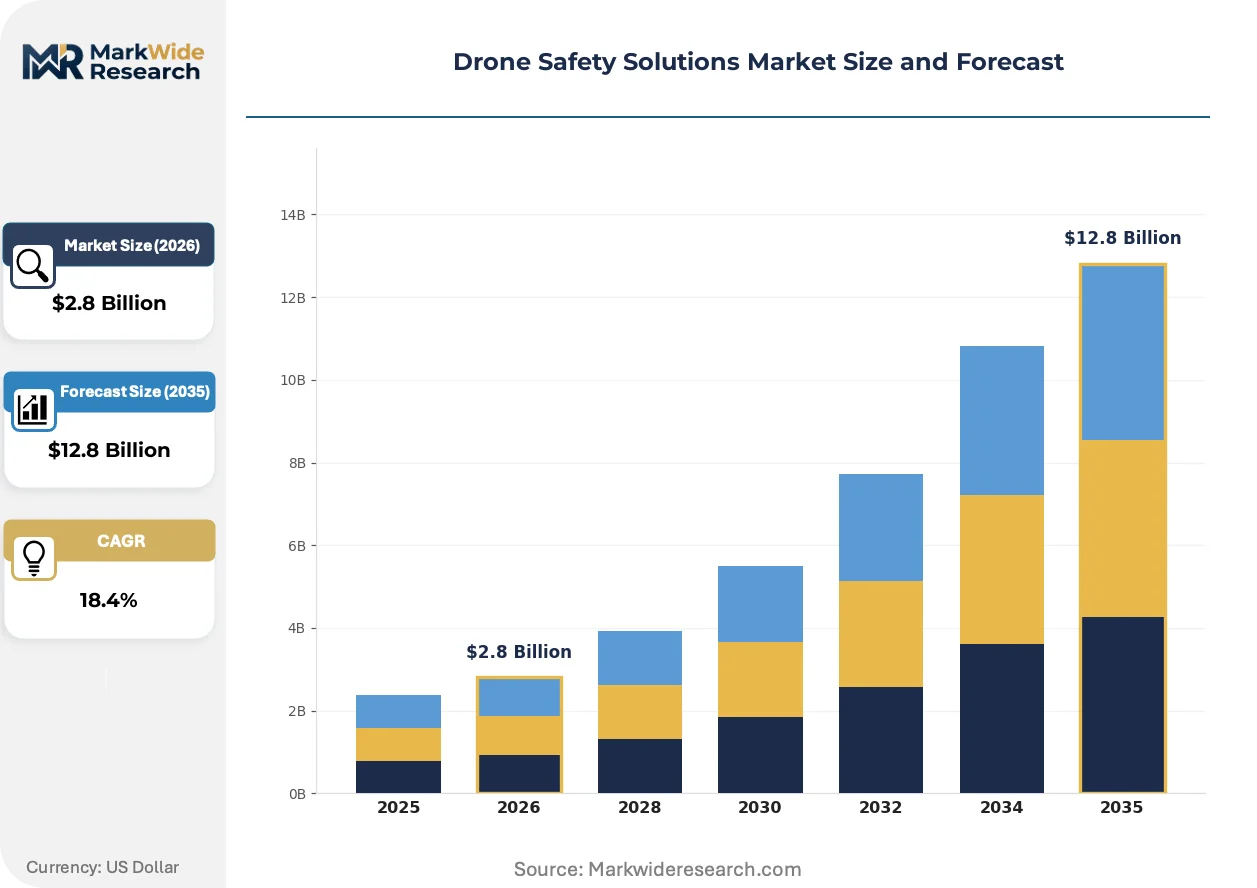
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $12.8 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Collision Avoidance Systems, Geo-Fencing Solutions, Emergency Recovery Systems, Flight Control Software, Anti-Collision Lights Technology: Radar, LiDAR, Ultrasonic Sensors, Computer Vision, GPS Tracking Application: Aerial Surveillance, Precision Agriculture, Infrastructure Inspection, Emergency Response, Media & Entertainment End User: Drone Manufacturers, Law Enforcement Agencies, Environmental Monitoring Organizations, Delivery Service Providers, Research Institutions |
| Companies Covered | DroneShield Ltd, QinetiQ Group PLC, Thales Group, Lockheed Martin Corporation, Dedrone Holdings, Inc., Rohde & Schwarz, D-Fend Solutions AD Ltd., CERBAIR, Anduril Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Drone Safety Solutions Market Trends and Innovations
Edge computing architectures are redistributing processing load from centralized servers to distributed sensor nodes, collapsing latency for real-time threat response. This shift alters competitive advantage toward semiconductor and embedded software capabilities.
Software-defined radio is decentralizing jamming system architecture by replacing hardware-tuned analog chains with reprogrammable digital waveforms. Military procurement offices in the United States and Germany are mandating SDR modularity for future counter-UAS awards. The technology compresses upgrade cycles from years to firmware releases, disadvantaging hardware-centric legacy suppliers.
EASA's drone regulation framework is mandating broadcast Remote ID and network Remote ID capabilities simultaneously, forcing dual-mode radio designs. Manufacturers serving European markets must engineer redundant communication stacks. The compliance burden falls heaviest on commercial drone OEMs below 25 kilograms maximum takeoff weight, where unit economics resist added bill-of-materials cost.
Law enforcement agencies are unbundling detection and interdiction procurement, awarding separate contracts for sensor networks and kinetic or electronic defeat systems. This pattern fragments vendor relationships that previously favored integrated platform providers. The shift is most visible in United States municipal and state police departments with independent purchasing authority outside federal defense procurement channels.
Drone Safety Solutions Market Segmentation
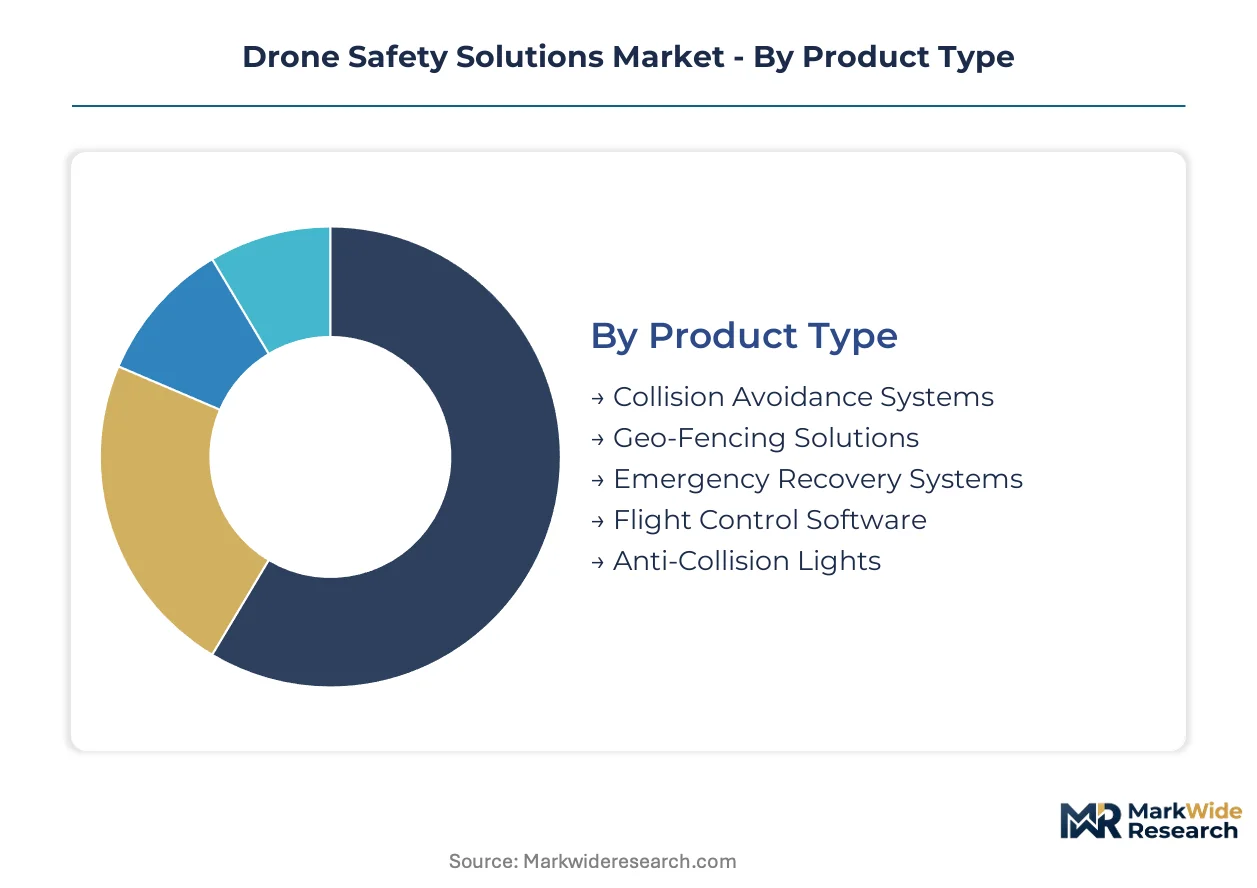
Drone safety solutions fragment across four critical dimensions that determine procurement priorities and technology roadmaps. Buyers evaluate trade-offs between detection range, computational load, and regulatory compliance when selecting system architectures. Each segmentation layer reveals distinct margin structures and competitive dynamics.
Product Type:
Procurement budgets concentrate on systems that reduce liability exposure in dense urban airspace.
- Collision Avoidance Systems:Multi-sensor fusion platforms integrating radar, optical, and ultrasonic inputs achieve centimeter-level positioning accuracy for autonomous navigation. Demand clusters in Germany's urban air mobility corridors where EASA mandates active sense-and-avoid capability for beyond-visual-line-of-sight operations.
- Geo-Fencing Solutions:Software-defined perimeter enforcement using GPS and GLONASS augmentation prevents drone entry into restricted zones. China's CAAC mandates dynamic geofencing updates for all commercial operators, creating persistent retrofit demand for legacy fleets.
- Emergency Recovery Systems:Parachute deployment and controlled autorotation mechanisms protect payloads during propulsion failure.
- Flight Control Software:Autopilot firmware with real-time kinematic correction stabilizes flight in GPS-denied environments.
- Anti-Collision Lights:Strobe and navigation lighting packages ensure visual conspicuity per FAA night-waiver requirements.
Collision avoidance systems lead on scale; geo-fencing solutions lead on momentum.
Technology:
Component selection hinges on power-to-weight constraints and all-weather operational requirements.
- Computer Vision:Edge-deployed neural networks process optical feeds for object classification without centralized server dependency. Falling GPU costs and tensor-optimized silicon from NVIDIA and Qualcomm accelerate adoption in law enforcement drone fleets across the United States.
- Radar:Solid-state phased arrays penetrate fog, dust, and precipitation for reliable detection in adverse conditions. Military procurement offices in the United States prioritize radar for mobile counter-UAS platforms where optical systems degrade.
- LiDAR:Pulsed laser ranging generates high-resolution point clouds for precision mapping and obstacle detection.
- Ultrasonic Sensors:Short-range proximity detection supplements primary sensors during landing and low-altitude maneuvering.
- GPS Tracking:Multi-constellation receivers with RTK correction enable geofencing enforcement and flight path logging.
Radar dominates defense procurement; computer vision climbs the fastest in commercial deployment.
Application:
Use-case intensity determines sensor payload requirements and certification burden.
- Aerial Surveillance:Persistent observation missions demand redundant navigation and encrypted datalinks for border security and critical infrastructure protection. United States Customs and Border Protection operates the largest fleet, driving hardened system specifications.
- Precision Agriculture:Crop monitoring and variable-rate application require sub-meter GPS accuracy and spray-avoidance algorithms. Brazil's agricultural operators deploy collision avoidance to prevent manned aircraft encounters over vast soy and sugarcane estates.
- Infrastructure Inspection:Power line and pipeline surveys utilize proximity sensors for close-quarters flight near conductive structures.
- Emergency Response:Search-and-rescue and firefighting missions prioritize all-weather detection for safe operation in smoke and darkness.
- Media & Entertainment:Cinematography drones balance payload capacity with obstacle avoidance for dynamic tracking shots.
Aerial surveillance commands premium pricing; precision agriculture shows steepest expansion trajectory.
End User:
Customer type dictates contract structure, with classified budgets enabling longest development cycles.
- Law Enforcement Agencies:Municipal and federal police procure sense-and-avoid systems for pursuit and crowd monitoring operations. United States Department of Justice grants fund dedicated airspace protection units in major metropolitan departments.
- Drone Manufacturers:Original equipment integrators embed safety systems at factory level to achieve type certification. DJI and Autel Robotics compete on bundled safety feature sets for consumer and prosumer tiers.
- Environmental Monitoring Organizations:Conservation groups deploy geofencing to prevent disturbance of protected wildlife corridors.
- Delivery Service Providers:Logistics operators test emergency recovery for over-populated delivery routes.
- Research Institutions:Universities validate experimental algorithms in controlled airspace before commercial transfer.
Law enforcement agencies lead on margin capture; drone manufacturers lead on unit volume.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Counter-drone technology originated in Israeli and United States defense laboratories during asymmetric warfare campaigns in the early 2010s, then diffused to European and Asian markets as civilian airspace conflicts multiplied. Regulatory mandates now drive procurement velocity across distinct national frameworks.
United States
Defense procurement dominates volume, with Customs and Border Protection operating extensive aerial surveillance corridors along southern frontiers. FAA Remote ID mandates compel hardware retrofits across commercial fleets above 250 grams. Austin and Boston anchor competing development clusters for RF sensing and directed-energy subsystems.
Germany
EASA's Specific Category operational authorization process shapes product certification timelines extending 18-24 months for new platforms. Urban air mobility corridors in Hamburg and Munich generate persistent demand for collision avoidance infrastructure. The country's automotive electronics heritage supplies embedded computing talent to drone safety integrators.
China
CAAC and NMPA coordinate GB standards for civilian drone certification, creating parallel compliance tracks for domestic and export markets. Shenzhen's electronics manufacturing ecosystem produces cost-optimized sensor modules at scale. Military-civil fusion policies accelerate technology transfer from defense laboratories to commercial suppliers.
Israel
Asymmetric threat experience drove early counter-UAS innovation for border security and critical infrastructure protection. The national regulator maintains classified waveform standards that diverge from NATO interoperability frameworks. Tel Aviv's defense technology cluster specializes in software-defined radio architectures for adaptive jamming.
India
DGCA drone rules and PLI scheme incentives trigger compliance-driven hardware replacement cycles for imported Chinese systems. Bangalore's aerospace engineering base supports indigenous radar development programs. Power utilities in Maharashtra contract managed airspace protection services rather than capital purchases.
Drone Safety Solutions Market Competitive Landscape
The competitive structure tilts toward integrated platform providers over point-solution vendors as defense ministries mandate federated sensor architectures. Procurement consolidation favors vendors offering detection-jamming-kill chains through common command interfaces. Three archetypes dominate: radar heritage defense contractors, sensor fusion specialists, and software-defined radio innovators. Strategic moves concentrate on technology licensing partnerships and vertical integration into semiconductor supply chains.
Among defense heritage contractors, Thales Group and Lockheed Martin Corporation occupy positions as anchor providers for government-grade programs. Dedrone Holdings, Inc. exemplifies the sensor fusion specialist archetype targeting urban airspace monitoring. These three represent distinct competitive vectors—European radar integration, United States directed-energy partnerships, and commercial sensor network deployment.
| Leading Market Players |
|---|
| DroneShield Ltd |
| QinetiQ Group PLC |
| Thales Group |
| Lockheed Martin Corporation |
| Dedrone Holdings, Inc. |
| Rohde & Schwarz |
| D-Fend Solutions AD Ltd. |
| CERBAIR |
| Anduril Industries |
| Others |
Pricing and Supply Chain Analysis
FAA Remote ID retrofit mandates across commercial fleets above 250 grams force hardware redesigns that compress margins for legacy sensor manufacturers and shift procurement toward firmware-upgradeable platforms. This specification pressure concentrates pricing power with semiconductor-integrated vendors capable of absorbing compliance costs while point-solution suppliers face contract losses.
Pricing Analysis
Three-tier pricing structure across defense-grade, commercial-certified, and consumer tiers dominates procurement contracts, with certification level and after-sales service bundling as primary differentiation drivers. Cost compression in the commercial tier intensifies because DJI and Autel Robotics bundle safety features at factory level, eroding standalone system margins. Law enforcement agencies show lowest price sensitivity given classified procurement budgets, while municipal police departments exhibit highest sensitivity due to grant-dependent funding cycles.
Supply Chain Analysis
Single-source vulnerability sits with Chinese foundries for gallium nitride RF power amplifier substrates, creating chokepoint exposure for jamming system manufacturers. Component sourcing draws from Taiwan for phased-array radar silicon, Germany for precision optical sensors, and South Korea for solid-state laser diodes. Tariff exposure runs through Sino-American trade restrictions on dual-use technologies. Distribution runs through defense contracting primes for government segments and direct OEM integration for commercial drone manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Drone safety solutions function as a stable compounder anchored by persistent regulatory mandate velocity across FAA, EASA, and CAAC jurisdictions that perpetuates hardware replacement cycles.
For Market Incumbents: To counter software-defined radio modularization threatening hardware-tuned legacy architectures, Thales Group and Lockheed Martin should deepen backward integration into GaN substrate supply and accelerate firmware-release cadences that compress competitor upgrade windows. Certification investment in EASA's Specific Category operational authorization creates moats against point-solution vendors lacking regulatory affairs scale. For New Entrants and Emerging Players: Municipal power utilities in Germany and Maharashtra seeking managed airspace protection services represent underserved buyer archetypes with procurement autonomy outside federal defense channels. White-space concentration sits with AI-edge sensor fusion for standalone detection nodes eliminating server dependency. Channel partnership with regional drone service operators enables bypass of prime-contractor gatekeeping. For Investors and Strategic Acquirers: Asymmetric upside sits with sensor fusion specialists possessing deployable urban airspace monitoring networks and embedded software capabilities rather than hardware-centric legacy suppliers. Five-to-ten year viability favors vendors with semiconductor design competence and recurring revenue from firmware subscriptions. The signal to watch is EASA authorization timeline compression as indicator of regulatory efficiency enabling product launch velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Software-Defined Radio Modularization | Firmware-upgradeable architectures displace hardware-tuned systems in United States military procurement. |
| GaN Substrate Backward Integration | In-house production of RF power amplifiers mitigates Chinese foundry concentration risk for jamming systems. |
| AI-Edge Sensor Fusion Development | Onboard radar processing eliminates centralized server dependency for urban airspace monitoring nodes. |
| EASA Specific Category Certification | Operational authorization accelerates product launches in European urban air mobility corridors. |
| Managed Airspace Protection Services | Recurring revenue contracts with German power utilities displace capital purchase models. |
Research Methodology
Direct dialogue with counter-UAS program officers at defense ministries, RF engineering directors at radar manufacturers, procurement leads at municipal police departments, and regulatory affairs specialists at FAA and EASA anchored qualitative grounding. Secondary validation drew from FAA Remote ID rulemakings, EASA drone regulation framework documents, SEC 10-K filings of listed defense contractors, and customs trade data for gallium nitride substrate flows. Bottom-up segment sizing triangulated against top-down macroeconomic drivers across the analysis window.
Top-down modeling anchored aggregate market boundaries using defense procurement disclosures and commercial fleet retrofit obligations, while bottom-up builds aggregated individual segment trajectories across collision avoidance systems, computer vision technology modules, and law enforcement end-user contracts. Segmentation dimensions modeled encompass product type, technology, application, end user, and regulatory jurisdiction cluster. CAGRs derived from fitted growth curves incorporating FAA mandate compliance deadlines and EASA authorization pipeline visibility.
Underlying measurement precision varies by segment; defense procurement disclosures carry tighter precision than commercial fleet estimates subject to OEM reporting opacity. Forecasts reflect assumptions regarding regulatory enforcement consistency and gallium nitride supply continuity that material shifts in trade policy or foundry capacity could revise. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Safety Equipment and Personal Protective Equipment (PPE)
Global Safety and Eyewash Shower Market
Safety Equipment and Personal Protective Equipment (PPE)
Plastics in Personal Protective Equipment Market
Safety Equipment and Personal Protective Equipment (PPE)
Hazardous Disposal Bag Market
Safety Equipment and Personal Protective Equipment (PPE)
Global Guns Safes Market
Safety Equipment and Personal Protective Equipment (PPE)
Global Emergency Stop Switches Market
Safety Equipment and Personal Protective Equipment (PPE)
Disposable Respirator Market
Safety Equipment and Personal Protective Equipment (PPE)
Protective Fluid Market
Safety Equipment and Personal Protective Equipment (PPE)
Asia-Pacific Riot Control Equipment Market
Safety Equipment and Personal Protective Equipment (PPE)
Electrical Safety Gloves Market
Safety Equipment and Personal Protective Equipment (PPE)
Global Radiation Protection Apron Market
Safety Equipment and Personal Protective Equipment (PPE)
Electrical Safety Products Market
Safety Equipment and Personal Protective Equipment (PPE)
US Industrial Hearing Protection Market
Safety Equipment and Personal Protective Equipment (PPE)
Cut Resistant Gloves Market
Safety Equipment and Personal Protective Equipment (PPE)
Chemical Protective Gloves Market
Safety Equipment and Personal Protective Equipment (PPE)
Industrial Machine Guarding Fence Market
Safety Equipment and Personal Protective Equipment (PPE)
Safety Light Curtains Market