
 North America Respiratory Protective Equipment (RPE) Market | 2026-2036
North America Respiratory Protective Equipment (RPE) Market Size, Share, and Industry Trends Forecast 2026-2036
North America Respiratory Protective Equipment (RPE) Market Insights
Market Context
Healthcare procurement is recalibrating toward higher-assurance respiratory systems as post-acute facilities expand fit-testing programs. 3M leverages its filtration R&D infrastructure to sustain N95 dominance across hospital group purchasing organizations. MSA Safety anchors industrial channel share through its firefighter SCBA installed base and confined-space ventilation portfolios.
Technical Definition and Segment Structure
Respiratory Protective Equipment encompasses tight-fitting facepieces, loose-fitting hoods, and powered air-purifying systems engineered to NIOSH 42 CFR Part 84 filtration efficiency standards, designed to prevent inhalation of particulates, gases, vapors, or oxygen-deficient atmospheres in occupational environments. Disposable respirators command volume leadership due to healthcare consumption patterns, yet powered air-purifying respirators represent the fastest-expanding margin pool as manufacturing and pharmaceutical cleanrooms adopt positive-pressure hood systems. Filtration technology occupies the dominant share position across industrial safety applications, while chemical absorption configurations differentiate offerings in oil & gas hazardous environment contracts.
Regulatory Framework and Outlook
OSHA's respiratory protection standard (29 CFR 1910.134) mandates medical evaluation, fit testing, and training protocols that directly inflate compliance-driven replacement cycles. NIOSH certification requirements and FDA emergency use authorizations for healthcare settings create dual jurisdictional complexity for manufacturers serving both medical and industrial buyers. Stakeholders must monitor pending OSHA rulemaking on silica and beryllium exposure limits, as tighter permissible exposure levels would force accelerated respirator upgrades across construction and foundry end users.
Market Dynamics
OSHA's silica and beryllium rulemaking is compressing replacement cycles across construction and foundry operations, forcing end users toward higher-assurance filtration systems ahead of compliance deadlines.
Growth Catalysts
- NIOSH 42 CFR Part 84 recertification waves:Updated filter efficiency benchmarks are mandating equipment turnover across healthcare systems and industrial facilities, sustaining replacement demand through 2035.
- Texas Gulf Coast petrochemical expansion:Capacity additions across Beaumont-Port Arthur refining corridors are driving contract awards for supplied-air respirators and SCBA systems in hydrogen sulfide environments.
- Positive-pressure hood adoption:Pharmaceutical cleanrooms in North Carolina's Research Triangle are transitioning from negative-pressure elastomerics to powered air-purifying systems for sterile compound handling.
Market Restraints
- Polypropylene meltblown supply concentration:Filter media production clusters in the southeastern United States create single-source vulnerability for N95 and P100 cartridge manufacturers.
- Fit-testing infrastructure gaps:Rural long-term care facilities lack quantitative fit-testing equipment, limiting compliance penetration outside metropolitan hospital networks.
- Reusable elastomeric substitution limits:Healthcare infection control protocols block widespread adoption of cleanable half-mask respirators despite lower lifetime costs.
Strategic Opportunities
- Mexican maquiladora manufacturing corridors:Underpenetrated automotive assembly and electronics operations along the Tijuana-Mexicali axis present first-mover potential for distributor partnerships.
- Wearable sensor convergence:Integration of biometric monitoring with PAPRs enables real-time respirator performance tracking for high-exertion firefighters and hazmat teams.
- California agricultural processing zones:Permanent pesticide handler regulations are mandating annual respirator program audits, expanding service contract attach rates for distributors.
Industry Challenges
- Respiratory protection program administrator certification:OSHA's 29 CFR 1910.134 training requirements face acute instructor shortages, delaying employer compliance timelines.
- Legacy SCBA fleet interoperability:Fire departments face integration friction when mixing new NFPA 1981-compliant units with existing cylinder and mask configurations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Respiratory Protective Equipment (RPE) Market |
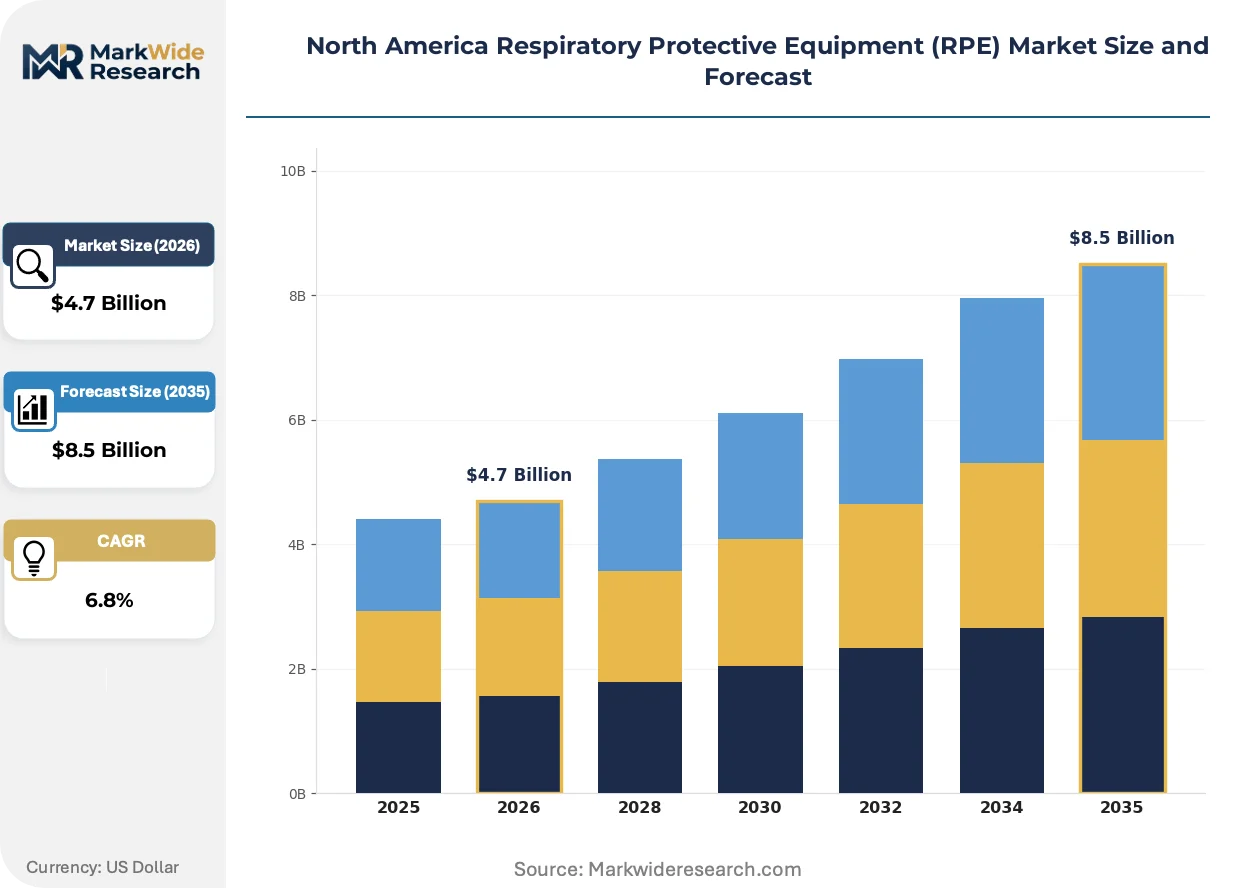
| Market Size in 2026 | $4.7 Billion |
| Market Size in 2035 | $8.5 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Half Mask, Full Face Mask, Disposable Respirator, Powered Air-Purifying Respirator End User: Healthcare, Manufacturing, Construction, Oil & Gas Technology: Filtration, Chemical Absorption, Combination, Ventilation Application: Industrial Safety, Healthcare Settings, Hazardous Environments, Firefighting |
| Companies Covered | 3M, Honeywell International, MSA Safety, Kimberly-Clark, Alpha Pro Tech, Bullard, Avon Protection Systems, Drägerwerk, Gentex, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Respiratory Protective Equipment (RPE) Market Trends and Innovations
Smart connectivity and predictive maintenance capabilities are migrating from industrial asset management into respiratory protection, reshaping how end users monitor equipment integrity and worker exposure.
Next-generation cartridge designs are modularizing filtration architecture across chemical manufacturing sites. Honeywell and MSA Safety platforms now permit field-swappable particulate, organic vapor, and acid gas elements without full facepiece replacement. Refinery maintenance crews in Louisiana and Texas are adopting these systems to reduce inventory SKUs and cut changeout downtime. The technology is modularizing procurement patterns, compressing multi-cartridge contracts into unified platform agreements with recurring element subscriptions.
OSHA's pending crystalline silica enforcement memorandum is tightening permissible exposure calculations across masonry and countertop fabrication shops. The rulemaking is forcing engineered control hierarchies that elevate respirator selection from voluntary use to mandatory protection factor assignments. Construction contractors in Florida and Arizona are pre-positioning loose-fitting powered air-purifying hoods to stay ahead of citation exposure.
Hospital group purchasing organizations are consolidating respiratory SKU lists from fifteen-plus disposable respirator variants to three standardized N95 configurations. This supplier rationalization is displacing distributor branch inventory models with direct-to-facility consolidated deliveries managed through integrated supply chain platforms. The shift is most visible across Catholic health system networks in the Midwest and Southeast, where standardization committees now override individual facility preferences.
North America Respiratory Protective Equipment (RPE) Market Segmentation
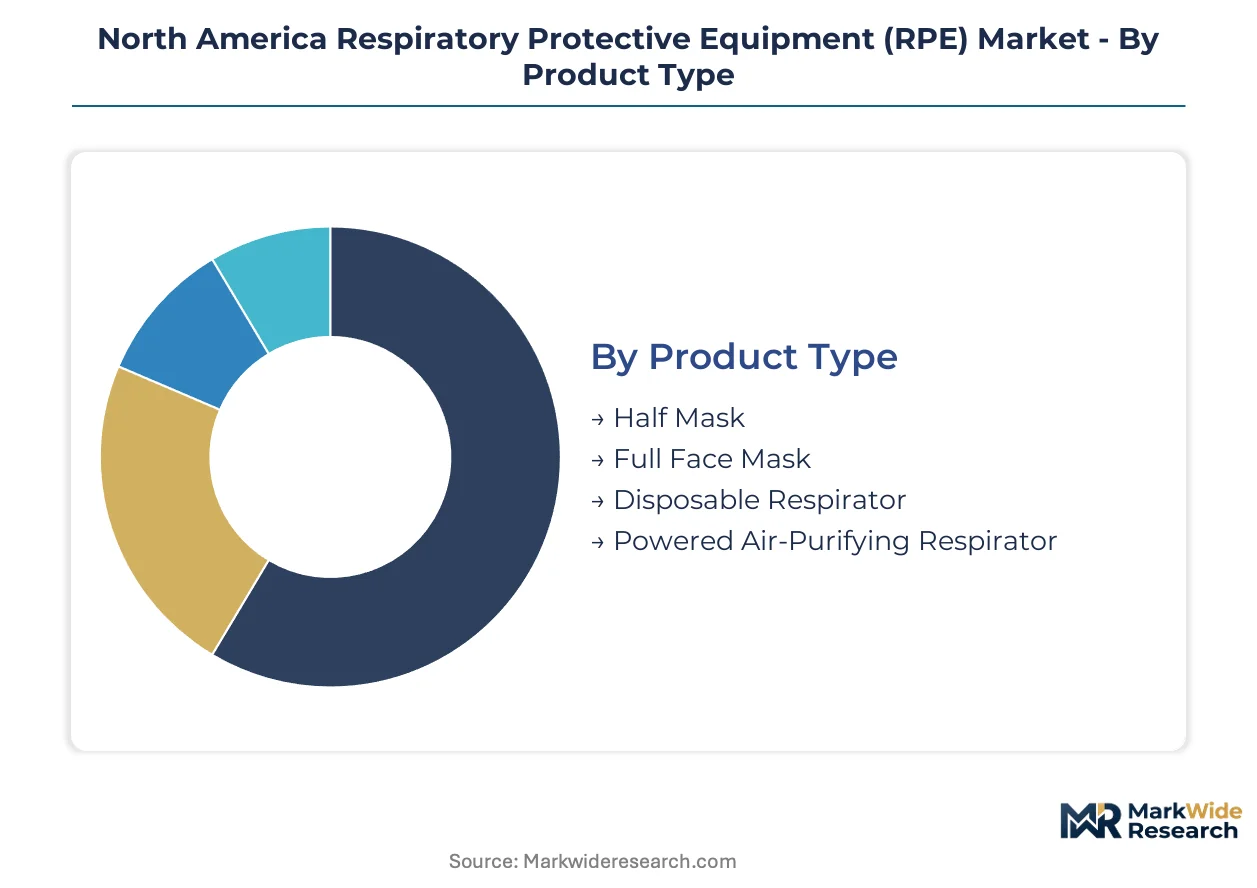
Segmentation in respiratory protective equipment reveals how certification requirements, exposure environments, and procurement budgets fragment demand across incompatible product architectures. Buyers select equipment based on OSHA-assigned protection factors, NIOSH approval classes, and end-use contamination profiles rather than interchangeable specifications.
Product Type:
NIOSH 42 CFR Part 84 certification burdens vary sharply across this category, with tight-fitting elastomerics requiring annual fit-testing documentation while loose-fitting hoods need only flow-verification protocols.
- Disposable Respirator:N95 and P100 filtering facepieces dominate hospital procurement through group purchasing organization contracts. California agricultural processing zones and Texas Gulf Coast petrochemical corridors sustain industrial volume despite higher per-unit costs than elastomeric alternatives.
- Powered Air-Purifying Respirator:Positive-pressure hood systems with HEPA filtration and belt-mounted blowers command premium positioning in pharmaceutical cleanrooms. North Carolina's Research Triangle facilities are transitioning from negative-pressure elastomerics to these systems for sterile compound handling, driven by USP 800 compliance deadlines.
- Half Mask:Elastomeric facepieces with dual-cartridge attachment points serve maintenance crews in manufacturing and construction where repeated donning justifies cleaning protocols.
- Full Face Mask:Panoramic lens designs with five-point harness systems protect against eye-irritant vapors in chemical processing and pesticide application settings.
Disposable respirators sit at the top of the volume ranking, with powered air-purifying respirators climbing the fastest.
End User:
Procurement authority and compliance documentation requirements diverge across this category, with healthcare systems mandating FDA-cleared devices while industrial buyers operate under OSHA respiratory protection program standards alone.
- Healthcare:Acute care hospitals and long-term care facilities consume N95 disposables through emergency preparedness stockpiles and isolation precaution protocols. Fit-testing infrastructure gaps in rural facilities constrain compliance penetration outside metropolitan networks.
- Oil & Gas:Hydrogen sulfide exposure risks across Louisiana and Texas refining corridors drive supplied-air respirator and SCBA system contracts. Beaumont-Port Arthur capacity expansions are accelerating replacement cycles for legacy breathing apparatus fleets.
- Manufacturing:Metal fabrication and electronics assembly operations balance reusable elastomeric economics against disposable convenience in high-turnover workforce environments.
- Construction:Silica and beryllium rulemaking is compressing equipment replacement cycles across masonry and countertop fabrication shops, elevating respirator selection from voluntary use to mandatory protection factor assignments.
Healthcare dominates absolute volume, with oil and gas expanding most quickly on petrochemical corridor investments.
Technology:
Margin structures align with technical complexity, with single-mechanism filtration commanding commodity pricing while multi-threat combination systems capture service-attach revenue through cartridge subscription programs.
- Filtration:Mechanical particulate capture using meltblown polypropylene media achieves N95 and P100 efficiency ratings. Polypropylene supply concentration in southeastern US manufacturing clusters creates single-source vulnerability for cartridge producers.
- Combination:Layered particulate and gas-vapor protection addresses multi-contaminant environments without facepiece changeout. Refinery maintenance crews in Texas and Louisiana are adopting modular field-swappable designs to reduce inventory SKUs and cut changeout downtime.
- Chemical Absorption:Activated carbon and specialized sorbent beds target organic vapors, acid gases, and ammonia in confined-space entry operations.
- Ventilation:Supplied-air and self-contained breathing apparatus systems deliver breathable atmosphere in oxygen-deficient or immediately dangerous to life and health environments.
Filtration technology sits at the top of the volume ranking, with combination systems gaining share fastest through modular platform adoption.
Application:
Regulatory enforcement intensity and penalty exposure shape procurement budgets across this category, with firefighting NFPA 1981 compliance carrying liability implications that dwarf industrial safety program costs.
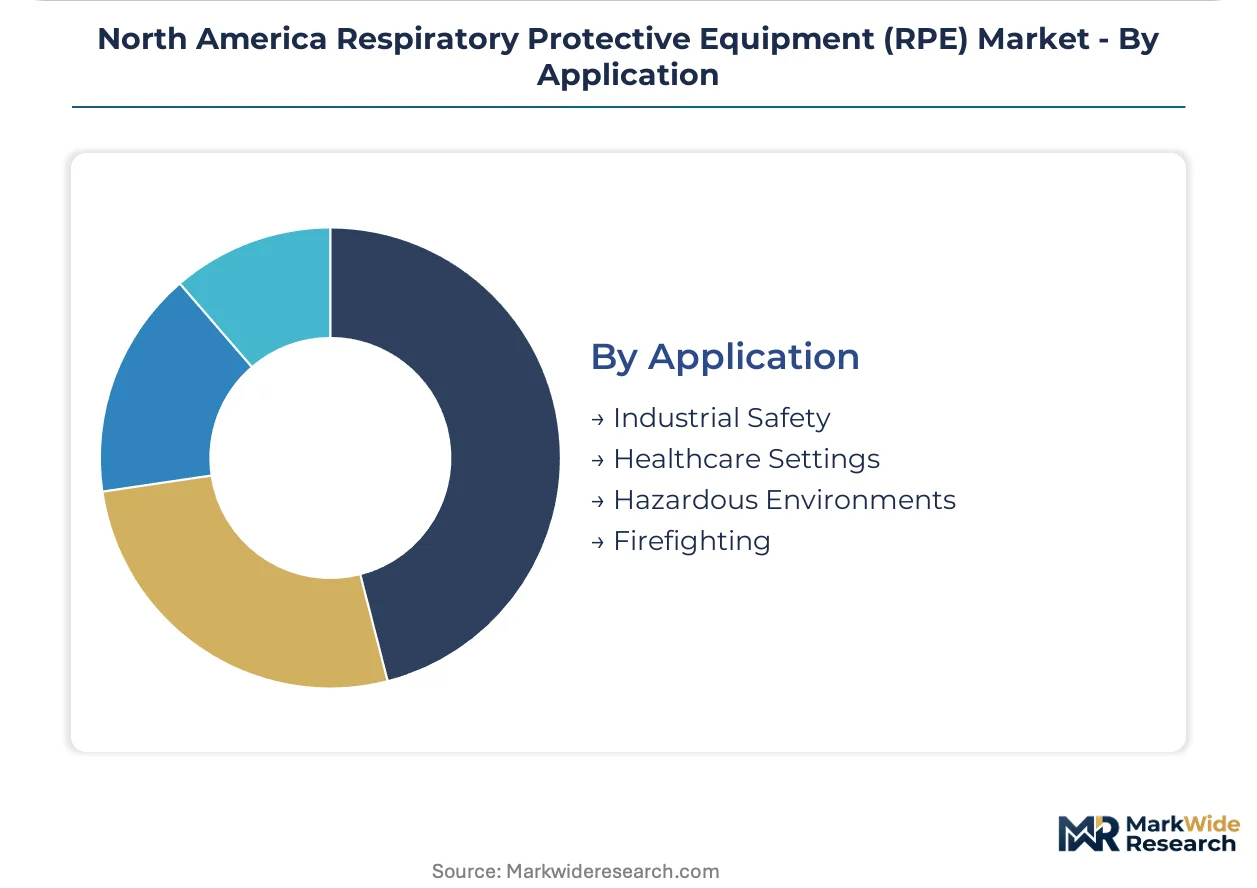
- Industrial Safety:General manufacturing and warehouse operations deploy half-mask elastomerics against nuisance dust and solvent vapor exposures. OSHA's pending crystalline silica enforcement memorandum is tightening permissible exposure calculations across masonry and countertop fabrication shops.
- Firefighting:NFPA 1981-compliant SCBA systems with integrated PASS devices and thermal imaging compatibility face interoperability friction when mixed with legacy cylinder and mask configurations.
- Healthcare Settings:Isolation rooms and surgical suites require fluid-resistant N95 or PAPR protection against airborne infectious agents.
- Hazardous Environments:Chemical manufacturing and waste remediation operations specify combination cartridge systems against unpredictable contaminant profiles.
Industrial safety sits at the top of the volume ranking, with firefighting climbing the fastest on NFPA compliance upgrade cycles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are shifting production toward jurisdictions with streamlined NIOSH certification pathways, while end-use demand concentrates in high-enforcement corridors where OSHA inspection intensity creates compliance-driven replacement cycles.
United States
Texas Gulf Coast petrochemical expansions and California agricultural processing zones anchor industrial demand for supplied-air systems and pesticide-handler respirators. OSHA's pending silica enforcement memorandum is accelerating equipment turnover across masonry and countertop fabrication shops. Beaumont-Port Arthur refining corridors are driving contract awards for SCBA systems in hydrogen sulfide environments.
Canada
Alberta oil sands operations and Ontario manufacturing clusters sustain demand for full-face elastomerics against organic vapor exposures. Health Canada alignment with NIOSH filtration standards simplifies cross-border procurement for integrated North American operators. British Columbia mining and forestry operations are adopting powered air-purifying systems for silica and wood dust abatement.
Mexico
Maquiladora automotive assembly along the Tijuana-Mexicali corridor and electronics manufacturing in Baja California present underpenetrated opportunities for distributor partnerships. Mexican federal labor law amendments are tightening occupational exposure limits toward OSHA-equivalent thresholds. Guanajuato and Nuevo León industrial parks are expanding respiratory protection program mandates for foreign-owned assembly operations.
United States — Southeast
North Carolina's Research Triangle pharmaceutical cleanrooms are transitioning from negative-pressure elastomerics to positive-pressure hood systems for USP 800 compliance. Polypropylene meltblown filter media production clusters in Tennessee and South Carolina create supply concentration for N95 cartridge manufacturers. Florida construction contractors are pre-positioning loose-fitting PAPRs ahead of crystalline silica enforcement.
United States — Midwest
Catholic health system networks across Illinois, Michigan, and Ohio are consolidating respiratory SKU lists from fifteen-plus variants to three standardized N95 configurations. Rural long-term care facilities face fit-testing infrastructure gaps that constrain compliance penetration outside metropolitan hospital networks. Ohio metal fabrication and foundry operations are upgrading filtration systems ahead of beryllium exposure limit reductions.
North America Respiratory Protective Equipment (RPE) Market Competitive Landscape
Strategic partnerships dominate the current landscape as manufacturers seek to bridge fit-testing infrastructure gaps and secure cartridge subscription revenue streams. The vendor base organizes into three tiers: diversified industrial conglomerates with filtration R&D infrastructure, safety specialists with firefighter SCBA installed bases, and disposable-focused healthcare suppliers. Two strategic archetypes predominate: platform providers pursuing unified system agreements with recurring element subscriptions, and regional distributors capturing service-attach revenue through program administrator certification training. Competitive moves center on modular cartridge architecture licensing and wearable sensor convergence for real-time performance tracking.
Among diversified industrial conglomerates, 3M leverages its filtration R&D infrastructure to sustain N95 dominance across hospital group purchasing organizations. MSA Safety anchors industrial channel share through its firefighter SCBA installed base and confined-space ventilation portfolios. Honeywell International occupies a position bridging both healthcare and industrial segments through modular platform designs that permit field-swappable filtration elements.
| Leading Market Players |
|---|
| 3M |
| Honeywell International |
| MSA Safety |
| Kimberly-Clark |
| Alpha Pro Tech |
| Bullard |
| Avon Protection Systems |
| Drägerwerk |
| Gentex |
| Others |
Pricing and Supply Chain Analysis
Polypropylene meltblown filter media costs cascade through three pricing tiers as southeastern US production clusters feed cartridge manufacturers serving hospital group purchasing organizations and industrial distributors.
Pricing Analysis
Distributor margin compression runs through the disposable respirator tier as Catholic health system networks consolidate SKU lists from fifteen-plus variants to three standardized N95 configurations. Three-tier pricing structure across premium powered air-purifying systems, standard elastomeric platforms, and economy disposable facepieces reflects certification grade and after-sales service bundling. Price erosion intensifies in the healthcare channel as direct-to-facility consolidated deliveries displace branch inventory models. Construction contractors in Florida and Arizona show highest price sensitivity, while pharmaceutical cleanrooms in North Carolina's Research Triangle absorb premium positioning for USP 800-compliant positive-pressure hoods.
Supply Chain Analysis
Single-source vulnerability sits with polypropylene meltblown production concentrated in Tennessee and South Carolina manufacturing clusters. Raw material inputs draw from petroleum feedstocks, activated carbon sorbents, and silicone elastomer components. Tariff exposure on Chinese-sourced filtration media creates inventory risk for N95 and P100 cartridge producers. Distribution runs through industrial safety distributors with respiratory protection program administrator certification capabilities, anchored by firefighter SCBA service infrastructure.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunity concentrates in cartridge subscription revenue as modular platform designs compress multi-SKU contracts into unified agreements with recurring element attach rates.
For Market Incumbents: Lock in respiratory protection program administrator certification training revenue by acquiring regional distributors with OSHA 29 CFR 1910.134 instructor capabilities. Secure backward integration into polypropylene meltblown media production to defend against southeastern US supply concentration risk. MSA Safety's firefighter SCBA installed base and 3M's filtration R&D infrastructure demonstrate how channel control and certification investment create defensive moats against modular platform competitors. For New Entrants and Emerging Players: Wearable sensor convergence for real-time respirator performance tracking offers a technology-first wedge into firefighter and hazmat team segments currently served by legacy PASS device architectures. Target Mexican maquiladora corridors along the Tijuana-Mexicali axis where federal labor law amendments are tightening occupational exposure limits toward OSHA-equivalent thresholds. Partner with automotive assembly operations in Guanajuato and Nuevo León to establish distributor relationships ahead of respiratory protection program mandate expansion. For Investors and Strategic Acquirers: Consolidation pressure builds where fit-testing infrastructure gaps in rural long-term care facilities constrain compliance penetration outside metropolitan hospital networks. Five-to-ten year viability favors platform providers with recurring cartridge subscription revenue over disposable-focused suppliers vulnerable to SKU rationalization. Watch NIOSH 42 CFR Part 84 recertification waves as inflection indicator for equipment turnover velocity across healthcare systems and industrial facilities.| Strategic Initiative | Industry Significance |
|---|---|
| Modular Cartridge Platform Licensing | Honeywell and MSA Safety field-swappable designs reduce inventory SKUs for refinery maintenance crews in Texas and Louisiana. |
| Fit-Testing Infrastructure Partnership | Quantitative fit-testing equipment deployment addresses compliance gaps in rural long-term care facilities outside metropolitan networks. |
| Cartridge Subscription Program Launch | Recurring element subscriptions capture service-attach revenue from pharmaceutical cleanrooms transitioning to positive-pressure hood systems. |
| Wearable Sensor Integration | Biometric monitoring convergence enables real-time performance tracking for high-exertion firefighters and hazmat teams. |
| Maquiladora Corridor Distributor Expansion | Tijuana-Mexicali automotive assembly and Baja California electronics manufacturing present first-mover partnership potential. |
Research Methodology
Coverage spans the United States, Canada, and Mexico, with primary inputs from each jurisdiction combined with secondary validation. Primary interviews engaged respiratory protection program administrators, industrial safety distributors, hospital GPO contracts managers, and firefighter equipment procurement officers. Secondary sources included OSHA regulatory filings, NIOSH certification databases, Health Canada device licensing records, and Mexican federal labor law amendments. Bottom-up segment sizing triangulated against top-down macroeconomic indicators.
Rate-of-change decomposition separated volume drivers from price-mix effects across the projection horizon. Segmentation dimensions modeled include product type, end user, technology, and application, with additional granularity on NIOSH approval class and OSHA-assigned protection factor. CAGRs derived from equipment replacement cycle analysis, regulatory compliance deadline mapping, and petrochemical capacity expansion tracking. Forecast inputs incorporated silica and beryllium rulemaking enforcement timelines and USP 800 compliance transition patterns.
The model holds under stable regulatory enforcement intensity; deviation in OSHA inspection priority shifts or NIOSH recertification schedule acceleration would reshape replacement demand timing. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Safety Equipment and Personal Protective Equipment (PPE)
Latin America Hand Sanitizer Market
Safety Equipment and Personal Protective Equipment (PPE)
Supplementary Protectors Market
Safety Equipment and Personal Protective Equipment (PPE)
Passenger Security Equipment Market
Safety Equipment and Personal Protective Equipment (PPE)
Bullet Proof Jackets Market
Safety Equipment and Personal Protective Equipment (PPE)
Respirator Mask Particulate Market
Safety Equipment and Personal Protective Equipment (PPE)
Armoured Thermocouple Market
Safety Equipment and Personal Protective Equipment (PPE)
Safety Eyewear Market
Safety Equipment and Personal Protective Equipment (PPE)
Europe Safes and Vaults Market
Safety Equipment and Personal Protective Equipment (PPE)
Driving Protection Gear Market
Safety Equipment and Personal Protective Equipment (PPE)
Medical Respiratory Protective Equipment Market
Safety Equipment and Personal Protective Equipment (PPE)
Flu Protection Kits Market
Safety Equipment and Personal Protective Equipment (PPE)
Global Protective Face Mask Market
Safety Equipment and Personal Protective Equipment (PPE)
Emergency Showers Market
Safety Equipment and Personal Protective Equipment (PPE)
Pest Control Devices Market
Safety Equipment and Personal Protective Equipment (PPE)
Tourniquet Market
Safety Equipment and Personal Protective Equipment (PPE)
South America Protective Coating Market