
 Supplied Air Respirators Market | 2026-2036
Supplied Air Respirators Market Size, Share, and Industry Trends Forecast 2026-2036
Supplied Air Respirators Market Outlook
Buyer concentration in industrial manufacturing is broadening as large chemical processors and petroleum refiners consolidate respiratory protection procurement under centralized safety budgets. MSA Safety leverages its integrated breathing apparatus portfolio to anchor long-term service contracts with downstream energy operators. Drägerwerk AG & Co. KGaA sustains technology leadership in positive pressure systems through sustained engineering investment in lightweight hose assemblies. Honeywell International Inc. competes across multiple application verticals with modular platform architectures that reduce spare parts complexity for plant maintenance teams.
Supplied air respirators deliver breathable air from an uncontaminated source through a hose or compressor system, typically operating at pressures between 4-15 psi depending on whether continuous flow or pressure-demand configurations serve the wearer. These systems protect workers in immediately dangerous to life or health atmospheres where filter-based devices prove inadequate against gases, vapors, or oxygen-deficient environments. Product type segmentation shows powered air purifying respirators occupying the largest installed base due to their hybrid flexibility, while airline respirators capture premium positioning in confined space entries where tethered air supply remains non-negotiable. Application segmentation reveals industrial safety as the mature revenue core, whereas emergency services represents the fastest structural expansion as fire departments modernize from self-contained units to extended-duration supplied air platforms for technical rescue scenarios.
OSHA 29 CFR 1910.134 governs respiratory protection program requirements in the United States, mandating fit testing, medical evaluation, and equipment maintenance protocols that directly shape replacement cycles and training service demand. NIOSH certification standards for supplied air respirators establish minimum airflow rates and hose integrity benchmarks that manufacturers must satisfy for market access. EPA chemical facility safety rules and state-level process safety management inspections further tighten compliance exposure for petrochemical operators. Stakeholders must monitor evolving silica and beryllium exposure limits that could accelerate fleet upgrades beyond standard replacement schedules.
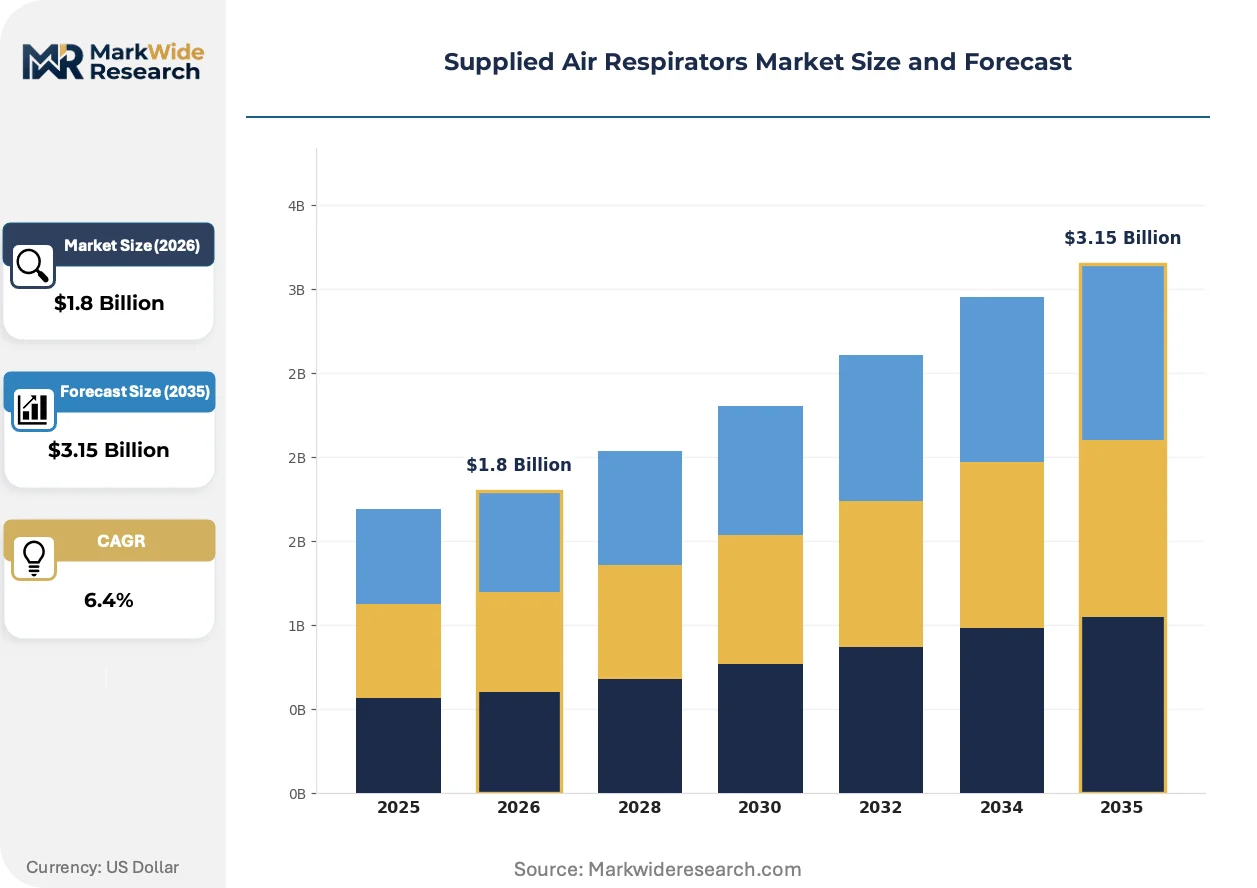
Market Dynamics
Industrial manufacturing buyers are consolidating respiratory protection procurement under centralized safety budgets while OSHA tightens compliance requirements for supplied air systems, compressing replacement cycles and elevating service contract value.
Growth Catalysts
- OSHA 29 CFR 1910.134 enforcement:Mandatory fit testing and medical evaluation protocols accelerate fleet refresh rates among chemical processors and petroleum refiners.
- Silica exposure rule expansion:Stricter permissible exposure limits for respirable crystalline silica force construction and foundry operators to upgrade from filter-based devices to supplied air systems.
- Confined space rescue modernization:Fire departments across the United States are replacing self-contained breathing apparatus with extended-duration supplied air platforms for technical rescue scenarios.
Market Restraints
- Compressor maintenance burden:Breathing air compressor systems require quarterly filter changes and annual certification, creating lifecycle cost penalties versus disposable alternatives.
- Hose assembly fragility:Lightweight thermoplastic hose materials degrade under UV exposure and chemical contact, constraining deployment duration in outdoor refining operations.
- NIOSH certification bottlenecks:Approval timelines for new positive pressure configurations extend 18-24 months, freezing product pipeline velocity for manufacturers.
Strategic Opportunities
- Emergency services platform shift:Technical rescue teams in urban fire departments present untapped demand for airline respirators with 300-foot hose reach capabilities.
- Remote monitoring integration:Convergence of pressure sensors and telemetry systems enables real-time airflow tracking, opening predictive maintenance service revenue streams.
- State-level PSM inspections:California and Texas process safety management enforcement creates compliance-driven replacement demand beyond federal minimums.
Industry Challenges
- Respiratory protection program administration:Industrial safety managers face staffing shortages for medical evaluation coordination and fit test documentation.
- Legacy SCBA integration:Fire departments struggle to interconnect new supplied air systems with existing self-contained breathing apparatus inventory and training protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Supplied Air Respirators Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.15 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: PAPR, SAR, Airline Respirators, Combination Respirators Application: Industrial Safety, Healthcare, Emergency Services, Construction End User: Manufacturing, Oil & Gas, Mining, First Responders Technology: Filtration, Positive Pressure Systems, Compressed Air Supply, Chemical Absorption |
| Companies Covered | 3M Company, Honeywell International Inc., MSA Safety, Avon Protection, Drägerwerk AG & Co. KGaA, Bullard, Alpha Pro Tech, ILC Dover, Lakeland Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Supplied Air Respirators Market Strategic Shifts
Supplied air respirator architecture is fragmenting into configurable subsystems that reduce spare parts proliferation and simplify field maintenance for plant operators.
Lightweight carbon composite breathing air compressors is modularizing field deployment options for offshore oil platforms and remote construction sites. Platform operators are adopting skid-mounted compressor packages at twice the rate of traditional stationary installations. This technology is modularizing supply chain logistics by enabling rapid relocation between wellhead sites without recertification delays.
EPA chemical facility safety rules are tightening secondary containment requirements for breathing air compressor installations. Petrochemical operators must now install spill containment and vapor recovery systems for lubricated compressor units. Gulf Coast refineries are responding by accelerating conversion to oil-free compressor technologies ahead of inspection cycles.
Centralized procurement through integrated safety distributors is displacing direct manufacturer relationships among mid-sized chemical processors. Industrial distributors are capturing respiratory protection spend by bundling supplied air systems with gas detection and fall protection equipment. This pattern concentrates most visibly in the Ohio River Valley manufacturing corridor where multi-site operators favor single-source safety contracts.
Supplied Air Respirators Market Segmentation
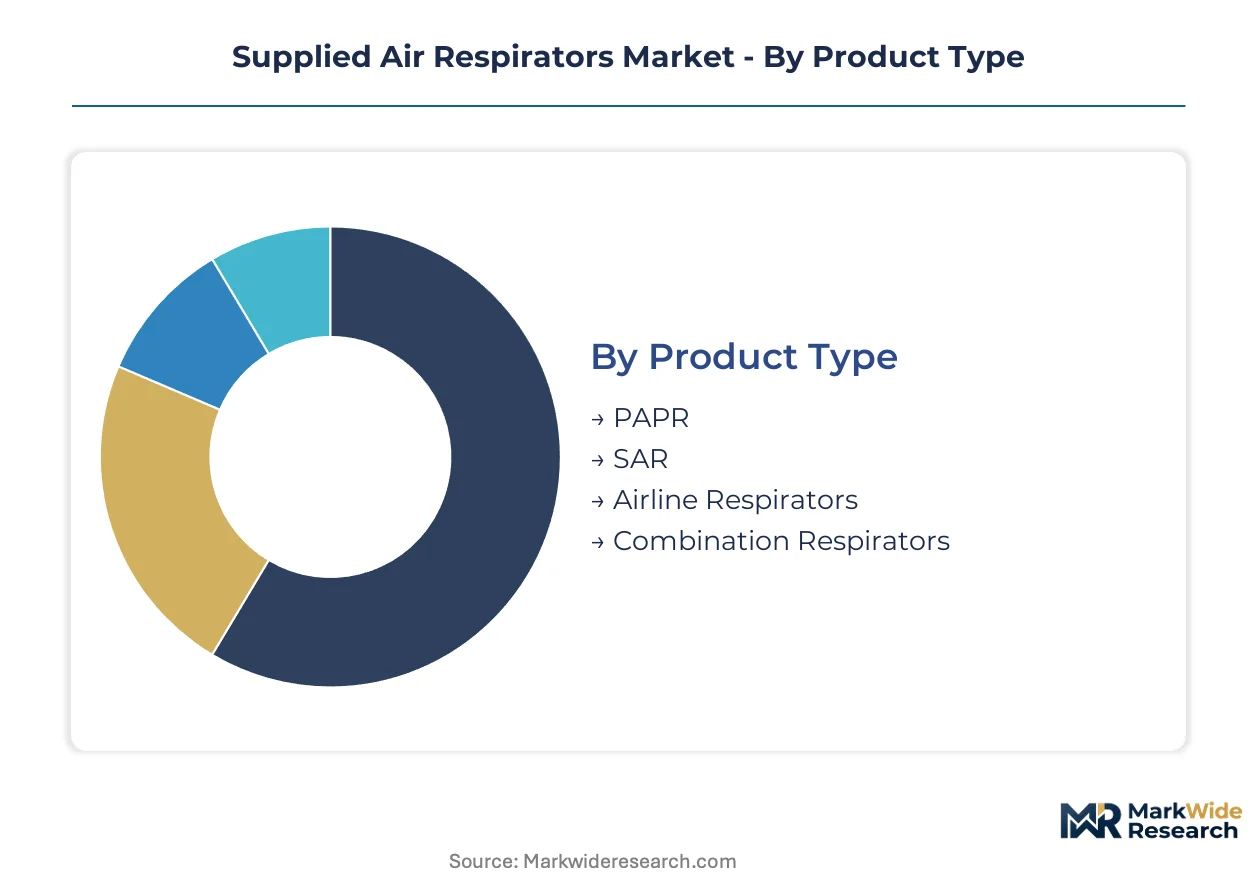
Supplied air respirator segmentation reveals how engineering specifications diverge across hazard intensity and mobility requirements. Procurement patterns cluster around regulatory compliance thresholds rather than pure performance metrics.
Product Type:
Standardization dominates low-hazard environments while custom configurations proliferate where confined space protocols demand tethered air supply.
- PAPR:Powered air purifying respirators combine battery-driven blowers with filter cartridges to deliver positive-pressure airflow without external air lines. Demand concentrates in pharmaceutical manufacturing cleanrooms where mobility outweighs absolute atmospheric isolation. OSHA silica enforcement is accelerating PAPR deployment in construction trades previously served by disposable N95 units.
- SAR:Self-contained breathing apparatus systems carry compressed air cylinders on the wearer, enabling complete independence from ambient atmosphere. First responder agencies in Texas and California are modernizing SAR fleets with reduced-profile cylinders that extend operational duration without increasing weight burden.
- Airline Respirators:Tethered systems deliver breathable air through hoses from stationary compressors or portable cylinders. Chemical processors along the Ohio River Valley specify 300-foot hose reach for tank cleaning operations.
- Combination Respirators:Hybrid architectures switch between supplied air and filtered modes based on atmospheric monitoring. Offshore platform operators favor these for transition zones between process areas and administrative spaces.
Most installed capacity flows through PAPR configurations. Expansion is steepest in airline respirators as petrochemical operators extend confined space protocols.
Application:
Cost tier stratification separates mature industrial safety budgets from emerging emergency services procurement.
- Industrial Safety:Chemical processing and petroleum refining operations anchor revenue concentration with scheduled replacement cycles tied to OSHA respiratory protection program audits. Refinery turnarounds in Louisiana and Texas drive peak demand for rental airline systems.
- Healthcare:Hospital isolation rooms and pharmaceutical compounding facilities deploy supplied air for protection against novel therapeutic compounds. BSL-3 laboratory construction in Maryland and North Carolina is expanding positive-pressure suit demand.
- Emergency Services:Technical rescue teams require extended-duration systems for trench and structural collapse scenarios. Urban fire departments in Chicago and Los Angeles are transitioning from SCBA-only to combined supplied air platforms.
- Construction:Silica exposure rule compliance is displacing disposable respirators in concrete cutting and demolition. Infrastructure projects in New York and California specify airline systems for tunnel boring operations.
Industrial Safety commands the largest procurement volumes. Emergency Services represents the fastest-growing trajectory as mutual aid agreements standardize equipment interoperability.
End User:
Customer type segmentation reflects divergent maintenance capabilities and capital cycle timing.
- Manufacturing:Automotive and aerospace plants integrate supplied air into centralized breathing air compressor networks. Boeing's Charleston and Everett facilities operate dedicated compressor houses serving multiple assembly lines.
- Oil & Gas:Upstream operators prioritize portable compressor packages for wellhead work while downstream refineries invest in permanent installations. Gulf Coast refineries are consolidating respiratory protection under integrated safety contracts.
- Mining:Underground coal and metal mines specify intrinsically safe systems for methane atmospheres. MSHA enforcement patterns in Appalachia and the Mountain West drive replacement timing.
- First Responders:Municipal fire departments face budget constraints that favor grant-funded modernization cycles. FEMA assistance to firefighter grants is concentrating SAR upgrades in mid-sized cities.
Manufacturing deploys the most compressor capacity. First Responders are expanding most quickly through federal grant programs.
Technology:
Supply concentration clusters around positive pressure engineering where NIOSH certification creates entry barriers.
- Filtration:High-efficiency particulate filters and chemical cartridges remove contaminants from ambient air. Foundry operators in Indiana and Ohio specify P100 filtration for metal fume protection.
- Positive Pressure Systems:Maintains outward airflow to prevent contaminant ingress if facepiece seal degrades. This architecture dominates NIOSH-approved configurations for IDLH atmospheres.
- Compressed Air Supply:Breathing air compressors with filtration and monitoring deliver Grade D air through distribution networks. Offshore platform operators specify oil-free scroll compressors to eliminate hydrocarbon contamination risk.
- Chemical Absorption:Specialized canisters neutralize specific toxic gases through reactive media. Semiconductor fabrication facilities in Arizona and Oregon deploy these for arsine and phosphine protection.
Positive Pressure Systems carry the largest installed base. Compressed Air Supply is gaining share fastest through petrochemical facility upgrades.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Petrochemical workforce concentrations along the Gulf Coast and Ohio River Valley anchor North American demand, while European chemical clusters and Asian manufacturing hubs sustain procurement velocity through regulatory enforcement cycles.
United States
OSHA 29 CFR 1910.134 enforcement compresses replacement cycles among Louisiana and Texas refiners. EPA chemical facility safety rules tighten secondary containment for breathing air compressor installations. Gulf Coast petrochemical operators accelerate conversion to oil-free compressor technologies ahead of inspection cycles.
Germany
REACH compliance and industrial safety standards drive fleet modernization among Rhine-Ruhr chemical processors. ECHA substance restrictions on respirable crystalline silica force foundry operators to upgrade from filter-based devices. Bavarian automotive plants integrate supplied air into centralized breathing air compressor networks serving multiple assembly lines.
China
GB standards for occupational respiratory protection tighten compliance requirements across Yangtze River Delta manufacturing zones. MEE enforcement of workplace exposure limits accelerates upgrades in semiconductor fabrication facilities. Shandong Peninsula chemical processors specify oil-free scroll compressors to eliminate hydrocarbon contamination risk.
Japan
METI industrial safety guidelines elevate positive-pressure system requirements for confined space entries. JIS certification standards for supplied air respirators establish minimum airflow benchmarks that manufacturers must satisfy. Kansai region pharmaceutical manufacturers deploy powered air purifying respirators in cleanroom environments.
India
BIS respiratory protection standards expand certification requirements for manufacturing sector employers. Factories Act enforcement drives replacement demand among Maharashtra chemical processors. Gujarat petrochemical operators consolidate procurement under integrated safety contracts with bundled gas detection equipment.
Supplied Air Respirators Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across product architecture tiers. The market structure concentrates around integrated breathing apparatus portfolios and modular platform architectures that reduce spare parts complexity. Three archetypes dominate: full-line respiratory protection specialists, diversified industrial safety conglomerates, and regional fabrication specialists serving niche certification requirements. Competitive moves center on long-term service contract anchoring and technology licensing for positive pressure configurations.
Within the integrated portfolio tier, MSA Safety and Honeywell International Inc. represent archetypes of full-line respiratory protection coverage. Drägerwerk AG & Co. KGaA exemplifies the engineering-intensive specialist model focused on positive pressure systems. These three anchors occupy positions that span industrial manufacturing, emergency services, and healthcare application verticals through differentiated certification strategies and service network density.
| Leading Market Players |
|---|
| 3M Company |
| Honeywell International Inc. |
| MSA Safety |
| Avon Protection |
| Drägerwerk AG & Co. KGaA |
| Bullard |
| Alpha Pro Tech |
| ILC Dover |
| Lakeland Industries |
| Others |
Value Chain & Pricing Dynamics
Large chemical processors and petroleum refiners consolidating respiratory protection procurement under centralized safety budgets anchor contract-based pricing that bundles equipment, maintenance, and certification services into multi-year agreements.
Pricing Analysis
Bundled service contracts versus unbundled equipment-only transactions split the market into divergent pricing models. Three-tier pricing structure across premium, standard, and economy levels separates NIOSH-certified positive pressure systems from industrial-grade continuous flow units and rental fleet configurations. Price differentiation rests on certification grade and after-sales service intensity. Cost compression in economy-tier rental equipment is intensifying because distributor consolidation squeezes standalone compressor lessors. Construction contractors show highest price sensitivity while petrochemical operators prioritize total cost of ownership over unit acquisition cost.
Supply Chain Analysis
Direct-to-refinery channels handle hyperscale buyer demand while industrial safety distributors serve mid-sized chemical processors through bundled procurement programs. Manufacturing concentrates in the United States, Germany, and China where NIOSH, CE marking, and GB standards compliance capabilities cluster. Breathing air compressor systems draw from precision-machined aluminum castings, high-efficiency filtration media, and specialized synthetic lubricants. Single-source vulnerability in lightweight thermoplastic hose assemblies creates supply chain risk. Distribution runs through integrated safety distributors capturing respiratory protection spend alongside gas detection and fall protection equipment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Service contract anchoring and predictive maintenance platform deployment represent margin-expansion pathways as buyers shift from capital procurement to outcome-based safety spending.
For Market Incumbents: Acquire remote monitoring and telemetry technology assets to capture predictive maintenance revenue streams. MSA Safety and Honeywell International Inc. should consolidate aftermarket service networks in the Ohio River Valley manufacturing corridor before distributor exclusivity windows close. Backward integration into breathing air compressor filtration media production defends against raw material cost volatility from specialty chemical suppliers. For New Entrants and Emerging Players: Capture technical rescue equipment demand in mid-sized municipal fire departments transitioning from SCBA-only to combined supplied air platforms. White-space concentration sits in 300-foot hose reach airline respirators for urban trench rescue scenarios where mutual aid agreements standardize equipment interoperability. Grant-funded procurement cycles through FEMA assistance to firefighter programs provide the most penetrable entry pathway. For Investors and Strategic Acquirers: Industrial safety conglomerates are the most active acquirer in this space, seeking positive pressure system specialists with NIOSH certification pipelines. Long-term viability hinges on regulatory enforcement durability across OSHA silica rules and EPA chemical facility safety mandates. Watch state-level process safety management inspection intensity in California and Texas as the inflection indicator for replacement cycle acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Service Contract Anchoring | Multi-year agreements with Louisiana refiners lock out competitor aftermarket access. |
| Predictive Maintenance Platform | Pressure sensor telemetry integration opens recurring revenue from Ohio River Valley processors. |
| NIOSH Certification Pipeline Investment | Accelerated approval timelines for positive pressure configurations capture confined space demand. |
| Oil-Free Compressor Technology Transition | Gulf Coast petrochemical operators convert ahead of EPA secondary containment enforcement. |
| Distributor Exclusivity Agreements | Integrated safety contracts in the Ohio River Valley bundle respiratory protection with gas detection. |
Study Parameters
Multiple input streams — safety equipment procurement managers at petrochemical refineries, respiratory protection program administrators, industrial distributor category heads, and aftermarket service technicians — were reconciled with secondary validation from OSHA enforcement databases, NIOSH certification records, and SEC filings of publicly traded safety equipment manufacturers. Bottom-up equipment shipment analysis and top-down industrial safety spending estimates were triangulated to anchor market sizing.
Data-stream reconciliation across product type, application vertical, end-user industry, and technology architecture dimensions shaped the analytical framework over the projection horizon. CAGRs were derived from replacement cycle modeling tied to regulatory audit frequencies and fleet age distributions. Silica exposure rule enforcement timelines and confined space rescue protocol modernization served as industry-specific forecast inputs.
Regulatory enforcement intensity shifts, breathing air compressor certification bottlenecks, and distributor consolidation patterns are the dominant revision risks to modeled outcomes. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Safety Equipment and Personal Protective Equipment (PPE)
Safety Eyewear Market
Safety Equipment and Personal Protective Equipment (PPE)
US Personal Protective Equipment Market
Safety Equipment and Personal Protective Equipment (PPE)
Global Guns Safes Market
Safety Equipment and Personal Protective Equipment (PPE)
Electrical Safety Gloves Market
Safety Equipment and Personal Protective Equipment (PPE)
Safety Instrumentation Systems Market
Safety Equipment and Personal Protective Equipment (PPE)
Passenger Emergency Oxygen Deployment Systems Market
Safety Equipment and Personal Protective Equipment (PPE)
Saudi Arabia Personal Protective Equipment Market
Safety Equipment and Personal Protective Equipment (PPE)
Global Respiratory Protection Equipment (RPE) Market
Safety Equipment and Personal Protective Equipment (PPE)
FFP2 Grade Medical Protective Mask Market
Safety Equipment and Personal Protective Equipment (PPE)
North America Respiratory Protective Equipment (RPE) Market
Safety Equipment and Personal Protective Equipment (PPE)
Smart Hazard and Safety Indicator Control Modules Market
Safety Equipment and Personal Protective Equipment (PPE)
Pest Control Devices Market
Safety Equipment and Personal Protective Equipment (PPE)
Bullet Proof Jackets Market
Safety Equipment and Personal Protective Equipment (PPE)
Firefighter Tape Market
Safety Equipment and Personal Protective Equipment (PPE)
Flu Protection Kits Market
Safety Equipment and Personal Protective Equipment (PPE)
North America Process Safety Services Market