
 Plastics in Personal Protective Equipment Market | 2026-2036
Plastics in Personal Protective Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Plastics in Personal Protective Equipment Market Intelligence
China is reconfiguring regional supply dynamics through expanded polypropylene compounding capacity serving PPE converters. BASF leverages integrated polyamide production for high-performance glove membranes in European medical markets. SABIC anchors Middle Eastern feedstock advantages into specialty polyethylene grades for chemical protective suits. Evonik Industries AG differentiates through transparent polycarbonate shield formulations that sustain optical clarity under repeated sterilization cycles.
Plastics in personal protective equipment encompass engineered thermoplastics and elastomers formulated into barriers against biological, chemical, and physical hazards, typically requiring tensile strength above 15 MPa and compliance with permeation resistance standards for target agents. Polypropylene dominates mask melt-blown layers and spunbond cover stocks due to favorable charge retention and breathability trade-offs. Polyethylene competes aggressively in glove segments where cost-per-unit sensitivity among industrial buyers shapes procurement patterns. Nylon occupies premium positions in reusable chemical protective apparel where abrasion resistance and thermal stability justify higher material outlays.
OSHA enforces permissible exposure limits that mandate minimum barrier performance, while EU MDR requires biocompatibility documentation for plastics contacting skin or mucosa during extended clinical use. China's NMPA and GB standards institute pre-market testing protocols that foreign suppliers must navigate for domestic distribution clearance. Stakeholders must monitor regulatory divergence between jurisdictions as compliance costs fragment pricing architectures and reshape sourcing footprints across the value chain.
Market Dynamics
Healthcare procurement consolidation and regulatory fragmentation across OSHA, EU MDR, and China's NMPA are forcing material suppliers to maintain parallel certification portfolios while polypropylene compounding capacity concentrates in East Asia.
Growth Catalysts
- OSHA Permissible Exposure Limits:Stricter workplace chemical exposure mandates in US industrial settings are expanding demand for multilayer barrier films in chemical protective suits.
- China's NMPA Pre-Market Testing:Domestic certification requirements for foreign PPE suppliers are accelerating localized production investments by global compounders seeking market access.
- Melt-Blown Polypropylene Charge Retention:Electret treatment advances in mask filtration media are sustaining replacement cycles for N95 and surgical respirator stockpiles.
Market Restraints
- Propylene Feedstock Volatility:Crude-linked monomer pricing swings compress converter margins on fixed-price hospital supply contracts.
- Spunbond Concentration in Zhejiang Province:Single-region dependence for nonwoven substrate production creates exposure to port congestion and energy rationing disruptions.
- EU MDR Biocompatibility Documentation:Extended clinical data requirements for skin-contacting plastics are lengthening time-to-market for new glove formulations by 18-24 months.
Strategic Opportunities
- India's PLI Scheme for Medical Textiles:Production-linked incentives for domestic PPE manufacturing are attracting compounding joint ventures in Gujarat and Tamil Nadu.
- Reusable Chemical Apparel Nylon Formulations:Industrial laundries are specifying high-tenacity polyamide blends with 50+ wash cycles to reduce disposable gown waste volumes.
- Direct Hospital Contracting Platforms:E-procurement portals are disintermediating distributor networks for high-volume glove and gown categories.
Industry Challenges
- Electret Stability Expertise Gap:Formulators with deep knowledge of charge retention degradation under gamma sterilization remain scarce relative to capacity expansion needs.
- Multijurisdictional Certification Parallelism:Simultaneous FDA, CE marking, and NMPA dossier preparation strains regulatory affairs teams without harmonized testing protocols.
- Legacy ERP Integration with Track-and-Trace:Batch-level serialization requirements under EU MDR and US DSCSA are forcing mid-tier converters to replace aging manufacturing execution systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Plastics in Personal Protective Equipment Market |
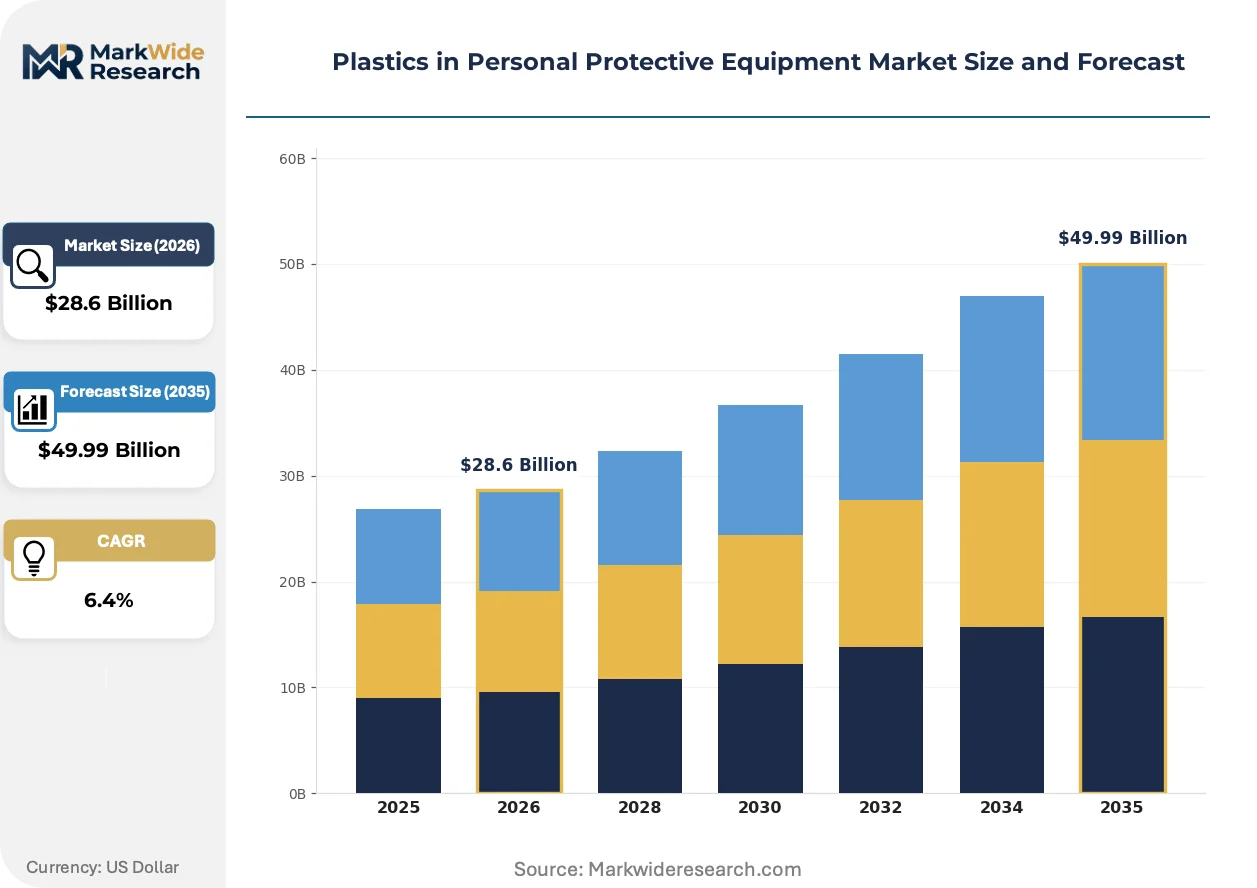
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $49.99 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Gloves, Masks, Gowns, Face Shields Material Type: Polyethylene, Polypropylene, PVC, Nylon End User: Healthcare, Industrial, Laboratory, Construction Application: Infection Control, Chemical Protection, Hazardous Environments, Biohazard Handling |
| Companies Covered | BASF, SABIC, Celanese Corporation, Evonik Industries AG, Sumitomo Chemical Co., Ltd., Arkema, Eastman Chemical Company, Chevron Phillips Chemical Company LLC, Exxon Mobil Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Plastics in Personal Protective Equipment Market Strategic Shifts & Innovations
Material science convergence with digital manufacturing is compressing development cycles for customized barrier properties while regulatory data requirements reshape competitive moats around formulation IP.
Smart extrusion control systems are digitizing real-time melt rheology adjustments during spunbond production. Medical nonwoven converters in Germany and the US are deploying these platforms to reduce basis weight variability below 3% standard deviation. The technology is digitizing quality assurance labor out of high-speed lines while enabling lot-specific digital certificates for hospital procurement systems.
EU MDR's post-market surveillance obligations are mandating systematic clinical follow-up for all skin-contacting plastics. Compounders must now maintain vigilance databases tracking adverse event reports across European notified body jurisdictions. The regulation is compressing smaller suppliers lacking pharmacovigilance infrastructure while favoring integrated chemical-medical device conglomerates with existing complaint handling systems.
Hospital group purchasing organizations are consolidating specification authority for disposable gloves into centralized formulary committees. Industrial safety distributors are losing direct access to individual facility purchasing managers as IDN procurement platforms absorb volume aggregation. The shift is most visible in US acute care networks exceeding 50 hospital affiliates, where standardized barrier performance metrics are displacing brand preference in award decisions.
Plastics in Personal Protective Equipment Market Segmentation
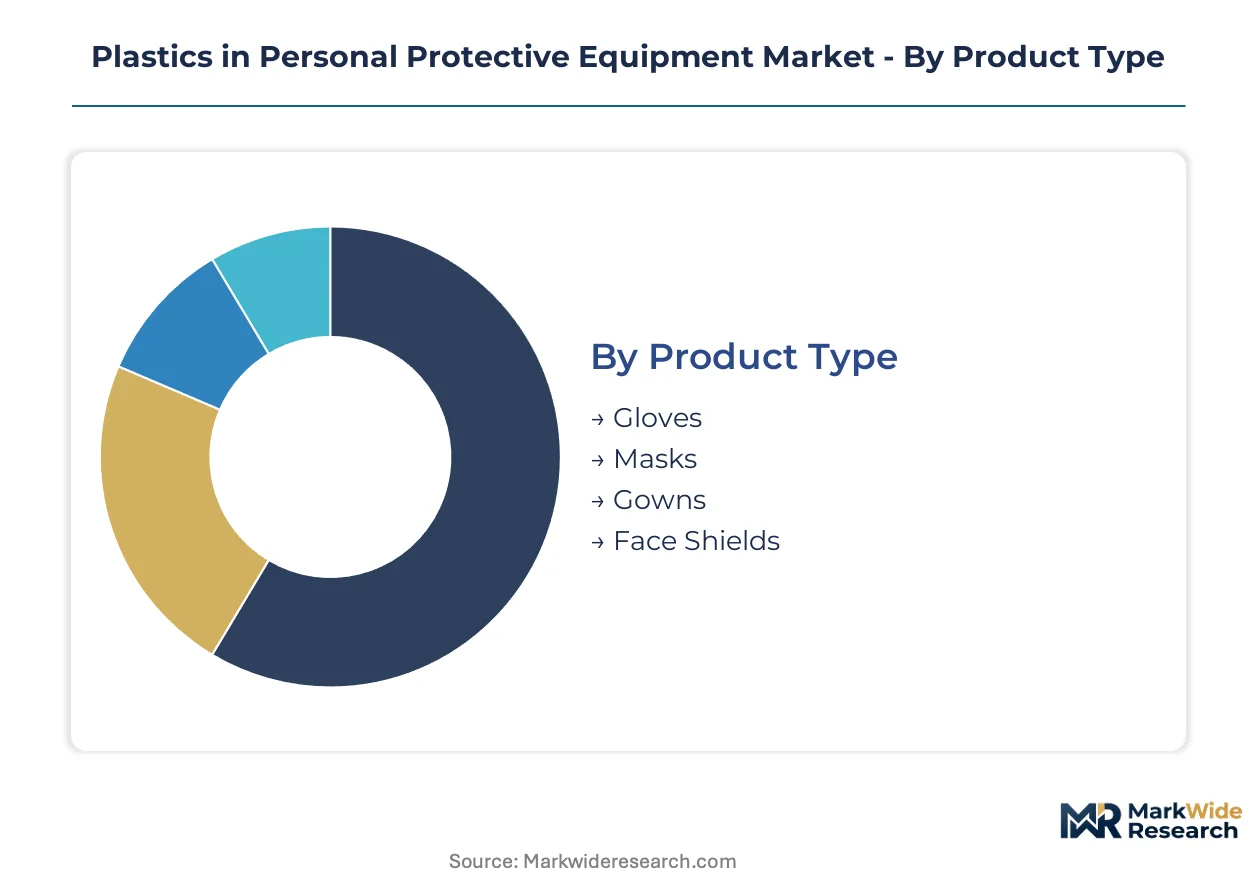
Barrier performance requirements diverge sharply across PPE categories, forcing material suppliers to maintain parallel formulation portfolios optimized for either disposable throughput or reusable durability. Segmentation clarity enables compounders to align R&D spending with the specific permeation, tensile, and biocompatibility thresholds governing each product class.
Product Type:
Mature categories dominate procurement volumes while emerging formats reshape specification standards through advanced barrier integration.
- Gloves:Nitrile and latex alternatives formulated from thermoplastic elastomers and polyethylene blends deliver puncture resistance above 3.5 MPa for clinical and chemical handling. Hospital procurement consolidation in the US and Germany is compressing SKU counts while elevating lot traceability requirements.
- Masks:Melt-blown polypropylene electret layers with 0.3-micron filtration efficiency anchor N95 and surgical respirator construction. China's Zhejiang and Hubei provinces concentrate spunbond substrate capacity serving both domestic stockpiles and export markets.
- Gowns:Spunbond-meltblown-spunbond laminates provide AAMI Level 1-4 fluid resistance for isolation and surgical applications.
- Face Shields:Transparent polycarbonate and polyethylene terephthalate glycol formulations maintain optical clarity through repeated sterilization cycles.
Gloves handle the majority of throughput; face shields are gaining share fastest as integrated head protection protocols expand beyond acute care into industrial settings.
Material Type:
Cost tier positioning separates commodity thermoplastics from engineered grades commanding certification premiums.
- Polyethylene:Low-density and linear low-density grades dominate industrial glove segments where cost-per-unit sensitivity shapes procurement patterns among safety distributors. FDA 21 CFR 177.1520 compliance remains mandatory for food-contacting applications in US meatpacking and processing facilities.
- Polypropylene:Isotactic homopolymer and random copolymer grades serve mask filtration media and spunbond cover stocks through favorable charge retention and breathability trade-offs. China's Sinopec and PetroChina are expanding compounding capacity to capture converter demand from domestic PPE manufacturers.
- PVC:Plasticized formulations provide chemical resistance in industrial gauntlets and protective aprons for laboratory environments.
- Nylon:High-tenacity polyamide 6 and 6,6 grades occupy premium positions in reusable chemical protective apparel where abrasion resistance and thermal stability justify higher material outlays.
Polypropylene commands the largest volume position; nylon is climbing the fastest as industrial laundries specify 50-plus wash cycle durability to reduce disposable waste.
End User:
Customer type fragmentation creates divergent specification regimes across regulated and self-certified procurement channels.
- Healthcare:Acute care networks and outpatient clinics drive demand for disposable gloves, masks, and gowns meeting FDA and EU MDR biocompatibility documentation requirements. US hospital group purchasing organizations are consolidating formulary authority into centralized procurement platforms.
- Industrial:Manufacturing, oil and gas, and chemical processing facilities specify chemical protective suits and hand protection against OSHA permissible exposure limits for solvents and corrosives.
- Laboratory:Research institutions and diagnostic facilities require barrier integrity against biological agents and chemical splashes.
- Construction:Site safety protocols mandate impact-resistant face shields and protective eyewear for welding and grinding operations.
Healthcare absorbs the dominant share of material throughput; industrial end-use is expanding most quickly as OSHA enforcement tightens across manufacturing sectors.
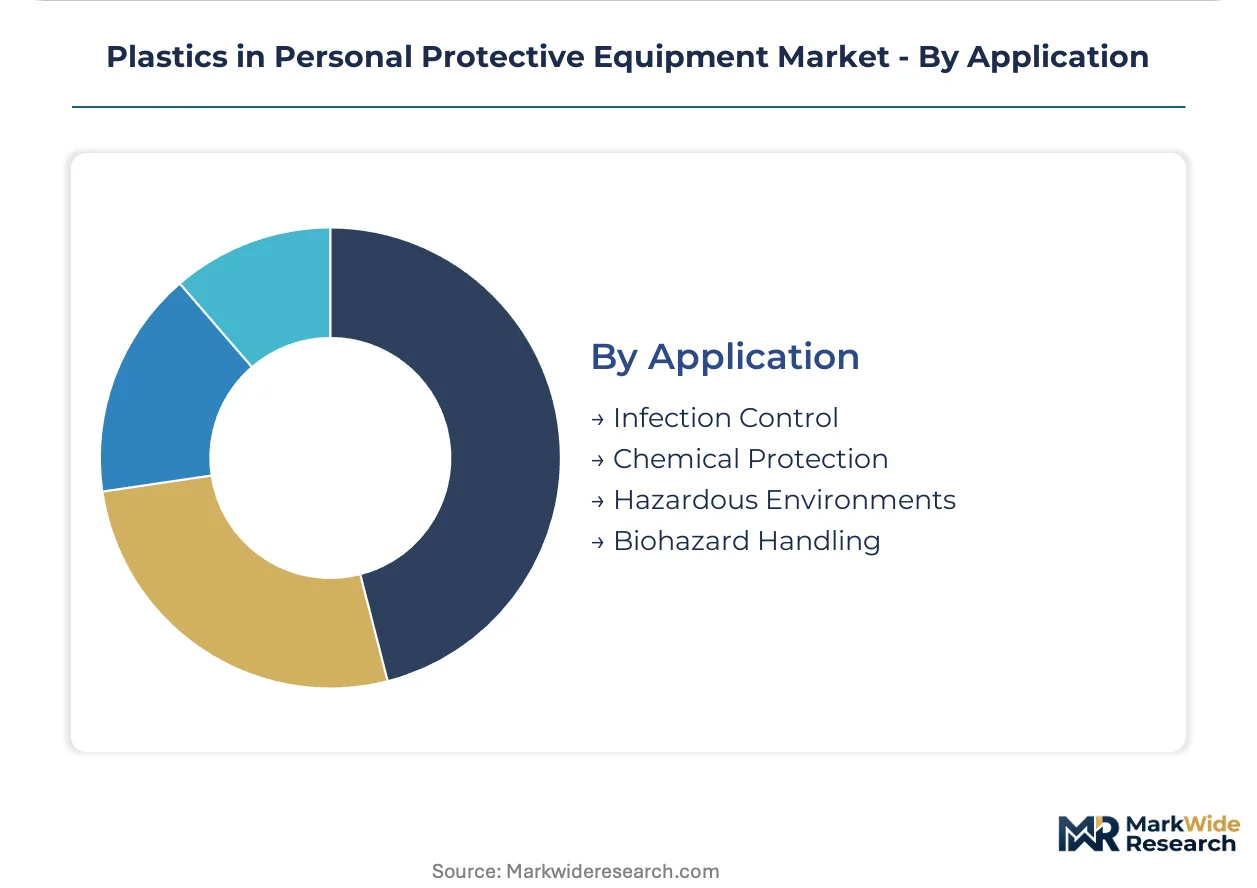
Application:
Functional risk categories determine the severity of barrier performance validation and certification depth.
- Infection Control:Gloves, masks, and gowns engineered for viral and bacterial barrier protection in clinical settings require ISO 22609 and ASTM F2100 compliance. EU MDR post-market surveillance obligations now mandate systematic clinical follow-up for all skin-contacting plastics in this category.
- Chemical Protection:Multilayer barrier films and encapsulated suit designs must demonstrate permeation resistance against specific agent lists under ASTM F739 and EN 374 testing protocols.
- Hazardous Environments:Fire-resistant and arc-flash protective apparel incorporates flame-retardant polymer additives for electrical utility and petrochemical applications.
- Biohazard Handling:Biosafety level 3 and 4 laboratory protocols specify sealed seam construction and positive-pressure ventilation integration for maximum containment scenarios.
Infection control represents the steepest expansion trajectory; chemical protection maintains the most stringent margin structure due to specialized testing and certification requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Polypropylene compounding capacity clusters in Zhejiang and Hubei provinces, with Chinese converters capturing export share through integrated spunbond-meltblown lines. Regulatory divergence between OSHA, EU MDR, and China's NMPA fragments certification requirements across major demand centers.
United States
Hospital group purchasing organizations consolidate formulary authority for disposable gloves and gowns across integrated delivery networks exceeding 50 affiliates. OSHA enforces permissible exposure limits mandating multilayer barrier films in chemical protective suits for manufacturing and petrochemical workers. Texas and Louisiana host specialty polyethylene compounders serving Gulf Coast industrial safety distributors.
Germany
EU MDR post-market surveillance obligations mandate systematic clinical follow-up for skin-contacting plastics, compressing smaller suppliers lacking pharmacovigilance infrastructure. Medical nonwoven converters deploy smart extrusion control systems to reduce basis weight variability below 3% standard deviation. The Rhine-Ruhr industrial corridor concentrates chemical protective apparel manufacturers specifying high-tenacity polyamide blends.
China
NMPA pre-market testing protocols for foreign PPE suppliers accelerate localized production investments by global compounders seeking domestic distribution clearance. Domestic PPE manufacturing scales through Sinopec and PetroChina polypropylene expansion serving mask melt-blown and spunbond cover stock demand. Zhejiang Province concentrates nonwoven substrate production, creating exposure to port congestion and energy rationing disruptions.
India
PLI scheme production-linked incentives for medical textiles attract compounding joint ventures in Gujarat and Tamil Nadu. Central Drug Standard Control Organization regulates biocompatibility documentation for plastics contacting skin during extended clinical use. Ahmedabad and Chennai industrial clusters emerge as alternative supply bases reducing dependence on Chinese spunbond imports.
Saudi Arabia
SABIC anchors Middle Eastern feedstock advantages into specialty polyethylene grades for chemical protective suits serving regional petrochemical and oilfield operations. Saudi Food and Drug Authority implements pre-market testing aligned with international barrier performance standards. The Eastern Province industrial zone around Jubail concentrates polymer production integrated with downstream PPE converter relationships.
Plastics in Personal Protective Equipment Market Key Industry Players
Platform integrators command the system tier; component specialists sit upstream supplying certified resin grades to converters. The vendor base stratifies across integrated chemical conglomerates with captive polymer production, independent compounders serving regional converter networks, and specialized electret treatment technology providers. Three archetypes dominate: feedstock-integrated multinationals, formulation-focused compounders, and electret stability specialists. Capacity expansion and backward integration into monomer supply represent the dominant competitive moves.
Among feedstock-integrated multinationals, BASF and SABIC exemplify the archetype of chemical conglomerates leveraging integrated polymer production for medical and industrial barrier applications. Evonik Industries AG occupies a position within the formulation-specialist tier, representing compounders differentiated through transparent polycarbonate shield formulations. These three entities anchor the competitive structure without exhaustively mapping participant positions.
| Leading Market Players |
|---|
| BASF |
| SABIC |
| Celanese Corporation |
| Evonik Industries AG |
| Sumitomo Chemical Co., Ltd. |
| Arkema |
| Eastman Chemical Company |
| Chevron Phillips Chemical Company LLC |
| Exxon Mobil Corporation |
| Others |
Cost & Logistics Intelligence
Yantian Port freight corridors connecting Zhejiang spunbond producers to Rotterdam and Los Angeles route cost volatility through polypropylene compounder margins, compressing converter pricing power while amplifying tier separation between FDA-certified medical grades and industrial safety stock.
Pricing Analysis
EU MDR dictates the pricing tier structure across skin-contacting plastics, separating biocompatibility-documented medical grades from industrial safety materials. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification depth, with FDA 510(k) pathways commanding 40-60% premiums over self-certified industrial alternatives. Cost compression in standard-grade polyethylene gloves is intensifying because hospital GPO formulary consolidation favors volume aggregation over brand loyalty. Industrial safety distributors exhibit highest price sensitivity, while integrated delivery networks with captive laundry operations absorb premium nylon formulations for reusable chemical apparel.
Supply Chain Analysis
Specialized electret treatment providers and spunbond-meltblown converters in Zhejiang, Hubei, and Thuringia hold concentrated capacity serving mask filtration media demand. Propylene monomer, melt-blown polypropylene resin, and electret charging equipment constitute critical input dependencies. Single-source vulnerability in Zhejiang Province nonwoven substrate production exposes downstream converters to energy rationing and port congestion disruptions. Distribution runs through hospital group purchasing organizations and industrial safety distributors, with direct-to-hospital e-procurement portals disintermediating traditional channel networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Hospital procurement consolidation across US integrated delivery networks exceeding 50 affiliates has shifted bargaining power decisively toward buyers, fragmenting supplier pricing autonomy and elevating lot traceability requirements above brand preference.
For Market Incumbents: Harden regulatory dossier capabilities against EU MDR post-market surveillance obligations by embedding pharmacovigilance infrastructure that smaller compounders cannot replicate. Deepen backward integration into polypropylene compounding capacity within India PLI scheme jurisdictions to defend margin position against Chinese export pricing. Electret stability expertise retention represents the critical defensive moat as gamma sterilization protocols proliferate. For New Entrants and Emerging Players: Build out localized production platforms in Gujarat and Tamil Nadu to capture PLI-linked medical textile incentives while Chinese spunbond imports face regulatory friction. Target India's CDSCO certification pathway for skin-contacting plastics as the most penetrable regulatory entry point. Direct hospital contracting platforms offer disintermediated access bypassing entrenched distributor relationships. For Investors and Strategic Acquirers: Formulation-specialist compounders with captive electret treatment capabilities and EU MDR vigilance databases present asymmetric upside acquisition targets. Long-term viability centers on regulatory data assets rather than commodity resin throughput. Watch NMPA pre-market testing timeline compression as the inflection signal indicating Chinese market access premium realization.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polypropylene Compounding | Sinopec and PetroChina expansion demonstrates feedstock control securing converter relationships. |
| EU MDR Pharmacovigilance Infrastructure Buildout | Systematic clinical follow-up databases compress smaller suppliers lacking complaint handling systems. |
| India PLI Scheme Joint Venture Formation | Gujarat and Tamil Nadu clusters reduce dependence on Chinese spunbond substrate imports. |
| Direct Hospital E-Procurement Platform Launch | IDN procurement systems disintermediate distributor networks for high-volume glove categories. |
| Electret Stability R&D Partnership | Gamma sterilization protocol proliferation deepens expertise scarcity relative to capacity expansion. |
Research Approach
Cross-validation between primary interviews with polymer compounders, hospital procurement managers, industrial safety distributors, and regulatory affairs specialists anchors the qualitative findings against secondary validation from FDA 510(k) filings, EU MDR notified body databases, NMPA registration records, and customs trade data. Bottom-up volume modeling from individual PPE category consumption patterns triangulates against top-down resin demand estimates from polypropylene and polyethylene producer disclosures.
Calibration against historical CAGR realization rates across medical plastics and industrial safety materials sectors informs the projection framework. Segmentation dimensions span product type, material grade tier, end-use industry, and regional regulatory cluster. Electret treatment technology diffusion curves and hospital GPO formulary consolidation timelines constitute industry-specific forecast inputs. Growth rates derive from elasticity-adjusted demand modeling rather than extrapolation.
Stress conditions across propylene feedstock volatility, Zhejiang port congestion duration, and EU MDR clinical data requirement stringency were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding OSHA enforcement intensity and NMPA market access liberalization. Quarterly review of electret stability patent filings and GPO contract award announcements is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Safety Equipment and Personal Protective Equipment (PPE)
North America Self-Contained Breathing Apparatus Market
Safety Equipment and Personal Protective Equipment (PPE)
Smart Hazard and Safety Indicator Control Modules Market
Safety Equipment and Personal Protective Equipment (PPE)
Protective Goggles Market
Safety Equipment and Personal Protective Equipment (PPE)
Saudi Arabia Personal Protective Equipment Market
Safety Equipment and Personal Protective Equipment (PPE)
N95 Mask Market
Safety Equipment and Personal Protective Equipment (PPE)
In Room Safes Market
Safety Equipment and Personal Protective Equipment (PPE)
Digital Camlock Market
Safety Equipment and Personal Protective Equipment (PPE)
Industrial Personal Protective Equipment Market
Safety Equipment and Personal Protective Equipment (PPE)
Isolation Gloves Market
Safety Equipment and Personal Protective Equipment (PPE)
Global above the Waist PPE Market
Safety Equipment and Personal Protective Equipment (PPE)
Global Surgical Mask and Respirators Market
Safety Equipment and Personal Protective Equipment (PPE)
Supplied Air Respirators Market
Safety Equipment and Personal Protective Equipment (PPE)
Middle East and Africa Intrinsically Safe Equipment Market
Safety Equipment and Personal Protective Equipment (PPE)
Non Ionizing Radiation/EMF Detection, Measurement, and Safety Market
Safety Equipment and Personal Protective Equipment (PPE)
Global Explosion Proof Equipment Market
Safety Equipment and Personal Protective Equipment (PPE)
Global Protective Face Mask Market