
 Global Respirator Filter Market | 2026-2036
Global Respirator Filter Market Size, Share, and Industry Trends Forecast 2026-2036
Global Respirator Filter Market Foresight
Activated carbon is restructuring cost-performance tradeoffs across the respirator filter supply chain as manufacturers substitute traditional cellulose media with synthetic fiber blends. 3M leverages its captive materials science portfolio to sustain pricing power in cartridge filters for industrial hygiene applications. Honeywell International anchors North American distribution through its safety equipment channel network. Drägerwerk AG & Co. KGaA competes on certification breadth, dominating European regulatory compliance for combination filter designs.
A respirator filter is a replaceable or integral component within a respiratory protective device, typically constructed from melt-blown polypropylene, activated carbon granules, or glass microfiber matrices with pore ratings from N95 to P100, designed to remove particulate matter, gases, vapors, or biological aerosols from inhaled air before it reaches the user's respiratory system. Disposable filters retain volume leadership in high-turnover construction and mining environments where contamination events mandate immediate replacement. Reusable filters with replaceable cartridges are capturing margin pools in manufacturing plants and chemical processing facilities where total cost-of-ownership calculations favor extended service life. HEPA and ULPA filtration technologies are penetrating healthcare and environmental safety applications as stakeholders prioritize near-absolute particulate capture efficiency.
NIOSH certification requirements in the United States, CE marking under the EU Personal Protective Equipment Regulation, and GB standards administered by China's SAMR collectively determine market access thresholds and product testing protocols for respirator filters sold across major economies. OSHA enforcement of silica exposure limits and the EU's REACH restrictions on hazardous substances are directly expanding replacement filter consumption as employers retrofit legacy equipment to meet stricter protection factors. Stakeholders must monitor divergence between regional certification standards, as misalignment between NIOSH flow rates and European EN test protocols is fragmenting product platforms and complicating global manufacturing scale.
Market Dynamics
OSHA's tightened silica exposure limits are forcing manufacturing plants across the United States to abandon disposable filters for higher-efficiency cartridge systems, compressing replacement cycles and elevating specification standards throughout industrial supply chains.
Growth Catalysts
- REACH substance restrictions:European employers face mandatory equipment upgrades as ECHA expands hazardous substance controls, accelerating filter replacement rates in chemical processing facilities.
- India's industrial corridor expansion:Chemical plants and construction sites stretching from Mumbai to Pune are generating concentrated demand for combination particulate-gas filters.
- Powered air-purifying respirators:Healthcare systems across Southeast Asia are expanding procurement for infectious disease control, driving premium filter attachment rates.
Market Restraints
- Activated carbon supply volatility:Coconut shell and coal-based carbon feedstocks face price instability from Southeast Asian sourcing disruptions.
- NIOSH-EN protocol divergence:Misaligned flow rate testing standards between United States and European certification bodies fragment product platforms and prevent manufacturing scale.
- Electrostatic filter durability limits:Synthetic fiber media lose charge degradation protection in high-humidity environments, constraining tropical market penetration.
Strategic Opportunities
- GB standard harmonization:China's SAMR is consolidating respirator testing protocols, creating pathways for multinational manufacturers to streamline China-bound product lines.
- Wearable sensor convergence:Integration of real-time filter loading monitors with IoT-enabled respirators opens predictive replacement service models.
- Environmental remediation:Asbestos abatement and wildfire smoke response are emerging as specialized high-margin filter applications in Australia and western Canada.
Industry Challenges
- Multi-certification engineering complexity:Product teams must simultaneously satisfy NIOSH, CE marking, and GB standard requirements, extending development timelines.
- Filter-to-facepiece integration testing:Legacy respirator platforms require costly revalidation when cartridge interfaces are modified for new filter media.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Respirator Filter Market |
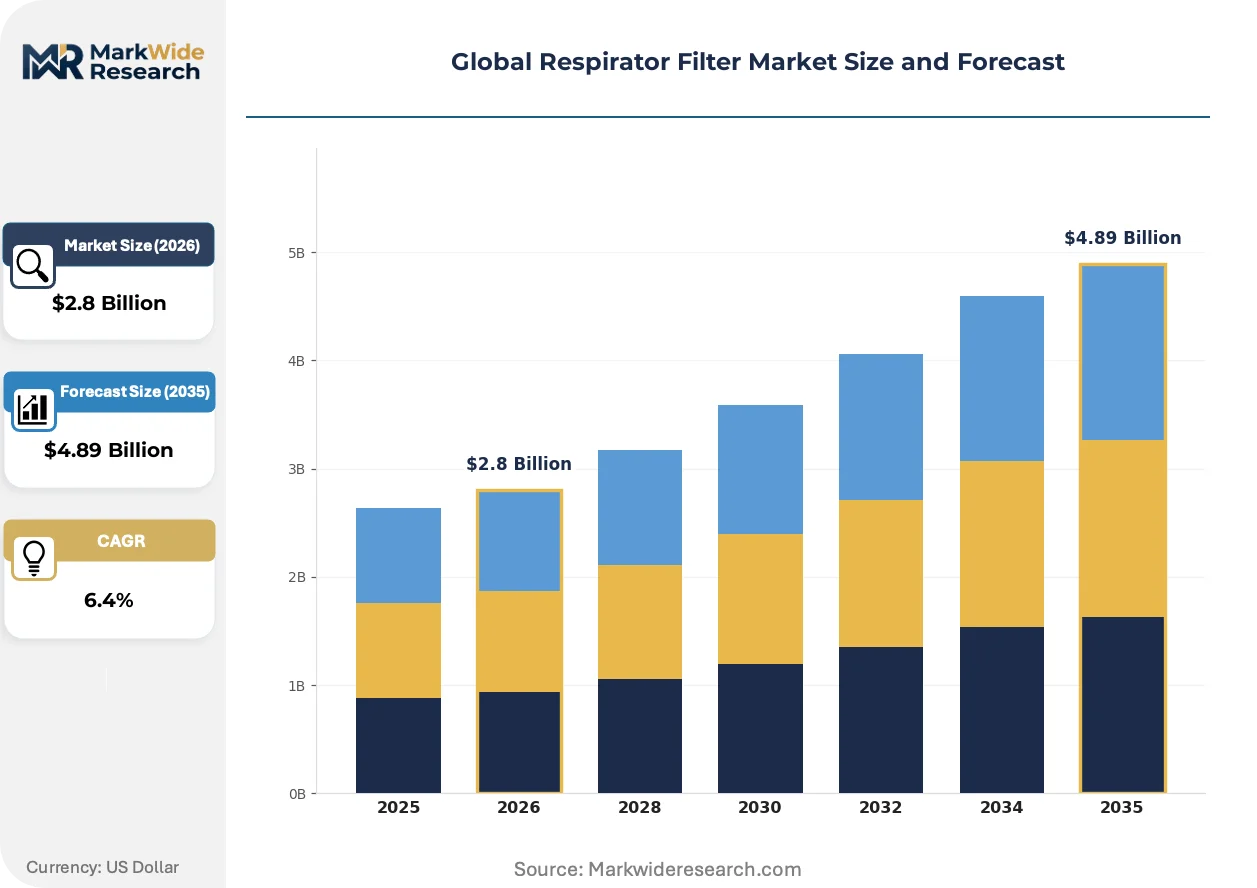
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.89 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Disposable Filters, Reusable Filters, Cartridge Filters, Combination Filters Filtration Technology: Mechanical Filters, Electrostatic Filters, Activated Carbon, HEPA Filters, ULPA Filters End User Industry: Manufacturing Plants, Construction Sites, Chemical Processing, Mining Operations, Firefighting Units Application: Particulate Matter Filtration, Gas & Vapor Filtration, Respiratory Protection, Industrial Hygiene, Environmental Safety |
| Companies Covered | 3M, Honeywell International, Drägerwerk AG & Co. KGaA, MSA Safety, Moldex-Metric, Kimberly-Clark, Solventum, ResMed, Fisher & Paykel Healthcare, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Respirator Filter Market Shifts & Advancements
Electrospun nanofiber media, real-time breathing resistance sensors, and consolidated procurement platforms are restructuring how filters are engineered, monitored, and purchased across industrial and healthcare verticals.
Synthetic nanofiber filtration layers are decentralizing manufacturing footprints by enabling regional producers to achieve N95-equivalent performance without melt-blown polypropylene supply dependencies. Chemical processing facilities in Germany and the United States are adopting these materials for beryllium and hexavalent chromium protection. The technology is decentralizing supply chains away from concentrated Asian melt-blown capacity toward distributed regional production.
REACH authorization procedures are compelling filter manufacturers to eliminate phthalate plasticizers and certain flame retardants from elastomeric components. Industrial hygiene purchasers in the European Union now require full material disclosure documentation upstream of procurement decisions. Combination filter designs incorporating both particulate and ABEK gas protection are experiencing the most intensive reformulation pressure.
Consolidated safety equipment distributors are unbundling filter replacement services from respirator hardware sales, shifting toward subscription-based consumption models. Large manufacturing employers in the United States are negotiating enterprise filter supply agreements directly with manufacturers, bypassing traditional channel intermediaries. This restructuring is most visible in automotive assembly and metal fabrication sectors where OSHA inspection intensity has elevated compliance documentation requirements.
Global Respirator Filter Market Segmentation
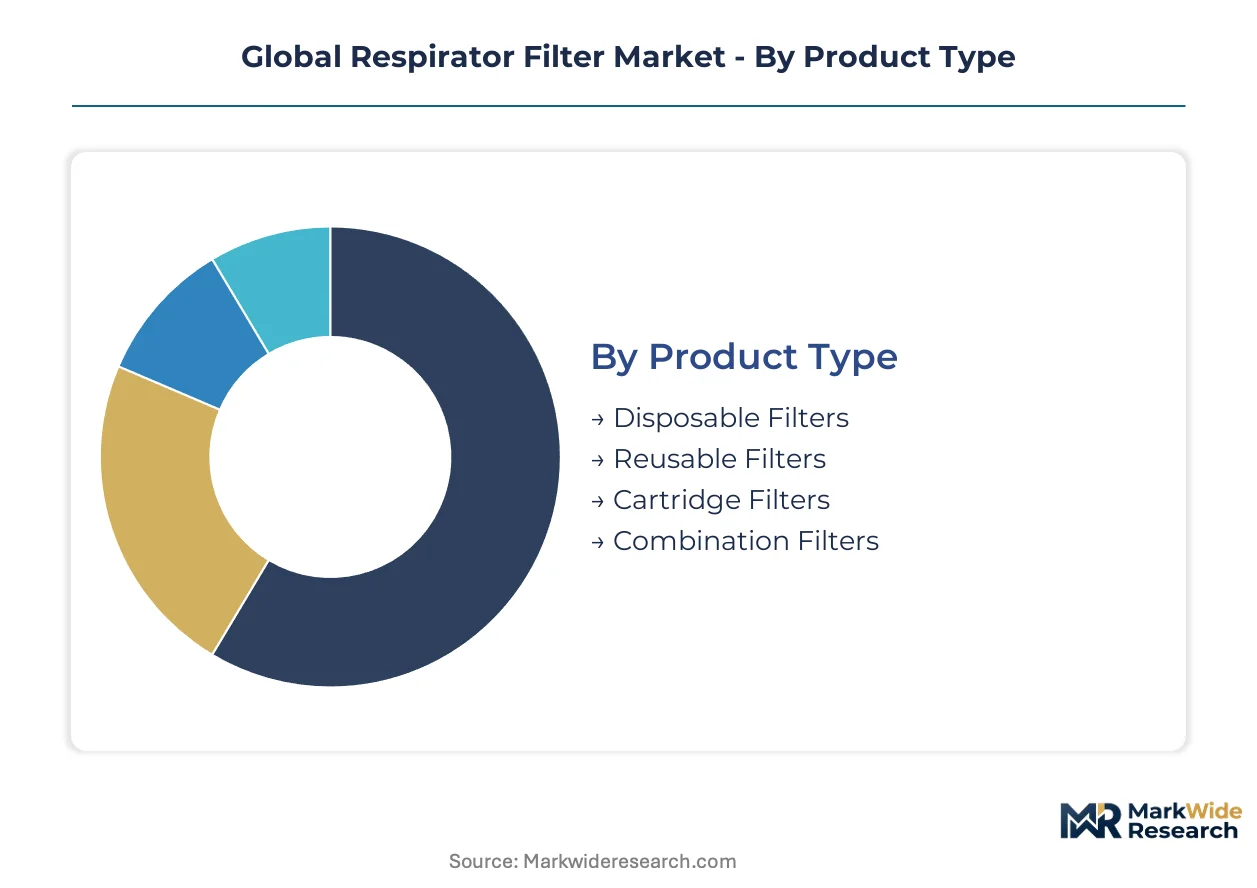
Respirator filter segmentation reveals how certification requirements, replacement economics, and hazard specificity fragment procurement patterns across industrial and healthcare verticals. Understanding these divides clarifies why cartridge systems command premium positioning while disposables dominate volume.
Product Type:
NIOSH certification for disposable filters demands lower testing investment than the multi-protocol validation required for reusable cartridge systems, reshaping manufacturer entry barriers across each tier.
- Disposable Filters:Constructed from melt-blown polypropylene with electrostatic charge enhancement, these single-use units achieve N95 to P100 ratings. Construction sites across the United States and mining operations in Australia's Queensland basin consume these in continuous replacement cycles driven by contamination protocols and OSHA inspection intensity.
- Reusable Filters:Elastomeric facepiece systems with replaceable cartridge interfaces extend service life through cleaning protocols. German chemical processors and Japanese automotive assembly plants favor these for total cost-of-ownership advantages under REACH and JIS regulatory frameworks.
- Cartridge Filters:Modular screw-on designs enable field adaptation to specific hazard profiles. Brazil's petrochemical corridor purchases these for hexavalent chromium protection.
- Combination Filters:Integrated particulate-gas designs require dual NIOSH and CE marking pathways. Firefighting units in France and Saudi Arabia specify these for multi-threat response scenarios.
Disposable filters sit at the top of the volume ranking, with combination filters climbing the fastest.
Filtration Technology:
Technology selection tracks the cost-performance frontier where activated carbon displaces legacy media and nanofiber layers challenge established melt-blown supply chains.
- Mechanical Filters:Glass microfiber matrices with depth-loading architecture capture particles through interception and impaction. India's construction sector from Mumbai to Pune deploys these in cost-sensitive high-dust environments.
- Electrostatic Filters:Charged synthetic fibers achieve high initial efficiency at reduced pressure drop, though humidity degrades performance. Southeast Asian healthcare systems limit deployment to climate-controlled powered air-purifying respirator systems.
- Activated Carbon:Coconut shell and coal-based granules adsorb organic vapors and acid gases. Chemical processing facilities in Germany's Ruhr region and the United States Gulf Coast specify these for benzene and chlorine protection.
- HEPA Filters:99.97% efficiency at 0.3 micron certification for asbestos abatement and healthcare isolation. Canadian wildfire response teams and Australian environmental remediation contractors drive replacement demand.
- ULPA Filters:99.999% efficiency ratings for semiconductor cleanrooms and pharmaceutical aseptic processing. South Korean memory chip fabs and Swiss pharmaceutical packaging lines represent concentrated demand pockets.
Activated carbon holds the broadest installed base, while electrospun nanofiber layers gain share fastest.
End User Industry:
Industry verticals distribute across hazard intensity gradients, with silica-exposed sectors facing the steepest compliance-driven upgrade cycles.
- Manufacturing Plants:Metal fabrication and automotive assembly in the United States Midwest retrofit legacy equipment under OSHA's tightened permissible exposure limits, elevating cartridge specification rates.
- Construction Sites:High-turnover workforces and contamination events mandate disposable filter dominance. Saudi Arabia's Neom infrastructure buildout and Canadian infrastructure stimulus generate concentrated procurement.
- Chemical Processing:Combination filters for multi-gas protection dominate. Facilities along India's Mumbai-Pune corridor and Germany's Ludwigshafen cluster require REACH-compliant material disclosure.
- Mining Operations:Silica and diesel particulate exposure drives premium filter attachment. South African platinum belt and Australian iron ore operations specify P100 and powered air-purifying configurations.
- Firefighting Units:ABEK-rated combination filters for smoke, ammonia, and hydrogen cyanide protection. Urban fire departments in France and the United Arab Emirates standardize on Dräger and MSA platforms.
Construction sites lead absolute volume, with chemical processing expanding most quickly.
Application:
Application segmentation aligns with regulatory hazard classifications, where industrial hygiene and environmental safety categories capture compliance-driven premium pricing.
- Particulate Matter Filtration:N95 through P100 ratings for dust, fume, and mist. China's construction sector under GB standards and the United States under NIOSH protocols represent parallel certification pathways.
- Gas & Vapor Filtration:Activated carbon and catalytic media for organic vapors, acid gases, and ammonia. European chemical plants under ECHA authorization procedures drive specification complexity.
- Respiratory Protection:General-purpose fit-tested systems for multi-hazard environments. Japanese manufacturing under METI guidelines emphasizes compact, low-breathing-resistance designs.
- Industrial Hygiene:Programmatic compliance documentation for OSHA, REACH, and SAMR enforcement. Large employers in the United States automotive sector negotiate direct manufacturer contracts bypassing distributors.
- Environmental Safety:Asbestos abatement, wildfire smoke, and mold remediation. Australian remediation contractors and western Canadian fire response teams specify HEPA and P100 configurations.
Particulate matter filtration anchors volume, with environmental safety gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Mumbai-Pune industrial corridor anchors procurement intensity for combination particulate-gas filters as chemical processing and construction activity intensify simultaneously across India's western manufacturing belt.
United States
OSHA enforcement of tightened silica and beryllium exposure limits compels manufacturing plants in the Midwest automotive belt to upgrade from disposable filters to cartridge systems. Metal fabrication facilities across Michigan and Ohio retrofit legacy equipment under intensified inspection protocols. The Gulf Coast petrochemical cluster drives specification demand for activated carbon configurations.
Germany
ECHA authorization procedures under REACH mandate material disclosure documentation for elastomeric filter components. Chemical processors in the Ruhr region and Ludwigshafen cluster require reformulated combination filters eliminating phthalate plasticizers. German industrial hygiene purchasers now demand upstream supply chain transparency before procurement approval.
China
SAMR consolidation of GB testing standards creates pathways for multinational manufacturers to streamline China-bound product lines. Construction activity under national infrastructure stimulus generates N95 and P100 demand across the Yangtze River Delta. Shanghai-based distributors report accelerating replacement cycles for mechanical filtration media.
Australia
Environmental remediation contractors in Queensland and New South Wales specify HEPA configurations for asbestos abatement operations. Wildfire response teams across Victoria and Western Australia drive seasonal procurement spikes for P100-rated systems. The country's national occupational health regulator enforces fit-testing documentation for all respiratory protection deployments.
Saudi Arabia
NEOM infrastructure construction and urban fire department modernization generate concentrated demand for ABEK-rated combination filters. The Saudi Food and Drug Authority oversees medical-grade respirator import licensing for healthcare system expansion. Petrochemical facilities along the Eastern Province corridor specify multi-gas protection for hydrogen sulfide and ammonia exposure.
Global Respirator Filter Market Competitive Landscape
Global majors compete with regional champions across certification breadth and distribution density, producing a tiered structure where materials science capabilities separate premium positioning from commodity supply. The vendor base concentrates around three strategic archetypes: diversified conglomerates with captive polymer research, specialized safety equipment pure-plays, and healthcare crossovers leveraging respiratory therapy expertise. Competitive moves center on backward integration into activated carbon sourcing and direct enterprise contracting that bypasses traditional distribution channels.
Within the diversified industrial tier, 3M and Honeywell International exemplify scale-driven positioning anchored by materials science portfolios and established channel networks. Drägerwerk AG & Co. KGaA occupies a specialist position representing European regulatory compliance leadership for combination filter designs. These three entities collectively illustrate how certification breadth, geographic coverage, and upstream material control define sustainable positioning across fragmented end-use verticals.
| Leading Market Players |
|---|
| 3M |
| Honeywell International |
| Drägerwerk AG & Co. KGaA |
| MSA Safety |
| Moldex-Metric |
| Kimberly-Clark |
| Solventum |
| ResMed |
| Fisher & Paykel Healthcare |
| Others |
Supply & Pricing Matrix
REACH authorization procedures for phthalate-free elastomeric components gate qualified supply access and premium-tier pricing power for manufacturers serving European chemical processors. Manufacturers lacking upstream material disclosure documentation face exclusion from procurement shortlists at German industrial hygiene purchasers, compressing margins for non-compliant competitors.
Pricing Analysis
Input-cost pass-through from coconut shell and coal-based activated carbon feedstocks is intensifying pricing volatility across cartridge filter tiers. Three-tier pricing structure across premium, standard, and economy levels separates NIOSH-certified industrial systems from CE-marked European configurations and unbranded regional alternatives. Cost compression in standard-tier disposables is intensifying because Southeast Asian melt-blown polypropylene supply disruptions are elevating raw material baselines. Construction site procurement teams in the United States exhibit highest price sensitivity, while German chemical processors under REACH compliance mandates demonstrate lowest elasticity.
Supply Chain Analysis
Warehouse-distribution layer consolidation is restructuring downstream access as Honeywell International and 3M operate regional distribution centers in Chicago, Rotterdam, and Singapore to serve industrial clusters. Manufacturing concentrates in the United States, Germany, and China as NIOSH, CE marking, and GB standard certification requirements anchor production proximity to regulatory expertise. Raw material dependencies center on melt-blown polypropylene, activated carbon granules, and electrospun nanofiber media. Single-source vulnerability from concentrated Southeast Asian carbon feedstock sourcing elevates disruption risk. Distribution runs through consolidated safety equipment channels and direct enterprise contracting with automotive and metal fabrication employers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where OSHA's tightened silica exposure limits generate sustained replacement demand across United States manufacturing plants. Compliance-driven upgrade cycles create predictable revenue visibility for positioned suppliers.
For Market Incumbents: Cement pricing power through backward integration into activated carbon sourcing and captive materials science R&D. Defend against nanofiber substitution threats by accelerating electrospun media platform development. Prioritize certification breadth investments spanning NIOSH, CE marking, and converging GB standards to prevent product platform fragmentation.
For New Entrants and Emerging Players: Begin with environmental safety applications in Australia and western Canada where asbestos abatement and wildfire response generate specialized demand with lower incumbent saturation. Target predictive replacement service models integrating IoT-enabled filter loading monitors as the most penetrable white-space. Pursue direct contracting relationships with mid-sized manufacturing employers bypassing consolidated distributor channels.
For Investors and Strategic Acquirers: Roll-up economics work for regional certification specialists because NIOSH-EN protocol divergence fragments product platforms and prevents manufacturing scale, creating acquisition targets with irreplaceable regulatory expertise. Five-to-ten year viability rests on positioning for GB standard harmonization enabling China market access. Watch ECHA expansion of REACH substance restrictions as the inflection signal accelerating replacement filter consumption.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Activated Carbon | Captive sourcing from Southeast Asian coconut shell suppliers insulates margin pressure from feedstock volatility. |
| Multi-Certification Platform Consolidation | Unified NIOSH-CE-GB testing protocols reduce engineering complexity and accelerate product development timelines. |
| Wearable Sensor Convergence | Integration with Honeywell and Dräger IoT-enabled respirators opens predictive replacement subscription revenue. |
| Direct Enterprise Contracting | Bypassing consolidated distributors captures margin pools from United States automotive and metal fabrication sectors. |
| Nanofiber Manufacturing Decentralization | Regional production without melt-blown polypropylene dependencies reduces supply chain concentration risk. |
Research Methodology
Multiple input streams — primary interviews with plant engineers and procurement directors, secondary validation through customs records and SEC filings, and technical patent analysis — were reconciled to construct market estimates. Stakeholder consultations included industrial hygiene officers at German chemical processors, safety equipment distributors in Mumbai and Shanghai, and maintenance directors at United States automotive assembly plants. Secondary sources comprised OSHA enforcement databases, ECHA authorization registries, SAMR GB standard documentation, and trade flow data from United States and European customs authorities. Bottom-up filter shipment analysis and top-down industrial safety equipment market sizing were triangulated for consistency.
Historical volume trajectories were cross-referenced against panel input from industry participants to anchor projection assumptions across the analysis window. Segmentation dimensions modeled include product type tier, filtration technology platform, end-use industry vertical, and regional regulatory cluster. CAGRs were derived from fitted growth curves incorporating compliance-driven replacement cycle acceleration and penetration rates for powered air-purifying respirators in Southeast Asian healthcare systems. Forecast inputs included OSHA inspection intensity indices and ECHA substance restriction timelines.
Caveats apply where activated carbon supply disruptions, NIOSH-EN protocol divergence resolution, or GB standard harmonization delays could materially shift the outlook. Forecasts reflect documented assumptions regarding regulatory enforcement continuity and industrial capital expenditure patterns. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Safety Equipment and Personal Protective Equipment (PPE)
Europe N95 Mask Market
Safety Equipment and Personal Protective Equipment (PPE)
South America Protective Coating Market
Safety Equipment and Personal Protective Equipment (PPE)
China Hand Sanitizer Market
Safety Equipment and Personal Protective Equipment (PPE)
Safety Light Curtains Market
Safety Equipment and Personal Protective Equipment (PPE)
Drone Safety Systems Market
Safety Equipment and Personal Protective Equipment (PPE)
Hearing Protection Products Market
Safety Equipment and Personal Protective Equipment (PPE)
Active Seat Belt System Market
Safety Equipment and Personal Protective Equipment (PPE)
Middle East and Africa Intrinsically Safe Equipment Market
Safety Equipment and Personal Protective Equipment (PPE)
PPE Detection Market
Safety Equipment and Personal Protective Equipment (PPE)
US Conducted Energy Weapons Market
Safety Equipment and Personal Protective Equipment (PPE)
Flammable Storage Cabinets Market
Safety Equipment and Personal Protective Equipment (PPE)
Europe Safes and Vaults Market
Safety Equipment and Personal Protective Equipment (PPE)
Body Armor Accessories Market
Safety Equipment and Personal Protective Equipment (PPE)
Strobe Beacon Market
Safety Equipment and Personal Protective Equipment (PPE)
US Industrial Barrier Systems Market
Safety Equipment and Personal Protective Equipment (PPE)
Booster Seat Type Child Safety Seats Market