
 Global Explosion Proof Equipment Market | 2026-2036
Global Explosion Proof Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Global Explosion Proof Equipment Market Intelligence
Aluminum alloy housings is decoupling from traditional cast-iron enclosures in explosion proof motor and lighting fabrication, cutting weight by roughly one-third while maintaining IP66 ingress ratings. Eaton Corporation leverages captive foundry partnerships across Southeast Asia to secure aluminum supply continuity. Pepperl+Fuchs anchors its sensor portfolio on intrinsic safety barriers that simplify loop architecture in Zone 0 deployments. Siemens dominates large-drives integration, bundling flameproof motors with variable-frequency drives for compressor stations.
Explosion proof equipment comprises electrical and mechanical apparatus engineered to contain internal ignition of flammable gases, vapors, or combustible dusts without transmitting flame to the surrounding hazardous atmosphere, typically certified to IEC 60079 or NEC 500/505 standards with temperature class ratings from T1 to T6. Flameproof enclosure technology leads volume shipments due to its applicability across Zone 1 and Zone 2 environments, while intrinsic safety is displacing legacy architectures in instrument loops where maintenance access proves costly. Oil refining and petrochemical facilities command the largest application share, with chemical processing trailing as European REACH compliance drives replacement of legacy pressurized systems.
The IECEx international certification scheme, the EU ATEX Directive 2014/34/EU, and the US National Electrical Code Article 500 collectively define market access thresholds, with IECEx mutual recognition reducing retesting burdens for exporters targeting multiple jurisdictions. China's NMPA-equivalent explosion safety administration enforces GB 3836 standards that diverge from IEC baselines, forcing dual-certification strategies for foreign suppliers. Stakeholders must monitor divergence between IECEx and national GB certification timelines when prioritizing factory qualification investments.
Market Dynamics
Aluminum alloy substitution is compressing traditional foundry economics while IECEx-ATEX regulatory divergence forces dual-certification capital allocation across manufacturing footprints.
Growth Catalysts
- Petrochemical capacity expansion:Refinery operators in the United States, Germany, and China are extending replacement cycles for flameproof enclosures across upstream and downstream facilities, sustaining equipment refresh demand.
- REACH compliance mandates:European chemical processors must replace legacy pressurized systems with certified explosion proof alternatives, accelerating hardware turnover in Zone 1 environments.
- Intrinsic safety architecture:Instrument loop simplification through barrier-based designs reduces maintenance access costs in Zone 0 deployments, pulling adoption from legacy protection methods.
Market Restraints
- Aluminum supply concentration:Captive foundry partnerships in Southeast Asia create single-source dependency for lightweight housing fabrication, exposing cost volatility to regional smelter output.
- GB 3836 divergence:China's national explosion safety standards deviate from IEC baselines, forcing foreign suppliers into parallel certification tracks that extend factory qualification timelines.
- Cast-iron foundry consolidation:Traditional enclosure material supply is concentrating among fewer specialty metalworkers, constraining pricing flexibility for legacy specification holdouts.
Strategic Opportunities
- Variable-frequency drive bundling:Compressor station operators seek integrated flameproof motor and drive packages, opening white space for system-level suppliers against component vendors.
- Zone 2 LED lighting retrofit:Chemical processing facilities in India and Brazil present underpenetrated demand for IP66-rated luminaires as they phase out legacy incandescent hazardous area fixtures.
- Digital twin integration:Predictive maintenance platforms converging with explosion proof sensor networks enable remote diagnostics, reducing physical inspection frequency in inaccessible installations.
Industry Challenges
- IECEx-GB timeline misalignment:Certification interval gaps between international and Chinese national schemes delay product launches and strand inventory in qualification queues.
- Intrinsic safety loop engineering:Barrier specification and entity parameter matching require scarce hazardous area electrical design expertise, constraining project execution capacity.
- Legacy system interoperability:New flameproof architectures must interface with decades-old pressurized and increased safety installations, complicating upgrade pathways.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Explosion Proof Equipment Market |
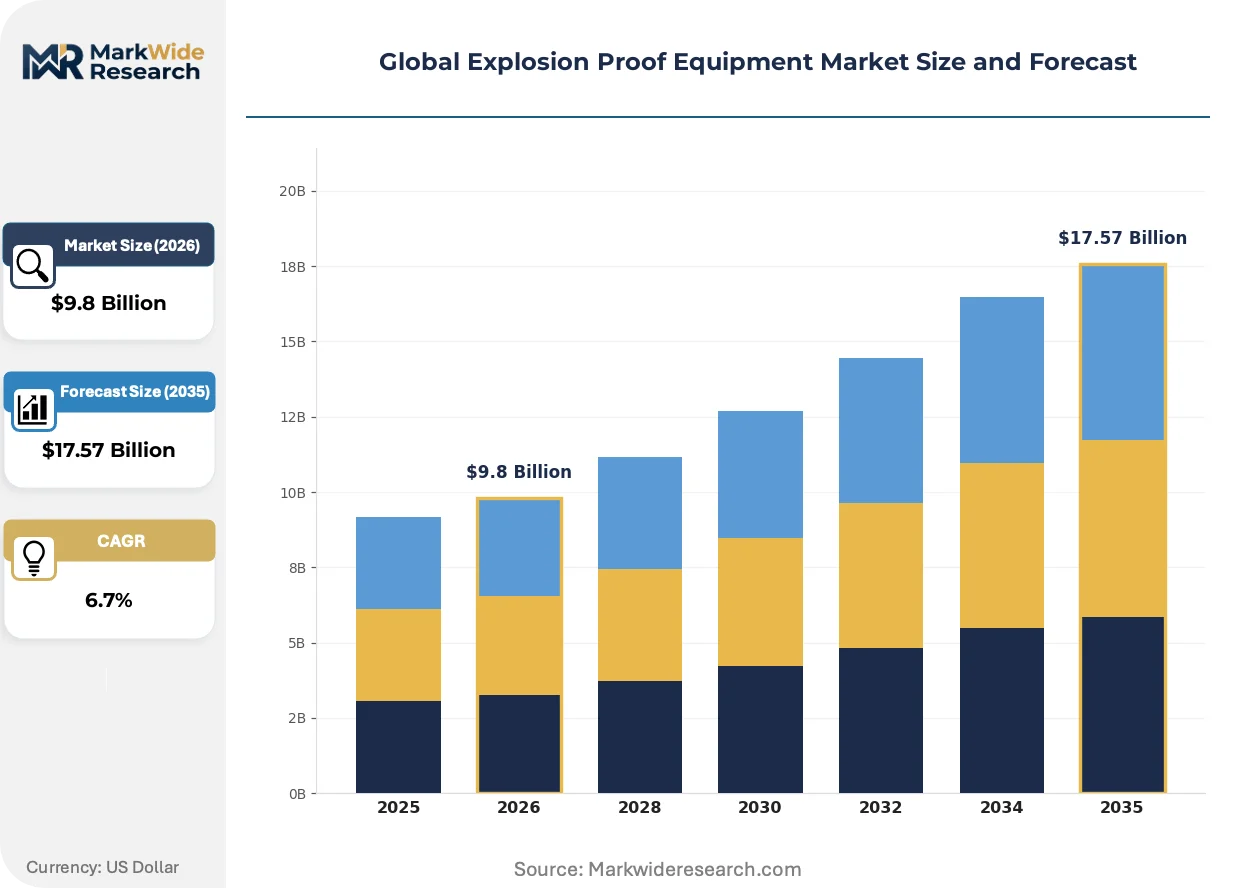
| Market Size in 2026 | $9.8 Billion |
| Market Size in 2035 | $17.57 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Explosion Proof Motors, Explosion Proof Sensors, Explosion Proof Switches, Explosion Proof Lighting, Explosion Proof Cabinets Technology: Intrinsic Safety, Flameproof Enclosure, Increased Safety, Pressurized, Oil Immersion, Powder Filling Application: Oil Refining, Chemical Processing, Mining Operations, Grain Handling, Pharmaceutical Manufacturing, Petrochemical Facilities End User: Refineries, Chemical Plants, Mining Contractors, Agricultural Processors, Biotech Firms, E&P Companies |
| Companies Covered | Eaton Corporation, Emerson Electric Co., Siemens, Patlite Corporation, R. STAHL, Honeywell International Inc., Rockwell Automation Inc., Pepperl+Fuchs, ABB Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Explosion Proof Equipment Market Strategic Shifts & Innovations
Equipment architecture is pivoting from passive containment to active electronic protection, compressing maintenance windows and reshaping supplier value capture toward software-enabled monitoring.
Wireless sensor networks are decentralizing hazardous area data collection by eliminating conduit runs through Zone 0 boundaries. Offshore platform operators in the North Sea are deploying battery-powered transmitters with encapsulated antenna designs, cutting installation labor by two-thirds while maintaining T6 temperature ratings. This topology is decentralizing control system architecture and reducing the panel footprint in crowded process areas.
The EU ATEX Directive 2014/34/EU is tightening conformity assessment procedures for Category 1 equipment, requiring notified body intervention for all Zone 0 certifications. Manufacturers serving European chemical clusters must now budget additional third-party audit cycles and technical file depth. German refineries are responding by consolidating supplier relationships toward full-service certification holders with in-house testing laboratories.
Integrated service contracts are displacing transactional equipment sales as owner-operators seek to transfer compliance liability to vendors. Saudi Aramco and similar national oil companies now specify ten-year performance guarantees covering certification maintenance and recertification costs. This model concentrates procurement authority among integrated suppliers with captive technical service organizations, squeezing pure-play hardware manufacturers.
Global Explosion Proof Equipment Market Segmentation
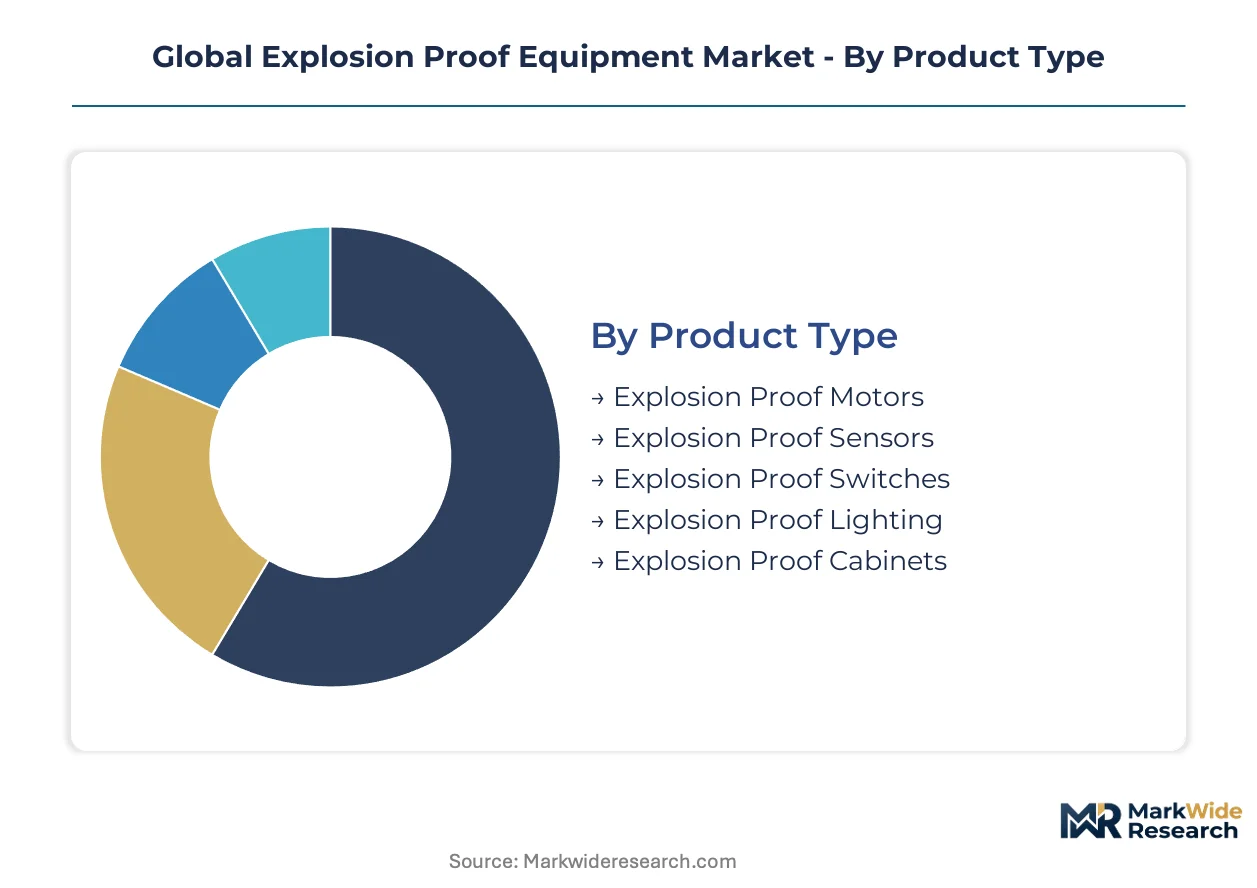
Segmentation in explosion proof equipment reveals distinct capital deployment patterns across protection technologies and end-use environments. Procurement decisions hinge on zone classification, maintenance accessibility, and certification jurisdiction rather than unit economics alone.
Product Type:
Capital intensity varies sharply across enclosure categories, with integrated motor-drive systems demanding the highest upfront engineering investment.
- Explosion Proof Motors:These units combine flameproof stator housings with T4-T6 temperature class windings to contain internal ignition sources. Siemens and ABB dominate large-drive integration for compressor stations across the United States, Germany, and China as petrochemical capacity expands.
- Explosion Proof Sensors:Pepperl+Fuchs anchors its portfolio on intrinsic safety barriers that simplify loop architecture in Zone 0 deployments. Demand concentrates in offshore North Sea platforms where battery-powered transmitters with encapsulated antenna designs eliminate conduit runs through hazardous boundaries.
- Explosion Proof Switches:Heavy-duty actuators certified to IEC 60079-1 serve isolation points in upstream oil facilities.
- Explosion Proof Lighting:IP66-rated LED luminaires replace legacy incandescent fixtures in chemical processing retrofits across India and Brazil.
- Explosion Proof Cabinets:Junction and distribution enclosures house termination points in crowded process areas.
Explosion proof motors absorb the bulk of installed capacity; explosion proof sensors are expanding most quickly.
Technology:
Protection methodology determines lifecycle cost structure, with passive containment architectures requiring less field engineering than active electronic systems.
- Intrinsic Safety:Barrier-based designs limit energy available for ignition through zener diode networks and galvanic isolation. Zone 0 instrument loops in European chemical clusters favor this approach as REACH compliance mandates replacement of legacy pressurized systems.
- Flameproof Enclosure:Cast-aluminum or cast-iron housings withstand internal explosions without transmitting flame to surrounding atmospheres. Oil refining operators in the United States, Germany, and China extend replacement cycles across upstream and downstream facilities.
- Increased Safety:Enhanced construction techniques prevent arcs and sparks in Zone 2 terminal boxes.
- Pressurized:Purged enclosures maintain positive pressure to exclude hazardous gases, common in legacy analyzer shelters.
- Oil Immersion:Submerged contact designs isolate ignition sources in mining switchgear.
- Powder Filling:Encapsulated components resist dust ignition in grain handling elevators.
Flameproof enclosure retains the largest installed base; intrinsic safety is climbing the fastest as digital instrument density rises.
Application:
Process hazard severity dictates specification tier, with hydrocarbon handling environments commanding the most stringent certification requirements.
- Oil Refining:Atmospheric and vacuum distillation units deploy flameproof motors and lighting across Zone 1 process areas. Saudi Aramco and similar national oil companies now specify ten-year performance guarantees covering certification maintenance costs.
- Chemical Processing:Batch reactors and solvent recovery systems require Category 1 equipment under tightened EU ATEX Directive 2014/34/EU conformity procedures. German refineries consolidate supplier relationships toward full-service certification holders with in-house testing laboratories.
- Mining Operations:Underground coal and metal extraction deploys explosion proof switchgear against methane and coal dust hazards.
- Grain Handling:Elevator leg boots and dust collectors specify powder-filled or dust-ignition-proof enclosures.
- Pharmaceutical Manufacturing:Solvent-based coating and granulation suites require Zone 2 lighting and sensor networks.
- Petrochemical Facilities:Ethylene crackers and polymerization units integrate large-drive systems with variable-frequency control.
Oil refining commands the largest application share; chemical processing shows the steepest replacement trajectory as European REACH compliance accelerates.
End User:
Ownership structure shapes procurement modality, with integrated oil companies transferring compliance liability through long-term service contracts.
- Refineries:Owner-operators seek to bundle equipment supply with certification maintenance, concentrating authority among suppliers with captive technical service organizations. This model squeezes pure-play hardware manufacturers.
- Chemical Plants:European processors face dual pressure from ATEX tightening and REACH substitution mandates. Notified body intervention now required for all Zone 0 certifications extends factory qualification timelines.
- Mining Contractors:Project-based procurement favors modular switchgear packages for site mobility.
- Agricultural Processors:Grain elevators and feed mills prioritize dust-ignition protection in material handling zones.
- Biotech Firms:Solvent-based API manufacturing requires hybrid cleanroom-hazardous area equipment specifications.
- E&P Companies:Exploration and production units specify portable flameproof equipment for drilling and well servicing.
Refineries dominate capital deployment; chemical plants are gaining share fastest as European regulatory pressure intensifies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for explosion proof equipment concentrates in three national markets where petrochemical capacity expansion intersects with tightening hazardous area regulations. Refinery operators in the United States, Germany, and China are extending replacement cycles for flameproof enclosures while navigating divergent certification requirements.
United States
Upstream shale processing and Gulf Coast downstream expansion sustain equipment refresh demand across Texas and Louisiana petrochemical corridors. OSHA and the National Electrical Code Article 500 define installation standards for hazardous locations, with NEC 500/505 classifications governing Zone 0 through Zone 2 deployments. Houston anchors the largest concentration of refinery engineering procurement, where owner-operators bundle ten-year performance guarantees with certification maintenance contracts.
Germany
Rhine-Ruhr chemical clusters face dual pressure from ATEX Directive 2014/34/EU tightening and REACH substitution mandates for legacy pressurized systems. Notified body intervention now required for all Category 1 Zone 0 certifications extends factory qualification timelines for equipment suppliers. BASF and Bayer facilities in Ludwigshafen and Leverkusen consolidate procurement toward full-service certification holders with captive technical service organizations.
China
Ethylene cracker construction along the Yangtze River Delta and Bohai Rim drives large-drive integration demand for compressor stations. GB 3836 national explosion safety standards diverge from IEC baselines, forcing foreign suppliers into parallel certification tracks that delay product launches. Sinopec and CNPC refineries in Ningbo and Dalian specify integrated flameproof motor and variable-frequency drive packages from system-level suppliers.
India
Chemical processing retrofits in Gujarat and Maharashtra present underpenetrated demand for IP66-rated LED luminaires as facilities phase out legacy incandescent hazardous area fixtures. The Central Electricity Authority enforces hazardous location standards through IS/IEC 60079 adoption with national modifications. Reliance Industries' Jamnagar refinery complex anchors Zone 2 lighting replacement programs across western India.
Saudi Arabia
Offshore platform upgrades in the Arabian Gulf and Red Sea drive wireless sensor network deployment with encapsulated antenna designs. The national oil company specifies long-term service contracts transferring compliance liability to vendors, concentrating procurement authority among integrated suppliers. Saudi Aramco facilities in Ras Tanura and Jubail Industrial City demand flameproof equipment with recertification cost coverage spanning decade-long operational windows.
Global Explosion Proof Equipment Market Key Industry Players
Branded specialists and contract manufacturers split share differently across segments, with integrated system suppliers capturing premium positions in motor-drive bundling while component vendors compete on specification breadth. The vendor base organizes around three archetypes: full-service certification holders with captive technical service organizations, pure-play hardware manufacturers, and captive foundry-integrated fabricators securing aluminum supply continuity. Consolidation pressures squeeze pure-play manufacturers as national oil companies transfer compliance liability through performance guarantees. Strategic moves center on backward integration into Southeast Asian foundry partnerships and geographic expansion through IECEx mutual recognition to bypass retesting burdens.
Among diversified electrical conglomerates, Eaton Corporation, Siemens, and ABB Ltd occupy positions exemplifying the full-service archetype with integrated certification capabilities. These entities represent the tier capturing procurement authority from owner-operators seeking bundled equipment supply with decade-long compliance maintenance. Pepperl+Fuchs anchors the specialist segment, its positioning reflecting the intrinsic safety barrier approach displacing legacy architectures in Zone 0 instrument loops. Emerson Electric Co. and Honeywell International Inc. sit within the automation-integrated tier, their hazardous area portfolios extending from sensor networks to control system architecture.
| Leading Market Players |
|---|
| Eaton Corporation |
| Emerson Electric Co. |
| Siemens |
| Patlite Corporation |
| R. STAHL |
| Honeywell International Inc. |
| Rockwell Automation Inc. |
| Pepperl+Fuchs |
| ABB Ltd |
| Others |
Cost & Logistics Intelligence
Sovereign-backed national oil companies in Saudi Arabia and China compress supplier margins through decade-long performance guarantees that bundle certification maintenance with equipment procurement. This financing pattern forces pure-play hardware manufacturers toward distressed valuations while full-service certification holders capture pricing power through captive technical service organizations.
Pricing Analysis
High-volume flameproof motor shipments trade at compressed margins while integrated motor-drive bundles command premium positioning. Three-tier pricing structure across IECEx-certified premium, ATEX-standard, and GB 3836-economy levels separates system-level suppliers from component vendors. Pricing pressure stems from aluminum foundry consolidation in Southeast Asia exposing cost volatility to regional smelter output. EPC contractors in India and Brazil exhibit highest price sensitivity, whereas Saudi Aramco and Sinopec prioritize total cost of ownership over unit economics.
Supply Chain Analysis
Certification/qualification gating funnels qualified suppliers through IECEx, ATEX, and GB 3836 parallel tracks that extend factory qualification timelines. Manufacturing concentrates in Germany, China, and the United States, with captive foundry partnerships in Southeast Asia securing aluminum alloy supply continuity for lightweight housing fabrication. Raw material dependencies center on aluminum ingot, cast-iron scrap, and copper windings. Single-source vulnerability runs through Southeast Asian smelter concentration. Distribution runs through direct OEM relationships and EPC contractor channels with long-lead project coordination.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a consolidation play where regulatory divergence between IECEx and GB 3836 certification timelines forces capital-constrained pure-play manufacturers toward acquisition or exit.
For Market Incumbents: Acquire captive technical service organizations to capture ten-year performance guarantee contracts from national oil companies. Defensive consolidation demands backward integration into Southeast Asian aluminum foundry partnerships and in-house IECEx testing laboratories. Threat from emerging automation-integrated competitors intensifies as Emerson and Honeywell extend hazardous area portfolios into control system architecture. For New Entrants and Emerging Players: Channel partners specializing in Zone 2 LED lighting retrofits offer the most penetrable entry vector for undercapitalized specialists. White space concentrates in Indian and Brazilian chemical processing facilities phasing out legacy incandescent hazardous area fixtures. Target wireless sensor network deployments for offshore platform upgrades in the North Sea and Arabian Gulf. Go-to-market leverage rests on digital twin integration partnerships with predictive maintenance platform providers. For Investors and Strategic Acquirers: Distressed-cycle entries favor pure-play hardware manufacturers with stranded GB 3836 qualification inventory in China. Long-term viability over a multi-year horizon hinges on certification breadth spanning IECEx, ATEX, and Chinese national schemes. Acquisition target archetype: mid-cap specialists with captive foundry relationships and in-house testing capacity. Signal to watch: divergence or convergence between IECEx and GB 3836 timeline alignment as inflection indicator for factory qualification investment returns.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Foundry Partnerships | Eaton Corporation's Southeast Asian captive supply secures aluminum alloy continuity against regional smelter volatility. |
| IECEx Mutual Recognition Expansion | Reduces retesting burdens for exporters targeting United States, Germany, and China petrochemical corridors simultaneously. |
| Integrated Motor-Drive Bundling | Siemens captures compressor station demand by combining flameproof motors with variable-frequency drive packages. |
| Wireless Sensor Network Deployment | North Sea offshore platforms cut installation labor through battery-powered transmitters with encapsulated antenna designs. |
| Long-Term Service Contract Structuring | Saudi Aramco transfers compliance liability to vendors through decade-long performance guarantees covering recertification costs. |
Research Approach
Independent corroboration across plant engineers at Texas and Louisiana refineries, procurement leads at German chemical clusters, and certification specialists at notified bodies underwrites the qualitative findings. Primary interviews with maintenance directors, EPC contractors, and aftermarket service heads combined with secondary validation from IECEx certification databases, SEC 10-K filings, and customs trade data. Bottom-up equipment shipment analysis triangulates against top-down petrochemical capacity expansion tracking.
Rate-of-change decomposition separates volume growth from mix-shift effects across the projection horizon. Segmentation dimensions modeled include protection technology, zone classification, application environment, and certification jurisdiction. CAGRs derive from equipment replacement cycle analysis and petrochemical capacity buildout schedules. Industry-specific forecast inputs incorporate REACH compliance substitution mandates and ATEX Directive 2014/34/EU tightening timelines.
Caveats apply where GB 3836-IECEx divergence acceleration or aluminum supply disruption could materially shift the outlook. Forecasts reflect assumptions about certification timeline convergence and foundry capacity expansion. A model refresh is warranted upon material change in Sinopec or Saudi Aramco procurement contract structures.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Safety Equipment and Personal Protective Equipment (PPE)
Respiratory Protective Equipment Market
Safety Equipment and Personal Protective Equipment (PPE)
Safety Mirrors Market
Safety Equipment and Personal Protective Equipment (PPE)
Military Gas Mask Market
Safety Equipment and Personal Protective Equipment (PPE)
Welding Helmets Market
Safety Equipment and Personal Protective Equipment (PPE)
Electrical Safety Gloves Market
Safety Equipment and Personal Protective Equipment (PPE)
Ballistic Floatation Vest Market
Safety Equipment and Personal Protective Equipment (PPE)
APAC Safety Instrumented Systems Market
Safety Equipment and Personal Protective Equipment (PPE)
Fall Protection Equipment Market
Safety Equipment and Personal Protective Equipment (PPE)
Ballistic Shields Market
Safety Equipment and Personal Protective Equipment (PPE)
Industrial Protective Clothing Market
Safety Equipment and Personal Protective Equipment (PPE)
Saudi Arabia Personal Protective Equipment Market
Safety Equipment and Personal Protective Equipment (PPE)
Diving and Survival Equipment Market
Safety Equipment and Personal Protective Equipment (PPE)
Public Address and Voice Alarm Systems Market
Safety Equipment and Personal Protective Equipment (PPE)
China Protective Clothing Market
Safety Equipment and Personal Protective Equipment (PPE)
Supplementary Protectors Market
Safety Equipment and Personal Protective Equipment (PPE)
Chemical Protective Gloves Market