
 Intrinsically Safe Lighting Market | 2026-2036
Intrinsically Safe Lighting Market Size, Share, and Industry Trends Forecast 2026-2036
Intrinsically Safe Lighting Market Insights
The EU Green Deal is restructuring procurement criteria across European process industries, compelling plant operators to replace legacy halogen fixtures with low-energy hazardous-area luminaires. Eaton leverages its circuit protection heritage to anchor specification lists in North American petrochemical complexes. Wolf Safety specializes in ATEX and IECEx certifications that dominate North Sea oil platform maintenance cycles. Streamlight competes in portable intrinsically safe lighting for confined-space inspection teams across downstream facilities.
Intrinsically safe lighting denotes luminaires engineered to limit electrical and thermal energy below ignition thresholds for explosive atmospheres, typically achieving this through encapsulated LED drivers, sealed battery compartments, and flameproof enclosures rated to IEC 60079-0. These fixtures serve primary industrial purpose in Zone 0, Zone 1, and Zone 2 hazardous locations where standard illumination would trigger combustible gas or dust detonations. LED product types now lead volume shipments due to their extended operational life and minimal heat signature in enclosed process vessels. Battery Operated technology segments are expanding fastest as wireless telemetry integration enables remote luminance monitoring without conduit installation. Oil and Gas Extraction applications concentrate margin pools because platform operators prioritize certification compliance over upfront unit cost in procurement decisions.
FDA oversight of pharmaceutical manufacturing cleanrooms intersects with OSHA electrical safety standards to mandate intrinsically safe fixtures in solvent-handling areas, while the EU ATEX Directive 2014/34/EU defines essential health requirements for equipment deployed in potentially explosive atmospheres. IECEx certification schemes further streamline multinational acceptance for manufacturers seeking unified testing protocols across member countries. Stakeholders must monitor evolving battery chemistry regulations and harmonization gaps between regional certification bodies when configuring product portfolios for cross-border deployment.
Market Dynamics
LED encapsulation and wireless telemetry integration are compressing replacement cycles across hazardous-zone installations, while ATEX and IECEx certification harmonization is redrawing competitive entry barriers for fixture suppliers.
Growth Catalysts
- EU F-Gas Regulation:Chemical processing clusters in Germany are accelerating halogen-to-LED retrofits to meet fluorinated gas phase-down mandates, driving bulk procurement of sealed driver assemblies.
- Offshore platform maintenance:North Sea operators are expanding capital budgets for Zone 1 rated fixtures as extended field life programs require lighting infrastructure replacement without production shutdowns.
- Battery chemistry advances:Solid-state lithium cell formats are enabling portable inspection lamps with extended runtime in confined-space pharmaceutical manufacturing cleanrooms.
Market Restraints
- Raw material concentration:Rare earth phosphor supply from Chinese processing facilities creates input cost volatility for high-CRI LED emitters specified in pharmaceutical applications.
- Certification timeline friction:Divergent testing protocols between ATEX Notified Bodies and IECEx Certification Bodies extend product launch cycles by 8-14 months for multinational fixture portfolios.
- Technical limitation:Thermal management constraints in Zone 0 enclosures cap lumen output per fixture, forcing higher unit counts for adequate illuminance in large process vessels.
Strategic Opportunities
- Underpenetrated mining automation:Underground coal and potash operations in Poland and Czechia present retrofit demand for wireless-mesh enabled cap lamps with real-time gas detection integration.
- EU Green Deal procurement criteria:Public tender rules for industrial infrastructure are mandating lifecycle carbon assessments that favor LED fixtures over legacy discharge lamps in public-private chemical park developments.
- Technology convergence:Integration of luminaire power buses with Industrial Internet of Things sensor networks is creating specification preference for fixture suppliers with embedded telemetry partnerships.
Industry Challenges
- Specialized workforce scarcity:Qualified hazardous-area electricians certified for both IEC 60079 installation and LED driver troubleshooting command wage premiums that inflate project deployment costs.
- Legacy system integration:Retrofit projects in decades-old petrochemical complexes require custom mounting adapters and conduit modifications that extend commissioning timelines beyond original estimates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Intrinsically Safe Lighting Market |
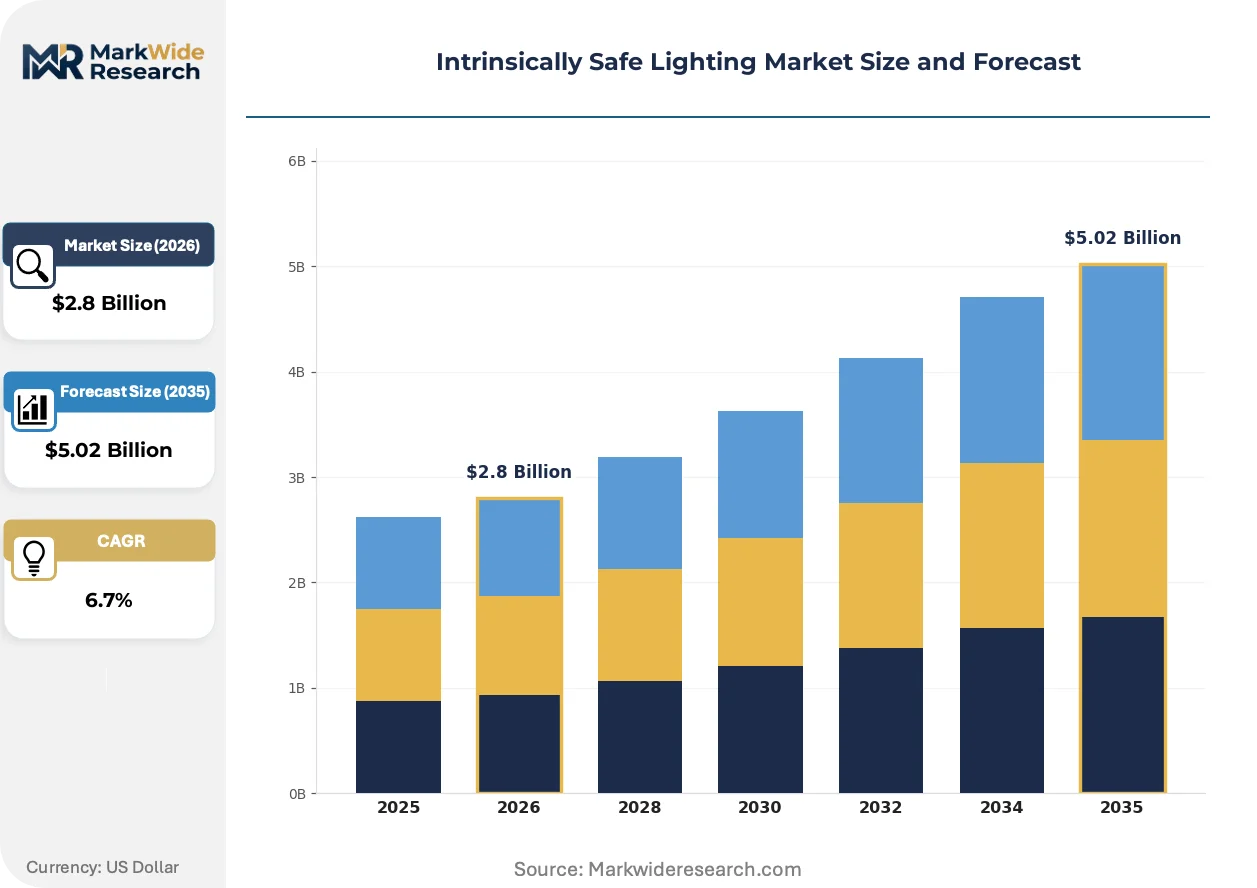
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.02 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: LED, Fluorescent, Halogen, Solar-Powered, High-Intensity Discharge Technology: Battery Operated, Wired, Wireless, Photovoltaic, Solar Cells Application: Oil & Gas Extraction, Mining Operations, Chemical Processing, Petrochemical Plants, Pharmaceutical Manufacturing End User: Exploration Firms, Extraction Companies, Manufacturing Plants, Industrial Safety Providers, Research Facilities |
| Companies Covered | Fluke, Eaton, Streamlight, Nightstick, Peli, Wolf Safety, Larson Electronics, Exloc Instruments, CorDEX Instruments, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Intrinsically Safe Lighting Market Trends and Innovations
Fixture architectures are converging around sealed electronic assemblies and predictive maintenance connectivity, compressing the traditional separation between lighting hardware and plant control systems.
Advanced polymer encapsulation of LED driver electronics is overtaking conventional flameproof enclosure designs in Zone 2 chemical processing applications. Bayer and BASF facility engineering teams are specifying potted driver modules for solvent-handling areas. This technology is overtaking metal-housed alternatives by eliminating gasket maintenance schedules and reducing fixture weight for elevated mounting structures.
The EU F-Gas Regulation's phase-down schedule is forcing refrigerant and propellant manufacturers to audit electrical installations in classified zones for ignition risk. Chemical plant operators are responding with accelerated replacement programs for legacy high-bay fixtures. German chemical parks along the Rhine corridor are prioritizing ATEX-rated LED high-bays in their 2026-2028 capital plans.
Specification authority is migrating from maintenance departments to centralized engineering procurement functions with standardized vendor qualification lists. Integrated oil companies are consolidating approved manufacturer lists to three to four fixture suppliers per region. This concentration is most visible in Norwegian continental shelf operations where Equinor and Aker BP have aligned their technical specifications.
Intrinsically Safe Lighting Market Segmentation
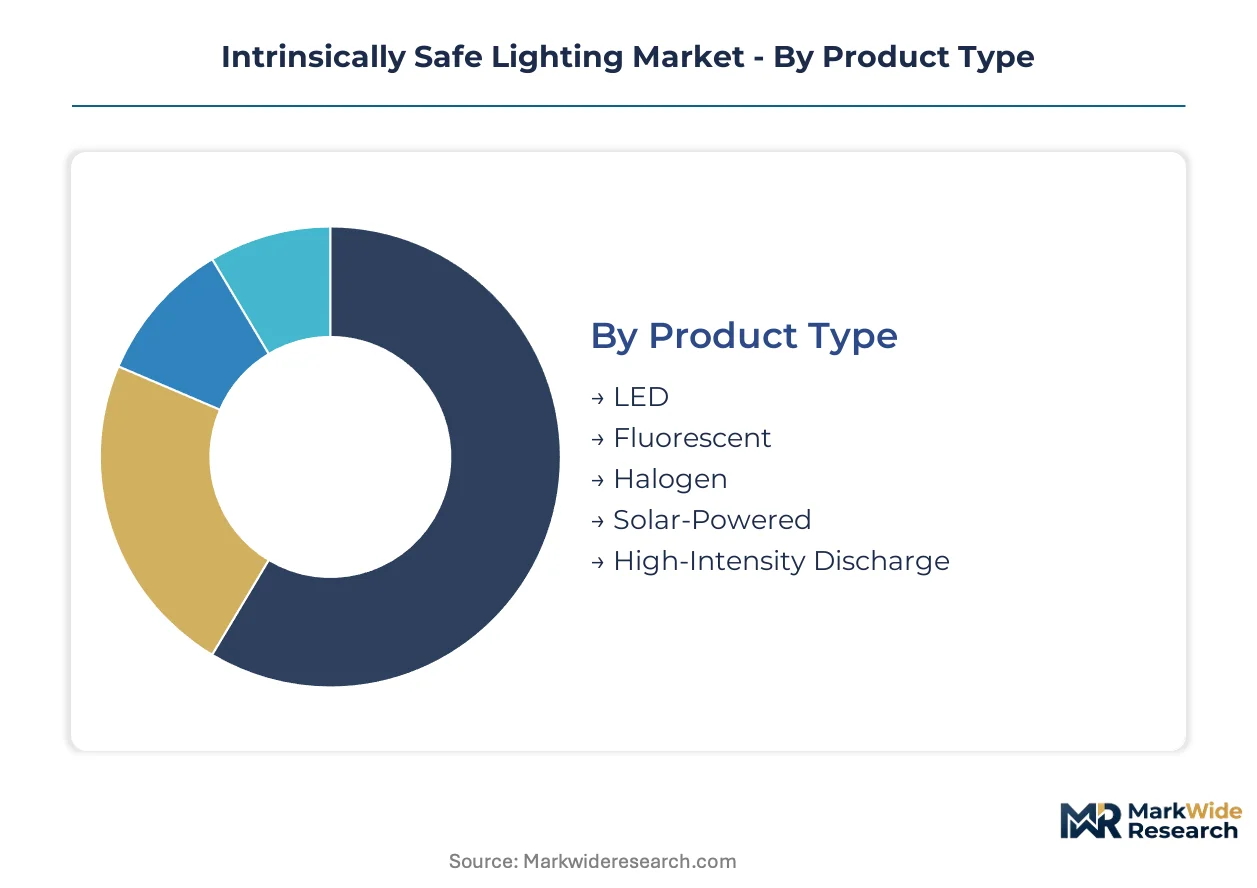
Hazardous-area lighting procurement splits across technical specifications, power architectures, and operational environments. Buyers prioritize certification grade over unit cost in high-risk zones, while wireless telemetry integration is reshaping technology preferences across all verticals.
Product Type:
Fixture selection hinges on thermal signature constraints and maintenance access economics in classified zones.
- LED:Encapsulated driver assemblies with minimal heat emission dominate retrofits in German chemical parks and North Sea platforms. Solid-state construction eliminates filament failure risks in continuous-operation process vessels.
- Fluorescent:Legacy T5 and T8 formats persist in budget-constrained mining operations across Eastern Europe, though mercury content faces tightening disposal regulations under REACH.
- Halogen:High-CRI output retains niche demand in pharmaceutical inspection stations where color rendering accuracy is mandatory; EU F-Gas phase-downs are accelerating displacement timelines.
- Solar-Powered:Autonomous operation suits remote wellhead monitoring in desert extraction zones where grid extension is uneconomical.
- High-Intensity Discharge:Metal halide and sodium vapor fixtures cling to legacy high-bay installations in decades-old petrochemical complexes with extended replacement cycles.
LED leads volumes today; solar-powered formats are gaining share fastest in greenfield extraction sites.
Technology:
Power delivery architecture determines installation cost, inspection protocol, and integration with plant control systems.
- Battery Operated:Solid-state lithium cells enable portable inspection lamps with wireless telemetry for real-time gas detection integration in confined-space pharmaceutical cleanrooms. Remote luminance monitoring eliminates conduit installation in retrofit projects.
- Wired:Hardwired 24V DC bus systems anchor permanent installations in Zone 1 process areas where continuous power is non-negotiable; cable gland sealing adds commissioning complexity.
- Wireless:Mesh-networked fixtures with embedded sensors are penetrating Norwegian continental shelf operations where Equinor and Aker BP have aligned technical specifications.
- Photovoltaic:Thin-film solar integration supports auxiliary lighting in remote pipeline monitoring stations with minimal maintenance access.
- Solar Cells:Crystalline silicon panels paired with battery storage serve off-grid extraction camps in arid climate zones.
Wired systems retain the largest installed base; battery operated configurations are expanding most quickly through telemetry integration.
Application:
Operational environment dictates ignition risk classification and corresponding certification tier requirements.
- Oil & Gas Extraction:Offshore platform operators prioritize ATEX and IECEx compliance over upfront cost in procurement decisions for Zone 0 and Zone 1 fixtures. Extended field life programs in the North Sea are driving capital budget expansion for lighting infrastructure replacement.
- Mining Operations:Underground coal and potash extraction in Poland and Czechia presents retrofit demand for wireless-mesh enabled cap lamps with methane detection integration.
- Chemical Processing:Solvent-handling areas in German Rhine corridor chemical parks are accelerating LED retrofits to meet EU F-Gas Regulation phase-down mandates.
- Petrochemical Plants:Legacy facility retrofits require custom mounting adapters and conduit modifications that extend commissioning timelines.
- Pharmaceutical Manufacturing:FDA oversight of cleanroom operations intersects with OSHA electrical safety standards to mandate intrinsically safe fixtures in solvent-handling zones.
Oil and gas extraction concentrates margin pools; pharmaceutical manufacturing is climbing the fastest on regulatory stringency.
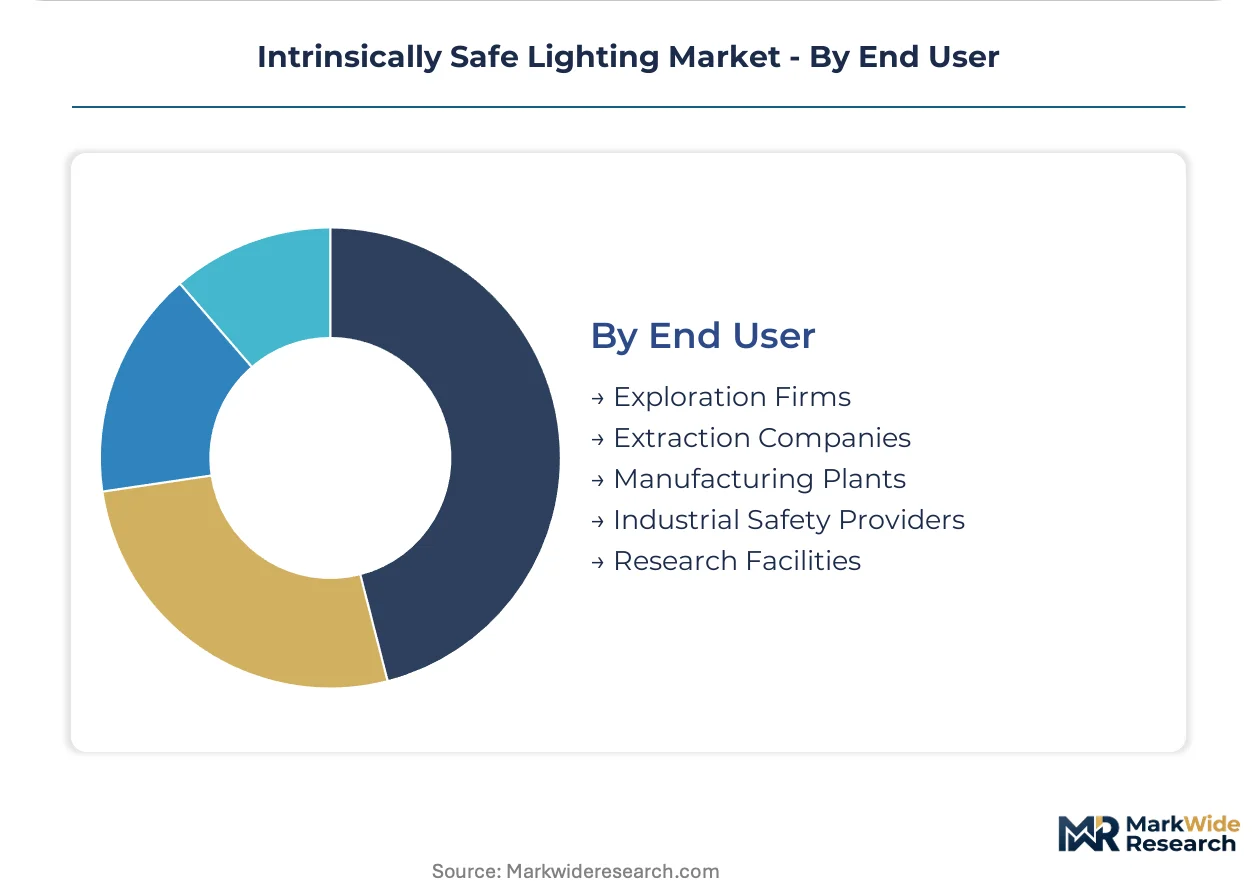
End User:
Procurement authority varies from centralized engineering functions to decentralized maintenance departments.
- Exploration Firms:Early-stage operators favor portable battery-operated systems for temporary camp installations with rapid redeployment requirements.
- Extraction Companies:Integrated oil companies are consolidating approved manufacturer lists to three to four fixture suppliers per region, most visible in Norwegian continental shelf operations.
- Manufacturing Plants:Bayer and BASF facility engineering teams are specifying potted driver modules over metal-housed alternatives in solvent-handling areas.
- Industrial Safety Providers:Rental and leasing specialists stock certified portable inventories for turnaround maintenance contracts.
- Research Facilities:Laboratory-scale solvent handling requires compact Zone 2 rated fixtures with minimal footprint in fume hood installations.
Extraction companies dominate procurement volumes; industrial safety providers are expanding most quickly through rental model adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Intrinsically safe lighting emerged from British coal mining safety engineering in the early twentieth century, with certification protocols later formalized through IEC standards adopted across industrial economies. Germany now anchors European procurement volumes, while the United States and China concentrate manufacturing scale. Norway, the United Kingdom, and Saudi Arabia represent distinct demand profiles shaped by offshore extraction and petrochemical expansion.
Germany
BASF and Bayer facility engineering teams are specifying potted LED driver modules for solvent-handling areas in Rhine corridor chemical parks. The EU F-Gas Regulation mandates fluorinated gas phase-downs that accelerate halogen-to-LED retrofit programs. Ludwigshafen and Leverkusen clusters are executing bulk procurement of ATEX-rated fixtures through 2028 capital plans.
United States
OSHA electrical safety standards intersect with FDA pharmaceutical cleanroom oversight to mandate certified luminaires across downstream facilities. Gulf Coast petrochemical complexes in Texas and Louisiana are consolidating approved manufacturer lists to three to four fixture suppliers per region. Houston-area engineering procurement functions now hold specification authority previously decentralized to maintenance departments.
Norway
Equinor and Aker BP have aligned technical specifications for North Sea platform maintenance cycles, prioritizing IECEx certification over upfront unit cost. Extended field life programs require lighting infrastructure replacement without production shutdowns. Stavanger and Bergen engineering clusters are expanding capital budgets for Zone 1 rated fixtures.
United Kingdom
ATEX Notified Body testing protocols create certification timeline friction that extends product launch cycles for multinational fixture portfolios. Aberdeen offshore supply bases concentrate maintenance procurement for North Sea operations. Manchester and Liverpool chemical processing facilities are retrofitting legacy high-bay installations with sealed driver assemblies.
Saudi Arabia
Aramco and SABIC are expanding greenfield petrochemical capacity that requires hazardous-area lighting infrastructure from project inception. The country's national industrial regulator mandates IECEx-equivalent certification for equipment deployed in potentially explosive atmospheres. Jubail and Yanbu industrial cities are specifying wireless-mesh enabled fixtures for new process units.
Intrinsically Safe Lighting Market Competitive Landscape
Premium-margin players sit above commodity-margin players across certification tier and application complexity, with ATEX and IECEx accreditation creating definitional entry barriers. The vendor base organizes into three strategic archetypes: diversified electrical conglomerates with circuit protection heritage, specialists in portable hazardous-area illumination, and regional fabricators serving national certification requirements. Competitive moves concentrate on strategic partnerships for telemetry integration and portfolio diversification into battery chemistry advances.
Within the specialist tier, Wolf Safety and Streamlight exemplify divergent positioning—Wolf Safety anchors ATEX and IECEx certification dominance for North Sea platform maintenance, while Streamlight occupies a position in portable intrinsically safe lighting for confined-space inspection teams. Eaton represents the diversified conglomerate archetype, leveraging circuit protection heritage to anchor specification lists in North American petrochemical complexes. These three companies illustrate how certification focus, product form factor, and geographic anchoring create distinct competitive vectors.
| Leading Market Players |
|---|
| Fluke |
| Eaton |
| Streamlight |
| Nightstick |
| Peli |
| Wolf Safety |
| Larson Electronics |
| Exloc Instruments |
| CorDEX Instruments |
| Others |
Pricing and Supply Chain Analysis
Integrated oil companies consolidating approved manufacturer lists to three to four fixture suppliers per region anchor contract-based long-term procurement that compresses margin dispersion across certification tiers. This buyer concentration shifts pricing power toward volume-scale negotiations and multi-year service bundling rather than transactional spot purchasing.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates ATEX Zone 0 certified fixtures from Zone 2 equivalents and uncertified industrial alternatives. Price differentiation hinges on IECEx certification grade and embedded telemetry capability, with pharmaceutical cleanroom specifications commanding the widest spreads. Cost compression in standard-tier LED assemblies is intensifying because rare earth phosphor volatility feeds into emitter pricing. Exploration firms operating temporary camp installations exhibit the highest price sensitivity, while North Sea platform operators prioritize compliance over unit cost.
Supply Chain Analysis
Single-source vulnerability sits with Chinese rare earth processing facilities that concentrate high-CRI phosphor supply for pharmaceutical-grade LED emitters. Manufacturing draws from Germany for precision driver electronics, China for LED die and phosphor integration, and Mexico for final assembly serving North American petrochemical demand. Supply chain risk centers on tariff exposure for crystalline silicon solar cells used in remote extraction lighting. Distribution runs through authorized hazardous-area electrical distributors with certified installation partnerships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The intrinsically safe lighting market represents a late-cycle quality story as EU F-Gas Regulation mandates and OSHA electrical safety standards displace legacy halogen and fluorescent inventories with certified LED alternatives. Procurement authority migration toward centralized engineering functions favors specification-grade suppliers over commodity fabricators.
For Market Incumbents: Extend certification portfolio breadth into IECEx-Zone 0 portable formats to defend against battery chemistry specialists encroaching from confined-space inspection segments. Deepen backward integration into solid-state lithium cell sourcing to secure supply for telemetry-integrated product lines. Anchor specification lists through embedded Industrial Internet of Things partnerships that raise switching costs for platform operators. For New Entrants and Emerging Players: Direct-to-industry digital channels enable bypass of traditional authorized distributor networks for standardized Zone 2 fixtures in budget-constrained mining operations. Target Polish and Czechia underground coal retrofit demand with wireless-mesh enabled cap lamps featuring methane detection integration. Pursue rental and leasing service models through industrial safety providers expanding turnaround maintenance inventories. For Investors and Strategic Acquirers: Diversified electrical conglomerates with circuit protection heritage are the most active acquirer in this space, seeking hazardous-area certification capabilities to complement existing industrial portfolios. Acquisition targets should exhibit ATEX and IECEx accreditation depth alongside telemetry integration partnerships. Watch for harmonization progress between ATEX Notified Bodies and IECEx Certification Bodies as signal for margin compression or expansion in multinational fixture portfolios.| Strategic Initiative | Industry Significance |
|---|---|
| Certification Portfolio Expansion | ATEX and IECEx Zone 0 accreditation opens North Sea platform maintenance cycles to new suppliers. |
| Backward Integration into Battery Chemistry | In-house solid-state lithium cell sourcing secures supply for telemetry-integrated portable inspection lamps. |
| Telemetry Partnership Development | Industrial Internet of Things sensor network integration raises specification preference in Norwegian continental shelf operations. |
| Geographic Manufacturing Footprint | Mexico final assembly capacity reduces tariff exposure for North American petrochemical complex deliveries. |
| Service Model Diversification | Rental and leasing through industrial safety providers captures turnaround maintenance contract demand. |
Research Methodology
Bottom-up oil and gas extraction modeling reconciled against top-down LED fixture manufacturing tracking forms the analytical core of this study. Primary interviews with platform engineering managers, hazardous-area procurement leads, certified installation contractors, and chemical plant maintenance directors combined with secondary validation from IECEx certification databases, ATEX Notified Body registries, SEC filings of diversified electrical conglomerates, and EU F-Gas Regulation compliance filings. Triangulation between demand-side capital budget disclosures and supply-side production capacity assessments ensures consistency across estimation approaches.
Input-output matrices map fixture shipments by certification tier, power architecture, and end-use vertical across the projection horizon. Segmentation dimensions include product type, technology, application environment, and procurement authority level. CAGRs derive from weighted regression against historical replacement cycle data and regulatory mandate phase-in schedules. Forecast inputs incorporate EU Green Deal procurement criteria evolution and battery chemistry advance timelines for solid-state lithium formats.
The model assumes a particular technology adoption path; alternative pathways for wireless telemetry integration or polymer encapsulation overtaking metal-housed flameproof designs would alter the outlook. Forecasts reflect assumptions regarding certification harmonization progress, rare earth phosphor supply stability, and offshore platform extended field life program continuity. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Safety Equipment and Personal Protective Equipment (PPE)
Medical Safety Goggles Market
Safety Equipment and Personal Protective Equipment (PPE)
N95 Mask Market
Safety Equipment and Personal Protective Equipment (PPE)
Blast Monitoring Equipment Market
Safety Equipment and Personal Protective Equipment (PPE)
Hearing Protection Devices Market
Safety Equipment and Personal Protective Equipment (PPE)
Global Rodent Control Market
Safety Equipment and Personal Protective Equipment (PPE)
Global Radiation Protection Apron Market
Safety Equipment and Personal Protective Equipment (PPE)
Crash Barrier Systems Market
Safety Equipment and Personal Protective Equipment (PPE)
Anti-Shock Trouser Market
Safety Equipment and Personal Protective Equipment (PPE)
Firefighter Tape Market
Safety Equipment and Personal Protective Equipment (PPE)
Medical Respiratory Protective Equipment Market
Safety Equipment and Personal Protective Equipment (PPE)
Remote Breathalyzer Market
Safety Equipment and Personal Protective Equipment (PPE)
Explosion Proof Devices Market
Safety Equipment and Personal Protective Equipment (PPE)
Diving and Survival Equipment Market
Safety Equipment and Personal Protective Equipment (PPE)
Strobe Beacon Market
Safety Equipment and Personal Protective Equipment (PPE)
Law Enforcement and Military Clothing Market
Safety Equipment and Personal Protective Equipment (PPE)
Emergency Showers Market