
 North America Fire Protection Water Storage Tanks Market | 2026-2036
North America Fire Protection Water Storage Tanks Market Size, Share, and Industry Trends Forecast 2026-2036
North America Fire Protection Water Storage Tanks Market Intelligence
Advanced corrosion-resistant coating systems and modular bolted-steel fabrication is reconfiguring how fire protection water storage tanks are engineered for rapid deployment. Tank Connection leverages proprietary fusion-bonded epoxy applications to extend tank service life in aggressive soil conditions. CST Industries, Inc. sustains dominant manufacturing scale across its multi-facility network. Highland Tank specializes in turnkey underground concrete systems for urban fire departments with limited surface area.
Fire protection water storage tanks are engineered vessels designed to store dedicated water reserves for automatic sprinkler systems, fire hydrant networks, and standpipe installations, typically constructed from welded steel, precast concrete, or fiberglass-reinforced polymer with capacity ratings from thousands to millions of gallons. These systems ensure immediate water availability independent of municipal supply pressure during emergency events. Above ground steel tanks anchor the installed base across North American industrial corridors due to lower capital outlay and faster field erection. Modular installation configurations are gaining share among temporary construction site applications and disaster-response staging areas where rapid relocation proves essential.
The National Fire Protection Association's NFPA 22 standard governs tank design, seismic anchorage, and capacity sizing across the United States, while Canada's National Building Code incorporates parallel requirements through provincial adoption frameworks. Factory Mutual Global certification shapes insurer-mandated specifications for commercial and industrial risk properties, effectively filtering market access for non-approved fabricators. Stakeholders must monitor evolving wildfire risk maps and corresponding water reserve multipliers that California's Office of the State Fire Marshal and comparable provincial authorities are embedding into land-use approvals.
Market Dynamics
NFPA 22's updated seismic anchorage and coating specifications are forcing engineered-systems providers to recertify entire product lines, compressing margins for fabricators lacking in-house metallurgical testing capabilities.
Growth Catalysts
- Data Center Campus Expansion:Hyperscale facilities across Texas and Arizona are mandating on-site fire suppression reserves independent of municipal infrastructure. These installations require million-gallon capacity ratings with rapid-fill protocols.
- NFPA 22 Standard Elevation:The National Fire Protection Association's revised engineering requirements for corrosion-resistant coatings and seismic design are triggering replacement cycles in earthquake-prone zones.
- Wildland-Urban Interface Mandates:California's Office of the State Fire Marshal is embedding water reserve multipliers into land-use approvals, compelling larger standby volumes for residential developments adjacent to high-risk zones.
Market Restraints
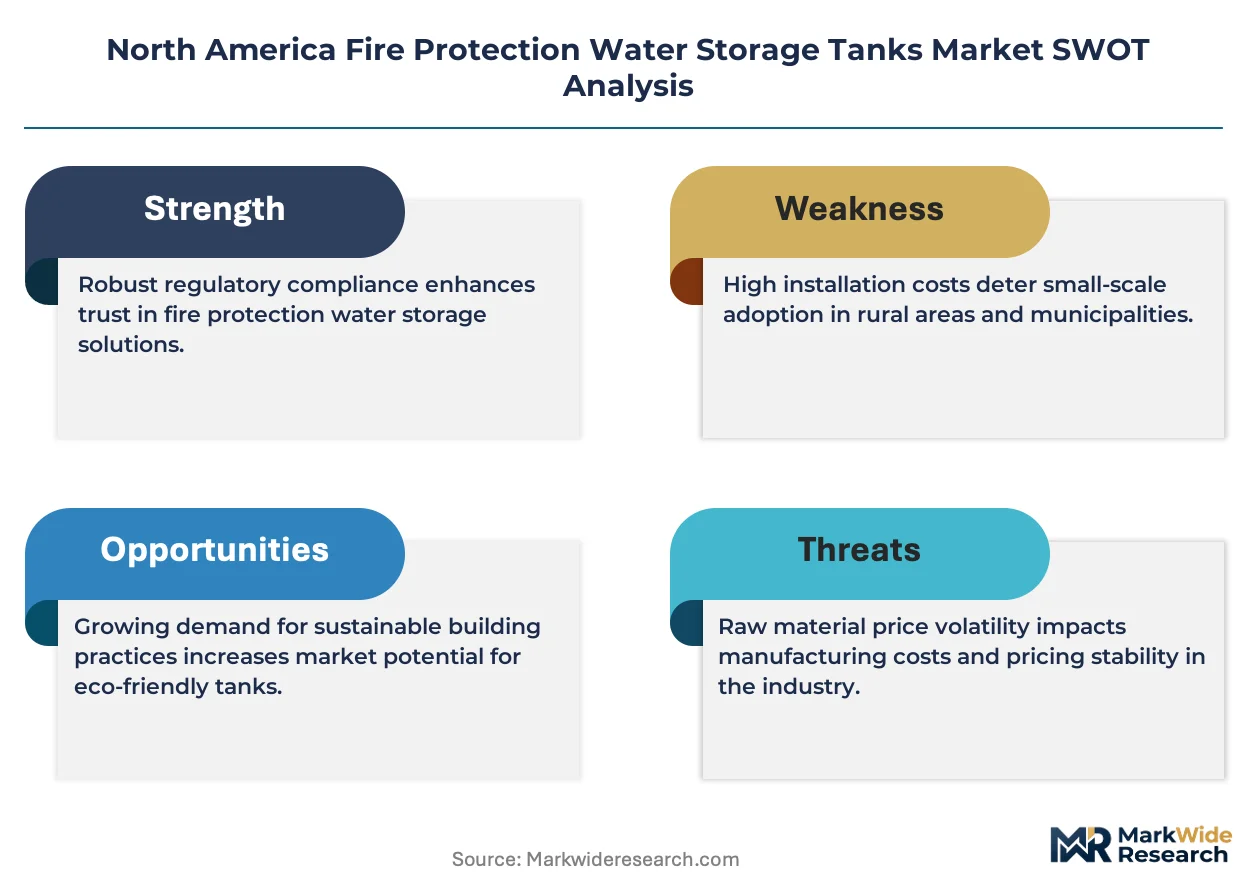
- Steel Input Volatility:Hot-rolled coil price fluctuations directly compress fabrication margins for welded-steel tank producers, particularly those locked into fixed-price municipal contracts.
- Factory Mutual Certification Concentration:Commercial property insurers effectively filter market access, creating a dual-vendor bottleneck where non-approved fabricators cannot bid on industrial risk properties.
- Concrete Curing Limitations:Precast concrete systems face extended installation timelines in northern climates, restricting seasonal deployment windows for underground municipal projects.
Strategic Opportunities
- Modular Bolted-Steel Deployment:Temporary construction sites and disaster-response staging areas across the US and Canada are adopting rapid-relocation configurations that bypass permanent foundation requirements.
- Provincial Code Harmonization:Canada's National Building Code adoption frameworks are creating pathways for US-certified fabricators to enter Ontario and British Columbia markets with minimal retesting.
- Fusion-Bonded Epoxy Convergence:Advanced coating systems paired with cathodic protection are extending service life in aggressive soil conditions, opening replacement demand in coastal and industrial corridor installations.
Industry Challenges
- Certified Welder Scarcity:American Welding Society-certified technicians for field-erected steel tanks command premium wages, constraining expansion timelines for regional fabricators.
- Legacy System Integration:Municipal water districts require seamless interconnection with aging hydrant networks, demanding custom valve configurations that extend engineering cycles.
- Seismic Recertification Backlogs:NFPA 22's updated anchorage calculations have overwhelmed third-party engineering review capacity, delaying project commencements in California and the Pacific Northwest.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Fire Protection Water Storage Tanks Market |
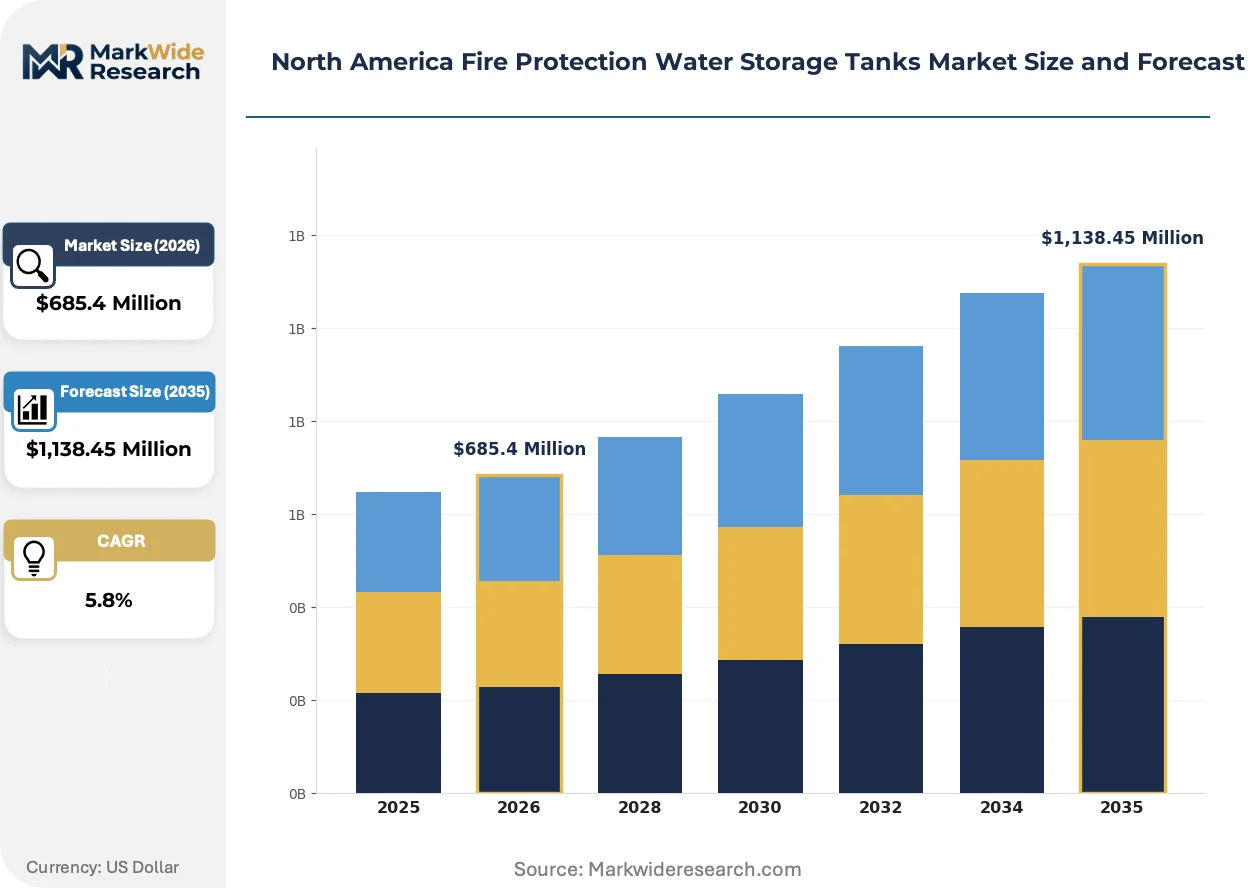
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,138.45 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Above Ground Tanks, Underground Tanks, Mobile Tanks, Fire Cisterns Installation: Permanent, Temporary, Modular, Custom-Built End User: Municipalities, Industrial Facilities, Commercial Buildings, Fire Departments Material: Steel, Concrete, Plastic, Fiberglass |
| Companies Covered | Tank Connection, Preload Inc., CST Industries, Inc., Fisher Tank Company, Highland Tank, Caldwell Tanks, Inc., Superior Tank Co. Inc, TF Warren Group, DN Tanks, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Fire Protection Water Storage Tanks Market Strategic Shifts & Innovations
Digital instrumentation and predictive maintenance protocols are redefining how fire protection water storage assets are monitored, shifting buyer expectations from passive infrastructure to actively managed emergency reserves.
Smart tank monitoring systems equipped with ultrasonic level sensors and cellular telemetry are digitizing compliance reporting for remote facilities. Industrial campuses with limited on-site maintenance staff are adopting these packages fastest, particularly in Arizona and Nevada where water theft and evaporation losses compound operational risks. The technology is digitizing what was previously manual inspection cycles, compressing insurance audit intervals from quarterly to real-time.
The National Fire Protection Association's 2023 coating durability amendments are elevating epoxy application thickness minimums and mandating holiday detection testing. Tank fabricators must now document every millimeter of fusion-bonded coverage or risk decertification. California's wildland-urban interface zones face the steepest compliance costs, driving specification changes that favor automated spray application over manual methods.
Buyers are consolidating vendor relationships around turnkey design-build contracts that bundle engineering, fabrication, and long-term maintenance. Municipal fire departments with constrained capital budgets are displacing traditional bid-specify-install sequences with performance-based agreements where contractors retain lifecycle responsibility. This pattern concentrates procurement authority in Texas and Florida where rapid population growth strains district engineering staff.
North America Fire Protection Water Storage Tanks Market Segmentation
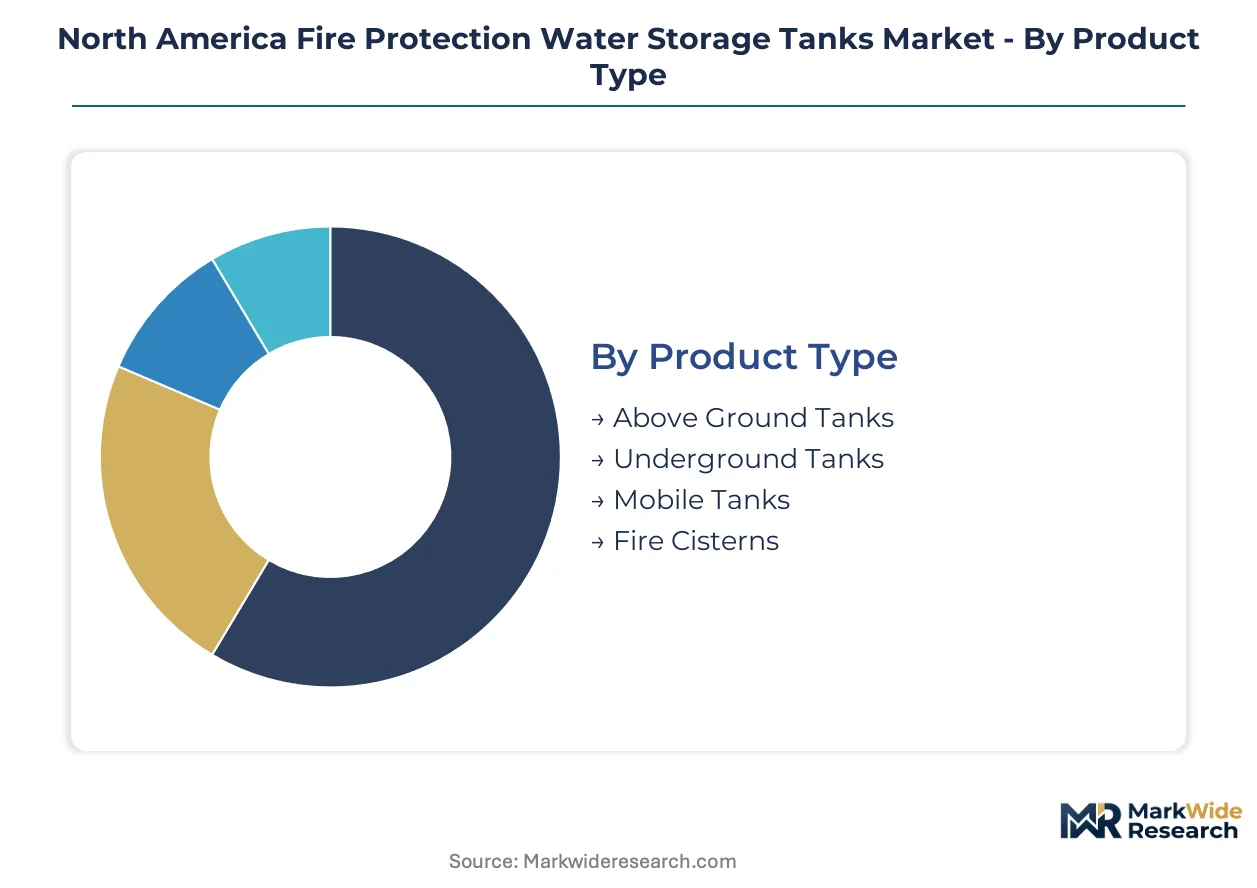
Fire protection water storage tanks segment across installation permanence, material durability, and end-user risk profiles. Each dimension shapes specification requirements, engineering cycles, and vendor selection criteria across North American procurement channels.
Product Type:
Volume capacity and site constraints determine which tank configuration delivers optimal fire suppression readiness for specific deployment contexts.
- Above Ground Tanks:Welded or bolted steel vessels ranging from thousands to millions of gallons anchor industrial corridor installations. Texas and Arizona data center campuses are mandating million-gallon capacities with rapid-fill protocols independent of municipal infrastructure.
- Underground Tanks:Precast concrete or steel systems with cathodic protection occupy minimal surface footprint. Urban fire departments in California and Florida with constrained real estate specify these for hydrant network reserves.
- Mobile Tanks:Trailer-mounted configurations serve temporary construction sites and disaster-response staging areas.
- Fire Cisterns:Below-grade concrete reservoirs with dedicated pump connections address wildland-urban interface zones.
Above ground tanks command the established base. The steepest expansion runs through mobile tanks.
Installation:
Project timelines and foundation requirements separate rapid-deployment solutions from engineered permanent infrastructure.
- Permanent:Engineered foundations with seismic anchorage per NFPA 22 standards support decades-long service life. California municipalities face recertification backlogs as updated anchorage calculations overwhelm third-party engineering review capacity.
- Temporary:Surface-mounted systems bypass excavation for construction-phase coverage. Arizona and Nevada industrial sites adopt these fastest to satisfy insurer mandates during facility buildout.
- Modular:Bolted-steel panels enable field assembly without certified welders. Canada's northern provinces specify these to compress seasonal deployment windows.
- Custom-Built:Site-specific engineering addresses irregular topography or legacy hydrant interconnection requirements.
Permanent installations retain the largest share of installed capacity. Modular configurations are climbing the fastest as procurement shifts toward rapid-deployment specifications.
End User:
Risk exposure and regulatory oversight intensity vary sharply across municipal, industrial, commercial, and emergency response procurement channels.
- Municipalities:Water districts mandate standby volumes for hydrant networks and residential sprinkler coverage. California's Office of the State Fire Marshal embeds water reserve multipliers into land-use approvals for wildland-urban interface developments.
- Industrial Facilities:Petrochemical processors and manufacturing campuses require dedicated reserves per Factory Mutual Global certification. Insurer-mandated specifications filter market access to approved fabricators exclusively.
- Commercial Buildings:High-rise developments and retail centers specify smaller-capacity systems tied to automatic sprinkler networks.
- Fire Departments:Rural districts with limited hydrant infrastructure deploy standalone tanks for tanker truck refill operations.
Industrial facilities concentrate premium specification demand. Municipal procurement channels are gaining share fastest as wildland-urban interface mandates expand.
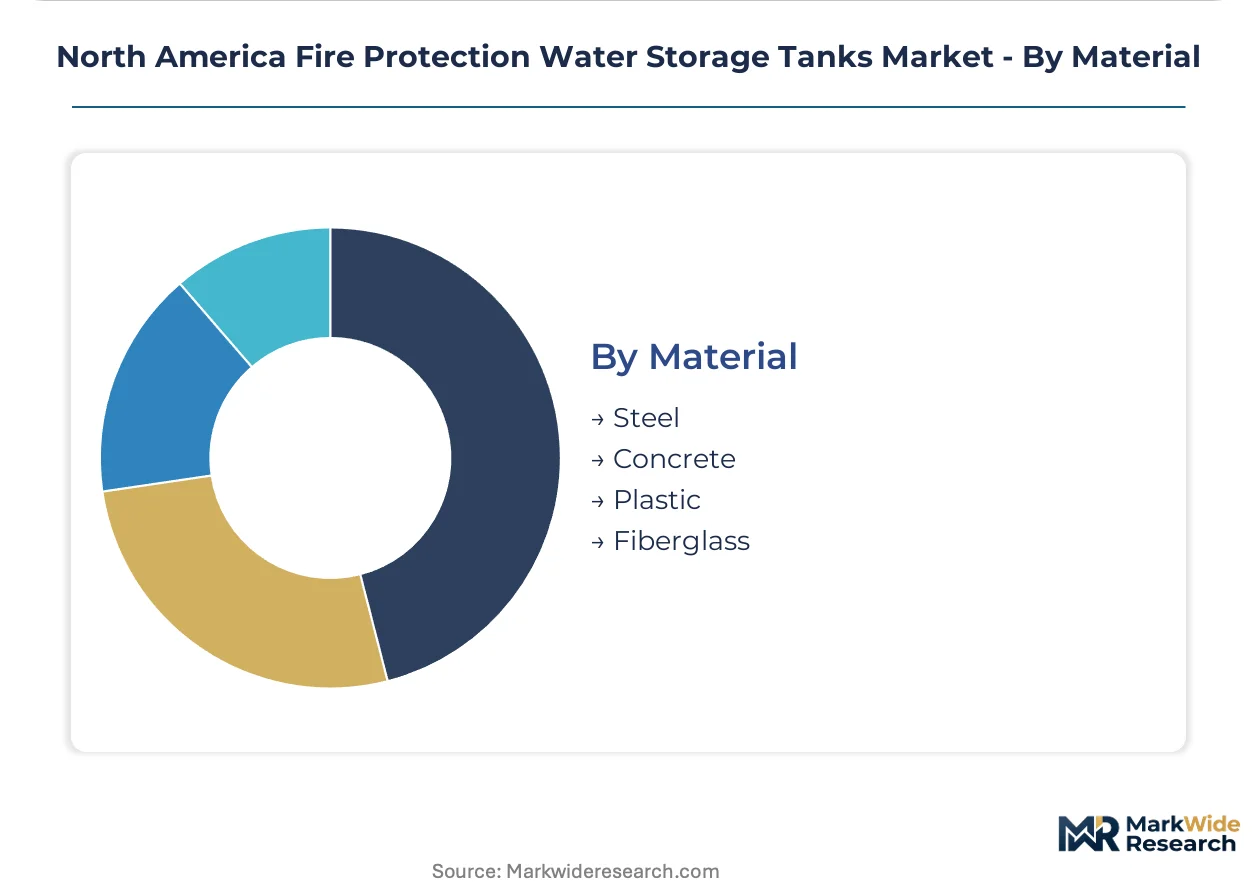
Material:
Corrosion resistance, seismic performance, and capital outlay tradeoffs drive material selection across soil conditions and climate zones.
- Steel:Fusion-bonded epoxy coatings extend service life in aggressive soil conditions. Tank fabricators now document every millimeter of coverage per NFPA 2023 amendments or risk decertification.
- Concrete:Precast systems deliver decades of underground durability. Northern climates restrict seasonal deployment due to extended curing requirements.
- Plastic:Polyethylene tanks serve lower-capacity commercial applications with minimal maintenance requirements.
- Fiberglass:Corrosion-proof construction suits coastal and chemical exposure environments.
Steel dominates current installations by volume. Fiberglass is expanding most quickly in coastal corridor replacement cycles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Canadian fabricators export bolted-steel tank systems to U.S. municipal buyers across the Pacific Northwest and Upper Midwest, leveraging provincial code harmonization to minimize retesting burdens.
United States
Texas data center campuses and Arizona hyperscale facilities mandate million-gallon on-site reserves with rapid-fill protocols independent of municipal infrastructure. The National Fire Protection Association's NFPA 22 standard governs seismic anchorage and coating specifications nationwide. California's wildland-urban interface zones concentrate demand where the Office of the State Fire Marshal embeds water reserve multipliers into land-use approvals.
Canada
Ontario and British Columbia municipal water districts specify standby volumes for hydrant networks and residential sprinkler coverage under provincial adoption frameworks of the National Building Code. Factory Mutual Global certification filters market access for commercial and industrial risk properties. Alberta's oil sands processing corridors anchor industrial procurement for petrochemical fire suppression reserves.
Mexico
Northern border states concentrate manufacturing campus expansion requiring dedicated fire suppression infrastructure. The country's national building code regulator incorporates seismic design requirements parallel to U.S. standards. Monterrey and Tijuana industrial clusters specify above-ground steel systems for rapid deployment during facility construction phases.
North America Fire Protection Water Storage Tanks Market Key Industry Players
Channel-controlling players compete with product-specialist players across certification-gated procurement channels. Factory Mutual Global approval creates a dual-vendor bottleneck where non-certified fabricators cannot bid on industrial risk properties. Three archetypes dominate: vertically integrated tank fabricators with in-house metallurgical testing, regional specialists in turnkey underground concrete systems, and modular bolted-steel providers serving temporary deployment markets. Capacity expansion and strategic partnerships represent the dominant competitive moves as fabricators address seismic recertification backlogs.
Among U.S.-based fabricators, Tank Connection exemplifies the vertically integrated archetype with proprietary coating capabilities, while CST Industries, Inc. occupies a position representing manufacturing scale across multi-facility networks. Highland Tank anchors the underground concrete specialization tier for urban fire departments with constrained surface area. These three represent distinct strategic positions within a certification-concentrated competitive structure.
| Leading Market Players |
|---|
| Tank Connection |
| Preload Inc. |
| CST Industries, Inc. |
| Fisher Tank Company |
| Highland Tank |
| Caldwell Tanks, Inc. |
| Superior Tank Co. Inc |
| TF Warren Group |
| DN Tanks |
| Others |
Cost & Logistics Intelligence
Steel input volatility determines both pricing tier spreads and supply chain shape across the North America fire protection water storage tanks market. Hot-rolled coil price fluctuations compress fabrication margins for welded-steel producers locked into fixed-price municipal contracts, forcing tier separation between certified and non-certified fabricators.
Pricing Analysis
The pricing gap between legacy coating systems and fusion-bonded epoxy specifications widened following NFPA's 2023 amendments. Three-tier pricing structure across premium certified, standard approved, and economy non-certified levels separates Factory Mutual Global-approved fabricators from regional competitors. Price differentiation hinges on certification tier and seismic engineering depth. Cost compression in economy tiers intensifies because municipal procurement offices prioritize lowest-bid compliance over lifecycle value. Industrial facilities with insurer mandates show least price sensitivity; rural fire districts with grant-dependent budgets exhibit highest.
Supply Chain Analysis
Export-control regimes on advanced cathodic protection technologies limit component flows from select jurisdictions into North American fabrication networks. Raw material supply concentrates in the United States, Canada, and Mexico under USMCA provisions. Steel coil, epoxy resin, and sacrificial anode systems anchor component dependencies. Single-source vulnerability runs through specialized fusion-bonded powder coating suppliers serving seismic-certified tank producers. Distribution runs through engineer-procure-construct contractors and municipal procurement offices with multi-year maintenance bundling.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The North America fire protection water storage tanks market sits at a regulatory inflection where NFPA 22 seismic recertification demands are accelerating replacement cycles. Smart instrumentation convergence is reshaping buyer expectations from passive infrastructure to managed service relationships.
For Market Incumbents: Insulate certified market position through captive metallurgical testing capabilities and in-house seismic engineering review capacity. Factory Mutual Global approval concentration creates defensive moats against non-certified competitors. Backward integration into epoxy coating production secures margin control against resin price volatility. For New Entrants and Emerging Players: Pursue modular bolted-steel deployment opportunities in Canada's northern provinces and Arizona construction-phase markets where rapid relocation specifications bypass permanent foundation requirements. Disaster-response staging areas offer lowest certification barriers. Partner with regional engineer-procure-construct contractors to bypass direct municipal bidding complexity. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors vertically integrated fabricators with proprietary coating capabilities. Long-term viability rests on lifecycle service contract penetration and smart monitoring technology integration. Acquisition targets should demonstrate NFPA 22 recertification completion and established Factory Mutual Global relationships. Watch California wildland-urban interface mandate expansion as volume inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Seismic Recertification Investment | NFPA 22 compliance unlocks California and Pacific Northwest municipal procurement channels. |
| Smart Monitoring Platform Integration | Cellular telemetry packages compress insurance audit intervals for Arizona industrial campuses. |
| Modular Bolted-Steel Capacity Expansion | Panel fabrication networks serve Canada's compressed seasonal deployment windows. |
| Fusion-Bonded Epoxy Backward Integration | In-house coating control secures margin against resin price volatility in aggressive soil markets. |
| Turnkey Design-Build Partnership | Performance-based agreements concentrate procurement authority with Texas municipal fire districts. |
Research Approach
A standing panel of tank fabrication executives, municipal fire district procurement officers, Factory Mutual Global certification engineers, and engineer-procure-construct contractors provided ongoing calibration across primary research phases. Secondary validation drew from NFPA technical committee minutes, municipal bid-tabulation databases, steel trade association shipment reports, and provincial building code adoption frameworks. Bottom-up tank shipment tallies by capacity tier and top-down infrastructure spending analysis triangulated market sizing.
Scenario-bracketing anchored the analytical framework across the projection horizon, with high-growth and constrained-permitting pathways testing sensitivity to wildland-urban interface mandate expansion. Segmentation dimensions modeled include installation permanence, material durability grade, end-user risk profile, and regional regulatory cluster. CAGRs derived from fitted adoption curves against historical replacement cycle data. Forecast inputs incorporated data center campus pipeline tracking and seismic recertification backlog monitoring.
Sensitivities concentrate around steel price volatility, Factory Mutual Global certification timeline delays, and California wildfire risk map revisions. Forecasts reflect documented assumptions on NFPA 22 enforcement intensity and provincial code harmonization pace. Material shifts in federal infrastructure spending allocation or USMCA steel tariff adjustments would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fire Safety & Protection
Fire Department Software Market
Fire Safety & Protection
Global Fire Control System Market
Fire Safety & Protection
Flame Barrier Market
Fire Safety & Protection
Global Portable Foam Fire Extinguisher Market
Fire Safety & Protection
Civil Combustible Gas Alarm Market
Fire Safety & Protection
Fireproof Insulation Market
Fire Safety & Protection
Commercial Smoke Alarm Market
Fire Safety & Protection
Fire Extinguisher Inspection Services Market
Fire Safety & Protection
Fire Resistant Silicone Sealant Market
Fire Safety & Protection
Smart Smoke Detector Market
Fire Safety & Protection
Global Flame Detector Market
Fire Safety & Protection
Global Fire Resistant Cable Market
Fire Safety & Protection
GCC Firefighting Foam Market
Fire Safety & Protection
Fire Door Market
Fire Safety & Protection
Fire Safety Systems Market
Fire Safety & Protection
Europe Fire-Resistant Glass Market