
 Parts and Equipment Market | 2026-2036
Parts and Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Parts and Equipment Market Analytics
Direct-to-fleet digital parts procurement is reshaping how construction and agricultural operators source replacement components. Caterpillar leverages its dealer network and proprietary parts platform to sustain captive aftermarket revenue across North American mining fleets. Komatsu anchors its competitive position through telematics-integrated predictive maintenance, which preemptively triggers parts shipments before field failures occur.
Parts and equipment encompass mechanically engineered components—gear sets with AGMA 2001-D04 tolerances, ISO 281-rated rolling-element bearings, and ASTM A193 alloy steel fasteners—fabricated through subtractive and formative processes to restore or extend capital asset function. CNC machining dominates precision-critical aerospace and automotive applications where surface finishes below Ra 0.8 micrometers are mandatory, while casting retains cost advantage for construction equipment housings and marine propulsion components. Gear and bearing categories command the deepest margin pools due to metallurgical complexity and certification requirements, whereas fastener segments compete primarily on volume scale and logistics velocity.
The EPA's Tier 4 Final and Stage V emissions frameworks compel parts suppliers to engineer exhaust aftertreatment-compatible components, while ISO 9001 and AS9100 quality standards govern market access for aerospace and defense applications. China's SAMR enforces GB standards on imported machinery components, creating compliance barriers for uncertified foreign suppliers. Stakeholders must monitor evolving carbon-border adjustment mechanisms and material traceability mandates to align sourcing strategies with regulatory trajectories.
Market Dynamics
Fleet operators across North America and Asia-Pacific are extending equipment replacement cycles, forcing suppliers to pivot from new unit sales toward aftermarket parts and retrofit-compatible component engineering.
Growth Catalysts
- EPA Tier 4 Final and EU Stage V frameworks:Emissions mandates compel exhaust aftertreatment retrofits, generating demand for compatible turbochargers, diesel oxidation catalysts, and selective catalytic reduction modules in heavy machinery.
- Predictive maintenance platforms:Telematics-integrated sensor networks now trigger automated parts replenishment before field failures, compressing downtime and locking in supplier relationships.
- Germany's industrial corridor concentration:Precision-engineered bearing and gear manufacturing clusters in Baden-Württemberg and Bavaria supply exacting-tolerance components to automotive and aerospace OEMs.
Market Restraints
- Alloy steel input volatility:ASTM A193-grade fastener and gear stock prices fluctuate with nickel and chromium spot markets, compressing margin stability for mid-volume fabricators.
- China SAMR GB standard enforcement:Uncertified foreign suppliers face mandatory testing and documentation barriers for imported machinery components, delaying market entry.
- Additive manufacturing substitution:Metal 3D printing for low-volume aerospace brackets and repair geometries threatens subtractive machining demand in prototyping and legacy part reproduction.
Strategic Opportunities
- India's PLI scheme for capital goods:Production-linked incentives for precision component manufacturing attract greenfield CNC machining investments serving domestic construction and mining fleets.
- Carbon-border adjustment mechanisms:EU CBAM phase-in creates first-mover advantage for suppliers with verified Scope 3 emissions data and material traceability systems.
- Direct-to-fleet digital platforms:Bypassing traditional dealer networks, construction operators now source replacement parts through proprietary procurement portals, disintermediating legacy distribution tiers.
Industry Challenges
- AS9100 and ISO 9001 certification timelines:Aerospace and defense market access requires 12-18 month quality system audits, constraining cash flow for specialty gear and bearing entrants.
- Legacy equipment interoperability:Pre-Tier 4 machinery fleets require adapter kits and modified mounting geometries, multiplying SKU complexity and inventory carrying costs.
- Metallurgical talent scarcity:Heat treatment and precision grinding expertise concentrates among aging workforces in Japan and Germany, limiting knowledge transfer to emerging manufacturing bases.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Parts and Equipment Market |
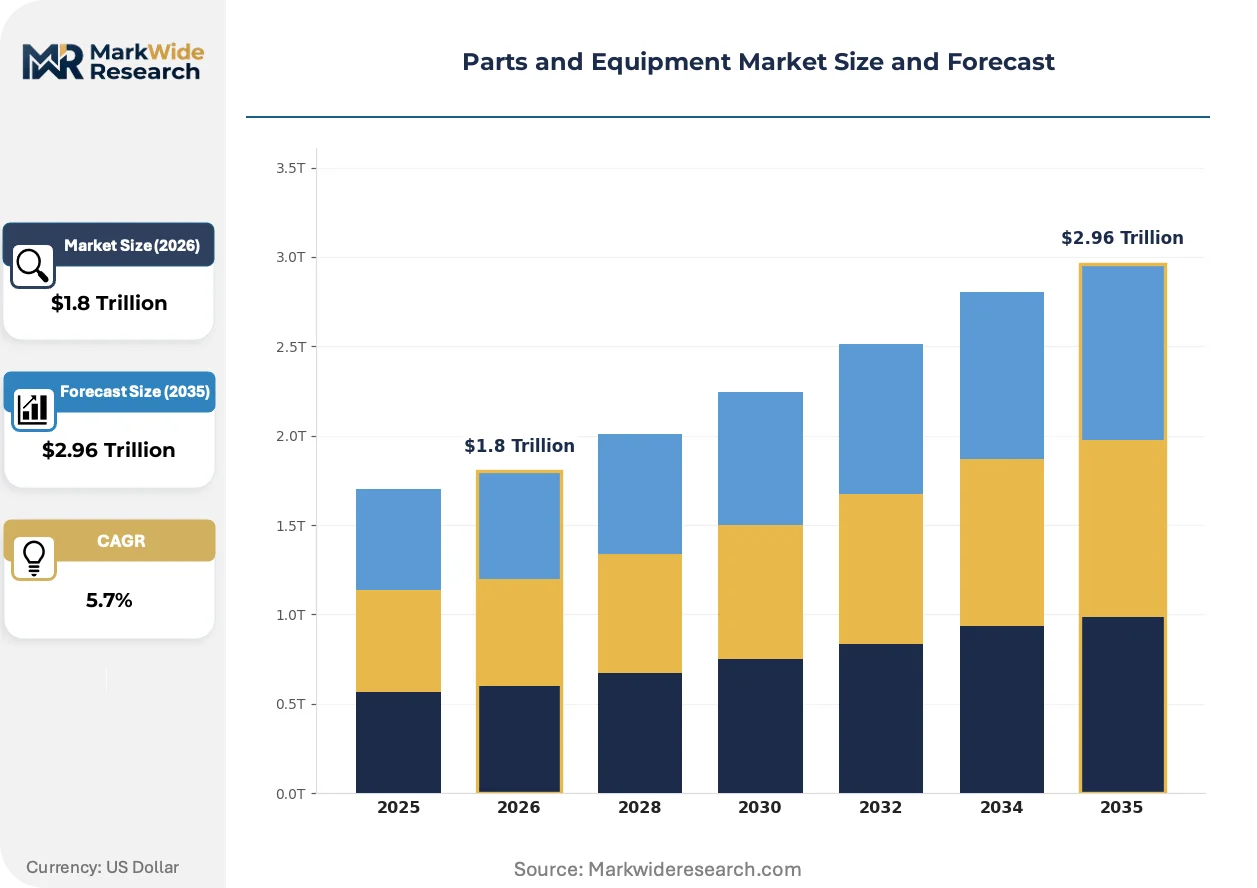
| Market Size in 2026 | $1.8 Trillion |
| Market Size in 2035 | $2.96 Trillion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Gear, Bearings, Fasteners, Valves Technology: 3D Printing, CNC Machining, Injection Molding, Casting Application: Aerospace, Automotive, Construction, Marine End User: Manufacturers, Distributors, Repair Shops, OEMs |
| Companies Covered | Hitachi Construction Machinery, CNH Industrial, Caterpillar, Liebherr, Atlas Copco Group, Komatsu, JCB, John Deere, Volvo Construction Equipment, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Parts and Equipment Market Evolving Landscape
Component engineering is converging around emissions compliance, digital lifecycle management, and supply chain transparency, reshaping how parts are specified, procured, and serviced across capital-intensive industries.
Advanced high-strength steels and powder metallurgy is hybridizing traditional gear and bearing production, blending wrought alloy performance with near-net-shape forming economics. Mining and construction OEMs in Australia and Canada are specifying these hybrid-process components for high-load transmission applications. The technology is compressing lead times for AGMA 2001-D04 precision gears while reducing raw material waste in subtractive finishing operations.
The EU F-Gas Regulation and China's dual carbon goals are tightening refrigerant and hydraulic fluid containment standards for mobile machinery. Component suppliers must now engineer sealed bearing assemblies and impermeable hose couplings compatible with low-global-warming-potential working fluids. German and Japanese hydraulic system manufacturers are accelerating validation programs for bio-based fluid compatibility, locking in specification advantages for compliant parts vendors.
Construction and agricultural fleet managers are unbundling after-sales service from equipment purchase contracts, negotiating standalone parts availability agreements with penalty clauses for stockout delays. This behavioral shift disrupts traditional dealer-captive parts revenue models. North American mining operators are pioneering this approach, demanding real-time inventory visibility and 48-hour emergency fulfillment guarantees from independent distributors.
Parts and Equipment Market Segmentation
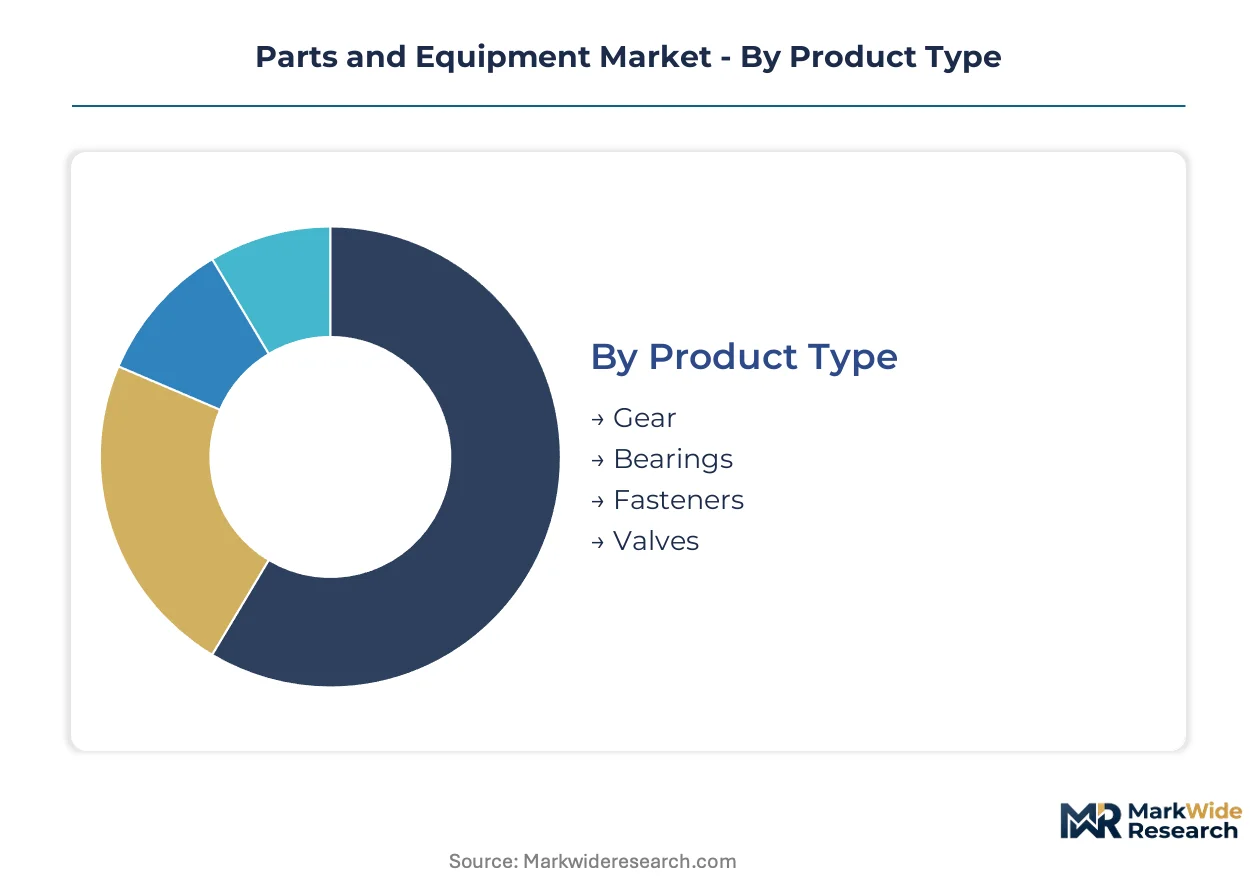
Component specification varies sharply across capital-intensive industries, with tolerance grades, material certifications, and interoperability requirements dictating supplier selection. Segmentation reveals where margin pools concentrate and which technical capabilities unlock market access.
Product Type:
Demand spans from precision-rotational systems to structural joining elements, with metallurgical complexity determining pricing power and certification barriers.
- Gear:AGMA 2001-D04 precision gear sets transmit torque in heavy machinery drivetrains with surface hardness above 58 HRC. Mining fleet operators in Australia specify these for haul truck transmissions, driven by extended replacement cycles and predictive maintenance adoption.
- Bearings:ISO 281-rated rolling-element bearings manage radial and axial loads with L10 life calculations exceeding 10,000 hours. German automotive OEMs in Baden-Württemberg source these for powertrain assemblies, constrained by AS9100 certification requirements that limit qualified supplier pools.
- Fasteners:ASTM A193 alloy steel bolts and studs secure pressure-boundary joints in construction and marine applications.
- Valves:Flow-control components regulate hydraulic and pneumatic circuits across mobile machinery fleets.
The dominant share belongs to Bearings, while Gear is closing the gap fastest.
Technology:
Process selection trades precision against throughput, with aerospace and construction applications diverging on surface finish requirements and lot size economics.
- CNC Machining:Subtractive manufacturing achieves Ra 0.8 micrometer surface finishes through multi-axis milling and grinding operations. Aerospace tier-one suppliers in France and Italy dominate this segment, leveraging AS9100-certified workflows for airframe bracket production.
- 3D Printing:Powder-bed fusion builds titanium and Inconel geometries without tooling investment for low-volume aerospace repair components. NASA and ESA contractors in the US and Germany are qualifying these parts for satellite propulsion hardware, displacing legacy forging for complex manifolds.
- Casting:Sand and investment casting produce near-net-shape housings and marine propulsion components at volume scale.
- Injection Molding:Thermoplastic and metal injection molding deliver high-volume polymer gears and structural fasteners for automotive interiors.
CNC Machining retains the largest installed base, though 3D Printing is expanding most quickly in aerospace aftermarket applications.
Application:
End-use industries impose distinct certification regimes and performance validation protocols that reshape supplier competitive requirements.
- Aerospace:AS9100 and NADCAP-accredited components must demonstrate traceability from melt source through heat treatment. Boeing and Airbus supply chains in Washington State and Toulouse demand this documentation for flight-critical gear and bearing assemblies, with audit cycles spanning 18-24 months.
- Construction:EPA Tier 4 Final and EU Stage V aftertreatment compatibility drives turbocharger and exhaust component specifications. Caterpillar and Komatsu fleet operators in Texas and Alberta prioritize retrofit-ready parts inventory, compressing procurement lead times through direct-to-fleet platforms.
- Automotive:Powertrain and chassis components face IATF 16949 quality mandates and zero-defect ppm targets.
- Marine:Saltwater corrosion resistance and Lloyd's Register classification govern propulsion and deck machinery specifications.
Aerospace commands premium pricing, while Construction is gaining share fastest through aftermarket parts procurement transformation.
End User:
Channel structure determines inventory risk allocation and technical support obligations across the value chain.
- OEMs:Original equipment manufacturers specify certified components for new unit assembly with multi-year supply agreements. Siemens and ABB industrial drivetrain divisions in Germany and Switzerland lock in bearing suppliers through 3-5 year contracts with price-adjustment clauses tied to alloy steel indices.
- Repair Shops:Independent maintenance facilities source replacement parts through distributor networks with 24-48 hour availability guarantees. US mining repair contractors in Nevada and Arizona now bypass dealers through digital procurement portals, disintermediating traditional tiered distribution.
- Manufacturers:Tier-two and tier-three fabricators integrate purchased components into subassemblies for upstream OEM supply.
- Distributors:Inventory-carrying intermediaries consolidate SKU breadth and logistics velocity for fragmented end-user bases.
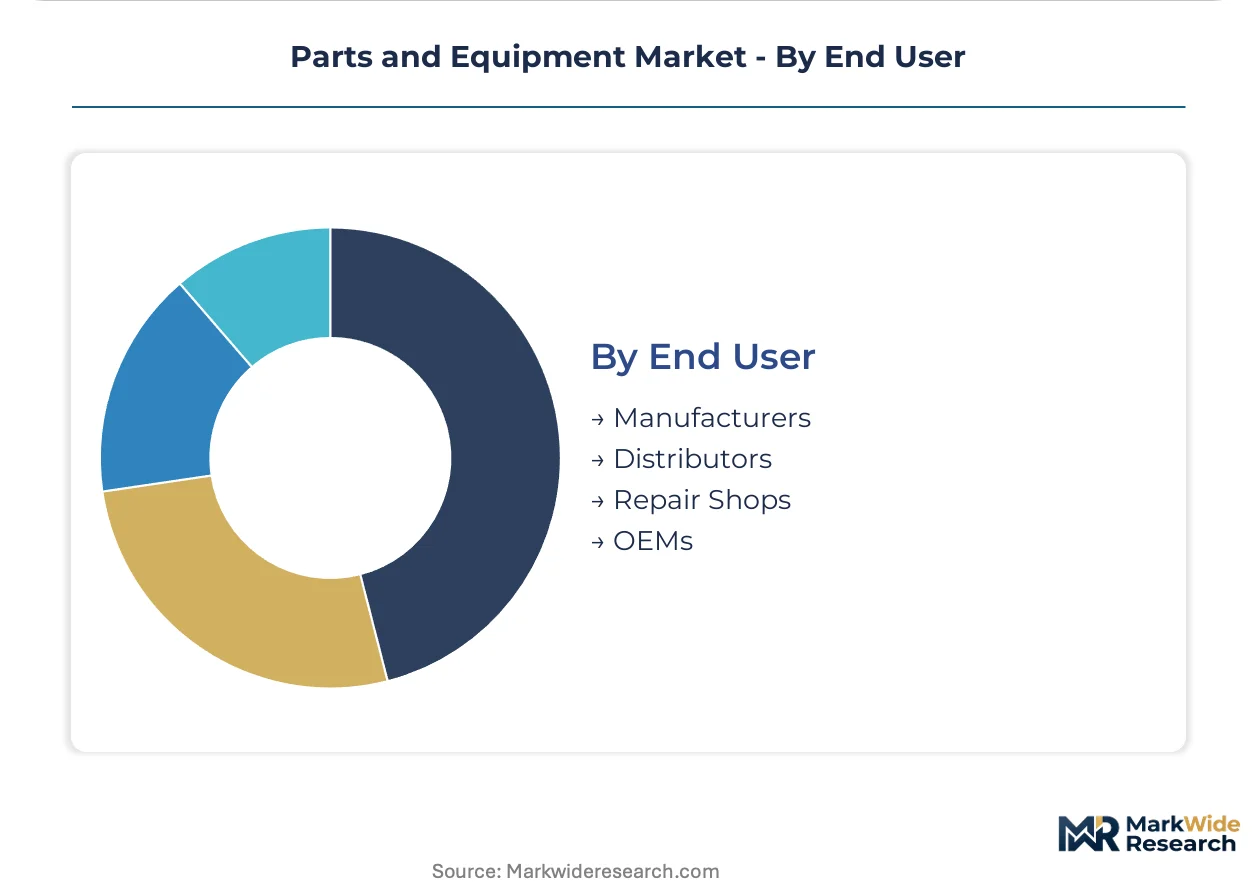
OEMs represent the largest revenue concentration, while Repair Shops are climbing the fastest through digital procurement disintermediation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Hamburg anchors Germany's industrial corridor, channeling precision-engineered bearings and gear sets from Baden-Württemberg workshops to automotive and aerospace OEMs worldwide. This maritime gateway underwrites Europe's densest concentration of AGMA-certified component manufacturing.
United States
Texas shale basins and Nevada mining districts drive turbocharger and exhaust aftertreatment demand as EPA Tier 4 Final deadlines compel fleet retrofits. The Department of Energy enforces efficiency standards on industrial drivetrain components. Houston's energy corridor hosts Caterpillar and Komatsu service hubs that now source directly through digital procurement portals, bypassing traditional dealer tiers.
Germany
Automotive powertrain and industrial automation OEMs in Stuttgart and Munich consume ISO 281-rated bearings with exacting tolerance requirements. The EU F-Gas Regulation mandates sealed bearing assemblies compatible with low-GWP hydraulic fluids. Bavaria's precision engineering cluster around Augsburg and Nuremberg supplies Siemens and ABB with multi-year contracted gear assemblies.
China
Construction equipment replacement cycles lengthening across Inner Mongolia mining belts and Yangtze River Delta infrastructure projects shift procurement toward aftermarket parts. SAMR enforces GB standards on imported machinery components, creating compliance barriers for uncertified foreign suppliers. Zhengzhou and Xuzhou manufacturing bases concentrate CNC machining capacity serving domestic mining fleet operators.
Japan
Telematics-integrated predictive maintenance platforms trigger automated parts replenishment for construction and mining fleets before field failures occur. METI promotes carbon-neutral manufacturing targets for heavy machinery components. Nagoya's industrial belt retains concentrated heat treatment and precision grinding expertise, though workforce aging constrains knowledge transfer.
India
Domestic mining and construction fleet expansion under the PLI scheme for capital goods attracts greenfield CNC machining investments. BIS certification requirements govern imported machinery component quality. Gujarat and Tamil Nadu industrial corridors host emerging precision component fabricators serving both domestic OEM assembly and aftermarket repair channels.
Parts and Equipment Market Competitive Landscape
On the supply side, the industry is consolidating around three distinct tiers: integrated OEM-captive parts divisions, independent precision specialists with AS9100 certification, and volume-scale fastener distributors competing on logistics velocity. Strategic archetypes include telematics-enabled predictive maintenance providers, carbon-border-ready suppliers with verified Scope 3 data, and direct-to-fleet digital platform operators. Dominant competitive moves encompass backward integration into heat treatment capabilities and strategic partnerships with alloy steel mills to secure ASTM A193-grade stock.
Among diversified machinery manufacturers, Caterpillar and Komatsu exemplify the OEM-captive archetype, leveraging proprietary dealer networks and telematics platforms to lock in aftermarket parts revenue. Hitachi Construction Machinery represents the precision-engineering tier, occupying a position within Japan's concentrated metallurgical expertise cluster. These three anchors illustrate how geographic manufacturing heritage and digital procurement capabilities now jointly determine competitive positioning.
| Leading Market Players |
|---|
| Hitachi Construction Machinery |
| CNH Industrial |
| Caterpillar |
| Liebherr |
| Atlas Copco Group |
| Komatsu |
| JCB |
| John Deere |
| Volvo Construction Equipment |
| Others |
Value Network & Pricing Analysis
German precision-engineering clusters around Stuttgart and Augsburg concentrate AGMA-certified gear and bearing production, anchoring premium pricing power for exacting-tolerance components demanded by automotive and aerospace OEMs. This geographic concentration of metallurgical expertise and certification infrastructure directly shapes where margin pools accumulate downstream.
Pricing Analysis
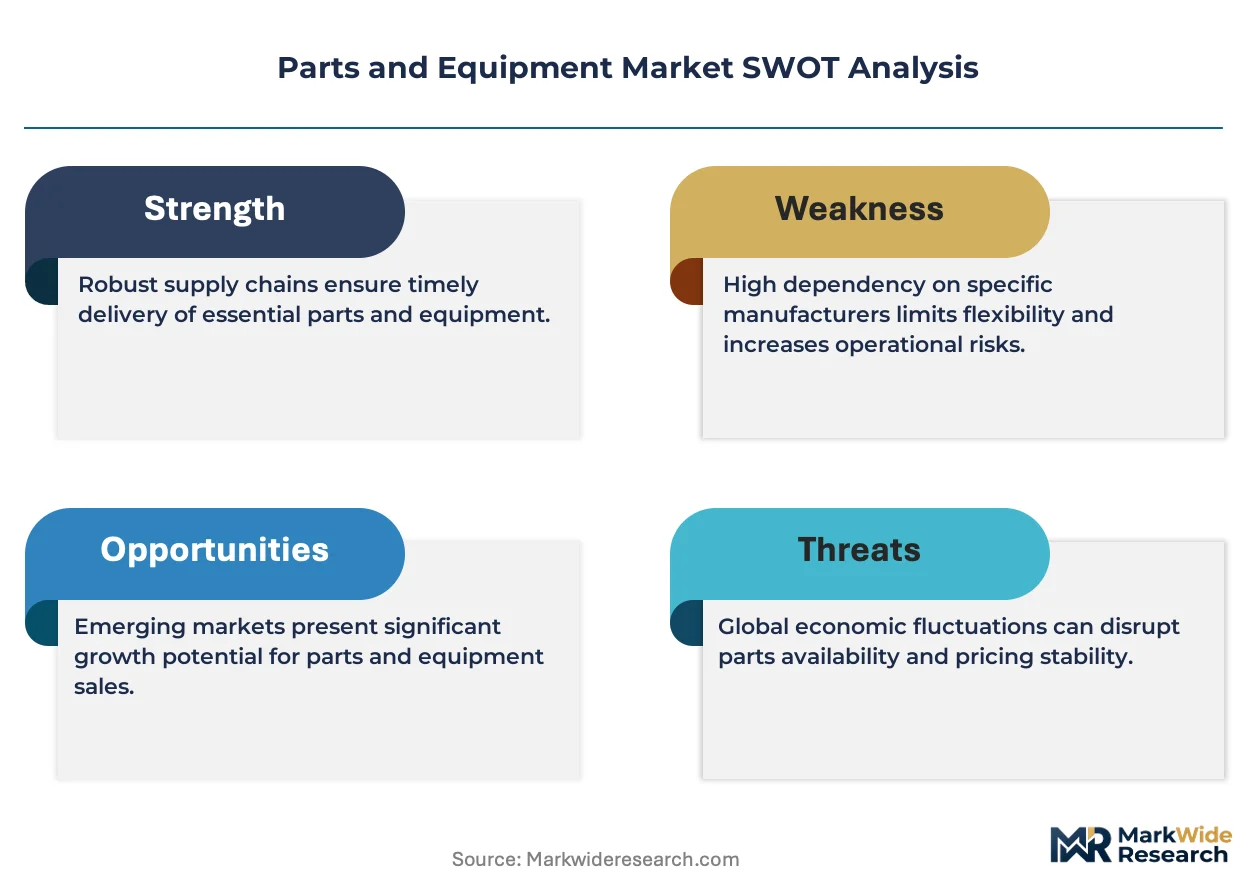
Three-tier pricing structure across premium, standard, and economy levels separates AS9100-certified aerospace bearings from construction-grade fasteners and commodity hardware. Price differentiation hinges on certification grade and volume scale, with OEM long-term contracts commanding stability against spot-market volatility. Cost compression in standard-tier fasteners is intensifying because Chinese volume producers are expanding CNC capacity under domestic PLI incentives. Repair shops exhibit highest price sensitivity due to inventory carrying constraints, while aerospace OEMs prioritize certification compliance over unit cost.
Supply Chain Analysis
Extended payment terms and supply-chain finance facilities from German and Japanese tier-one suppliers are squeezing mid-volume fabricators in India and Southeast Asia. Raw material sourcing draws from Chinese alloy steel mills, Swedish bearing steel producers, and Australian nickel-chromium suppliers. Single-source vulnerability concentrates in heat treatment and precision grinding capabilities concentrated among aging workforces in Japan and Germany. Distribution runs through OEM-captive dealer networks, independent distributor networks, and emerging direct-to-fleet digital platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Parts and Equipment Market is entering a cyclical recovery phase driven by construction equipment replacement cycle extension across North American mining belts. Fleet operators are prioritizing aftermarket parts procurement over new unit purchases, creating sustained demand visibility for component suppliers.
For Market Incumbents: Insulate captive aftermarket revenue by deepening telematics-integrated predictive maintenance platforms that preemptively trigger parts shipments before field failures occur. Secure backward integration into heat treatment capabilities to protect against metallurgical talent scarcity in Japan and Germany. Prioritize AS9100 recertification investments to maintain aerospace market access against emerging precision specialists.
For New Entrants and Emerging Players: Build out carbon-border-ready supply chains with verified Scope 3 emissions data and material traceability systems to capture first-mover advantage as EU CBAM phase-in accelerates. Target India's PLI-supported precision component manufacturing corridors in Gujarat and Tamil Nadu, where domestic mining fleet expansion outpaces qualified supplier capacity. Pursue direct-to-fleet digital procurement partnerships with North American construction operators seeking to bypass traditional dealer tiers.
For Investors and Strategic Acquirers: Capital is best deployed toward AS9100-certified precision specialists with established aerospace supply relationships and multi-year contracted revenue visibility. Long-term viability favors suppliers with demonstrated interoperability engineering for pre-Tier 4 legacy equipment adapter kits. Watch for inflection signals in alloy steel spot market stabilization and SAMR GB standard enforcement intensity affecting import compliance timelines.
| Strategic Initiative | Industry Significance |
|---|---|
| Predictive Maintenance Platform Deployment | Komatsu and Caterpillar leverage telematics to lock in aftermarket parts revenue through automated replenishment triggers. |
| Carbon-Border Compliance Investment | Suppliers with verified Scope 3 data capture EU CBAM first-mover advantage against uncertified competitors. |
| Direct-to-Fleet Digital Platform Launch | Independent distributors disintermediate legacy dealer networks by offering 48-hour emergency fulfillment guarantees. |
| Heat Treatment Capability Integration | Backward integration into metallurgical processing protects against talent scarcity in Japan's aging industrial belt. |
| Legacy Equipment Interoperability Engineering | Adapter kit development for pre-Tier 4 machinery fleets multiplies SKU breadth and inventory carrying requirements. |
Research Methodology
Initial hypotheses were tested against primary input from maintenance directors at mining and construction fleets, OEM procurement teams at Caterpillar and Komatsu, aftermarket service heads, and precision component manufacturing executives, and refined through secondary validation. Bottom-up demand modeling incorporated customs and trade data, SEC 10-K filings from diversified machinery manufacturers, AGMA and ISO certification registry analysis, and alloy steel spot market indices. Top-down triangulation cross-referenced capital expenditure disclosures from aerospace and automotive OEMs with regional industrial production statistics.
Demand-supply-balance framing anchored the analytical framework across the projection horizon, with segmentation dimensions spanning product type, manufacturing technology, end-use application, and channel structure. CAGRs were derived from regression analysis against equipment replacement cycle trends, emissions regulatory phase-in schedules, and fleet telematics adoption curves. Industry-specific forecast inputs included EPA Tier 4 Final and EU Stage V compliance deadlines, China's dual carbon policy trajectory, and India's PLI scheme disbursement patterns for capital goods.
Stress conditions across alloy steel price volatility, SAMR enforcement intensity, and additive manufacturing substitution rates were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding regulatory implementation timelines and fleet operator procurement behavior evolution. Macroeconomic contraction, accelerated additive manufacturing adoption, or unilateral tariff escalation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Equipment
Global Industrial Enclosures Market
Industrial Equipment
UV Conveyor Systems Market
Industrial Equipment
Soldering Iron Market
Industrial Equipment
Electric Cartridge Heaters Market
Industrial Equipment
Demagnetizer Market
Industrial Equipment
Digital Servo Press Market
Industrial Equipment
Chemical Storage Tank and Bottle for Semiconductor Market
Industrial Equipment
Ultrasonic Cleaning Equipment Market
Industrial Equipment
Cleanroom Equipment Market
Industrial Equipment
Precision Positioning Equipment Market
Industrial Equipment
Cartridge Heaters Market
Industrial Equipment
Camera Tripods Market
Industrial Equipment
Screw Air End Market
Industrial Equipment
Latin America Explosion-Proof Equipment Market
Industrial Equipment
Laser Marking Machine Market
Industrial Equipment
Grading and Batching Systems Market