
 Laser Marking Market | 2026-2036
Laser Marking Market Size, Share, and Industry Trends Forecast 2026-2036
Laser Marking Market Outlook
The laser marking equipment landscape is rebalancing as premium fiber laser systems pull away from commodity CO2 alternatives on precision and speed metrics. Trumpf leverages its German manufacturing base to dominate high-wattage industrial installations across automotive OEMs. Han's Laser anchors its position through vertical control over resonator production and aggressive pricing in Asian export markets. Gravotech specializes in compact engraving systems for small-batch jewelry and medical device workshops, occupying a defensible mid-market tier.
Laser marking employs focused electromagnetic radiation to alter surface properties of metals, polymers, and ceramics, typically operating at wavelengths from 1064 nm (fiber) to 355 nm (UV) with beam diameters below 50 microns for traceability codes and decorative engraving. Fiber laser technology leads industrial adoption due to superior wall-plug efficiency and minimal maintenance intervals, while UV laser systems command premium pricing in electronics applications where thermal damage must be eliminated. The electronics application segment shows the fastest structural expansion as miniaturized components require sub-millimeter Data Matrix codes, whereas CO2 laser marking in packaging remains a mature, margin-compressed category serving high-volume cardboard and label operations.
FDA's Unique Device Identification rules and EU MDR traceability mandates are forcing medical device manufacturers to upgrade marking durability and readability standards, directly lifting demand for picosecond and femtosecond laser sources. ISO 13485 quality management requirements and REACH substance restrictions further constrain material choices and validation protocols for European and North American suppliers. Stakeholders must monitor pending amendments to China's GB standards for medical device labeling, as SAMR alignment with international traceability norms would unlock substantial replacement demand across domestic manufacturing capacity.
Market Dynamics
Medical device traceability mandates are compressing upgrade cycles across installed laser marking bases, forcing capital redeployment toward picosecond and femtosecond sources that withstand sterilization cycles without degradation.
Growth Catalysts
- FDA UDI Mandate:Unique Device Identification rules require permanent, machine-readable marks on all Class II and III medical devices, directly lifting fiber laser demand for surgical instrument manufacturers.
- EU MDR Traceability:The Medical Device Regulation's enhanced labeling requirements are accelerating replacement of legacy CO2 systems with UV and green laser platforms across European contract manufacturers.
- Automotive Electrification:Battery pack serialization and motor component tracking are expanding high-speed galvo-head installations across German and Chinese EV supply chains.
Market Restraints
- Rare Earth Supply Concentration:Neodymium-doped fiber laser resonators depend on Chinese-processed rare earth oxides, creating input cost volatility and geopolitical exposure for Western system builders.
- Technical Limitation on Plastics:Carbon black loading requirements for 1064 nm fiber laser contrast limit markable polymer substrates, excluding transparent medical-grade polycarbonates without additive modification.
- REACH Substance Restrictions:European Chemicals Agency constraints on chromate-containing laser-marking additives are forcing reformulation of passivation chemistries for stainless steel surgical instruments.
Strategic Opportunities
- India Medical Device Manufacturing:PLI scheme incentives for domestic device production are creating greenfield demand for ISO 13485-compliant marking systems in Gujarat and Karnataka clusters.
- Femtosecond-Electronics Convergence:Cold ablation marking of flexible PCBs and microLED substrates is opening premium pricing tiers for sub-picosecond sources in South Korean and Taiwanese fabs.
- Cloud-Connected Maintenance:Predictive optics degradation monitoring via IoT sensors is enabling subscription-based service models that reduce customer capex barriers.
Industry Challenges
- Multi-Wavelength Process Engineering:Qualifying hybrid fiber-UV systems for diverse substrate portfolios demands specialized application engineers scarce in mid-tier system houses.
- ISO 13485 Certification Timelines:Medical device supplier validation protocols extend sales cycles 8-14 months, straining working capital for smaller equipment vendors.
- Legacy ERP Integration:Connecting modern laser controllers to 1990s-era MES architectures in automotive tier-2 shops requires costly middleware development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Laser Marking Market |
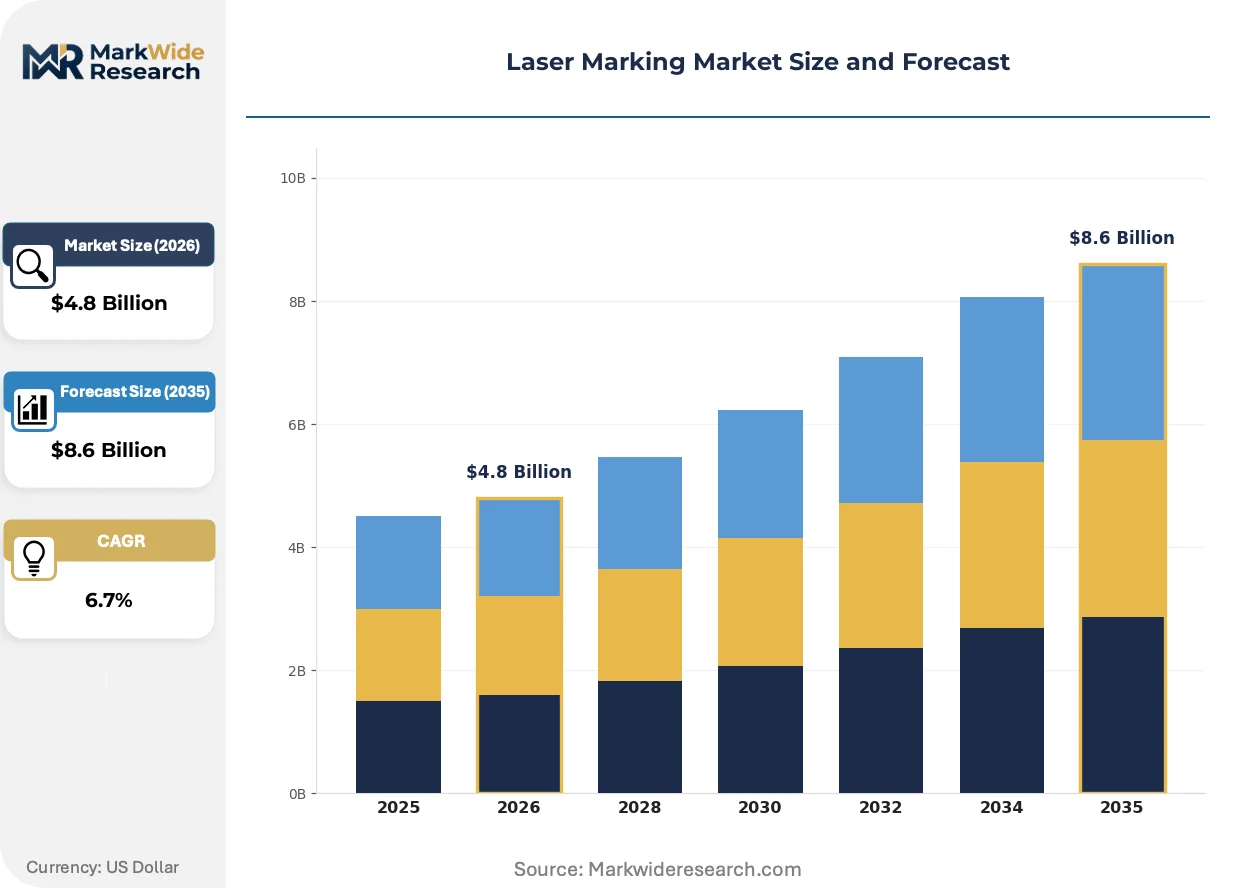
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Fiber Laser, CO2 Laser, UV Laser, Green Laser Application: Aerospace, Automotive Parts, Packaging, Electronics End User: Manufacturing, Pharmaceuticals, Food & Beverage, Consumer Goods Method: Direct Marking, Engraving, Etching, Coding |
| Companies Covered | Laserax, Videojet Technologies, Han's Laser, IPG Photonics, Telesis Technologies, Trumpf, Gravotech, Epilog Laser, Keyence, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Laser Marking Market Strategic Shifts
Ultrafast laser technology is collapsing the historical trade-off between marking speed and thermal damage thresholds, enabling new substrate classes and traceability applications previously excluded from laser processing.
Picosecond fiber lasers are unifying marking and micromachining functions in single platforms, allowing medical device contract manufacturers in Switzerland and Germany to consolidate equipment footprints. Swissmedic-registered suppliers are adopting these sources at 15-20% annual clip for orthopedic implant marking. The technology is compressing capital allocation per production line while expanding addressable substrate portfolios to include PEEK and bioabsorbable polymers.
EU MDR Article 27's EUDAMED database linkage requirements are forcing European device manufacturers to upgrade mark durability standards for reprocessing survival. EMA-coordinated notified bodies are rejecting legacy electrochemical etching for permanent implant identifiers. Cardiovascular stent and joint replacement segments are responding with femtosecond black marking protocols that maintain readability through 500+ sterilization cycles.
Japanese automotive suppliers are consolidating vendor relationships around full-line integration partners capable of delivering marked components rather than marking equipment. METI's quality infrastructure push is accelerating this behavioral shift among Toyota and Honda tier-1 suppliers. Procurement teams in Aichi and Kanagawa prefectures now specify Data Matrix quality grades in component purchase agreements, transferring process risk upstream to specialized job shops.
Laser Marking Market Segmentation
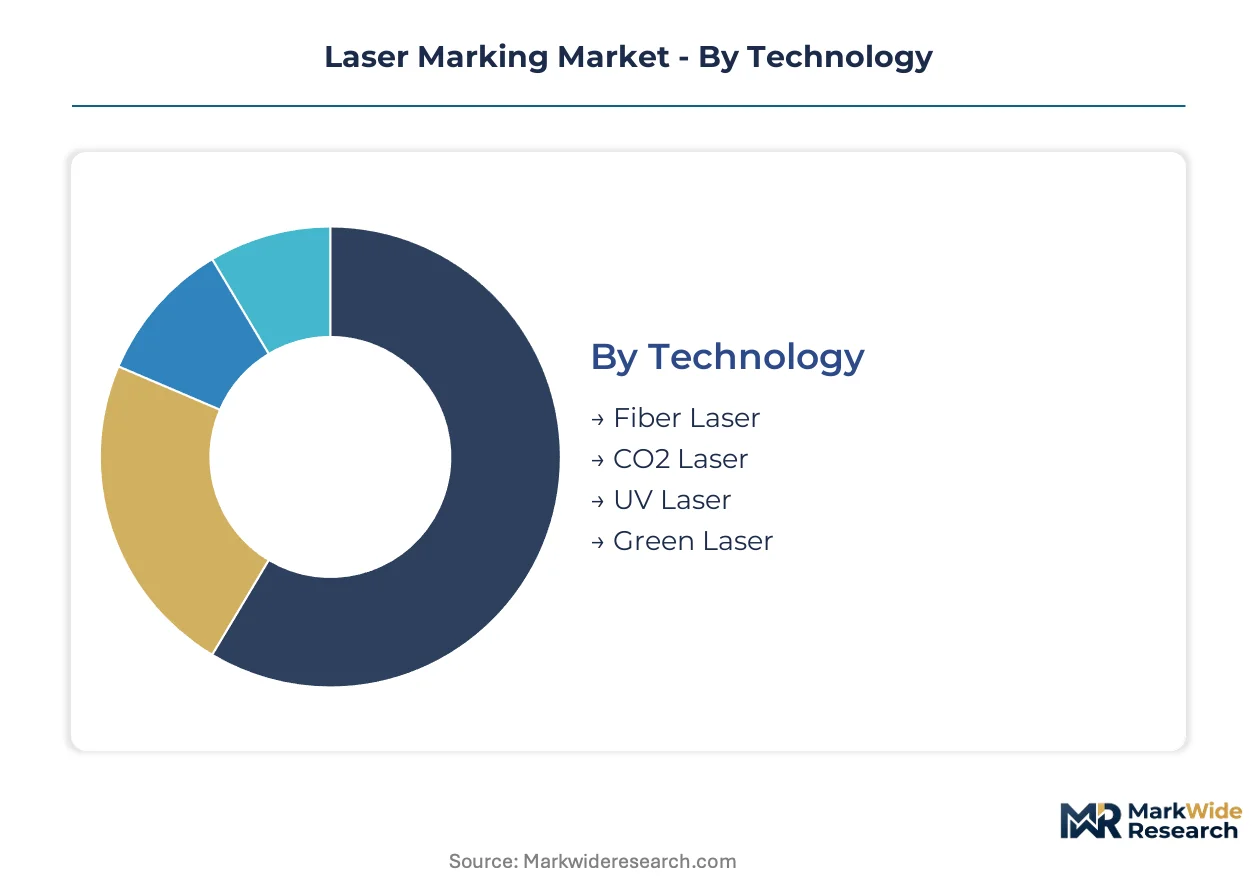
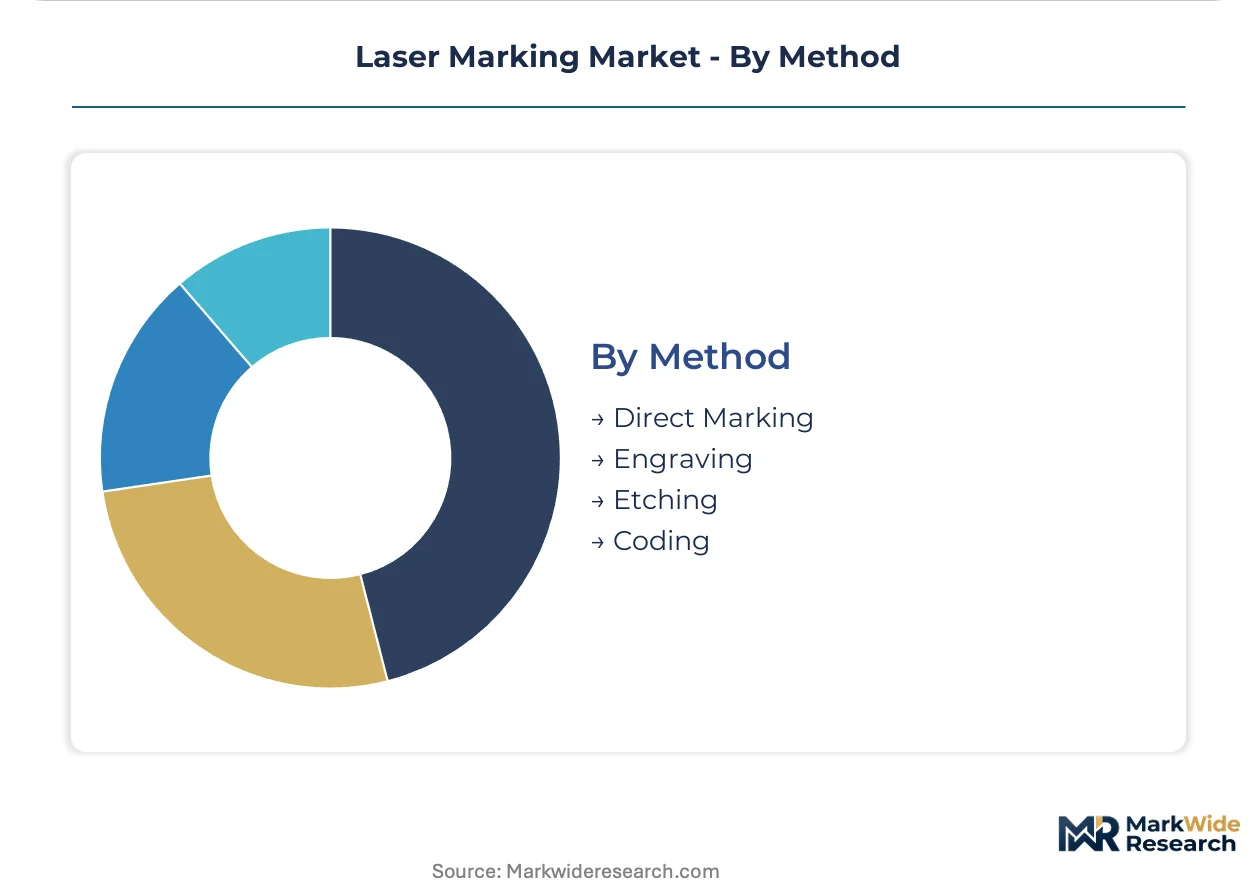
Laser marking segmentation reveals distinct technology-performance tiers that align with substrate requirements and regulatory durability standards. Application-specific traceability mandates create divergent equipment specifications across medical device, automotive, and electronics verticals.
Technology:
Specification thresholds for beam quality, wavelength precision, and thermal damage control define competitive positioning across laser sources.
- Fiber Laser:Ytterbium-doped fiber resonators deliver 1064 nm output with wall-plug efficiency exceeding 30% and maintenance intervals stretching beyond 50,000 hours. German automotive OEMs and Chinese battery manufacturers anchor demand for high-wattage galvo-head installations in EV component serialization.
- UV Laser:Frequency-tripled solid-state systems at 355 nm enable cold marking of thermally sensitive substrates through direct bond-breaking rather than thermal ablation. Electronics contract manufacturers in South Korea and Taiwan specify UV sources for flexible PCB and microLED substrate processing where heat-affected zones must stay below 10 microns.
- CO2 Laser:Gas-discharge systems at 10.6 microns dominate cardboard and polymer film packaging applications where contrast requirements are modest and capital budgets are constrained.
- Green Laser:Frequency-doubled Nd:YAG platforms at 532 nm occupy a narrow niche for high-contrast marking of reflective metals and certain medical-grade polymers with specific chromophore responses.
Fiber laser leads on scale; UV laser leads on momentum.
Application:
End-use durability requirements and mark density specifications drive equipment selection and process validation complexity.
- Electronics:Miniaturized component traceability demands sub-millimeter Data Matrix codes on silicon, ceramic, and polyimide substrates. South Korean semiconductor fabs and Taiwanese OSATs are expanding picosecond laser installations for through-silicon via marking and wafer ID engraving.
- Automotive Parts:Powertrain component serialization and battery pack traceability require deep, corrosion-resistant marks surviving 20+ year service lives. German precision engineering clusters in Baden-Württemberg and Bavaria concentrate high-speed fiber laser deployments for power electronics and motor housing marking.
- Aerospace:FAA-compliant UID marking of titanium and nickel superalloy components demands specialized parameters for heat-affected zone control and fatigue resistance validation.
- Packaging:High-volume cardboard and label operations utilize CO2 systems for date codes and batch numbers in margin-compressed, throughput-maximized environments.
Automotive parts leads on scale; electronics leads on momentum.
End User:
Regulatory compliance intensity and batch size variability shape procurement patterns across customer categories.
- Pharmaceuticals:FDA serialization mandates and EU FMD track-and-trace requirements force validated, audit-ready marking systems with 21 CFR Part 11 electronic records compliance. Contract manufacturers in Ireland and Switzerland concentrate ISO 15378-compliant installations.
- Manufacturing:Diverse OEM and tier supplier base spans high-mix, low-volume job shops to mass production lines, creating fragmented demand for benchtop through fully automated marking cells.
- Food & Beverage:Ink replacement economics and washdown durability requirements are shifting some premium packaging lines from continuous inkjet to CO2 laser coding.
- Consumer Goods:Cosmetic engraving and personalization services drive compact fiber laser demand in jewelry and accessory workshops.
Manufacturing leads on scale; pharmaceuticals leads on momentum.
Method:
Process physics and mark topology requirements determine equipment configuration and cycle time economics.
- Engraving:Material removal to 50-500 micron depths creates permanent, tactile marks for aerospace and heavy equipment components requiring mechanical durability.
- Direct Marking:Surface annealing or color change without material removal preserves dimensional tolerances on precision medical instruments and surgical implants.
- Etching:Chemical-assisted laser processes enhance contrast on challenging substrates like glass and certain ceramics.
- Coding:High-speed alphanumeric and 2D code application on moving production lines prioritizes throughput over mark depth.
Direct marking leads on scale; engraving leads on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's precision engineering corridor commands premium fiber laser installations, while China's battery manufacturing expansion drives volume procurement of high-wattage galvo-head systems.
United States
FDA UDI enforcement and aerospace UID mandates sustain demand for picosecond sources in surgical instrument and titanium component marking. The FAA maintains strict heat-affected zone protocols for fatigue-critical aerospace alloys. Boston's medical device cluster and Seattle's aerospace corridor concentrate validation-intensive installations for implant and airframe applications.
Germany
EU MDR traceability deadlines and automotive electrification converge in Baden-Württemberg's precision engineering belt. The KBA enforces component serialization standards for EV battery traceability. Stuttgart and Munich anchor high-specification fiber laser deployments across BMW, Mercedes-Benz, and tier-1 supplier networks.
China
Domestic EV battery serialization and SAMR alignment with international medical device traceability norms drive dual demand streams. GB standards evolution for medical device labeling would unlock substantial replacement demand. Shenzhen and Ningbo concentrate galvo-head manufacturing and automotive marking system integration.
Japan
METI's quality infrastructure push consolidates vendor relationships around full-line integration partners. Toyota and Honda tier-1 suppliers in Aichi and Kanagawa prefectures now specify Data Matrix quality grades in component purchase agreements. Nagoya's automotive cluster transfers process risk upstream to specialized job shops.
India
PLI scheme incentives for domestic medical device production create greenfield demand for ISO 13485-compliant marking systems. CDSCO alignment with FDA traceability norms accelerates validation protocol adoption. Gujarat and Karnataka clusters concentrate contract manufacturer investment in surgical instrument and orthopedic implant marking capacity.
Laser Marking Market Competitive Environment
Top-tier vendors anchor high-wattage industrial installations, while mid-tier specialists occupy defensible niches in compact engraving and medical device workshops. The competitive landscape stratifies across German precision engineering houses, Chinese vertical integrators, and Japanese automation conglomerates. Three archetypes dominate: wavelength-specialized technology licensors, application-engineered system integrators, and resonator-production-integrated volume manufacturers. M&A activity concentrates on UV and ultrafast source capabilities, while geographic expansion targets Indian and Southeast Asian medical device manufacturing clusters.
Within the wavelength-specialized tier, IPG Photonics and Trumpf exemplify divergent approaches to resonator technology and system architecture. Han's Laser occupies a position among vertically integrated volume manufacturers with captive fiber production. These three anchors demonstrate how competitive positioning separates technology licensors from integrated system houses across the premium-to-standard equipment spectrum.
| Leading Market Players |
|---|
| Laserax |
| Videojet Technologies |
| Han's Laser |
| IPG Photonics |
| Telesis Technologies |
| Trumpf |
| Gravotech |
| Epilog Laser |
| Keyence |
| Others |
Value Chain & Pricing Dynamics
EU REACH substance restrictions on chromate-containing laser-marking additives gate qualified supply access and premium-tier pricing power for European medical device marking systems. Manufacturers without validated passivation chemistries face exclusion from high-margin surgical instrument contracts regardless of equipment performance.
Pricing Analysis
Capacity additions in China are reshaping price floors for standard-wattage fiber laser systems. Three-tier pricing structure across premium, standard, and economy levels separates ISO 13485-validated medical platforms from industrial commodity units and entry-level benchtop systems. Price differentiation hinges on certification grade and after-sales service bundling. Cost compression in the economy tier is intensifying because resonator oversupply from domestic Chinese producers floods export markets. Contract manufacturers in India and Southeast Asia exhibit highest price sensitivity; German automotive OEMs demonstrate lowest.
Supply Chain Analysis
Single-source vulnerability sits with Chinese-processed rare earth oxides for neodymium-doped fiber laser resonators. Manufacturing concentrates in China, Germany, and Japan. Raw material dependencies span ytterbium-doped fiber, precision galvo-head assemblies, and rare earth oxides. Tariff exposure on Chinese-sourced resonators threatens Western system builders' input cost stability. Distribution runs through direct OEM sales for high-wattage industrial installations and specialized distributors for compact engraving systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Laser marking functions as a stable compounder anchored by irreversible regulatory traceability mandates across medical device and automotive verticals. FDA UDI enforcement and EU MDR deadlines ensure replacement demand regardless of macroeconomic cycles.
For Market Incumbents: Extend femtosecond source capabilities through targeted R&D partnerships with Swiss and German precision engineering houses. Chinese vertical integrators threaten margin compression in standard fiber laser tiers; defend through ISO 13485 certification depth and predictive maintenance service bundling that locks in medical device customers through validation protocol entanglement.
For New Entrants and Emerging Players: The price-point gap between premium Swiss-German medical platforms and economy Chinese exports creates entry space for mid-tier specialists. Target India's PLI-subsidized medical device clusters in Gujarat and Karnataka with ISO 13485-compliant systems priced below European incumbents. Lead with application engineering support and rapid validation timeline guarantees as the go-to-market angle.
For Investors and Strategic Acquirers: Valuations sit cheapest among wavelength-specialized technology licensors lacking downstream system integration. Long-term viability favors acquisition targets with captive ultrafast source IP and established medical device validation track records. Watch SAMR alignment with international UDI norms as the inflection signal unlocking Chinese domestic replacement demand.
| Strategic Initiative | Industry Significance |
|---|---|
| Femtosecond Source Capability Expansion | Enables cold ablation marking of PEEK and bioabsorbable polymers for orthopedic implants. |
| ISO 13485 Certification Investment | Unlocks surgical instrument and implant marking contracts with FDA and EU MDR compliance. |
| Predictive Maintenance Service Launch | Reduces customer capex barriers through IoT-enabled subscription optics degradation monitoring. |
| India Manufacturing Footprint Establishment | Captures PLI scheme incentives for domestic medical device production in Gujarat clusters. |
| UV Laser Platform Integration | Addresses flexible PCB and microLED substrate marking demand from South Korean fabs. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window. Primary engagement with laser system procurement managers at German automotive OEMs, biomedical engineers at Swiss medical device manufacturers, maintenance directors at Chinese battery plants, and aftermarket service heads at Japanese automation conglomerates informed demand-side validation. Secondary sources included SEC filings of listed laser equipment vendors, SAMR GB standards evolution tracking, FDA UDI guidance documents, and EU MDR implementation notices. Bottom-up equipment shipment tracking and top-down end-use industry spend analysis were triangulated for cross-verification.
Segment-weighting across technology, application, end user, and method dimensions structured the analytical framework. Fiber laser, UV laser, CO2 laser, and green laser platforms were modeled separately with distinct replacement cycle assumptions. Electronics, automotive parts, aerospace, and packaging applications carried divergent durability specifications. CAGRs were derived from installed base depreciation schedules and regulatory mandate compliance deadlines. Rare earth oxide price volatility and SAMR regulatory alignment timelines served as scenario inputs.
Caveats apply where rare earth supply disruptions or accelerated EU MDR enforcement could materially shift the outlook. Forecasts reflect assumptions about certification timeline standardization and Chinese export pricing discipline. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Equipment
Diaphragm Coupling Market
Industrial Equipment
Industrial Magnetrons Market
Industrial Equipment
Commercial Refrigeration System Market
Industrial Equipment
Press-Insertion Systems Market
Industrial Equipment
Asia-Pacific Industrial Centrifuge Market
Industrial Equipment
Glass Washer Market
Industrial Equipment
Cable Granulator Market
Industrial Equipment
Dust Collector Systems Market
Industrial Equipment
Digital Tube Roller Market
Industrial Equipment
Laser Marking Equipment Market
Industrial Equipment
Global Abrasive Waterjet Cutting Machine Market
Industrial Equipment
Global Industrial Dispensing System and Equipment Market
Industrial Equipment
Hot Runner Temperature Controller Market
Industrial Equipment
Vibration Isolation Tables Market
Industrial Equipment
High-Speed Electric Spindle Market
Industrial Equipment
Global Industrial Weighing Machines Market