
 Global Pneumatic Actuators Market | 2026-2036
Global Pneumatic Actuators Market Size, Share, and Industry Trends Forecast 2026-2036
Global Pneumatic Actuators Market Intelligence
The integration of smart, IIoT-enabled sensors directly within actuator casings is rewriting the operational and maintenance paradigms for industrial automation. Emerson Electric Co. leverages its digital ecosystem to offer predictive maintenance analytics with its valve automation products. Festo SE & Co. KG differentiates through its focus on modular and energy-efficient compact pneumatic solutions for electronics fabrication. SMC Corporation sustains a dominant market position through its extensive product portfolio and global distribution network.
A pneumatic actuator is a device that converts energy from compressed air into mechanical motion, typically linear or rotary. These devices operate at specific pressure ranges, such as 4 to 8 bar, to generate controlled force for industrial tasks. Double-acting actuators represent a mature, high-volume product category due to their precise control in both directions of movement. The valves automation application segment is expanding, driven by process-intensive end users like chemical plants and oil refineries seeking greater process control.
ISO standards, such as ISO 15552 for cylinder dimensions, ensure interoperability and facilitate global component sourcing. In parallel, compliance with the EU's Machinery Directive and OSHA's safety regulations in the United States governs machine safety and workplace hazard prevention. Future competitive advantage will depend on a vendor's ability to embed intelligence and energy efficiency features without compromising the core value proposition of simplicity and reliability.
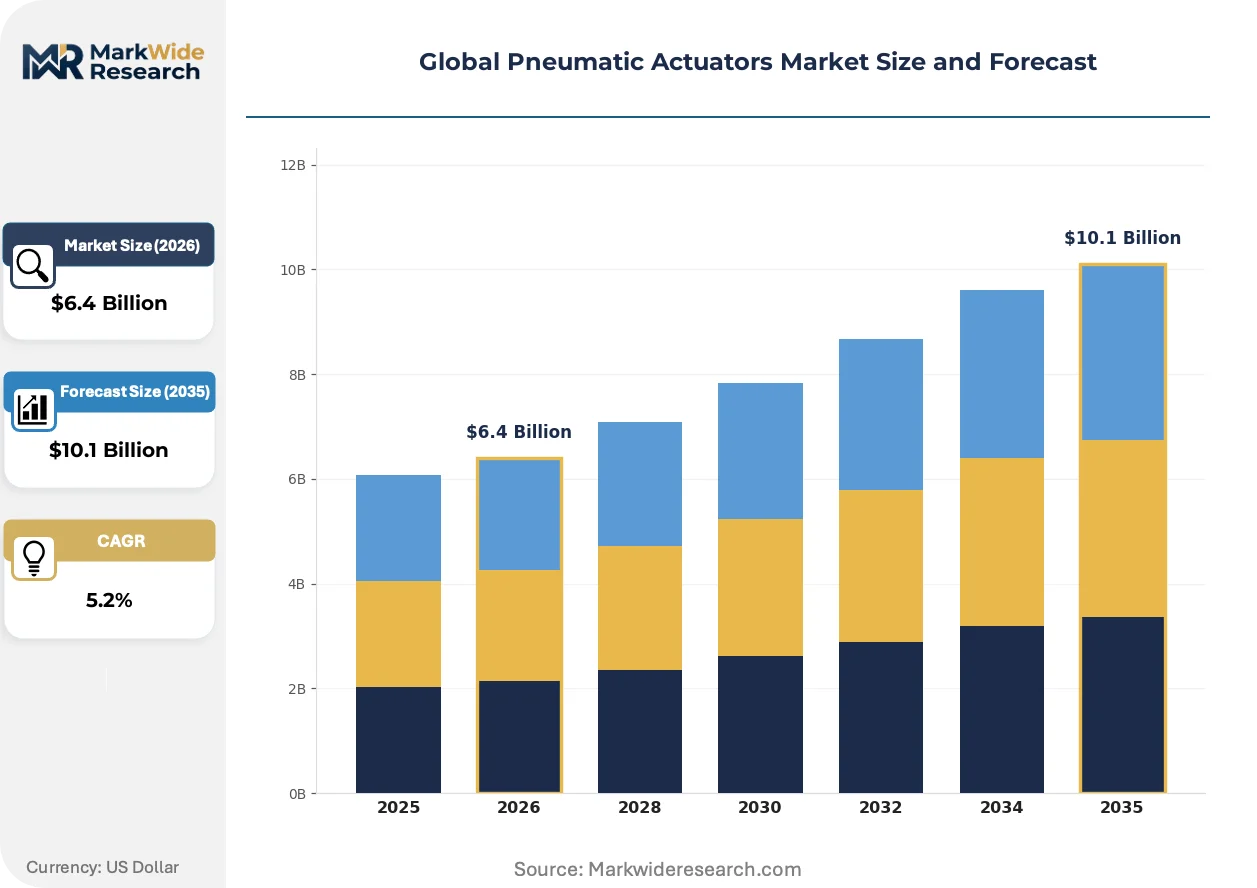
Market Dynamics
The fundamental dynamic shaping the pneumatic actuators market is the dual pressure for increased automation intelligence and heightened energy efficiency. This is driven by the manufacturing sector's pivot towards smart factories and sustainable production, particularly within automotive and electronics assembly lines.
Growth Catalysts
- IIoT Integration:The embedding of sensors for real-time diagnostics and predictive maintenance analytics creates significant value for end-users in process-intensive industries, reducing unplanned downtime and optimizing asset performance.
- Automotive Electrification:The global build-out of electric vehicle (EV) and battery manufacturing plants, especially in industrial clusters in China and Germany, requires vast quantities of pneumatic actuators for new automated assembly and material handling lines.
- Standardization Benefits:Adherence to ISO standards like ISO 15552 for cylinder dimensions ensures component interchangeability, simplifying global supply chains for OEMs and enabling a more competitive and resilient sourcing environment.
Market Restraints
- Competition from Electric Actuators:Electric actuation systems offer superior precision, control, and programmability, posing a significant substitution threat in applications like medical robotics and semiconductor manufacturing that demand exacting position control.
- Energy Cost Volatility:Pneumatic systems are inherently dependent on compressed air, which is an energy-intensive utility. Fluctuations in industrial electricity prices directly impact the total cost of ownership, making it a less attractive option in high-cost energy markets.
- Force and Power Limitations:Compared to hydraulic systems, pneumatic actuators offer lower force density, restricting their use in heavy-duty industrial applications such as large-scale metal forming, presses, and construction equipment.
Strategic Opportunities
- Miniaturization for Life Sciences:Developing compact and micro-pneumatic actuators opens significant opportunities in high-value applications like lab automation, diagnostic equipment, and medical device manufacturing where clean, precise, and small-scale motion is required.
- Food and Beverage Sector Expansion:The growing need for hygienic, washdown-rated automation components in food processing and packaging presents an opportunity for actuators made with corrosion-resistant materials and designed to meet stringent food safety regulations.
- Energy Recovery Systems:Innovating actuators and control systems that can capture and reuse energy from exhaust air addresses a key operational cost concern, creating a compelling value proposition centered on sustainability and reduced total cost of ownership.
Industry Challenges
- Skilled Workforce Deficit:Integrating smart actuators with IIoT platforms and factory-level software requires a workforce skilled in both mechanical engineering and data science, a talent combination that is currently scarce.
- Legacy System Integration:A significant challenge for end-users is the complexity and cost of integrating modern, digitally-enabled pneumatic components with older, existing plant infrastructure and legacy programmable logic controllers (PLCs) without causing major disruptions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Pneumatic Actuators Market |
| Market Size in 2026 | $6.4 Billion |
| Market Size in 2035 | $10.1 Billion |
| CAGR (2026 – 2036) | 5.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Double Acting, Single Acting, Spring Return, Diaphragm, Rotary, Rack & Pinion Technology: Electro-Pneumatic, Compact Pneumatic, Rotary Vane, Piston Type, Scotch Yoke, Rodless Cylinder Application: Valves Automation, Packaging Equipment, Material Handling, Robotics, Food Processing, Textile Machinery End User: Automotive Manufacturers, Chemical Plants, Oil Refineries, Electronics Fabricators, Marine Engineering, Power Generation |
| Companies Covered | Emerson Electric Co., Parker Hannifin Corporation, Festo SE & Co. KG, SMC Corporation, ABB Ltd., Rotork plc, Bosch Rexroth AG, Honeywell International Inc., Flowserve Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Pneumatic Actuators Market Strategic Shifts & Innovations
Intelligence and efficiency are being systematically engineered into the core of pneumatic technology. This transforms actuators from simple mechanical components into connected devices that contribute directly to process optimization and sustainability goals within modern industrial environments.
Digital valve positioners integrating microprocessors and advanced control algorithms provide unparalleled command over actuator movement. Process industries, particularly chemical manufacturing and refining, are rapidly adopting these systems for critical flow control applications. This technology is rendering obsolete purely mechanical positioners and the time-consuming manual calibration they require, directly improving process stability and output quality.
European Union energy efficiency mandates, such as the Ecodesign for Sustainable Products Regulation (ESPR), are compelling component-level improvements. The regulation pressures manufacturers to minimize the energy consumption of their products, including the compressed air used by pneumatic systems. This shift most affects producers of high-volume, standard actuators, who must now innovate with low-friction seals and lightweight materials to maintain competitiveness.
OEM purchasing behavior is evolving from sourcing individual components to procuring complete, pre-engineered pneumatic subsystems. This preference for modular, plug-and-play solutions that include actuators, valves, sensors, and tubing disrupts the traditional distributor-led sales channel. The trend is most pronounced in the fast-moving electronics and packaging machinery sectors in Asia, where it accelerates machine design and assembly timelines.
Global Pneumatic Actuators Market Segmentation
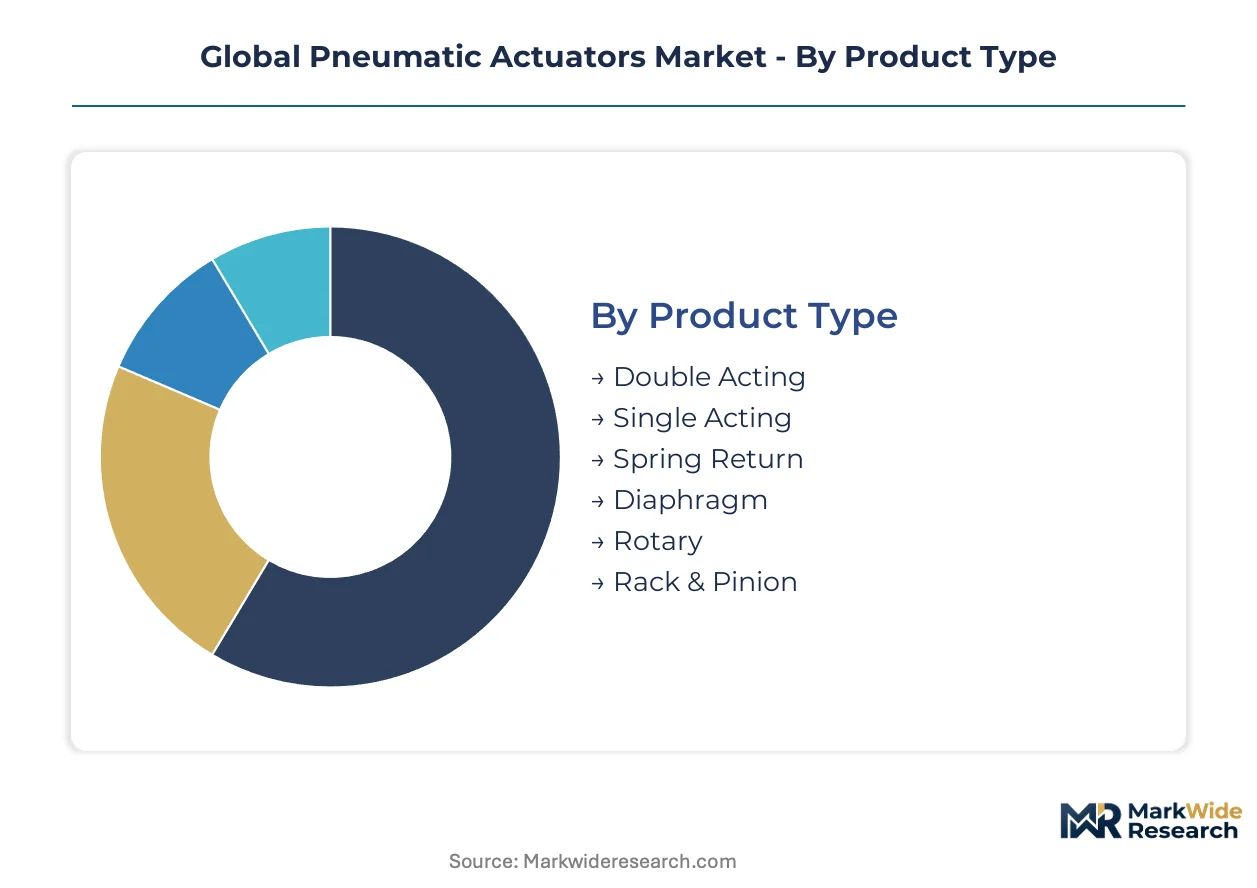
The segmentation of the global pneumatic actuators market illuminates the diverse needs and technological advancements driving adoption across various industrial sectors. Understanding these distinct segments helps manufacturers tailor solutions for specific performance requirements and operational environments. This granular analysis provides clarity on where demand concentrates and how innovation is shaping product development for pneumatic systems.
Product Type:
The product type spectrum for pneumatic actuators addresses diverse mechanical motion requirements across industrial operations.
- Double Acting:These actuators utilize compressed air to drive movement in both directions, offering precise control for pushing and pulling tasks. Demand is robust in industrial automation and automotive manufacturing for high-volume production lines.
- Rotary:These devices convert pneumatic energy into rotational motion, commonly employed for valve control and indexing applications. Process industries, particularly chemical plants, rely on rotary actuators for precise flow regulation.
- Single Acting:Single acting actuators use compressed air for movement in one direction and a spring for return, simplifying control.
- Spring Return:These actuators feature an internal spring for fail-safe operation, crucial in safety-critical applications like emergency shutdowns.
- Diaphragm:Diaphragm actuators operate at lower pressures, offering high sensitivity and suitability for clean environments such as pharmaceuticals.
- Rack & Pinion:This type converts linear piston movement into rotary motion, providing robust and reliable valve actuation.
The dominant share belongs to Double Acting actuators, while Rotary actuators are expanding their application scope fastest.
Technology:
Technological advancements differentiate pneumatic actuator designs, offering enhanced control and efficiency features.
- Electro-Pneumatic:These actuators integrate electronic control with pneumatic power, enabling precise positioning and digital communication capabilities. Process control applications and advanced robotics increasingly utilize electro-pneumatic systems for seamless integration with digital platforms.
- Compact Pneumatic:Characterized by their miniaturized design and energy-efficient operation, compact pneumatic solutions are critical for space-constrained applications. Electronics fabrication and medical device manufacturing benefit from these small-footprint, high-precision components.
- Rotary Vane:Rotary vane actuators provide simple and cost-effective rotary motion for light to medium torque requirements.
- Piston Type:Piston type actuators generate powerful linear force, making them suitable for robust industrial applications requiring significant pushing or pulling.
- Scotch Yoke:Scotch yoke mechanisms deliver high torque output, specifically designed for heavy-duty valve actuation in demanding environments.
- Rodless Cylinder:Rodless cylinders offer long strokes within a reduced overall footprint, optimizing space utilization in automated machinery.
Industry preference is shifting towards Electro-Pneumatic and Compact Pneumatic solutions for their advanced capabilities.
Application:
Pneumatic actuators significantly enhance operational efficiency across a wide array of industrial applications.
- Valves Automation:This application involves using actuators to control the opening and closing of industrial valves, crucial for fluid and gas flow regulation. Chemical plants and oil refineries depend on valve automation for precise process control and safety protocols.
- Material Handling:Pneumatic actuators are extensively used in systems for lifting, pushing, gripping, and positioning materials within factories and warehouses. Automotive assembly lines and logistics operations leverage these actuators for high-speed, repetitive tasks.
- Packaging Equipment:Actuators provide rapid cycling and precise positioning for tasks like sealing, filling, and sorting within packaging lines.
- Robotics:Pneumatic actuators are commonly integrated into robotic end-effectors for gripping, clamping, and pick-and-place operations.
- Food Processing:This sector utilizes hygienic, washdown-rated pneumatic components for tasks in food preparation and packaging environments.
- Textile Machinery:Pneumatic systems facilitate fabric manipulation, tension control, and high-speed weaving processes in textile manufacturing.
Valves Automation and Material Handling remain foundational applications, demonstrating the broad utility of pneumatic systems.
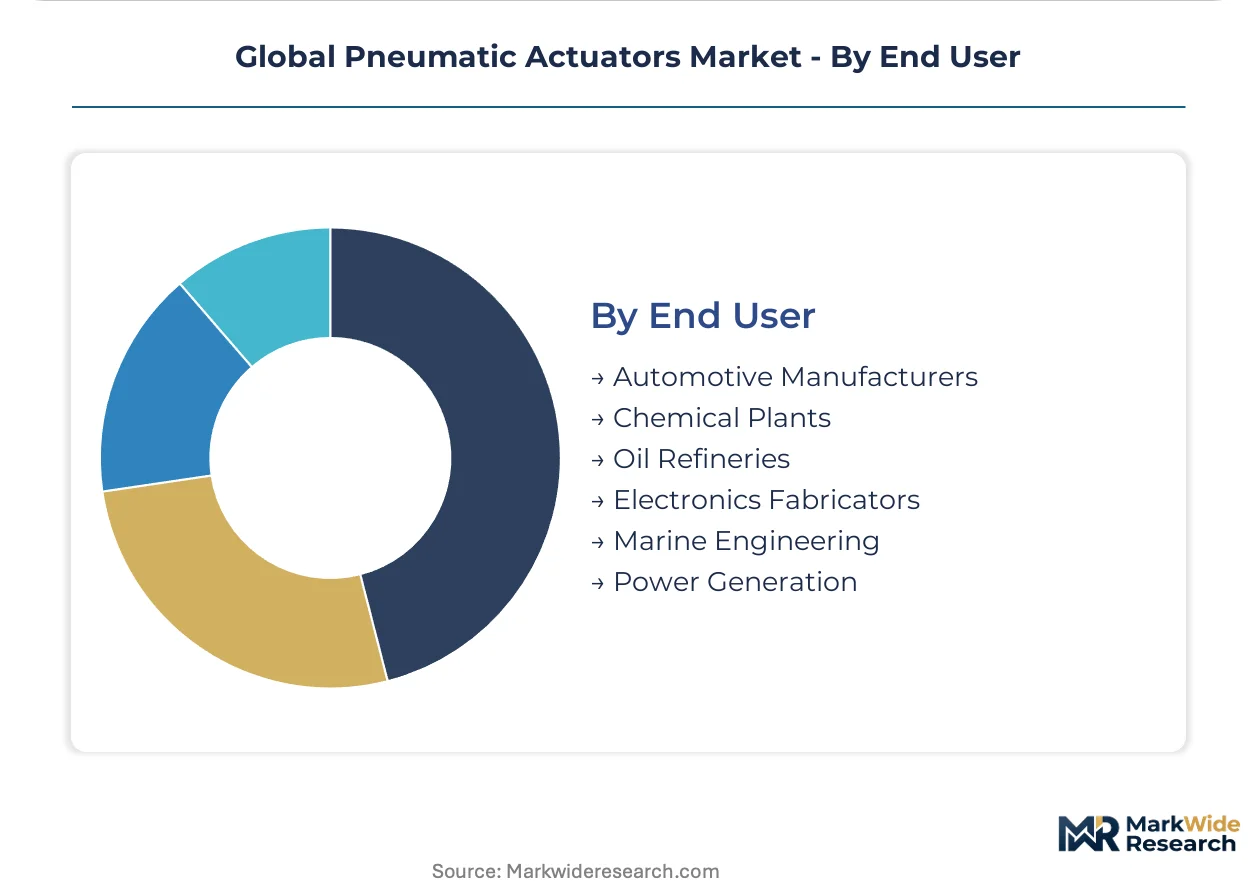
End User:
Diverse end-user industries adopt pneumatic actuators based on their specific operational and environmental requirements.
- Automotive Manufacturers:This sector uses pneumatic actuators extensively across assembly lines for welding, painting, and material transfer operations. The global build-out of electric vehicle production and battery manufacturing plants drives significant demand for automated pneumatic systems.
- Electronics Fabricators:These manufacturers rely on pneumatic actuators for precise pick-and-place operations and in cleanroom environments for semiconductor manufacturing and PCB assembly. The need for contamination control and high precision is paramount in these facilities.
- Chemical Plants:Chemical plants utilize pneumatic actuators for controlling valves and dampers in hazardous and corrosive processing environments.
- Oil Refineries:Refineries deploy pneumatic systems for critical process control, including valve actuation in harsh and high-temperature conditions.
- Marine Engineering:This sector integrates robust pneumatic actuators into shipboard systems for engine controls, cargo handling, and other demanding applications.
- Power Generation:Power generation facilities use pneumatic actuators for damper control, turbine systems, and various auxiliary equipment.
Automotive Manufacturers and Electronics Fabricators serve as significant growth engines for pneumatic actuator demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The robust trade flow of advanced manufacturing equipment from Germany to global markets significantly influences pneumatic actuator demand. This demand is further amplified by the industrial build-out of automated production lines across key economic blocs, especially for electric vehicle manufacturing. Specific countries are driving innovation and adoption based on their industrial strengths and regulatory frameworks.
China
China's rapid expansion in electric vehicle and battery manufacturing drives substantial demand for pneumatic actuators in automated assembly lines. The nation's dual carbon goals policy encourages manufacturers to adopt energy-efficient automation solutions. Industrial clusters within the Yangtze River Delta and Pearl River Delta are central to this growth.
Germany
Germany's advanced manufacturing sector, particularly its automotive industry, requires high volumes of pneumatic actuators for precision assembly. The EU's Ecodesign for Sustainable Products Regulation (ESPR) pressures German manufacturers to develop highly energy-efficient pneumatic components. Bavaria and North Rhine-Westphalia serve as key hubs for industrial automation research.
United States
The United States experiences strong demand from its automotive and electronics manufacturing sectors, alongside process industries like chemical plants. OSHA's safety regulations influence the design and implementation of pneumatic systems, particularly concerning fail-safe mechanisms. Michigan's automotive corridor and California's technology manufacturing centers are significant consumers.
Japan
Japan's electronics fabrication and precision machinery industries rely heavily on pneumatic actuators for delicate and high-speed pick-and-place operations. The Ministry of Economy, Trade and Industry (METI) promotes industrial automation and smart factory initiatives that integrate advanced pneumatic solutions. The Kanto region, including Tokyo, remains a primary hub for technological development.
South Korea
South Korea's dominant semiconductor and automotive manufacturing industries are significant end-users for pneumatic actuators, especially for cleanroom and high-precision applications. Government initiatives supporting smart factories and advanced robotics contribute to the integration of modern pneumatic systems. The Seoul Capital Area and the Busan-Ulsan industrial region house major facilities.
Global Pneumatic Actuators Market Key Industry Players
On the supply side, the industry is moderately concentrated, featuring a mix of large global players and specialized regional vendors. Strategic archetypes include technology innovators focusing on advanced features, broad-portfolio providers catering to diverse industrial needs, and application-specific specialists. Dominant competitive moves involve strategic partnerships for IIoT integration, continuous product development in energy efficiency, and geographic expansion into high-growth manufacturing hubs.
Technology innovators in pneumatic actuation, such as Festo SE & Co. KG, exemplify the focus on modular and energy-efficient compact solutions, particularly for specialized applications like electronics fabrication. SMC Corporation represents a broad-portfolio provider, sustaining a dominant market position through its extensive product range and robust global distribution network. Emerson Electric Co. anchors the segment focused on advanced digital ecosystems, offering predictive maintenance analytics seamlessly integrated with its valve automation products.
| Leading Market Players |
|---|
| Emerson Electric Co. |
| Parker Hannifin Corporation |
| Festo SE & Co. KG |
| SMC Corporation |
| ABB Ltd. |
| Rotork plc |
| Bosch Rexroth AG |
| Honeywell International Inc. |
| Flowserve Corporation |
Cost & Logistics Intelligence
Commodity volatility in raw materials like aluminum and specialized polymers for seals determines both pricing tier spreads and supply chain shape for pneumatic actuators. This directly impacts manufacturing costs and subsequently the final product pricing across different performance grades.
Pricing Analysis
Technology-generation pricing gaps persist, with advanced electro-pneumatic solutions commanding premium pricing over mature double-acting actuators. The dominant pricing model remains per-unit transactional, though long-term contracts with OEMs are common. Price differentiation stems from precision control capabilities and specific industry certifications like those for cleanroom environments. Pricing pressure stems from the ongoing competition from electric actuators in high-precision applications. Electronics fabricators exhibit the highest price sensitivity for standard components, while process industries prioritize performance and reliability over initial cost.
Supply Chain Analysis
Geopolitical tensions affecting key manufacturing regions such as China and Germany dominate the supply chain for pneumatic actuators. Geographic supply concentration primarily centers in industrial clusters within China, Germany, and Japan. Raw material dependencies include specialized aluminum alloys for cylinders, high-performance polymers for seals, and electronic components for smart sensors. Logistics chokepoints, particularly for intercontinental shipping, represent a significant structural risk. Distribution runs through a hybrid model, combining direct sales to large OEMs with an extensive network of regional distributors for smaller clients and aftermarket support.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The global pneumatic actuators market is an early-cycle expansion story, driven by the accelerating build-out of automated production lines for electric vehicles and battery manufacturing.
For Market Incumbents: Entrench core market share by deepening vertical integration into critical component manufacturing, particularly for advanced seals and integrated IIoT sensors. Invest heavily in R&D for next-generation energy-efficient designs to counter the growing threat from electric actuator substitutes. Expand manufacturing capacity strategically within high-growth regions like Southeast Asia to serve emerging electronics and automotive hubs, enhancing supply chain resilience.
For New Entrants and Emerging Players: Underpenetration in the life sciences sector presents significant white-space opportunities for compact and micro-pneumatic actuators. Target the burgeoning lab automation and medical device manufacturing segments, focusing on solutions that offer precise, clean, and miniature motion control. A compelling go-to-market angle involves offering modular, pre-engineered subsystems that simplify integration for specialized OEM customers, reducing their design cycles.
For Investors and Strategic Acquirers: The EU's Ecodesign for Sustainable Products Regulation (ESPR) reshapes the acquisition landscape, favoring companies with proven energy-efficient technologies. Long-term viability over the next decade hinges on integrating intelligence and sustainability into core product offerings. Acquisition targets should include specialized technology innovators in IIoT integration or compact pneumatic solutions. A key signal to watch is the accelerating adoption of energy recovery systems.
| Strategic Initiative | Industry Significance |
|---|---|
| Invest in IIoT Sensor Integration | This enhances predictive maintenance capabilities, reducing unplanned downtime for end-users in process-intensive industries. |
| Develop Energy Recovery Systems | This addresses high operational costs associated with compressed air, improving sustainability and total cost of ownership. |
| Expand Compact Actuator Portfolio | This captures growing demand from electronics fabrication and life sciences for precise, space-efficient motion control. |
| Form Strategic OEM Partnerships | This secures long-term supply agreements and integrates pneumatic solutions early into next-generation automated machinery designs. |
| Strengthen Global Distribution Network | This ensures broad market reach and efficient delivery of products to diverse industrial clusters, particularly in Asia. |
Research Approach
Two parallel data streams informed the analysis: extensive primary interviews with industry stakeholders and rigorous secondary validation. Primary research involved discussions with plant engineers, OEM procurement teams, automation integrators, and maintenance directors across key industrial sectors. Secondary data sources included customs and trade data, industry association reports, financial filings of public companies, and technical journals. Bottom-up and top-down triangulation ensured data consistency and accuracy.
Forecast inputs considered historical market performance, current industry trends, and future technological advancements across the analysis window. The analytical framework modeled segmentation dimensions including product type, technology, application, end-user industry, and regional production clusters. Compound Annual Growth Rates derived from historical growth trends and projected market shifts incorporate EV production forecasts and IIoT sensor integration.
The forecast holds incumbent behavior within observed patterns; aggressive moves by electric actuator manufacturers or unforeseen regulatory shifts would shift outcomes. Forecasts reflect assumptions regarding economic stability, technological development, and market dynamics. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Equipment
Global DC Drives Market
Industrial Equipment
Global Integrated Drive Systems Market
Industrial Equipment
Precision Dispensing Accessories Market
Industrial Equipment
UV Conveyor Systems Market
Industrial Equipment
Ultrasonic Cleaning Equipment Market
Industrial Equipment
Digital Load Indicator Market
Industrial Equipment
Camera Tripods Market
Industrial Equipment
Semiconductor Cartridge Heaters Market
Industrial Equipment
Magnetic Chip Conveyors Market
Industrial Equipment
Europe Fans and Blowers Market
Industrial Equipment
Electro-Pneumatic Systems Market
Industrial Equipment
Global Industrial Enclosures Market
Industrial Equipment
Vacuum Concentrators Market
Industrial Equipment
Floor Scales Market
Industrial Equipment
Linear Transfer System Market
Industrial Equipment
North America Industrial Centrifuge Market