
 Linear Shaft Motor Market | 2026-2036
Linear Shaft Motor Market Size, Share, and Industry Trends Forecast 2026-2036
Linear Shaft Motor Market Insights
Japanese and German precision motor suppliers is restructuring capacity allocation toward direct-drive architectures. NTI AG LinMot leverages its Swiss engineering heritage to dominate medical equipment applications. Aerotech Inc. sustains R&D intensity in nanopositioning subsystems for semiconductor lithography. Kollmorgen Corporation anchors North American demand through captive supply of frameless torque motors paired with linear shaft designs.
A linear shaft motor is a cylindrical direct-drive electromagnetic actuator comprising a tubular magnetic shaft and a forcer winding assembly that generates thrust without mechanical transmission elements, achieving positioning accuracy below one micron. It eliminates backlash and wear by operating through non-contact magnetic force, serving precision automation in semiconductor wafer handling and robotic surgery platforms. Brushless motor types command the largest installed base due to thermal efficiency and maintenance intervals exceeding twenty thousand hours, while magnetic levitation variants represent the fastest-growing technology segment as vacuum-compatible and frictionless operation commands premium pricing in cleanroom environments. Medical equipment applications concentrate margin pools where FDA-validated motion control justifies extended qualification cycles and higher unit economics.
The EU Machinery Directive and CE marking requirements enforce functional safety standards for electromagnetic actuators deployed in collaborative robotics, compelling redesigns of servo control architectures. China's SAMR and GB standards mandate electromagnetic compatibility testing for industrial automation components entering domestic manufacturing supply chains, creating certification barriers for non-compliant imports. Japan's METI promotes precision mechatronics through JIS standards that align with ISO safety frameworks, reinforcing technical convergence across export markets. Stakeholders must monitor how regional certification divergence affects platform standardization decisions and supplier qualification costs.
Market Dynamics
Direct-drive electromagnetic architectures are displacing ball-screw and belt-drive mechanisms in precision automation, as semiconductor lithography and robotic surgery platforms demand sub-micron positioning without mechanical wear or backlash.
Growth Catalysts
- Semiconductor capital intensity:Wafer-handling equipment in Taiwan and South Korea requires vacuum-compatible linear motion systems that eliminate particle generation from mechanical contact.
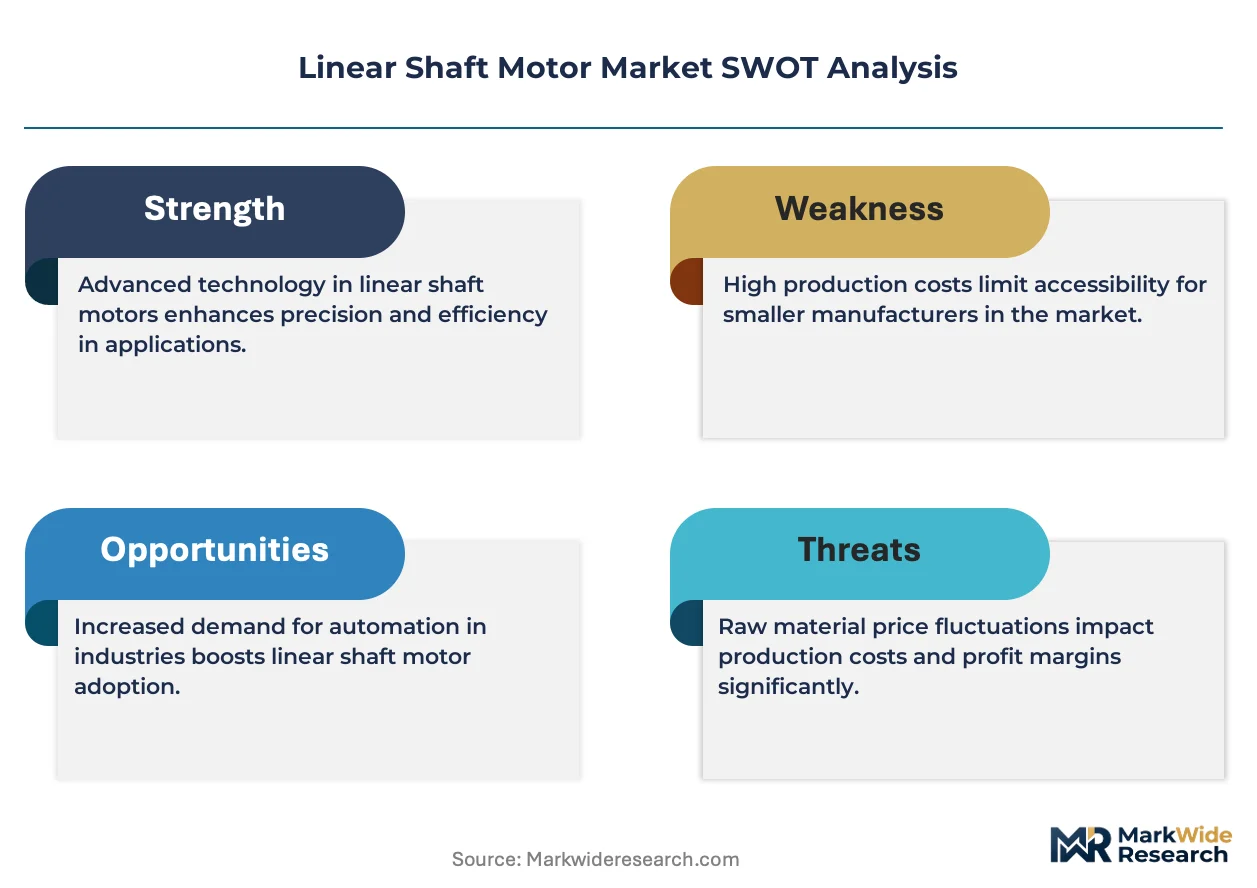
- EU Machinery Directive:Functional safety mandates for collaborative robotics compel redesigns of servo architectures toward inherently safer direct-drive topologies.
- Magnetic levitation variants:Frictionless operation commands premium positioning in cleanroom environments where maintenance access is restricted.
Market Restraints
- Rare-earth magnet supply:Neodymium price volatility and China's export licensing for magnetic materials create input cost uncertainty for shaft motor manufacturers.
- Technical thermal limits:Continuous thrust density remains constrained by coil insulation class and forced cooling requirements in compact form factors.
- Substitution by voice coils:Short-stroke precision applications below 100mm travel increasingly adopt voice coil actuators for simpler integration.
Strategic Opportunities
- Robotic surgery expansion:FDA-validated motion control for minimally invasive procedures extends qualification cycles but locks in multi-year supply agreements.
- China GB standards compliance:Electromagnetic compatibility certification barriers for industrial automation components create first-mover advantage for pre-qualified suppliers.
- Additive manufacturing convergence:Topology-optimized forcer windings produced through selective laser melting reduce mass and improve thermal performance.
Industry Challenges
- Mechatronics talent scarcity:Cross-functional expertise combining electromagnetic design, thermal management, and motion control firmware remains concentrated in Japanese and German engineering clusters.
- Qualification timeline compression:ISO 13849 functional safety certification for medical and collaborative robot applications extends development cycles by 18-24 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Linear Shaft Motor Market |
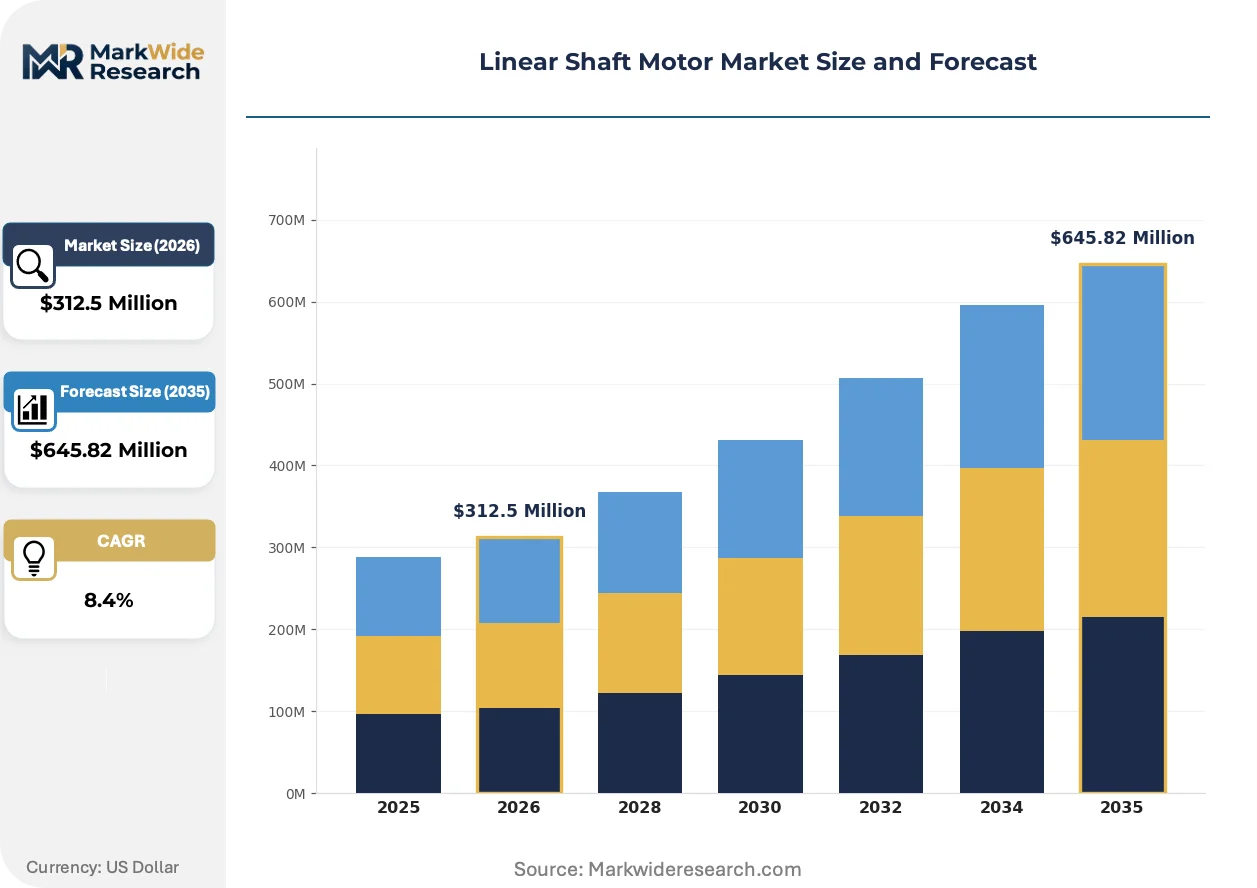
| Market Size in 2026 | $312.5 Million |
| Market Size in 2035 | $645.82 Million |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Motor Type: Brushless, Stepper, AC Induction, DC Servomotor Application: Medical Equipment, Robotics, CNC Machines, Packaging End User: Aerospace, Automotive, Electronics, Manufacturing Technology: Direct Drive, Linear Actuation, Magnetic Levitation, Servo Control |
| Companies Covered | NTI AG LinMot, ETEL S.A., Aerotech Inc., Kollmorgen Corporation, ESR Pollmeier GmbH, Jenny Science AG, H2W Technologies Inc., Beckhoff Automation GmbH & Co. KG, Oswald Elektromotoren GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Linear Shaft Motor Market Trends and Innovations
Precision automation is pivoting toward frictionless electromagnetic architectures as thermal management advances and cleanroom compatibility requirements harden. Three developments are restructuring competitive positioning.
Halbach-array magnet configurations are integrating into tubular shaft designs to maximize airgap flux density while minimizing radial forces. Semiconductor lithography OEMs in Taiwan and South Korea are adopting these configurations for wafer stage positioning. This topology is integrating into next-generation systems by enabling thinner magnetic shafts without sacrificing thrust output.
Japan's METI has aligned JIS standards with ISO safety frameworks for precision mechatronics, creating technical convergence pressure across export markets. Japanese motor suppliers must now certify to unified electromagnetic compatibility and functional safety benchmarks. Medical equipment manufacturers sourcing from Japan face streamlined qualification when entering European and North American markets.
Buyers are consolidating vendor relationships around motion subsystem integrators capable of delivering validated axis assemblies rather than discrete motor components. Semiconductor equipment makers in Shenzhen and Seoul now specify complete linear stages with pre-tuned servo parameters. This preference shift is compressing the addressable market for standalone shaft motor suppliers without positioning feedback and control expertise.
Linear Shaft Motor Market Segmentation
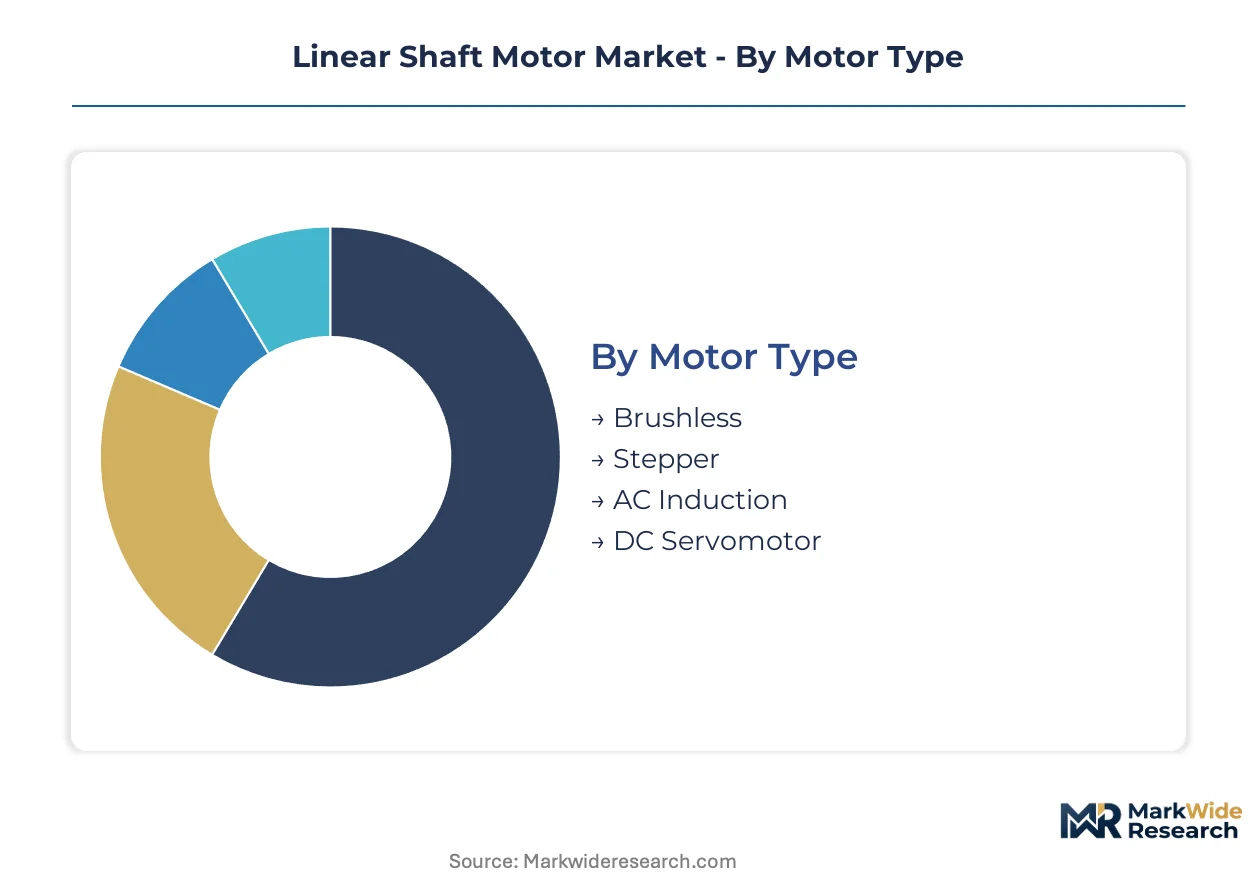
Precision automation buyers select shaft motor configurations based on thermal envelope, positioning accuracy, and integration complexity. Segmentation reveals how upgrade cycles from mechanical transmission to direct-drive architectures concentrate demand across specific motor types and end-use configurations.
Motor Type:
Equipment refresh cycles in semiconductor fabrication and medical device manufacturing favor motors with extended maintenance intervals and sub-micron repeatability.
- Brushless:Permanent magnet synchronous designs achieve thermal efficiency through distributed winding topologies and rare-earth magnet arrays. Taiwan and South Korean wafer-handling equipment OEMs specify these for vacuum-compatible stages where particle generation must be eliminated.
- DC Servomotor:Wound-field or permanent magnet DC architectures deliver rapid torque response for dynamic positioning loops. Robotic surgery platforms in North America and Europe integrate these for haptic feedback systems requiring instantaneous current control.
- Stepper:Hybrid stepper motors with microstepping drives serve cost-sensitive automation where open-loop positioning suffices.
- AC Induction:Squirrel-cage induction designs persist in heavy-duty material handling with relaxed precision requirements.
Brushless motors sit at the top of the volume ranking, with DC Servomotor climbing the fastest as medical device qualification cycles lock in multi-year supply agreements.
Application:
Margin concentration varies sharply by validation burden and cleanroom compatibility requirements.
- Medical Equipment:FDA-validated motion control for robotic surgery and diagnostic imaging demands electromagnetic architectures with documented MTBF data and traceable calibration chains. Extended qualification cycles in the United States and European Union justify premium unit economics.
- Robotics:Collaborative robot joints and Cartesian positioning systems require force-torque sensing integration. Shenzhen and Seoul manufacturing clusters specify direct-drive linear modules for pick-and-place operations in electronics assembly.
- CNC Machines:High-speed machining centers adopt linear shaft motors for tool positioning in die and mold applications.
- Packaging:Food and pharmaceutical filling equipment utilizes stainless steel encapsulated motors for washdown compliance.
Medical Equipment commands the steepest margin tier, with Robotics gaining share fastest as collaborative automation penetrates precision assembly lines.
End User:
Capital allocation patterns across industrial sectors determine specification stringency and supplier qualification depth.
- Electronics:Semiconductor capital equipment makers in Taiwan and South Korea drive specifications for vacuum-compatible, particle-free linear motion. These buyers consolidate vendor relationships around subsystem integrators capable of delivering complete axis assemblies.
- Automotive:Electric vehicle battery assembly and electric motor winding equipment requires high-throughput linear transfer systems. German and Japanese automotive Tier 1 suppliers specify shaft motors for stator winding and cell stacking operations.
- Aerospace:Flight control test rigs and satellite component positioning demand radiation-hardened and extreme temperature variants.
- Manufacturing:General industrial automation represents volume demand with moderate precision requirements.
Electronics leads absolute volume, with Automotive expanding most quickly as battery production capacity scales across East Asia and Europe.
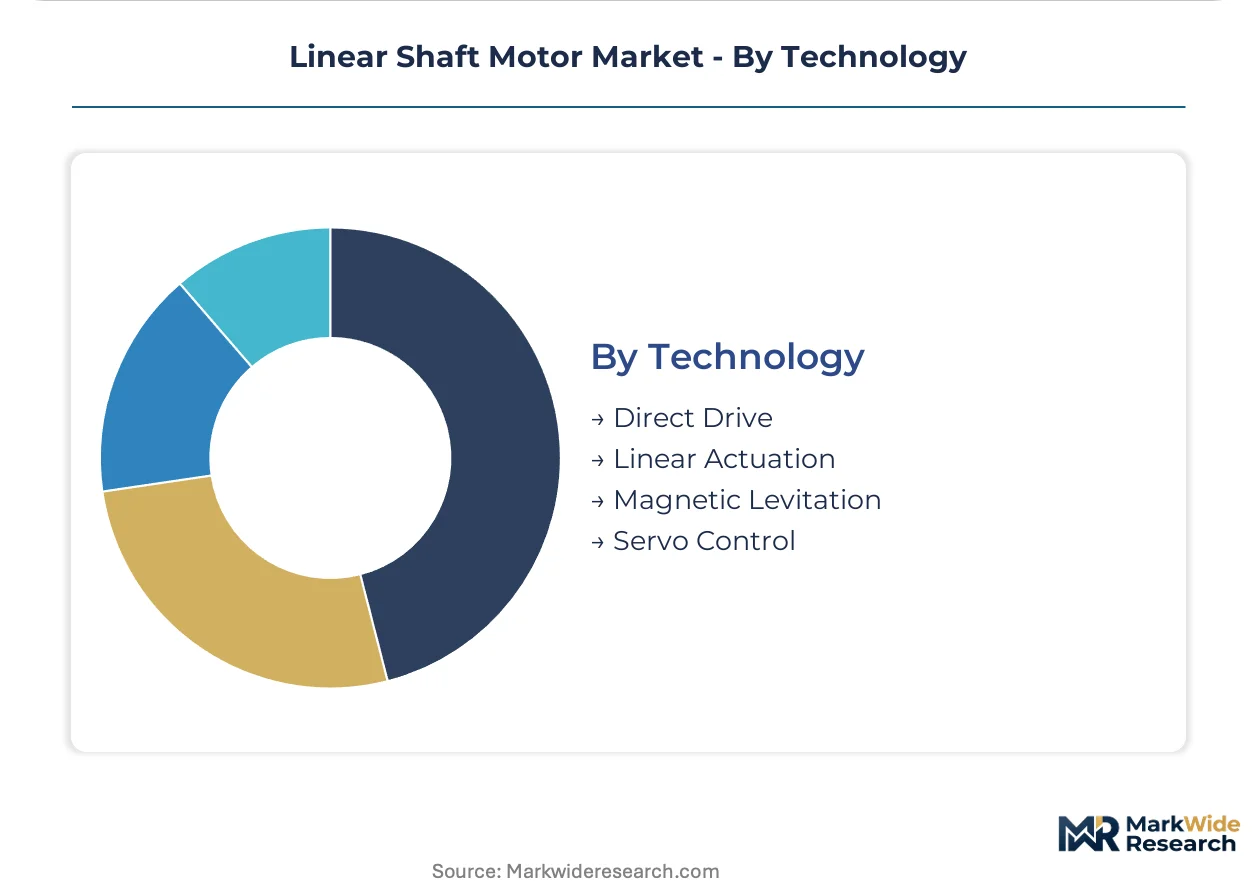
Technology:
Architecture selection determines thermal dissipation path, feedback resolution, and control loop complexity.
- Direct Drive:Elimination of mechanical transmission elements enables positioning accuracy below one micron without backlash or wear. Semiconductor lithography OEMs in Taiwan specify these for wafer stage positioning where maintenance access is restricted.
- Magnetic Levitation:Frictionless operation through active magnetic bearings commands premium pricing in cleanroom environments. South Korean display panel manufacturing adopts these for OLED deposition stages where particle contamination risks are acute.
- Linear Actuation:Simplified electromagnetic topologies serve cost-constrained applications with moderate stroke lengths.
- Servo Control:Closed-loop architectures with optical or magnetic encoders provide the feedback necessary for dynamic tracking.
Direct Drive dominates installed base, with Magnetic Levitation representing the fastest-growing trajectory as vacuum-compatible cleanroom applications multiply.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Taiwan and South Korea outpace Germany in semiconductor capital equipment deployment, while Japan maintains tighter regulatory alignment with European safety frameworks than either competitor.
Taiwan
Wafer-handling equipment OEMs in Hsinchu Science Park drive vacuum-compatible linear motion procurement. Taiwan's Industrial Development Bureau enforces electromagnetic compatibility certification under local standards harmonized with IEC frameworks. Precision automation suppliers cluster around Taichung, where subsystem integrators deliver complete axis assemblies for lithography stages.
South Korea
Display panel manufacturers in Gyeonggi Province specify magnetic levitation shaft motors for OLED deposition equipment. MFDS medical device regulations and KATS industrial standards create dual compliance pathways for motion control vendors. Seoul-based equipment makers consolidate vendor relationships around pre-qualified motion subsystem suppliers.
Germany
Automotive Tier 1 suppliers in Baden-Württemberg deploy shaft motors for electric motor winding and battery cell stacking operations. The EU Machinery Directive and CE marking requirements enforce ISO 13849 functional safety standards for collaborative robotics. Stuttgart engineering clusters concentrate mechatronics talent combining electromagnetic design with thermal management expertise.
Japan
Precision motor suppliers in Nagoya and Osaka restructure capacity toward direct-drive architectures for semiconductor and medical applications. METI-aligned JIS standards converge with ISO safety frameworks, streamlining export qualification. Yokohama-based subsystem integrators now specify complete linear stages rather than discrete motor components.
China
Shenzhen precision manufacturing clusters demand direct-drive linear modules for electronics assembly automation. SAMR mandates GB standards compliance and electromagnetic compatibility testing for industrial automation components entering domestic supply chains. Suzhou and Shanghai equipment makers increasingly source from pre-certified suppliers to avoid import barriers.
Linear Shaft Motor Market Competitive Landscape
Japanese and German producers anchor the premium tier; Swiss and American specialists hold differentiated positions in medical and semiconductor subsegments. The vendor base concentrates around precision mechatronics engineering clusters with rare-earth magnet supply proximity. Three archetypes dominate: integrated motion subsystem suppliers, standalone motor fabricators with captive magnet processing, and medical equipment specialists with FDA-validated qualification chains. Competitive moves center on backward integration into rare-earth magnet sourcing and strategic partnerships with semiconductor lithography OEMs.
Within the medical-specialist tier, NTI AG LinMot and Jenny Science AG exemplify Swiss precision engineering heritage applied to FDA-validated motion control. Aerotech Inc. occupies a position among North American nanopositioning specialists serving semiconductor lithography. Kollmorgen Corporation anchors the integrated subsystem approach through captive supply of complementary torque motor technologies.
| Leading Market Players |
|---|
| NTI AG LinMot |
| ETEL S.A. |
| Aerotech Inc. |
| Kollmorgen Corporation |
| ESR Pollmeier GmbH |
| Jenny Science AG |
| H2W Technologies Inc. |
| Beckhoff Automation GmbH & Co. KG |
| Oswald Elektromotoren GmbH |
| Others |
Pricing and Supply Chain Analysis
Semiconductor equipment OEMs in Taiwan and South Korea now mandate complete linear stage assemblies with pre-tuned servo parameters rather than discrete motor components, forcing suppliers to absorb integration costs or cede margin to subsystem integrators. This procurement consolidation concentrates pricing power among motion control specialists capable of delivering validated axis assemblies, compressing standalone motor margins while elevating premium tiers for FDA-validated medical configurations.
Pricing Analysis
Distributor margins in the 15-25% range separate premium medical-grade shaft motors from standard industrial variants, with ISO 13849 functional safety certification and FDA validation cycles justifying 40-60% unit price premiums over unqualified alternatives. Three-tier pricing structure across premium, standard, and economy levels stratifies by thermal envelope and positioning accuracy, with brushless synchronous designs commanding top tier placement. Cost compression in standard industrial tiers intensifies as Chinese suppliers achieve GB standards compliance and compete on electromagnetic compatibility certification. Electronics assembly buyers in Shenzhen manufacturing clusters exhibit highest price sensitivity, while robotic surgery platform developers in North America and Europe prioritize qualification reliability over unit cost.
Supply Chain Analysis
Dual-sourcing requirements from Japanese and German automotive Tier 1 suppliers mandate qualified secondary suppliers for rare-earth magnet arrays and precision-wound forcer assemblies, extending vendor qualification timelines. Magnet processing concentrates in China, precision winding in Japan and Germany, and final subsystem integration across Taiwan and South Korea. Neodymium and dysprosium supply draws from Chinese export licensing frameworks and Australian mining operations, with coil insulation materials sourced from specialized chemical suppliers in Japan and the United States. Single-source vulnerability in rare-earth magnet supply creates input cost uncertainty during export quota adjustments. Distribution runs through motion control distributors serving regional industrial automation clusters, with direct OEM relationships dominating semiconductor and medical equipment procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion trajectories in this market rest on thermal management innovation reducing forced cooling system costs and magnetic levitation variants capturing premium positioning in vacuum-compatible applications.
For Market Incumbents: Deploy backward integration into rare-earth magnet sourcing to insulate against Chinese export licensing volatility and secure cost visibility for multi-year semiconductor supply agreements. Incumbent suppliers must anchor relationships with Taiwan lithography OEMs through Halbach-array topology development, while defending against voice coil substitution in sub-100mm stroke applications by emphasizing maintenance interval superiority. Capacity addition in Taichung and Hsinchu Science Park clusters supports proximity to wafer-handling equipment demand. For New Entrants and Emerging Players: Mid-tier CNC machine builders in Southeast Asia represent an underserved buyer archetype seeking direct-drive linear positioning without full semiconductor-grade qualification burdens. New entrants should prioritize additive manufacturing convergence for topology-optimized forcer windings, targeting cost-sensitive automation where open-loop stepper alternatives currently dominate. A go-to-market angle emphasizing selective laser melting production and reduced thermal mass offers differentiation against established Japanese and German fabricators. For Investors and Strategic Acquirers: Asymmetric upside sits with medical equipment specialists possessing FDA-validated motion control qualification chains and documented MTBF data for robotic surgery platforms. Long-term viability favors subsystem integrators capable of delivering complete linear stages rather than discrete motor suppliers facing vendor consolidation pressure. Watch for inflection signals in South Korean OLED deposition equipment procurement, where magnetic levitation adoption rates indicate premium technology migration timing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Magnet Processing | Captive neodymium supply insulates Japanese suppliers against Chinese export licensing volatility. |
| Halbach-Array Topology Development | Maximized airgap flux density enables thinner magnetic shafts for Taiwan lithography OEMs. |
| Medical Device Qualification Investment | FDA-validated motion control locks in multi-year supply agreements with robotic surgery developers. |
| Additive Manufacturing Forcer Production | Selective laser melting reduces forcer mass and improves thermal dissipation in compact form factors. |
| Subsystem Integration Partnership | Pre-tuned axis assemblies meet Shenzhen semiconductor equipment procurement consolidation preferences. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with semiconductor equipment procurement managers, medical device engineering directors, precision motor R&D leads, and motion control subsystem integrators with secondary validation against METI industrial statistics, SAMR certification registries, EU Machinery Directive implementation guidance, and SEC filings from precision automation suppliers. Bottom-up demand modeling across wafer-handling equipment deployments and top-down macroeconomic triangulation anchored volume estimates.
Segment-weighting approaches distributed value across brushless, DC servomotor, stepper, and AC induction motor types, with further stratification by direct drive, magnetic levitation, linear actuation, and servo control technology architectures. End-use weighting incorporated medical equipment, robotics, CNC machines, and packaging applications across electronics, automotive, aerospace, and general manufacturing sectors. CAGRs derived from equipment refresh cycle analysis and capital expenditure trajectories in semiconductor fabrication and electric vehicle battery assembly.
Underlying measurement precision varies by segment; medical equipment and semiconductor applications carry tighter precision than general industrial automation given documented procurement data availability. Forecasts reflect assumptions regarding rare-earth magnet supply continuity, GB standards enforcement consistency, and JIS-ISO convergence maintenance. Deviation in Chinese export licensing frameworks or EU Machinery Directive enforcement timing would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Equipment
Electrode Slag Remelting (ESR) Furnace Market
Industrial Equipment
Industrial Linear Accelerator Market
Industrial Equipment
Industrial Monitor Market
Industrial Equipment
Global Industrial Dispensing System and Equipment Market
Industrial Equipment
Fiber Laser Coding System Market
Industrial Equipment
Mounted Bearing Market
Industrial Equipment
Air Filters Market
Industrial Equipment
Global Twister Winder Market
Industrial Equipment
Global Thick Film Heater Market
Industrial Equipment
Latin America Explosion-Proof Equipment Market
Industrial Equipment
Soldering Iron Market
Industrial Equipment
Electron Beam Welding Systems Market
Industrial Equipment
Europe Ceramic Roller Bearings Market
Industrial Equipment
Linear Motion (LM) Shaft Market
Industrial Equipment
Dry Block Heaters Market
Industrial Equipment
Industrial Fans Market