
 Mounted Bearing Market | 2026-2036
Mounted Bearing Market Size, Share, and Industry Trends Forecast 2026-2036
Mounted Bearing Market Analysis
Chinese foundry capacity is broadening the supply base for cast iron bearing housings. SKF leverages integrated sealing technology to sustain premium positioning across European wind turbine OEMs. Schaeffler AG anchors its mounted bearing portfolio through backward integration into heat treatment and rolling element production. The TIMKEN Company competes aggressively in North American agricultural equipment channels where seasonal replacement cycles drive recurring revenue.
A mounted bearing combines a rolling element bearing with a mechanical housing that enables secure attachment to a frame or structure, typically incorporating set screws, adapter sleeves, or eccentric locking collars for shaft fixation; cast iron and stainless steel housings dominate industrial specifications, with sealing configurations rated for IP65 or higher environmental protection. Pillow block units occupy the largest volume share due to their versatility in conveyor and fan applications, while stainless steel variants are capturing margin pools in food processing and pharmaceutical settings where FDA compliance and frequent washdown cycles mandate corrosion resistance. Flange-mounted configurations are displacing traditional pillow blocks in compact machinery designs where vertical space constraints limit installation options.
ISO 492 and ABMA standards govern dimensional tolerances and load ratings, while OSHA machinery guarding regulations in the United States and the EU Machinery Directive enforce safety-critical performance thresholds for bearing failures in exposed rotating equipment. REACH compliance across European supply chains restricts certain lubricant additives and surface coatings, compelling reformulation of bearing greases and housing finishes. Stakeholders must monitor evolving carbon border adjustment mechanisms and raw material traceability requirements that will reshape supplier qualification protocols and procurement criteria.
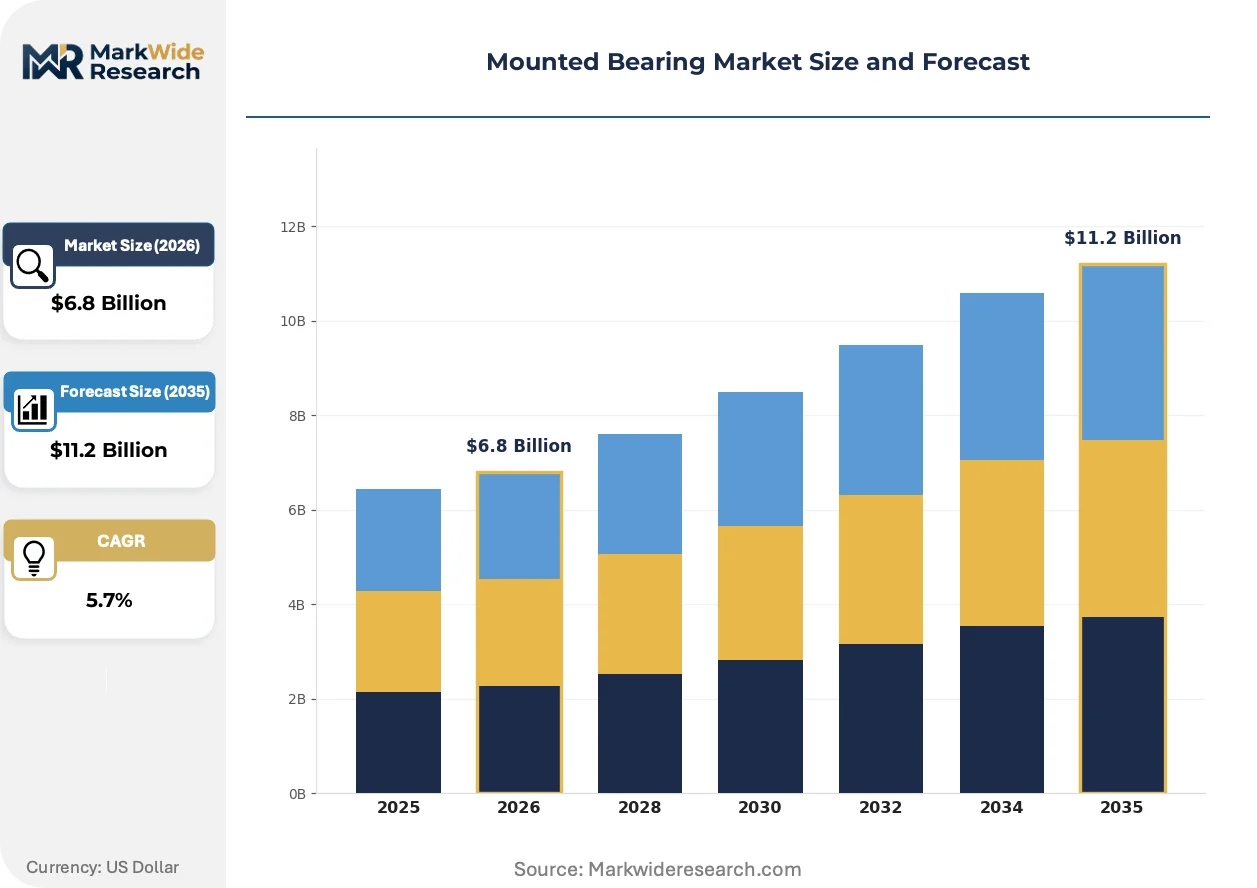
Market Dynamics
The EU Machinery Directive and escalating ISO cleanliness protocols are forcing manufacturers to redesign sealing configurations and housing materials, compressing product development cycles while elevating certification costs across European supply chains.
Growth Catalysts
- REACH compliance mandates:Restrictions on lubricant additives and surface coatings compel reformulation of bearing greases, creating pull for certified clean-label products across EU member states.
- Food processing automation:Washdown-resistant stainless steel housings are becoming standard in FDA-inspected facilities, replacing cast iron units in wet-process environments.
- German precision manufacturing clusters:Automotive OEM supply chains anchor procurement volumes for high-load pillow block and flange-mounted configurations.
Market Restraints
- Raw material concentration:Chinese foundry capacity dominates cast iron housing supply, exposing buyers to carbon border adjustment mechanism risks and traceability compliance costs.
- Stainless steel input volatility:Nickel and chromium price swings compress margin pools for corrosion-resistant product lines, particularly affecting food-grade and pharmaceutical specifications.
- Technical limitation in extreme environments:IP65 sealing configurations struggle in sub-zero Arctic applications and high-pressure washdown cycles above 80°C, restricting addressable markets.
Strategic Opportunities
- Wind turbine OEM channels:Integrated sealing technology demand from European renewable energy installers creates premium positioning for suppliers with in-house lubrication system design.
- Agricultural equipment seasonal replacement:North American harvesting and planting cycles drive recurring revenue through dealer network stocking programs.
- Compact machinery vertical space constraints:Flange-mounted configurations displace traditional pillow blocks in material handling and packaging equipment where footprint reduction is critical.
Industry Challenges
- Heat treatment skill scarcity:Specialized metallurgical expertise for rolling element production concentrates in legacy industrial regions, constraining capacity expansion.
- Multi-standard certification timelines:Simultaneous ISO 492, ABMA, and OSHA machinery guarding compliance extends product launch schedules by 8-14 months.
- Legacy system integration friction:Smart sensor-enabled mounted bearings face interoperability barriers with existing predictive maintenance platforms in brownfield industrial facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mounted Bearing Market |
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $11.2 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pillow Block, Flange, Take-Up, Split Material: Cast Iron, Stainless Steel, Plastic, Bronze Application: Agricultural Equipment, Manufacturing Machinery, Conveyors, Automotive End User: Aerospace, Food Processing, Mining, Marine |
| Companies Covered | SKF, Schaeffler AG, The TIMKEN Company, NSK Ltd., NTN Corporation, JTEKT Corporation, RBC Bearings, Regal Rexnord, FYH Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mounted Bearing Market Emerging Trajectories
Sealing technology convergence with condition monitoring systems is compressing the traditional separation between mechanical components and digital infrastructure, reshaping how buyers evaluate total cost of ownership.
Polymer-composite bearing housings with embedded vibration sensors is unifying structural support and predictive diagnostics into single SKUs. Food processing OEMs in the Netherlands and Denmark are piloting these units at 15-20% premium pricing. The technology is unifying maintenance scheduling with production planning, eliminating the historical disconnect between mechanical procurement and Industry 4.0 investments.
REACH restrictions on perfluorinated compounds are eliminating legacy PTFE-based seals from European supply chains. Industrial grease formulations now rely on calcium sulfonate and polyurea thickeners to maintain EP performance. German wind turbine service providers face the steepest reformulation costs, passing compliance premiums through 24-month service contracts.
Buyer consolidation among agricultural equipment distributors is compressing supplier counts and extending payment terms. Independent bearing distributors in the US Midwest are ceding share to manufacturer-direct programs with seasonal inventory guarantees. Iowa and Illinois implement the most aggressive channel restructuring, with OEM captive parts operations capturing 60% of replacement volume in Class 8 combines.
Mounted Bearing Market Segmentation
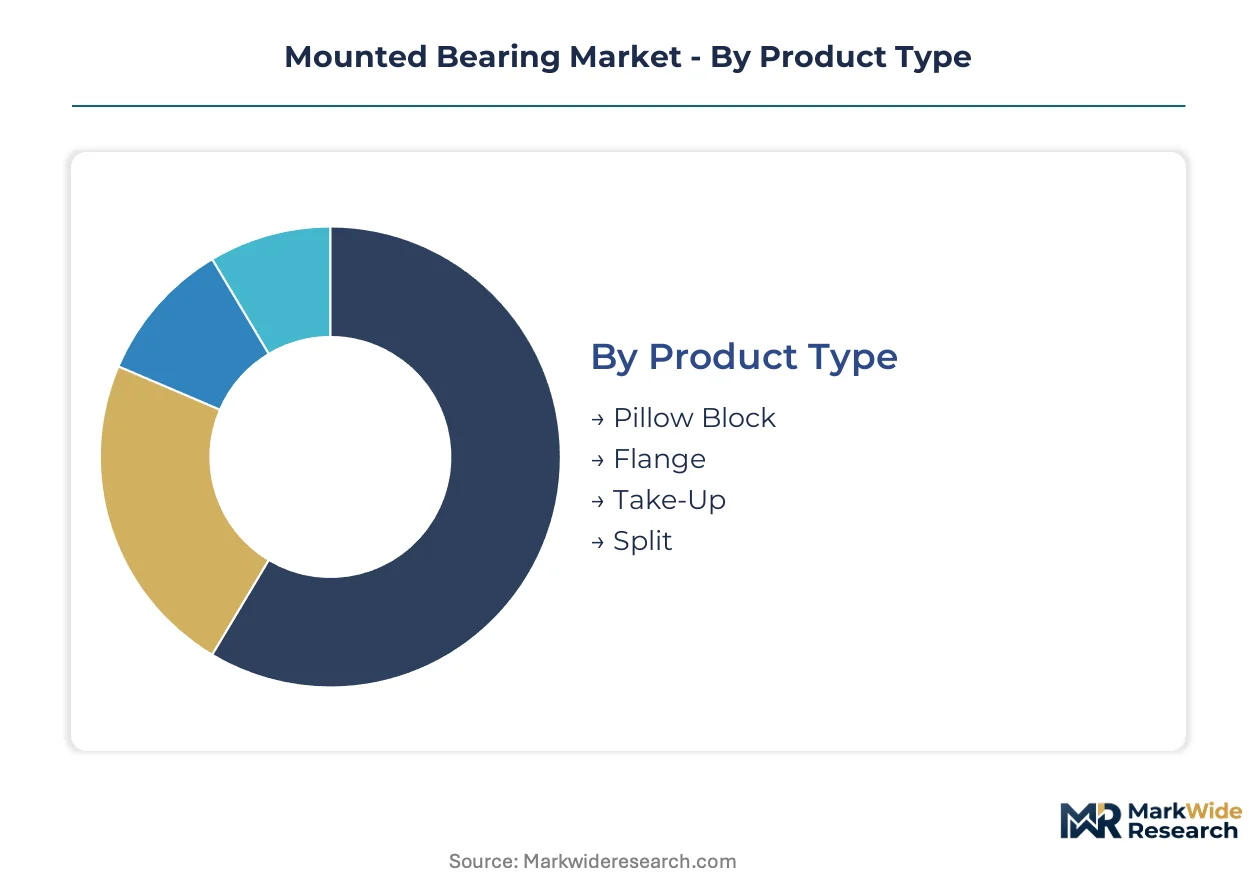
Mounted bearing procurement hinges on environmental exposure, load requirements, and regulatory compliance rather than price alone. Buyers evaluate housing materials and sealing configurations against specific duty cycles, creating distinct preference clusters across industrial verticals.
Product Type:
Equipment footprint and shaft orientation dictate housing geometry selection, with maintenance accessibility and load distribution as secondary filters.
- Pillow Block:Horizontal split housings with two bolt mounting feet accommodate shaft diameters from 12mm to 100mm. Demand concentrates in German automotive supplier parks where conveyor systems require rapid bearing replacement during shift changes. Cast iron variants dominate, though stainless steel units are penetrating washdown zones.
- Flange:Square or circular bolt patterns enable vertical mounting where floor space constraints eliminate pillow block options. Compact packaging machinery in the Netherlands and Denmark drives specification, with four-bolt square configurations preferred for high-moment loads.
- Take-Up:Sliding rail housings permit belt tension adjustment in bulk material handling systems. Mining operations in Western Australia specify these for overland conveyor installations exceeding three kilometers.
- Split:Bisected housings allow installation on continuous shafts without disassembly. Marine propulsion systems and large industrial fans use these where shaft removal is impractical.
Volume sits with Pillow Block; growth tilts toward Flange.
Material:
Corrosion exposure and thermal cycling determine housing alloy selection, with total cost of ownership calculations favoring premium materials in high-downtime environments.
- Cast Iron:Gray iron ASTM A48 Class 30 provides vibration damping and machinability at lowest unit cost. Chinese foundries supply the majority of global volume, exposing buyers to carbon border adjustment risks under EU CBAM implementation.
- Stainless Steel:AISI 304 and 316 housings withstand caustic washdown cycles in FDA-inspected facilities. Food processing OEMs in Denmark accept 40-60% price premiums for corrosion resistance and surface finish compliance.
- Plastic:Glass-reinforced polyamide housings eliminate galvanic corrosion in chemical exposure and reduce weight by 70%. Semiconductor wet process equipment and pool filtration systems specify these for submersible duty.
- Bronze:C93200 bearing bronze offers seawater compatibility and anti-galling properties. Offshore wind turbine nacelles and desalination plants specify these for 25-year service life targets.
Cast Iron captures current procurement volumes; Stainless Steel climbs the fastest as food safety protocols tighten.
Application:
Duty cycle intensity and contamination exposure separate specification tiers, with seasonal replacement patterns creating distinct revenue rhythms.
- Agricultural Equipment:Harrow bearings and combine header drives experience concentrated seasonal loads. Iowa and Illinois dealer networks stock pillow block inventories for 90-day harvest windows, generating recurring replacement revenue.
- Manufacturing Machinery:Machine tool spindles and robotic positioning axes demand ABEC 7 precision classes. German precision manufacturing clusters anchor specification authority for high-load configurations.
- Conveyors:Bulk handling and unit handling systems drive the largest unit volumes. Mining overland systems and airport baggage handling represent opposite ends of the load spectrum.
- Automotive:Paint shop conveyor chains and welding fixture positioning require IP65 sealing minimum. OEM captive parts operations capture majority replacement volume through direct service contracts.
Conveyors dominate installed base; Agricultural Equipment shows steepest expansion trajectory through precision farming mechanization.
End User:
Certification requirements and environmental severity create non-overlapping procurement specifications with minimal cross-buying.
- Food Processing:USDA and FDA compliance mandates stainless steel housings with smooth surface finishes below 0.8 micrometers Ra. Netherlands pilot programs test polymer-composite sensor-embedded units at premium pricing.
- Mining:Dust ingress and shock loading exceed standard IP ratings. Australian iron ore operations specify custom labyrinth seals with automatic grease replenishment systems.
- Aerospace:AS9100 quality systems and traceability requirements restrict supplier pools. Landing gear and actuation systems use split bronze configurations for weight-critical applications.
- Marine:Classification society rules from DNV and ABS govern material specifications. Offshore platform crane slewing bearings represent the highest load-duty segment.
Mining holds current volume leadership; Food Processing gains share fastest through automation and washdown standardization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chinese foundry capacity anchors cast iron housing supply chains, while European precision manufacturing clusters and North American agricultural equipment channels concentrate demand for specialized configurations.
United States
OSHA machinery guarding regulations enforce safety-critical performance thresholds for bearing failures in exposed rotating equipment. Iowa and Illinois dealer networks stock pillow block inventories for 90-day harvest windows, generating recurring replacement revenue through seasonal agricultural cycles.
Germany
REACH compliance mandates restrictions on lubricant additives and surface coatings, compelling reformulation of bearing greases across EU member states. Automotive OEM supply chains in Baden-Württemberg anchor procurement volumes for high-load pillow block and flange-mounted configurations.
China
Domestic foundry capacity dominates gray iron ASTM A48 Class 30 supply, exposing buyers to carbon border adjustment mechanism risks under EU CBAM implementation. Yangtze River Delta manufacturing hubs feed component demand for conveyor and fan applications across Asia-Pacific assembly operations.
Netherlands
Food processing OEMs pilot polymer-composite sensor-embedded units at 15-20% premium pricing, unifying maintenance scheduling with production planning. FDA-inspected facilities in Randstad industrial zones specify stainless steel housings with smooth surface finishes below 0.8 micrometers Ra.
Australia
Mining operations in Western Australia specify take-up units for overland conveyor installations exceeding three kilometers. Dust ingress and shock loading exceed standard IP ratings, driving custom labyrinth seals with automatic grease replenishment systems in Pilbara iron ore districts.
Mounted Bearing Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue sensor-embedded and condition-monitoring adjacent spaces. The vendor base stratifies across integrated rolling-element manufacturers, specialized housing fabricators, and regional distribution-focused assemblers. Three archetypes dominate: full-stack producers with captive heat-treatment capacity, component specialists sourcing seals and lubrication systems externally, and private-label distributors leveraging contract foundries. Competitive moves concentrate on backward integration into metallurgical processes and strategic partnerships with predictive maintenance platform providers.
Among European-integrated manufacturers, SKF exemplifies the premium-tier archetype through sealing technology convergence with digital infrastructure. Schaeffler AG occupies a position within the full-stack producer category, anchored by in-house rolling element and heat treatment capabilities. The TIMKEN Company represents the North American agricultural channel specialist, sitting within the distribution-integrated tier serving seasonal replacement cycles.
| Leading Market Players |
|---|
| SKF |
| Schaeffler AG |
| The TIMKEN Company |
| NSK Ltd. |
| NTN Corporation |
| JTEKT Corporation |
| RBC Bearings |
| Regal Rexnord |
| FYH Inc. |
| Others |
Supply Flow & Price Mechanics
Family-owned mid-cap housing fabricators in Italy and Spain anchor regional supply clusters, translating captive foundry relationships into pricing discipline that resists spot-market volatility. Their long-term OEM contracts embed cost-pass-through mechanisms for nickel and chromium swings, insulating margin pools while compressing flexibility for spot buyers.
Pricing Analysis
Warranty and service bundling separates premium-tier suppliers from commodity assemblers, with integrated sealing technology and predictive maintenance subscriptions commanding 15-20% uplifts over bare-unit transactions. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade divergence—REACH-compliant clean-label products, ISO 492 precision classes, and unmarked gray-market imports. Cost compression in standard cast iron tiers intensifies because Chinese foundry overcapacity feeds spot-price erosion. Agricultural equipment distributors exhibit highest price sensitivity due to seasonal inventory turns, while wind turbine OEMs prioritize total cost of ownership over unit economics.
Supply Chain Analysis
Dual-sourcing mandates from German automotive OEMs and Dutch food processing conglomerates force qualification of secondary housing suppliers across Poland and the Czech Republic, diluting concentration risk. Raw material flows draw from Chinese gray iron foundries, Swedish bearing steel mills, and Finnish nickel refineries. Carbon border adjustment mechanism exposure under EU CBAM implementation threatens cost competitiveness of single-source China-reliant buyers. Distribution runs through manufacturer-direct programs for wind and automotive channels, while independent distributors retain agricultural and aftermarket service presence.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market consolidates around REACH compliance costs and smart-sensor R&D thresholds that exhaust mid-tier balance sheets. Multi-standard certification timelines extending 8-14 months accelerate exits among undercapitalized regional assemblers.
For Market Incumbents: Hedge carbon border exposure by qualifying Eastern European foundry partners before CBAM full implementation. Capture heat treatment skill scarcity through apprenticeship pipelines in Baden-Württemberg and Thuringia. Backward integration into rolling element production defends margin pools against Chinese bearing steel price volatility. For New Entrants and Emerging Players: Enter via polymer-composite sensor-embedded configurations where Dutch and Danish food processing OEMs pilot at premium acceptance. Target bronze housing specifications for offshore wind nacelles, a segment where 25-year service life requirements restrict incumbent flexibility. Partner with predictive maintenance platform providers to bypass brownfield interoperability barriers. For Investors and Strategic Acquirers: Distressed-cycle entries favor stainless steel specialists with FDA-registered surface finish capabilities in Denmark and the Netherlands. Five-to-ten year viability hinges on clean-label grease formulation portfolios and sensor integration roadmaps. Monitor REACH restriction expansion on perfluorinated compounds as inflection signal for compliance-cost winners.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Heat Treatment | Captive metallurgical capacity insulates Schaeffler AG and SKF from rolling element supply constraints. |
| Sensor-Embedded Housing Development | Polymer-composite units with vibration diagnostics unify mechanical and digital infrastructure for Dutch food OEMs. |
| REACH-Compliant Grease Reformulation | Calcium sulfonate and polyurea thickeners replace PTFE seals, passing compliance premiums through German wind service contracts. |
| Seasonal Inventory Guarantee Programs | Manufacturer-direct stocking in Iowa and Illinois dealer networks captures 60% of Class 8 combine replacement volume. |
| Eastern European Foundry Qualification | Polish and Czech supplier diversification hedges EU CBAM exposure for German automotive OEM supply chains. |
Methodological Framework
Independent corroboration across maintenance directors at German automotive supplier parks, procurement leads at Dutch food processing OEMs, and aftermarket service heads at North American agricultural equipment distributors underwrites the qualitative findings. Secondary validation draws from EU Machinery Directive implementation guidance, REACH restriction updates from ECHA, customs data on Chinese gray iron exports, and SEC filings from listed bearing manufacturers. Bottom-up unit economics from housing fabrication cost models triangulate against top-down demand projections from conveyor and wind turbine installation databases.
Rate-of-change decomposition segments volume and value trajectories across housing material tiers, sealing configuration ratings, and end-user certification requirements throughout the forecast period. Product type splits—pillow block, flange, take-up, split—intersect with application intensity segments including mining overland conveyors, food washdown cycles, and agricultural seasonal duty. CAGR derivation rests on installed base replacement curves and OEM procurement cycle analysis, with nickel price volatility and CBAM phase-in schedules as sensitivity inputs.
Forecast precision tightens around the base case; tail outcomes carry wider variance under accelerated REACH restriction expansion or abrupt Chinese foundry capacity rationalization. Deviation in German wind turbine installation pace would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Equipment
North America Industrial Embedded Systems Market
Industrial Equipment
Floor Scales Market
Industrial Equipment
Global Special Purpose Machines Market
Industrial Equipment
Global Cold Plate Market
Industrial Equipment
Pin Marking Machine Market
Industrial Equipment
United States Fusion Splicer Market
Industrial Equipment
Global Cryostat Market
Industrial Equipment
Asia-Pacific Fans and Blowers Market
Industrial Equipment
Global Industrial Enclosures Market
Industrial Equipment
Air Bearings Market
Industrial Equipment
Electron Beam Welding Systems Market
Industrial Equipment
CNC Tool Storage System Market
Industrial Equipment
Roller Bearings Market
Industrial Equipment
Middle-East Fans and Blowers Market
Industrial Equipment
Industrial Joysticks Market
Industrial Equipment
Actuators Market