
 Middle-East Fans and Blowers Market | 2026-2036
Middle-East Fans and Blowers Market Size, Share, and Industry Trends Forecast 2026-2036
Middle-East Fans and Blowers Market Foresight
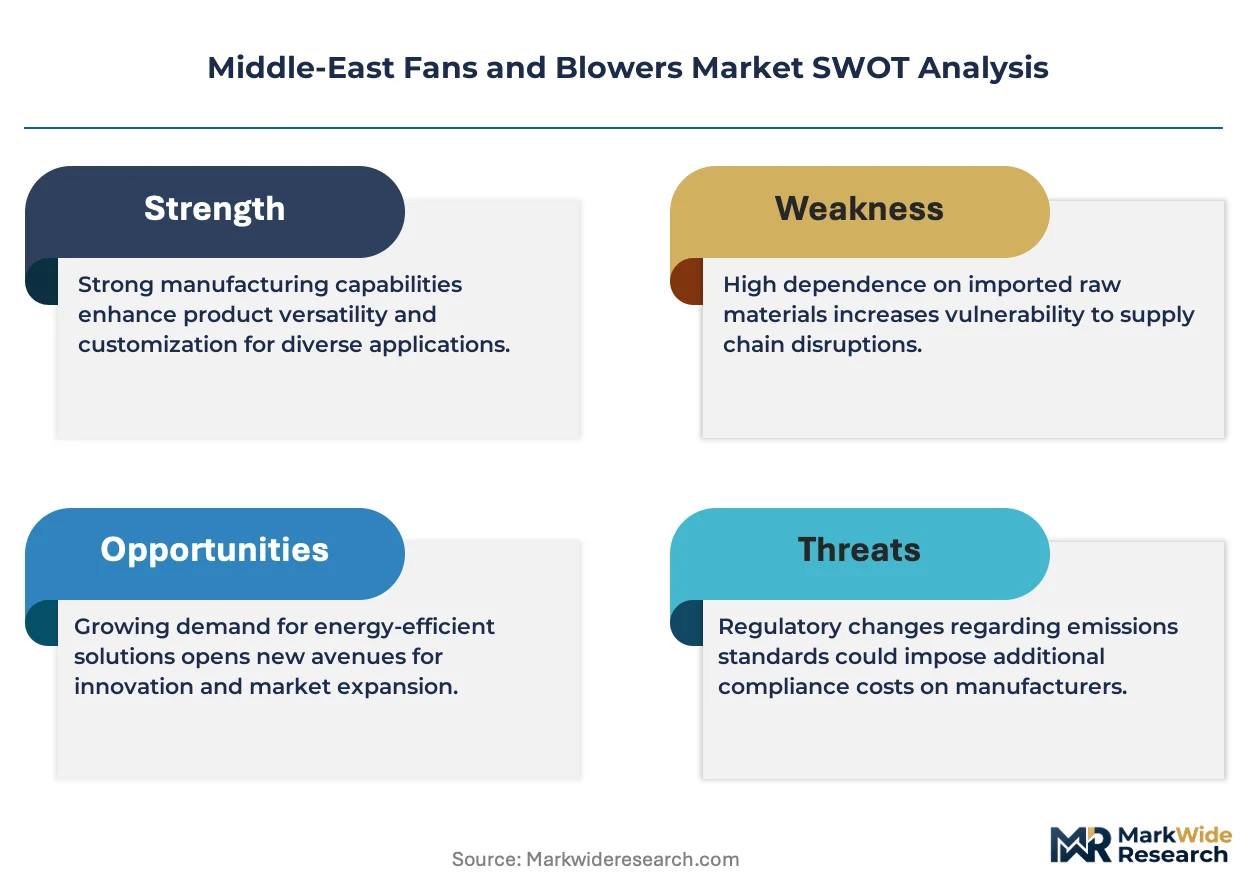
Multi-source procurement is restructuring supply relationships across the Middle-East Fans and Blowers Market. Zamil Industrial Investment Company anchors regional manufacturing with captive foundry and fabrication capabilities in Saudi Arabia. Gardner Denver Inc. competes through aftermarket service density and oil-free compressor technology adjacencies. Howden Group Ltd. specializes in heavy-duty centrifugal systems for petrochemical clients across the Gulf.
Fans and blowers are electromechanical devices that generate airflow through rotating impellers or blades, with centrifugal designs producing pressure ratios up to 1.2 and axial configurations delivering high-volume, low-pressure movement for ventilation and process cooling. Their primary purpose spans industrial process air handling, building climate control, and combustion or exhaust management across energy-intensive facilities. Centrifugal fans command the largest installed base in Middle Eastern petrochemical complexes due to their pressure-handling suitability for high-temperature process streams. Low-noise technology is gaining specification share in healthcare and premium commercial end users across the UAE and Qatar, where acoustic compliance now filters procurement shortlists.
Saudi Standards, Metrology and Quality Organization (SASO) efficiency labeling and UAE's Emirates Authority for Standardization and Metrology (ESMA) thermal performance codes are tightening minimum efficiency thresholds for imported HVAC equipment, compelling manufacturers to redesign motor and impeller packages for Gulf climate conditions. SFDA and MOHAP facility ventilation standards in Saudi Arabia and the UAE respectively mandate specific air-change rates in healthcare construction, directly shaping blower sizing and redundancy requirements for hospital projects. Stakeholders must weigh regional certification complexity against the volume concentration in Saudi Vision 2030 and Qatar National Vision infrastructure pipelines.
Market Dynamics
SASO efficiency labeling and ESMA thermal performance codes are compressing product lifecycles across the Middle-East Fans and Blowers Market, forcing manufacturers to redesign motor-impeller packages specifically for Gulf climate conditions while Gulf Cooperation Council infrastructure pipelines concentrate demand timing.
Growth Catalysts
- Saudi Vision 2030 infrastructure pipeline:Giga-project construction in NEOM and the Red Sea is generating concentrated demand for high-capacity HVAC and process cooling systems. Hospital ventilation mandates from SFDA are specifying redundant blower configurations.
- Qatar National Vision 2030 stadium cooling:Legacy sports infrastructure requires direct-drive axial systems with desert-optimized coatings. FIFA event specifications are accelerating adoption of low-noise centrifugal designs.
- Petrochemical capacity expansion:High-temperature process streams across Jubail and Yanbu industrial cities are sustaining demand for heavy-duty centrifugal fans. Sour gas handling requirements are tightening material specifications.
Market Restraints
- Copper and rare-earth magnet cost volatility:Motor winding materials face supply concentration from East Asian refiners. Price swings compress margin predictability for Saudi-based fabricators.
- Foundry capacity bottleneck:Regional casting capabilities concentrate in Dammam industrial corridor. Lead times for specialized impeller alloys extend procurement cycles.
- Water-cooled system substitution:District cooling networks in Dubai and Abu Dhabi are displacing distributed fan-coil units in premium commercial segments.
Strategic Opportunities
- Oman and Kuwait greenfield healthcare:Hospital construction in Muscat and Kuwait City is underpenetrated by specialized medical-grade ventilation suppliers. MOH-equivalent facility standards are creating specification windows.
- Variable frequency drive convergence:Integration of permanent magnet motors with IoT-enabled controls is opening retrofit markets in existing petrochemical assets.
- Aftermarket service digitization:Predictive maintenance platforms are creating new revenue streams beyond equipment sales. Remote monitoring contracts are penetrating Qatar's stadium operator segment.
Industry Challenges
- Computational fluid dynamics talent scarcity:Impeller design optimization requires specialized simulation expertise. Regional engineering programs produce insufficient aerodynamics specialists.
- Multi-jurisdiction certification timelines:Simultaneous SASO, ESMA, and Qatar Civil Defense approvals extend product launch cycles. Testing facility capacity in the Gulf remains constrained.
- Legacy BAS integration complexity:New high-efficiency units must interface with existing building automation protocols in Dubai's commercial stock. Protocol translation adds commissioning cost.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle-East Fans and Blowers Market |
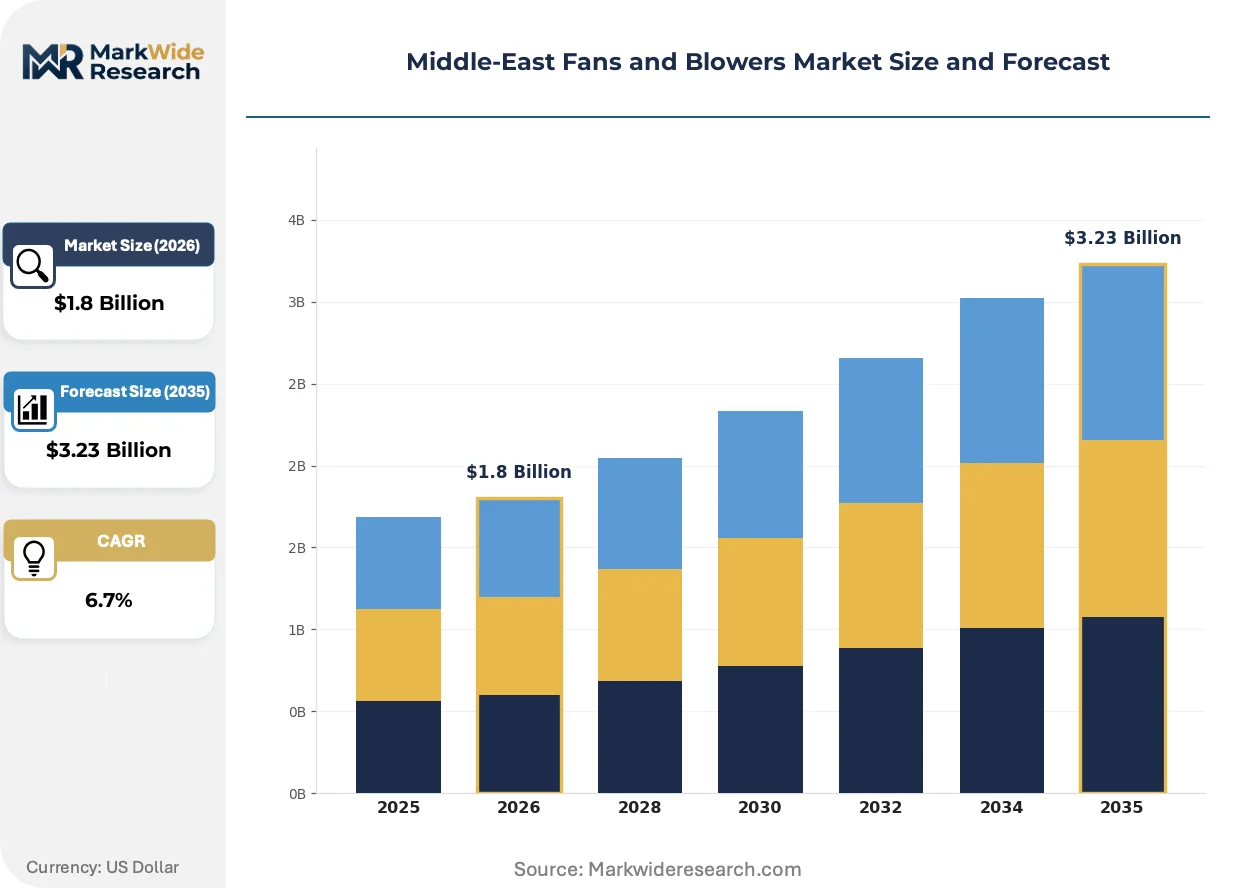
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Axial Fans, Centrifugal Fans, Blowers, Exhaust Fans End User: Manufacturing, Healthcare, Commercial, Residential Application: HVAC, Industrial Processes, Ventilation, Cooling Technology: Direct Drive, Belt Driven, Electric, Low Noise |
| Companies Covered | Acme Engineering & Manufacturing Corp., Gardner Denver Inc., Greenheck Fan Corporation, Howden Group Ltd., Flakt Woods Group SA, Continental Blower LLC, Twin City Fan, Systemair AB, Zamil Industrial Investment Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle-East Fans and Blowers Market Shifts & Advancements
Electrification of industrial processes and tightening acoustic standards are reshaping equipment specifications across Middle Eastern installations. Manufacturers are optimizing for dual performance vectors: thermal efficiency under extreme ambient conditions and noise attenuation for urban proximity.
Permanent magnet synchronous motor technology is absorbing specification share in Saudi petrochemical and healthcare applications. Aramco and SABIC affiliates are specifying oil-free bearing systems for critical process streams. This magnetic drive architecture is absorbing maintenance intervals and reducing vibration signatures in high-availability installations.
ESMA thermal performance codes and SASO efficiency labeling are mandating minimum IE3 motor classifications for imported HVAC equipment. These frameworks are disqualifying legacy induction motor designs from Gulf procurement shortlists. Healthcare and premium commercial segments in Dubai and Abu Dhabi are responding fastest, with engineering consultants rewriting specifications to exclude non-compliant submissions.
Multi-year service contracts are unbundling from capital equipment sales in Qatar's stadium and infrastructure cooling segments. Facility operators are separating performance guarantees from hardware procurement, with Zamil Industrial and international OEMs competing on availability metrics rather than upfront pricing. This unbundling is most visible in Doha metro and Lusail stadium maintenance tenders, where outcome-based agreements now dominate procurement evaluation criteria.
Middle-East Fans and Blowers Market Segmentation
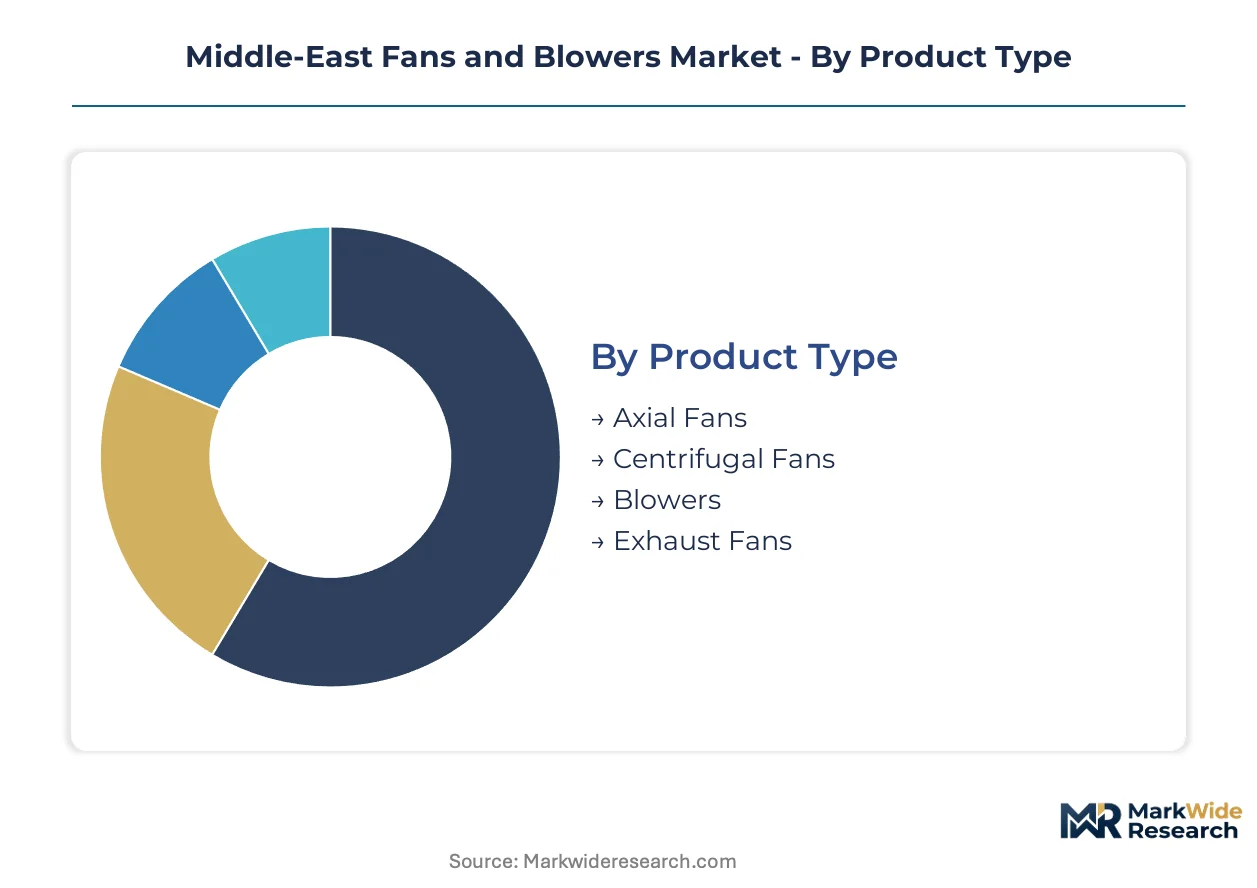
Equipment classification in the Middle-East Fans and Blowers Market determines which SASO, ESMA, or Qatar Civil Defense certifications apply. Segmentation boundaries shape procurement workflows, maintenance protocols, and margin structures across Saudi petrochemical complexes and UAE healthcare facilities.
Product Type:
Certification burden varies sharply by impeller architecture: centrifugal designs face Qatar Civil Defense pressure-vessel approvals for sour gas service, while axial configurations trigger ESMA acoustic compliance for stadium and healthcare installations.
- Axial Fans:Propeller-style impellers generate high-volume, low-pressure airflow optimized for ventilation and cooling towers. Demand concentrates in Qatar's Lusail stadium district and NEOM's linear city infrastructure, where direct-drive variants with desert-optimized coatings are displacing belt-driven legacy units under FIFA event specifications.
- Centrifugal Fans:Radial blade configurations deliver pressure ratios up to 1.2 for process air handling and high-temperature exhaust. SABIC and Aramco affiliates in Jubail and Yanbu specify heavy-duty alloy impellers for sour gas streams, with material certifications from SASO extending procurement cycles.
- Blowers:Positive-displacement and regenerative designs serve pneumatic conveying and combustion air supply. Medical-grade variants for Saudi SFDA hospital mandates require redundant configurations.
- Exhaust Fans:Rooftop and inline configurations manage fume extraction across commercial kitchens and industrial facilities. ESMA fire-safety integration standards apply to Dubai high-rise installations.
Leading the category by volume: Centrifugal Fans. Growing fastest: Axial Fans.
End User:
Customer type dictates service intensity and contract structure, with petrochemical operators demanding multi-year availability guarantees and healthcare buyers separating performance metrics from hardware procurement.
- Manufacturing:Petrochemical, cement, and steel producers in Saudi Arabia's Eastern Province sustain demand for high-availability process cooling. Aramco maintenance contracts specify magnetic bearing systems to reduce vibration signatures in continuous-duty installations.
- Healthcare:Hospital construction under Saudi Vision 2030 and UAE MOHAP standards mandates specific air-change rates. SFDA ventilation requirements are reshaping blower sizing and redundancy specifications for Riyadh and Jeddah medical cities.
- Commercial:Office towers and retail complexes across Dubai and Abu Dhabi prioritize acoustic compliance over raw efficiency. District cooling substitution is compressing distributed fan-coil demand in premium segments.
- Residential:Villa and apartment HVAC in Riyadh and Doha drives volume demand for compact axial units. SASO efficiency labeling is disqualifying induction motor designs from new construction.
Highest service revenue attachment: Manufacturing. Steepest specification tightening: Healthcare.
Application:
Functional deployment determines motor classification requirements under ESMA thermal performance codes and SASO efficiency labeling frameworks.
- HVAC:Climate control systems account for the largest installed base across Saudi commercial construction. NEOM and Red Sea giga-projects are specifying IE3 minimum motors with IoT-enabled controls.
- Industrial Processes:Process air handling in Jubail and Yanbu petrochemical corridors demands high-temperature alloys and oil-free bearing architectures. Sour gas compatibility filters supplier shortlists.
- Ventilation:Fresh air supply and exhaust management in healthcare and commercial buildings. MOHAP and SFDA air-change mandates directly shape equipment sizing.
- Cooling:Data center and critical infrastructure thermal management is absorbing permanent magnet synchronous motor technology for efficiency gains under extreme ambient conditions.
Widest technology choice: HVAC. Tightest material specifications: Industrial Processes.
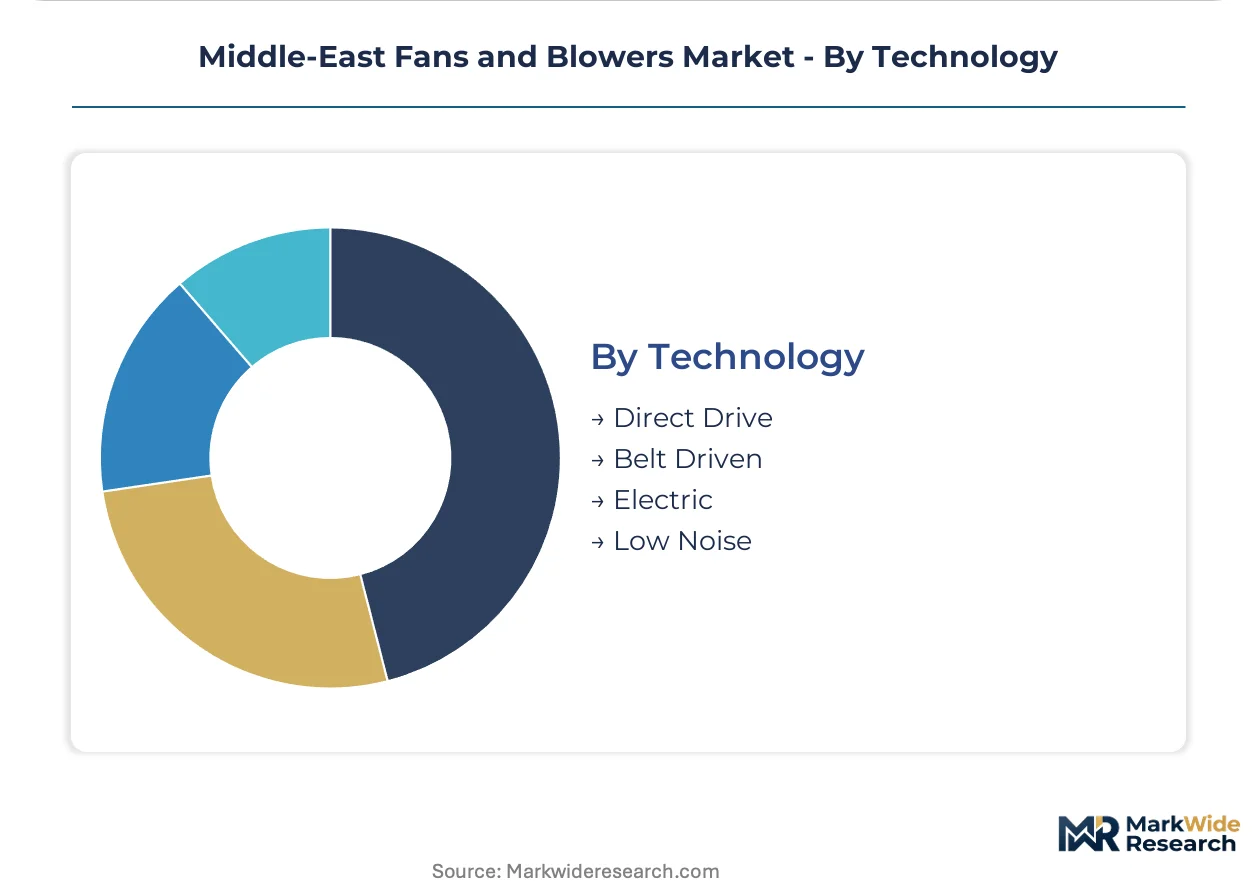
Technology:
Drive architecture and acoustic engineering separate premium from standard tiers, with permanent magnet systems commanding price premiums in Saudi petrochemical and healthcare segments.
- Direct Drive:Motor-impeller integration eliminates belt maintenance and reduces vibration. Qatar stadium operators are specifying this architecture for legacy cooling infrastructure under outcome-based maintenance contracts.
- Belt Driven:Flexible speed ratios through pulley configurations persist in cost-sensitive residential and light commercial segments. SASO efficiency thresholds are accelerating replacement demand.
- Electric:Grid-powered systems dominate across all voltage classes, with variable frequency drive convergence opening retrofit markets in existing Dubai commercial stock.
- Low Noise:Acoustic attenuation packages for healthcare and premium commercial buyers in Abu Dhabi and Doha. FIFA event specifications are accelerating adoption in Qatar sports infrastructure.
Highest efficiency tier: Direct Drive. Fastest specification gain: Low Noise.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Foundry-grade aluminum and copper concentrate in Saudi Arabia's Eastern Province, anchoring regional impeller fabrication capacity while Gulf Cooperation Council energy mandates reshape equipment specifications across six national markets.
Saudi Arabia
NEOM giga-projects and Red Sea tourism infrastructure are absorbing high-capacity HVAC systems at unprecedented scale. SASO efficiency labeling mandates IE3 minimum motor classifications for all imported climate-control equipment. Riyadh medical city construction under Vision 2030 specifies redundant blower configurations per SFDA ventilation standards.
United Arab Emirates
Dubai's premium commercial towers and Abu Dhabi healthcare campuses prioritize acoustic compliance in procurement shortlists. ESMA thermal performance codes disqualify legacy induction motor designs from new construction tenders. Jebel Ali industrial corridor hosts the Gulf's densest concentration of aftermarket service providers.
Qatar
Lusail stadium district and metro infrastructure require direct-drive axial systems with desert-optimized coatings. FIFA event specifications accelerate low-noise centrifugal adoption across legacy sports facilities. Doha facility operators now unbundle multi-year service contracts from capital equipment procurement.
Kuwait
Greenfield hospital construction in Kuwait City creates specification windows for medical-grade ventilation suppliers. MOH-equivalent facility standards mandate specific air-change rates in new healthcare infrastructure. Al-Zour refinery expansion sustains demand for high-temperature process air handling systems.
Oman
Muscat healthcare construction remains underpenetrated by specialized blower suppliers serving SFDA-equivalent standards. Sultan Qaboos University Hospital expansion and new medical city projects reshape procurement pipelines. Sohar industrial port petrochemical investments absorb heavy-duty centrifugal configurations for sour gas streams.
Middle-East Fans and Blowers Market Competitive Landscape
Global majors compete with regional champions across certification complexity and service density, producing a tiered structure where captive foundry capacity separates premium fabricators from import-dependent distributors. Three archetypes dominate: vertically integrated regional champions with in-house casting, global OEMs competing through aftermarket service networks, and specialized centrifugal producers for petrochemical applications. Capacity expansion in Saudi Arabia's Eastern Province and outcome-based maintenance contracting in Qatar's stadium segment represent the dominant competitive vectors reshaping positioning.
Among regional fabricators, Zamil Industrial Investment Company anchors Saudi manufacturing with captive foundry capabilities in Dammam. Global OEMs Gardner Denver Inc. and Howden Group Ltd. occupy positions across the aftermarket service and heavy-duty process equipment tiers respectively, with the former exemplifying oil-free technology adjacencies and the latter representing petrochemical-specialist centrifugal configurations. These three entities illustrate the competitive spectrum from localized vertical integration to global technology licensing models.
| Leading Market Players |
|---|
| Acme Engineering & Manufacturing Corp. |
| Gardner Denver Inc. |
| Greenheck Fan Corporation |
| Howden Group Ltd. |
| Flakt Woods Group SA |
| Continental Blower LLC |
| Twin City Fan |
| Systemair AB |
| Zamil Industrial Investment Company |
| Others |
Supply & Pricing Matrix
Sovereign-backed producers and family-owned mid-caps dominate Middle Eastern fabrication capacity, compressing margin variability through captive foundry operations while Gulf energy mandates reshape procurement cost structures across Saudi Arabia, UAE, and Qatar.
Pricing Analysis
Warranty and service bundling separates premium tenders from commodity procurement in Qatar's stadium segment, where multi-year availability contracts now trade independently of hardware pricing. Three-tier pricing structure across premium, standard, and economy levels reflects certification burden divergence: SASO efficiency-labeled IE3 systems command premiums in Saudi healthcare, while belt-driven axial units face cost compression in residential Riyadh construction. Pricing pressure stems from copper and rare-earth magnet volatility transmitted through East Asian refiner concentration. Manufacturing petrochemical operators exhibit lowest price sensitivity due to continuous-duty reliability requirements; residential buyers in Doha and Jeddah remain most price-elastic.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale demand from NEOM and Red Sea giga-projects, while distributor networks serve fragmented healthcare and commercial construction across Kuwait and Oman. Supply concentrates in Saudi Arabia's Eastern Province foundry corridor and China's motor winding component base. Raw material dependencies span aluminum impeller alloys, copper windings, and neodymium permanent magnets. Single-source vulnerability in East Asian rare-earth processing exposes Saudi fabricators to price transmission lag. Distribution runs through Zamil Industrial's Dammam captive capacity and Jebel Ali aftermarket service clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Foundry capacity bottlenecks in the Dammam industrial corridor prop pricing discipline, constraining volume response to Qatar stadium and Saudi healthcare demand surges.
For Market Incumbents: Anticipate permanent magnet motor substitution accelerating replacement cycles in Jubail petrochemical assets. Defensive consolidation through backward integration into copper winding supply and certification pre-positioning for Qatar Civil Defense pressure-vessel approvals will offset margin compression from water-cooled district cooling substitution in Dubai commercial towers. For New Entrants and Emerging Players: Engineering procurement consultants in Muscat and Kuwait City represent the most penetrable channel partner type for specialized medical-grade ventilation. White-space concentration in Oman healthcare construction and aftermarket digitization for Qatar stadium operators offers specification entry before incumbent service contracts renew. Pursue outcome-based maintenance tender unbundling as the primary go-to-market angle. For Investors and Strategic Acquirers: Zamil Industrial's foundry capacity utilization rates are the leading indicator that regional fabrication margins will sustain compression resistance. Long-term viability centers on captive upstream supply control and certification moats across SASO, ESMA, and Qatar Civil Defense frameworks. Acquisition screening should prioritize mid-cap specialists with aerodynamics simulation talent and existing Gulf regulator relationships.| Strategic Initiative | Industry Significance |
|---|---|
| Foundry Capacity Expansion | Dammam corridor additions reduce lead times for specialized impeller alloys serving SABIC affiliates. |
| Permanent Magnet Motor Integration | IE3-compliant architectures capture Saudi healthcare mandates under SASO efficiency labeling. |
| Outcome-Based Service Contracting | Availability metrics separate Zamil Industrial from capital-equipment competitors in Qatar stadium tenders. |
| Low-Noise Technology Certification | Acoustic compliance opens FIFA-specified procurement in Doha sports infrastructure. |
| Predictive Maintenance Platform Launch | IoT-enabled remote monitoring penetrates Aramco continuous-duty installations for vibration signature reduction. |
Research Methodology
Document review covered customs trade data, SASO and ESMA regulatory filings, and petrochemical operator maintenance records, complemented by interviews with plant engineers at Jubail industrial complexes, procurement leads at Saudi healthcare construction firms, aftermarket service heads in Jebel Ali, and aerodynamics specialists at regional engineering consultancies. Secondary validation drew from SEC filings of listed OEMs, Qatar Civil Defense certification databases, and Gulf Cooperation Council infrastructure pipeline announcements. Bottom-up equipment demand modeling triangulated against top-down macro construction forecasts.
Cross-referencing historical import volumes against expert panel input on NEOM and Red Sea project timing shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include impeller architecture, end-user industry, motor technology tier, and application function. CAGRs derived from equipment replacement cycles, regulatory compliance deadlines, and infrastructure spend trajectories. Industry-specific inputs incorporated SFDA air-change mandates and FIFA event specification timelines.
Caveats apply where copper and rare-earth magnet price volatility, foundry capacity constraints, or multi-jurisdiction certification delays could materially shift the outlook. Forecasts reflect documented assumptions on infrastructure completion rates and regulatory enforcement intensity. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Equipment
United States Fusion Splicer Market
Industrial Equipment
Air Preparation Equipment (FRL) Market
Industrial Equipment
Laser Processing Market
Industrial Equipment
Micro Motor Market
Industrial Equipment
Europe Vacuum Pump Market
Industrial Equipment
Global Laser Material Market
Industrial Equipment
Global Linear Bearings Market
Industrial Equipment
Dustless Workstations Market
Industrial Equipment
Microbubble Cleaning Device Market
Industrial Equipment
Ultrasonic Atomizer Market
Industrial Equipment
Global Industrial Dispensing System and Equipment Market
Industrial Equipment
Global Dicing Blades Market
Industrial Equipment
UV Conveyor Systems Market
Industrial Equipment
Cartridge Heaters Market
Industrial Equipment
Laser Cleaning Market
Industrial Equipment
Spot Curing System Market