
 Active Buzzer Market | 2026-2036
Active Buzzer Market Size, Share, and Industry Trends Forecast 2026-2036
Active Buzzer Market Outlook
Automotive safety alert systems is hardening as the dominant end-use vertical, displacing traditional consumer electronics share. Murata Manufacturing Co., Ltd. leverages its ceramic resonator expertise to anchor premium piezoelectric supply chains. TDK Corporation sustains broad magnetic buzzer portfolios across industrial automation channels. Changzhou Shenghui Electronic Co., Ltd. competes aggressively on electromechanical unit cost for alarm and notification OEMs.
An active buzzer is a self-oscillating electroacoustic transducer containing a built-in driving circuit that generates audible tones at fixed frequencies between 1 kHz and 4 kHz when DC voltage is applied, eliminating the need for external waveform generators. Piezoelectric variants dominate volume due to lower current draw and thinner form factors, while magnetic types retain share in high-decibel industrial alarms where sound pressure levels exceed 85 dB. Digital technology integration is accelerating as IoT endpoints demand addressable, software-configurable alert tones. Bluetooth-enabled wireless buzzers represent the fastest-expanding technology niche, though analog architectures still occupy the bulk of cost-sensitive notification applications.
FCC Part 15 emissions rules in the United States and CE marking under the EU Electromagnetic Compatibility Directive constrain RF-emitting buzzer designs, pushing manufacturers toward shielded driver architectures. China's SAMR enforces GB 8898 safety standards for audio components in consumer devices, while Japan's METI mandates standby power limits that favor piezoelectric efficiency. Stakeholders must monitor evolving wireless certification burdens as Bluetooth buzzers penetrate medical and automotive alert systems.
Market Dynamics
The active buzzer market is undergoing a structural compression as automotive safety mandates harden specification requirements while East Asian manufacturing clusters consolidate supply-side control over piezoelectric component sourcing.
Growth Catalysts
- Automotive Safety Mandates:NHTSA pedestrian alert regulations and EU acoustic vehicle alerting systems are mandating external sound generators for electric vehicles, creating specification-hardened demand for weather-resistant piezoelectric modules.
- China GB 8898 Standards:SAMR-enforced audio component safety rules for consumer electronics are accelerating factory upgrades toward certified driver architectures, filtering subscale suppliers from Shenzhen and Dongguan manufacturing bases.
- Bluetooth Low Energy Integration:Wireless addressable endpoints in medical alert systems and smart building automation are pulling software-configurable tone libraries into hardware previously limited to fixed-frequency analog outputs.
Market Restraints
- Piezoelectric Ceramic Input Concentration:Lead zirconate titanate powder supply concentrates among Japanese and Chinese specialty chemical producers, exposing buzzer assemblers to price volatility and dual-use export control friction.
- Magnetic Buzzer Core Cost Structure:Copper winding wire and ferrite magnet prices fluctuate with energy-intensive smelting economics, compressing margins for high-decibel industrial alarm manufacturers competing on unit cost.
- CE EMC Certification Burden:EU Electromagnetic Compatibility Directive testing timelines and notified body backlogs extend product launch cycles for RF-emitting Bluetooth-enabled designs, favoring incumbents with established compliance infrastructure.
Strategic Opportunities
- Medical Wearable Penetration:Fall-detection pendants and medication adherence devices in aging Western European demographics represent underexploited demand for sub-2mA piezoelectric alerts with ISO 13485 quality certification.
- India PLI Scheme Tailwinds:Production-linked incentives for electronic components manufacturing are drawing assembly investment toward Gujarat and Tamil Nadu industrial corridors, creating localized supply for domestic appliance and automotive OEMs.
- Matter Protocol Convergence:Thread and Wi-Fi interoperability standards for smart home devices are enabling unified alert tone libraries across lighting, security, and HVAC endpoints, consolidating software-defined audio subsystem procurement.
Industry Challenges
- Acoustic Engineer Talent Scarcity:Specialized expertise in piezoelectric resonator tuning and enclosure acoustic design concentrates among aging Japanese and Taiwanese engineering cohorts, constraining new product velocity for Western entrants.
- Multi-Protocol Certification Complexity:Simultaneous FCC Part 15, CE RED, and Japan Radio Law approvals for Bluetooth buzzer SKUs fragment testing budgets and extend validation timelines for mid-tier suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Active Buzzer Market |
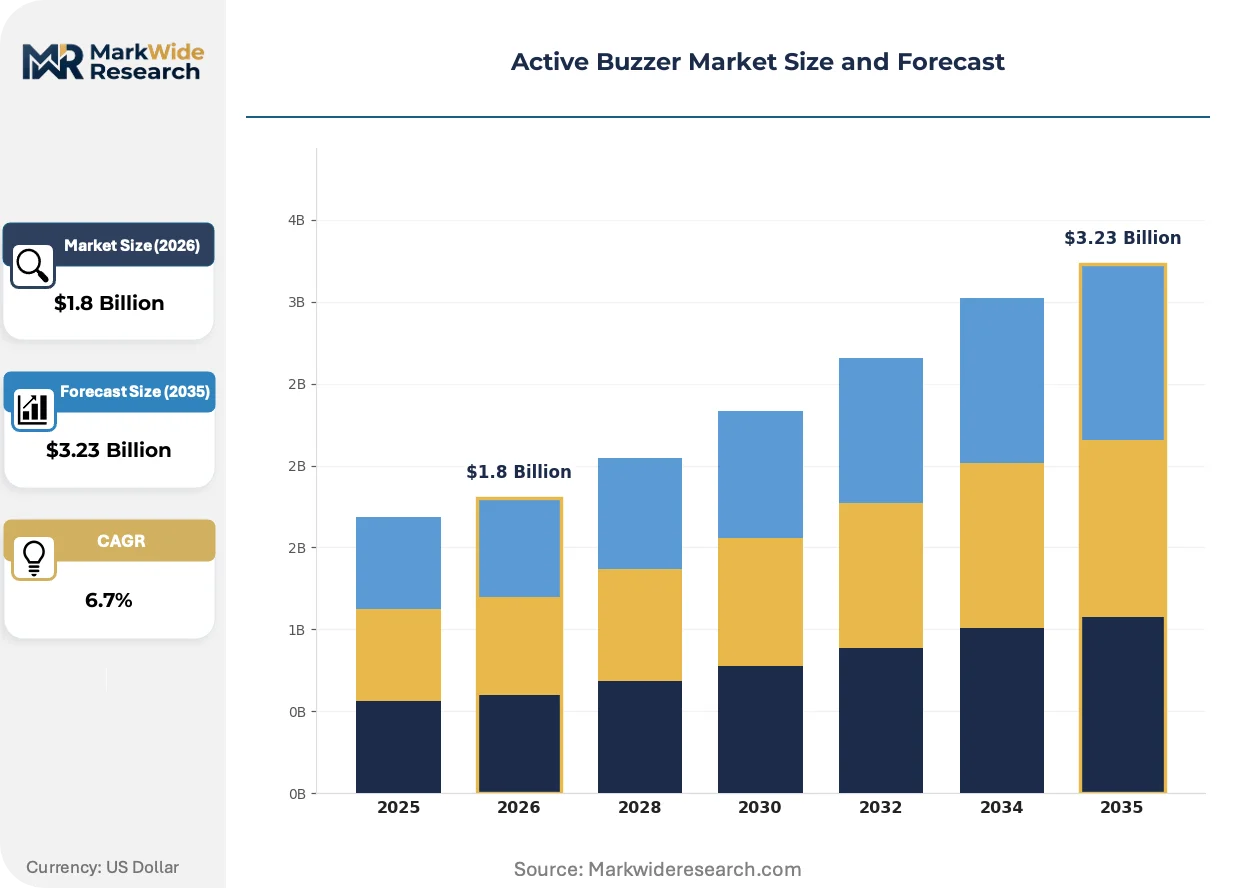
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dynamic, Piezoelectric, Magnetic, Electromechanical Technology: Digital, Analog, Wireless, Bluetooth End User: Consumer Electronics, Medical Devices, Automotive, Industrial Equipment Application: Alarms, Notifications, Feedback, Gaming |
| Companies Covered | Changzhou Shenghui Electronic Co., Ltd., Ariose Electronics Co., Ltd., Murata Manufacturing Co., Ltd., CUI Devices, FBelec Electronics Co., Ltd., TDK Corporation, Jiangsu HUAWHA Electronics Co., Ltd., Db Products, Kingstate Electronics Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Active Buzzer Market Strategic Shifts
Digital signal processing integration is actively compressing the traditional boundary between passive acoustic hardware and software-defined alert systems, enabling dynamic tone reconfiguration without physical component swaps.
Surface-mount piezoelectric buzzers with integrated CMOS driver circuits are rewriting component procurement economics for space-constrained IoT endpoints. Medical device OEMs in Germany and Switzerland are specifying these modules for portable diagnostic equipment. The technology is compressing bill-of-material complexity by eliminating external oscillator crystals and discrete driver transistors.
Japan's METI standby power regulations and China's dual carbon goals are hardening efficiency mandates that favor piezoelectric architectures over electromagnetic alternatives. Industrial automation buyers in Osaka and Nagoya manufacturing clusters are now specifying sub-10mA idle current draw as a procurement gate. Korean automotive Tier-1 suppliers are responding with dual-source qualification of ultra-low-power piezoelectric designs for next-generation electric vehicle pedestrian warning systems.
Consolidated procurement of audio alert subsystems by smart home platform operators is displacing fragmented component sourcing through traditional electronics distributors. Amazon Alexa and Google Home ecosystem device manufacturers are now specifying pre-certified buzzer modules with integrated protocol stacks. This concentration is most visible in Shenzhen ODM corridors, where white-label smart speaker and security camera assemblers have shifted from discrete component purchasing to subsystem-level supplier contracts.
Active Buzzer Market Segmentation
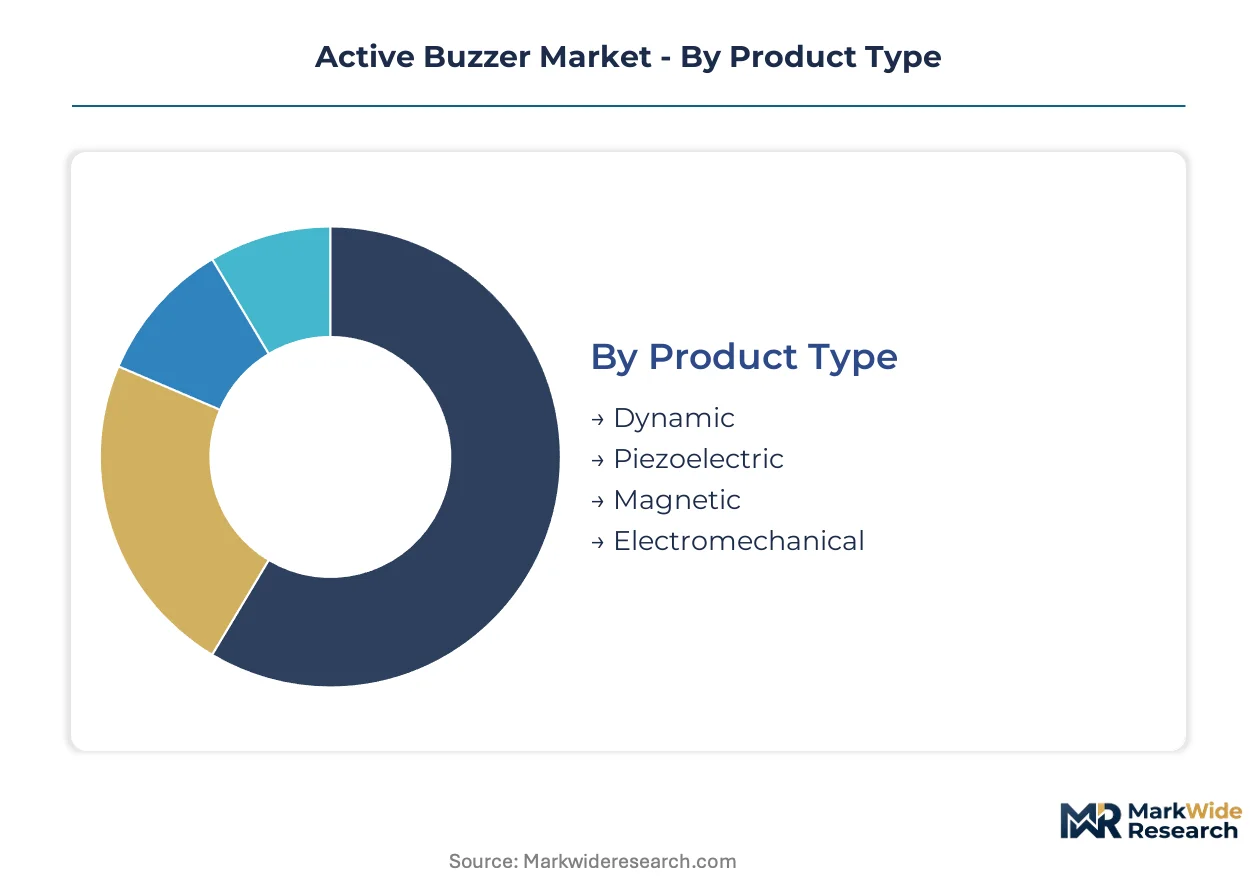
Active buzzer procurement diverges sharply across end-use verticals, with automotive safety mandates demanding certified piezoelectric modules while consumer electronics buyers prioritize unit cost above acoustic precision. Technology integration patterns and regulatory exposure further fragment sourcing strategies across supplier tiers.
Product Type:
Acoustic output requirements and current draw specifications differentiate buyer procurement profiles across industrial, automotive, and portable device segments.
- Piezoelectric:Ceramic resonator architecture generates sound through mechanical deformation of lead zirconate titanate elements, achieving sub-10mA current draw in compact surface-mount packages. Korean automotive Tier-1 suppliers in Seoul and Ulsan industrial corridors specify these modules for electric vehicle pedestrian warning systems under METI standby power regulations.
- Magnetic:Copper-wound voice coil and ferrite magnet assemblies produce sound pressure levels exceeding 85 dB for factory floor alarms and heavy machinery alerts. German industrial automation OEMs in Stuttgart and Munich manufacturing clusters source these from Japanese suppliers despite copper price volatility compressing assembler margins.
- Dynamic:Moving-coil designs with polymer diaphragms occupy mid-decibel notification applications in appliance control panels.
- Electromechanical:Relay-driven hammer mechanisms serve legacy elevator alarm and emergency call systems with minimal electronics integration.
Volume sits with Piezoelectric variants across consumer and automotive channels; growth tilts toward Magnetic types as industrial safety mandates harden in European manufacturing zones.
Technology:
Integration complexity and certification burden separate buyers seeking fixed-frequency simplicity from those requiring software-configurable alert architectures.
- Digital:Integrated CMOS driver circuits with EEPROM-stored tone libraries enable dynamic frequency switching without hardware swaps. Swiss medical device OEMs in Basel and Zurich specify these for portable diagnostic equipment requiring ISO 13485-certified alert subsystems.
- Bluetooth:Low-energy wireless stacks with FCC Part 15 and CE RED pre-certification support addressable endpoints in smart building automation. Shenzhen ODM corridors dominate sourcing for Amazon Alexa and Google Home ecosystem device manufacturers consolidating subsystem procurement.
- Analog:Discrete oscillator and driver transistor architectures persist in cost-sensitive alarm and timer applications with single-tone requirements.
- Wireless:Proprietary RF protocols serve industrial sensor networks and agricultural monitoring systems with extended range requirements.
Shipment volume concentrates in Analog architectures for legacy notification hardware; Bluetooth-enabled designs are gaining share fastest in medical wearable and smart home penetration.
End User:
Certification grade requirements and volume procurement scale create tiered supplier access patterns across regulated and consumer markets.
- Automotive:NHTSA pedestrian alert and EU acoustic vehicle alerting system mandates specify weather-resistant piezoelectric modules with AEC-Q200 qualification. Osaka and Nagoya manufacturing clusters filter suppliers through dual-source qualification protocols for next-generation electric vehicle platforms.
- Medical Devices:Fall-detection pendants and medication adherence devices in aging Western European demographics demand sub-2mA piezoelectric alerts with ISO 13485 quality certification and biocompatibility testing.
- Consumer Electronics:White-label smart speaker and security camera assemblers in Shenzhen and Dongguan corridors have shifted from discrete component purchasing to subsystem-level supplier contracts with pre-integrated protocol stacks.
- Industrial Equipment:Factory automation buyers specify high-decibel magnetic buzzers for machinery fault alerts in noise-intensive environments.
Revenue concentration rests with Automotive safety system procurement; Medical Devices show the steepest expansion trajectory as aging demographics drive wearable alert device penetration.
Application:
Sound pressure level thresholds and duty cycle requirements determine technology selection and supplier qualification depth.
- Alarms:Continuous-tone emergency systems in fire safety and industrial shutdown applications require 85 dB+ magnetic architectures with thermal overload protection. German KBA vehicle certification extends to external sound generators for commercial transport.
- Notifications:Intermittent alert tones in smartphone and appliance interfaces favor piezoelectric surface-mount modules for space-constrained PCB layouts.
- Feedback:Haptic-audio combination systems in gaming controllers and automotive interfaces integrate digital signal processing for variable frequency response.
- Gaming:Immersive audio feedback in console peripherals and VR headsets drives software-configurable tone library integration.
Unit volume clusters in Notifications for mobile and smart home devices; Feedback applications are climbing fastest as gaming and automotive interface designers converge on software-defined audio subsystems.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's PLI scheme for electronic components manufacturing is concentrating assembly investment toward Gujarat and Tamil Nadu industrial corridors, creating localized supply for domestic appliance and automotive OEMs.
China
GB 8898 safety standards enforced by SAMR are accelerating factory upgrades toward certified driver architectures, filtering subscale suppliers from Shenzhen and Dongguan manufacturing bases. Shenzhen ODM corridors dominate sourcing for smart home ecosystem device manufacturers consolidating subsystem procurement.
Japan
METI standby power regulations and dual carbon goals are hardening efficiency mandates that favor piezoelectric architectures over electromagnetic alternatives. Osaka and Nagoya manufacturing clusters filter suppliers through dual-source qualification protocols for next-generation electric vehicle platforms.
Germany
Industrial automation OEMs in Stuttgart and Munich manufacturing clusters source high-decibel magnetic buzzers for machinery fault alerts despite copper price volatility compressing assembler margins. KBA vehicle certification extends to external sound generators for commercial transport.
South Korea
Seoul and Ulsan industrial corridors specify piezoelectric modules for electric vehicle pedestrian warning systems under METI standby power regulations. Korean automotive Tier-1 suppliers are responding with dual-source qualification of ultra-low-power piezoelectric designs.
Switzerland
Medical device OEMs in Basel and Zurich specify digital CMOS driver circuits with EEPROM-stored tone libraries for portable diagnostic equipment requiring ISO 13485-certified alert subsystems. Swiss precision manufacturing standards favor sub-2mA piezoelectric alerts with biocompatibility testing.
Active Buzzer Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with premium piezoelectric supply chains consolidating around ceramic resonator expertise while electromechanical unit cost competition fragments alarm and notification OEM sourcing. The vendor base organizes into three archetypes: integrated component conglomerates with resonator-to-module vertical control, mid-scale contract assemblers serving white-label consumer electronics, and specialized magnetic buzzer fabricators for industrial safety applications. Capacity expansion and strategic partnerships dominate competitive moves as manufacturers seek to secure lead zirconate titanate powder supply and pre-certified Bluetooth module qualification.
Within the integrated component tier, Murata Manufacturing Co., Ltd. and TDK Corporation exemplify divergent strategic positions—Murata leverages ceramic resonator heritage to anchor premium piezoelectric supply chains, while TDK sustains broad magnetic buzzer portfolios across industrial automation channels. Changzhou Shenghui Electronic Co., Ltd. occupies a position among aggressive electromechanical cost competitors serving alarm and notification OEMs.
| Leading Market Players |
|---|
| Changzhou Shenghui Electronic Co., Ltd. |
| Ariose Electronics Co., Ltd. |
| Murata Manufacturing Co., Ltd. |
| CUI Devices |
| FBelec Electronics Co., Ltd. |
| TDK Corporation |
| Jiangsu HUAWHA Electronics Co., Ltd. |
| Db Products |
| Kingstate Electronics Co., Ltd. |
| Others |
Value Chain & Pricing Dynamics
Captive integration into lead zirconate titanate powder processing anchors both supply security and pricing power for Japanese and Chinese ceramic resonator specialists, while outsourced electromechanical assembly in Dongguan corridors locks cost-competitive tiers to spot-market copper and ferrite volatility.
Pricing Analysis
Short-lead-time premiums for AEC-Q200-certified piezoelectric modules command substantial markups from Korean automotive Tier-1 suppliers facing NHTSA pedestrian alert deadlines. Three-tier pricing structure across premium, standard, and economy levels separates ISO 13485-certified medical subsystems from consumer-grade surface-mount units and unbranded alarm components. Cost compression in magnetic buzzer tiers is intensifying because copper winding wire prices fluctuate with energy-intensive smelting economics. Industrial automation OEMs in Stuttgart show least price sensitivity for 85 dB+ emergency alarms, while Shenzhen white-label assemblers squeeze electromechanical suppliers hardest on unit cost.
Supply Chain Analysis
Freight cost differentials between air and sea lanes from Osaka and Nagoya to European automotive plants distort procurement timing for just-in-sequence electric vehicle assembly. Raw material supply concentrates in Japan and China for lead zirconate titanate ceramics, with copper wire and ferrite magnets sourced from South Korean and German specialty metal producers. Single-source vulnerability in Japanese ceramic powder processing exposes buzzer assemblers to dual-use export control friction. Distribution runs through consolidated subsystem contracts with Amazon Alexa and Google Home ecosystem device manufacturers rather than fragmented electronics distributor channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a cost-of-compliance story where China's GB 8898 safety standards and Japan's METI standby power regulations erect barrier-to-entry moats favoring certified driver architecture specialists over subscale Shenzhen assemblers.
For Market Incumbents: Anchor premium positioning through backward integration into lead zirconate titanate powder processing and captive CMOS driver circuit fabrication. Murata Manufacturing and TDK Corporation should defend against emerging Bluetooth module specialists by accelerating pre-certified subsystem qualification for medical wearable OEMs in Basel and Zurich. Dual-source protocols in Osaka-Nagoya automotive corridors reward incumbents with established AEC-Q200 testing infrastructure. For New Entrants and Emerging Players: Direct-to-manufacturer digital channels bypass traditional electronics distributor markups for mid-scale medical device and smart home ODM procurement. India's Gujarat and Tamil Nadu industrial corridors offer the most penetrable geography under PLI scheme tailwinds, with localized assembly for domestic appliance OEMs avoiding China's SAMR certification backlog. Target subsystem-level contracts with pre-integrated Matter protocol stacks rather than discrete component sales. For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to integrated component conglomerates seeking ceramic resonator expertise or Bluetooth module qualification. Long-term viability favors specialists with ISO 13485 medical certification and AEC-Q200 automotive qualification dual-holding capability. Watch for inflection when Korean automotive Tier-1 suppliers accelerate dual-source qualification timelines for next-generation electric vehicle pedestrian warning systems.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Ceramic Powder Processing | Captive lead zirconate titanate supply secures margin control against Japanese specialty chemical price volatility. |
| Pre-Certified Bluetooth Module Qualification | FCC Part 15 and CE RED pre-approval compresses launch cycles for medical wearable and smart home endpoints. |
| Dual-Source Automotive Qualification | AEC-Q200 certification with Korean Tier-1 suppliers in Seoul-Ulsan corridors locks in electric vehicle platform share. |
| ISO 13485 Medical Subsystem Certification | Swiss and German diagnostic equipment OEMs in Basel-Zurich mandate quality-certified alert subsystems for portable devices. |
| India PLI Scheme Manufacturing Footprint | Gujarat-Tamil Nadu assembly localizes supply for domestic appliance and automotive OEMs avoiding China tariff exposure. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs, with primary interviews conducted across acoustic design engineers at Japanese ceramic resonator specialists, procurement managers at Korean automotive Tier-1 suppliers, quality directors at Swiss medical device OEMs, and supply chain leads at Shenzhen ODM corridors. SAMR GB standard enforcement records, METI energy-efficiency directive compliance databases, and FCC Part 15 certification filings supplemented bottom-up component shipment analysis with top-down end-use demand verification.
Data-stream reconciliation across piezoelectric versus magnetic buzzer unit economics, Bluetooth module certification timelines, and regional manufacturing cost structures generated volume and value outputs throughout the forecast period. Segmentation dimensions modeled include product architecture, technology integration level, end-use certification grade, and geographic production cluster. CAGRs derived from historical shipment trajectories weighted against automotive safety mandate implementation schedules and medical wearable penetration curves in aging Western European demographics.
The model holds under stable ceramic powder supply and sustained automotive electrification investment; deviation in dual-use export controls or copper price volatility would shift component mix assumptions and margin trajectories. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Detection and Regulation Devices
Temperature Detection Screen Market
Detection and Regulation Devices
Global Counterfeit Money Detection Market
Detection and Regulation Devices
Vapour Particle Barrier Market
Detection and Regulation Devices
Registering Clock Driver (RCD) Market
Detection and Regulation Devices
Smart Water Leak Detector Market
Detection and Regulation Devices
Digital Attenuators Market
Detection and Regulation Devices
Neutron Detector Market
Detection and Regulation Devices
Betavoltaic Device Market
Detection and Regulation Devices
Global Noise Detection and Monitoring Market
Detection and Regulation Devices
Duct Smoke Detectors Market
Detection and Regulation Devices
Global Gas Detection System Market
Detection and Regulation Devices
Arc Fault Detection Devices Market
Detection and Regulation Devices
Null Detector Market
Detection and Regulation Devices
Latin America Trace Detection Market
Detection and Regulation Devices
Voltage Detector Market
Detection and Regulation Devices
Spark Detector Market