
 Asia-Pacific Fans and Blowers Market | 2026-2036
Asia-Pacific Fans and Blowers Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Fans and Blowers Market Insights
Aftermarket service revenue is fragmenting across the Asia-Pacific fans and blowers landscape as original equipment manufacturers defend installed bases against independent service providers. Ebm-papst Group leverages its direct-drive motor integration to capture recurring maintenance contracts in cleanroom applications. Howden Group Ltd anchors its position through heavy-duty centrifugal fan refurbishment programs at steel and cement plants across Australia and Southeast Asia.
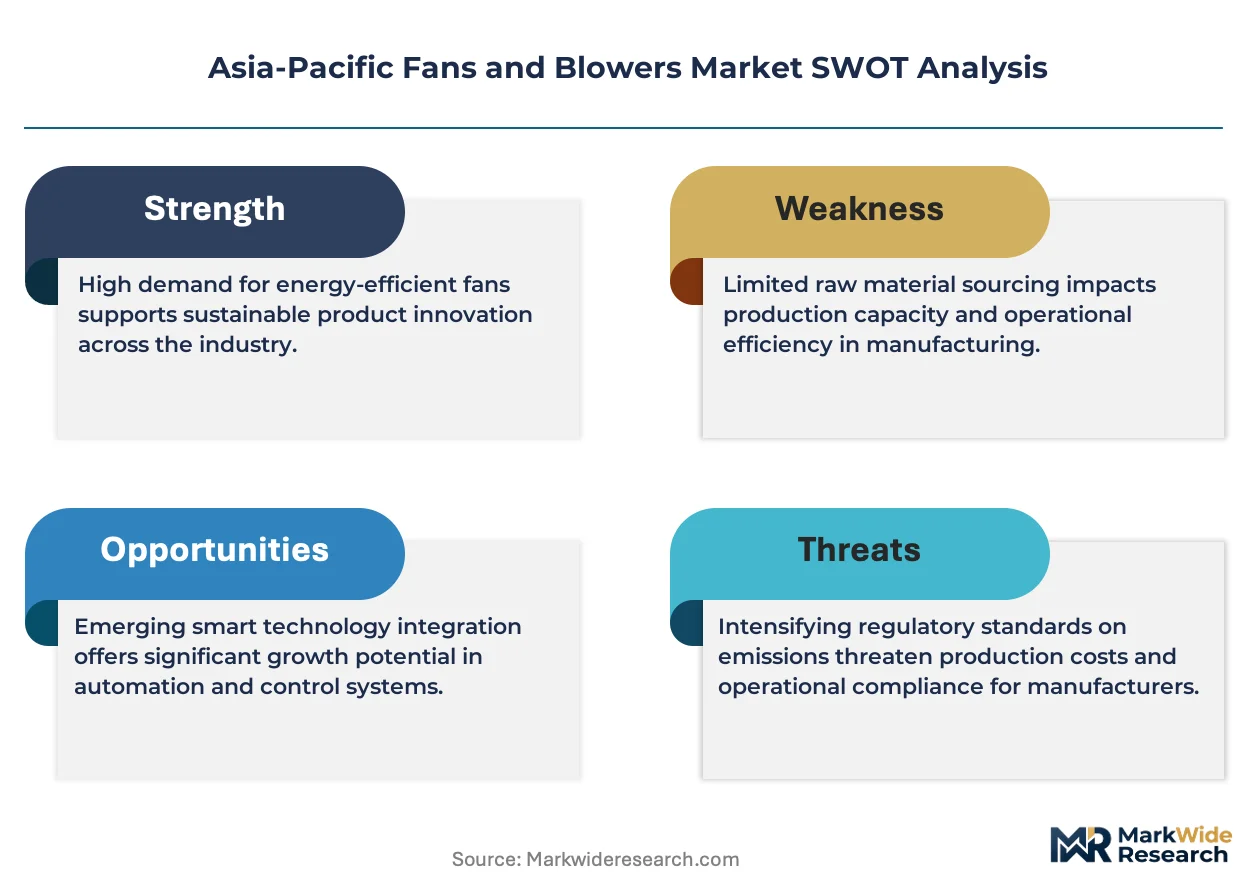
Fans and blowers are electromechanical devices that generate airflow through rotating impellers or blades, with centrifugal designs producing pressures up to several thousand pascals via radial blade acceleration and axial configurations moving large air volumes at lower static pressures for ventilation and cooling. Their primary purpose spans industrial process air handling, building climate control, and combustion air supply across manufacturing and infrastructure. Centrifugal fans command the dominant product position due to their pressure-generation superiority in chemical processing and wastewater treatment applications, while energy-efficient technology segments are expanding fastest as China's GB standards and India's BIS energy labeling force equipment upgrades. Variable speed technology captures expanding margin pools through reduced power consumption and demand-responsive operation in commercial HVAC systems.
Japan's METI enforces Top Runner efficiency standards that continuously escalate minimum performance thresholds for industrial fans, compelling manufacturers to redesign impeller geometries and motor systems. China's MEE implements GB energy efficiency grades that restrict market access for non-compliant equipment in state-procured infrastructure projects. India's BIS mandates ISI certification for electrical fans and blowers used in hazardous industrial environments, creating compliance barriers for uncertified imports. Stakeholders must monitor regulatory divergence across these three jurisdictions to determine whether regional product platforms or country-specific designs yield superior returns.
Market Dynamics
GB energy efficiency grades from China's MEE and METI's Top Runner program are compressing replacement cycles across industrial HVAC installations, forcing simultaneous upgrades to motor systems and impeller geometries.
Growth Catalysts
- Data center expansion:Semiconductor fabrication facilities in Taiwan and South Korea require cleanroom-grade ventilation systems with precise pressure control and contamination filtration.
- GB standards compliance:China's state-procured infrastructure projects now restrict market access for fans below Grade 2 efficiency, compelling equipment upgrades across wastewater treatment plants.
- Pharmaceutical corridor growth:Gujarat through Maharashtra hosts rapid capacity additions where chemical processing demands centrifugal blowers with corrosion-resistant alloys.
Market Restraints
- Rare earth magnet dependency:High-efficiency permanent magnet motors rely on neodymium supply concentrated in Chinese processing facilities, exposing cost volatility.
- ISI certification barriers:India's BIS mandates create 12-18 month approval timelines for electrical fans in hazardous environments, blocking uncertified import flows.
- Steel input cost swings:Heavy-duty centrifugal fan housings absorb nickel and chromium price volatility from Australian and Indonesian ore markets.
Strategic Opportunities
- Western India industrialization:Maharashtra's chemical clusters and Gujarat's pharmaceutical parks remain undersupplied with localized aftermarket service networks.
- Variable speed convergence:Integration of IoT-enabled condition monitoring with VFD motor controls enables predictive maintenance contracts in commercial HVAC.
- Dual carbon alignment:China's 2060 carbon neutrality targets channel subsidies toward magnetic bearing turbo blowers replacing traditional multi-stage centrifugal units.
Industry Challenges
- Aerodynamic engineering scarcity:Computational fluid dynamics expertise for impeller optimization concentrates in Japanese and German engineering centers, constraining local design capabilities.
- Legacy system integration:Retrofitting variable speed drives into fixed-speed installations across Southeast Asian textile mills demands custom control architecture.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Fans and Blowers Market |
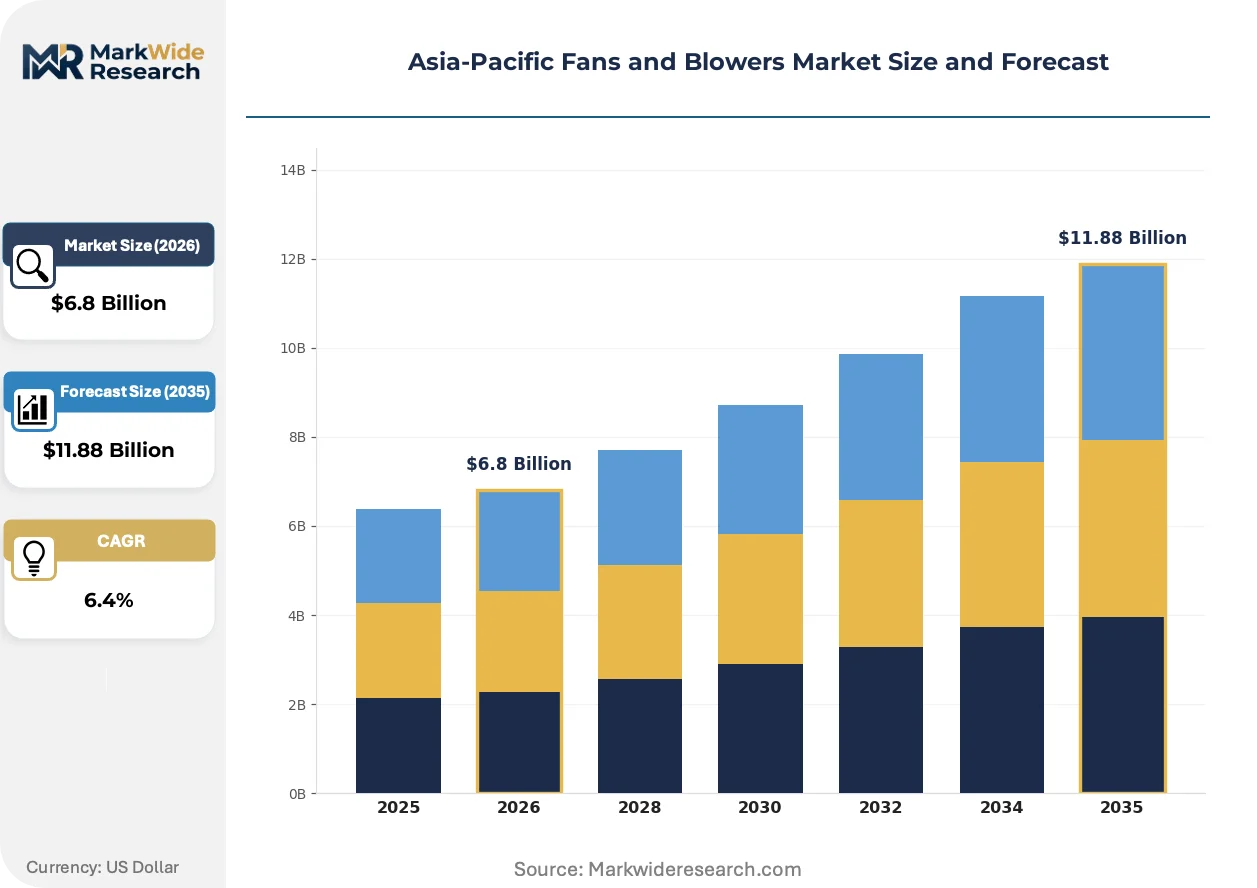
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $11.88 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Centrifugal Fans, Axial Fans, Blowers, Exhaust Fans End User: Commercial, Industrial, Residential, Agricultural Application: HVAC, Automotive, Chemical Processing, Wastewater Treatment Technology: Direct Drive, Belt Drive, Energy Efficient, Variable Speed |
| Companies Covered | DongKun Industrial Co. Ltd, Greenheck Fan Corp, Howden Group Ltd, Continental Blower LLC, Trane Technologies plc, Hangzhou Airflow Electric Appliances Co., Ltd, Xinxiang SIMO Blower Co., Ltd, Ebm-papst Group, FläktGroup, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Fans and Blowers Market Trends and Innovations
Magnetic bearing turbo blower technology is collapsing the traditional multi-stage centrifugal architecture, while regulatory efficiency mandates accelerate motor system redesigns. Procurement patterns are fragmenting as end-users unbundle equipment purchase from service contracts.
Direct-drive permanent magnet motors are eliminating gearbox maintenance and belt-drive losses in high-pressure applications. Data centers in Singapore and Sydney are specifying these units for continuous-duty cooling towers. The technology is collapsing the distinction between premium and mid-tier product categories by delivering variable-speed capability at standardized price points.
METI's Top Runner program escalates minimum efficiency thresholds every three years for industrial fans above 0.75kW. Manufacturers must redesign impeller blade angles and motor slot configurations to maintain market access. Heavy-duty applications in Japanese steel and cement plants face compressed product lifecycles as compliance thresholds advance.
Aftermarket service unbundling is accelerating as end-users separate equipment procurement from maintenance contracts. Independent service providers in Australia and Thailand are capturing refurbishment work previously retained by original manufacturers. Pharmaceutical processors in India's western corridor now source spare impellers and bearing assemblies through regional distributors rather than factory-direct channels.
Asia-Pacific Fans and Blowers Market Segmentation
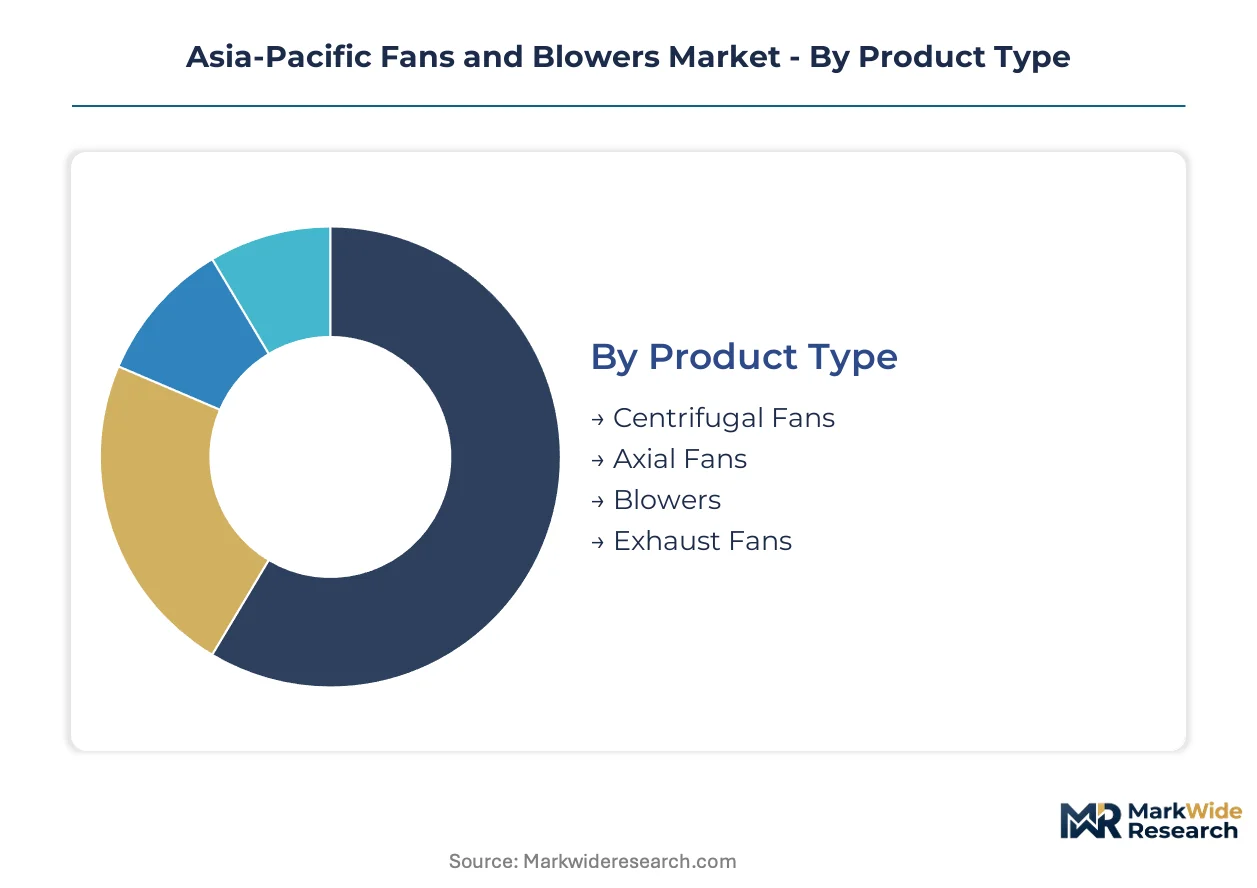
Segmentation in the Asia-Pacific fans and blowers market reveals how procurement specifications diverge across regulatory jurisdictions and end-use intensity. Equipment selection in this region follows efficiency mandates from China's MEE, Japan's METI, and India's BIS rather than pure cost optimization.
Product Type:
Centrifugal designs dominate pressure-intensive applications while axial configurations serve high-volume ventilation needs across the region's industrial corridors.
- Centrifugal Fans:Radial blade acceleration generates static pressures up to several thousand pascals through volute housing geometry. Chemical processing facilities in Gujarat and Maharashtra specify corrosion-resistant alloy impellers for aggressive gas streams, with India's western pharmaceutical corridor driving specification upgrades.
- Axial Fans:Propeller-style blade arrays move large air volumes at minimal static pressure for ventilation and cooling towers. Data centers in Singapore and Sydney deploy these units for continuous-duty thermal management, with direct-drive permanent magnet motors eliminating gearbox maintenance.
- Blowers:Positive-displacement and turbo designs deliver precise pressure control for aeration and pneumatic conveying.
- Exhaust Fans:Fume extraction systems for hazardous environments require spark-resistant construction and explosion-proof motors.
The dominant share belongs to Centrifugal Fans, while Energy Efficient technology variants are gaining share fastest across procurement specifications.
End User:
Customer type determines service contract structures and replacement cycle timing across the region's fragmented aftermarket.
- Industrial:Steel plants, cement kilns, and chemical processors operate heavy-duty centrifugal units under continuous load. Australia's mining sector and Southeast Asian textile mills anchor refurbishment demand for Howden Group's service programs.
- Commercial:Office buildings, retail complexes, and hospitality infrastructure specify packaged HVAC systems with integrated fan arrays. Variable speed drives enable demand-responsive operation in Japan's commercial districts under METI efficiency mandates.
- Residential:Ceiling fans and ventilation units face price pressure from mass-market imports.
- Agricultural:Grain drying and livestock ventilation applications favor robust axial designs with minimal maintenance requirements.
Industrial end users command the largest equipment spend, though Commercial installations are expanding most quickly through green building certifications.
Application:
Process intensity and contamination sensitivity dictate material selection and precision engineering requirements.
- HVAC:Climate control systems integrate fans with filtration, heating, and cooling subsystems. Taiwan's semiconductor fabs and South Korea's memory fabrication facilities require cleanroom-grade ventilation with HEPA filtration and precise pressure cascades.
- Chemical Processing:Aggressive gas streams demand hastelloy or titanium impellers with specialized coatings. Maharashtra's expanding chemical clusters source corrosion-resistant blowers for reactor ventilation and solvent recovery.
- Wastewater Treatment:Aeration blowers account for 40-60% of plant energy consumption, driving magnetic bearing turbo adoption.
- Automotive:Paint booth ventilation and engine cooling systems require balanced airflow distribution.
HVAC applications absorb the dominant equipment volume, while Chemical Processing specifications are climbing the fastest on capacity expansion in India's western corridor.
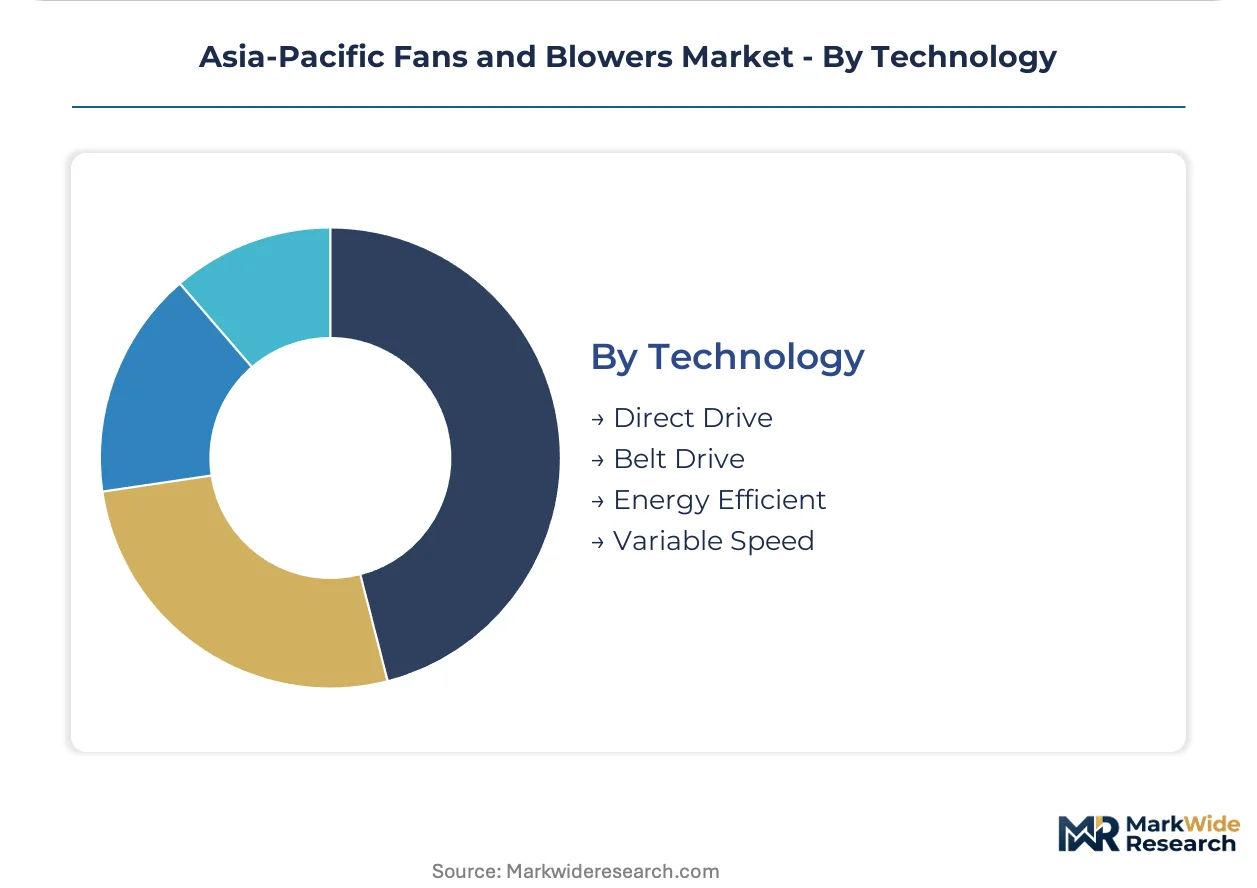
Technology:
Motor-drive architecture determines efficiency compliance and lifecycle cost structure under regional regulatory programs.
- Energy Efficient:Premium efficiency motors and optimized impeller geometries meet China's GB Grade 2 thresholds and Japan's Top Runner standards. State-procured infrastructure projects in China now exclude non-compliant equipment, forcing redesigns across supplier portfolios.
- Variable Speed:VFD integration enables demand-responsive operation and predictive maintenance through IoT condition monitoring. Commercial HVAC systems in Australia's urban centers specify these controls for peak demand management.
- Direct Drive:Permanent magnet motors eliminate belt losses and gearbox maintenance in high-pressure applications.
- Belt Drive:Traditional pulley systems persist in cost-sensitive retrofit installations.
Energy Efficient technology holds the dominant procurement position, while Variable Speed configurations are expanding most rapidly through smart building integration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Component manufacturing clusters in eastern China and precision engineering centers in Japan concentrate supply-side capacity for high-efficiency impeller systems. Procurement specifications diverge sharply across national regulatory regimes, compressing equipment replacement timelines in some markets while extending them in others.
China
State-procured wastewater treatment plants and data center cooling infrastructure drive equipment procurement volumes along the Yangtze River Delta. The Ministry of Ecology and Environment enforces GB energy efficiency grades that exclude non-compliant fans from government tenders, forcing domestic and foreign suppliers to redesign motor-impeller packages. Zhejiang and Jiangsu provinces host expanding manufacturing capacity for magnetic bearing turbo blowers serving municipal aeration systems.
Japan
Semiconductor fabrication facilities in Kyushu and memory chip plants in the Tokyo metropolitan area require cleanroom-grade ventilation with HEPA filtration and precise pressure cascades. METI's Top Runner program escalates minimum efficiency thresholds every three years for industrial fans above 0.75kW, compelling manufacturers to redesign blade geometries and motor slot configurations. Heavy-duty steel and cement applications in Chubu face compressed product lifecycles as compliance thresholds advance.
India
Pharmaceutical processing capacity expansion across Gujarat and Maharashtra generates demand for corrosion-resistant centrifugal blowers with hastelloy impellers. The Bureau of Indian Standards mandates ISI certification for electrical fans in hazardous environments, creating 12-18 month approval timelines that block uncertified import flows. The western industrial corridor from Ahmedabad through Mumbai remains undersupplied with localized aftermarket service networks for high-pressure aeration equipment.
South Korea
Memory fabrication facilities in Gyeonggi Province and semiconductor foundries require cleanroom ventilation systems with contamination filtration and precise pressure control. National efficiency regulations align with corporate carbon neutrality commitments from major electronics manufacturers, accelerating equipment upgrade cycles. Busan-Ulsan industrial complexes anchor demand for heavy-duty centrifugal units in petrochemical processing applications.
Australia
Mining sector ventilation requirements and commercial HVAC retrofits in Sydney and Melbourne drive aftermarket refurbishment demand for heavy-duty centrifugal fans. Independent service providers capture maintenance contracts previously retained by original manufacturers, fragmenting revenue pools across the equipment lifecycle. Queensland's coal and iron ore operations specify robust axial designs for continuous-duty mine ventilation systems.
Asia-Pacific Fans and Blowers Market Competitive Landscape
Integrated system suppliers and component specialists split the market along the equipment-service boundary. The vendor base concentrates around three strategic archetypes: direct-drive motor integrators capturing recurring maintenance contracts, heavy-duty refurbishment specialists anchoring industrial aftermarket programs, and mass-market fabricators serving cost-sensitive retrofit installations. Competitive dynamics center on geographic expansion into underserviced industrial corridors and technology licensing for magnetic bearing turbo blower architectures.
Among Asia-Pacific-based fabricators, Hangzhou Airflow Electric Appliances Co., Ltd. and Xinxiang SIMO Blower Co., Ltd. occupy positions within the mid-tier equipment segment, while Ebm-papst Group represents the direct-drive integration archetype. Howden Group Ltd anchors the heavy-duty refurbishment specialist position across Australian and Southeast Asian industrial markets. These companies exemplify the strategic divergence between component-level motor integration and full-system aftermarket service capture.
| Leading Market Players |
|---|
| DongKun Industrial Co. Ltd |
| Greenheck Fan Corp |
| Howden Group Ltd |
| Continental Blower LLC |
| Trane Technologies plc |
| Hangzhou Airflow Electric Appliances Co., Ltd |
| Xinxiang SIMO Blower Co., Ltd |
| Ebm-papst Group |
| FläktGroup |
| Others |
Pricing and Supply Chain Analysis
Neodymium processing concentration in Chinese facilities anchors cost structures for high-efficiency permanent magnet motors, compressing margins for manufacturers lacking captive rare earth supply or long-term offtake agreements with Jiangxi and Inner Mongolia processors.
Pricing Analysis
Aftermarket service contracts and spare parts provisioning drive lifetime value capture across the equipment lifecycle. Three-tier pricing structure across premium, standard, and economy levels segments procurement specifications, with GB Grade 2 certification and METI Top Runner compliance commanding 15-25% premiums over uncertified alternatives. Cost compression in mid-tier centrifugal units is intensifying because Hangzhou and Xinxiang fabricators expand capacity for wastewater treatment tenders. Municipal procurement officers in China's Yangtze River Delta exhibit highest price sensitivity, while Japanese semiconductor fabs prioritize performance guarantees over unit economics.
Supply Chain Analysis
Zhejiang and Jiangsu provinces host the dominant contract manufacturing clusters for magnetic bearing turbo blower assemblies, with secondary concentration in Tokyo-Osaka precision engineering corridors. Rare earth magnet supply draws from Chinese separation facilities, while hastelloy and titanium impeller forgings source from Japanese specialty metals processors. Single-source vulnerability in neodymium oxide refining exposes cost volatility. Distribution runs through regional equipment distributors in India's western corridor and direct OEM channels for cleanroom-grade specifications in Taiwan and South Korea.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is entering a cyclical recovery phase as industrial HVAC replacement cycles compress under China's GB efficiency mandates and Japan's escalating Top Runner thresholds.
For Market Incumbents: Build aftermarket service moats through predictive maintenance platform deployment and localized spare parts warehousing in Maharashtra and Gujarat. Magnetic bearing turbo blowers threaten traditional multi-stage centrifugal architectures; defend through backward integration into permanent magnet motor production and ISI certification pre-positioning for Indian hazardous environment tenders. For New Entrants and Emerging Players: Australia's mining sector aftermarket remains fragmented between independent service providers and OEM-retained contracts, offering white-space entry through mobile refurbishment units for heavy-duty centrifugal fans. India's western pharmaceutical corridor lacks localized aeration blower service networks; penetrate through corrosion-resistant impeller specialization and BIS certification fast-track partnerships with Gujarat industrial parks. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across magnetic bearing turbo blower manufacturing as precision engineering capabilities concentrate in Japanese and German centers. Long-term viability favors vertically integrated specialists with captive motor technology and regional service density. Monitor GB standard revision announcements and METI threshold escalations as inflection indicators for replacement cycle acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Magnetic Bearing Turbo Blower Manufacturing Scale-Up | Collapses multi-stage centrifugal architecture in municipal wastewater aeration across China's Yangtze River Delta. |
| Backward Integration into Permanent Magnet Motors | Eliminates rare earth magnet cost volatility exposure for high-pressure industrial fan producers. |
| ISI Certification Fast-Track Investment | Accelerates market access for hazardous environment equipment in India's western pharmaceutical corridor. |
| Predictive Maintenance Platform Deployment | Captures recurring revenue from data center cooling tower installations in Singapore and Sydney. |
| Regional Service Network Expansion | Addresses undersupply of localized aftermarket support in Maharashtra's chemical processing clusters. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with plant engineers, maintenance directors at steel and cement facilities, OEM procurement teams, and aftermarket service heads. Secondary validation incorporated customs and trade flow data, SEC 10-K filings from listed equipment manufacturers, MEE and METI regulatory documentation, and BIS certification records. Bottom-up equipment shipment analysis triangulated against top-down industrial capital expenditure tracking.
Calibration against historical replacement cycle patterns and regulatory compliance deadlines shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, end-user intensity, application process requirements, and technology architecture. CAGRs were derived from installed base aging profiles and efficiency mandate phase-in schedules, with magnetic bearing adoption curves and rare earth price volatility incorporated as scenario inputs.
Practitioners should monitor GB standard revision announcements, METI Top Runner threshold escalations, and neodymium oxide price movements for early signals of forecast deviation. Quarterly review of BIS certification backlog durations and municipal tender award patterns is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Equipment
Screw Air End Market
Industrial Equipment
Laser Drilling Market
Industrial Equipment
Global Servo Motor Market
Industrial Equipment
Microwave Equipment Market
Industrial Equipment
Asia-Pacific Industrial Centrifuge Market
Industrial Equipment
Soldering Iron Market
Industrial Equipment
Global Abrasive Waterjet Cutting Machine Market
Industrial Equipment
Snowrator Market
Industrial Equipment
Photography Panoramic Tripod Heads Market
Industrial Equipment
Camera Tripods Market
Industrial Equipment
Vacuum Concentrators Market
Industrial Equipment
Microbubble Cleaning Device Market
Industrial Equipment
Digital Tube Roller Market
Industrial Equipment
Laser Cleaning Market
Industrial Equipment
Industrial Magnetrons Market
Industrial Equipment
Roller Bearings Market