
 Medical Goggle Market | 2026-2036
Medical Goggle Market Size, Share, and Industry Trends Forecast 2026-2036
Medical Goggle Market Analysis
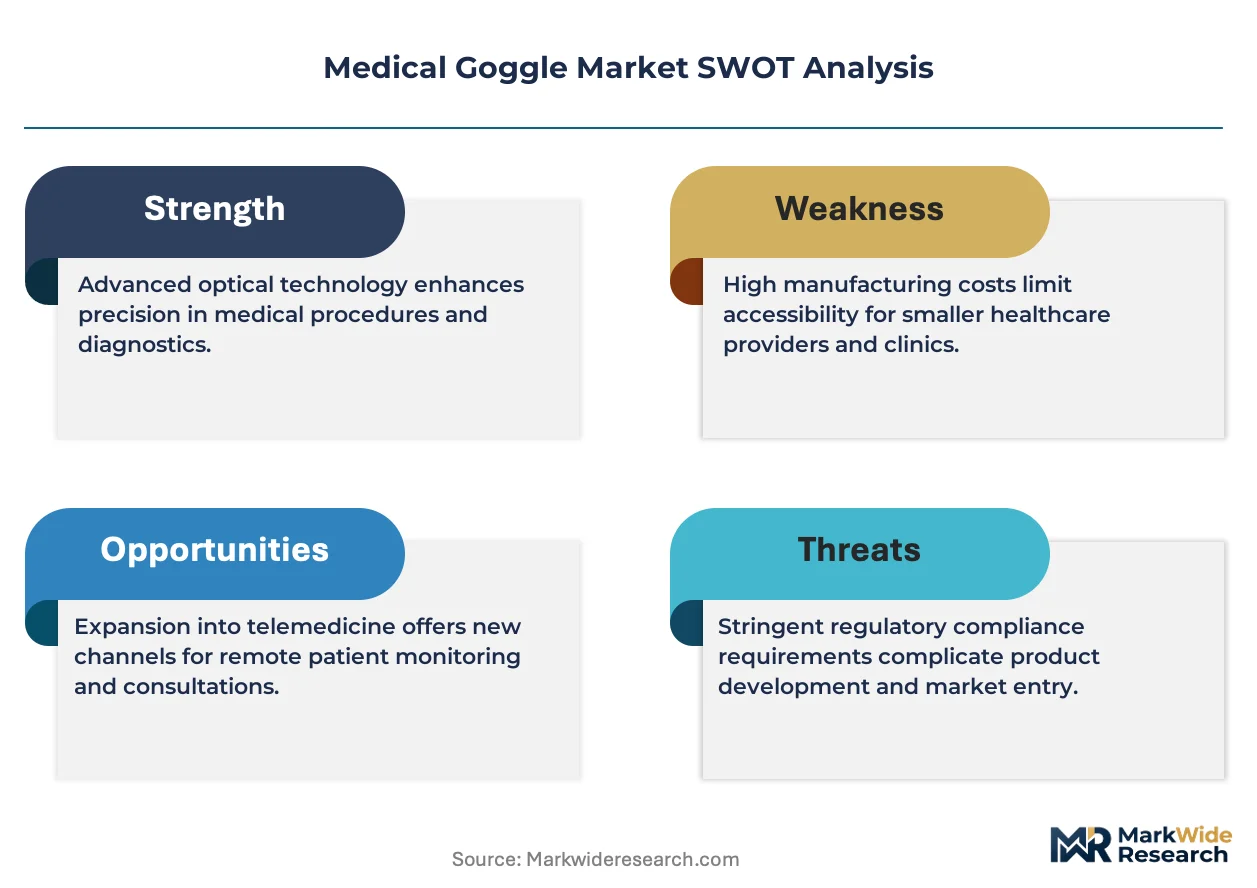
REACH compliance is hardening the cost-of-entry calculus for polycarbonate and PVC suppliers serving European healthcare channels. 3M Company leverages its respiratory and eye protection portfolio to sustain dual-certification advantages across surgical and laboratory environments. Honeywell International Inc. anchors its position through ANSI Z87.1-plus-chemical-splash configurations that dominate North American hospital procurement. Mölnlycke Health Care AB differentiates via sterile single-use goggle systems tailored to Nordic and British operating theater protocols.
Medical goggles are tight-sealing eyewear devices engineered from polycarbonate, glass, or polymer composites with anti-fog coatings and indirect ventilation systems, designed to shield ocular tissue from biological splashes, chemical exposure, and impact hazards in clinical and laboratory settings. Safety goggles and surgical goggles together command the dominant volume share, with wraparound configurations representing the fastest-growing product type as all-angle splash protection becomes standard in interventional procedures. Polycarbonate lenses capture the largest material share due to their impact resistance and lightweight properties, while glass retains niche preference in laser surgery suites where optical clarity at specific wavelengths remains critical.
FDA 510(k) clearance requirements and OSHA Bloodborne Pathogens standards govern product design and market access in the United States, while the EU Medical Device Regulation and CE marking obligations reshape conformity assessment burdens for manufacturers exporting into European Economic Area countries. BIS certification under Indian standards and NMPA registration in China add further layer complexity for brands pursuing volume in Asia's expanding hospital networks. Stakeholders must monitor harmonization gaps between regional sterilization validation protocols and emerging chemical resistance testing methodologies as procurement specifications tighten.
Market Dynamics
Hospital procurement departments are consolidating supplier relationships around dual-certified eyewear portfolios that satisfy both OSHA Bloodborne Pathogens standards and ANSI Z87.1 impact requirements, compressing vendor lists and elevating compliance documentation to a primary selection criterion.
Growth Catalysts
- Surgical Volume Expansion:Rising cataract and refractive procedure counts in Germany, Japan, and the United States are amplifying demand for sterile single-use goggle systems in operating theaters.
- REACH Compliance Hardening:ECHA's tightening chemical restrictions on polycarbonate and PVC formulations are accelerating supplier consolidation toward certified European manufacturers with validated sterilization protocols.
- Laboratory Safety Mandates:Research institutions across the United Kingdom and France are mandating indirect-ventilation goggle designs for BSL-2 and BSL-3 facilities, creating pull-through demand for wraparound configurations.
Market Restraints
- Raw Material Concentration:Optical-grade polycarbonate resin production concentrates among three Asian petrochemical suppliers, exposing European and North American goggle manufacturers to feedstock volatility and allocation risk.
- Regulatory Friction:Divergent sterilization validation requirements between FDA 510(k) pathways and EU MDR conformity assessment create redundant testing burdens that extend product launch timelines by 8-14 months.
- Substitution Pressure:Face shield systems with integrated eye protection are capturing preference in low-splash dental and dermatology settings, compressing addressable volume for standalone goggle formats.
Strategic Opportunities
- Indian Hospital Network Expansion:BIS certification requirements under IS 5983 are creating first-mover advantages for suppliers establishing local sterilization partnerships ahead of public sector tender waves.
- Laser Surgery Optical Clarity:Wavelength-specific glass lens configurations for excimer and femtosecond laser suites represent an underserved premium segment with pricing power intact.
- Integrated PPE Platforms:Convergence of eye protection with respiratory and dermal coverage is enabling bundled procurement contracts that lock out standalone competitors.
Industry Challenges
- Anti-Fog Coating Durability:Hydrophilic surface treatments degrade through repeated autoclave cycles, forcing manufacturers to balance coating longevity against optical clarity specifications.
- Multi-Jurisdiction Certification:Simultaneous pursuit of FDA 510(k), CE marking under MDR, and NMPA registration requires dedicated regulatory affairs capacity that strains mid-tier manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Medical Goggle Market |
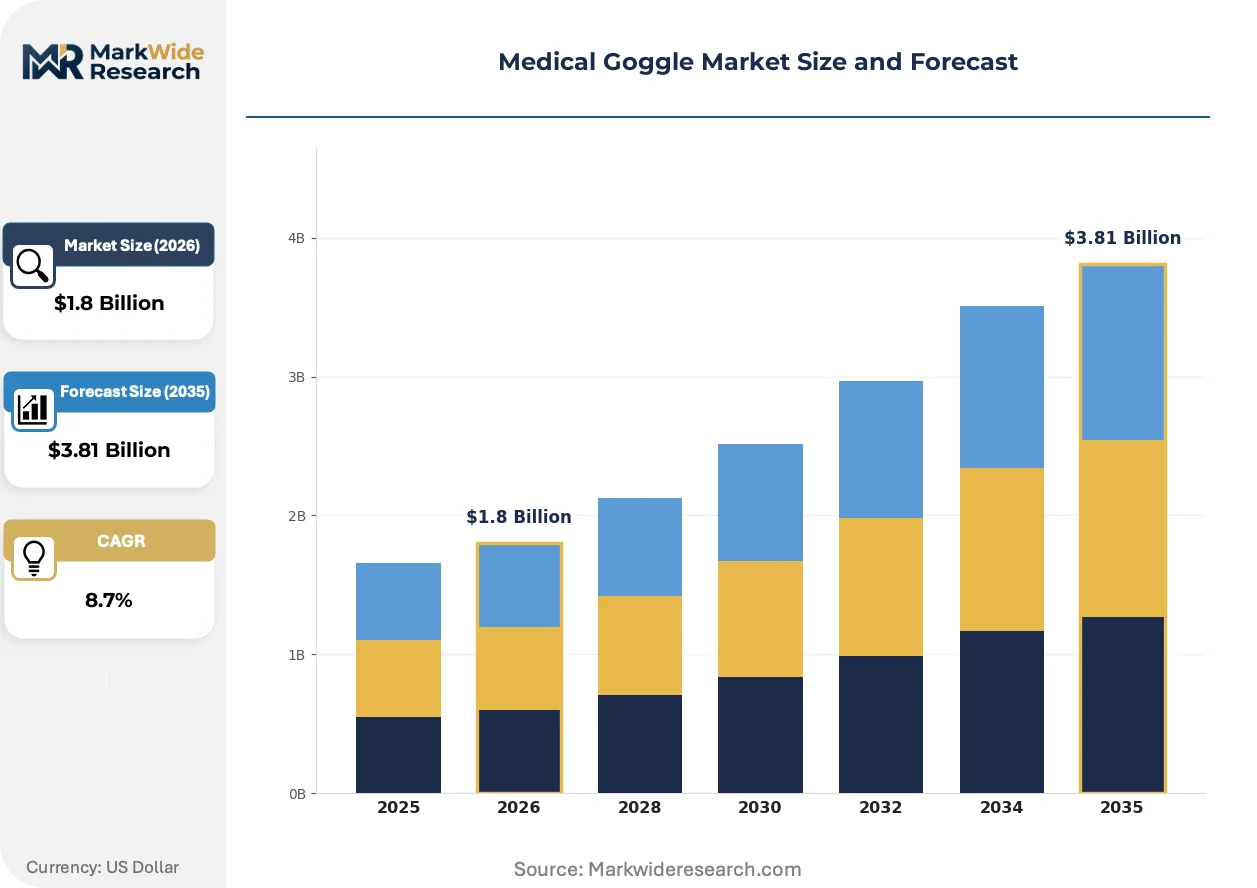
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Prescription Goggles, Safety Goggles, Wraparound Goggles, Surgical Goggles End User: Hospitals, Clinics, Research Laboratories, Optical Stores Material: Polycarbonate, Glass, PVC, Polypropylene Application: Eye Protection, Surgical Procedures, Laboratory Work, Patient Care |
| Companies Covered | Honeywell International Inc., 3M Company, Mölnlycke Health Care AB, Xiamen Jiayu Optical Co., Ltd, TIDI Products, G.F. Health Products, Inc., UNIVET S.R.L., Narang Medical Ltd., U.S.A. Medical and Surgical Supplies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Medical Goggle Market Emerging Trajectories
Active coating technologies and ventilation architectures are displacing passive designs as the baseline specification in acute care settings, with procurement committees now weighting fog-resistance duration and bacterial filtration efficiency above unit cost.
Photochromic polycarbonate formulations that darken under surgical lamp intensity are electrifying demand among ophthalmology suites in the United States and Germany. Leading academic medical centers in Boston and Munich are specifying these lenses for combined microsurgical environments where laser and conventional illumination alternate. The technology is compressing the addressable market for fixed-tint alternatives by establishing dynamic light adaptation as a standard-of-care expectation.
EU MDR's 2021 implementation has forced manufacturers to rebuild technical documentation around clinical evidence requirements for Class I reusable devices. German notified bodies are demanding biocompatibility testing beyond previous MEDDEV guidelines, while French regulators are scrutinizing cleaning validation data more aggressively. Suppliers with legacy product portfolios are responding by accelerating transitions to single-use formats that bypass the most burdensome conformity assessment pathways.
Hospital procurement committees are consolidating eye protection purchasing through integrated distributor agreements that bundle goggles with gloves, gowns, and masks. This model is displacing direct manufacturer relationships in the United States, where Premier and Vizient contracting vehicles now capture over sixty percent of acute care volume. The shift is most visible in multi-hospital systems across Texas and Florida, where standardization committees are mandating uniform PPE platforms across all affiliated facilities.
Medical Goggle Market Segmentation
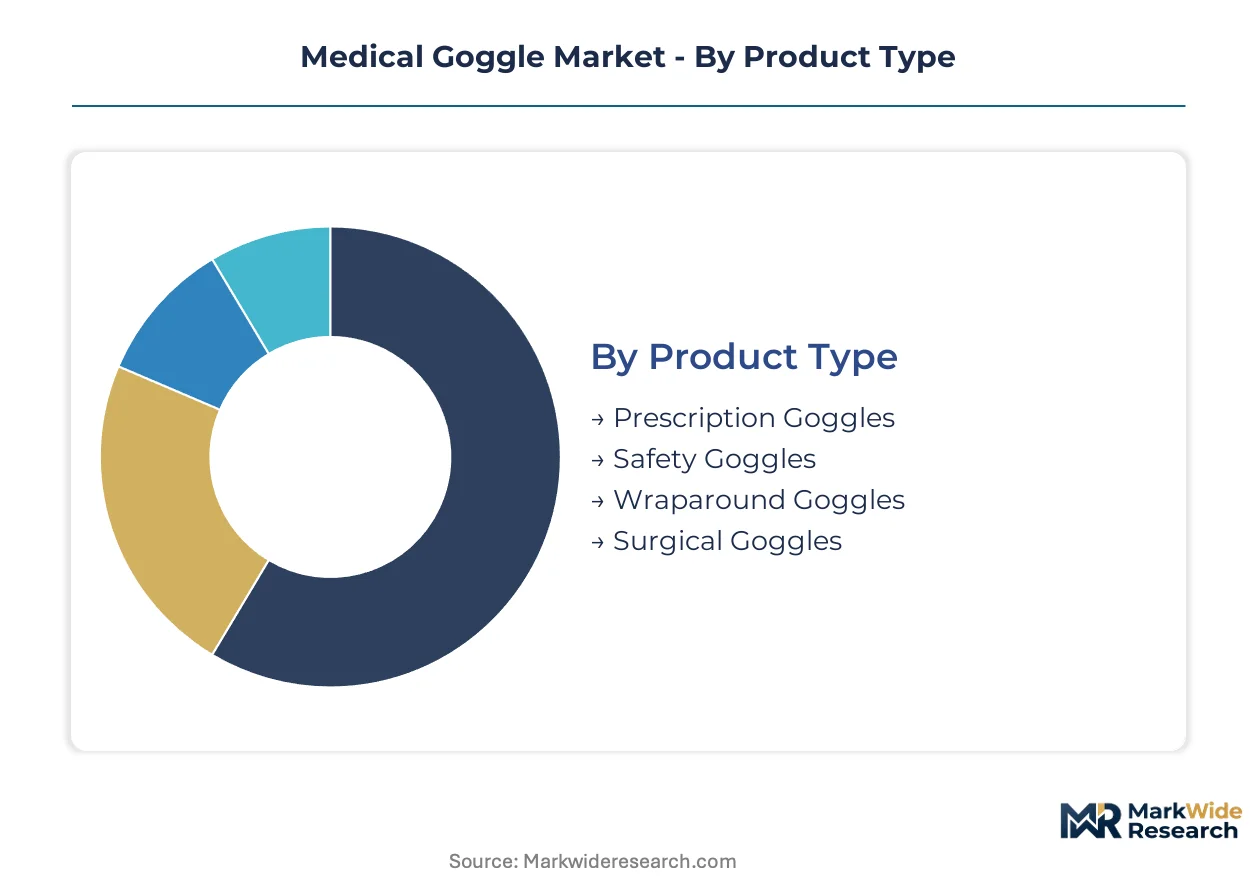
Medical goggle procurement committees segment demand by certification burden, material performance, and sterilization protocol compatibility. Understanding these divisions exposes where FDA 510(k), CE marking under EU MDR, and ANSI Z87.1 compliance costs concentrate.
Product Type:
FDA 510(k) clearance timelines vary sharply across this category, with surgical formats demanding clinical evidence dossiers that wraparound configurations escape.
- Safety Goggles:ANSI Z87.1 impact-rated designs with indirect ventilation and anti-fog coatings. Hospital procurement in Texas and Florida concentrates here as multi-hospital systems standardize PPE platforms across emergency departments and procedural suites.
- Surgical Goggles:Sterile single-use systems engineered for operating theater protocols. Nordic and British NHS trusts drive specification intensity, with Mölnlycke Health Care AB capturing volume through disposable formats that bypass EU MDR's heaviest conformity burdens.
- Wraparound Goggles:All-angle splash protection configurations gaining traction in interventional cardiology and endoscopy suites.
- Prescription Goggles:Custom-lens integrations for healthcare workers requiring vision correction in clinical environments.
Safety Goggles sit at the top of the volume ranking, with Wraparound Goggles climbing the fastest.
End User:
Cost tier stratification separates acute care procurement—where bundled distributor contracts dominate—from research channels where specification precision commands premium positioning.
- Hospitals:Premier and Vizient contracting vehicles capture over sixty percent of acute care volume in the United States. German university hospitals and Japanese tertiary centers anchor demand for dual-certified eyewear satisfying both impact standards and infection control protocols.
- Research Laboratories:BSL-2 and BSL-3 facilities across the United Kingdom and France mandate indirect-ventilation designs with validated chemical splash resistance. ECHA REACH compliance hardens supplier qualification criteria for polycarbonate and PVC formulations.
- Clinics:Outpatient settings where face shield substitution pressures compress standalone goggle demand.
- Optical Stores:Retail channels serving prescription-integrated configurations for healthcare workers.
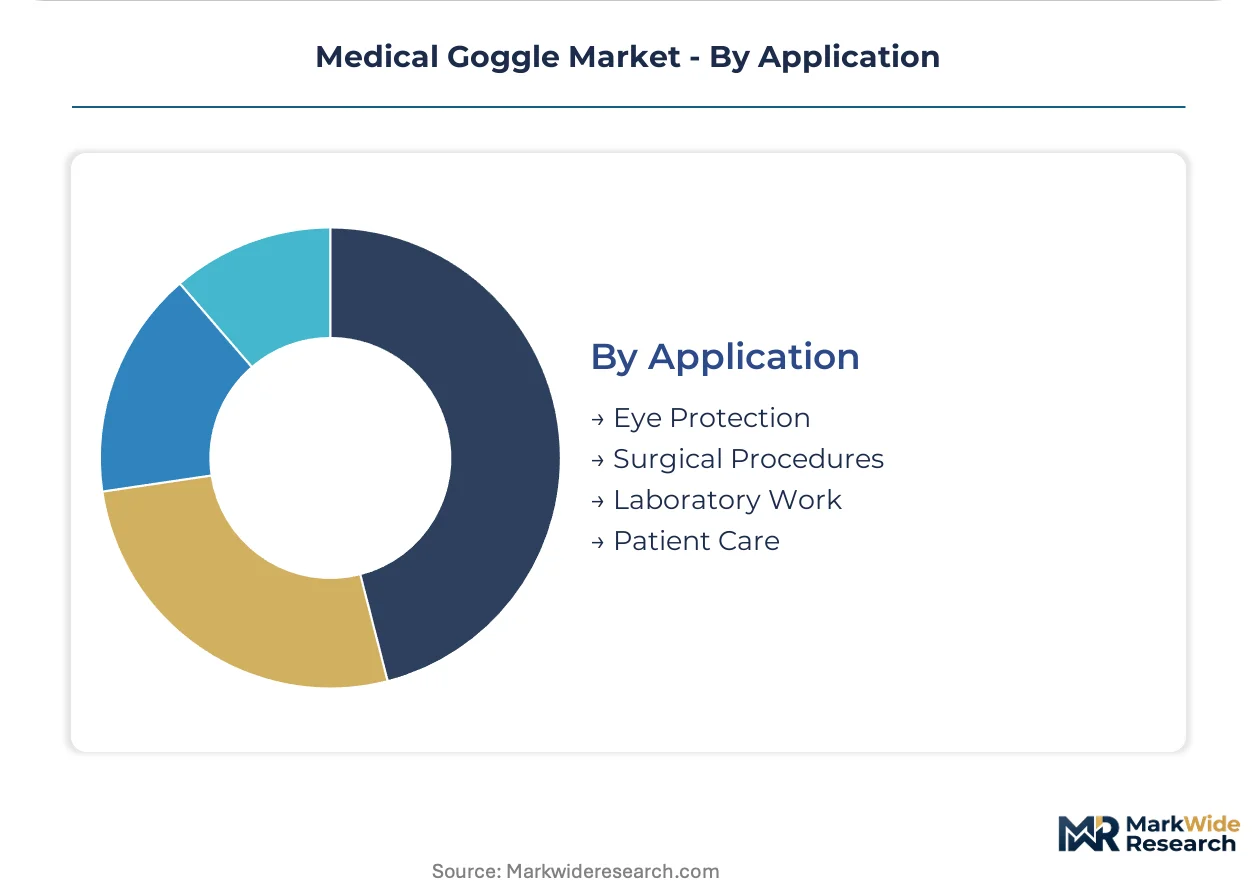
Hospitals command the dominant procurement scale, with Research Laboratories expanding most quickly.
Material:
Supply concentration among Asian petrochemical producers shapes margin pressure and allocation risk across optical-grade resin grades.
- Polycarbonate:Impact-resistant, lightweight thermoplastic capturing the largest material share. Production concentrates among three Asian suppliers, exposing European and North American manufacturers to feedstock volatility. Photochromic formulations for ophthalmology suites in Boston and Munich represent a premium sub-segment.
- Glass:Optical clarity at specific wavelengths retains niche preference in laser surgery suites. Wavelength-specific configurations for excimer and femtosecond procedures command intact pricing power in Germany and the United States.
- PVC:Cost-driven formulations facing REACH restriction pressure in European healthcare channels.
- Polypropylene:Lightweight alternative for single-use disposable systems in high-turnover clinical settings.
Polycarbonate leads material volume, with Glass gaining share fastest in premium surgical applications.
Application:
Maturity gradients separate established eye protection mandates from emerging specification intensity in combined microsurgical environments.
- Eye Protection:Baseline OSHA Bloodborne Pathogens compliance driving standardization across United States hospital networks. ANSI Z87.1 certification serves as the minimum viable specification for vendor list inclusion.
- Surgical Procedures:Sterile single-use systems tailored to Nordic and British operating theater protocols. Cataract and refractive procedure volume expansion in Germany, Japan, and the United States amplifies demand for dynamic light adaptation technologies.
- Laboratory Work:Chemical splash and impact dual-certification requirements dominating academic medical center procurement.
- Patient Care:Lower-specification formats where substitution by face shields compresses addressable volume.
Eye Protection anchors the installed base, with Surgical Procedures showing the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Skilled surgical workforces in Germany, the United States, and Japan concentrate demand for ANSI Z87.1-certified eyewear and sterile single-use systems. Hospital procurement committees in these markets prioritize dual-certification portfolios that satisfy both impact standards and infection control protocols.
United States
Hospital procurement departments in Texas and Florida are consolidating supplier relationships around bundled PPE platforms. OSHA Bloodborne Pathogens standards and FDA 510(k) clearance requirements govern product design and market access. Premier and Vizient contracting vehicles capture over sixty percent of acute care volume across multi-hospital systems.
Germany
German university hospitals and tertiary centers anchor European demand for polycarbonate lens configurations with photochromic properties. EU MDR conformity assessment and ECHA REACH compliance reshape technical documentation burdens for reusable devices. Munich and Berlin academic medical centers specify dynamic light adaptation lenses for combined microsurgical environments.
Japan
Japanese tertiary centers drive specification intensity for sterile single-use goggle systems in cataract and refractive surgery suites. METI industrial safety guidelines and PMDA medical device registration create layered compliance requirements. Tokyo and Osaka hospital clusters prioritize lightweight polycarbonate formats for high-volume ophthalmology procedures.
United Kingdom
NHS trusts across England and Scotland mandate indirect-ventilation goggle designs for BSL-2 and BSL-3 research facilities. UK Health and Safety Executive regulations align with EU MDR transition timelines for conformity assessment. London and Cambridge academic medical centers specify chemical splash-resistant configurations for laboratory safety mandates.
India
Expanding hospital networks in Maharashtra and Karnataka are intensifying BIS certification requirements under IS 5983 standards. CDSCO medical device registration and public sector tender waves create first-mover advantages for suppliers establishing local sterilization partnerships. Delhi-NCR and Mumbai procurement committees prioritize cost-efficient polycarbonate formats for high-turnover clinical settings.
Medical Goggle Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across certification-intensive procurement channels. The vendor base stratifies into three tiers: multinational industrial safety conglomerates with respiratory and eye protection portfolios, regional healthcare specialists with sterile disposable expertise, and optical fabricators with lens technology capabilities. Consolidation pressures favor players with dual-certification advantages spanning surgical and laboratory environments. Strategic moves center on integrated PPE platform bundling and geographic expansion through local sterilization partnerships.
Among diversified industrial safety conglomerates, Honeywell International Inc. and 3M Company exemplify the certification-breadth archetype that dominates North American hospital procurement. Mölnlycke Health Care AB represents the focused healthcare specialist model with sterile single-use positioning. Xiamen Jiayu Optical Co., Ltd. and UNIVET S.R.L. occupy positions within the optical fabrication tier serving prescription-integrated and wavelength-specific applications. TIDI Products, G.F. Health Products, Inc., Narang Medical Ltd., and U.S.A. Medical and Surgical Supplies distribute through regional healthcare supply channels.
| Leading Market Players |
|---|
| Honeywell International Inc. |
| 3M Company |
| Mölnlycke Health Care AB |
| Xiamen Jiayu Optical Co., Ltd |
| TIDI Products |
| G.F. Health Products, Inc. |
| UNIVET S.R.L. |
| Narang Medical Ltd. |
| U.S.A. Medical and Surgical Supplies |
| Others |
Supply Flow & Price Mechanics
Private-equity-rolled-up distributors now control sixty percent of acute care volume through Premier and Vizient contracting vehicles, compressing manufacturer pricing power while consolidating procurement leverage across multi-hospital systems in Texas and Florida. This ownership concentration feeds back into supply chain decisions, as bundled PPE platforms displace standalone goggle relationships and force suppliers to absorb certification costs across broader product portfolios.
Pricing Analysis
Bundled distributor contracts versus direct manufacturer relationships split the pricing architecture in this market. Three-tier pricing structure across premium, standard, and economy levels separates photochromic polycarbonate configurations for ophthalmology suites from basic ANSI Z87.1 safety formats and disposable single-use systems. Cost compression in standard-tier safety goggles is intensifying because hospital procurement committees weight fog-resistance duration above unit cost. Research laboratories exhibit the least price sensitivity, prioritizing ECHA REACH-compliant formulations over economy alternatives.
Supply Chain Analysis
Dual-sourcing requirements from hospital procurement committees mandate multi-supplier qualification for optical-grade polycarbonate resin, yet production gravity centers on South Korea, Japan, and China among three Asian petrochemical suppliers. Feedstock draws from benzene and phosgene derivatives, with anti-fog coating chemistries resting on hydrophilic polymer formulations. Single-source vulnerability in optical-grade resin exposes European and North American manufacturers to allocation risk during feedstock volatility. Distribution runs through integrated healthcare distributors and GPO contracting vehicles that bundle goggles with complementary PPE.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Medical Goggle Market functions as a stable compounder, with infection control protocol tightening across hospital networks providing steady demand visibility regardless of macroeconomic cycles.
For Market Incumbents: Deploy certification breadth as the primary defensive lever. Accelerate FDA 510(k) and EU MDR dual-certification investments to maintain vendor list inclusion as procurement committees consolidate around compliant portfolios. Build backward integration into optical-grade polycarbonate resin through strategic partnerships with Asian petrochemical suppliers, mitigating feedstock allocation risk that threatens margin stability. For New Entrants and Emerging Players: Begin with BIS certification partnerships in Maharashtra and Karnataka ahead of Indian public sector tender waves, where first-mover advantages remain available. Target wavelength-specific glass lens configurations for excimer laser suites in German and United States academic medical centers, an underserved premium segment with intact pricing power. Pursue sterile single-use format positioning that bypasses EU MDR's heaviest conformity burdens for reusable devices. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-tier optical fabricators lacking integrated distributor relationships but possessing lens technology capabilities. Long-term viability over a five-to-ten-year window rests on regulatory compliance infrastructure rather than manufacturing scale alone. Monitor harmonization progress between FDA 510(k) pathways and EU MDR conformity assessment as the signal indicating whether certification burdens will compress launch timelines or extend competitive moats.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Technical Documentation Rebuild | Forced clinical evidence requirements for Class I reusable devices reshape competitive viability across European Economic Area markets. |
| Photochromic Polycarbonate Formulation Launch | Dynamic light adaptation establishes standard-of-care expectations in Boston and Munich ophthalmology suites. |
| Indian Sterilization Partnership Establishment | Local BIS certification capabilities unlock first-mover positioning ahead of public sector procurement waves. |
| Integrated PPE Platform Bundling | Convergence with respiratory and dermal coverage locks out standalone competitors through multi-year distributor contracts. |
| Laser Surgery Wavelength-Specific Lens Development | Optical clarity at excimer and femtosecond specifications commands premium positioning in underserved surgical segments. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with hospital procurement managers, biomedical engineers, GPO contracts managers, and regulatory affairs leads with secondary validation. FDA 510(k) filings, EU MDR notified body documentation, hospital procurement databases, and customs trade records anchored the data foundation. Bottom-up volume builds across product type, material, end user, and application segments were cross-checked against top-down market sizing.
Historical reference periods anchored the forecast window to established surgical volume trends and regulatory implementation timelines. The analytical framework modeled segmentation across product format, certification tier, sterilization protocol, and regional regulatory cluster. CAGRs were derived from procedure volume elasticity, procurement standardization intensity, and compliance cost pass-through assumptions. Anti-fog coating durability cycles and photochromic formulation adoption curves served as industry-specific demand drivers.
Several conditions sit outside the modeled scope, including sudden harmonization breakthroughs between FDA and EU sterilization validation protocols, breakthrough substitution by face shield systems in dental settings, and raw material allocation crises among Asian petrochemical suppliers. Deviation in REACH restriction enforcement intensity would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Sputum Ejection Machine Market
Medical Devices
Smart Wheelchairs Market
Medical Devices
Europe Biopsy Devices Market
Medical Devices
United States Ultrasound Devices Market
Medical Devices
Non-Invasive Pulse Oximeter Market
Medical Devices
Membrane Oxygenators Market
Medical Devices
North America Electrophysiology Market
Medical Devices
PPG Biosensors Market
Medical Devices
Hearing Aid with Lithium-Ion Battery Market
Medical Devices
US Trauma Fixation Devices Market
Medical Devices
UAE Artificial Organs and Bionic Implants Market
Medical Devices
Global Cerebral Somatic Oximeters Market
Medical Devices
Global Insulin Pumps Market
Medical Devices
Spectacle Lens Market
Medical Devices
Epilepsy Treatment Devices Market
Medical Devices
Cardiac Ablation Devices Market