
 Medical Tubing Market | 2026-2036
Medical Tubing Market Size, Share, and Industry Trends Forecast 2026-2036
Medical Tubing Market Intelligence
The premium and commodity tiers in medical tubing is decoupling along biocompatibility certification lines, with platinum-cured silicone commanding price multiples over peroxide-cured alternatives. Saint-Gobain leverages its fluoropolymer expertise to dominate drug-delivery tubing for oncology applications. Freudenberg Medical anchors its position through vertical integration from silicone compounding to cleanroom extrusion. W. L. Gore & Associates differentiates via expanded PTFE membranes in neurovascular catheter shafts.
Medical tubing comprises extruded polymer conduits manufactured to tight tolerances, typically ranging from 0.005 to 0.5 inches in inner diameter, designed to transport fluids, gases, or devices within sterile clinical environments. Silicone tubing leads in implantable segments due to its thermal stability and elastomeric recovery, while polyurethane tubing captures share in percutaneous applications requiring tensile strength and lubricious surfaces. Extrusion remains the dominant manufacturing technology, though co-extrusion is displacing single-layer construction in multi-lumen cardiac catheters where distinct material properties must coexist in one profile.
FDA enforces biocompatibility testing under ISO 10993 for all patient-contact tubing, while the EU MDR imposes stricter post-market surveillance and unique device identification requirements that reshape supplier qualification timelines. The EPA regulates volatile organic compound emissions from solvent-based tubing production, pushing manufacturers toward aqueous or plasma surface treatments. Stakeholders must monitor how FDA guidance on 3D-printed medical devices extends to additively manufactured tubing geometries, as this convergence threatens to redraw competitive boundaries between extrusion specialists and digital manufacturing platforms.
Market Dynamics
Catheterization volume expansion in ambulatory surgery centers is compressing lead-time requirements for multi-lumen extrusions, forcing manufacturers to reconfigure cleanroom scheduling around same-day sterilization validation.
Growth Catalysts
- EU MDR traceability mandates:Device identification rules compel tubing suppliers to implement laser-etched lot codes, creating captive demand for integrated extrusion-marking systems.
- Cardiovascular OEM clustering in Germany:Precision extrusion hubs around Stuttgart and Munich attract catheter developers seeking sub-micron tolerance capabilities.
- Platinum-cured silicone certification:Implantable-grade biocompatibility standards pull procurement toward higher-validation material tiers.
Market Restraints
- Specialty polymer concentration:Fluoropolymer resin supply concentrates among three chemical conglomerates, exposing catheter shaft producers to allocation risk.
- ISO 10993 testing timelines:Cytotoxicity and sensitization protocols extend supplier qualification cycles by 14-18 months.
- Peroxide-cured silicone substitution ceiling:Lower-grade alternatives face exclusion from Class III implantable segments regardless of price advantage.
Strategic Opportunities
- Additive manufacturing convergence:3D-printed lattice structures integrated with extruded lumens enable patient-specific catheter geometries.
- Oncology drug-delivery expansion:Closed-system transfer devices for cytotoxic agents require chemically inert tubing with barrier-layer co-extrusion.
- EPA aqueous treatment adoption:Solvent-free surface activation processes open compliance pathways for US-based extrusion capacity.
Industry Challenges
- Cleanroom extrusion technician scarcity:Polymer science graduates with ISO 14644-1 environment experience command 40% wage premiums.
- Multi-lumen co-extrusion tooling capex:Precision die heads for cardiac catheter profiles require $2-4 million capital commitments per product line.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Medical Tubing Market |
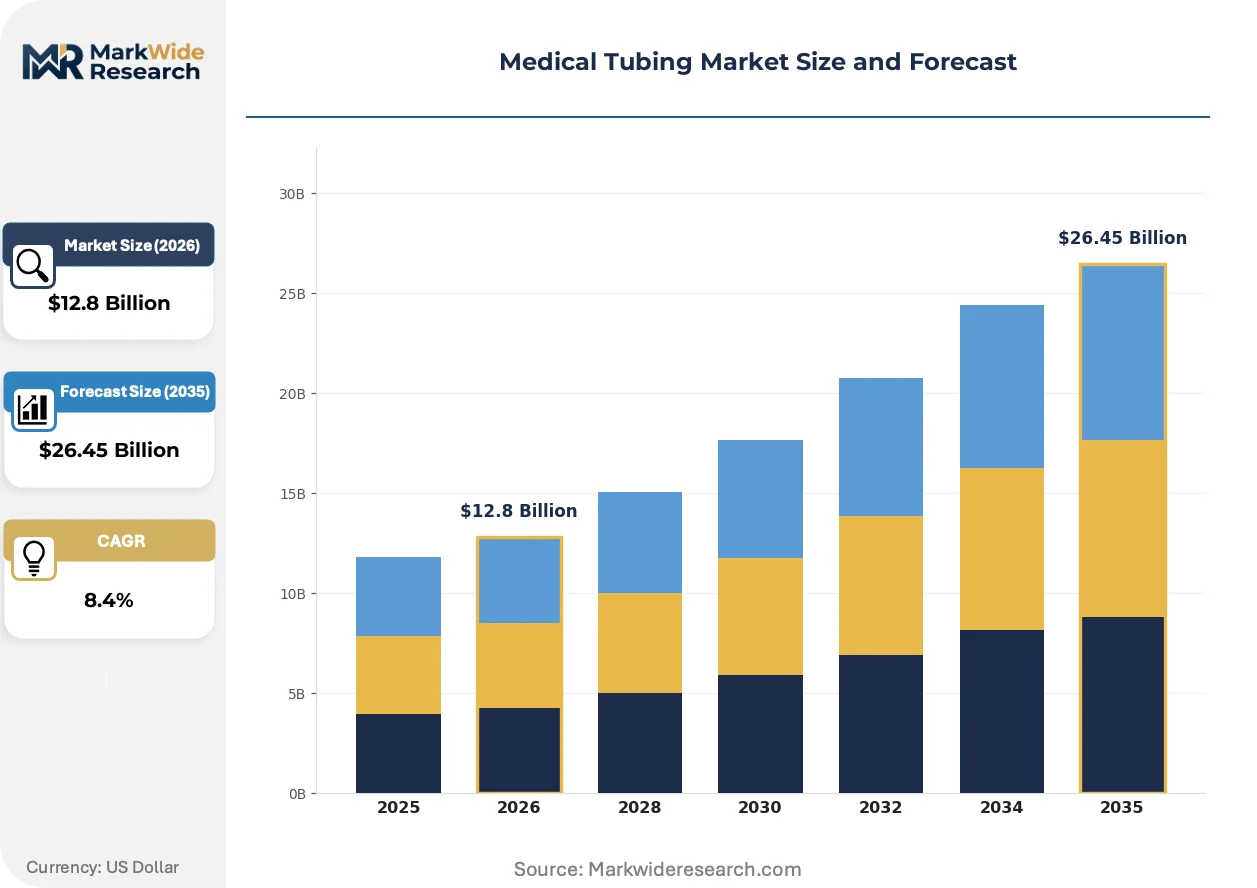
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $26.45 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Silicone Tubing, PVC Tubing, Thermoplastic Elastomers, Polyurethane Tubing Application: Intravenous Therapy, Catheterization, Surgical Drainage, Respiratory Equipment End User: Hospitals, Ambulatory Surgery Centers, Diagnostic Laboratories, Specialty Clinics Technology: Extrusion, Co-extrusion, Braiding, Injection Molding |
| Companies Covered | Saint-Gobain, Freudenberg Medical, W. L. Gore & Associates, Nordson Corporation, The Lubrizol Corporation, TE Connectivity, RAUMEDIC AG, Elkem ASA, Trelleborg AB, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Medical Tubing Market Strategic Shifts & Innovations
Material science and regulatory convergence are compressing product development cycles while fragmenting the supplier base between certified implantable-grade specialists and commodity percutaneous providers.
Multi-layer co-extrusion is absorbing capital investment from single-lumen equipment as cardiac catheter developers demand distinct mechanical properties in one profile. Interventional cardiology OEMs in Germany and Massachusetts specify tri-layer constructions combining lubricious inner surfaces with radiopaque intermediate layers. This capability compression is marginalizing extruders without in-house polymer compounding expertise.
EU MDR post-market surveillance requirements are extending tubing supplier liability into device lifetime traceability. Manufacturers must maintain production records for 15 years post-implant, forcing ERP system upgrades and cloud-based batch record storage. Cardiovascular segments face the steepest compliance cost escalation as notified body audit frequency doubles.
Consignment inventory models are displacing traditional purchase-order relationships in high-volume catheter OEM supply chains. Suppliers maintain finished goods at customer cleanrooms, invoicing only upon sterilization and release. This working capital burden concentrates among mid-tier extruders serving Boston Scientific and Medtronic procurement hubs in Minnesota and Ireland.
Medical Tubing Market Segmentation
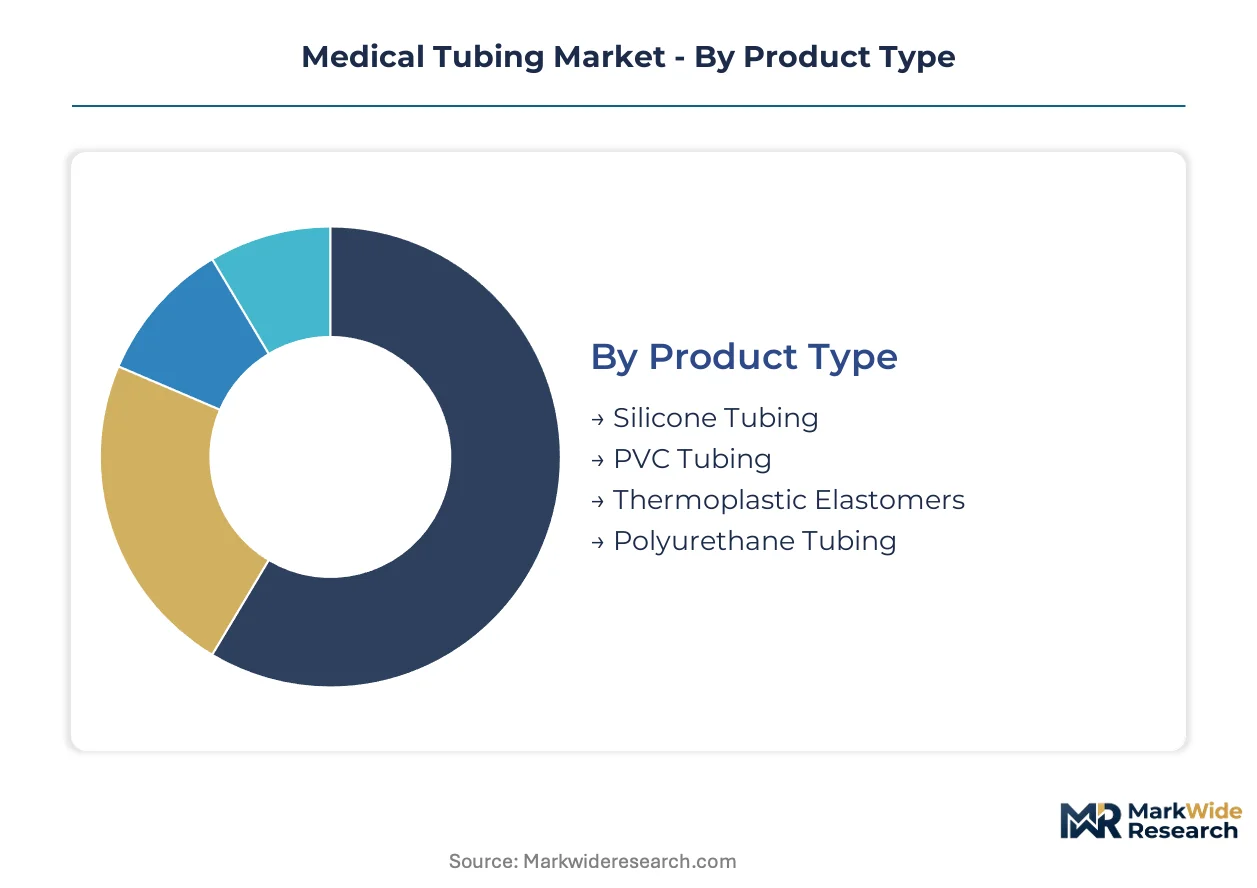
Medical tubing procurement splits across material certification tiers, clinical application risk classes, and manufacturing precision requirements. Each segmentation axis reveals distinct margin structures and supplier qualification barriers that reshape competitive positioning.
Product Type:
Customization intensity spans from implantable-grade platinum-cured formulations to commodity peroxide-cured alternatives, with certification cost differentials driving procurement bifurcation.
- Silicone Tubing:Platinum-cured formulations deliver thermal stability and elastomeric recovery for long-term implantables. Demand concentrates in cardiovascular OEM clusters across Germany and Massachusetts, where FDA and EU MDR biocompatibility mandates pull procurement toward validation-heavy supply tiers.
- Polyurethane Tubing:Segmented aromatic and aliphatic grades offer tensile strength with lubricious surfaces for percutaneous access. Ambulatory surgery centers in Stuttgart and Minneapolis drive volume for multi-lumen cardiac catheter constructions requiring thin-wall integrity.
- PVC Tubing:Plasticized formulations dominate disposable fluid transfer with cost-optimized extrusion economics.
- Thermoplastic Elastomers:Block copolymer structures bridge silicone softness with thermoplastic processability for rapid-cycle disposables.
Most installed capacity flows through silicone tubing. Expansion is steepest in polyurethane formulations.
Application:
Clinical risk stratification separates Class III implantable segments from single-use percutaneous applications, with regulatory burden intensity mapping directly to pricing power.
- Catheterization:Multi-lumen extrusions for interventional cardiology require sub-micron tolerances and radiopaque layering. Germany's precision extrusion hubs around Munich capture OEM development programs seeking integrated co-extrusion and laser-marking capabilities.
- Intravenous Therapy:High-volume gravity and pump sets prioritize material clarity and kink resistance over mechanical complexity. Demand concentrates in hospital procurement consortia across Ireland and Minnesota.
- Surgical Drainage:Large-bore evacuated systems emphasize collapse resistance and radiopacity for post-operative monitoring.
- Respiratory Equipment:Corrugated and smooth-bore configurations for ventilator circuits balance flexibility with gas permeation control.
Catheterization commands the highest unit margins. Intravenous therapy generates the largest absolute volume throughput.
End User:
Facility scale and sterilization infrastructure determine whether procurement favors consignment inventory models or traditional purchase-order relationships.
- Hospitals:Integrated health systems leverage centralized procurement to enforce material standardization across catheterization labs and operating theaters. EU MDR traceability mandates drive ERP upgrades at major German university hospitals.
- Ambulatory Surgery Centers:Compressed case volumes demand same-day sterilization validation and compressed lead times for multi-lumen extrusions. Freestanding cardiology centers in Massachusetts and Bavaria specify pre-sterilized kits.
- Diagnostic Laboratories:Analytical-grade tubing for liquid handling emphasizes chemical inertness and optical clarity.
- Specialty Clinics:Dialysis and infusion centers prioritize supply continuity over technical customization.
Hospitals anchor current procurement volume. Ambulatory surgery centers are expanding most quickly.
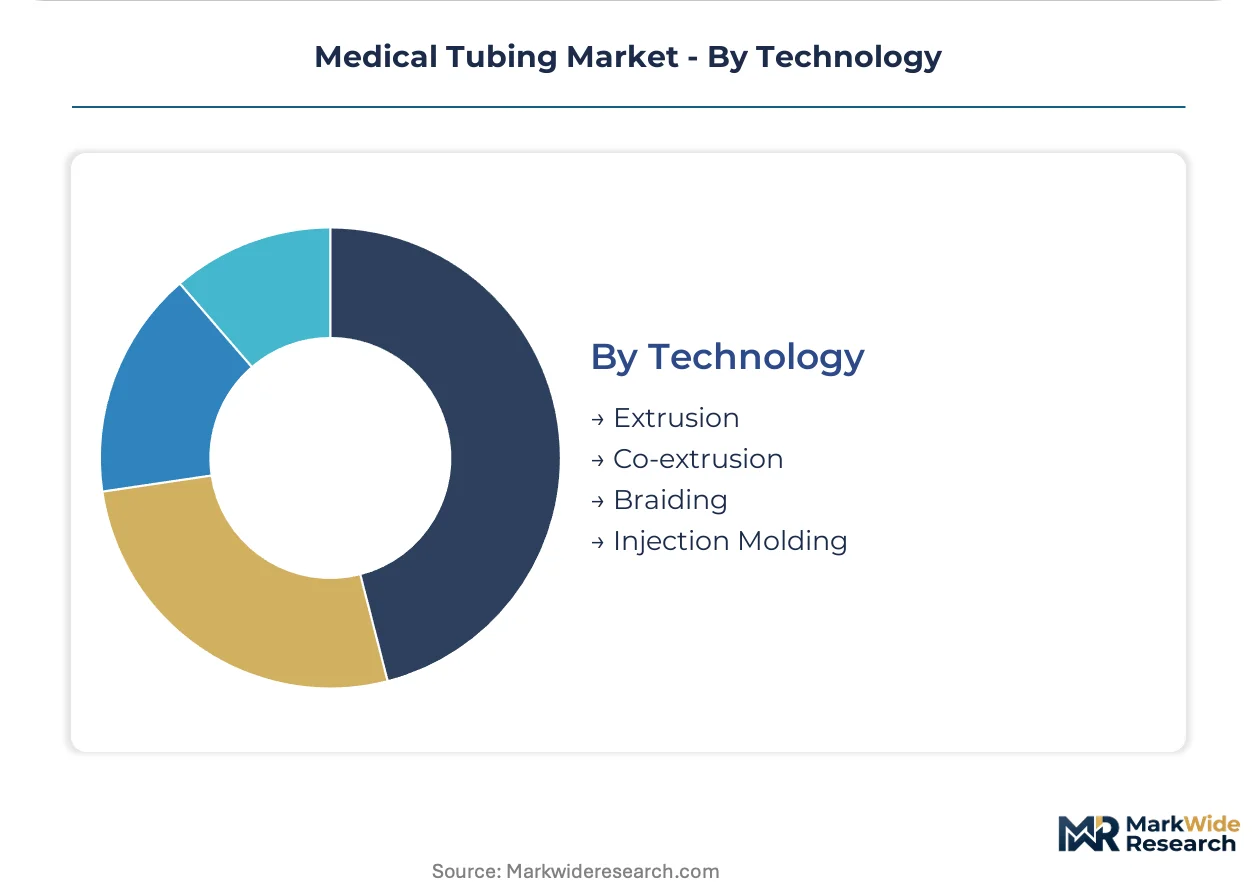
Technology:
Capital intensity gradients separate precision co-extrusion specialists from commodity single-lumen producers, with tooling amortization periods structuring competitive moats.
- Extrusion:Single-screw and twin-screw systems remain the dominant manufacturing platform for standard-profile tubing. Cleanroom-classified lines in Germany and Ireland serve cardiovascular device OEMs with ISO 14644-1 compliance.
- Co-extrusion:Multi-layer die heads enable distinct material properties in one profile, combining lubricious inner surfaces with radiopaque or reinforcing outer layers. Tri-layer cardiac catheter constructions require $2-4 million capital commitments per product line.
- Braiding:Wire or polymer reinforcement integration enhances kink resistance and pressure ratings for high-performance access devices.
- Injection Molding:Overmolding and connector integration complete fluid pathway assemblies for closed-system transfer devices.
Extrusion holds the broadest installed base. Co-extrusion attracts the steepest capital allocation growth.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Precision polymer engineers with ISO 14644-1 cleanroom experience command 40% wage premiums across Germany, the United States, and Japan. This talent scarcity concentrates extrusion capacity in established medical device manufacturing corridors.
Germany
Cardiovascular OEMs in Stuttgart and Munich drive procurement of sub-micron tolerance multi-lumen extrusions. EU MDR traceability mandates force ERP upgrades at precision extrusion hubs. Bavaria's medical technology cluster integrates laser-etched lot coding with captive sterilization validation.
United States
FDA biocompatibility testing under ISO 10993 extends supplier qualification cycles by 14-18 months for implantable-grade tubing. EPA aqueous surface treatment regulations push Massachusetts and Minnesota extruders toward solvent-free production. Greater Boston hosts catheter development programs specifying tri-layer co-extrusion constructions.
Japan
PMDA post-market surveillance requirements align with EU MDR standards for 15-year production record retention. METI funding supports fluoropolymer innovation in neurovascular catheter shafts. Osaka-Kobe manufacturing belt concentrates precision extrusion for Class III implantable segments.
Switzerland
Swissmedic enforcement of MDR-equivalent device identification rules compels laser-marking system investments. Basel-Zurich corridor attracts oncology drug-delivery tubing specialists seeking barrier-layer co-extrusion capabilities. Precision polymer compounding expertise supports closed-system transfer device manufacturing.
Ireland
Medtronic and Boston Scientific procurement hubs in Galway and Dublin drive consignment inventory models for high-volume catheter production. Health Products Regulatory Authority alignment with EU MDR streamlines notified body audit pathways. Shannon-Freeport zone offers tax-efficient extrusion capacity for US market access.
Medical Tubing Market Key Industry Players
Top-tier vendors anchor implantable-grade certification tiers, while mid-scale extruders compete on percutaneous volume throughput. The supplier base splits between fluoropolymer specialists with captive resin relationships and polyurethane compounders serving rapid-cycle disposables. Three archetypes dominate: vertically integrated silicone compounders, precision co-extrusion boutiques, and diversified industrial polymer houses. Competitive moves center on backward integration into polymer compounding and geographic co-location with cardiovascular OEM clusters.
Among diversified materials conglomerates, Saint-Gobain occupies a position exemplifying fluoropolymer expertise for drug-delivery applications. Freudenberg Medical anchors the vertically integrated archetype spanning silicone compounding through cleanroom extrusion. W. L. Gore & Associates represents the membrane-specialist tier with expanded PTFE capabilities for neurovascular segments.
| Leading Market Players |
|---|
| Saint-Gobain |
| Freudenberg Medical |
| W. L. Gore & Associates |
| Nordson Corporation |
| The Lubrizol Corporation |
| TE Connectivity |
| RAUMEDIC AG |
| Elkem ASA |
| Trelleborg AB |
| Others |
Cost & Logistics Intelligence
EPA aqueous treatment mandates gate qualified supply and premium-tier pricing access, as Massachusetts and Minnesota extruders absorbing solvent-free surface activation costs pass compliance premiums through to cardiovascular OEMs while commodity peroxide-cured alternatives face procurement exclusion from implantable segments regardless of price positioning.
Pricing Analysis
Unbundled compounding services versus bundled cleanroom extrusion packages split procurement economics, with platinum-cured silicone commanding validation-heavy premiums over peroxide-cured alternatives and ISO 10993 certification tier driving price differentiation. Pricing pressure stems from consignment inventory models concentrating working capital burdens among mid-tier suppliers serving Boston Scientific and Medtronic hubs. Ambulatory surgery centers exhibit acute price sensitivity for rapid-turn catheter kits, while Class III implantable segments absorb premium tiers with limited elasticity.
Supply Chain Analysis
Freight cost escalation from fluoropolymer resin origins reshapes landed cost structures for catheter shaft producers dependent on concentrated chemical conglomerate supply. Germany, the United States, and Japan anchor precision extrusion capacity, drawing from silicone compound, fluoropolymer resin, and radiopaque additive feedstocks. Single-source vulnerability concentrates among three fluoropolymer suppliers, exposing allocation risk during demand surges. Distribution runs through consignment inventory at OEM cleanrooms in Minnesota and Ireland, displacing traditional purchase-order relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market compounds steadily as cardiovascular device OEM clustering in Germany and Massachusetts generates captive demand for sub-micron tolerance multi-lumen extrusions with limited supplier substitution.
For Market Incumbents: Acquire precision co-extrusion tooling capabilities to defend against additive manufacturing convergence threatening extrusion-specialist boundaries. Backward integration into platinum-cured silicone compounding locks in implantable-grade certification tiers. Expand captive sterilization validation capacity in Bavaria to compress lead times for ambulatory surgery center procurement.
For New Entrants and Emerging Players: EU MDR traceability mandates in Germany open a window for integrated extrusion-marking system specialists lacking legacy ERP upgrade burdens. Target oncology drug-delivery tubing in the Basel-Zurich corridor, where barrier-layer co-extrusion demand outpaces qualified supply. Pursue hospital system partnerships for pre-sterilized catheter kits with same-day release protocols.
For Investors and Strategic Acquirers: Roll-up economics work for precision co-extrusion boutiques because cardiovascular OEM procurement concentrates among extruders with in-house polymer compounding and ISO 14644-1 cleanroom certification. Five-to-ten year viability hinges on additive manufacturing convergence velocity. Monitor FDA guidance on 3D-printed medical devices as inflection signal for extrusion-digital manufacturing boundary redraw.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Silicone Compounding | Captive supply of platinum-cured formulations secures implantable-grade certification tiers for cardiovascular OEMs. |
| Cleanroom Extrusion Capacity Expansion | ISO 14644-1 classified lines in Stuttgart and Munich capture sub-micron tolerance procurement from Boston Scientific and Medtronic. |
| Laser-Etched Lot Coding System Deployment | EU MDR traceability compliance creates differentiated positioning against commodity extruders lacking integrated marking capabilities. |
| Consignment Inventory Model Adoption | Pre-positioned finished goods at customer cleanrooms lock in high-volume catheter supply relationships with compressed working capital cycles. |
| Aqueous Surface Treatment Transition | EPA-compliant solvent-free activation opens compliance pathways for US-based capacity serving Massachusetts and Minnesota hubs. |
Research Approach
Direct dialogue with biomedical engineers, hospital purchasing committee members, GPO contracts managers, and cleanroom extrusion technicians grounded qualitative findings, cross-referenced against FDA 510(k) filings, EU MDR notified body audit records, hospital procurement databases, and SEC 10-K disclosures from diversified materials conglomerates. Bottom-up and top-down triangulation validated segmentation splits across material certification tiers, clinical application risk classes, and manufacturing precision requirements.
Bottom-up modeling aggregated unit economics across silicone, polyurethane, PVC, and thermoplastic elastomer formulations, while top-down validation tracked cardiovascular OEM procurement patterns and ambulatory surgery center expansion trajectories across the analysis window. Segmentation dimensions spanned product type, application, end user, and technology, with CAGRs derived from trend extrapolation of catheterization volume expansion and regulatory compliance cost escalation. Forecast inputs incorporated precision extrusion technician wage premium trajectories and multi-lumen co-extrusion tooling capital commitment cycles.
Forecast precision tightens around the base case; tail outcomes carry wider variance under fluoropolymer resin allocation disruptions or accelerated FDA guidance on additively manufactured tubing geometries. A model refresh is warranted upon material change in EU MDR notified body audit frequency or EPA enforcement posture on solvent-based surface treatments.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Equipment
Tanning Units Market
Medical Equipment
Global Medical Copper Tubing Market
Medical Equipment
Medical Linear Accelerators (MLA) Market
Medical Equipment
Operating Light Market
Medical Equipment
Medical Ethylene Oxide Sterilization Equipment Market
Medical Equipment
Medical Ultrasonic Cleaners Market
Medical Equipment
Global Medical Equipment Calibration Market
Medical Equipment
Global Carbon Dioxide Incubators Market
Medical Equipment
Global Emergency Medical Equipment Market
Medical Equipment
Medical Oxygen Concentrators and Oxygen Cylinders Market
Medical Equipment
Global Steam Autoclaves Market
Medical Equipment
PCR Plate Sealer Market
Medical Equipment
Global Countertop Platelet Incubator Market
Medical Equipment
RFID Blood Refrigerators and Freezers Market
Medical Equipment
Medical Thawing Systems Market
Medical Equipment
Dialyzer Reprocessing Machines and Concentrates Market