
 CO2 Medical Laser Systems Market | 2026-2036
CO2 Medical Laser Systems Market Size, Share, and Industry Trends Forecast 2026-2036
CO2 Medical Laser Systems Market Outlook
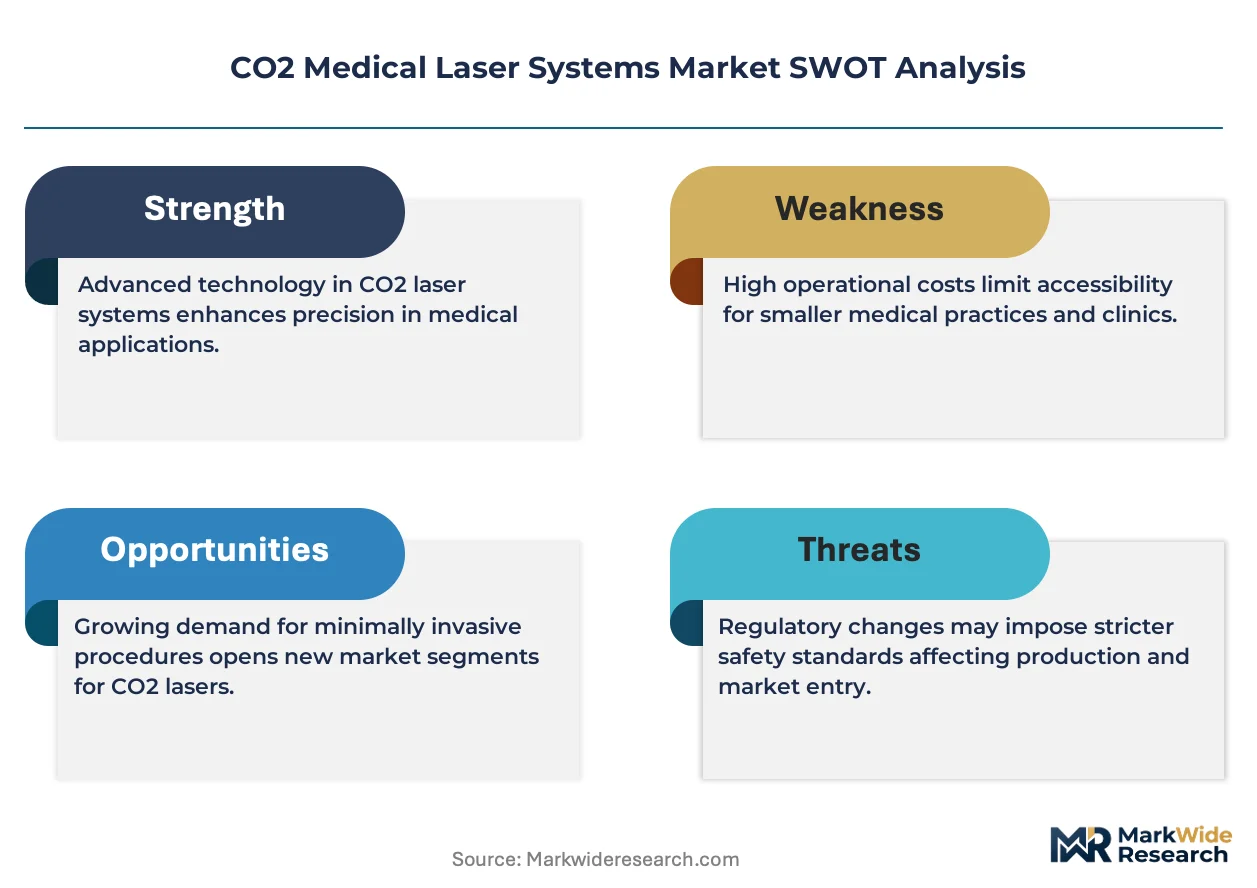
EU MDR is recalibrating the cost-of-entry calculus for CO2 medical laser manufacturers seeking CE marking in European markets. Lumenis leverages its vertically integrated manufacturing footprint to sustain compliance investments across multiple regulatory jurisdictions. Alma Lasers Ltd differentiates through specialized aesthetic laser platforms that navigate diverse national approval pathways.
CO2 medical laser systems generate monochromatic infrared radiation at 10,600 nm wavelength, vaporizing targeted tissue through photothermal ablation while sparing adjacent structures via precise pulse duration control. These devices serve dermatology, dentistry, ophthalmology, and gynecology with tunable tissue interaction modes. Surgical lasers command premium positioning in hospital procurement due to their integration with robotic surgical platforms and electrosurgical compatibility requirements. Aesthetic lasers represent the fastest-expanding category, propelled by fractional technology adoption in dermatology centers and medical spas seeking outpatient revenue diversification. Continuous wave technology dominates industrial manufacturing applications, though pulsed wave configurations lead clinical settings where thermal diffusion control determines procedural safety margins.
FDA 510(k) premarket notifications and EU MDR technical documentation requirements shape product development timelines and clinical evidence standards for CO2 laser platforms entering commercial distribution. ISO 13485 quality management systems and IEC 60601-1-22 laser equipment safety standards establish baseline manufacturing and testing protocols that manufacturers must maintain across all target markets. Stakeholders must monitor evolving cybersecurity guidance from FDA and post-market surveillance obligations under EU MDR as connected laser platforms proliferate in outpatient settings.
Market Dynamics
Fractional CO2 laser technology is compressing procedure recovery times from weeks to days, forcing dermatology centers and hospital outpatient departments to recalibrate capital allocation toward platforms with tunable pulse parameters and integrated cooling systems.
Growth Catalysts
- FDA 510(k) pathway streamlining:Expedited review timelines for predicate-based laser submissions are accelerating commercialization of next-generation fractional platforms in US dermatology centers.
- Medical spa channel expansion:Non-hospital outpatient facilities in South Korea and Japan are deploying compact CO2 systems for aesthetic revenue diversification, broadening addressable procedure volumes.
- Photothermal ablation precision:Advanced pulse duration control at 10,600 nm wavelength enables sub-millimeter tissue targeting, expanding indications from skin resurfacing into gynecological and dental microsurgery.
Market Restraints
- EU MDR technical documentation burden:Recalibrated clinical evidence requirements for CE marking are extending product development timelines by 18-24 months for manufacturers without established notified body relationships.
- German hospital procurement concentration:Centralized purchasing through university hospital networks limits vendor access for mid-tier laser manufacturers lacking robotic surgical platform integration.
- Non-ablative laser substitution:Erbium-doped fiber and picosecond platforms are capturing price-sensitive aesthetic segments where downtime tolerance has shifted.
Strategic Opportunities
- India outpatient dermatology infrastructure:Underpenetrated tier-2 and tier-3 cities present first-mover positioning for compact, serviceable CO2 platforms with localized training protocols.
- Telemedicine-integrated post-procedure monitoring:Connected laser systems with encrypted patient data transmission align with FDA cybersecurity guidance and enable remote complication triage.
- Japan METI carbon-neutral hospital mandates:Energy-efficient solid-state CO2 resonator designs qualify for green procurement incentives in public healthcare facilities.
Industry Challenges
- Laser safety officer certification scarcity:IEC 60601-1-22 compliance requires specialized biomedical engineering expertise that outpatient clinics struggle to recruit and retain.
- Legacy electrosurgical integration:Hybrid operating rooms demand seamless CO2 laser compatibility with existing robotic arms and smoke evacuation infrastructure, comifying system validation protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | CO2 Medical Laser Systems Market |
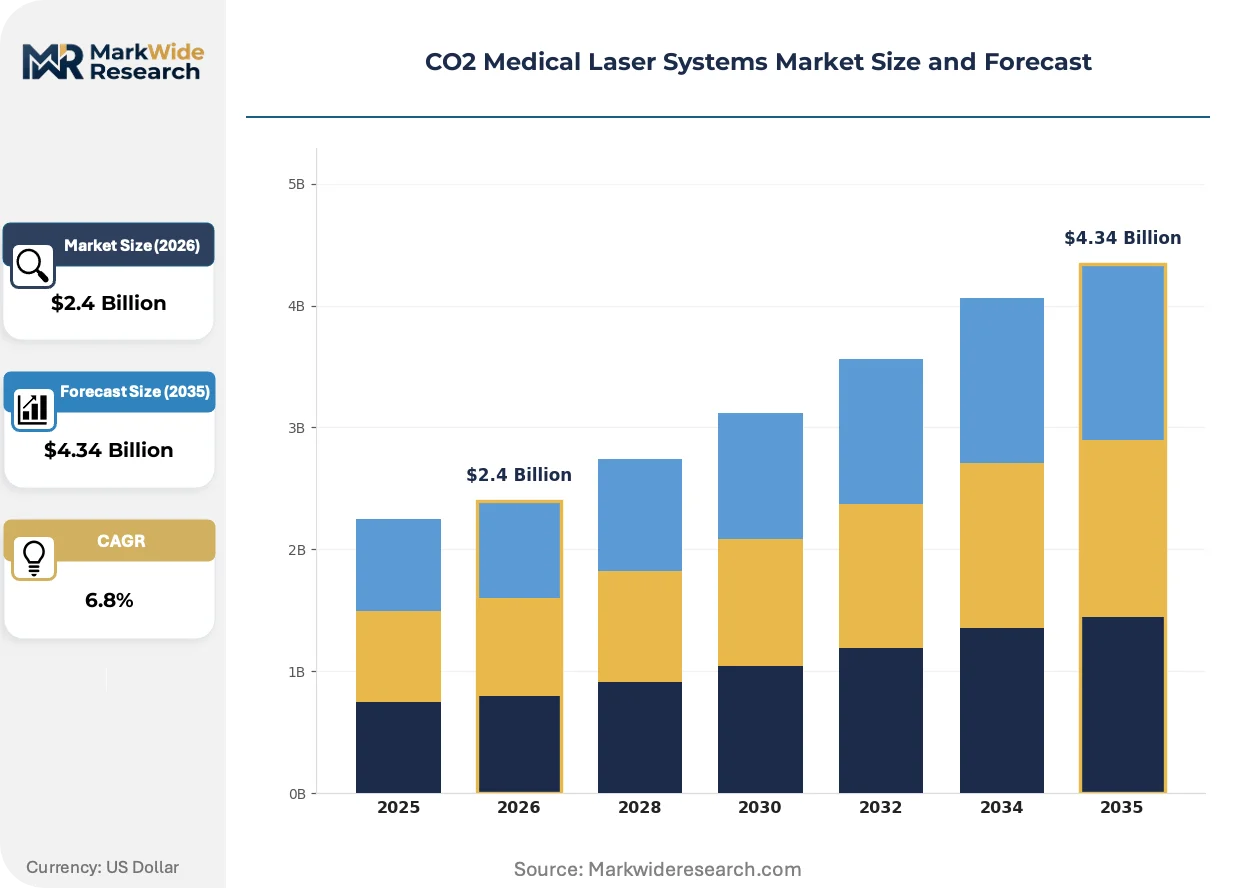
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $4.34 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Surgical Lasers, Aesthetic Lasers, Diagnostic Lasers, Industrial Lasers Application: Dermatology, Dentistry, Ophthalmology, Gynecology End User: Hospitals, Clinics, Dermatology Centers, Surgical Centers Technology: Continuous Wave, Pulsed Wave, Fractional, Non-Fractional |
| Companies Covered | Cutera Inc, Lutronic Aesthetics, Lumenis, Limmer Laser, LightScalpel, Alma Lasers Ltd, Candela Medical, BISON Medical, Cynosure, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
CO2 Medical Laser Systems Market Strategic Shifts
Digital beam delivery systems and AI-assisted tissue recognition are converging to automate procedural parameters, reducing operator-dependent variability in clinical outcomes across dermatology and surgical specialties.
Superpulse technology with microsecond-range pulse stacking is electrifying tissue interaction precision. Academic medical centers in Germany and Japan are prioritizing platforms with real-time thermal feedback sensors. This capability is electrifying competitive differentiation for manufacturers serving high-volume hospital networks where liability exposure drives specification stringency.
EU MDR post-market surveillance obligations now mandate systematic collection of serious incident data across all member states. Manufacturers face expanded vigilance reporting costs that disproportionately burden single-product laser specialists. Surgical CO2 system vendors with diversified aesthetic portfolios absorb these compliance investments across revenue streams more efficiently than pure-play competitors.
Medical spa buyers are unbundling after-sales service contracts from capital purchases, favoring third-party maintenance providers with ISO 13485-certified field engineering networks. This behavior compresses OEM service margins while creating independent service organization opportunities in Florida, California, and Texas where aesthetic clinic density supports technician specialization. Dermatology groups with multi-site footprints negotiate master service agreements that standardize response time SLAs across their estate.
CO2 Medical Laser Systems Market Segmentation
CO2 medical laser systems fragment across four critical dimensions that determine procurement patterns, clinical utility, and margin structures. Each segmentation axis reveals distinct integration requirements, from standalone outpatient platforms to embedded surgical suites requiring robotic compatibility.
Product Type:
Standalone laser platforms dominate outpatient revenue models, while embedded surgical systems command premium positioning through OR integration depth.
- Surgical Lasers:These systems deliver precision photothermal ablation at 10,600 nm with robotic arm compatibility and electrosurgical integration. German university hospital networks and Japanese tertiary centers concentrate procurement, driven by liability-sensitive microsurgical applications requiring sub-millimeter thermal control.
- Aesthetic Lasers:Fractional technology platforms with tunable pulse parameters and integrated cooling systems target dermatology centers and medical spas. South Korea and Japan lead outpatient deployment for revenue diversification beyond traditional cosmetic procedures.
- Diagnostic Lasers:Low-power CO2 systems enable tissue imaging and biopsy guidance with minimal thermal footprint.
- Industrial Lasers:Continuous wave configurations serve manufacturing applications outside clinical settings with lower precision requirements.
Volume placements concentrate in Surgical Lasers; the faster expansion belongs to Aesthetic Lasers.
Application:
Procedure reimbursement rates and regulatory clearance pathways vary sharply across medical specialties, reshaping vendor go-to-market investments.
- Dermatology:Skin resurfacing, scar revision, and lesion removal drive the broadest installed base. US dermatology centers and South Korean medical spas represent the primary demand concentration, propelled by fractional technology adoption compressing recovery timelines.
- Dentistry:Soft tissue procedures and periodontal applications require compact, portable platforms with precise hemorrhage control. Japanese dental clinics prioritize systems with real-time thermal feedback for oral microsurgery.
- Ophthalmology:Corneal and retinal microsurgery demands the highest specification stringency for pulse duration control.
- Gynecology:Cervical and vulvar procedures expand addressable volumes through outpatient clinic deployment.
Revenue concentration sits with Dermatology; Gynecology climbs the fastest as screening protocols expand.
End User:
Capital allocation authority and service contract negotiation leverage diverge substantially across facility types, fragmenting vendor pricing power.
- Hospitals:Centralized procurement through German university networks and Japanese tertiary centers demands robotic platform integration and comprehensive service SLAs. FDA 510(k) clearance and EU MDR CE marking serve as baseline qualification thresholds.
- Clinics:Independent outpatient facilities prioritize compact footprints and third-party maintenance flexibility over OEM service bundles.
- Dermatology Centers:Multi-site groups in Florida, California, and Texas negotiate master service agreements standardizing response times.
- Surgical Centers:Ambulatory facilities concentrate on high-throughput aesthetic procedures with rapid turnover requirements.
Capital deployment concentrates in Hospitals; Dermatology Centers gain share fastest through medical spa channel expansion.
Technology:
Tissue interaction physics and thermal diffusion control determine clinical safety margins, creating distinct competitive moats across technical architectures.
- Fractional:Microbeam array technology delivers photothermal ablation through thousands of microscopic treatment zones, preserving surrounding tissue for accelerated healing. Academic medical centers in Germany and Japan prioritize platforms with real-time thermal feedback sensors for specification stringency.
- Pulsed Wave:Microsecond-range pulse stacking enables precise thermal confinement for microsurgical applications requiring minimal collateral damage.
- Continuous Wave:Uninterrupted beam output dominates industrial manufacturing with lower precision requirements.
- Non-Fractional:Traditional ablative approaches retain niche positioning for deep resurfacing procedures.
Installed base concentrates in Pulsed Wave configurations; Fractional technology expands most quickly across aesthetic applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States dermatology centers and German university hospitals concentrate procurement for high-specification CO2 laser platforms, while South Korean medical spas and Japanese tertiary centers drive aesthetic segment expansion. Regulatory divergence between FDA 510(k) pathways and EU MDR technical documentation requirements fragments vendor compliance investments across Atlantic markets.
United States
Florida, California, and Texas dermatology groups negotiate master service agreements for multi-site fractional laser deployments. FDA 510(k) premarket notifications for predicate-based submissions compress review timelines for next-generation platforms. The Southeast corridor from Miami to Atlanta hosts dense medical spa clusters unbundling OEM service contracts.
Germany
University hospital networks in Bavaria and North Rhine-Westphalia centralize surgical CO2 laser procurement through robotic platform integration mandates. EU MDR recalibrated clinical evidence requirements extend CE marking timelines for manufacturers without established notified body relationships. The Munich-Stuttgart axis concentrates precision medical device engineering talent for thermal feedback sensor development.
Japan
Tokyo and Osaka tertiary centers prioritize superpulse platforms with real-time thermal monitoring for microsurgical liability control. METI carbon-neutral hospital procurement incentives favor energy-efficient solid-state resonator designs in public healthcare facilities. Nagoya medical device clusters supply precision optics for beam delivery system manufacturing.
South Korea
Seoul medical spas deploy compact CO2 systems for outpatient aesthetic revenue diversification beyond traditional cosmetic procedures. MFDS regulatory alignment with IEC 60601-1-22 laser safety standards streamlines domestic platform approval. The Gangnam district anchors premium dermatology center concentration with rapid technology refresh cycles.
India
Maharashtra and Karnataka outpatient dermatology infrastructure in tier-2 cities like Pune and Mysuru present first-mover positioning for serviceable compact platforms. CDSCO medical device rules require localized clinical evidence for Class C laser registrations. Delhi-NCR hospital procurement is shifting toward robotic-compatible surgical suites demanding electrosurgical integration.
CO2 Medical Laser Systems Market Competitive Environment
Israeli producers anchor one tier with vertically integrated aesthetic laser manufacturing; German specialists hold precision surgical system positioning through university hospital relationships. The vendor base stratifies across three tiers: diversified conglomerates absorbing compliance costs across portfolios, mid-cap regional specialists with ISO 13485-certified service networks, and single-product laser vendors facing disproportionate EU MDR vigilance burdens. Dominant competitive moves include portfolio diversification into adjacent energy-based devices and strategic partnerships with robotic surgical platform OEMs for OR integration validation.
Among Israel-based laser specialists, Lumenis and Alma Lasers Ltd exemplify vertically integrated manufacturing architectures that sustain multi-jurisdictional compliance investments. Lumenis occupies a position representing diversified energy-based medical device portfolios with backward integration into resonator production. Alma Lasers Ltd sits within the aesthetic specialization tier, navigating diverse national approval pathways through modular platform designs. Lutronic Aesthetics, with Korean origins, represents the Asia-Pacific regional specialist archetype serving medical spa channel expansion with compact system footprints.
| Leading Market Players |
|---|
| Cutera Inc |
| Lutronic Aesthetics |
| Lumenis |
| Limmer Laser |
| LightScalpel |
| Alma Lasers Ltd |
| Candela Medical |
| BISON Medical |
| Cynosure |
| Others |
Value Chain & Pricing Dynamics
Surgical-aesthetic tier divergence splits CO2 laser procurement economics, with robotic-integrated hospital systems commanding premium positioning while compact outpatient platforms compete on serviceability and third-party maintenance flexibility. This bifurcation concentrates margin capture in German and Japanese university networks while compressing returns for standalone aesthetic vendors in medical spa channels.
Pricing Analysis
Volume placements concentrate in mid-tier aesthetic platforms while margin capture concentrates in surgical systems with robotic compatibility. Three-tier pricing structure across premium, standard, and economy levels reflects FDA 510(k) clearance tier, ISO 13485 certification depth, and bundled service contract duration. Pricing pressure stems from medical spa buyers unbundling OEM service agreements in favor of independent ISO 13485-certified maintenance providers. Dermatology centers exhibit highest price sensitivity; hospital procurement committees show lowest sensitivity due to liability-driven specification stringency.
Supply Chain Analysis
Regional distribution centers in Israel, Germany, and South Korea anchor hub-and-spoke patterns for laser resonator components and precision optics. Manufacturing draws from German precision engineering clusters for thermal feedback sensors, Israeli vertically integrated resonator production, and Japanese solid-state design expertise. Single-source vulnerability concentrates in 10,600 nm wavelength-specific optical coatings and FDA-cleared control software modules. Distribution runs through manufacturer-direct hospital sales teams for surgical systems and third-party aesthetic device distributors for outpatient channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The CO2 medical laser market has become a vertical-integration race, with manufacturers pursuing backward integration into resonator production to defend margin structures against regulatory compliance cost inflation.
For Market Incumbents: Extend service contract bundling into multi-site master agreements for dermatology groups in Florida, California, and Texas to lock out independent service organizations. Deepen backward integration into precision optics manufacturing to absorb EU MDR vigilance reporting costs across diversified revenue streams rather than pure-play aesthetic portfolios. For New Entrants and Emerging Players: Digital-channel training protocols offer a direct route to penetrate India's tier-2 and tier-3 outpatient dermatology infrastructure where localized clinical education gaps persist. Target compact, serviceable platform deployment in Maharashtra and Karnataka with CDSCO Class C registration pathways, leveraging telemedicine-integrated post-procedure monitoring as a differentiated go-to-market angle. For Investors and Strategic Acquirers: Re-rating potential sits with diversified energy-based device portfolios given EU MDR compliance cost absorption advantages over single-product laser specialists. Monitor FDA cybersecurity guidance finalization as an inflection signal for connected platform valuations, with long-term viability hinging on hospital network penetration depth rather than medical spa channel exposure.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR technical documentation investments recalibrate competitive entry costs across European markets. |
| Hospital System Partnership | Robotic surgical platform integration validates specification stringency for German university network procurement. |
| Software Companion Development | AI-assisted tissue recognition modules automate procedural parameters reducing operator-dependent variability. |
| Reimbursement Strategy | Dermatology procedure coding alignment expands addressable volumes in US outpatient settings. |
| FDASubmission | 510(k) predicate-based pathways accelerate fractional platform commercialization in aesthetic segments. |
Study Parameters
Document review covered FDA 510(k) premarket notification databases, EU MDR technical documentation guidance, and ISO 13485 quality management system standards, complemented by interviews with biomedical engineers, hospital purchasing committee members, dermatology center operators, and GPO contracts managers. Secondary validation drew from CMS Medicare procedure data, hospital procurement databases, and MFDS regulatory filings. Bottom-up installation base modeling triangulated against top-down market sizing across product type, application, end user, and technology dimensions.
Historical shipment data cross-referenced against panel input from laser safety officers and clinical engineering directors anchored the analytical framework across the analysis window. Segmentation modeling incorporated product architecture, medical specialty indication, facility type procurement authority, and thermal control technology. CAGRs derived from procedure volume elasticity to capital equipment replacement cycles and regulatory approval timeline compression. Forecast inputs included medical spa channel expansion rates and METI carbon-neutral procurement incentive qualification thresholds.
Inputs from FDA 510(k) clearance databases and EU notified body technical documentation reviews were available through the study window; gaps in real-time medical spa inventory tracking and private dermatology group capital expenditure plans introduce uncertainty bands around aesthetic segment projections. Forecasts reflect documented assumptions regarding regulatory pathway streamlining and reimbursement stability. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Equipment
North America Medical Carts Market
Medical Equipment
Global Refrigerated Incubators Market
Medical Equipment
Sanitary Napkin Equipment Market
Medical Equipment
Refurbished Medical Equipment Market
Medical Equipment
Global Medical Refrigerators Market
Medical Equipment
Tanning Units Market
Medical Equipment
Global Laminar Airflow Cabinets Market
Medical Equipment
Global Medical Device Reprocessing Market
Medical Equipment
Hemodialysis Equipment Market
Medical Equipment
Blood Bank Refrigerators Market
Medical Equipment
Hospital-at-Home Equipment Rental Market
Medical Equipment
US ECG Equipment Market
Medical Equipment
Contact Lens Inspection Equipment Market
Medical Equipment
Contact Type Liquid Handling Workstation Market
Medical Equipment
Europe Medical Automation Market
Medical Equipment
Auditory Brainstem Response Analyzers Market