
 Global Self-Injection Device Market | 2026-2036
Global Self-Injection Device Market Size, Share, and Industry Trends Forecast 2026-2036
Global Self-Injection Device Market Foresight
The capital-intensity divergence between large-scale injection molders and boutique connectivity specialists is unwinding traditional competitive boundaries in self-injection devices. Becton Dickinson and Company leverages its integrated manufacturing footprint across North America and Europe to sustain cost advantages in high-volume auto-injector production. Ypsomed AG anchors its position through dedicated R&D centers in Switzerland that specialize in connected pen injector platforms with embedded dose-tracking electronics. SHL Medical AG competes by controlling vertically integrated assembly lines for disposable mechanical devices serving global pharmaceutical contract manufacturing demand.
Self-injection devices are drug delivery systems that combine a primary container—typically a glass syringe barrel or cartridge—with a mechanism enabling patients to administer parenteral therapies without healthcare professional assistance; most incorporate either a spring-driven plunger or electronic motor with needle-safety features engineered to ISO 11608-5 standards for dose accuracy and injection depth. Their primary commercial purpose centers on enabling chronic disease patients to maintain therapeutic adherence outside clinical settings while reducing healthcare system burden. Auto-injectors occupy the dominant margin pool due to premium pricing tied to biologic drug co-development partnerships, while pen injectors represent the fastest-expanding category as insulin and GLP-1 agonist volumes accelerate in diabetes management. Needle-free injectors remain structurally constrained by higher manufacturing complexity and limited reimbursement coverage despite technological maturation.
FDA human factors guidance, EMA MDR requirements, and ISO 13485 quality management standards collectively shape device development timelines, validation costs, and market access pathways for manufacturers seeking multi-jurisdictional approval. The EU MDR transition has extended conformity assessment durations for electronic delivery systems, while FDA emphasis on use-error mitigation in home settings drives incremental engineering investment in audible dose-completion indicators and ergonomic grip surfaces. Stakeholders must monitor evolving connectivity regulations as software-as-medical-device frameworks in the United States and Europe begin capturing Bluetooth-enabled dose loggers and companion mobile applications under expanded premarket scrutiny.
Market Dynamics
Biologic drug pipelines are concentrating therapeutic development around large-molecule parenterals that demand purpose-built delivery systems, forcing device manufacturers to co-develop platforms years ahead of commercialization. This upstream integration into pharmaceutical R&D cycles is compressing traditional supplier selection timelines and elevating technical partnership criteria above unit cost.
Growth Catalysts
- GLP-1 Agonist Expansion:Diabetes and obesity therapeutic volumes are pulling dedicated pen injector capacity through pharmaceutical contract manufacturing channels, particularly in United States and German markets where reimbursement pathways for weight management have matured.
- FDA Human Factors Guidance:The 2016 guidance document and subsequent enforcement emphasis on use-error mitigation in home settings is creating design specification premiums for devices with integrated audible dose-completion indicators and ergonomic grip surfaces.
- Home Care Migration:Chronic disease management protocols across oncology, rheumatology, and neurology are shifting administration sites from infusion centers to patient residences, generating pull-through demand for disposable auto-injectors with extended stability profiles.
Market Restraints
- Glass Cartridge Supply Concentration:Borosilicate glass barrel production for primary containers concentrates among German and Italian specialty glass manufacturers, exposing device assemblers to input cost volatility and allocation risk during pharmaceutical vial demand surges.
- EU MDR Transition Friction:Extended conformity assessment durations for electronic delivery systems under the Medical Device Regulation are delaying market entry timelines and inflating validation expenditure for Bluetooth-enabled dose loggers and companion mobile applications.
- Needle-Free Technical Ceiling:Powder-based and liquid jet injectors remain constrained by dose accuracy variance across subcutaneous tissue density profiles and limited reimbursement coverage under United States Medicare Part D pharmacy benefit structures.
Strategic Opportunities
- Japanese Elder Care Infrastructure:METI-sponsored smart health initiatives and PMDA streamlined review pathways for combination products create favorable conditions for connected pen platforms with embedded adherence monitoring in one of the world's most aged populations.
- Software-as-Medical-Device Capture:FDA and EMA frameworks expanding premarket scrutiny to Bluetooth-enabled dose loggers and companion applications open revenue streams for firmware developers and digital health integrators previously outside regulatory perimeter.
- Insulin Biosimilar Volume:Patent expirations for originator insulin analogs are fragmenting pharmaceutical supply, creating openings for device manufacturers to secure multi-source platform agreements with emerging biosimilar sponsors in Indian and South Korean markets.
Industry Challenges
- Human Factors Engineering Talent Scarcity:Cross-functional expertise bridging mechanical design, clinical validation, and regulatory submission under ISO 14971 risk management standards commands premium compensation and extended recruitment cycles in Swiss and Boston metropolitan clusters.
- Validation Facility Capex Burden:Cleanroom assembly expansion for high-volume auto-injector programs requires dedicated mold qualification cells and automated vision inspection systems that strain balance sheets of mid-scale contract manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Self-Injection Device Market |
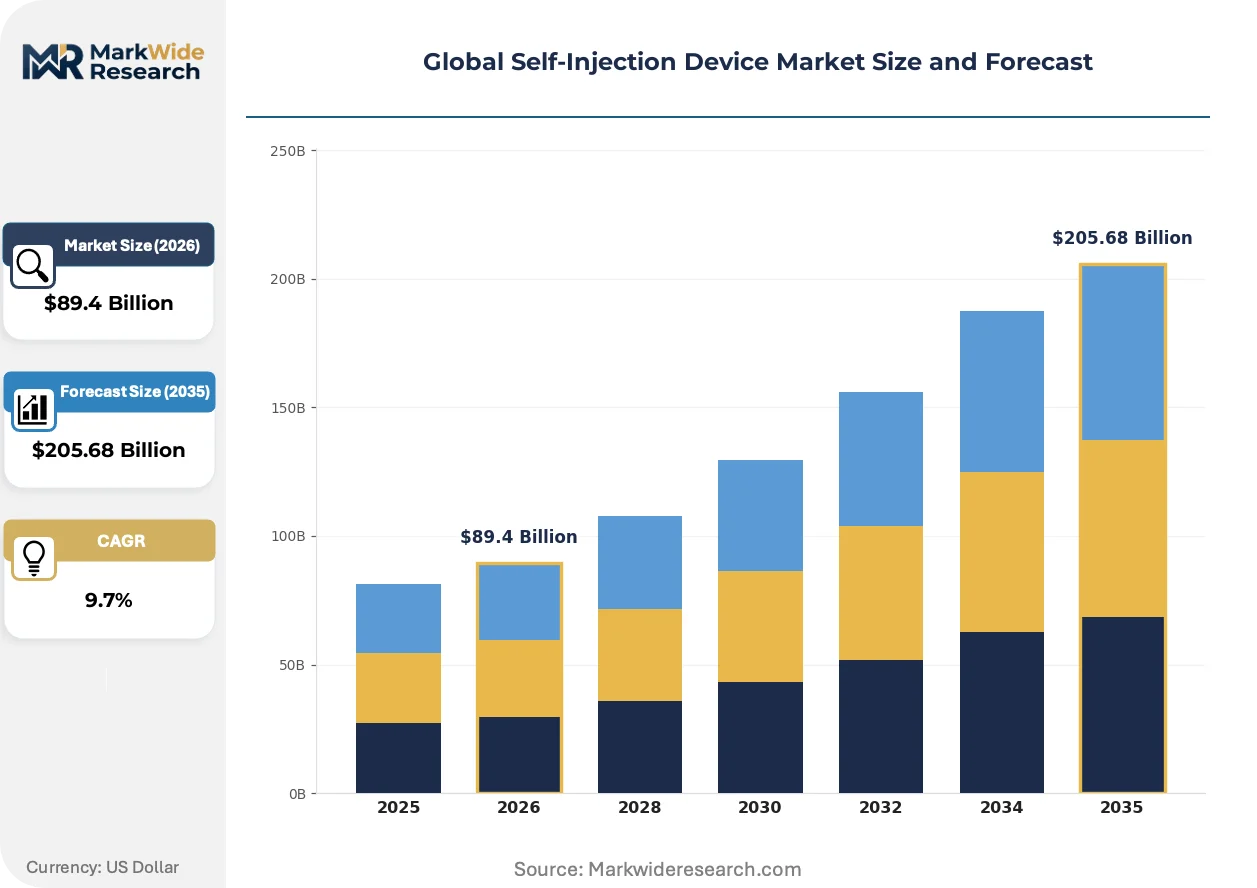
| Market Size in 2026 | $89.4 Billion |
| Market Size in 2035 | $205.68 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Auto-Injectors, Prefilled Syringes, Pen Injectors, Needle-Free Injectors Therapy Area: Diabetes, Rheumatoid Management, Multiple Sclerosis, Allergic Conditions End User: Home Care Patients, Outpatient Clinics, Specialty Pharmacies, Long-Term Care Facilities Delivery Mode: Manual, Mechanical, Electronic, Disposable |
| Companies Covered | Becton Dickinson and Company, Ypsomed AG, SHL Medical AG, Gerresheimer AG, Owen Mumford, West Pharmaceutical Services, Insulet Corporation, Halozyme Therapeutics, Nemera, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Self-Injection Device Market Shifts & Advancements
Connectivity modules are migrating from premium-tier differentiators to baseline expectations as pharmaceutical sponsors seek real-world evidence generation capabilities and payers demand adherence documentation. This functional elevation is compressing development timelines and forcing hardware-software integration competencies into core device engineering teams.
Spring-driven mechanical platforms with embedded NFC tags and low-energy Bluetooth transmitters are supplanting purely passive disposable auto-injectors in biologic co-development partnerships. Rheumatology and multiple sclerosis therapeutic sponsors in United States and German markets are specifying dose-timestamp logging as a contractual requirement. This connectivity mandate is enabling outcome-based contracting experiments between pharmaceutical manufacturers and United States commercial payers while compressing margin structures for device suppliers lacking firmware development capabilities.
EMA MDR requirements and FDA emphasis on cybersecurity for networked medical devices are reshaping quality management system investments across European and North American manufacturing footprints. Validation protocols now encompass penetration testing and software bill of materials documentation previously absent from mechanical device submissions. Electronic delivery system categories face the steepest compliance cost inflation as notified bodies extend technical documentation review cycles for products with wireless communication stacks.
Hospital procurement consortia in United States and United Kingdom are consolidating self-injection device purchasing through pharmaceutical channel intermediaries rather than direct device sourcing. This intermediation shift transfers price negotiation leverage to drug sponsors and compresses standalone device margins, particularly for standard mechanical pen platforms in insulin categories. Rheumatology clinic networks in German and Japanese metropolitan areas exhibit the most pronounced consolidation, with single-source agreements covering both therapeutic and delivery system components.
Global Self-Injection Device Market Segmentation
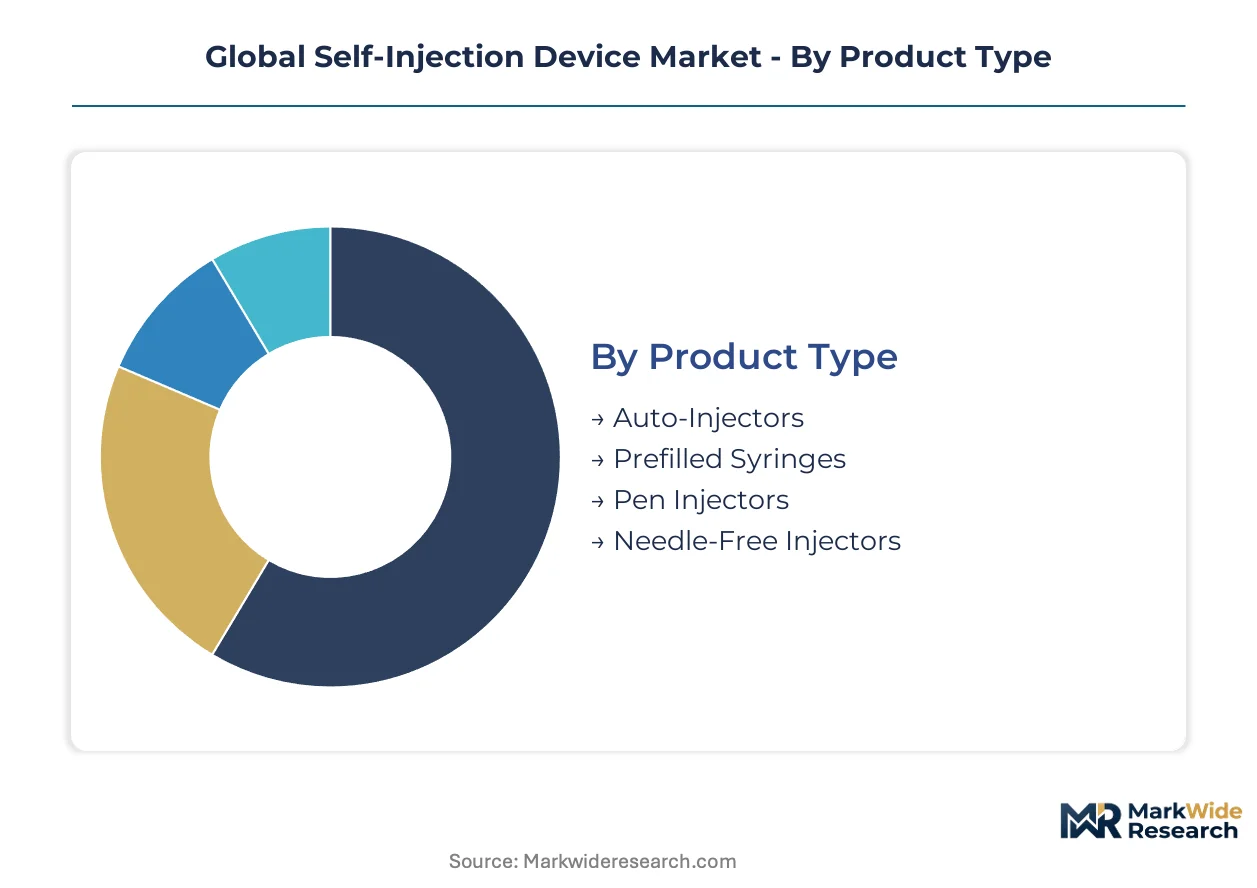
Segmentation in self-injection devices reveals how pharmaceutical channel strategies and patient site-of-care preferences reshape manufacturing priorities. Device specifications diverge sharply between hospital-contracted auto-injector programs and retail-distributed pen platforms.
Product Type:
Channel economics separate premium co-developed auto-injectors from commodity pen platforms, with connectivity modules increasingly mandatory across all tiers.
- Auto-Injectors:Spring-driven or electronic systems with integrated needle-safety mechanisms engineered to ISO 11608-5 standards. Demand concentrates in United States and German rheumatology markets where biologic sponsors specify audible dose-completion indicators and ergonomic grips for home administration.
- Pen Injectors:Reusable or disposable cartridge-based systems with dose-dialing mechanisms. Japanese and United States diabetes volumes are pulling dedicated manufacturing capacity through pharmaceutical contract channels as GLP-1 agonist prescriptions accelerate.
- Prefilled Syringes:Glass-barrel primary containers with luer-lock or staked-needle configurations for manual administration. Oncology and emergency medicine applications in German hospital consortia dominate procurement volumes.
- Needle-Free Injectors:Liquid-jet or powder-based systems using high-pressure propulsion through micro-orifices. Limited Medicare Part D reimbursement and dose-accuracy variance across tissue density profiles constrain United States adoption.
By volume, pen injectors lead. By growth pace, auto-injectors with embedded connectivity are climbing the fastest.
Therapy Area:
Regulatory validation requirements and injection frequency patterns create divergent device performance specifications across therapeutic categories.
- Diabetes:Daily or weekly subcutaneous administration of insulin analogs and GLP-1 receptor agonists. United States and Japanese markets specify connected dose-logging for adherence monitoring in value-based contracting arrangements.
- Rheumatoid Management:Biologic TNF-alpha inhibitors and IL-6 antagonists requiring precise subcutaneous delivery. German rheumatology clinic networks are consolidating procurement through single-source pharmaceutical agreements covering both drug and device.
- Multiple Sclerosis:Interferon-beta and monoclonal antibody therapies with varying injection frequencies. Patient self-efficacy requirements in home settings drive specification for audible feedback and anti-slip grip surfaces.
- Allergic Conditions:Epinephrine auto-injectors for emergency anaphylaxis management. United States school and public venue stocking mandates sustain replacement-cycle demand despite generic competition.
Diabetes commands the largest installed base. Rheumatoid management applications are gaining share fastest as biologic pipelines mature.
End User:
Site-of-care migration patterns are redistributing device specification authority from hospital procurement to pharmaceutical sponsor medical affairs teams.
- Home Care Patients:Individuals administering chronic therapies without professional supervision. FDA human factors guidance on use-error mitigation and EMA MDR requirements for electronic systems are elevating design validation costs for this channel.
- Outpatient Clinics:Physician-supervised administration in rheumatology, neurology, and endocrinology settings. German and Japanese metropolitan clinic networks are consolidating purchasing through pharmaceutical intermediaries.
- Specialty Pharmacies:Distribution nodes providing patient training and adherence support for complex biologics. United States hub pharmacy models are specifying connected devices for real-world evidence generation.
- Long-Term Care Facilities:Skilled nursing and assisted living residences with mixed professional and patient-administered injections. Staff turnover and training burden favor simplified mechanical platforms over electronic systems.
Home care patients represent the dominant volume endpoint. Specialty pharmacies are expanding most quickly as pharmaceutical sponsors seek adherence data capture.
Delivery Mode:
Manufacturing complexity and regulatory classification thresholds segment production capabilities across mechanical and electronic platforms.
- Mechanical:Spring-driven plunger systems with passive needle guards and manual dose activation. Swiss and North American contract manufacturers dominate high-volume auto-injector assembly for biologic co-development partnerships.
- Electronic:Motor-driven injection with programmable dose profiles and embedded connectivity. Extended EU MDR conformity assessment durations and FDA cybersecurity requirements are inflating validation expenditure for Bluetooth-enabled platforms.
- Manual:User-powered plunger operation without automated assistance. Prefilled syringe applications in oncology and emergency medicine retain this mode for cost minimization.
- Disposable:Single-use devices with no reusability components. Environmental regulations in European markets are pressuring material selection and end-of-life disposal pathways.
Mechanical platforms lead by unit volume. Electronic delivery systems are expanding most steeply as connectivity becomes a contractual baseline.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across major markets. The United States emphasizes connected auto-injectors for biologic adherence tracking, while Japan prioritizes ergonomic pen platforms for elderly diabetes patients, and Germany concentrates procurement through pharmaceutical intermediaries rather than direct device sourcing.
United States
FDA human factors guidance on use-error mitigation drives specification premiums for audible dose-completion indicators and ergonomic grip surfaces. Medicare Part D reimbursement structures favor disposable mechanical platforms over needle-free alternatives. Boston metropolitan clusters concentrate contract manufacturing capacity for biologic co-development partnerships.
Germany
Rheumatology clinic networks consolidate procurement through single-source pharmaceutical agreements covering both drug and device components. EU MDR transition extends conformity assessment durations for electronic delivery systems with Bluetooth-enabled connectivity. Stuttgart and Munich industrial corridors anchor specialty glass cartridge production for primary containers.
Japan
METI-sponsored smart health initiatives accelerate connected pen platform adoption among the world's most aged population. PMDA streamlined review pathways for combination products reduce regulatory friction for embedded adherence monitoring systems. Osaka and Nagoya manufacturing zones specialize in compact electronic motor assemblies for precision dose delivery.
Switzerland
Swissmedic quality standards and proximity to pharmaceutical headquarters sustain premium positioning for high-precision mechanical platforms. ISO 14971 risk management expertise concentrates in Basel and Zürich metropolitan clusters. Local R&D centers specialize in dose-tracking electronics and connected device firmware development.
India
CDSCO regulatory harmonization efforts attract contract manufacturing investment for export-oriented auto-injector assembly. Insulin biosimilar pipeline expansion creates demand for multi-source platform agreements with emerging pharmaceutical sponsors. Gujarat and Maharashtra industrial zones develop cleanroom capacity for disposable mechanical device production.
Global Self-Injection Device Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in self-injection device manufacturing. Large-scale molders with captive glass cartridge supply dominate high-volume auto-injector programs, while boutique connectivity developers capture premium positioning in electronic delivery systems. The competitive terrain separates three archetypes: vertically integrated pharmaceutical partners, modular platform specialists, and regional contract manufacturers. Consolidation pressure intensifies through pharmaceutical channel intermediation and co-development partnership exclusivity.
Among Swiss and German fabricators, Ypsomed AG and SHL Medical AG exemplify contrasting strategic positions within European device engineering. Becton Dickinson and Company anchors North American manufacturing scale across integrated North American and European production footprints. These three entities occupy distinct tier positions—specialist connectivity, vertical assembly control, and continental-scale molding capacity—without direct segment overlap.
| Leading Market Players |
|---|
| Becton Dickinson and Company |
| Ypsomed AG |
| SHL Medical AG |
| Gerresheimer AG |
| Owen Mumford |
| West Pharmaceutical Services |
| Insulet Corporation |
| Halozyme Therapeutics |
| Nemera |
| Others |
Supply & Pricing Matrix
ISO 11608-5 certification requirements gate both supplier qualification and price differentiation in self-injection devices, forcing pharmaceutical sponsors to pay premiums for validated manufacturing cells while excluding uncertified assemblers from biologic co-development partnerships. This regulatory threshold simultaneously protects incumbent margins and compresses commodity-tier pricing for undifferentiated mechanical platforms.
Pricing Analysis
Long-term offtake contracts dominate biologic co-development partnerships, with pharmaceutical sponsors locking multi-year supply agreements for connected auto-injector platforms. Price differentiation rests on FDA validation tier and embedded firmware capabilities, with Bluetooth-enabled systems commanding substantial premiums over passive mechanical alternatives. Cost compression in standard pen injectors is intensifying because insulin biosimilar sponsors prioritize unit economics over feature differentiation. Hospital procurement consortia exhibit the highest price sensitivity, while specialty pharmacies accepting outcome-based contracts show the least.
Supply Chain Analysis
Strategic stockpiling of borosilicate glass cartridges prevails among German and Swiss device assemblers seeking insulation from pharmaceutical vial demand surges. Supply concentrates in Germany, Italy, and Switzerland for specialty glass primary containers, with electronic motor assemblies sourcing from Japanese and South Korean precision manufacturers. Raw material dependencies include pharmaceutical-grade borosilicate glass, medical-grade stainless steel for spring mechanisms, and rare-earth magnets for electronic dosing motors. Single-source vulnerability in German specialty glass production exposes device manufacturers to allocation risk during demand spikes. Distribution runs through pharmaceutical channel intermediaries rather than direct device sourcing.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory entrenchment creates durable defensive moats in self-injection devices, as FDA and EMA validation timelines measured in years erect barriers that substitute technologies cannot easily circumvent.
For Market Incumbents: Fortify captive supply positions in borosilicate glass cartridge production to neutralize input cost volatility from German and Italian specialty glass manufacturers. Deepen firmware development capabilities in Swiss and Boston metropolitan clusters to defend against connectivity specialists eroding premium positioning in electronic delivery systems. Prioritize ISO 14971 risk management certification investments that extend validation lead times beyond challenger reach. For New Entrants and Emerging Players: Firmware integration services for legacy mechanical platforms represent a service-layer gap where incumbents under-serve mid-scale pharmaceutical sponsors lacking in-house digital health capabilities. Target Indian and South Korean insulin biosimilar sponsors seeking multi-source platform agreements without incumbent exclusivity constraints. Pursue CDSCO regulatory harmonization pathways to establish export-oriented manufacturing credibility before attempting United States or European market entry. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed contract manufacturers holding cleanroom assembly capacity but lacking connectivity engineering competencies. Five-to-ten year viability hinges on successful software-as-medical-device capability acquisition before FDA and EMA frameworks fully capture dose-logging applications under expanded premarket scrutiny. Watch for pharmaceutical sponsor consolidation of rheumatology clinic networks into single-source procurement agreements as an inflection indicator for standalone device margin compression.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Human Factors Submission | Accelerates biologic co-development partnerships by satisfying use-error mitigation requirements for home administration. |
| CE Marking Pathway | Unlocks German and Swiss rheumatology clinic procurement through EU MDR conformity assessment completion. |
| Backward Integration into Glass Cartridges | Neutralizes supply concentration risk from German and Italian specialty glass manufacturers during demand surges. |
| Software Companion Development | Captures Bluetooth-enabled dose loggers under FDA software-as-medical-device frameworks for adherence monitoring revenue. |
| Reimbursement Strategy | Secures Medicare Part D coverage for connected pen platforms in United States diabetes and obesity management categories. |
Research Methodology
A standing panel of regulatory affairs leads, pharmaceutical device engineers, hospital procurement managers, and GPO contracts managers provided ongoing calibration against secondary validation from FDA 510(k) filings, EMA MDR submissions, ISO certification databases, and hospital procurement records. Bottom-up segmentation modeling triangulated against top-down market sizing across product type, therapy area, end user, and delivery mode dimensions.
Consistency checks validated volume and value outputs against external benchmarks including pharmaceutical sponsor annual reports, contract manufacturing disclosures, and national healthcare expenditure databases. The analytical framework modeled mechanical versus electronic platform substitution, connectivity adoption curves, and regional regulatory cluster effects across the projection horizon. CAGRs derived from patient population growth, biologic pipeline maturation, and site-of-care migration patterns informed segment-level trajectories.
Underlying assumptions cover regulatory timeline stability, glass cartridge supply continuity, and reimbursement pathway durability, with deviation risk concentrated in EU MDR transition delays and pharmaceutical sponsor procurement consolidation. Forecasts reflect these documented conditions. Revision becomes warranted when FDA software-as-medical-device enforcement crosses thresholds that reclassify previously exempt connectivity modules.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Human Anatomy Model Market
Medical Devices
Global Mobile ECG Devices Market
Medical Devices
Cannula Market
Medical Devices
Asia Pacific Brachytherapy Devices Market
Medical Devices
Non-Magnetic Wheelchair Market
Medical Devices
Oral Appliance Market
Medical Devices
Sacroiliac Joint Fusion Market
Medical Devices
Veterinary Procedure Lights Market
Medical Devices
Breast Biopsy Localization Wire Market
Medical Devices
Blood Irradiator Device Market
Medical Devices
Polyether Ether Ketone (PEEK) Interbody Devices Market
Medical Devices
Ventilation Devices Market
Medical Devices
Reusable Medical Battery Market
Medical Devices
Chile Ultrasound Devices Market
Medical Devices
Global Thermoelectric Devices in Medical and Laboratory Offering Market
Medical Devices
Batteries for Skin Patches Market