
 Pre-Packaged Medical Supplies Market | 2026-2036
Pre-Packaged Medical Supplies Market Size, Share, and Industry Trends Forecast 2026-2036
Pre-Packaged Medical Supplies Market Analytics
Multi-source procurement toward integrated kit suppliers is consolidating purchasing power among the largest North American health systems. Medline Industries leverages its domestic manufacturing footprint to sustain same-day fulfillment commitments for surgical kits. Cardinal Health anchors its position through direct-to-OR distribution networks that bypass traditional warehouse layers. Owens & Minor competes on Veterans Affairs and federal supply schedule contracts where compliance documentation outweighs pure price metrics.
Pre-packaged medical supplies encompass sterile and non-sterile consumables assembled into standardized configurations, typically incorporating gamma-irradiated or ethylene-oxide-treated components with defined shelf-life parameters and lot-traceable packaging. These configurations serve to reduce operative preparation time, minimize contamination risk, and standardize clinical workflows across acute and ambulatory settings. The product type dimension shows gloves and dressings occupying mature, high-volume positions with compressed margins, while procedure-specific kits capture premium positioning through customization and regulatory documentation. End user segmentation reveals home care as the fastest-expanding channel, though hospitals still dominate absolute value procurement through multi-year enterprise agreements.
FDA 510(k) clearance pathways and EU MDR technical documentation requirements shape product development timelines and market access costs for kit assemblers and component suppliers alike. ISO 13485 quality management certification has become a baseline qualifier rather than a differentiator for contract manufacturing relationships. Stakeholders must monitor evolving EPA regulations on ethylene oxide sterilization residuals, as facility closures or emission restrictions could force rapid conversion to alternative sterilization modalities with significant capital and validation implications.
Market Dynamics
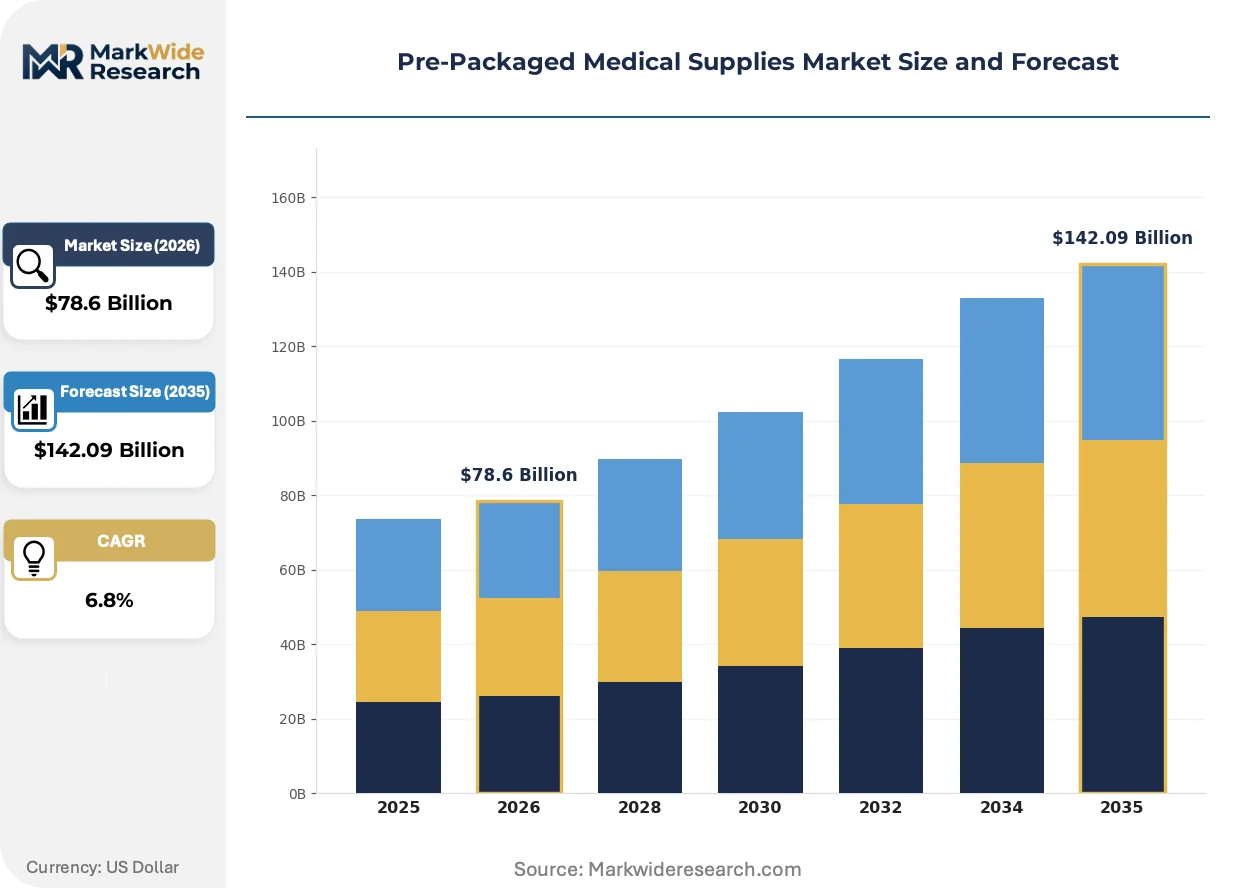
Consolidation among North American health systems is compressing supplier margins and forcing kit assemblers to absorb logistics costs that previously flowed to distributors. This purchasing-power concentration now dictates sterilization modality choices and inventory minimums.
Growth Catalysts
- FDA 510(k) pathway streamlining:Expedited clearance for kit configurations using predicate devices accelerates product launch timelines for domestic manufacturers serving ambulatory surgery centers.
- Home care services expansion:Aging patient populations in Germany and Japan are shifting post-acute procedures to residential settings, generating demand for sterile procedure packs designed for non-institutional environments.
- Gamma irradiation technology maturation:Terminal sterilization validation protocols now support extended shelf-life claims, reducing hospital inventory carrying costs and expiration waste.
Market Restraints
- Ethylene oxide supply concentration:EPA facility closures in the US Midwest have reduced commercial EtO capacity, forcing kit assemblers to queue for sterilization slots or validate gamma alternatives.
- EU MDR technical documentation burden:Kit classification as Class IIa or IIb devices requires clinical evidence and notified body review, extending time-to-market by 12-18 months for European entrants.
- Polypropylene price volatility:Resin input costs for blister packaging and tray components fluctuate with petrochemical feedstock markets, compressing gross margins on high-volume glove and dressing kits.
Strategic Opportunities
- India's PLI scheme for medical devices:Production-linked incentives for domestic kit manufacturing attract contract assemblers seeking to serve Southeast Asian markets with lower landed costs.
- Radio-frequency identification integration:Smart packaging combining RFID tags with sterilization indicators enables real-time inventory tracking across hospital supply chains and point-of-use documentation.
- Same-day surgical kit delivery models:Direct-to-OR logistics bypassing warehouse intermediaries capture premium positioning among integrated delivery networks optimizing block-time utilization.
Industry Challenges
- ISO 13485 auditor scarcity:Qualified certification bodies face backlogs extending quality management system renewal timelines, risking supply contract suspensions for manufacturers awaiting surveillance audits.
- Legacy enterprise resource planning integration:Kit assemblers migrating to cloud-based lot-traceability platforms encounter data migration friction with hospital materials management systems running on-premise architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pre-Packaged Medical Supplies Market |
| Market Size in 2026 | $78.6 Billion |
| Market Size in 2035 | $142.09 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dressings, Syringes, Gloves, Bandages End User: Hospitals, Clinics, Emergency Services, Home Care Packaging Type: Bulk Packs, Individual Packs, Kits, Reusable Containers Usage Type: Disposable, Reusable, Sterile, Non-Sterile |
| Companies Covered | Medline Industries, Cardinal Health, McKesson Corporation, 3M Company, Owens & Minor, BD, B. Braun SE, Molnlycke Health Care, Henry Schein Medical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pre-Packaged Medical Supplies Market Evolving Landscape
Sterilization modality diversification and intelligent packaging architectures are redefining competitive differentiation in kit assembly. Regulatory documentation automation and demand-responsive production models now separate scalable suppliers from legacy operators.
Sustainable sterilization alternatives including vaporized hydrogen peroxide and nitrogen dioxide systems are gaining validation for temperature-sensitive components. Academic medical centers in the Netherlands and Sweden are piloting these modalities for biologic-containing kits. This technology is converging with blockchain-based sterilization certificate verification to create immutable chain-of-custody records that satisfy EU MDR post-market surveillance requirements.
EPA ethylene oxide emission regulations are forcing facility retrofits or permanent closures across the US Gulf Coast sterilization corridor. Industrial consequence includes sterilization queue lengthening and geographic redistribution of EtO-dependent kit production toward remaining compliant facilities. Cardiac and orthopedic procedure kits with biologic components face the tightest capacity constraints, prompting accelerated gamma and e-beam validation programs.
Hospital procurement functions are consolidating SKU rationalization authority into centralized value-analysis committees. Integrated delivery networks in Texas and California are replacing physician preference item autonomy with standardized kit formularies negotiated through multi-year enterprise agreements. This concentration is most visible in cardiovascular and spine service lines where implant-kit bundling now dominates contract structures.
Pre-Packaged Medical Supplies Market Segmentation
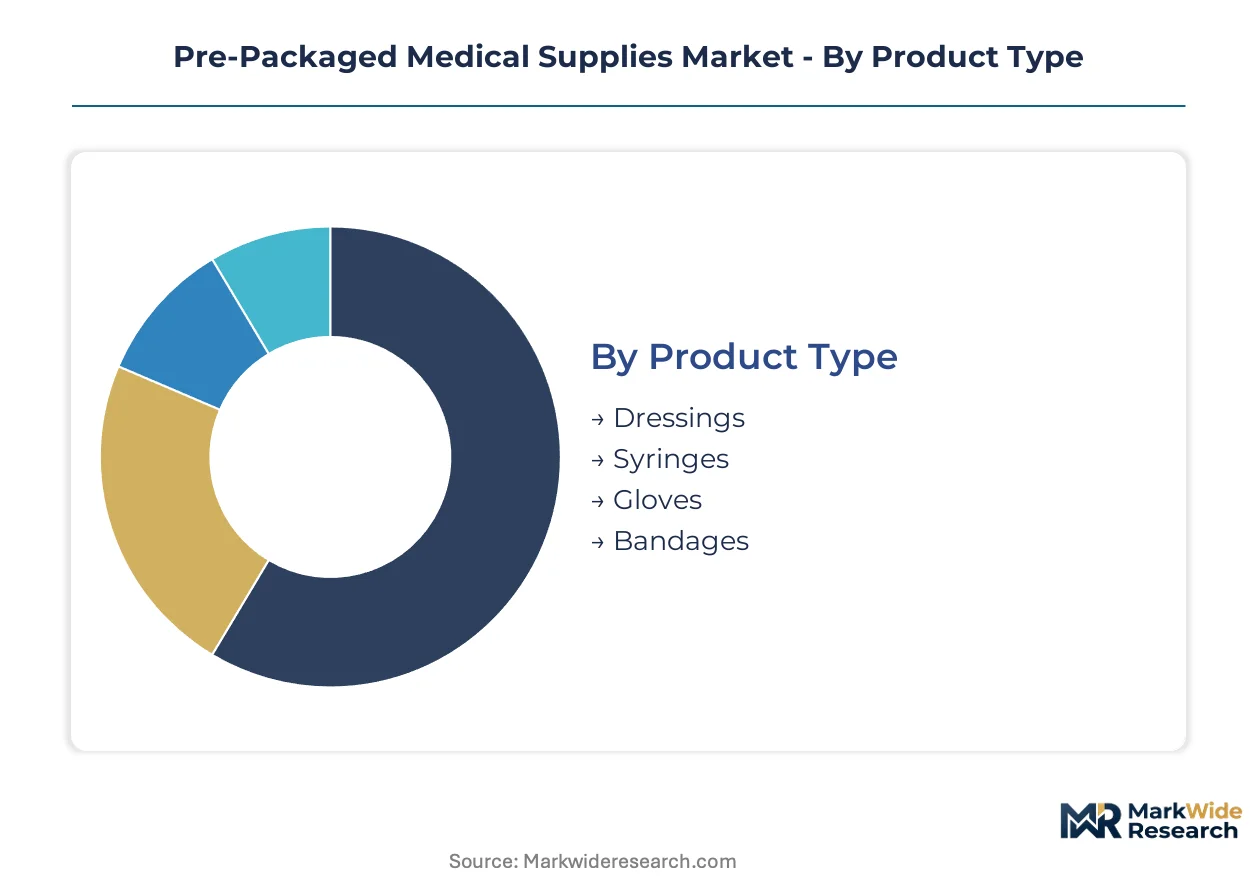
Pre-packaged medical supplies fragment across four intersecting dimensions that determine sterilization modality, shelf-life engineering, and distribution economics. Each segmentation layer carries distinct margin profiles and regulatory documentation burdens that shape supplier positioning.
Product Type:
Supply concentration among gamma-irradiation facilities favors high-volume segments with predictable sterilization throughput.
- Dressings:Woven and non-woven gauze configurations dominate hospital procurement through standardized burn and wound care protocols. Demand concentrates in German acute care networks where DRG reimbursement favors pre-sterilized formats over custom assembly.
- Syringes:Luer-lock and safety-engineered designs incorporate polypropylene barrels and rubber plunger assemblies with defined particle-count specifications. United States ambulatory surgery centers drive volume through single-use mandates that eliminate reprocessing labor costs.
- Gloves:Nitrile and latex examination gloves occupy mature, high-turnover positions with compressed margins and consolidated manufacturing in Southeast Asian production clusters.
- Bandages:Adhesive strip and cohesive wrap formats serve retail pharmacy and institutional channels with minimal sterilization requirements.
Today's leader: Dressings. Tomorrow's challenger: Syringes.
End User:
Application context determines packaging complexity, with acute settings demanding lot-traceable sterile formats.
- Hospitals:Operating rooms and catheterization laboratories require procedure-specific kits with component-level serialization and expiration-date validation. Japanese university hospitals anchor premium positioning through multi-year enterprise agreements that bundle implant and consumable procurement.
- Home Care:Self-administered wound care and infusion therapy generate demand for intuitive, single-use packs with pictorial instructions. Germany's aging population and ambulatory reimbursement expansion propel this channel's steepest expansion trajectory.
- Clinics:Physician offices and outpatient centers prioritize cost-optimized bulk formats with extended shelf-life claims.
- Emergency Services:Pre-hospital trauma kits require ruggedized packaging and rapid-deployment configurations for field deployment.
Volume dominance rests with Hospitals. Growth momentum belongs to Home Care.
Packaging Type:
Margin tiering separates commodity formats from value-added configurations with embedded documentation.
- Kits:Procedure-specific assemblies combine sterile and non-sterile components with custom tray designs and regulatory inserts. United States integrated delivery networks concentrate purchasing power through standardized cardiovascular and orthopedic kit formularies.
- Individual Packs:Unit-dose formats serve infection-control protocols with single-patient-use guarantees and minimal waste.
- Bulk Packs:High-count glove and dressing configurations minimize per-unit packaging cost for high-throughput settings.
- Reusable Containers:Rigid sterilization cases for surgical instruments face declining adoption amid single-use preference.
Premium capture flows to Kits. Commodity volume aggregates in Bulk Packs.
Usage Type:
Customer type stratification distinguishes regulated sterile formats from unregulated general supply categories.
- Sterile:Terminal sterilization with gamma irradiation or ethylene oxide requires ISO 11135 or ISO 11137 validation and FDA 510(k) or EU MDR technical documentation. FDA sterility assurance requirements and EU MDR kit classification rules tighten compliance burdens for cross-border suppliers.
- Disposable:Single-use designation drives material selection toward cost-optimized polymers with defined degradation timelines.
- Reusable:Reprocessing-validated designs face shrinking addressable market as infection-control protocols favor single-use alternatives.
- Non-Sterile:General-purpose gloves, bandages, and examination supplies bypass sterilization validation with corresponding margin compression.
Regulatory value concentrates in Sterile. Cost pressure intensifies on Non-Sterile.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The North Chicago-Mundelein corridor concentrates sterile kit manufacturing capacity for US hospital networks. German Ruhr Valley assemblers anchor European supply chains through gamma-irradiation partnerships. Japanese Kansai region fabricators serve aging home-care demand with compact procedure packs.
United States
Integrated delivery networks in Texas and California drive standardized cardiovascular kit procurement through multi-year enterprise agreements. FDA 510(k) pathway streamlining accelerates clearance for ambulatory surgery center configurations. The Gulf Coast sterilization corridor faces EPA ethylene oxide emission facility retrofits, redistributing production toward Midwest gamma-irradiation sites.
Germany
Aging demographics and ambulatory reimbursement expansion propel home-care sterile pack demand at double-digit rates. EU MDR kit classification as Class IIa or IIb devices requires clinical evidence and notified body review, extending time-to-market. Ruhr Valley industrial clusters maintain gamma-irradiation partnerships with Dutch academic medical centers piloting vaporized hydrogen peroxide alternatives.
Japan
University hospitals in Tokyo and Osaka anchor premium positioning through multi-year enterprise agreements bundling implant and consumable procurement. METI production incentives support domestic kit manufacturing automation. Kansai region fabricators specialize in compact procedure packs for residential post-acute settings.
India
Production-linked incentive schemes for medical devices attract contract assemblers seeking Southeast Asian market access with lower landed costs. CDSCO quality management requirements align with ISO 13485 certification baselines for export qualification. Gujarat and Maharashtra industrial corridors concentrate sterile glove and dressing kit manufacturing for Middle East and African markets.
United Kingdom
NHS procurement consolidation drives demand for standardized wound care and infusion therapy kits with extended shelf-life claims. MHRA post-Brexit regulatory autonomy maintains EU MDR technical documentation alignment for cross-border supply continuity. Midlands manufacturing clusters serve ambulatory care networks with cost-optimized bulk formats.
Pre-Packaged Medical Supplies Market Competitive Landscape
Global majors compete with regional champions across sterilization modality access and direct-to-OR distribution reach. The supplier base concentrates among integrated health system contract holders with captive sterilization capacity and federal supply schedule eligibility. Three archetypes dominate: domestic manufacturing footprint operators, direct-distribution network owners, and compliance-documentation specialists. Consolidation among North American health systems forces M&A activity and same-day fulfillment capability investments.
Within the integrated supply tier, Medline Industries, Cardinal Health, and Owens & Minor occupy positions defined by manufacturing geography and contract vehicle access. Medline exemplifies domestic footprint operators leveraging same-day fulfillment commitments. Cardinal anchors direct-to-OR distribution network archetypes bypassing warehouse intermediaries. Owens & Minor represents compliance-documentation specialists capturing Veterans Affairs and federal supply schedule awards.
| Leading Market Players |
|---|
| Medline Industries |
| Cardinal Health |
| McKesson Corporation |
| 3M Company |
| Owens & Minor |
| BD |
| B. Braun SE |
| Molnlycke Health Care |
| Henry Schein Medical |
| Others |
Value Network & Pricing Analysis
Polypropylene resin index volatility cascades through blister packaging and tray component costs, forcing kit assemblers to stratify pricing across gamma-irradiated sterile formats, EtO-dependent procedure packs, and non-sterile bulk configurations. Hospital GPOs and integrated delivery networks exploit this input-cost transparency to demand volume-tiered contracting that shifts sterilization modality risk onto suppliers.
Pricing Analysis
Input-cost pass-through from petrochemical feedstock markets drives three-tier pricing structure across premium, standard, and economy levels. FDA 510(k) clearance tier and ISO 13485 certification status differentiate sterile procedure kits from commodity glove and dressing formats. Pricing pressure stems from EPA ethylene oxide facility closures forcing sterilization queue premiums for cardiac and orthopedic biologic-containing kits. Ambulatory surgery centers exhibit highest price sensitivity due to DRG reimbursement constraints, while Japanese university hospitals anchor premium tier through implant-consumable bundling.
Supply Chain Analysis
India's PLI scheme domestic-content mandates reshape sourcing patterns for Southeast Asian contract assemblers seeking lower landed costs. Manufacturing gravity centers on the United States for same-day fulfillment commitments, Germany for Ruhr Valley gamma-irradiation partnerships, and India for sterile glove and dressing export production. Polypropylene resin, nitrile rubber, and sterilization services constitute critical input dependencies. Single-source vulnerability concentrates in the US Gulf Coast EtO sterilization corridor. Distribution runs through direct-to-OR networks bypassing warehouse intermediaries for integrated delivery networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
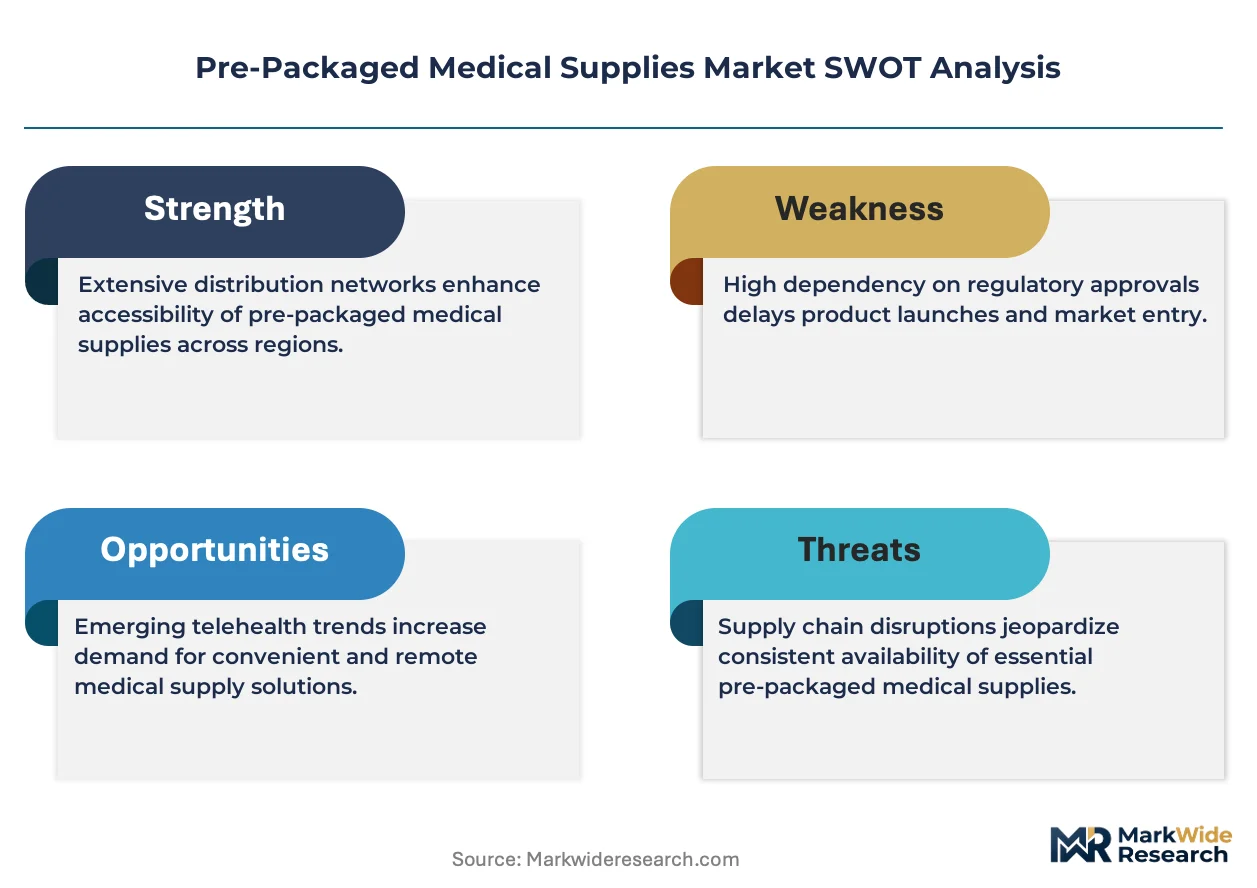
This market functions as a regulatory compounder where EU MDR kit reclassification as Class IIa or IIb devices extends time-to-market and deepens compliance moats around incumbent sterilization capacity.
For Market Incumbents: Extend gamma-irradiation capacity into remaining EPA-compliant Midwest facilities to capture EtO-dependent kit volumes displaced from Gulf Coast closures. Deepen backward integration into polypropylene tray molding to defend margins against resin price volatility. Lock multi-year enterprise agreements with Texas and California integrated delivery networks before standardized kit formularies fully consolidate. For New Entrants and Emerging Players: Launch via direct-to-OR same-day delivery models targeting ambulatory surgery centers bypassing incumbent warehouse layers. Penetrate Germany's home-care sterile pack segment where aging demographics and ambulatory reimbursement expansion outpace supply responsiveness. Exploit RFID-enabled smart packaging as differentiation wedge against legacy lot-traceability platforms. For Investors and Strategic Acquirers: Asymmetric upside sits with contract assemblers holding captive gamma-sterilization capacity and federal supply schedule eligibility. Five-to-ten year viability hinges on sterilization modality diversification execution. Watch EPA ethylene oxide emission rulemaking timeline as inflection trigger for capacity valuation repricing.| Strategic Initiative | Industry Significance |
|---|---|
| Sterilization Modality Diversification | Gamma and e-beam validation programs capture cardiac kit volumes displaced from EtO facility closures. |
| RFID-Enabled Smart Packaging | Real-time inventory tracking satisfies EU MDR post-market surveillance through immutable sterilization certificates. |
| Direct-to-OR Distribution Network | Same-day fulfillment commitments bypass warehouse intermediaries for Texas and California integrated delivery networks. |
| Federal Supply Schedule Eligibility | VA and DOD contract access prioritizes compliance documentation over pure price metrics in federal procurement. |
| ISO 13485 Certification Investment | Quality management system baseline qualifies contract manufacturing relationships amid auditor scarcity backlogs. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with hospital purchasing committee members, GPO contracts managers, sterilization facility operators, and biomedical engineers with secondary validation against FDA 510(k) filings, EU MDR technical documentation databases, hospital procurement records, and CMS Medicare reimbursement data. Bottom-up segment sizing triangulated against top-down macroeconomic indicators.
Segment-weighting approach modeled product type, end user, packaging format, and usage type dimensions across the analysis window. CAGRs derived from sterilization throughput capacity expansion trajectories, home-care reimbursement policy shifts, and health system consolidation patterns. Forecast inputs incorporated EPA ethylene oxide facility status, EU MDR notified body review timelines, and polypropylene resin price index movements.
Several conditions sit outside the modeled scope, including unannounced EPA enforcement actions, sudden EU MDR guidance revisions, and sterilization facility force-majeure events. Forecasts reflect documented assumptions about regulatory stability and input cost trajectories. A small set of named triggers warrants ongoing watch: EPA EtO emission rulemaking finalization, EU MDR audit body capacity expansion, and India PLI scheme disbursement velocity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Supplies
Specimen Retrieval Bags Market
Medical Supplies
Europe Ostomy Care and Accessories Market
Medical Supplies
Face Mask Market
Medical Supplies
First Aid Kit Market
Medical Supplies
Surgical Gowns Market
Medical Supplies
Foley Trays Market
Medical Supplies
Blood Preparation Market
Medical Supplies
Global IV Tubing Sets and Accessories Market
Medical Supplies
Global Dialysis Concentrate Market
Medical Supplies
Middle East and Africa Hospital Supplies Market
Medical Supplies
Evacuated Drainage Bottles Market
Medical Supplies
Global Medical Waste Containers Market
Medical Supplies
Japan Organ Preservation Market
Medical Supplies
Single Use Safety Lancet Market
Medical Supplies
Global Disposable Blood Bags Market
Medical Supplies
GCC Syringes and Needles Market