
 Transfusion Bottles Market | 2026-2036
Transfusion Bottles Market Size, Share, and Industry Trends Forecast 2026-2036
Transfusion Bottles Market Analytics
Hospital procurement of transfusion bottles is tilting toward consolidated national tenders and group purchasing organizations across North America and Western Europe. Fresenius Kabi AG leverages its integrated plasma therapy portfolio to anchor long-term supply contracts with major hospital networks. B. Braun Melsungen AG competes through specialized infusion and transfusion device ecosystems that bundle bottles with administration sets. Baxter International Inc. sustains geographic dominance in the Americas through captive manufacturing and direct-to-institution distribution channels.
Transfusion bottles are sterile, single-use containers manufactured from medical-grade PVC, polypropylene, or glass, designed to store and deliver blood components under controlled temperature and pressure conditions. The 450 mL and 500 mL capacities dominate hospital workflows due to standard whole-blood collection protocols, while sterile plastic bottles are displacing glass in emergency and field settings because of reduced breakage risk and lighter transport weight. Blood bags within the product type spectrum capture the largest volume share as apheresis and component therapy expand, though ISO-certified and CE-marked bottles command premium positioning in European tender processes where regulatory compliance functions as a non-negotiable gatekeeper.
FDA blood and biologics regulations, EMA medical device directives, and ISO 3826 standards for collapsible blood containers collectively dictate material selection, leachable testing, and shelf-life validation requirements. These frameworks elevate compliance costs for new entrants while reinforcing incumbents with established quality management systems and notified body relationships. Stakeholders must monitor evolving polymer substitution mandates and sterilization modality shifts as sustainability pressures intersect with patient safety imperatives.
Market Dynamics
Hospital procurement consolidation and polymer substitution mandates are compressing supplier margins while elevating compliance barriers. Blood banking modernization in mature healthcare systems is accelerating specification upgrades for collection and storage containers.
Growth Catalysts
- EMA MDR compliance deadlines:European tender processes now require ISO 3826-certified collapsible containers, locking in premium-grade suppliers with notified body relationships.
- Apheresis procedure expansion:Component therapy protocols in tertiary hospitals are multiplying single-unit consumption per patient encounter.
- United States surgical volume recovery:Elective procedure backlogs in major hospital networks are restoring baseline transfusion demand trajectories.
Market Restraints
- Medical-grade PVC resin concentration:Feedstock supply chains cluster in Gulf Coast petrochemical corridors, exposing converters to hurricane disruption risk.
- FDA sterilization validation requirements:Gamma and electron-beam modality switches demand multi-year shelf-life stability studies that freeze formulation changes.
- Glass-to-plastic substitution ceiling:Certain plasma-derived biologics still require borosilicate barrier properties that polymer alternatives cannot replicate.
Strategic Opportunities
- German centralized blood service tenders:National procurement frameworks favor vendors offering integrated collection-to-administration ecosystems.
- Polypropylene coextrusion advances:Multi-layer barrier films are opening oxygen-scavenging applications previously reserved for glass.
- Japan PMDA quality management harmonization:Mutual recognition agreements with European notified bodies are streamlining dual-market entry pathways.
Industry Challenges
- Polymer chemist talent scarcity:Formulation expertise for medical-grade leachable control concentrates among legacy PVC compounders approaching retirement.
- ISO 10993 biocompatibility testing backlog:Contract laboratory capacity constraints are extending new material qualification timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Transfusion Bottles Market |
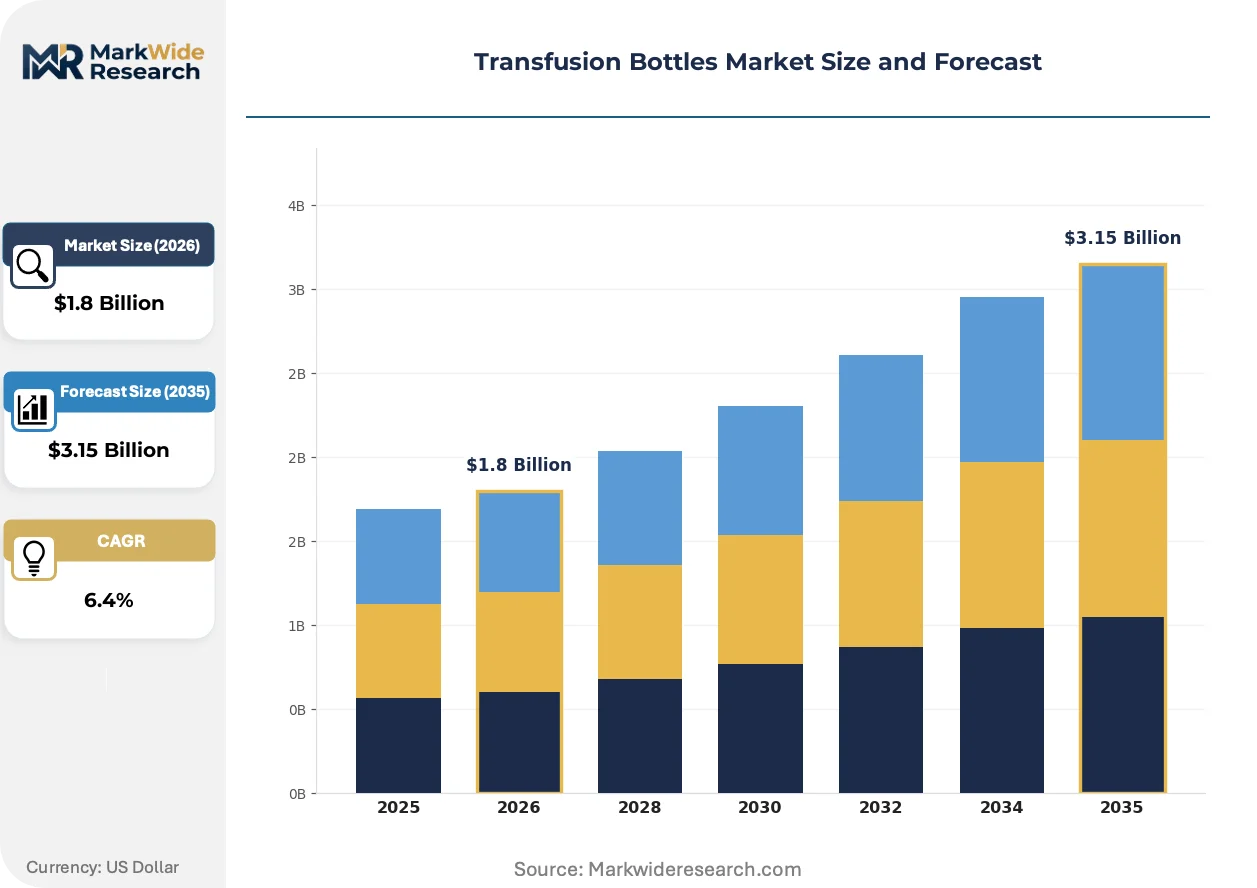
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.15 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Plastic Bottles, Glass Bottles, Sterile Bottles, Blood Bags End User: Hospitals, Blood Banks, Clinics, Diagnostic Laboratories Capacity: 50 mL, 100 mL, 250 mL, 500 mL Certification: ISO Certified, CE Marked, FDA Approved, GMP Compliant |
| Companies Covered | Fresenius Kabi AG, Medtronic, B. Braun Melsungen AG, Smiths Medical, Nipro Corporation, Baxter International Inc., ICU Medical Inc., Gerresheimer, Becton, Dickinson and Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Transfusion Bottles Market Evolving Landscape
Material science breakthroughs and regulatory harmonization efforts are compressing product development cycles while fragmenting competitive advantage sources. Blood container specifications are diverging between emergency field use and controlled hospital environments.
Multilayer polypropylene coextrusion with ethylene-vinyl alcohol barrier layers is extending platelet storage duration from five to seven days. Major German and Japanese blood services are qualifying these containers for routine inventory rotation. Glass is rendering obsolete for pre-hospital trauma kits where weight and breakage risk dominate selection criteria.
REACH polymer registration requirements are forcing systematic substitution of ortho-phthalate plasticizers in European-sourced PVC compounds. Compounders must resubmit technical dossiers for alternative citrate-based plasticizers. Blood bag manufacturers serving EMA-regulated markets face reformulation validation costs that favor incumbents with dedicated regulatory affairs teams.
Consolidated national tenders in the United States and Germany are compressing supplier rosters to three-to-four approved vendors per category. Group purchasing organizations now bundle transfusion bottles with administration sets and filtration devices. Japanese Red Cross Society procurement cycles have shifted from annual to multi-year framework agreements that lock in volume commitments.
Transfusion Bottles Market Segmentation
Transfusion bottle procurement splits sharply between mature hospital systems with standardized workflows and emerging blood banking networks upgrading collection infrastructure. Specification divergence across end users and regulatory jurisdictions forces suppliers to maintain parallel product lines with distinct validation dossiers.
Product Type:
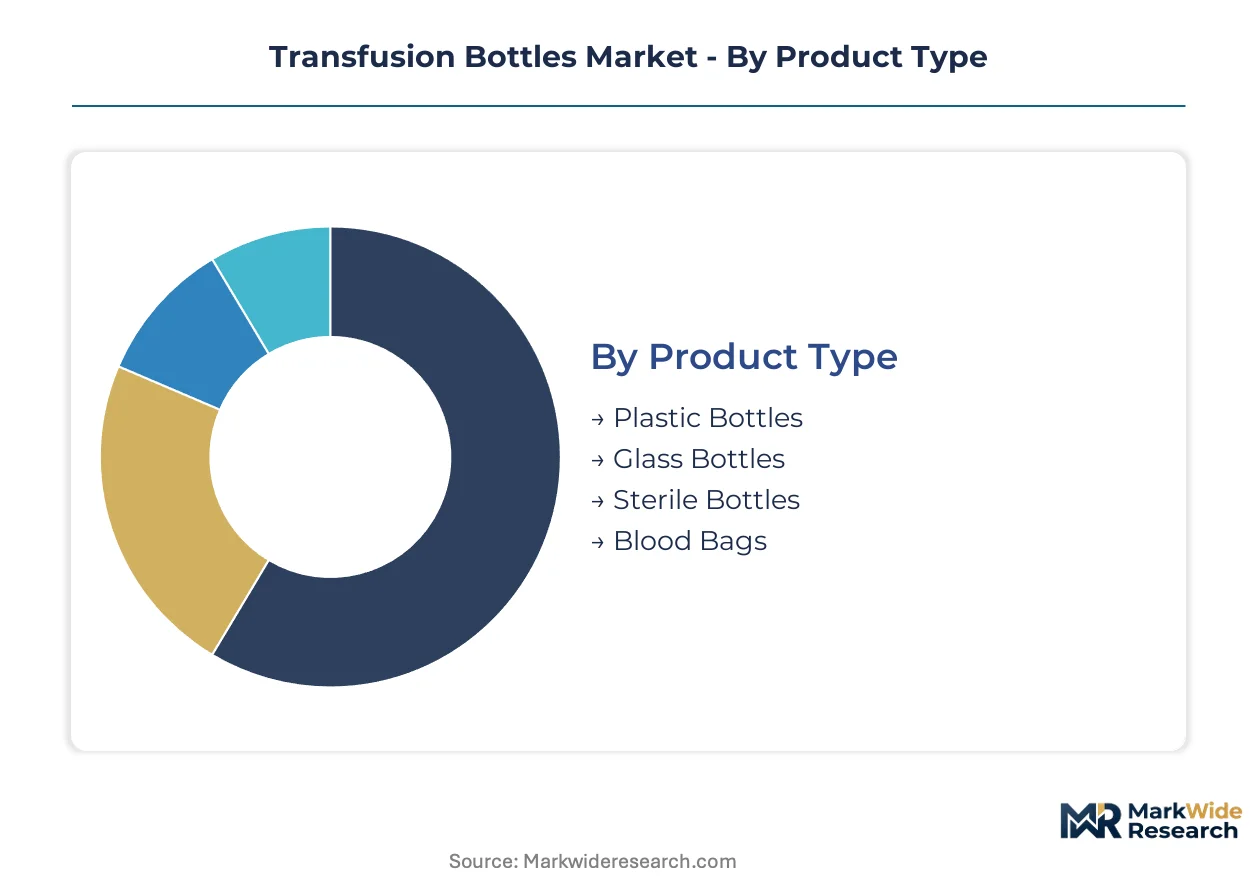
Mature sterile plastic formats dominate established blood services while emerging multilayer barrier technologies reshape storage duration benchmarks.
- Plastic Bottles:Medical-grade PVC and polypropylene formulations constitute the bulk of hospital inventory, with collapsible designs reducing air embolism risk during gravity-fed transfusions. Demand concentrates in United States trauma centers and German emergency services where weight reduction and breakage elimination outweigh material cost premiums.
- Blood Bags:Integrated collection-to-administration systems with inline leukoreduction filters capture the largest procurement volumes from national blood services. Japanese Red Cross Society and German centralized blood service tenders specify these configurations for apheresis and component therapy protocols, multiplying single-patient unit consumption.
- Glass Bottles:Borosilicate barriers retain niche positioning for plasma-derived biologics requiring oxygen impermeability that polymer alternatives cannot yet replicate.
- Sterile Bottles:Pre-sterilized single-use containers eliminate terminal sterilization steps for point-of-care blood warming applications.
Blood bags retain volume leadership; multilayer polypropylene coextrusion bottles hold the steepest expansion curve as seven-day platelet storage qualifications spread.
End User:
Customer concentration patterns separate high-volume tender-driven procurement from fragmented spot purchasing with diverging compliance thresholds.
- Hospitals:Tertiary surgical centers drive bulk consumption through group purchasing organization contracts bundling bottles with administration sets and filtration devices. United States hospital networks recovering elective procedure backlogs are restoring baseline transfusion demand trajectories.
- Blood Banks:National centralized services in Germany and Japan operate multi-year framework agreements locking in volume commitments and specification stability. These entities dictate industry standards through qualification protocols that smaller markets adopt by reference.
- Clinics:Outpatient transfusion centers favor smaller lot sizes with flexible delivery schedules.
- Diagnostic Laboratories:Quality control and research applications require traceable lot documentation and extended shelf-life guarantees.
Hospitals command procurement volume dominance; blood banks set the specification trajectory that upstream suppliers must follow.
Capacity:
Standardization pressures from blood collection protocols constrain format diversity despite emerging applications requiring volume flexibility.
- 500 mL:The dominant whole-blood collection specification aligns with international donor protocols and maximizes processing efficiency in component separation workflows. German and Japanese blood services specify this capacity for routine inventory rotation.
- 450 mL:Slightly reduced volume variants accommodate donor weight minimums in pediatric and geriatric collection programs without requiring separate processing line configurations.
- 250 mL:Pediatric and neonatal transfusion protocols use these formats for precise dosing control.
- 100 mL:Diagnostic and quality control applications drive demand for small-volume sterile containers.
- 50 mL:Research and specialized therapeutic apheresis procedures utilize these compact formats.
500 mL formats anchor procurement volumes; 250 mL capacities gain share fastest as pediatric transfusion protocols expand.
Certification:
Regulatory compliance tiers function as non-negotiable market entry barriers with escalating documentation requirements across jurisdictions.
- ISO Certified:ISO 3826 compliance for collapsible blood containers serves as the baseline qualification for European tender participation, with notified body relationships becoming competitive differentiators. EMA MDR deadlines have elevated these certifications from preference to mandatory gatekeeping.
- CE Marked:European Economic Area market access requires conformity assessment against medical device directives, with recent MDR transitions extending technical documentation requirements.
- FDA Approved:United States market entry demands biologics license application cross-references and sterilization validation studies.
- GMP Compliant:Pharmaceutical-grade manufacturing standards apply to containers intended for plasma-derived therapeutic production.
ISO certification anchors procurement specifications; CE marking complexity creates the steepest competitive filtration curve as MDR implementation extends.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EMA MDR compliance deadlines and FDA sterilization mandates are reshaping procurement specifications across major healthcare systems. National blood service tenders now prioritize ISO 3826-certified suppliers with established notified body relationships. Hospital network consolidation accelerates specification standardization in mature markets.
United States
Elective surgical volume recovery at tertiary hospital networks restores baseline transfusion demand trajectories. FDA blood and biologics regulations enforce gamma and electron-beam sterilization validation requirements that freeze formulation changes. The Gulf Coast petrochemical corridor concentrates medical-grade PVC resin supply, exposing converters to hurricane disruption risk.
Germany
Centralized blood service tenders favor vendors offering integrated collection-to-administration ecosystems. REACH polymer registration requirements force systematic substitution of ortho-phthalate plasticizers in PVC compounds. The Rhine-Ruhr industrial cluster hosts compounders resubmitting technical dossiers for citrate-based plasticizer alternatives.
Japan
Japanese Red Cross Society procurement cycles shifted from annual to multi-year framework agreements locking in volume commitments. PMDA quality management harmonization with European notified bodies streamlines dual-market entry pathways. The Kanto region around Tokyo anchors qualification protocols for seven-day platelet storage containers that smaller markets adopt by reference.
China
Hospital blood banking modernization drives specification upgrades for collection and storage containers. NMPA medical device registration requirements elevate documentation burdens for imported container systems. The Yangtze River Delta manufacturing base concentrates domestic producers seeking ISO certification for European tender participation.
India
Expanding apheresis and component therapy protocols multiply single-unit consumption per patient encounter. CDSCO medical device rules mandate quality management system compliance for sterile container imports. Maharashtra and Gujarat host emerging blood bank networks upgrading from glass to plastic collection systems.
Transfusion Bottles Market Competitive Landscape
On the supply side, the industry is consolidating around integrated therapy portfolios and specialized device ecosystems. Three-to-four approved vendors now dominate national tender categories in the United States and Germany. Two strategic archetypes prevail: diversified medical technology conglomerates with captive manufacturing, and focused infusion therapy specialists bundling bottles with administration sets. Competitive moves center on long-term supply contract anchoring and multi-year framework agreement locking.
Among diversified medical technology conglomerates, Fresenius Kabi AG and Baxter International Inc. exemplify the integrated plasma therapy portfolio archetype. B. Braun Melsungen AG occupies a position within the specialized infusion device ecosystem tier. These three entities represent the dominant competitive anchors in European and North American tender processes, with established notified body relationships functioning as non-negotiable qualification gatekeepers.
| Leading Market Players |
|---|
| Fresenius Kabi AG |
| Medtronic |
| B. Braun Melsungen AG |
| Smiths Medical |
| Nipro Corporation |
| Baxter International Inc. |
| ICU Medical Inc. |
| Gerresheimer |
| Becton, Dickinson and Company |
| Others |
Value Network & Pricing Analysis
Hurricane disruption risk across the Gulf Coast petrochemical corridor compresses supplier margins while amplifying price spreads between ISO-certified premium tiers and unvalidated alternatives. FDA sterilization validation requirements and EMA MDR compliance deadlines simultaneously elevate fixed qualification costs and reward incumbents with established notified body relationships.
Pricing Analysis
Certification level creates the primary spread between ISO 3826-validated premium tiers and standard-grade alternatives. Three-tier pricing structure across premium, standard, and economy levels reflects notified body audit depth, leachable testing rigor, and shelf-life guarantee duration. Cost compression in the standard tier is intensifying because REACH polymer registration mandates force ortho-phthalate plasticizer substitution. Blood banks and national centralized services demonstrate lowest price sensitivity due to multi-year framework agreement structures, while outpatient clinics and diagnostic laboratories exhibit highest sensitivity to per-unit procurement costs.
Supply Chain Analysis
Tariff exposure between United States and China compounds with single-source dependency on Gulf Coast medical-grade PVC resin production. Raw material feeds draw from Texas-Louisiana petrochemical clusters, German Rhine-Ruhr compounder networks, and Japanese Kanto region specialty polymer facilities. Formulation expertise for medical-grade leachable control represents the critical supply chain risk as legacy PVC compounders approach retirement. Distribution runs through group purchasing organization contracts bundling bottles with administration sets and filtration devices.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EMA MDR compliance deadlines and seven-day platelet storage container qualifications are reshaping competitive positioning in this high-growth disruption. Polymer substitution mandates and multilayer coextrusion advances create dual inflection points for material science differentiation.
For Market Incumbents: Harden notified body relationships through accelerated ISO 10993 biocompatibility testing investments before contract laboratory capacity constraints extend further. Lock in multi-year framework agreements with German centralized blood services and Japanese Red Cross Society procurement cycles. Vertical integration into citrate-based plasticizer compound production mitigates REACH registration cost volatility. For New Entrants and Emerging Players: Build out polypropylene coextrusion capabilities targeting seven-day platelet storage qualifications spreading from German and Japanese reference markets. Pediatric and neonatal transfusion protocols in India and China offer the most penetrable white-space segments upgrading from glass collection systems. Lead with ISO 3826 pre-certification to bypass European tender gatekeeping. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors diversified medical technology conglomerates with captive manufacturing and established regulatory affairs teams. Acquisition targets should demonstrate dual FDA-EMA qualification dossiers and active notified body relationships. Monitor polymer chemist talent scarcity and contract laboratory capacity utilization as inflection indicators for formulation bottleneck severity.| Strategic Initiative | Industry Significance |
|---|---|
| EMA MDR Compliance Pathway | Notified body relationships function as non-negotiable tender gatekeepers in German centralized procurement. |
| Polypropylene Coextrusion Scale-Up | Seven-day platelet storage qualifications in Japanese Red Cross Society protocols reshape inventory rotation standards. |
| Hospital System Partnership | Group purchasing organization bundling with administration sets locks in volume commitments across United States networks. |
| Citrate Plasticizer Formulation | REACH registration mandates force systematic substitution away from ortho-phthalate compounds in European-sourced PVC. |
| Dual-Market Qualification | PMDA harmonization with European notified bodies streamlines Japan-Germany entry pathways for emerging suppliers. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of FDA biologics license applications, EMA medical device directive filings, hospital procurement databases, and ISO certification registries. Blood bank procurement managers, biomedical engineers, polymer compounder technical directors, and GPO contracts managers provided operational validation. Customs and trade data, SEC 10-K medical device segment disclosures, and national blood service tender documentation anchored quantitative triangulation through bottom-up and top-down reconciliation.
Forecast inputs span product type segmentation across plastic bottles, blood bags, glass alternatives, and sterile formats; end-user categories separating hospital networks, blood banks, clinics, and diagnostic laboratories; capacity tiers from 50 mL research formats through 500 mL whole-blood standards; and certification levels distinguishing ISO, CE, FDA, and GMP compliance tiers. CAGRs were derived from surgical volume recovery trajectories, apheresis procedure expansion rates, and polymer substitution adoption curves across the projection horizon. Sterilization modality shifts and shelf-life validation timelines shaped scenario-weighted outcomes.
Stress conditions across Gulf Coast hurricane frequency, REACH polymer registration enforcement intensity, and contract laboratory capacity utilization were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding EMA MDR implementation pacing and FDA sterilization validation requirement stability. Macroeconomic contraction affecting elective surgical volumes, regulatory harmonization reversal, or breakthrough glass-barrier polymer alternatives would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Supplies
Disposable Hospital Gowns Market
Medical Supplies
Healthcare Cleanroom Consumables Market
Medical Supplies
Biodegradable Hemostat Market
Medical Supplies
Measured Volume Burette Set Market
Medical Supplies
Demulcent Eye Drops Market
Medical Supplies
Therapeutic Elastic Tapes Market
Medical Supplies
Blood Collection Tubes for Liquid Biopsy Market
Medical Supplies
Cryotubes Market
Medical Supplies
Cosmetic Pipette Market
Medical Supplies
Urine Meter Trays Market
Medical Supplies
Surgical Sealant and Adhesive Market
Medical Supplies
Disposable Face Mask Market
Medical Supplies
Medical Swabs Market
Medical Supplies
Anti Venom Market
Medical Supplies
Global Hospital Supplies Market
Medical Supplies
Global Unna Boot Market