
 Global Pulmonary Drug Delivery Systems Market | 2026-2036
Global Pulmonary Drug Delivery Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Global Pulmonary Drug Delivery Systems Market Foresight
Modular drug-device combinations is expanding as pharmaceutical firms unbundle nebulizer hardware from drug cartridges to lower patient switching costs. AstraZeneca leverages its biologics pipeline to anchor high-value combination products across hospital networks. GlaxoSmithKline sustains R&D intensity in particle engineering for dry powder formulations. Boehringer Ingelheim differentiates through geographic dominance in European respiratory care channels.
Pulmonary drug delivery systems administer therapeutic agents directly to lung tissue via inhalation devices engineered to achieve particle sizes between one and five micrometers for optimal alveolar deposition. Metered dose inhalers retain the largest installed base among product types, though soft mist inhalers are gaining share where hand-breath coordination challenges limit traditional pressurized device use. Smart inhalers with Bluetooth connectivity and dose tracking represent the fastest-growing technology segment as payers demand adherence data, while jet nebulization remains mature in institutional settings where lowest-cost aerosol generation suffices.
FDA enforces combination product regulations that require simultaneous drug and device approval, lengthening development timelines but raising barriers to generic entry. EMA's Medical Device Regulation and ISO 20072 standards for inhaler testing shape European market access and interoperability requirements. REACH compliance on propellant chemistry constrains reformulation options for pressurized devices. Stakeholders must monitor evolving bioequivalence protocols for complex generics and position manufacturing assets to serve both regulated Western markets and cost-sensitive Asian healthcare systems.
Market Dynamics
FDA combination product regulations and EMA's MDR framework are compressing development timelines while simultaneously elevating technical barriers for market entry across nebulizer and inhaler platforms.
Growth Catalysts
- EMA Medical Device Regulation:Harmonized testing protocols under ISO 20072 are streamlining cross-border approvals for European respiratory device manufacturers.
- Home healthcare expansion:Portable nebulizer demand from post-acute care providers is accelerating device miniaturization and battery chemistry investments.
- Smart inhaler connectivity:Bluetooth-enabled dose tracking is reshaping payer reimbursement models by generating adherence data for value-based contracts.
Market Restraints
- Hydrofluoroalkane propellant constraints:REACH compliance on propellant chemistry limits reformulation pathways for pressurized metered dose inhalers.
- Device-drug approval synchronization:FDA's simultaneous review requirement extends regulatory timelines and compounds development risk for combination products.
- Particle engineering specialization:Dry powder formulation expertise concentrates among a limited supplier base in Germany and Switzerland.
Strategic Opportunities
- Japan's aging respiratory patient pool:METI-supported telehealth infrastructure creates distribution channels for connected inhaler platforms in Tokyo and Osaka healthcare networks.
- Complex generic bioequivalence protocols:Evolving FDA guidance on therapeutic equivalence for inhaled products opens pathways for differentiated generic entry.
- Modular drug-cartridge unbundling:Separating nebulizer hardware from drug reservoirs reduces patient switching costs and enables subscription-based revenue models.
Industry Challenges
- Aerosol physicist talent scarcity:Specialized expertise in lung deposition modeling and cascade impaction testing concentrates within academic medical centers and contract research organizations.
- Legacy hospital procurement systems:Integration of smart inhaler data streams with existing electronic health record architectures requires customized middleware development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Pulmonary Drug Delivery Systems Market |
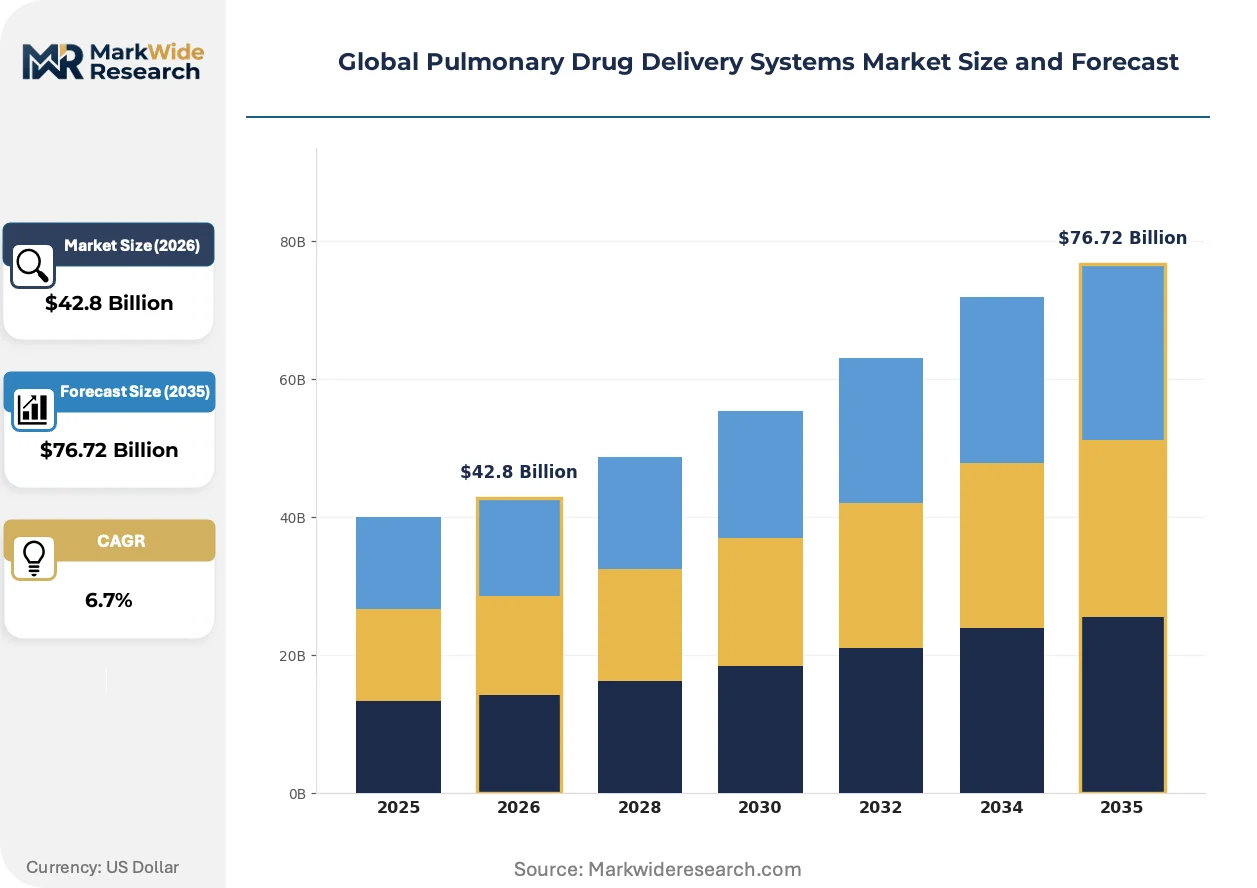
| Market Size in 2026 | $42.8 Billion |
| Market Size in 2035 | $76.72 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Metered Dose Inhalers, Dry Powder Inhalers, Nebulizers, Soft Mist Inhalers Technology: Particle Engineering, Smart Inhalers, Breath-Actuated Devices, Ultrasonic Nebulization, Jet Nebulization Application: Asthma, Chronic Obstructive Pulmonary Disease, Cystic Fibrosis, Pulmonary Arterial Hypertension, Bronchiectasis End User: Specialty Clinics, Respiratory Care Centers, Ambulatory Care Centers, Home Healthcare Providers |
| Companies Covered | AstraZeneca, GlaxoSmithKline, Boehringer Ingelheim, Novartis, 3M, Koninklijke Philips, PARI, OMRON Healthcare, AptarGroup, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Pulmonary Drug Delivery Systems Market Shifts & Advancements
Connectivity architectures and particle engineering advances are restructuring competitive advantage around data generation capabilities rather than hardware manufacturing scale alone.
Soft mist inhaler technology is automating aerosol generation without pressurized propellants, eliminating hand-breath coordination barriers that limit traditional metered dose device effectiveness. Pediatric and geriatric patient segments in German and Japanese hospital networks are adopting these platforms at accelerated rates. The technology is automating dose consistency validation and reducing training burden on respiratory therapists.
REACH F-Gas Regulation and EPA propellant phase-down mandates are forcing wholesale transitions away from hydrofluoroalkane formulations in pressurized devices. Dry powder and soft mist platforms capture displaced volume as manufacturers suspend legacy product lines. European contract manufacturers are retooling filling lines to accommodate alternative propulsion chemistries and powder blending operations.
Home healthcare providers are consolidating purchasing decisions around device ecosystems that integrate with remote patient monitoring platforms. Traditional durable medical equipment distributors face disintermediation as hospital systems establish direct procurement relationships with combination product manufacturers. United States post-acute care networks and German ambulatory respiratory clinics exhibit the most pronounced channel restructuring.
Global Pulmonary Drug Delivery Systems Market Segmentation
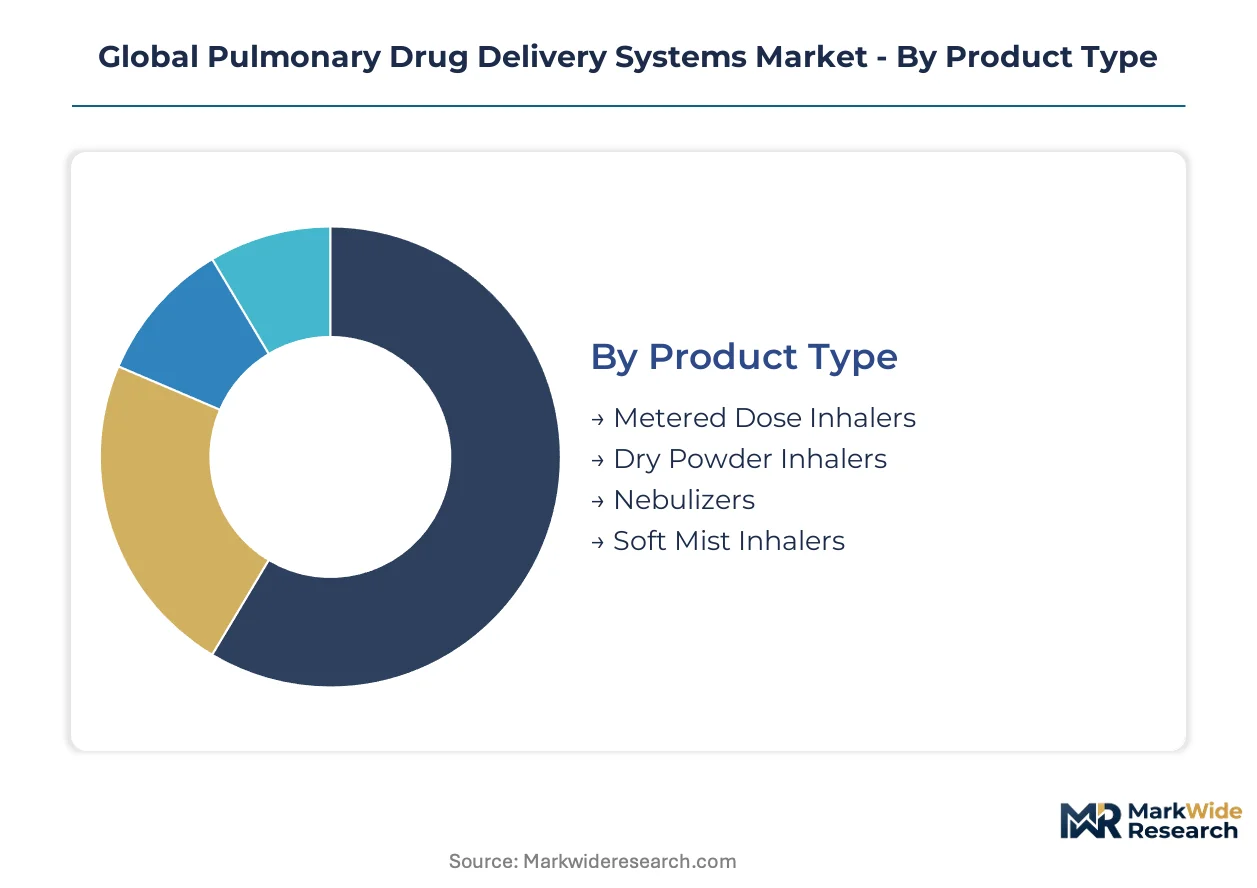
Product configuration, connectivity architecture, and care setting economics create distinct competitive battlegrounds across pulmonary delivery platforms. Each segmentation dimension reveals divergent margin structures and regulatory exposure profiles that reshape manufacturer positioning strategies.
Product Type:
Hospital procurement teams prioritize device reliability and total cost of ownership when selecting inhalation platforms across acute and ambulatory settings.
- Metered Dose Inhalers:Pressurized canister systems deliver precise aliquots of suspended drug using hydrofluoroalkane propellants. Demand concentrates in United States managed care networks where formulary placement depends on generic substitution economics and FDA bioequivalence pathways.
- Soft Mist Inhalers:Spring-mechanized aerosol generation eliminates hand-breath coordination requirements through slow-velocity mist delivery. German and Japanese respiratory clinics are adopting these platforms fastest where geriatric patient compliance drives reimbursement decisions.
- Dry Powder Inhalers:Breath-activated systems rely on patient inspiratory force for deaggregation and lung deposition.
- Nebulizers:Compressor-driven or vibrating mesh devices convert liquid formulations into respirable aerosols for patients unable to use handheld inhalers.
Volume sits with metered dose inhalers; growth tilts toward soft mist inhalers.
Technology:
Reimbursement data requirements and manufacturing scalability determine which technical approaches capture capital investment from device developers.
- Smart Inhalers:Bluetooth-enabled dose counters and adherence sensors transmit usage patterns to cloud-based platforms. United States payers are mandating connectivity for value-based contracting in post-acute respiratory management programs.
- Particle Engineering:Spray drying and micronization techniques control aerodynamic diameter and dispersibility for optimal alveolar deposition. Swiss and German contract manufacturers concentrate specialized capacity for high-potency biologic formulations.
- Breath-Actuated Devices:Mechanical triggers synchronize drug release with patient inhalation to reduce oropharyngeal deposition.
- Ultrasonic Nebulization:Piezoelectric vibration generates aerosol without compressors, enabling portable battery-operated designs.
- Jet Nebulization:Compressed gas shears liquid into droplets through baffle impaction for lowest-cost institutional applications.
Installed base concentrates in jet nebulization; expansion is accelerating most quickly in smart inhalers.
Application:
Disease prevalence trajectories and therapy duration shape addressable market calculations across respiratory indications.
- Chronic Obstructive Pulmonary Disease:Progressive airflow limitation requires long-acting bronchodilator maintenance and acute rescue therapy. United States Medicare spending on COPD hospitalizations is concentrating demand around devices that reduce exacerbation frequency.
- Asthma:Reversible airway inflammation affects pediatric and adult populations with variable control needs. Japanese school-based screening programs and German ambulatory networks are expanding controller therapy penetration.
- Cystic Fibrosis:Thick mucus accumulation necessitates mucolytic and antibiotic delivery via nebulization.
- Pulmonary Arterial Hypertension:Prostacyclin analog delivery requires specialized inhalation systems for continuous therapy.
- Bronchiectasis:Permanent airway dilation demands chronic airway clearance and anti-infective administration.
Patient volume clusters in asthma; therapeutic intensity is climbing the fastest in pulmonary arterial hypertension.
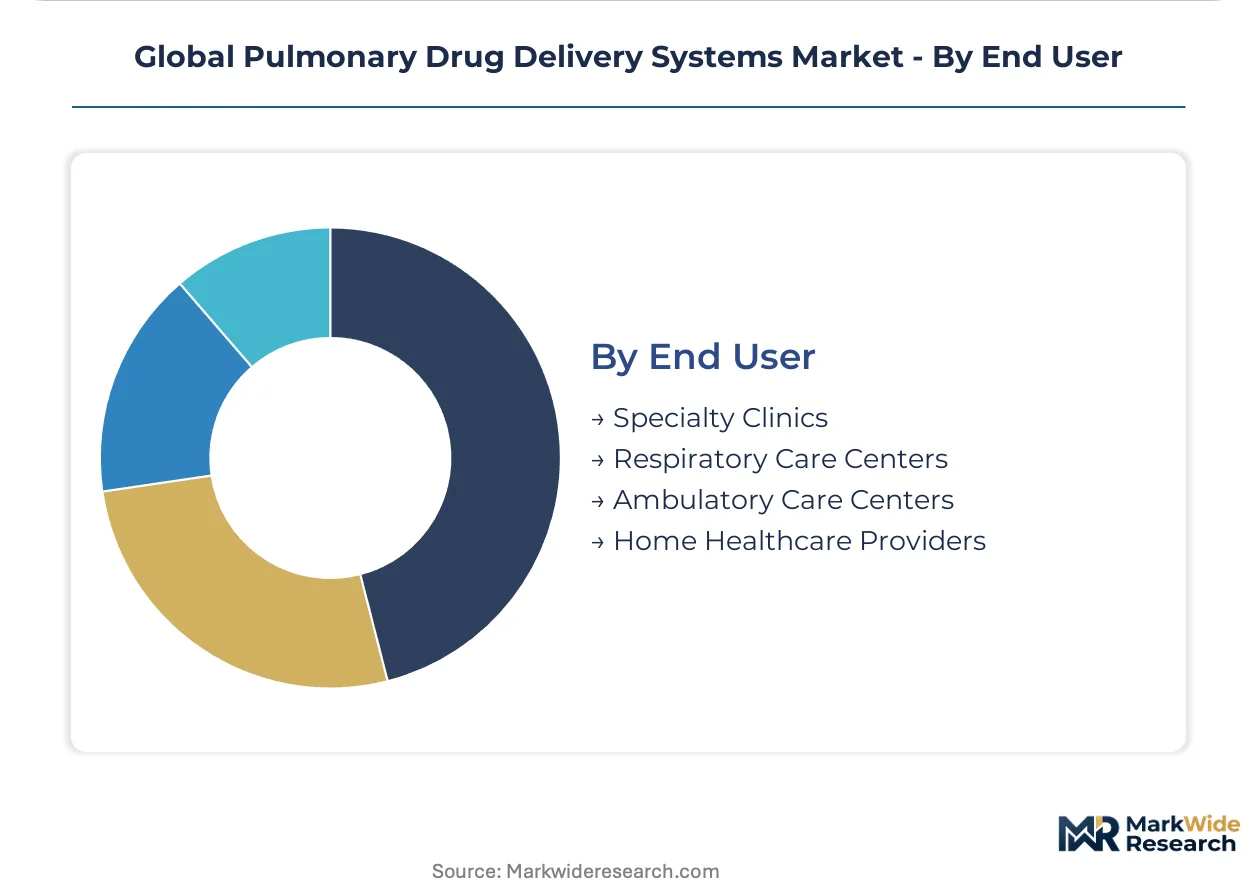
End User:
Care site economics and staffing models dictate device complexity tolerances and service bundling requirements.
- Home Healthcare Providers:Post-acute and long-term care services manage chronic respiratory patients outside institutional settings. United States home health agencies are consolidating purchasing around portable nebulizers with remote monitoring integration.
- Specialty Clinics:Pulmonology-focused practices deliver diagnosis, staging, and maintenance therapy for complex respiratory disease. German ambulatory respiratory clinics are deploying connected inhaler platforms to track patient adherence between visits.
- Respiratory Care Centers:Dedicated facilities provide pulmonary rehabilitation and acute exacerbation management.
- Ambulatory Care Centers:General outpatient settings handle initial diagnosis and routine follow-up for stable patients.
Procurement volume concentrates in specialty clinics; channel expansion is gaining share fastest in home healthcare providers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production of pulmonary drug delivery hardware concentrates in Germany and Switzerland, while consumption volumes concentrate in the United States and Japan where aging populations and reimbursement infrastructure drive device procurement at scale.
United States
Medicare spending on COPD hospitalizations is concentrating procurement decisions around devices that reduce exacerbation frequency. FDA combination product regulations enforce simultaneous drug and device approval, extending development timelines but raising barriers to generic entry for manufacturers targeting managed care networks. Boston and San Francisco medical technology clusters house specialized aerosol physicist talent for lung deposition modeling.
Germany
German ambulatory respiratory clinics are deploying connected inhaler platforms to track patient adherence between visits, driving demand for Bluetooth-enabled systems. EMA's Medical Device Regulation and ISO 20072 standards shape European market access requirements for inhaler testing protocols. The Baden-Württemberg and Bavaria industrial corridors concentrate particle engineering expertise for dry powder formulation manufacturing.
Japan
METI-supported telehealth infrastructure creates distribution channels for connected inhaler platforms in Tokyo and Osaka healthcare networks, where aging respiratory patient pools expand addressable markets. PMDA quality standards for bioequivalence align with FDA pathways, enabling streamlined dual-market registration for combination products. The Kanto region anchors domestic manufacturing of portable nebulizer systems for home healthcare expansion.
Switzerland
Swiss contract manufacturers concentrate specialized capacity for high-potency biologic formulations using spray drying and micronization techniques. Swissmedic regulations on device interoperability complement EMA frameworks, positioning the country as a regulatory bridge for Western European market access. Basel and Zurich clusters host formulation development services for complex generic bioequivalence protocols.
United Kingdom
NHS long-term plan commitments to respiratory disease management are scaling procurement of smart inhalers with adherence tracking capabilities. MHRA post-Brexit regulatory alignment with FDA and EMA pathways creates dual-registration efficiencies for manufacturers targeting both UK and EU markets. The Cambridge-Oxford-London life sciences triangle supports device connectivity architecture development for cloud-based patient monitoring platforms.
Global Pulmonary Drug Delivery Systems Market Competitive Landscape
The competitive structure tilts toward diversified pharmaceutical conglomerates with captive device manufacturing capabilities. Market concentration remains elevated among firms controlling both drug formulation intellectual property and inhaler hardware design. Three archetypes dominate: integrated pharma-device combinations, specialized respiratory-focused divisions, and contract manufacturing organizations with particle engineering expertise. Competitive moves center on modular drug-cartridge unbundling to enable subscription revenue models and strategic partnerships with home healthcare distributors to bypass traditional durable medical equipment channels.
Among the integrated pharmaceutical tier, AstraZeneca, GlaxoSmithKline, and Boehringer Ingelheim exemplify divergent strategic positioning. AstraZeneca leverages biologics pipeline depth to anchor high-value combination products across hospital networks. GlaxoSmithKline sustains research intensity in particle engineering for dry powder formulations. Boehringer Ingelheim occupies a position of geographic dominance in European respiratory care channels. These three firms represent the archetype of drug-centric competitive advantage where device capabilities serve formulation delivery requirements rather than standalone hardware margins.
| Leading Market Players |
|---|
| AstraZeneca |
| GlaxoSmithKline |
| Boehringer Ingelheim |
| Novartis |
| 3M |
| Koninklijke Philips |
| PARI |
| OMRON Healthcare |
| AptarGroup |
| Others |
Supply & Pricing Matrix
Captive manufacturing of inhaler hardware by pharmaceutical conglomerates anchors supply positions and preserves pricing power through FDA combination product exclusivity. This integration pattern limits contract manufacturer leverage while concentrating margin capture among firms controlling both drug formulation IP and device design.
Pricing Analysis
Margin tightening in standard-tier devices reflects REACH propellant phase-down costs and generic substitution economics in United States managed care networks. Three-tier pricing structure across premium connected inhalers, standard breath-actuated systems, and economy jet nebulizers stratifies by certification grade and after-sales service bundling. Hospital procurement committees exhibit highest price sensitivity, while specialty clinics accepting value-based contracts show lowest sensitivity due to adherence data monetization. Cost-down pressure on pressurized metered dose inhalers accelerates because hydrofluoroalkane reformulation expenses compound with bioequivalence testing burdens.
Supply Chain Analysis
ISO 20072 certification gating concentrates component supply among German, Swiss, and United States contract manufacturers with validated cascade impaction testing capabilities. Piezoelectric mesh membranes, hydrofluoroalkane propellants, and spray-dried lactose carriers constitute critical input dependencies. Single-source vulnerability persists for high-potency biologic formulation capacity in Basel and Baden-Württemberg clusters. Distribution runs through hospital system direct procurement channels and home healthcare agency consolidators, bypassing traditional durable medical equipment distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market consolidates around combination product expertise as FDA simultaneous review requirements force capital-constrained device specialists toward acquisition or exit.
For Market Incumbents: Acquire aerosol physicist talent pools and validated particle engineering facilities to defend against emerging modular drug-cartridge entrants. Backward integration into vibrating mesh nebulizer component manufacturing reduces single-source exposure from East Asian suppliers. Priority investment in Bluetooth connectivity architecture preserves value-based contracting eligibility with United States payers. For New Entrants and Emerging Players: Home healthcare agencies represent the most penetrable channel partner type for portable nebulizer platforms with remote monitoring integration. White-space targets include Japanese post-acute networks and German ambulatory respiratory clinics deploying adherence-tracking systems. Go-to-market execution should emphasize subscription-based hardware-plus-consumables models to reduce upfront capital barriers for price-sensitive buyers. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by pharmaceutical conglomerates seeking captive device capabilities for biologics pipelines. Long-term viability favors contract manufacturers with ISO 20072-validated testing infrastructure and established EMA regulatory consulting relationships. The signal to watch is FDA guidance evolution on complex generic bioequivalence protocols, which would revalue specialized formulation development assets.| Strategic Initiative | Industry Significance |
|---|---|
| Modular Drug-Cartridge Unbundling | Subscription revenue models reduce patient switching costs and lock in recurring consumables demand. |
| Smart Inhaler Connectivity Investment | Bluetooth-enabled adherence data satisfies United States payer requirements for value-based respiratory contracts. |
| Particle Engineering Capacity Expansion | Spray drying and micronization capabilities in Switzerland and Germany capture high-potency biologic formulation demand. |
| Hospital System Direct Partnership | Bypassing durable medical equipment distributors preserves margin and enables EHR integration customization. |
| REACH Compliance Reformulation | Transition from hydrofluoroalkane propellants to dry powder and soft mist platforms avoids regulatory obsolescence. |
Research Methodology
Independent corroboration across regulatory filings, hospital procurement databases, and contract manufacturer capacity disclosures underwrites the qualitative findings. Primary interviews with regulatory affairs leads at combination product firms, formulary directors at United States payers, hospital procurement managers, and biomedical engineers at German respiratory clinics were validated against secondary sources including FDA 510(k) submissions, EMA Medical Device Regulation guidance documents, ClinicalTrials.gov entries, and ISO 20072 testing protocols. Bottom-up patient volume estimates and top-down pharmaceutical R&D expenditure analysis were triangulated to cross-validate market sizing.
Comparable-period anchoring to historical regulatory approval timelines and reimbursement policy shifts structured the forecast window across the projection horizon. Segmentation modeling incorporated product type, connectivity architecture, application indication, and care setting economics dimensions. CAGRs were derived from patient population epidemiology trajectories, therapy penetration assumptions, and device replacement cycle analysis. Forecast inputs included Medicare COPD hospitalization expenditure trends and METI telehealth infrastructure deployment schedules.
Caveats apply where FDA bioequivalence protocol revisions or EMA MDR enforcement intensity changes could materially shift the outlook. Forecasts reflect assumptions regarding propellant chemistry transition timelines and home healthcare reimbursement stability. A model refresh is warranted upon material change in combination product regulatory harmonization between FDA and PMDA pathways.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Toe Fixation System Market
Medical Devices
Coronary Guidewires Market
Medical Devices
Medical Device Regulatory Affairs Market
Medical Devices
North America Medical Device Regulatory Affairs Market
Medical Devices
Global Pulse Oximetry Market
Medical Devices
Capnography Devices Market
Medical Devices
Brazil Aesthetic Equipment Market
Medical Devices
Endoscope Reprocessing Device Market
Medical Devices
Medical Manifolds Market
Medical Devices
Medical Fiber Optics Market
Medical Devices
MRI-Guided Radiation Therapy Systems Market
Medical Devices
Laparoscopic Surgical Robot Market
Medical Devices
Prefilled Syringe Small Molecule Market
Medical Devices
Urine Collection Devices Market
Medical Devices
Global Self Care Medical Devices Market
Medical Devices
Oxygen Conserving Devices Market