
 Pressure Monitoring Extension Tubing Sets Market | 2026-2036
Pressure Monitoring Extension Tubing Sets Market Size, Share, and Industry Trends Forecast 2026-2036
Pressure Monitoring Extension Tubing Sets Market Analytics
The divergence between premium silicone-based sets and commodity PVC tubing is repositioning procurement criteria across acute care settings. Smiths Medical leverages its integrated catheter-tubing platform to sustain pricing power in hemodynamic monitoring suites. Merit Medical competes through specialized anesthesia tubing configurations that anchor its presence in ambulatory surgical centers. B. Braun Melsungen AG dominates European hospital contracts through backward integration into medical-grade polymer compounding.
Pressure monitoring extension tubing sets are sterile, single-use conduits—typically 12–60 inches in length with male/female Luer lock terminations—engineered to transmit physiologic pressure signals from vascular access devices to transducer systems without compliance artifact or air entrapment. Polyurethane formulations lead in coronary care applications due to kink resistance and biocompatibility, while PVC retains volume in standard intravenous therapy where cost sensitivity governs purchasing. Multi-lumen configurations represent the fastest-growing product architecture as cath labs and ICUs consolidate multiple infusion and monitoring lines through single access points.
The US FDA's 510(k) program and the European Union's Medical Device Regulation (MDR) impose divergent clinical evidence requirements that fragment registration strategies for tubing manufacturers. ISO 80369 small-bore connector standards are forcing design modifications to prevent misconnection events across anesthesia and hemodynamic monitoring applications. Stakeholders must monitor how the EU's F-Gas Regulation affects fluoropolymer liner availability for specialized pressure relief tubing sets.
Market Dynamics
The consolidation of vascular access lines into single insertion sites is restructuring product specifications across hemodynamic monitoring, with multi-lumen tubing configurations now commanding priority in ICU and cath lab procurement protocols.
Growth Catalysts
- ICU capacity expansion:Tertiary hospitals in the United States and Germany are adding monitored beds equipped for invasive pressure monitoring, directly lifting tubing set consumption per facility.
- FDA 510(k) pathway streamlining:The US FDA's updated clearance protocols for Class II cardiovascular devices are compressing registration timelines and accelerating new product introductions.
- Polyurethane material advances:Enhanced kink resistance and signal fidelity in coronary care applications are displacing legacy PVC configurations in high-acuity settings.
Market Restraints
- Medical-grade polymer feedstock volatility:Price swings in specialized polyurethane resins are compressing margin stability for tubing converters without captive compounding capabilities.
- Freiburg-Heidelberg supply concentration:Germany's catheter manufacturing clusters create geographic vulnerability for European hospital supply security during logistics disruptions.
- ISO 80369 redesign mandates:Small-bore connector standardization is forcing non-recurring engineering costs across existing product portfolios.
Strategic Opportunities
- Ambulatory surgical center penetration:United States outpatient facilities remain underpenetrated for advanced pressure monitoring relative to inpatient surgical volumes.
- EU MDR clinical evidence pathways:The European Union's Medical Device Regulation creates first-mover advantage for manufacturers with robust technical documentation.
- Anesthesia tubing-hemodynamic convergence:Integration of pressure monitoring with anesthesia delivery systems opens cross-selling potential in integrated OR suites.
Industry Challenges
- Biocompatibility testing backlog:ISO 10993 cytotoxicity and sensitization studies are creating bottlenecks in product release cycles.
- Legacy transducer interface compatibility:New tubing designs must maintain signal integrity with installed base monitoring systems from multiple vendors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pressure Monitoring Extension Tubing Sets Market |
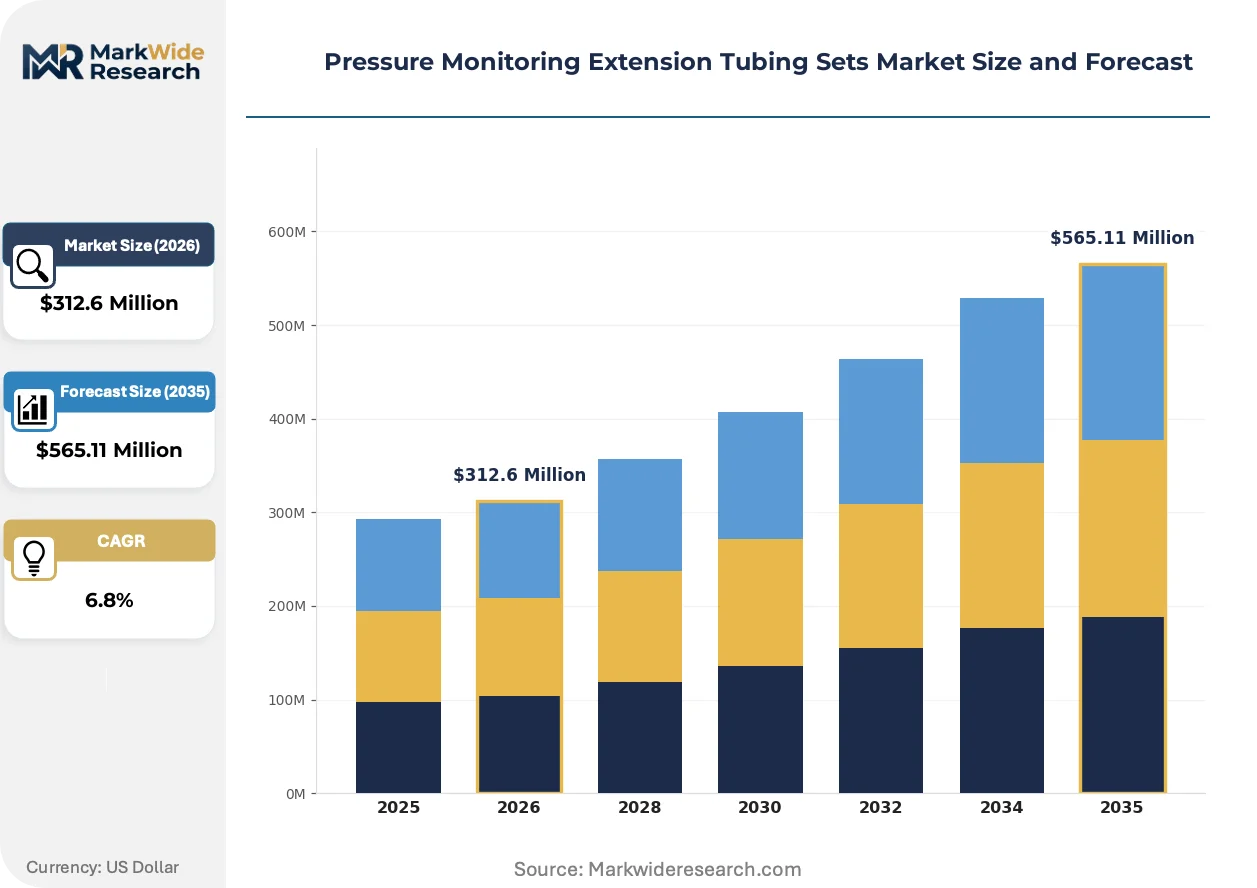
| Market Size in 2026 | $312.6 Million |
| Market Size in 2035 | $565.11 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single-Lumen, Multi-Lumen, Pressure Relief, Extension Set Material: Polyvinyl Chloride, Polyurethane, Silicone, Latex Application: Intravenous Therapy, Anesthesia, Hemodynamics Monitoring, Blood Transfusion End User: Hospitals, Clinics, Home Healthcare, Ambulatory Surgical Centers |
| Companies Covered | Smiths Group, Angiplast, Merit Medical, Poly Medicure, Polymed Medical, Medtronic, B. Braun Melsungen AG, Smiths Medical, Teleflex Incorporated, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pressure Monitoring Extension Tubing Sets Market Evolving Landscape
Material science advances and connector standardization are converging to redefine performance benchmarks, with manufacturers racing to capture premium positioning through differentiated compliance profiles and integrated platform designs.
Multi-lumen architectures are overtaking single-channel configurations in high-acuity settings by enabling simultaneous pressure monitoring, medication infusion, and blood sampling through one vascular access point. Cath labs and cardiac ICUs in the United States and Germany are specifying these configurations as default requirements. This shift is compressing demand for standalone single-lumen sets and rewarding manufacturers with integrated catheter-tubing platforms.
The European Union's F-Gas Regulation is restricting availability of fluoropolymer liners used in specialized pressure relief tubing sets, forcing reformulation toward alternative barrier materials. German and Swiss manufacturers with in-house polymer compounding capabilities are adapting faster than converters dependent on external fluoropolymer supply. High-pressure applications in interventional cardiology are experiencing the most acute material substitution pressures.
Hospital procurement departments are consolidating tubing set purchasing into multi-year framework agreements with integrated device suppliers, displacing spot-market purchasing and distributor-centric sourcing models. This concentration favors vendors with broad vascular access portfolios capable of serving entire catheterization service lines. The United States health system consolidation is accelerating this behavioral shift fastest among GPO-affiliated facilities.
Pressure Monitoring Extension Tubing Sets Market Segmentation
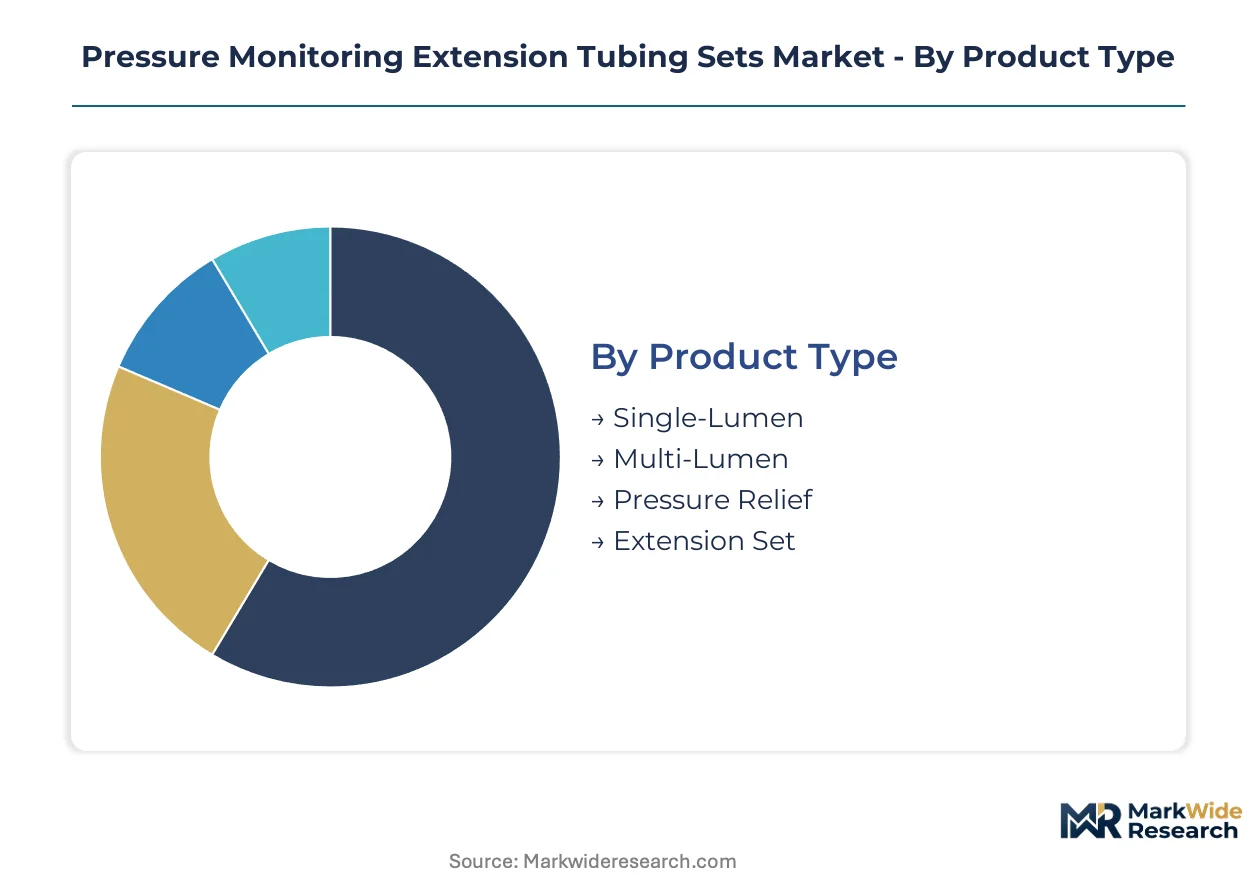
Product architecture and material selection in pressure monitoring tubing sets directly determine signal fidelity, kink resistance, and procurement tier placement across acute care settings. Segment boundaries are hardening as ICU consolidation and cath lab integration reshape specification requirements.
Product Type:
Volume concentration sits with single-lumen sets, while premium positioning clusters around multi-lumen and specialized configurations.
- Single-Lumen:Basic pressure transmission conduit with one fluid channel and standard Luer lock terminations. Demand concentrates in general medical-surgical floors and standard IV therapy settings where cost sensitivity governs purchasing decisions.
- Multi-Lumen:Integrated architecture enabling simultaneous pressure monitoring, medication infusion, and blood sampling through single vascular access. Cath labs and cardiac ICUs in the United States and Germany are specifying these as default requirements, compressing demand for standalone single-lumen alternatives.
- Pressure Relief:Specialized sets incorporating pressure-limiting valves for high-risk interventional procedures.
- Extension Set:Bridge configurations connecting vascular access devices to transducer systems at extended distances.
Mature deployment sits with single-lumen configurations. Newer deployment is concentrated in multi-lumen architectures.
Material:
Performance tiering separates kink-resistant premium formulations from commodity alternatives, with regulatory pressure accelerating substitution timelines.
- Polyvinyl Chloride:Lowest-cost option retaining volume in standard intravenous therapy where signal precision requirements are less stringent. Procurement departments in cost-constrained facilities continue specifying PVC for non-critical monitoring applications despite biocompatibility limitations.
- Polyurethane:Thermoplastic elastomer delivering superior kink resistance and pressure signal fidelity. Coronary care units and hemodynamic monitoring suites in tertiary hospitals are displacing legacy PVC with polyurethane as default material specifications tighten.
- Silicone:Platinum-cured formulation offering maximum biocompatibility and temperature stability for extended indwelling applications.
- Latex:Natural rubber compound with declining utilization due to allergen concerns and regulatory restrictions.
Procurement gravity centers on polyurethane for new ICU installations. PVC maintains installed-base replacement demand.
Application:
Clinical setting intensity determines specification grade, with invasive monitoring applications commanding material and connector premium tiers.
- Intravenous Therapy:Standard fluid administration and basic pressure monitoring in general ward settings. Volume concentration in this segment reflects routine hospital admissions across community and tertiary facilities.
- Hemodynamics Monitoring:Invasive arterial and central venous pressure measurement requiring artifact-free signal transmission. Cardiac ICUs and surgical intensive care units in the United States specify medical-grade polyurethane with anti-kink reinforcement as standard.
- Anesthesia:Operating room pressure monitoring integrated with anesthesia delivery workstations.
- Blood Transfusion:Specialized sets with filtered connectors and compatibility with rapid infusion systems.
Specification maturity is highest in hemodynamics monitoring. Fastest specification evolution is occurring in anesthesia-hemodynamic convergence applications.
End User:
Facility type dictates purchasing consolidation patterns, with integrated health systems favoring single-source vascular access contracts over distributor fragmentation.
- Hospitals:Tertiary medical centers with catheterization laboratories and level-1 trauma capabilities. Multi-year framework agreements with integrated device suppliers are displacing spot-market purchasing across GPO-affiliated facilities in the United States.
- Ambulatory Surgical Centers:Outpatient surgical facilities with growing penetration of advanced pressure monitoring relative to inpatient volumes. United States ASCs remain underpenetrated for hemodynamic monitoring suites compared to hospital-based surgical volumes.
- Clinics:Outpatient diagnostic and minor procedure settings with limited invasive monitoring requirements.
- Home Healthcare:Residential care settings with specialized requirements for patient-managed pressure monitoring.
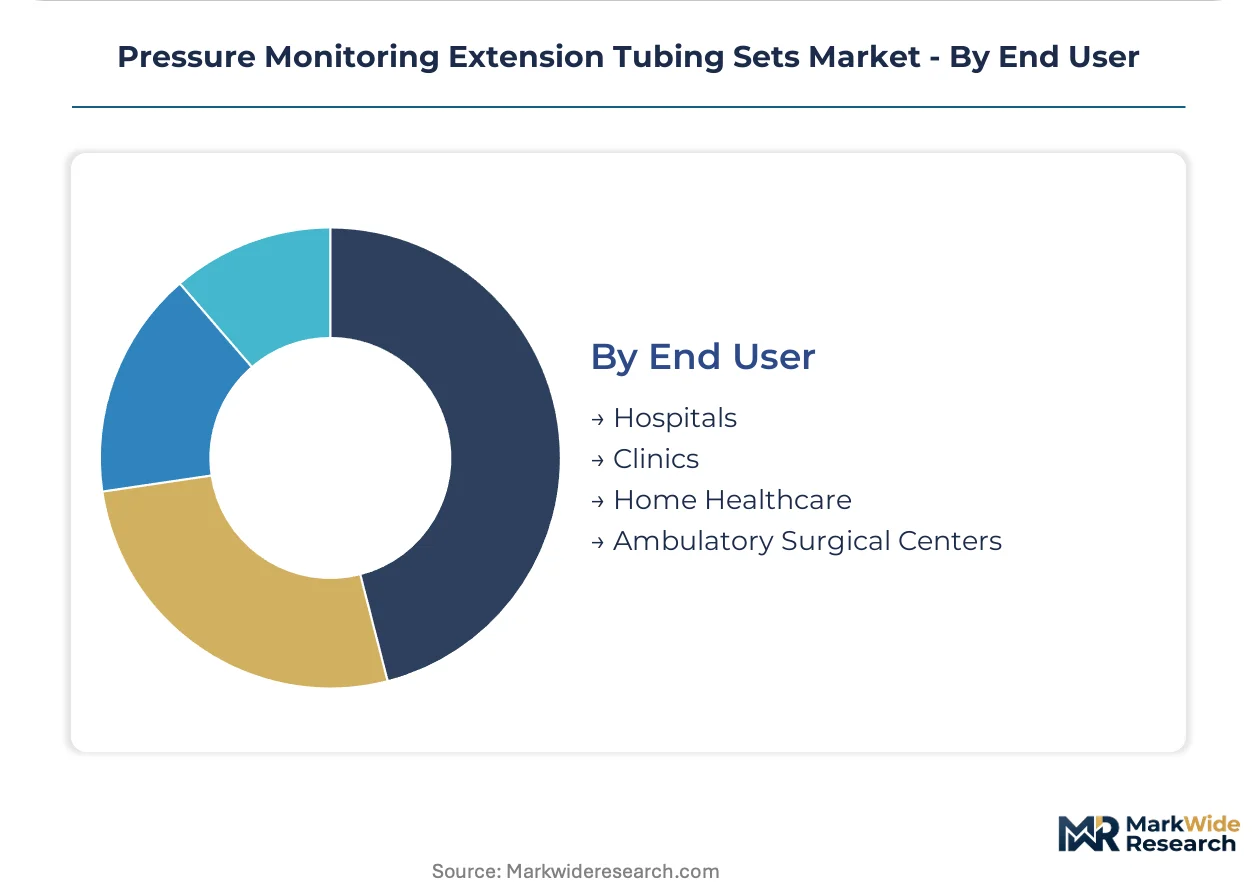
Contract consolidation is most advanced in hospitals. Penetration expansion is concentrated in ambulatory surgical centers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Freiburg and Heidelberg anchor European catheter manufacturing, while tertiary hospital expansion in the United States and Germany drives multi-lumen tubing adoption. Regulatory divergence between FDA 510(k) pathways and EU MDR compliance timelines fragments registration strategies across major markets.
United States
ICU capacity expansion at tertiary medical centers lifts consumption of polyurethane-based sets for invasive hemodynamic monitoring. The FDA's streamlined 510(k) clearance protocols for Class II cardiovascular devices compress registration timelines for new product introductions. Hospital procurement consolidation through GPO-affiliated facilities in the Midwest and Southeast is displacing spot-market purchasing with multi-year framework agreements.
Germany
Catheter manufacturing clusters around Freiburg and Heidelberg concentrate European supply for medical-grade polymer compounding and precision extrusion. The EU's F-Gas Regulation restricts fluoropolymer liner availability, forcing rapid reformulation toward alternative barrier materials for high-pressure interventional applications. Backward integration into captive polymer production distinguishes domestic manufacturers from external converters.
China
Domestic hospital infrastructure expansion accelerates demand for standard PVC configurations in provincial medical centers. The National Medical Products Administration (NMPA) imposes clinical evidence requirements that extend registration timelines relative to Western jurisdictions. Manufacturing gravity clusters in the Yangtze River Delta around Shanghai and Suzhou for export-oriented tubing conversion.
Japan
Aging demographics and cardiac procedure volumes sustain demand for premium silicone and polyurethane formulations in university hospitals. The Pharmaceuticals and Medical Devices Agency (PMDA) maintains stringent biocompatibility testing protocols that extend product release cycles. Industrial concentration in the Kansai region around Osaka supports precision medical device component fabrication.
India
Cost-sensitive public hospital procurement sustains volume demand for PVC-based standard configurations. The Central Drugs Standard Control Organization (CDSCO) regulates Class C and D medical devices with evolving technical documentation requirements. Manufacturing activity concentrates in Gujarat and Maharashtra for export-oriented disposable medical device production.
Pressure Monitoring Extension Tubing Sets Market Competitive Landscape
Premium-margin players sit above commodity-margin players across material sophistication and integrated platform capabilities. The vendor base stratifies into three tiers: multinational device conglomerates with captive tubing operations, specialized catheter-tubing integrators, and regional converters dependent on external polymer supply. Two dominant competitive moves define current positioning: backward integration into medical-grade polymer compounding to secure feedstock stability, and portfolio diversification into multi-lumen architectures to capture ICU and cath lab procurement consolidation.
Within the integrated platform tier, Smiths Medical and B. Braun Melsungen AG exemplify divergent geographic anchoring and supply chain configuration. Merit Medical occupies a position bridging specialized anesthesia configurations with hemodynamic monitoring convergence. Teleflex Incorporated represents the multinational device conglomerate archetype with broad vascular access portfolio breadth. Medtronic sits within the scale-driven tier leveraging global hospital system relationships.
| Leading Market Players |
|---|
| Smiths Group |
| Angiplast |
| Merit Medical |
| Poly Medicure |
| Polymed Medical |
| Medtronic |
| B. Braun Melsungen AG |
| Smiths Medical |
| Teleflex Incorporated |
| Others |
Value Network & Pricing Analysis
Medical-grade polyurethane resin costs cascade through three distinct pricing tiers as converters without captive compounding capabilities absorb feedstock volatility while integrated manufacturers stabilize margins through backward control over polymer production.
Pricing Analysis
Signal fidelity in hemodynamic monitoring anchors value-based pricing, with ICU procurement committees paying premiums for anti-kink polyurethane configurations that eliminate waveform artifact. Three-tier pricing structure across premium, standard, and economy levels separates silicone-based sets for extended indwelling use from commodity PVC alternatives for general ward monitoring. Cost compression in the PVC tier intensifies because Indian and Chinese converters flood spot markets with undifferentiated single-lumen configurations. Ambulatory surgical centers exhibit highest price sensitivity, while cardiac catheterization laboratories demonstrate lowest sensitivity due to outcome-critical monitoring requirements.
Supply Chain Analysis
Domestic-content mandates in India's medical device procurement are reshaping sourcing patterns for export-oriented converters in Gujarat and Maharashtra. Supply concentrates in Germany's Freiburg-Heidelberg corridor, China's Yangtze River Delta around Shanghai-Suzhou, and the United States' Midwest polymer processing belt. Raw material dependencies rest on specialized polyurethane resins, medical-grade PVC compounds, and platinum-cured silicone formulations. Single-source vulnerability runs through Germany's fluoropolymer liner supply as the EU F-Gas Regulation restricts availability. Distribution runs through hospital GPO framework agreements and specialized medical device distributors serving catheterization laboratories.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race where control over medical-grade polymer compounding separates margin-stable players from feedstock-exposed converters.
For Market Incumbents: Anticipate ISO 80369 connector redesign deadlines by accelerating non-recurring engineering investment ahead of regulatory enforcement waves. Consolidate position through captive polyurethane production capacity in Germany or the United States to neutralize resin price volatility that erodes converter margins. Defend against emerging Asian entrants by locking multi-year framework agreements with GPO-affiliated health systems before procurement consolidation completes.
For New Entrants and Emerging Players: Launch via direct hospital contracting in underpenetrated United States ambulatory surgical centers, bypassing distributor markups that inflate incumbent pricing. Target anesthesia-hemodynamic convergence applications where integrated OR suite specifications remain unsettled and incumbent platform lock-in is weakest. Exploit white-space in silicone-based pressure relief sets for high-risk interventional cardiology as fluoropolymer substitution creates formulation gaps.
For Investors and Strategic Acquirers: EU MDR technical documentation completion rates are the leading indicator that first-mover certification advantage is crystallizing among prepared manufacturers. Frame long-term viability around consolidation into three platform players with catheter-tubing integration and captive polymer supply. Target acquisition archetype: mid-scale European converters with backward integration into medical-grade compounding but lacking ICU channel access. Watch FDA 510(k) clearance velocity for multi-lumen configurations as the inflection signal for competitive positioning shifts.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polymer Compounding | Captive polyurethane production insulates margin stability against feedstock volatility from German chemical suppliers. |
| CE Marking Pathway under EU MDR | Robust technical documentation creates first-mover advantage as notified body capacity constrains competitor timelines. |
| Hospital System Partnership | Multi-year framework agreements with GPO-affiliated facilities displace spot-market purchasing and distributor fragmentation. |
| FDA 510(k) Submission for Multi-Lumen Sets | Streamlined Class II cardiovascular clearance protocols compress registration timelines versus legacy pathways. |
| Software Companion Development | Digital pressure waveform analytics integration differentiates tubing sets in hemodynamic monitoring suites. |
Research Methodology
FDA 510(k) filings, EU MDR technical documentation databases, and hospital GPO contract repositories formed the secondary backbone of this analysis. Primary interviews with catheterization laboratory directors, biomedical engineers, GPO contracts managers, and polymer compounding specialists validated demand assumptions and procurement behavior patterns. Bottom-up tubing set consumption estimates triangulated against top-down hospital infrastructure expansion projections across the analysis window.
Historical trendline analysis of ICU bed additions and cardiac procedure volumes established baseline demand parameters. The modeling framework segmented volume and value outputs across product architecture, material formulation, clinical application intensity, and facility type throughout the forecast period. CAGRs derived from regression analysis of installed base replacement cycles and new technology penetration curves, with specific inputs from polyurethane substitution rates in coronary care and multi-lumen configuration adoption in cath labs.
The model assumes a particular technology adoption path; alternative pathways for fluoropolymer-free pressure relief materials would alter the outlook if barrier performance fails to match legacy specifications. Forecasts reflect assumptions regarding regulatory enforcement timing, polymer feedstock availability, and hospital procurement consolidation velocity. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Supplies
China Hospital Supplies Market
Medical Supplies
Combat Dressing Market
Medical Supplies
Plastic Blood Bags Market
Medical Supplies
Bile Collection Bags Market
Medical Supplies
Laparoscopic Retrieval Bags Market
Medical Supplies
Trauma Products Market
Medical Supplies
Tissue Glue and Bio-Adhesive Sealants Market
Medical Supplies
Safety Box for Syringe Market
Medical Supplies
Luer Lock Syringe Market
Medical Supplies
Europe Intravenous Solutions Market
Medical Supplies
Latex Medical Disposables Market
Medical Supplies
Trach Care Trays Market
Medical Supplies
Compression Socks Market
Medical Supplies
Global IV Bags Market
Medical Supplies
Drainage Bottles Market
Medical Supplies
Plasma Separation Tubes Market