
 North America Liver Cancer Diagnostics Market | 2026-2036
North America Liver Cancer Diagnostics Market Size, Share, and Industry Trends Forecast 2026-2036
North America Liver Cancer Diagnostics Market Analytics
Hospital procurement committees is unwinding traditional imaging-centric purchasing patterns as academic medical centers and independent diagnostic laboratories gain influence over liver cancer testing protocols. Thermo Fisher Scientific leverages its clinical NGS infrastructure to anchor molecular profiling services across major oncology networks. Abbott Laboratories competes through point-of-care blood biomarker platforms that reduce turnaround times for cirrhosis surveillance programs. Illumina sustains its position in comprehensive genomic profiling by controlling instrument placement and assay content partnerships with leading hepatology practices.
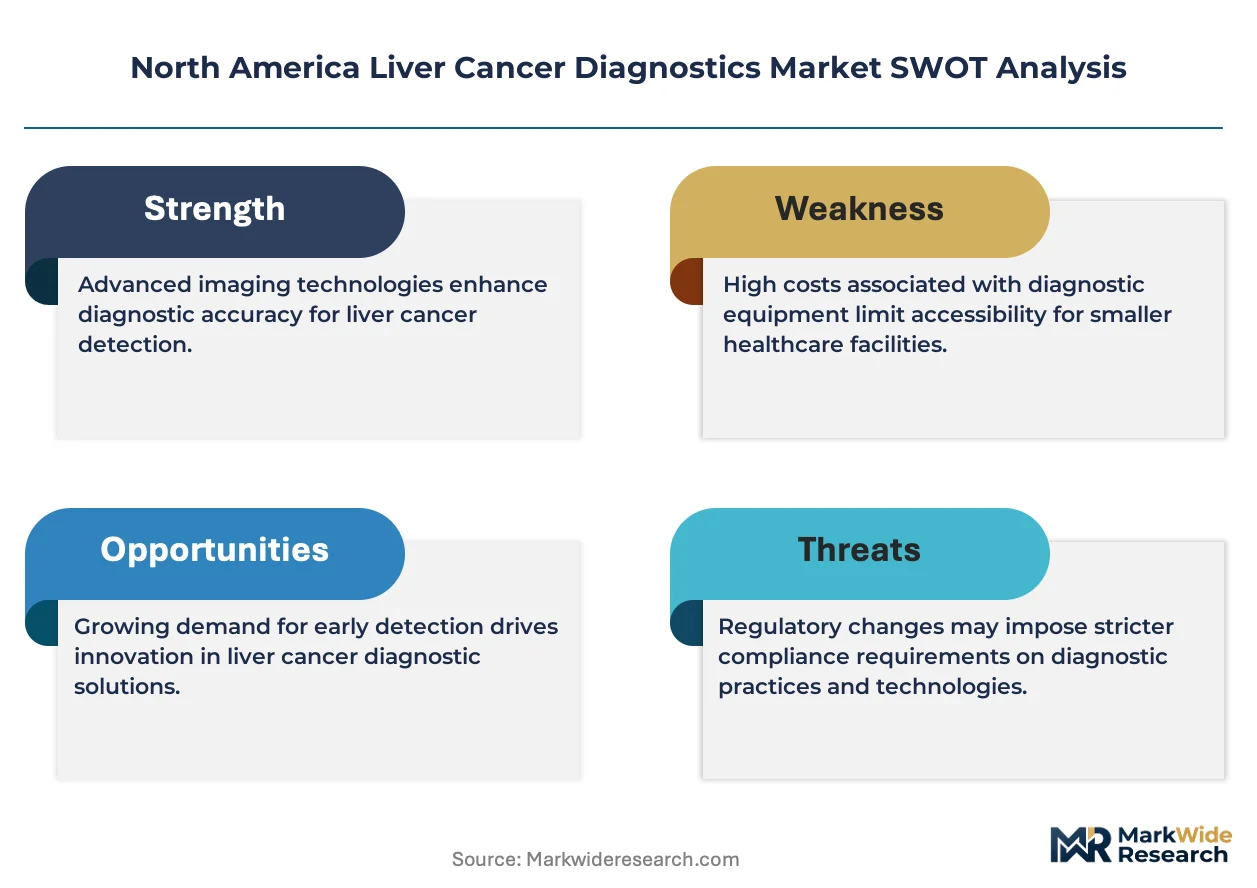
Liver cancer diagnostics encompasses imaging modalities, tissue and liquid biopsy techniques, serological assays, and molecular biomarker tests designed to detect hepatocellular carcinoma and cholangiocarcinoma at stages amenable to curative intervention, with CT and MRI protocols requiring contrast-enhanced multiphase acquisition to characterize arterial hyperenhancement and washout patterns characteristic of malignant hepatic lesions. Blood-based biomarker panels and circulating tumor DNA assays serve screening functions in cirrhotic populations where imaging surveillance intervals strain radiology capacity. Imaging tests dominate current procedure volumes but face margin compression from bundled payment models, while genetic testing represents the fastest-expanding segment as comprehensive genomic profiling becomes standard before systemic therapy selection. Biomarker development concentrates on glypican-3, AFP-L3, and des-gamma-carboxy prothrombin combinations with liquid biopsy platforms capturing growing share in recurrence monitoring applications.
FDA regulates in vitro diagnostic devices and companion assays through premarket approval and de novo pathways, while CMS national coverage determinations shape commercial payer reimbursement for molecular diagnostics in hepatocellular carcinoma. CLIA laboratory certification requirements govern high-complexity testing performed in diagnostic laboratories, creating barriers for decentralized blood-based screening programs. Stakeholders must monitor evolving FDA guidance on artificial intelligence-enabled radiology devices and state-level laboratory licensing harmonization to anticipate where capital deployment for integrated diagnostic platforms will yield sustainable returns.
Market Dynamics
Hospital procurement committees are unwinding traditional imaging-centric purchasing patterns as academic medical centers and independent diagnostic laboratories gain influence over liver cancer testing protocols. Molecular profiling services and liquid biopsy platforms are redirecting capital deployment away from radiology suites toward CLIA-certified laboratory infrastructure.
Growth Catalysts
- CMS coverage determinations:National coverage determinations for next-generation sequencing-based companion diagnostics are reshaping reimbursement pathways for hepatocellular carcinoma molecular testing across Medicare Advantage networks.
- Liquid biopsy platforms:Circulating tumor DNA assays are capturing growing share in recurrence monitoring applications among cirrhotic populations where imaging surveillance intervals strain radiology capacity.
- Tertiary cancer centers:Complex hepatocellular carcinoma case volumes in Texas, California, and New York are concentrating demand for integrated diagnostic platforms that combine imaging with molecular profiling.
Market Restraints
- Contrast agent supply volatility:Gadolinium-based and iodinated contrast shortages periodically disrupt CT and MRI protocol scheduling, forcing reliance on non-contrast alternatives with inferior lesion characterization.
- CLIA certification barriers:High-complexity testing requirements create structural obstacles for decentralized blood-based screening programs seeking to expand beyond academic medical center catchment areas.
- Biomarker specificity limitations:AFP-L3 and des-gamma-carboxy prothrombin combinations exhibit insufficient sensitivity for early-stage detection, limiting their utility as standalone screening tools in compensated cirrhosis.
Strategic Opportunities
- Artificial intelligence-enabled radiology:FDA breakthrough device designations for AI-assisted lesion detection create regulatory tailwinds for software-as-a-service models that integrate with existing PACS infrastructure.
- Point-of-care biomarker testing:Blood-based platforms that reduce turnaround times for cirrhosis surveillance programs represent underpenetrated white space in community hepatology practices outside major metropolitan clusters.
- Comprehensive genomic profiling standardization:Pre-treatment molecular profiling is becoming mandatory before systemic therapy selection, creating demand for harmonized assay menus across oncology networks.
Industry Challenges
- Molecular pathologist workforce scarcity:Interpretation of complex genomic signatures in hepatocellular carcinoma requires specialized expertise that concentrates in a limited number of academic pathology departments.
- Instrument placement lock-in:Sequencing platform vendors control installed base access, creating switching costs for laboratories seeking to diversify assay content partnerships.
- State licensing harmonization gaps:Inconsistent laboratory licensing requirements across jurisdictions complicate multi-site network expansion for integrated diagnostic service providers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Liver Cancer Diagnostics Market |
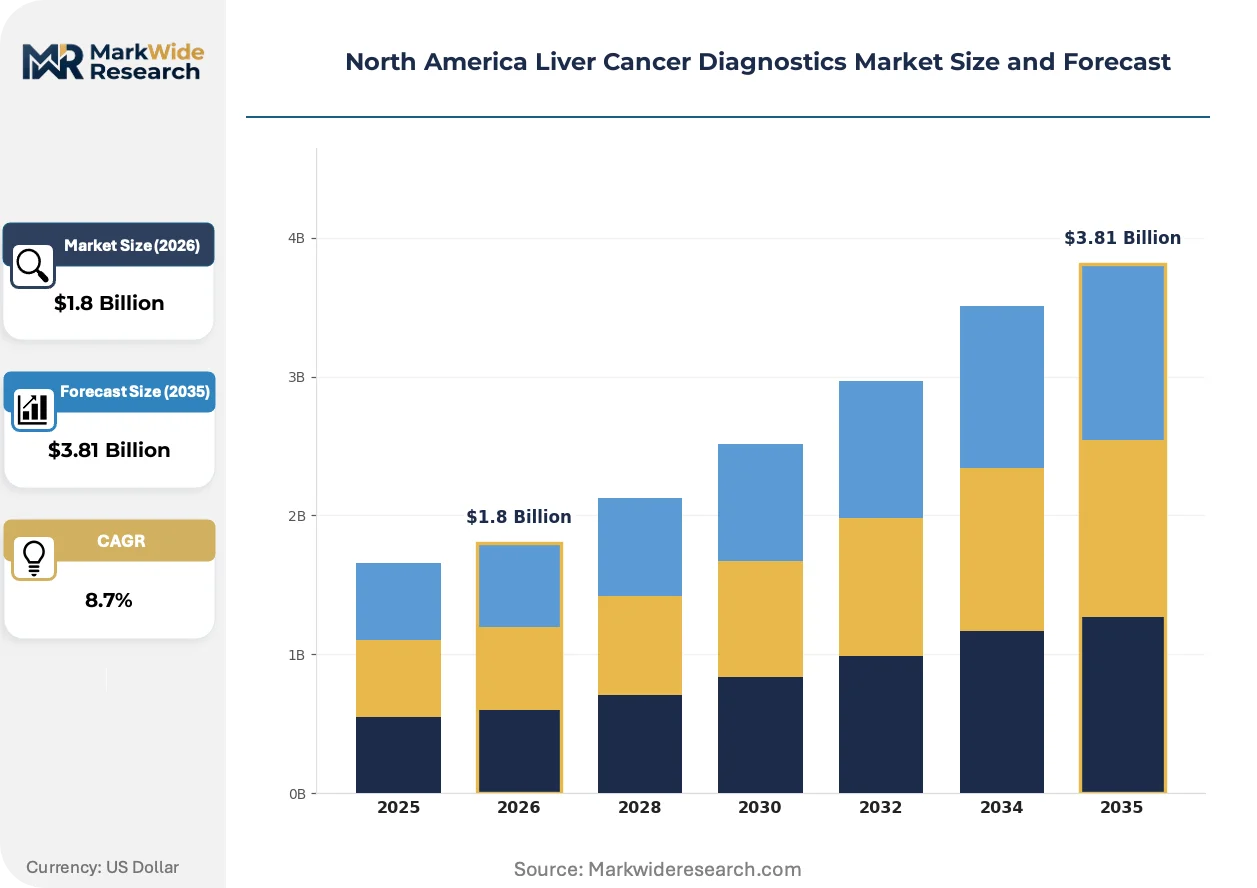
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Imaging Tests, Biopsy, Blood Tests, Biomarkers Technology: CT Scan, MRI, Ultrasound, Genetic Testing End User: Hospitals, Clinics, Diagnostic Laboratories, Research Institutions Application: Early Detection, Disease Monitoring, Treatment Planning, Prognosis |
| Companies Covered | Abbott Laboratories, Thermo Fisher Scientific, F. Hoffmann-La Roche Ltd, Qiagen N.V., Siemens Healthineers, Becton Dickinson & Company, Illumina, Koninklijke Philips N.V., Fujifilm Medical Systems, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Liver Cancer Diagnostics Market Evolving Landscape
Liquid biopsy molecular profiling is actively reshaping competitive positioning in liver cancer diagnostics. Technology convergence, regulatory acceleration, and procurement model evolution are compressing traditional testing hierarchies.
Multiphase contrast-enhanced MRI protocols for arterial hyperenhancement and washout pattern characterization are supplanting CT-first diagnostic algorithms in academic medical centers. Tertiary cancer centers in California and New York are adopting MRI-conditional biopsy pathways that reduce radiation exposure in cirrhotic patients requiring serial surveillance. This shift is compressing revenue per procedure for standalone imaging providers while expanding integrated service contracts that bundle radiology with molecular pathology.
FDA breakthrough device designations for next-generation sequencing companion diagnostics are accelerating pre-market review timelines for hepatocellular carcinoma assays. The agency's evolving guidance on artificial intelligence-enabled radiology devices is creating parallel pathways for software-based lesion detection tools. Diagnostic laboratories in Texas and California are restructuring quality management systems to accommodate dual-track submissions for imaging AI and liquid biopsy platforms.
Hospital procurement committees are consolidating vendor relationships around integrated diagnostic platforms that combine imaging, tissue pathology, and molecular testing under single master agreements. Independent diagnostic laboratories are responding by offering outcome-based risk-sharing arrangements that tie reimbursement to diagnostic accuracy metrics in hepatocellular carcinoma staging. This restructuring is most visible in New York and California health systems where bundled oncology payments create alignment incentives across radiology, pathology, and oncology service lines.
North America Liver Cancer Diagnostics Market Segmentation
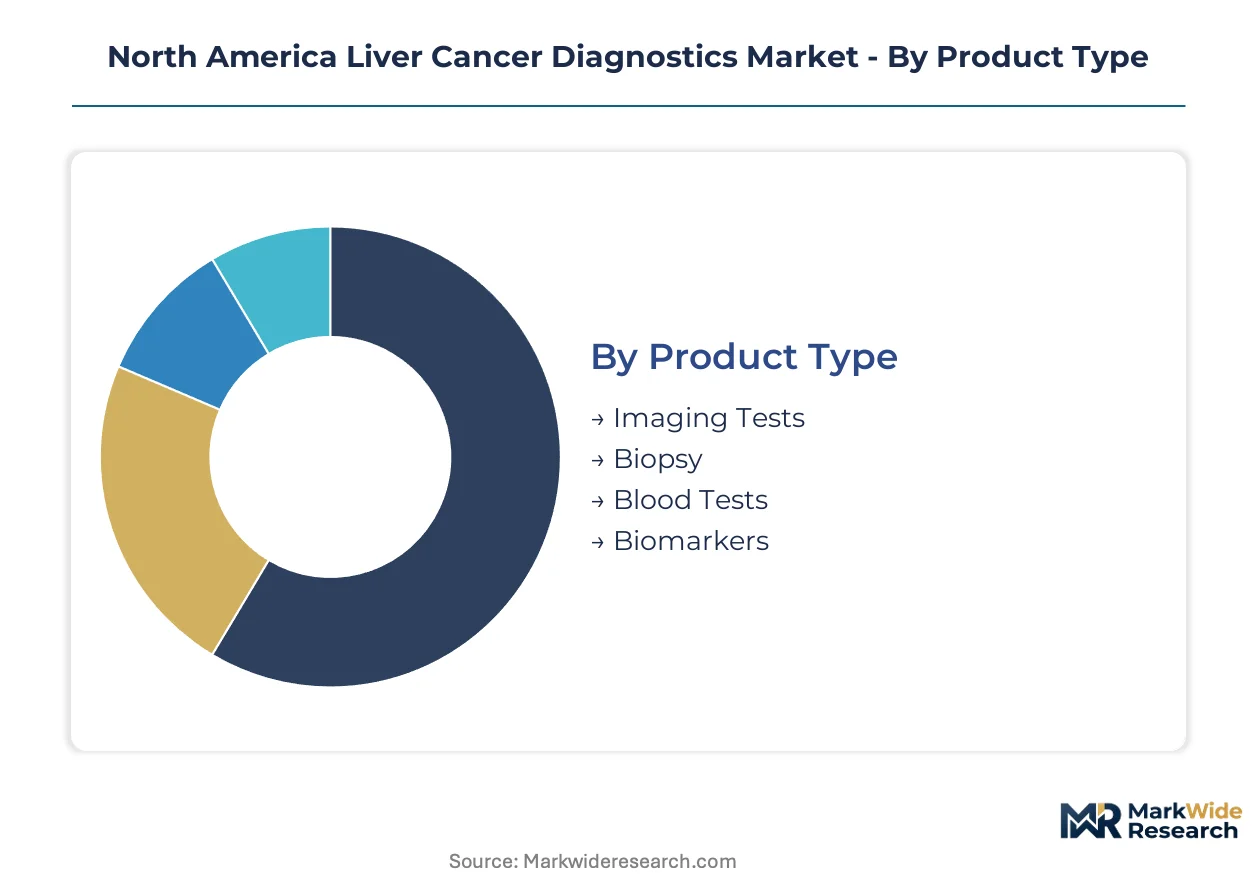
Segmentation reveals where capital deployment and margin capture diverge across testing modalities. Procurement committees in Texas, California, and New York tertiary centers are rebalancing spending toward molecular platforms while imaging maintains procedure volume dominance.
Product Type:
Margin pools concentrate in molecular biomarker platforms where reimbursement rates exceed imaging by substantial multiples, while bundled payment models compress returns on standalone radiology procedures.
- Imaging Tests:CT and MRI protocols with contrast-enhanced multiphase acquisition characterize arterial hyperenhancement and washout patterns. Demand concentrates in academic medical centers across Texas and California where complex hepatocellular carcinoma staging requires precise lesion delineation.
- Biomarkers:Glypican-3, AFP-L3, and des-gamma-carboxy prothrombin combinations enable blood-based screening in cirrhotic populations. New York and California health systems are expanding CLIA-certified laboratory infrastructure to capture pre-treatment molecular profiling volumes.
- Biopsy:Tissue acquisition for histopathological confirmation and molecular subtyping.
- Blood Tests:Serological assays for liver function monitoring and surveillance intervals.
Imaging Tests holds installed capacity. Biomarkers is rotating up the share rankings.
Technology:
Procedure volumes scale inversely with reimbursement per test across these modalities, creating divergent investment incentives for hospital systems and independent laboratories.
- Genetic Testing:Next-generation sequencing companion diagnostics for comprehensive genomic profiling before systemic therapy selection. CMS coverage determinations are reshaping Medicare Advantage network reimbursement in Texas and New York.
- MRI:Multiphase contrast-enhanced protocols with radiation-sparing advantages for serial surveillance in compensated cirrhosis. California tertiary centers are adopting MRI-conditional biopsy pathways that reduce patient exposure.
- CT Scan:First-line detection modality with iodinated contrast dependence.
- Ultrasound:Surveillance screening tool with operator-dependent sensitivity limitations.
MRI dominates procedure throughput. Genetic Testing is climbing the fastest in revenue contribution.
End User:
Customer concentration varies sharply by testing complexity, with high-complexity molecular assays concentrating in academic catchment areas while community access remains constrained.
- Diagnostic Laboratories:CLIA-certified facilities performing liquid biopsy and comprehensive genomic profiling. Independent laboratories in California and New York are offering outcome-based risk-sharing arrangements tied to diagnostic accuracy metrics.
- Hospitals:Integrated delivery networks bundling radiology, pathology, and oncology service lines. Texas Medical Center anchor institutions are consolidating vendor relationships around single master agreements.
- Clinics:Community hepatology practices with point-of-care biomarker testing potential.
- Research Institutions:Translational programs bridging biomarker discovery to clinical validation.
Hospitals retain capital allocation authority. Diagnostic Laboratories is gaining procurement influence fastest.
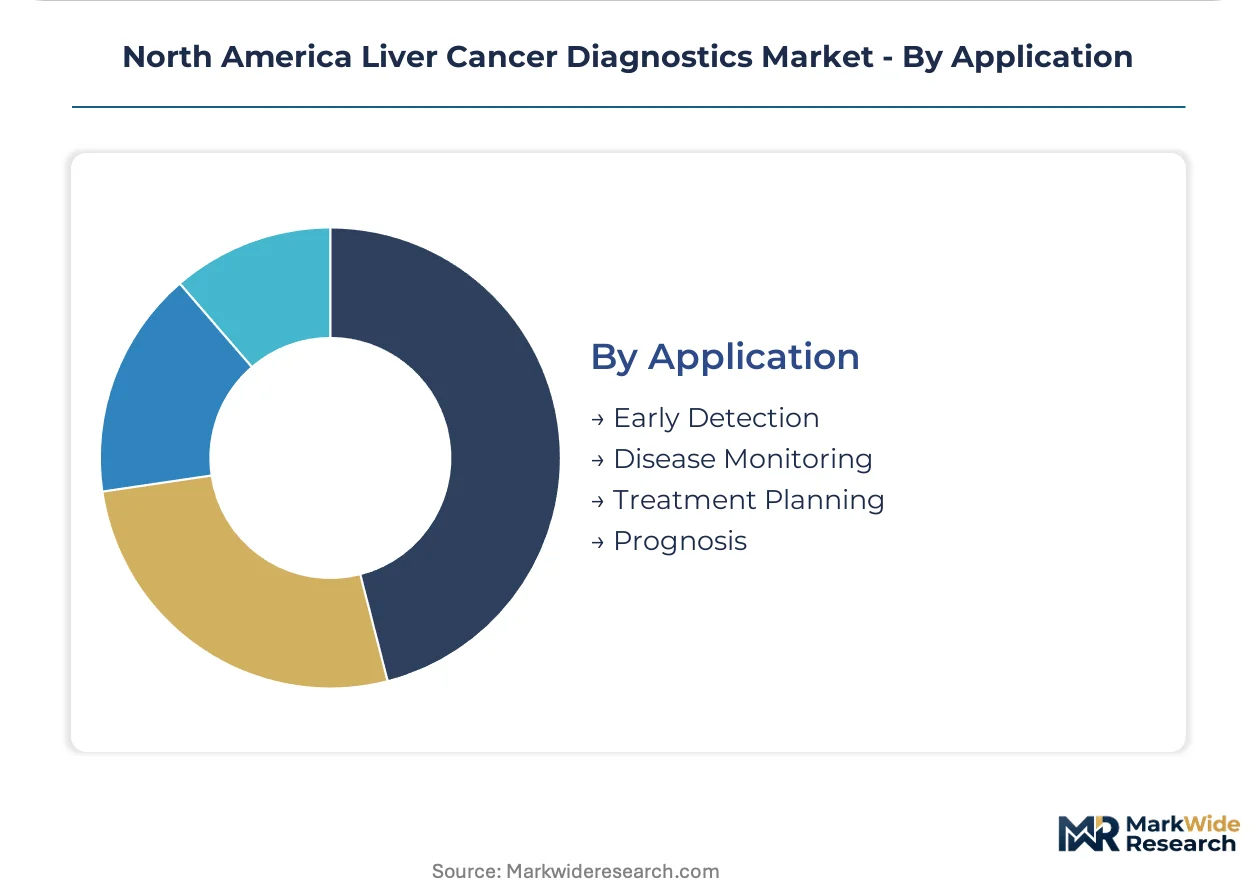
Application:
Commercial value per patient episode escalates dramatically from surveillance through treatment selection, with molecular profiling commanding premium positioning at the therapeutic decision point.
- Treatment Planning:Comprehensive genomic profiling mandatory before systemic therapy selection. Oncologists in New York and California are requiring harmonized assay menus across network institutions.
- Early Detection:Blood-based biomarker panels and circulating tumor DNA assays for cirrhotic populations where imaging surveillance intervals strain radiology capacity.
- Disease Monitoring:Recurrence surveillance through liquid biopsy platforms.
- Prognosis:Molecular signature stratification for survival forecasting.
Treatment Planning captures premium reimbursement. Early Detection is expanding most quickly in addressable population.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The I-95 healthcare corridor linking Boston to Washington anchors North American liver cancer diagnostics infrastructure, with tertiary cancer centers concentrated along this spine driving molecular testing adoption.
United States
Texas Medical Center in Houston and MD Anderson Cancer Center handle complex hepatocellular carcinoma staging volumes that reshape national testing protocols. FDA breakthrough device designations for next-generation sequencing companion diagnostics accelerate pre-market review timelines for hepatocellular carcinoma assays. California's Stanford Cancer Institute and UCSF Helen Diller Family Comprehensive Cancer Center are adopting MRI-conditional biopsy pathways that reduce radiation exposure in cirrhotic patients requiring serial surveillance.
Canada
Ontario's cancer care networks are expanding liquid biopsy access through provincial funding agreements for circulating tumor DNA assays. Health Canada's regulatory framework for in vitro diagnostic devices governs pre-market approval pathways for molecular biomarker platforms. Toronto's University Health Network and Princess Margaret Cancer Centre are consolidating vendor relationships around integrated diagnostic platforms that bundle imaging with molecular pathology.
Mexico
Metropolitan Mexico City's Instituto Nacional de Ciencias Médicas y Nutrición Salvador Zubirán concentrates public-sector hepatocellular carcinoma case volumes. The country's national pharmaceutical regulator oversees clinical trial approvals for companion diagnostics targeting liver cancer biomarkers. Private diagnostic laboratory chains in Nuevo León and Jalisco are importing CLIA-certified testing protocols to capture affluent patient segments seeking molecular profiling.
California
Academic medical centers in Los Angeles and San Francisco are restructuring quality management systems to accommodate dual-track submissions for imaging AI and liquid biopsy platforms. CMS coverage determinations for comprehensive genomic profiling reshape Medicare Advantage network reimbursement in the state's largest health systems. City of Hope and UC San Diego Moores Cancer Center are requiring harmonized assay menus across network institutions before systemic therapy selection.
New York
Memorial Sloan Kettering Cancer Center and NYU Langone Health are driving adoption of point-of-care blood biomarker platforms that reduce turnaround times for cirrhosis surveillance programs. The state's laboratory licensing requirements create structural barriers for decentralized screening programs seeking to expand beyond academic medical center catchment areas. New York-Presbyterian Hospital is consolidating procurement around single master agreements that bundle radiology, pathology, and oncology service lines.
North America Liver Cancer Diagnostics Market Competitive Landscape
Concentration sits with diversified life science conglomerates that control instrument placement and assay content partnerships across major oncology networks. The vendor base spans three distinct tiers: integrated diagnostic platform providers, point-of-care biomarker specialists, and imaging equipment manufacturers seeking molecular adjacencies. Strategic moves center on vendor consolidation through master service agreements and outcome-based risk-sharing arrangements that tie reimbursement to diagnostic accuracy metrics.
Within the integrated platform tier, Thermo Fisher Scientific and Illumina anchor competitive positioning through control of clinical NGS infrastructure and comprehensive genomic profiling partnerships. Abbott Laboratories occupies a distinct position in point-of-care blood biomarker testing, reducing turnaround times for cirrhosis surveillance programs. These three entities exemplify the archetype divergence between laboratory-centric molecular profiling and decentralized screening access.
| Leading Market Players |
|---|
| Abbott Laboratories |
| Thermo Fisher Scientific |
| F. Hoffmann-La Roche Ltd |
| Qiagen N.V. |
| Siemens Healthineers |
| Becton Dickinson & Company |
| Illumina |
| Koninklijke Philips N.V. |
| Fujifilm Medical Systems |
| Others |
Value Network & Pricing Analysis
FDA premarket approval and CLIA laboratory certification requirements gate both supply qualification and price differentiation simultaneously, concentrating high-complexity molecular testing within academic medical center catchment areas while bundling arrangements compress standalone imaging margins.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates the market. Premium tier captures comprehensive genomic profiling with harmonized assay menus before systemic therapy selection; standard tier covers MRI-conditional biopsy pathways with contrast-enhanced multiphase acquisition; economy tier serves point-of-care blood biomarker platforms in community hepatology practices. Cost compression in the imaging tier intensifies as bundled oncology payments force radiology-procurement committee renegotiations. Community clinics exhibit highest price sensitivity due to constrained capital budgets, while tertiary cancer centers prioritize diagnostic accuracy metrics over unit cost.
Supply Chain Analysis
Inventory lead times for gadolinium-based and iodinated contrast agents periodically disrupt CT and MRI protocol scheduling, forcing reliance on non-contrast alternatives. Manufacturing concentration for sequencing platforms centers on the United States, with reagent supply chains drawing from Germany and Japan. Critical dependencies include semiconductor components for NGS instruments, specialized enzymes for liquid biopsy assays, and rare earth elements for MRI magnet systems. Single-source vulnerability in contrast agent production creates structural exposure. Distribution runs through integrated delivery networks consolidating vendor relationships around single master agreements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits at a platform-economics inflection where instrument placement lock-in and assay content partnerships are converging toward interoperable diagnostic ecosystems, accelerated by CMS coverage determinations reshaping Medicare Advantage network reimbursement pathways.
For Market Incumbents: Fortify installed base control through sequencing platform vendor consolidation and CLIA-certified laboratory infrastructure expansion. Defend against liquid biopsy platform displacement by anchoring molecular profiling services within major oncology networks. Prioritize backward integration into reagent manufacturing to reduce supply volatility exposure. For New Entrants and Emerging Players: Lead with point-of-care blood biomarker platforms targeting community hepatology practices outside Texas, California, and New York metropolitan clusters. White space concentrates in cirrhosis surveillance programs with reduced turnaround time requirements. Pursue outcome-based risk-sharing arrangements tied to diagnostic accuracy metrics as the primary go-to-market angle. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across decentralized blood-based screening programs as CLIA certification barriers ease. Long-term viability favors platforms bridging imaging AI with liquid biopsy interoperability rather than standalone modality plays. Target acquisition archetypes include independent diagnostic laboratories with established hospital system partnerships. Monitor FDA breakthrough device designation velocity as the key inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| CLIA Laboratory Certification Expansion | Enables high-complexity molecular testing capture beyond academic medical center catchment areas. |
| CMS Reimbursement Strategy Alignment | Reshapes Medicare Advantage network coverage determinations for NGS companion diagnostics. |
| Hospital System Partnership Consolidation | Bundles radiology, pathology, and oncology service lines under single master agreements. |
| Software Companion Development | Integrates AI-assisted lesion detection with existing PACS infrastructure in tertiary centers. |
| Point-of-Care Platform Deployment | Reduces turnaround times for cirrhosis surveillance programs in community hepatology practices. |
Research Methodology
Two parallel data streams informed the analysis: primary interviews with molecular pathologists, hospital procurement managers, CLIA laboratory directors, and GPO contracts managers; and secondary validation against FDA 510(k) filings, CMS national coverage determinations, hospital procurement databases, and CLIA laboratory certification records. Bottom-up procedure volume estimates triangulated with top-down reimbursement rate analysis across the projection horizon.
Across the modeling period, forecasts incorporate segmentation by product type, technology platform, end-user concentration, and application stage from surveillance through treatment planning. CAGRs derive from procedure volume trajectories and reimbursement pathway evolution. Industry-specific inputs include liquid biopsy platform adoption curves and MRI-conditional biopsy pathway penetration rates in academic medical centers.
The analysis sits within stated boundaries; outcomes outside sustained CMS coverage expansion or contrast agent supply stabilization would require recalibration. Forecasts reflect documented assumptions regarding regulatory acceleration timelines and procurement model evolution. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Clinical Diagnostics
Cell Free DNA Testing Market
Clinical Diagnostics
Heart Failure Testing Market
Clinical Diagnostics
Adult Hemoglobinopathy Testing Market
Clinical Diagnostics
Global Cardiac Marker Testing Market
Clinical Diagnostics
Food Allergy Diagnosis and Treatment Market
Clinical Diagnostics
Global Breast Cancer Screening Test Market
Clinical Diagnostics
Genetic Disease Diagnostic Market
Clinical Diagnostics
Global Colorectal Cancer Diagnostics Market
Clinical Diagnostics
H. Pylori (Helicobacter Pylori) Test Market
Clinical Diagnostics
Immune Response Testing Market
Clinical Diagnostics
Cytomegalovirus Assay Market
Clinical Diagnostics
Clinical Refractometer Market
Clinical Diagnostics
Global Cardiac Biomarkers Testing Market
Clinical Diagnostics
Mitochondrial Myopathy Diagnosis and Treatment Market
Clinical Diagnostics
In-Vitro Colorectal Cancer Screening Tests Market
Clinical Diagnostics
Global Respiratory Disease Testing Market