
 MENA Syringes and Cannula Market | 2026-2036
MENA Syringes and Cannula Market Size, Share, and Industry Trends Forecast 2026-2036
MENA Syringes and Cannula Market Foresight
Prefilled syringe bundling with specialty cannulae is expanding across MENA procurement channels, reducing per-procedure setup time for clinical staff. Becton, Dickinson and Company leverages its integrated manufacturing footprint to sustain contract volumes with Saudi Ministry of Health facilities. B. Braun Melsungen AG anchors its regional position through sterile packaging specialization suited to Gulf climate logistics.
Syringes and cannulae are hollow cylindrical instruments, typically fabricated from medical-grade polypropylene or borosilicate glass with stainless-steel needles, designed for fluid aspiration or parenteral administration in clinical settings. Disposable syringes command the largest volume share across MENA hospital purchasing, while prefilled syringes capture expanding share in vaccination and biologic medication delivery protocols. Homecare settings represent the fastest-growing end-user channel as Saudi Arabia and the UAE expand post-acute care outside institutional walls.
SFDA in Saudi Arabia, MOHAP in the UAE, and Egypt's national pharmaceutical regulator enforce sterilization validation and traceability standards that shape product registration timelines and import clearance workflows. Compliance with these frameworks determines market access velocity for new entrants. Stakeholders must monitor harmonization gaps between Gulf standards and emerging African market requirements as distribution networks extend southward.
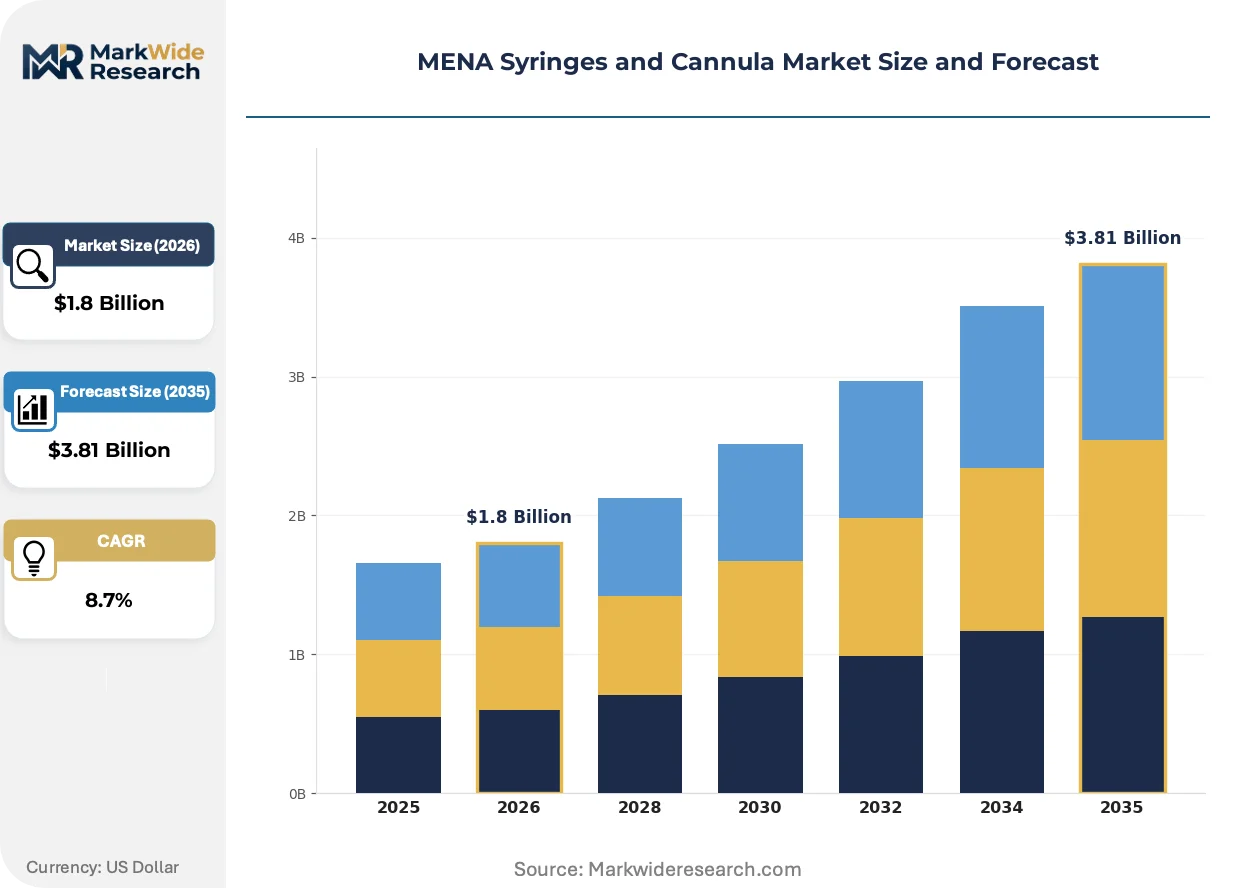
Market Dynamics
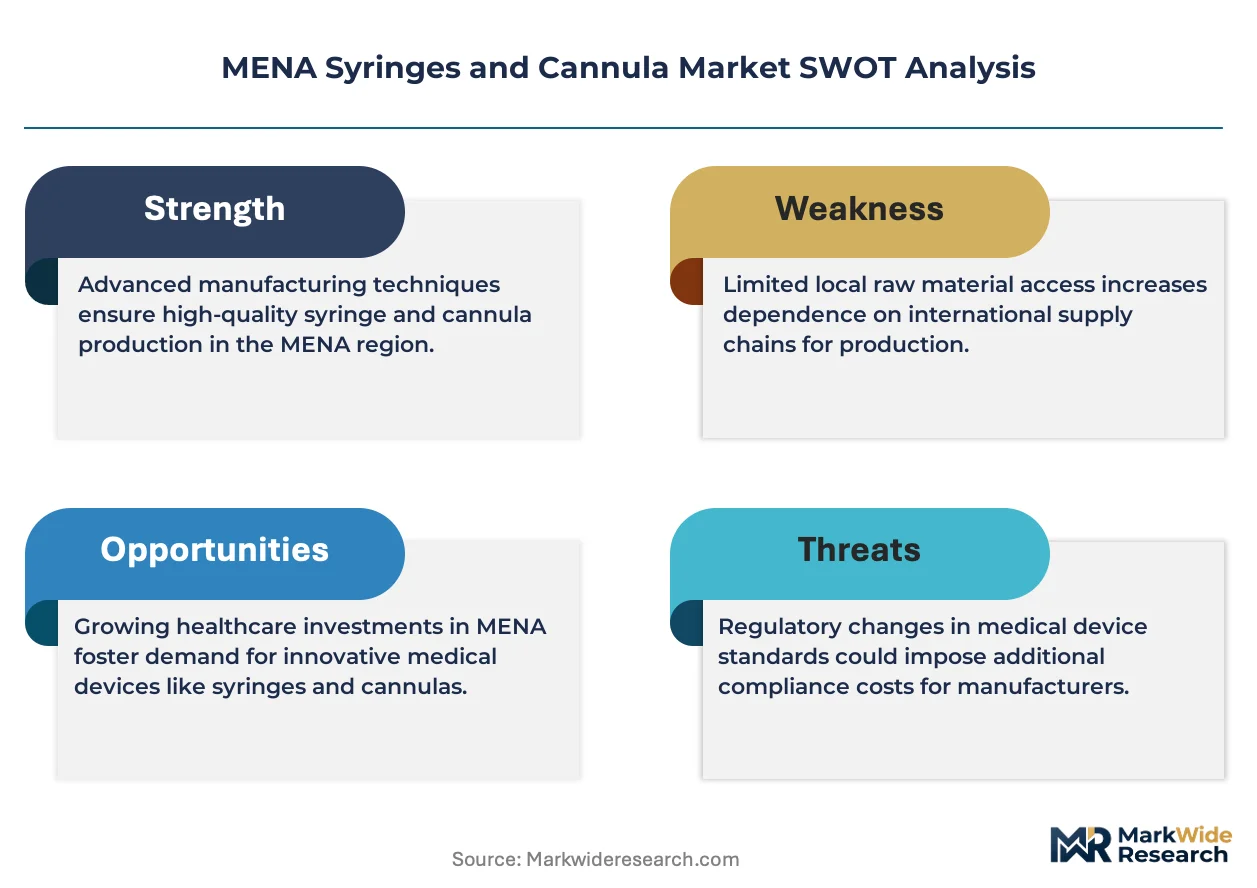
SFDA sterilization validation requirements are compressing supplier qualification timelines across Saudi Arabia's hospital procurement channels, favoring manufacturers with pre-certified sterile packaging capabilities.
Growth Catalysts
- Homecare expansion protocols:Saudi Arabia and the UAE are shifting post-acute infusion therapy outside institutional walls, creating pull for patient-administered injection systems with integrated safety features.
- MOHAP traceability mandates:Dubai's healthcare cluster now requires serialized device tracking from manufacture to point-of-care, accelerating adoption of barcoded prefilled syringes.
- Biologics cold-chain compatibility:Glass-barrel prefilled formats with specialized cannulae are capturing share in rheumatology and oncology outpatient units across Gulf health systems.
Market Restraints
- Polypropylene resin volatility:Medical-grade polymer feedstock costs fluctuate with petrochemical output from Gulf state oil complexes, squeezing margin structures for disposable syringe producers.
- Single-source sterilization capacity:Gamma irradiation facilities concentrate in Jeddah and Dubai industrial zones, creating geographic chokepoints for product release timelines.
- Glass substitution ceiling:Borosilicate formats face technical limitations in high-viscosity biologic delivery, constraining uptake in certain therapeutic categories.
Strategic Opportunities
- Egyptian manufacturing localization:Cairo-Alexandria corridor offers tariff-advantaged production bases for re-export across North African markets with harmonizing device regulations.
- Needlestick prevention mandates:Emerging safety-engineered device requirements across Gulf Cooperation Council jurisdictions create first-mover positioning for retractable-needle platforms.
- Direct-to-clinic distribution:Bypassing traditional medical device distributors through hospital group purchasing organization portals is opening margin recovery channels for qualified suppliers.
Industry Challenges
- Sterile packaging engineering talent:Gulf-based manufacturers face scarcity of polymer science specialists capable of designing climate-stable barrier systems for 50°C ambient logistics.
- SFDA registration timeline compression:Device approval workflows now demand simultaneous sterilization validation and clinical equivalence documentation, extending time-to-revenue for new entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | MENA Syringes and Cannula Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Disposable Syringes, Insulin Syringes, Specialty Cannulae, Prefilled Syringes End User: Hospitals, Clinics, Homecare Settings, Diagnostic Centers Material: Plastic, Glass, Stainless Steel, Latex Application: Anesthesia, Vaccination, Blood Sampling, Medication Delivery |
| Companies Covered | Cardinal Health, Medline Industries, Becton, Dickinson and Company, Ambu A/S, Teleflex Incorporated, B. Braun Melsungen AG, Nipro Corporation, Mohamed & Obaid AlMulla Group, Terumo Corporation, Others |
| Regions Covered | MENA: Saudi Arabia, UAE, Qatar, Kuwait, Egypt, Morocco, Algeria, Tunisia, Rest of MENA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
MENA Syringes and Cannula Market Shifts & Advancements
Connected delivery systems and climate-adapted packaging are reconfiguring how injection devices move through MENA supply chains, with implications for sterilization protocols and procurement specifications.
Prefilled syringes with integrated passive safety mechanisms are decentralizing medication preparation workflows from hospital pharmacy compounding units to point-of-care nursing stations. Saudi Ministry of Health facilities are adopting these formats for vaccination campaigns at scale. The shift compresses per-procedure setup time and reduces pharmacy labor allocation for high-volume injection protocols.
SFDA's 2024 sterilization validation guidance now mandates real-time environmental monitoring data for ethylene oxide and gamma irradiation cycles. Device manufacturers must retrofit quality management systems to capture continuous parameter logging. Egyptian and Jordanian suppliers are investing in automated sterilization documentation platforms to maintain Gulf market access velocity.
Hospital group purchasing organizations in the UAE are consolidating supplier panels around full-line disposable injection system providers. Single-source contracting for syringes, cannulae, and safety accessories is displacing fragmented multi-vendor purchasing across Dubai's private hospital networks. This concentration is most pronounced in the Riyadh-Jeddah corridor where Ministry of Health facilities are piloting integrated device procurement frameworks.
MENA Syringes and Cannula Market Segmentation
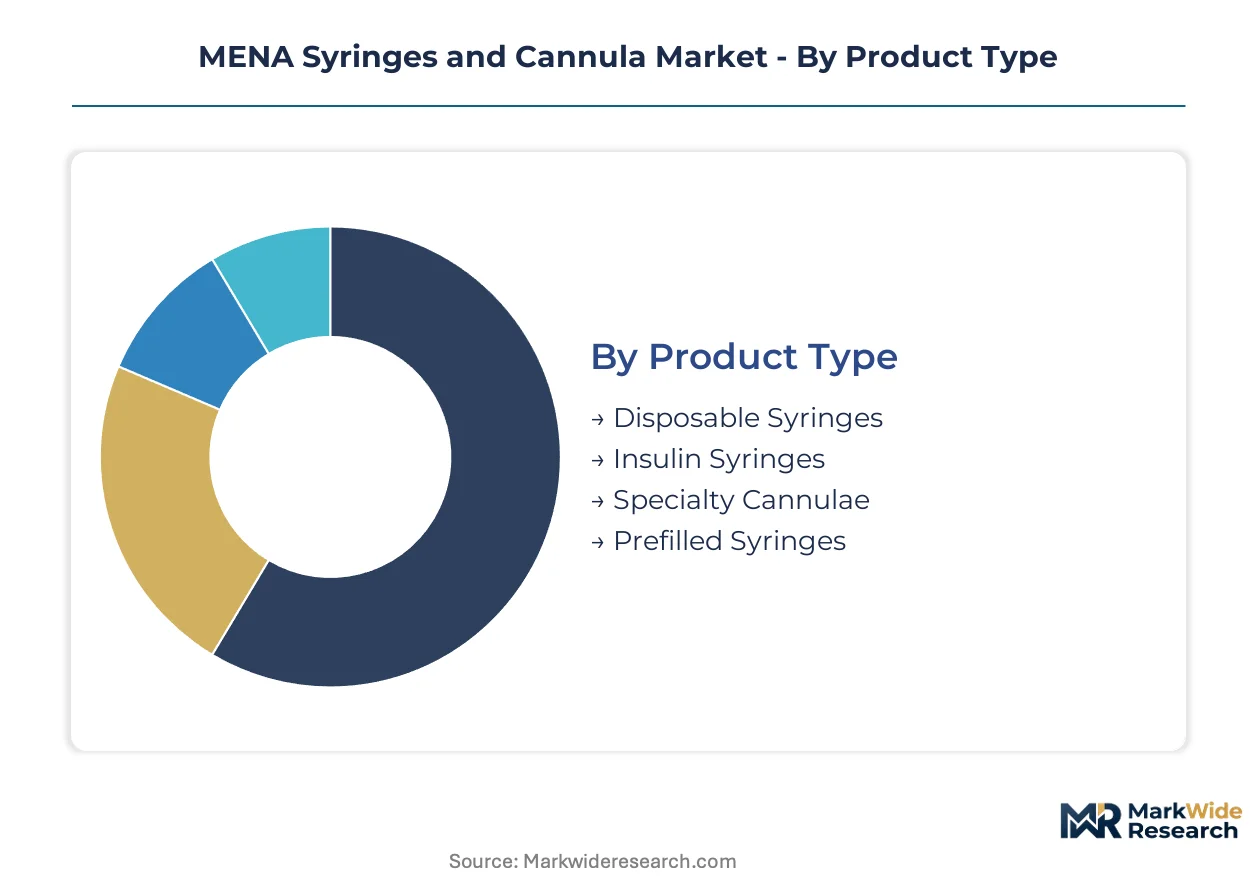
Device procurement patterns across MENA health systems diverge sharply by clinical setting and sterilization requirements. Understanding these segment boundaries clarifies where manufacturers must adapt packaging, pricing, and distribution strategies to secure contract volumes.
Product Type:
Replacement cycles accelerate where single-use mandates intersect with high-procedure environments, compressing upgrade windows for legacy formats.
- Disposable Syringes:Polypropylene barrel-and-plunger systems dominate high-volume hospital purchasing across Saudi Arabia's Ministry of Health facilities. Bulk contracting for vaccination campaigns and emergency department protocols sustains procurement velocity in Riyadh-Jeddah corridor institutions.
- Prefilled Syringes:Glass-barrel formats with integrated staked needles reduce pharmacy compounding labor in UAE oncology and rheumatology outpatient units. SFDA sterilization validation requirements favor suppliers with pre-certified barrier packaging capable of withstanding Gulf climate logistics.
- Insulin Syringes:Calibrated U-100 and U-40 formats serve diabetes management protocols expanding into Saudi and Emirati homecare channels.
- Specialty Cannulae:Winged infusion and scalp vein sets address pediatric and geriatric vascular access challenges in Dubai's private hospital networks.
Disposable syringes sit at the top of the volume ranking, with prefilled syringes climbing the fastest.
End User:
Cost tier stratification separates institutional purchasers with sterilization infrastructure from decentralized settings requiring pre-validated device formats.
- Hospitals:Saudi Arabia's public hospital sector drives bulk purchasing through centralized Ministry of Health tenders, with gamma-irradiated disposable syringes constituting the core procurement category.
- Homecare Settings:Patient-administered injection systems with passive safety mechanisms are gaining share fastest as Dubai and Riyadh shift post-acute infusion therapy outside institutional walls.
- Clinics:Outpatient surgical centers in the UAE's Dubai Healthcare City cluster source smaller lot sizes with expedited delivery terms.
- Diagnostic Centers:Blood collection hubs across Egypt's Cairo-Alexandria corridor prioritize vacuum tube compatibility in cannula selection.
Hospitals capture the dominant procurement value, while homecare settings are expanding most quickly.
Material:
Supply concentration around Gulf petrochemical complexes shapes polymer cost structures and sterilization compatibility profiles.
- Plastic:Medical-grade polypropylene dominates disposable syringe fabrication, with resin costs tracking regional oil complex output fluctuations.
- Glass:Borosilicate barrels enable biologic medication stability in prefilled formats, though viscosity limitations constrain high-concentration therapeutic delivery.
- Stainless Steel:Cannula needles require 304-grade alloy consistency for bevel sharpness retention across SFDA-regulated sterilization cycles.
- Latex:Gasket and plunger tip components face declining utilization as synthetic elastomer alternatives address allergy protocol requirements.
Plastic commands the volume base, with glass formats gaining share in biologic-compatible applications.
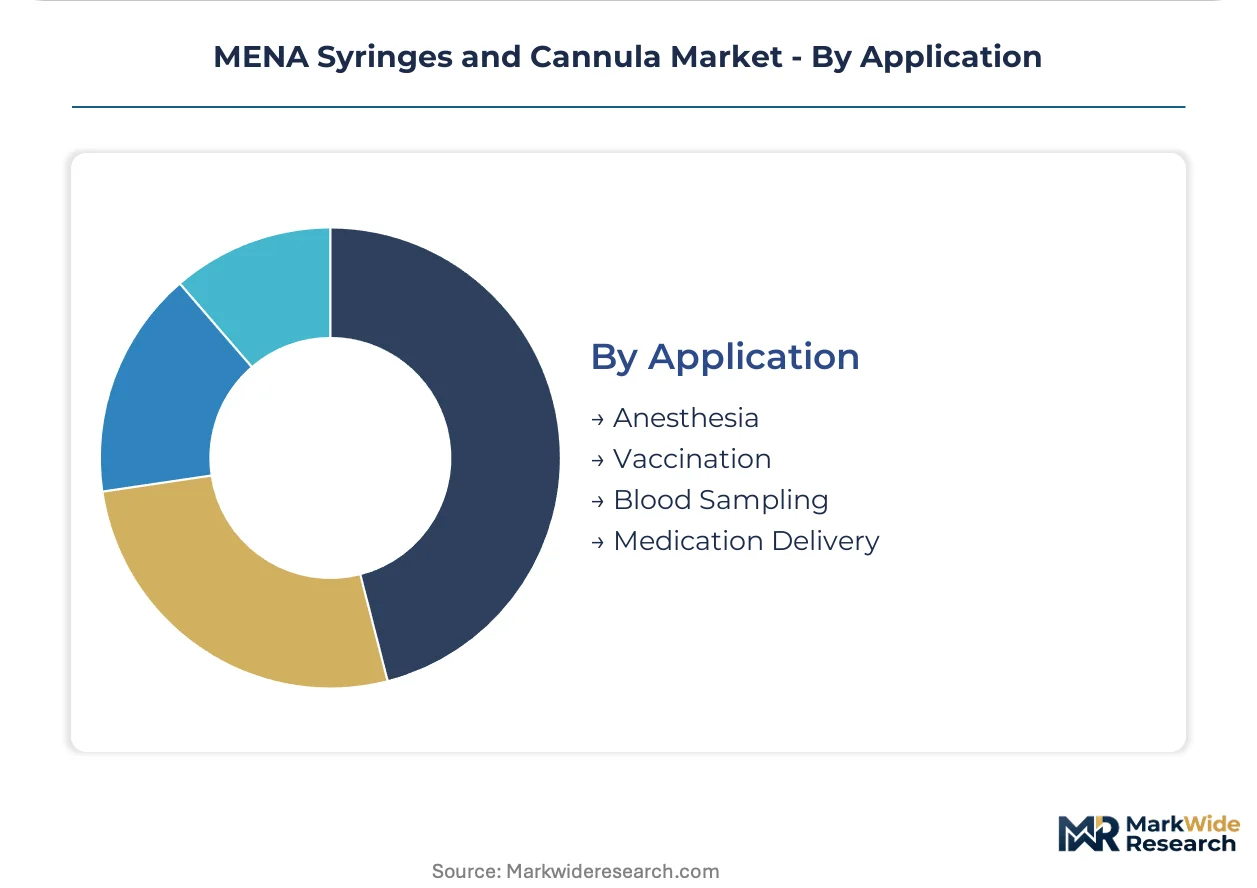
Application:
Procedure-specific device specifications determine margin structures, with anesthesia and vaccination protocols favoring standardized formats over customized solutions.
- Medication Delivery:Intravenous and intramuscular injection protocols across Saudi hospital wards sustain the highest throughput requirements for luer-lock syringe compatibility.
- Vaccination:National immunization programs in the UAE and Saudi Arabia drive demand for auto-disable syringes with fixed-needle safety engineering.
- Anesthesia:Epidural and spinal needle configurations serve surgical suites in Dubai's private hospital clusters with specialized gauge and length specifications.
- Blood Sampling:Vacuum-extraction cannulae integrate with tube holder systems in diagnostic workflows across Egypt's laboratory networks.
Medication delivery anchors procurement volumes, with vaccination applications showing steepest expansion trajectory tied to public health program scaling.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The MENA syringes and cannula industry traces its commercial scale to the 1970s, when Gulf petrochemical complexes began supplying medical-grade polypropylene feedstock to regional fabricators. Today procurement concentrates in health system clusters across five core markets.
Saudi Arabia
Ministry of Health tenders sustain bulk purchasing of gamma-irradiated disposable syringes for vaccination and emergency protocols. SFDA sterilization validation requirements compress supplier qualification timelines, favoring manufacturers with pre-certified barrier packaging. The Riyadh-Jeddah corridor anchors procurement concentration as public hospitals pilot integrated device procurement frameworks.
United Arab Emirates
Dubai Healthcare City and Abu Dhabi's SEHA network drive demand for prefilled syringes with serialized tracking from manufacture to point-of-care. MOHAP traceability mandates accelerate adoption of barcoded formats across private hospital networks. The Dubai industrial zone houses concentrated gamma irradiation capacity serving Gulf re-export channels.
Egypt
The Cairo-Alexandria corridor offers tariff-advantaged production bases for re-export across North African markets with harmonizing device regulations. The national pharmaceutical regulator enforces sterilization validation standards that shape import clearance workflows. Diagnostic laboratories across Greater Cairo prioritize vacuum-extraction cannulae integrating with tube holder systems.
Jordan
Amman-based manufacturers serve as regional sterilization documentation hubs for Gulf market access. Investment in automated quality management platforms addresses SFDA requirements for real-time environmental monitoring data. The Aqaba special economic zone facilitates re-export logistics to Iraqi and Palestinian health systems.
Kuwait
The Ministry of Health centralizes procurement for specialized cannulae serving pediatric and geriatric vascular access protocols. Public hospital networks source smaller lot sizes with expedited delivery terms from UAE-based distributors. Sabah Al-Ahmad medical city anchors demand concentration for safety-engineered retractable-needle platforms.
MENA Syringes and Cannula Market Competitive Landscape
Premium-margin players sit above commodity-margin players across sterilization certification and climate-stable packaging capabilities. The vendor base stratifies into three tiers: integrated multinationals with Gulf manufacturing footprints, regional specialists in sterile barrier engineering, and price-competitive distributors serving fragmented clinic networks. Dominant competitive moves include backward integration into polymer compounding and strategic partnerships with hospital group purchasing organizations.
Within the integrated multinational tier, Becton, Dickinson and Company and B. Braun Melsungen AG exemplify archetypes of scale-driven sterilization certification and sterile packaging specialization respectively. Cardinal Health occupies a position bridging distribution logistics with contract manufacturing capabilities. These anchors represent the structural divide between suppliers capable of simultaneous SFDA registration and clinical equivalence documentation versus those constrained to distributor relationships.
| Leading Market Players |
|---|
| Cardinal Health |
| Medline Industries |
| Becton, Dickinson and Company |
| Ambu A/S |
| Teleflex Incorporated |
| B. Braun Melsungen AG |
| Nipro Corporation |
| Mohamed & Obaid AlMulla Group |
| Terumo Corporation |
| Others |
Supply & Pricing Matrix
Sterile packaging certification tiers split the MENA syringes and cannula market into sharply divergent pricing bands, with SFDA-validated barrier systems commanding substantial premiums over standard gamma-irradiated formats while procurement concentration in Saudi Arabia's Ministry of Health facilities and Dubai's hospital clusters simultaneously compresses margins through volume aggregation and accelerates qualification timelines for pre-certified suppliers.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates SFDA-validated prefilled syringes with integrated safety mechanisms from bulk disposable formats and unbranded clinic-grade alternatives. Price differentiation rests on sterilization certification depth and climate-stable barrier engineering. Cost compression in standard disposable tiers intensifies because polypropylene resin costs track Gulf petrochemical output fluctuations. Ministry of Health procurement committees exhibit highest price sensitivity, while Dubai's private hospital networks prioritize total cost of ownership including reduced pharmacy labor.
Supply Chain Analysis
Regional distribution centers in Jeddah and Dubai industrial zones anchor hub-and-spoke patterns serving Gulf health systems and North African re-export channels. Manufacturing concentrates in Saudi Arabia, the UAE, and Egypt's Cairo-Alexandria corridor. Raw material sourcing draws from regional petrochemical complexes for medical-grade polypropylene, borosilicate glass imports, and 304-grade stainless steel cannula alloys. Single-source sterilization capacity in Jeddah and Dubai creates geographic chokepoints for product release timelines. Distribution runs through hospital group purchasing organization portals and traditional medical device distributors serving fragmented clinic networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The MENA syringes and cannula market represents a late-cycle quality story as homecare expansion protocols and biologics cold-chain requirements pull procurement toward premium prefilled formats with integrated safety engineering and serialized traceability.
For Market Incumbents: Hedge against margin erosion in standard disposable tiers by deepening backward integration into polymer compounding and sterile barrier packaging engineering. SFDA timeline compression threatens suppliers lacking simultaneous sterilization validation and clinical equivalence documentation capabilities. Prioritize capacity addition in Egypt's tariff-advantaged production corridor to capture North African re-export volumes.
For New Entrants and Emerging Players: Launch via direct-to-clinic distribution models bypassing traditional medical device distributors through hospital group purchasing organization portals. Egypt's diagnostic laboratory segment and Jordan's sterilization documentation hub functions offer the most penetrable white-space targets. Emphasize automated quality management platforms addressing real-time environmental monitoring mandates.
For Investors and Strategic Acquirers: Consolidation pressure builds where sterile packaging engineering talent scarcity intersects with SFDA registration timeline compression, favoring acquisition of regional specialists with pre-certified barrier capabilities and Gulf manufacturing footprints. Long-term viability centers on suppliers capable of simultaneous multi-jurisdiction certification. Watch for harmonization gaps between Gulf standards and emerging African market requirements as the inflection signal for distribution network extension strategies.
| Strategic Initiative | Industry Significance |
|---|---|
| SFDA Sterilization Certification Investment | Accelerates market access velocity for prefilled syringe formats in Saudi Ministry of Health tenders. |
| Egyptian Manufacturing Localization | Captures tariff advantages for re-export across North African markets with harmonizing device regulations. |
| Hospital GPO Portal Integration | Bypasses distributor margins and opens direct contracting channels with Dubai private hospital networks. |
| Climate-Stable Barrier Packaging R&D | Addresses 50°C ambient logistics requirements for Gulf supply chain integrity. |
| Safety-Engineered Device Platform Launch | Positions for emerging needlestick prevention mandates across Gulf Cooperation Council jurisdictions. |
Research Methodology
Direct dialogue with hospital procurement managers, biomedical engineers, GPO contracts specialists, and sterile packaging quality directors grounded the qualitative foundation, cross-referenced against SFDA registration databases, MOHAP traceability compliance filings, hospital tender documentation, and customs import records for medical device categories. Bottom-up facility-level demand estimation and top-down health system expenditure analysis were triangulated to validate segment sizing.
Segment-level outputs across product type, end user, material, and application dimensions were generated through the projection horizon, with compound annual growth rates derived from procedural volume trajectories in Saudi Arabia's hospital sector, biologics pipeline expansion in Gulf oncology units, and homecare protocol adoption curves. Modeled inputs incorporated sterilization validation timeline compression effects, polypropylene resin cost volatility assumptions, and regulatory harmonization progress between Gulf and North African jurisdictions.
Forecast precision tightens around the base case; tail outcomes carry wider variance under abrupt SFDA guidance revisions, gamma irradiation facility capacity constraints, or petrochemical complex output disruptions. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Supplies
Anesthesia Syringes and Needles Market
Medical Supplies
Asia-Pacific Insulin Syringe Market
Medical Supplies
Swab Cups Market
Medical Supplies
Global Adhesive Bandages Market
Medical Supplies
Europe Sharps Containers Market
Medical Supplies
Surgical Collagen Powders Market
Medical Supplies
Combat Dressing Market
Medical Supplies
Europe Medical Clothing Market
Medical Supplies
Western Europe Sterile Gloves Market
Medical Supplies
Global Automated Blood Tube Labeler and Specimen Transport Box Market
Medical Supplies
Medical Bags Market
Medical Supplies
France Hospital Supplies Market
Medical Supplies
Compression Garments and Stockings Market
Medical Supplies
Middle East and Africa Medical Rubber and Balloon Products Market
Medical Supplies
Emergency Transfer Vacuum Mattress Market
Medical Supplies
Anesthesia Disposables Market