
 South America Respiratory Monitoring Market | 2026-2036
South America Respiratory Monitoring Market Size, Share, and Industry Trends Forecast 2026-2036
South America Respiratory Monitoring Market Analytics
Hospital procurement departments is collapsing as the dominant buyer archetype while homecare providers gain purchasing influence across Brazil and Colombia. Philips sustains broad geographic coverage through established distribution networks in São Paulo and Rio de Janeiro. Medtronic anchors its position via deep specialization in intensive-care ventilator-integrated monitoring systems. Masimo differentiates through proprietary pulse oximetry technology that commands premium placement in tertiary facilities.
South America respiratory monitoring encompasses devices that measure pulmonary ventilation, gas exchange, and airway patency through sensors detecting airflow, pressure, oxygen saturation, and end-tidal carbon dioxide, typically operating within clinical accuracy thresholds of ±2% for SpO2 and ±0.3 kPa for etCO2. These systems serve to detect respiratory deterioration, titrate therapeutic interventions, and enable early discharge through remote surveillance. Portable monitors represent the fastest-expanding product category as ambulatory surgical centers and homecare networks prioritize mobility over bedside footprint. Pulse oximetry technology leads installed base volume but capnography is displacing it in post-surgical wards where opioid-induced respiratory depression demands continuous etCO2 tracking. Sleep apnea devices occupy concentrated margin pools due to recurring consumables revenue and long-term patient compliance protocols.
ANVISA governs medical device registration and post-market surveillance in Brazil, while Colombia's INVIMA and Argentina's ANMAT enforce parallel conformity requirements that fragment certification pathways for multinational suppliers. ISO 80601-2-55 and IEC 60601-1-8 standards shape electrical safety and alarm performance specifications that manufacturers must satisfy before market entry. Stakeholders must monitor pending Mercosur harmonization initiatives that could unify technical documentation requirements across Brazilian, Argentine, and Uruguayan jurisdictions.
Market Dynamics
ANVISA's accelerated registration pathway for connected monitoring platforms is compressing time-to-market for remote respiratory systems, forcing incumbent suppliers to reconfigure their Brazilian commercial operations around software-integrated hardware bundles rather than standalone devices.
Growth Catalysts
- Homecare network expansion:Post-acute care providers across São Paulo and Minas Gerais are deploying portable pulse oximetry and capnography systems to reduce hospital readmission penalties, creating pull-through demand for remote data platforms.
- ANVISA's risk-based classification update:The 2023 framework reclassifies non-invasive monitoring software as Class II devices with abbreviated technical documentation, slashing registration timelines for cloud-connected platforms.
- Opioid surveillance mandates:Colombian tertiary hospitals now require continuous etCO2 monitoring in post-surgical wards, displacing intermittent spot-check protocols and expanding capnography installed base.
Market Restraints
- Import dependency for sensor modules:Brazil lacks domestic manufacturing capacity for SpO2 and etCO2 sensor assemblies, exposing procurement costs to dollar-denominated input volatility and freight congestion at Santos port.
- Fragmented reimbursement codes:Brazil's SUS, Colombia's EPS networks, and Argentina's obras sociales maintain non-aligned coverage catalogs for remote monitoring, forcing suppliers to maintain parallel pricing structures.
- Technical limitation in connectivity infrastructure:Rural corridors in Brazil's North and Northeast regions lack reliable 4G coverage, degrading real-time alarm transmission from remote respiratory monitors to clinical command centers.
Strategic Opportunities
- Underpenetrated Colombian homecare segment:Bogotá and Medellín home health agencies currently deploy remote monitoring at one-third Brazilian penetration rates, presenting first-mover expansion territory for platform-integrated device suppliers.
- Technology convergence of pulse oximetry and sleep diagnostics:Wearable multi-parameter patches combining SpO2, actigraphy, and nasal airflow sensing are opening ambulatory sleep apnea diagnosis outside polysomnography centers.
- Mercosur harmonization tailwind:Pending technical documentation mutual recognition between Brazil, Argentina, and Uruguay would allow single-registration market access across 280 million consumers.
Industry Challenges
- Biomedical engineering talent scarcity:Brazilian universities graduate insufficient respiratory device specialists to support field service networks spanning the southeastern hospital corridor, forcing manufacturers to import technical personnel from Mexico and Portugal.
- Legacy system integration complexity:Tertiary facilities in São Paulo operate heterogeneous ventilator fleets from multiple generations, complicating seamless data integration with new monitoring platforms and requiring costly middleware development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South America Respiratory Monitoring Market |
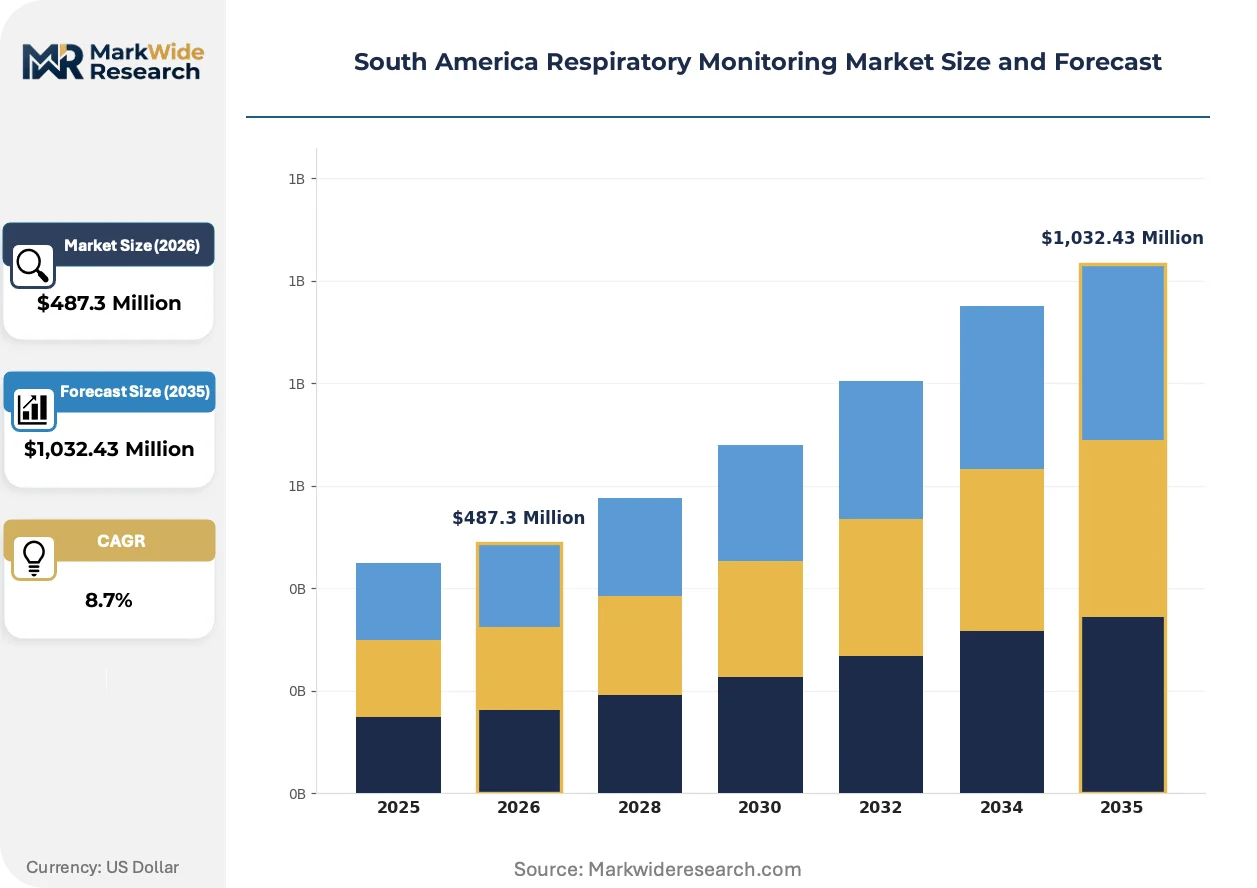
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $1,032.43 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable Monitors, Stationary Monitors, Wearable Devices, Sleep Apnea Devices End User: Hospitals, Homecare Providers, Diagnostic Centers, Emergency Services Technology: Capnometers, Pulse Oximeters, Spirometers, Nebulizers Application: Chronic Obstructive Pulmonary Disease, Asthma Management, Sleep Disorders, Acute Respiratory Failure |
| Companies Covered | Drägerwerk AG & Co. KGaA, Koninklijke Philips N.V., Medtronic Plc, Masimo Corporation, GE Healthcare, ResMed Inc., Fisher & Paykel Healthcare Limited, Smiths Medical, Hamilton Medical, Others |
| Regions Covered | South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South America Respiratory Monitoring Market Evolving Landscape
Software-defined monitoring architectures are displacing hardware-centric product strategies across South American respiratory care, with cloud analytics and algorithmic alarm management becoming the primary competitive differentiators rather than sensor precision alone.
Multi-parameter wearable patches integrating SpO2, respiratory rate, and temperature sensing are decomposing the traditional bedside monitor category. Ambulatory surgical centers in Rio de Janeiro and Porto Alegre are adopting these systems for same-day discharge protocols. The technology is decomposing capital equipment purchasing into recurring software subscription models that compress upfront procurement cycles.
ANVISA's updated software-as-medical-device guidance is mandating cybersecurity documentation for all cloud-connected respiratory platforms. Manufacturers must now submit penetration testing reports and data encryption protocols alongside traditional safety filings. Intensive-care ventilator-integrated systems face the steepest compliance burden, with several suppliers withdrawing legacy platforms rather than retrofitting security architectures.
Hospital procurement departments are fragmenting into specialty buying committees with independent authority for connected care technology. São Paulo's largest private hospital networks now maintain separate digital health procurement teams that bypass traditional biomedical engineering gatekeepers. This shift is most visible in southeastern Brazil, where three-tier pricing structures separate premium algorithm-enabled platforms from basic hardware-only configurations.
South America Respiratory Monitoring Market Segmentation
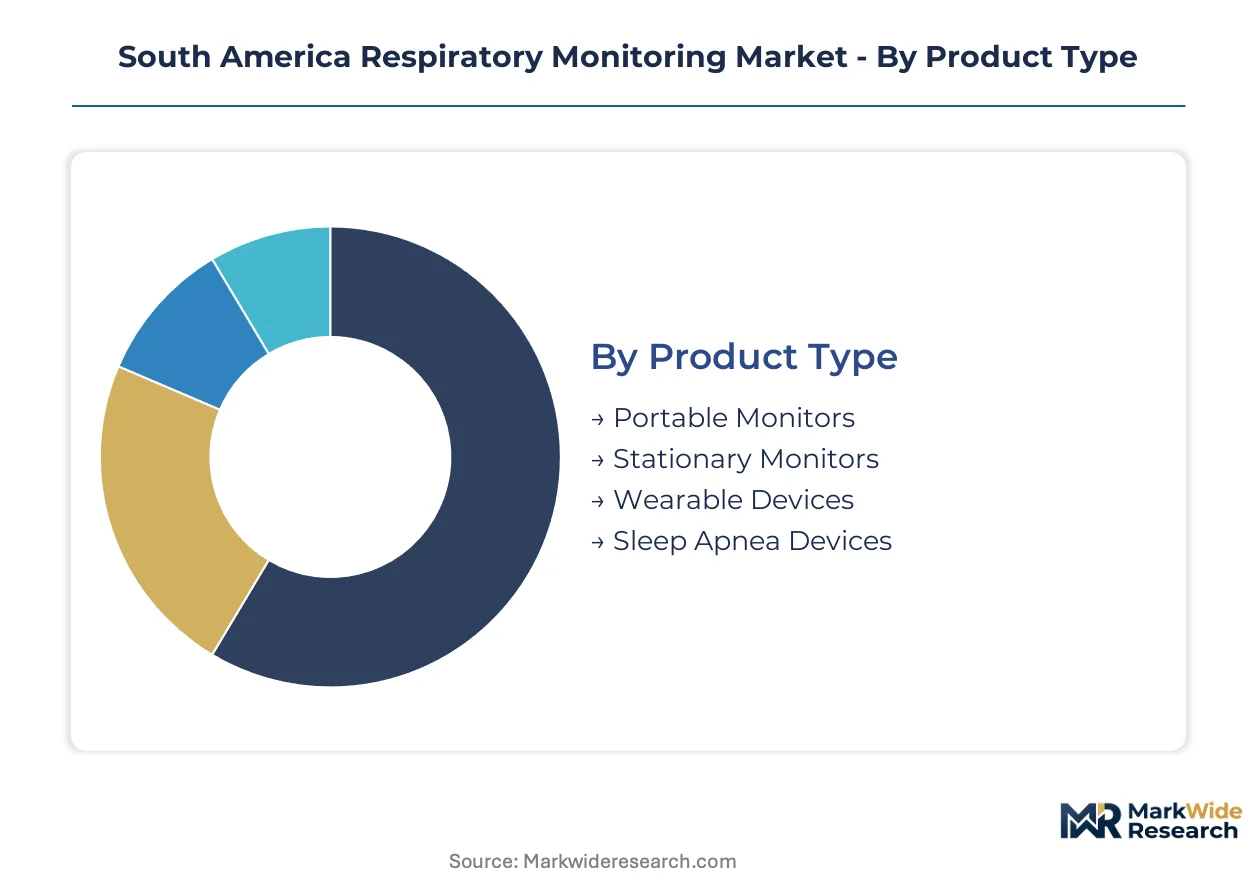
Channel dynamics in South American respiratory monitoring diverge sharply between capital-intensive hospital procurement and recurring-revenue homecare subscriptions. Understanding how each segment flows through these distinct commercial pathways determines pricing architecture and service bundling strategies for device manufacturers.
Product Type:
Portable monitors and wearable devices move predominantly through homecare provider channels with software subscription attachments, while stationary systems and sleep apnea devices anchor hospital and direct-to-patient e-commerce flows respectively.
- Portable Monitors:Battery-powered multi-parameter units weighing under 2kg integrate SpO2, capnography, and respiratory rate sensing for ambulatory surgical discharge protocols. São Paulo's post-acute networks deploy these for remote surveillance of COPD patients, with procurement bundled into per-patient monthly fees rather than capital expenditure.
- Stationary Monitors:Bedside systems with 15-inch displays and centralized alarm management dominate ICU footprints across Brazil's southeastern hospital corridor. Tertiary facilities in Minas Gerais prioritize these for ventilator-integrated workflows, though procurement cycles stretch 18-24 months due to ANVISA registration requirements for software-defined configurations.
- Wearable Devices:Chest-worn patches with Bluetooth telemetry enable continuous monitoring outside clinical settings.
- Sleep Apnea Devices:CPAP machines with cloud-connected compliance tracking generate recurring consumables revenue through mask and tubing replacements.
Stationary monitors dominate installed base. Portable monitors are where expansion concentrates.
End User:
Customer archetypes stratify by reimbursement mechanism — SUS-funded hospitals, EPS-reimbursed homecare, out-of-pocket diagnostic services, and municipal-funded emergency response.
- Hospitals:Public and private acute care facilities across São Paulo and Rio de Janeiro operate centralized biomedical engineering departments that evaluate total cost of ownership across 7-10 year equipment lifecycles. Procurement committees increasingly separate digital health platforms from hardware, creating dual vendor relationships.
- Homecare Providers:Post-acute agencies in Colombia's Bogotá corridor and Brazil's Minas Gerais deploy remote monitoring to reduce readmission penalties. These customers prioritize interoperability with existing EMR systems over device specifications.
- Diagnostic Centers:Sleep labs and pulmonary function clinics purchase spirometry and polysomnography equipment.
- Emergency Services:Municipal ambulance fleets require ruggedized portable monitors with 8-hour battery autonomy.
Hospitals anchor revenue concentration. Homecare providers are climbing the fastest.
Technology:
Technology selection tracks clinical setting acuity — capnography for perioperative surveillance, pulse oximetry for general ward screening, spirometry for outpatient diagnosis, nebulization for therapeutic delivery.
- Capnometers:Mainstream and microstream etCO2 sensors with sampling rates of 50-100ml/min enable continuous respiratory depression detection in post-surgical wards. Colombian tertiary hospitals mandate these for opioid surveillance, displacing intermittent spot-check protocols.
- Pulse Oximeters:Transmission and reflectance SpO2 sensors operate at 660nm and 940nm wavelengths with ±2% accuracy thresholds. These devices command the largest installed base volume across all South American clinical settings due to low unit cost and minimal training requirements.
- Spirometers:Volume-displacement and flow-sensing devices measure FEV1 and FVC for COPD and asthma diagnosis.
- Nebulizers:Jet, ultrasonic, and mesh technologies deliver bronchodilator aerosols for acute exacerbation management.
Pulse oximeters dominate installed base. Capnometers are where expansion concentrates.
Application:
Disease-specific demand patterns align with epidemiological burden and reimbursement coverage — COPD and asthma management through SUS chronic care programs, sleep disorders via private insurance, acute failure through emergency protocols.
- Chronic Obstructive Pulmonary Disease:Long-term oxygen therapy and non-invasive ventilation monitoring consume the highest device utilization hours. Brazil's SUS reimburses home oxygen concentrators and BiPAP systems for GOLD stage III-IV patients, creating stable recurring demand for connected monitoring accessories.
- Asthma Management:Peak flow monitoring and fractional exhaled nitric oxide testing guide controller therapy titration in pediatric and adult populations. Diagnostic centers in São Paulo deploy these technologies for allergy-asthma comorbidity screening.
- Sleep Disorders:Home sleep apnea testing with portable polygraphy displaces in-lab polysomnography.
- Acute Respiratory Failure:High-acuity monitoring in emergency and ICU settings demands full parameter suites.
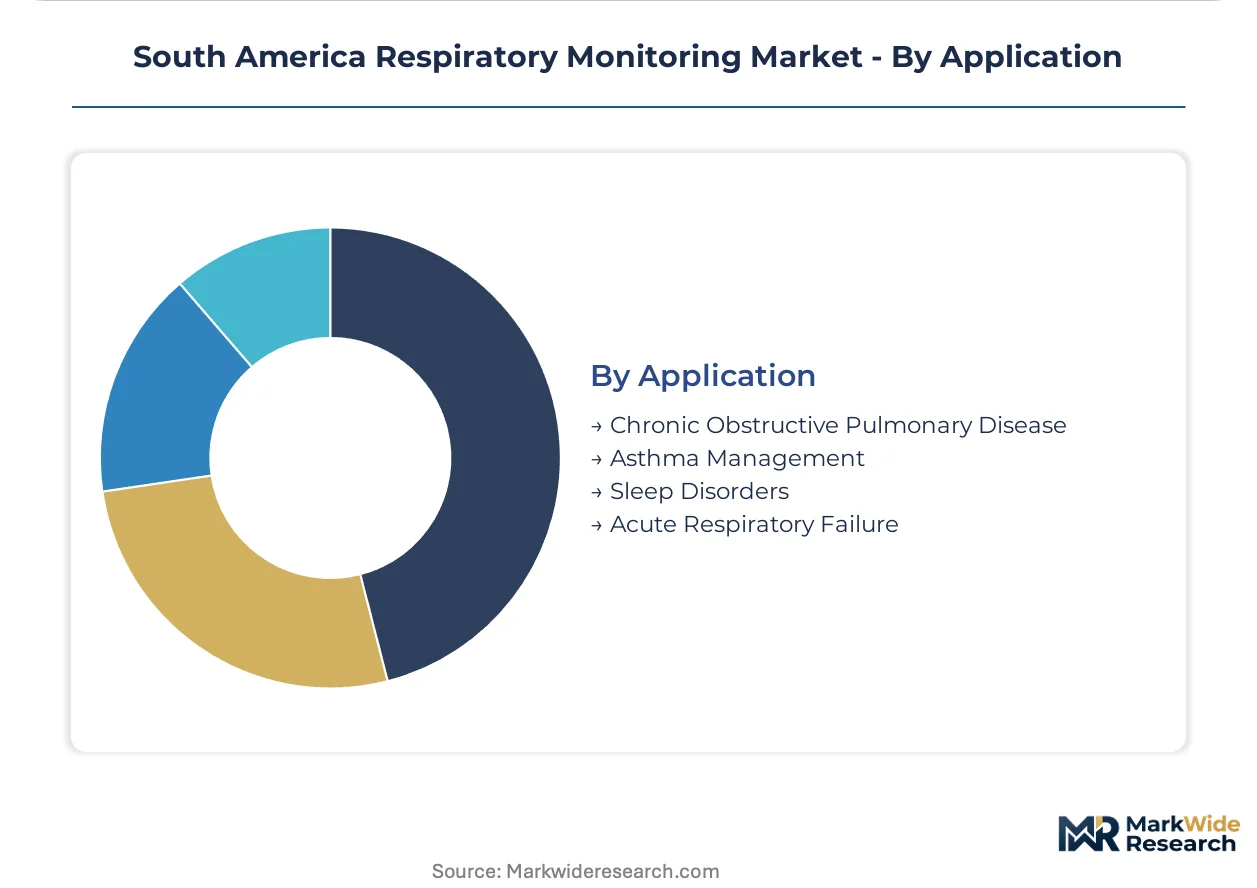
COPD management dominates installed base. Sleep disorders are where expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Santos anchors Brazil's respiratory device import corridor, processing over 80% of inbound medical electronics from Asia and North America while freight congestion periodically disrupts sensor module availability for domestic manufacturers.
Brazil
ANVISA's 2023 risk-based reclassification of connected monitoring software compresses registration timelines for cloud-integrated platforms, accelerating market entry for remote respiratory systems. São Paulo's southeastern hospital corridor concentrates procurement authority, with tertiary facilities in Minas Gerais deploying ventilator-integrated monitoring at scale.
Colombia
INVIMA enforces opioid surveillance mandates requiring continuous etCO2 monitoring in post-surgical wards, displacing intermittent spot-check protocols across Bogotá's tertiary network. Homecare providers in Medellín currently deploy remote respiratory tracking at one-third Brazilian penetration rates, creating first-mover expansion territory for platform suppliers.
Argentina
ANMAT maintains parallel conformity requirements that fragment certification pathways, though pending Mercosur harmonization could unify technical documentation with Brazilian and Uruguayan jurisdictions. Buenos Aires province anchors domestic demand, with private hospital networks prioritizing pulse oximetry upgrades amid currency volatility.
Chile
ISP certification requirements align closely with ISO 80601-2-55 electrical safety standards, streamlining entry for manufacturers already compliant with European MDR frameworks. Santiago's metropolitan health network concentrates purchasing influence, with ambulatory surgical centers adopting portable monitors for same-day discharge protocols.
Peru
DIGEMID governs medical device registration with technical documentation requirements that lag regional counterparts, extending time-to-market for connected platforms. Lima's private clinic clusters drive premium device adoption, while northern and southern regions depend on municipal procurement of basic respiratory screening equipment.
South America Respiratory Monitoring Market Competitive Landscape
Listed leaders compete with private specialists across software-integrated hardware bundles, with publicly traded multinationals commanding ICU-installed bases while private specialists capture homecare subscription revenue. The vendor base stratifies into three tiers: premium algorithm-enabled platforms, standard hardware-centric configurations, and economy spot-check devices. Dominant competitive moves include M&A activity targeting remote monitoring software capabilities and strategic partnerships with post-acute care networks to secure recurring revenue streams.
Within the premium-tier vector, Koninklijke Philips N.V. and Medtronic Plc exemplify scale-driven positioning through established distribution networks and intensive-care specialization respectively. Masimo Corporation occupies a position within the proprietary technology archetype, commanding placement through differentiated sensing platforms. These three listed entities represent contrasting strategic postures: geographic breadth versus clinical depth versus technology premium.
| Leading Market Players |
|---|
| Drägerwerk AG & Co. KGaA |
| Koninklijke Philips N.V. |
| Medtronic Plc |
| Masimo Corporation |
| GE Healthcare |
| ResMed Inc. |
| Fisher & Paykel Healthcare Limited |
| Smiths Medical |
| Hamilton Medical |
| Others |
Value Network & Pricing Analysis
Scale economies in SpO2 and etCO2 sensor module manufacturing concentrate production in Asian electronics corridors, compressing unit costs for tier-one suppliers while Brazilian assemblers face margin squeeze from dollar-denominated component imports and port congestion penalties.
Pricing Analysis
Volume-discount tiering structures separate algorithm-enabled platforms from basic hardware configurations across São Paulo's hospital procurement committees. Price differentiation rests on ANVISA registration status and software integration depth, with cloud-connected systems commanding premium placement. Cost compression in economy spot-check devices is intensifying as Colombian EPS networks consolidate purchasing. Public SUS-funded hospitals exhibit highest price sensitivity; private tertiary facilities in Rio de Janeiro demonstrate lowest.
Supply Chain Analysis
Inbound logistics costs through Santos port fluctuate with container availability on Asia-Brazil trade lanes, exposing domestic distributors to freight congestion surcharges. Manufacturing draws from China, Malaysia, and Mexico for sensor assemblies, printed circuit boards, and plastic housings. Single-source vulnerability concentrates in SpO2 emitter-detector pairs from Taiwanese optoelectronics specialists. Distribution runs through authorized medical device distributors with ANVISA-established import licenses.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story where ANVISA registration timelines and ventilator-integrated system switching costs entrench incumbent positions against software-native challengers.
For Market Incumbents: Shield installed base revenue by deepening software subscription attachments before hardware-only competitors achieve ANVISA Class II certification for cloud platforms. Accelerate field service network expansion across Minas Gerais to preempt biomedical engineering talent scarcity. Prioritize middleware development for legacy ventilator fleet integration.
For New Entrants and Emerging Players: Lead with underpenetrated Colombian homecare segments where Bogotá and Medellín agencies deploy remote monitoring at one-third Brazilian rates. Target ambulatory surgical center procurement committees in Porto Alegre seeking same-day discharge protocols. Pursue strategic partnerships with post-acute networks rather than direct hospital sales.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors software-defined monitoring architectures over hardware-centric legacy platforms. Long-term viability hinges on recurring revenue attachment rates and cybersecurity compliance documentation. Acquisition targets should demonstrate ANVISA registration completion and established GPO contracts. Watch Mercosur harmonization implementation as inflection indicator for regional scale economics.
| Strategic Initiative | Industry Significance |
|---|---|
| ANVISA Class II Registration Acceleration | Compresses time-to-market for cloud-connected platforms against legacy competitors. |
| Homecare Network Partnership | Secures recurring subscription revenue through post-acute provider channel control. |
| Legacy Ventilator Middleware Development | Enables data integration with heterogeneous ICU fleets across São Paulo corridor. |
| Cybersecurity Documentation Investment | Satisfies ANVISA software-as-medical-device guidance for platform market entry. |
| Colombian First-Mover Expansion | Captures underpenetrated Bogotá-Medellín homecare before Brazilian saturation. |
Research Methodology
A standing panel of hospital biomedical engineers, homecare procurement directors, ANVISA regulatory consultants, and GPO contracts managers provided ongoing calibration against secondary validation from FDA 510(k) filings, ANVISA registration databases, hospital procurement records, and import customs data. Bottom-up device shipment estimates triangulated with top-down healthcare expenditure flows.
Consistency checks validated volume and value outputs against external benchmarks across the projection horizon. Segmentation modeling spanned product type, end-user archetype, technology platform, and application area. CAGRs derived from fitted growth curves incorporating epidemiological burden projections, reimbursement policy trajectories, and connectivity infrastructure rollout patterns.
The analysis sits within stated boundaries; outcomes outside ANVISA regulatory stability or SUS reimbursement continuity would require recalibration. Forecasts reflect documented assumptions regarding sensor module import cost trajectories and 4G network expansion timelines. Practitioners should keep alternative scenarios live as Mercosur harmonization and Colombian opioid surveillance mandate enforcement evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Patient Monitoring
South America Cardiac Monitoring Market
Patient Monitoring
Portable Multi-Parameter Monitors Market
Patient Monitoring
North America Respiratory Monitoring Market
Patient Monitoring
Patient Monitoring Systems Market
Patient Monitoring
Remote Patient Monitoring Devices Market
Patient Monitoring
Europe Wireless Healthcare Market
Patient Monitoring
Europe Patient Monitoring Devices Market
Patient Monitoring
Gas Exchange Monitor Market
Patient Monitoring
Urine Output Monitoring Systems Market
Patient Monitoring
ECG Monitoring System Market
Patient Monitoring
South America Fetal and Neonatal Monitoring Market
Patient Monitoring
Canada Patient Monitoring Devices Market
Patient Monitoring
South America Patient Monitoring Market
Patient Monitoring
Drowsiness Monitoring System Market
Patient Monitoring
South America Hemodynamic Monitoring Market
Patient Monitoring
Urine Monitoring Systems Market