
 Medical Digital Imaging Systems Market | 2026-2036
Medical Digital Imaging Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Medical Digital Imaging Systems Market Intelligence
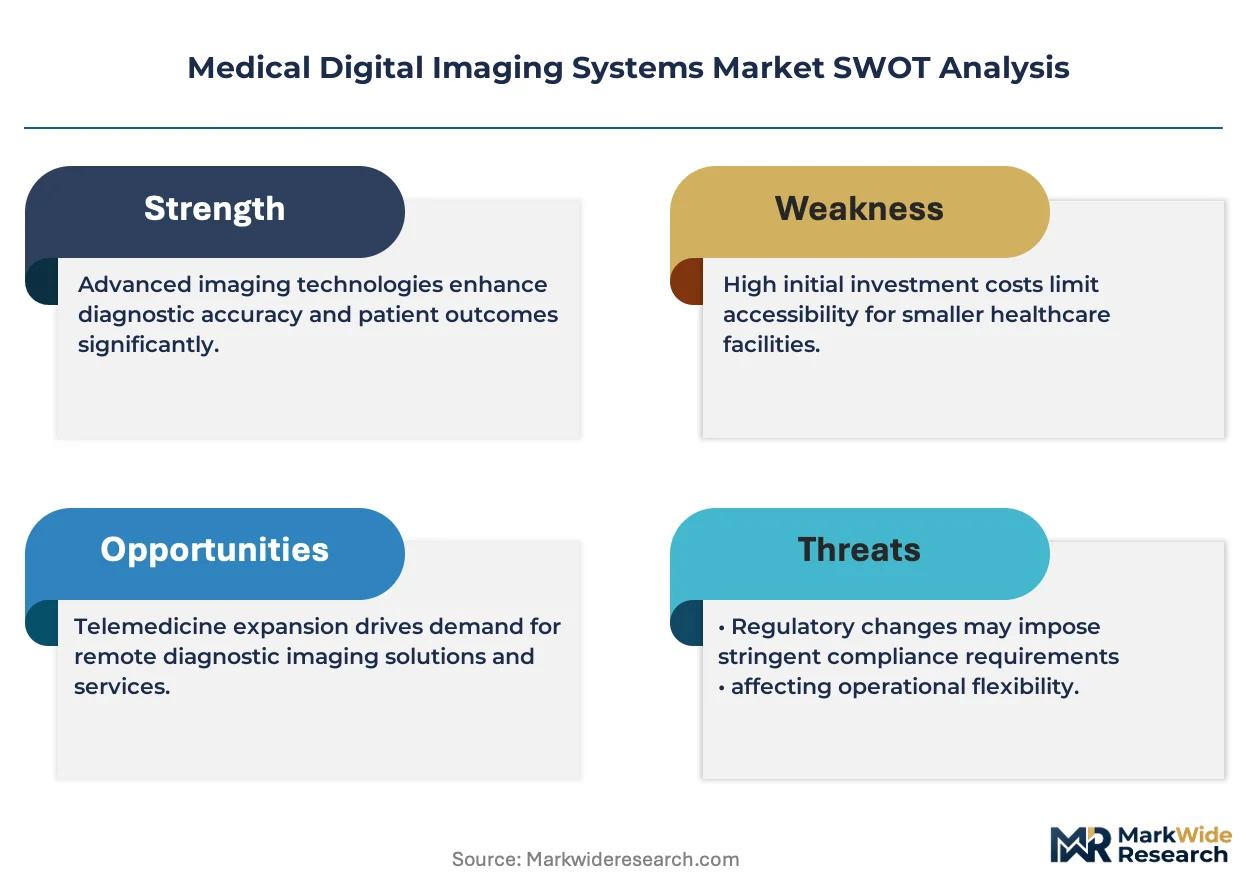
Artificial intelligence integration across imaging workflows is fragmenting traditional equipment procurement patterns. Siemens Healthineers leverages embedded AI reconstruction to differentiate its CT and MRI portfolios. GE Healthcare anchors its position through extensive installed-base service contracts. Canon Medical Systems Corporation specializes in photon-counting CT detectors that reduce radiation dose.
Medical digital imaging systems comprise electronic hardware and software platforms that capture, process, store, and display anatomical and functional patient data using X-ray, magnetic resonance, ultrasound, or computed tomography physics, with spatial resolution thresholds typically ranging from sub-millimeter to several millimeters depending on modality. These systems enable non-invasive disease detection, treatment planning, and interventional guidance across clinical settings. CT scanners command premium capital allocations due to their irreplaceable role in emergency and trauma diagnostics. Ultrasound systems occupy expanding point-of-care settings where portability and lower per-procedure cost reshape deployment economics. MRI systems sustain strong demand in neurology and musculoskeletal applications where soft-tissue contrast superiority justifies longer scan times and higher infrastructure investment.
FDA 510(k) clearance pathways and EMA MDR conformity assessments govern product commercialization timelines and clinical claim substantiation in major markets. The FDA's evolving software-as-a-medical-device framework imposes additional validation burdens on AI-enabled image analysis tools. ISO 13485 quality management certification remains mandatory for supply eligibility into regulated health systems. Stakeholders must weigh regulatory jurisdiction complexity against the revenue pull of multi-modality platform consolidation.
Market Dynamics
AI-integrated reconstruction algorithms are compressing scan times and radiation doses while forcing radiology departments to restructure capital allocation around software-enabled platforms rather than hardware specifications alone.
Growth Catalysts
- FDA 510(k) software-as-a-medical-device pathway:Accelerated clearance timelines for AI-enabled diagnostic tools are expanding reimbursable clinical indications and pulling forward replacement cycles for legacy CT and MRI systems.
- Oncology imaging demand:Precision radiotherapy planning and immunotherapy response monitoring are driving hospital networks to upgrade to spectral CT and quantitative MRI platforms with enhanced tissue characterization.
- Japan's PMDA reimbursement alignment:Favorable procedure codes for advanced imaging modalities are concentrating procurement decisions in Tokyo and Osaka metropolitan hospital networks.
Market Restraints
- Helium supply concentration:MRI magnet cooling depends on helium sourced from Qatar and the United States, with price volatility and export restrictions threatening operational continuity for high-field systems.
- EMA MDR technical documentation:Expanded clinical evidence requirements for Class III imaging software are extending conformity assessment timelines and delaying EU market entry.
- Interventional radiology substitution:Miniaturized ultrasound and optical coherence tomography systems are capturing cardiac and ophthalmic diagnostic volumes previously reserved for CT angiography.
Strategic Opportunities
- India's PLI scheme for medical electronics:Domestic manufacturing incentives are creating localized assembly opportunities for mid-range ultrasound and digital X-ray systems serving tier-2 and tier-3 cities.
- Photon-counting CT convergence:Direct conversion detector materials are enabling spectral imaging at diagnostic dose levels, opening cardiac and pediatric applications previously constrained by radiation exposure limits.
- Point-of-care deployment channels:Emergency departments and ambulatory surgical centers are adopting portable ultrasound and mobile X-ray systems outside traditional radiology department procurement hierarchies.
Industry Challenges
- Computational radiology talent scarcity:Deep learning model validation and regulatory submission preparation require hybrid clinical-engineering expertise that academic pipelines have not scaled to match industry demand.
- ISO 13485 audit backlogs:Notified body capacity constraints are stretching quality management system certification timelines and delaying supplier qualification for multi-modality platform launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Medical Digital Imaging Systems Market |
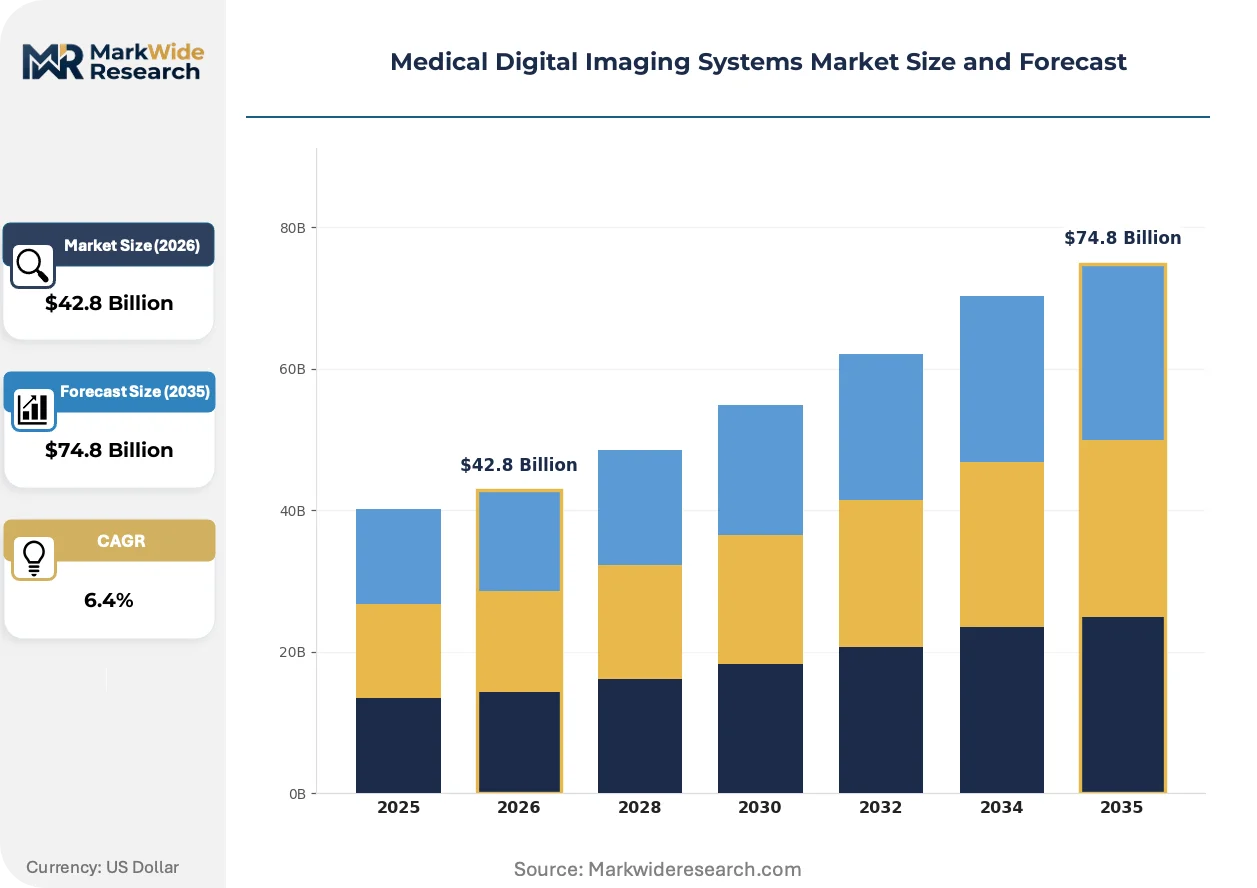
| Market Size in 2026 | $42.8 Billion |
| Market Size in 2035 | $74.8 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: X-ray Systems, MRI Systems, Ultrasound Systems, CT Scanners End User: Hospitals, Diagnostic Centers, Research Laboratories, Specialty Clinics Technology: Digital Radiography, Computed Tomography, Magnetic Resonance Imaging, 3D Imaging Application: Cardiology, Oncology, Orthopedics, Neurology |
| Companies Covered | Canon Medical Systems Corporation, Hologic, Inc., GE Healthcare, Hitachi, Ltd., Shimadzu Corporation, Siemens Healthineers, FUJIFILM Holdings Corporation, Mindray Medical International Limited, Koninklijke Philips N.V., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Medical Digital Imaging Systems Market Strategic Shifts & Innovations
Workflow automation and edge computing architectures are redistributing image processing from centralized PACS servers to scanner-embedded GPUs, altering service contract structures and capital depreciation schedules.
Photon-counting detector technology is migrating from research installations to clinical CT platforms. Academic medical centers in Germany and Japan are adopting Siemens Healthineers' NAEOTOM Alpha systems for cardiac and thoracic imaging. This migration from energy-integrating to photon-counting detection is compressing the technical differentiation window for conventional CT manufacturers and forcing accelerated R&D commitments.
The EU AI Act's risk classification framework for medical imaging software is imposing conformity assessment obligations on algorithm developers previously exempt under general-purpose software exemptions. High-risk diagnostic applications now require notified body intervention and post-market performance monitoring. European radiology departments are prioritizing vendors with established quality management systems for machine learning lifecycle processes.
Hospital procurement committees are unbundling equipment acquisition from multi-year service agreements. Large health systems in the United States are negotiating direct software maintenance contracts with AI developers, bypassing original equipment manufacturer service hierarchies. This disintermediation is most pronounced in integrated delivery networks with centralized informatics capabilities and dedicated biomedical engineering staffing.
Medical Digital Imaging Systems Market Segmentation
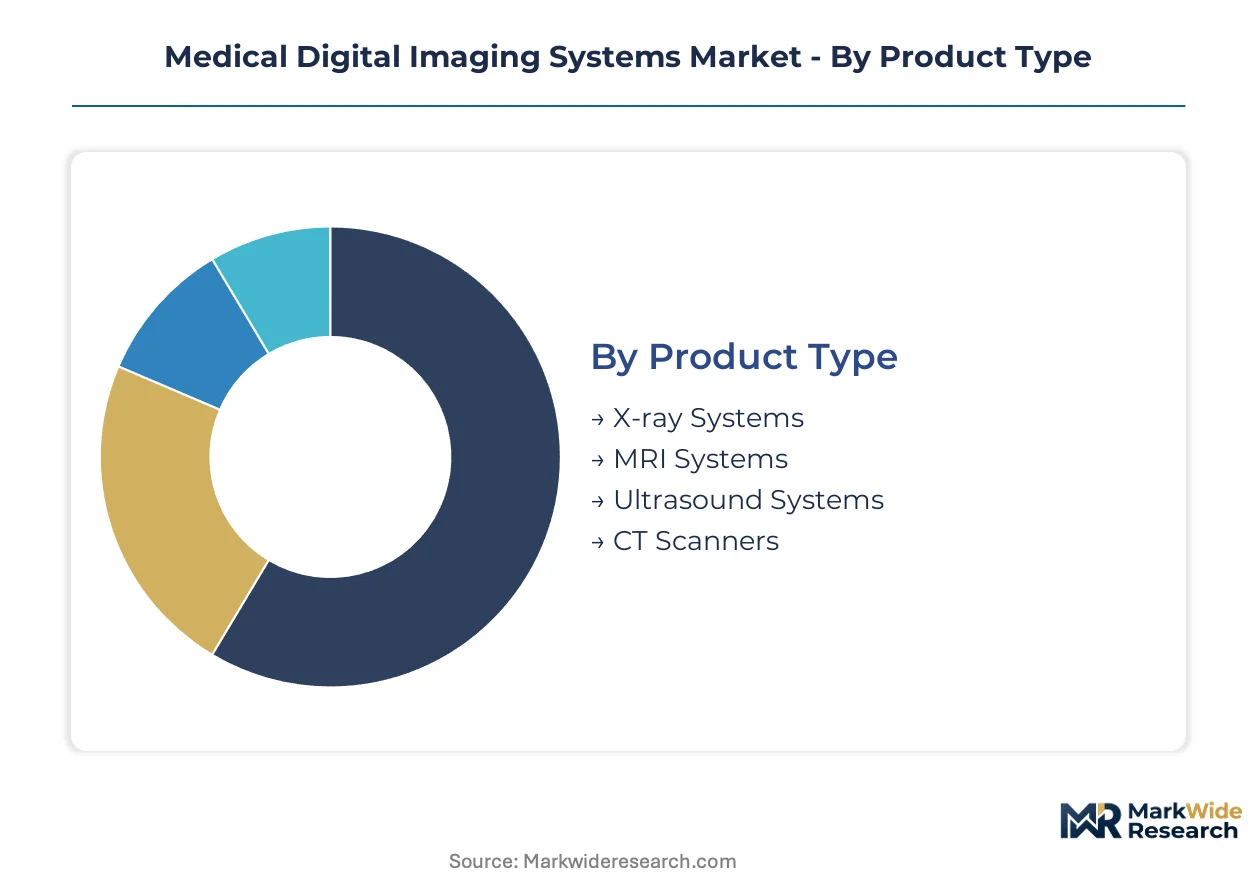
Segmentation in medical digital imaging systems determines procurement hierarchies, service contract structures, and software upgrade pathways. Hospital capital committees prioritize modality-specific performance metrics over bundled platform purchases when segment boundaries are clearly defined.
Product Type:
After-sales-service intensity varies sharply across modalities, with MRI systems demanding cryogenic maintenance contracts and CT scanners requiring tube replacement programs that reshape lifetime cost calculations.
- CT Scanners:Energy-integrating and photon-counting detector architectures generate cross-sectional anatomical datasets with sub-millimeter spatial resolution. Emergency departments in the United States and Germany prioritize spectral imaging capabilities for trauma triage, with procurement committees weighting radiation dose reduction specifications heavily in capital allocation decisions.
- MRI Systems:Superconducting magnets operating at 1.5T and 3.0T field strengths produce superior soft-tissue contrast through proton relaxation mapping. Neurology and musculoskeletal specialists in Japan's metropolitan hospital networks sustain demand despite helium supply volatility constraining high-field installations.
- Ultrasound Systems:Piezoelectric transducer arrays enable real-time anatomical imaging without ionizing radiation exposure.
- X-ray Systems:Digital radiography panels and fluoroscopy suites support skeletal and chest imaging workflows.
By volume, X-ray Systems leads. By growth pace, CT Scanners is ahead.
End User:
Procurement authority concentration differs materially across customer types, with integrated delivery networks centralizing imaging platform decisions while specialty clinics retain independent vendor relationships.
- Hospitals:Acute care facilities with emergency departments, surgical suites, and intensive care units deploy multi-modality imaging platforms across radiology, cardiology, and oncology service lines. United States health systems with centralized capital committees negotiate enterprise-wide service agreements covering CT, MRI, and ultrasound fleets.
- Diagnostic Centers:Outpatient imaging facilities operate high-throughput screening and diagnostic service models with rapid patient turnover requirements. Germany's statutory health insurance reimbursement frameworks favor standalone diagnostic centers for elective procedures, concentrating PET-CT and breast imaging volumes outside hospital settings.
- Research Laboratories:Academic medical centers and pharmaceutical development sites utilize preclinical and clinical imaging for protocol validation.
- Specialty Clinics:Cardiology, orthopedics, and women's health practices deploy point-of-care ultrasound and mini-C-arm fluoroscopy.
Hospitals command the largest installed base. Specialty Clinics are expanding most quickly.
Technology:
Regulatory clearance pathways segment technology adoption timelines, with FDA 510(k) software-as-a-medical-device frameworks accelerating AI-enabled reconstruction algorithm deployment compared to de novo classification requirements.
- 3D Imaging:Volumetric reconstruction algorithms generate multiplanar and surface-rendered datasets from CT, MRI, and ultrasound source acquisitions. Surgical planning applications in craniofacial reconstruction and joint replacement drive hospital investment in workstation-integrated visualization platforms.
- Magnetic Resonance Imaging:Radiofrequency coil arrays and gradient echo sequences enable functional and diffusion-weighted tissue characterization.
- Computed Tomography:Helical acquisition geometries and iterative reconstruction methods balance spatial resolution against radiation exposure.
- Digital Radiography:Flat-panel detectors and wireless cassette systems replace film-screen and computed radiography workflows.
Digital Radiography maintains the broadest installed footprint. 3D Imaging shows the steepest expansion trajectory.
Application:
Clinical indication specificity determines software feature requirements and reimbursement code alignment, with oncology applications demanding quantitative imaging biomarker capabilities that cardiac workflows do not require.
- Oncology:Tumor detection, staging, and treatment response monitoring utilize CT, PET-CT, MRI, and molecular imaging modalities with standardized measurement protocols. Precision radiotherapy planning in the United States and Japan drives spectral CT and quantitative MRI platform upgrades with RECIST-compatible lesion tracking.
- Cardiology:Coronary CT angiography, cardiac MRI, and stress echocardiography evaluate structural and functional cardiovascular pathology.
- Neurology:Stroke imaging protocols and functional MRI map cerebral perfusion and cortical activation patterns.
- Orthopedics:Musculoskeletal MRI and weight-bearing CT assess joint integrity and implant positioning.
Cardiology generates the highest procedure volume. Oncology is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany exports precision imaging components to hospital networks across the United States and Japan, establishing a dominant trade corridor in high-field MRI magnets and photon-counting CT detector arrays.
United States
Emergency departments and oncology centers drive CT and MRI procurement through integrated delivery networks. FDA 510(k) clearance pathways for AI-enabled reconstruction algorithms accelerate replacement cycles. Texas Medical Center in Houston anchors spectral CT adoption for trauma triage protocols.
Germany
Statutory health insurance reimbursement frameworks favor diagnostic center models for elective imaging procedures. EMA MDR conformity assessments govern software-as-a-medical-device commercialization timelines. Munich and Berlin metropolitan hospital networks concentrate procurement of quantitative MRI platforms for precision radiotherapy planning.
Japan
PMDA reimbursement alignment for advanced imaging modalities concentrates capital decisions in Tokyo and Osaka. METI industrial policy supports domestic manufacturing of superconducting magnet components. Nagoya medical device clusters supply gradient coil assemblies to regional OEMs.
China
NMPA regulatory harmonization with international standards accelerates market entry for multinational imaging platforms. Domestic hospital procurement committees prioritize mid-range ultrasound and digital X-ray systems for tier-2 city expansion. Shanghai and Beijing academic medical centers drive adoption of 3T MRI for neurological research applications.
India
PLI scheme incentives for medical electronics manufacturing create localized assembly opportunities for portable ultrasound systems. CDSCO regulatory pathways for Class B and C imaging devices streamline import substitution. Bangalore and Hyderabad diagnostic chains deploy digital radiography networks across tier-3 urban centers.
Medical Digital Imaging Systems Market Key Industry Players
Channel-controlling players compete with product-specialist players across procurement hierarchies. The market structure consolidates around diversified health technology conglomerates with installed-base service networks. Three archetypes dominate: full-platform OEMs with multi-modality portfolios, component specialists with detector or magnet expertise, and point-of-care device manufacturers emphasizing portability. M&A activity concentrates on AI software assets, while strategic partnerships redistribute service contract structures away from traditional equipment vendors.
Among diversified imaging platform providers, Siemens Healthineers and GE Healthcare occupy positions exemplifying full-modality integration. Canon Medical Systems Corporation represents the specialized detector technology archetype, with its organizational structure reflecting photon-counting CT development priorities. These three entities anchor competitive positioning across hospital procurement committees in the United States, Germany, and Japan.
| Leading Market Players |
|---|
| Canon Medical Systems Corporation |
| Hologic, Inc. |
| GE Healthcare |
| Hitachi, Ltd. |
| Shimadzu Corporation |
| Siemens Healthineers |
| FUJIFILM Holdings Corporation |
| Mindray Medical International Limited |
| Koninklijke Philips N.V. |
| Others |
Cost & Logistics Intelligence
Nagoya's superconducting magnet component clusters anchor MRI system cost structures, with gradient coil assembly capacity fluctuations transmitting directly into downstream pricing power for high-field installations across hospital procurement committees in Japan, Germany, and the United States.
Pricing Analysis
Energy-integrating CT platforms, photon-counting detector systems, and legacy analog X-ray architectures occupy distinct pricing tiers shaped by reconstruction algorithm sophistication and radiation dose reduction specifications. Three-tier pricing structure across premium, standard, and economy levels stratifies by FDA 510(k) clearance tier and ISO 13485 certification depth. Pricing pressure stems from hospital procurement committees unbundling equipment acquisition from multi-year service agreements. Diagnostic centers exhibit highest price sensitivity due to rapid patient turnover requirements, while academic medical centers prioritize spectral imaging capabilities over unit cost.
Supply Chain Analysis
Tariff exposure between Qatar and helium-dependent manufacturing clusters in the United States and Japan dominates supply chain risk planning for MRI magnet cooling systems. Superconducting wire production concentrates in Germany, Japan, and the United States, while photon-counting detector materials source from specialized semiconductor foundries in Japan and Germany. Single-source vulnerability for liquid helium rests on Qatari export policy and US strategic reserve releases. Distribution runs through OEM direct sales forces and authorized service networks with embedded biomedical engineering staffing.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics inflect around AI-enabled reconstruction algorithms that displace hardware-centric procurement hierarchies, with interoperability standards for DICOM-compliant AI workflows redistributing value capture toward software developers and away from traditional equipment vendors.
For Market Incumbents: Harden installed-base service contract structures against disintermediation by hospital informatics departments negotiating direct AI software maintenance agreements. Prioritize backward integration into photon-counting detector manufacturing to defend technical differentiation windows against Canon Medical Systems Corporation's specialized positioning. Lock GPO contract exclusivity clauses before point-of-care ultrasound vendors capture emergency department procurement authority.
For New Entrants and Emerging Players: Pursue India's PLI scheme incentives for localized assembly of mid-range ultrasound systems serving tier-2 and tier-3 city diagnostic chains. Target point-of-care deployment channels outside traditional radiology department hierarchies, where portable X-ray and emergency ultrasound procurement decisions concentrate in individual department budgets rather than centralized capital committees. Lead with AI-integrated reconstruction algorithms cleared under FDA 510(k) software-as-a-medical-device pathways.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified health technology conglomerates spinning off non-core imaging assets amid platform consolidation pressures. Long-term viability hinges on software-enabled recurring revenue streams displacing transactional equipment sales. Watch for EU AI Act conformity assessment bottlenecks that favor vendors with established machine learning lifecycle quality management systems as the inflection signal for competitive positioning shifts.
| Strategic Initiative | Industry Significance |
|---|---|
| Photon-Counting CT Platform Launch | Spectral imaging at diagnostic dose levels opens cardiac and pediatric applications previously constrained by radiation exposure limits. |
| AI Reconstruction Algorithm FDA Submission | Software-as-a-medical-device clearance accelerates reimbursable clinical indications and pulls forward replacement cycles. |
| Hospital System Partnership Agreement | Enterprise-wide service contracts covering CT, MRI, and ultrasound fleets lock out point-of-care competitors from emergency departments. |
| Software Companion Development | Workflow automation tools redistribute image processing from centralized PACS servers to scanner-embedded GPUs, altering service contract structures. |
| Reimbursement Strategy Alignment | Precision radiotherapy planning codes in Japan's PMDA framework and US Medicare drive spectral CT and quantitative MRI platform upgrades. |
Research Approach
Two parallel data streams informed the analysis: primary field engagement with radiology department chairs, hospital procurement committee members, biomedical engineering directors, and GPO contracts managers; and secondary validation against FDA 510(k) clearance databases, EMA MDR conformity assessment records, hospital procurement databases, and CMS Medicare reimbursement filings. Bottom-up triangulation across modality-specific installation data and top-down reconciliation against health system capital expenditure disclosures anchored volume and value estimates.
Forecast inputs span product type segmentation across CT, MRI, ultrasound, and X-ray modalities; end-user categories from acute care hospitals to point-of-care specialty clinics; technology tiers distinguishing 3D imaging from conventional reconstruction; and application-specific demand patterns in oncology, cardiology, neurology, and orthopedics. CAGRs derive from replacement cycle analysis, reimbursement code expansion trajectories, and AI-enabled platform adoption curves across the projection horizon. Helium supply volatility and EU AI Act implementation timelines feed as scenario variables.
Macroeconomic conditions sit as an overlay; deviation in hospital capital expenditure cycles, medical device tariff regimes, or semiconductor foundry capacity would shift the trajectory. Forecasts reflect documented assumptions about regulatory clearance timelines and reimbursement alignment. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Imaging
Medical Radiation Detection Market
Medical Imaging
Healthcare Cloud Picture Archiving and Communications System Market
Medical Imaging
Teleradiology Services Market
Medical Imaging
Digital X-Ray Imaging Market
Medical Imaging
South Korea Diagnostic Imaging Equipment Market
Medical Imaging
Multiphoton Microscopy Market
Medical Imaging
Ultrasound Imaging Solution Market
Medical Imaging
Global Veterinary Radiography System Market
Medical Imaging
Cryo-Electron Microscopy Market
Medical Imaging
Automated Contouring Radiotherapy Software Market
Medical Imaging
MR-Linac and Image-Guided Radiotherapy QA Measurement Systems Market
Medical Imaging
US Gadolinium-Based Contrast Media Market
Medical Imaging
Magnetic Resonance Imaging Equipment Coils Market
Medical Imaging
Dermatology Imaging Market
Medical Imaging
China Computed Tomography Market
Medical Imaging
Magnetic Resonance Imaging (MRI) Coils Market