
 3D Printed Ophthalmic Implants Market | 2026-2036
3D Printed Ophthalmic Implants Market Size, Share, and Industry Trends Forecast 2026-2036
3D Printed Ophthalmic Implants Market Analytics
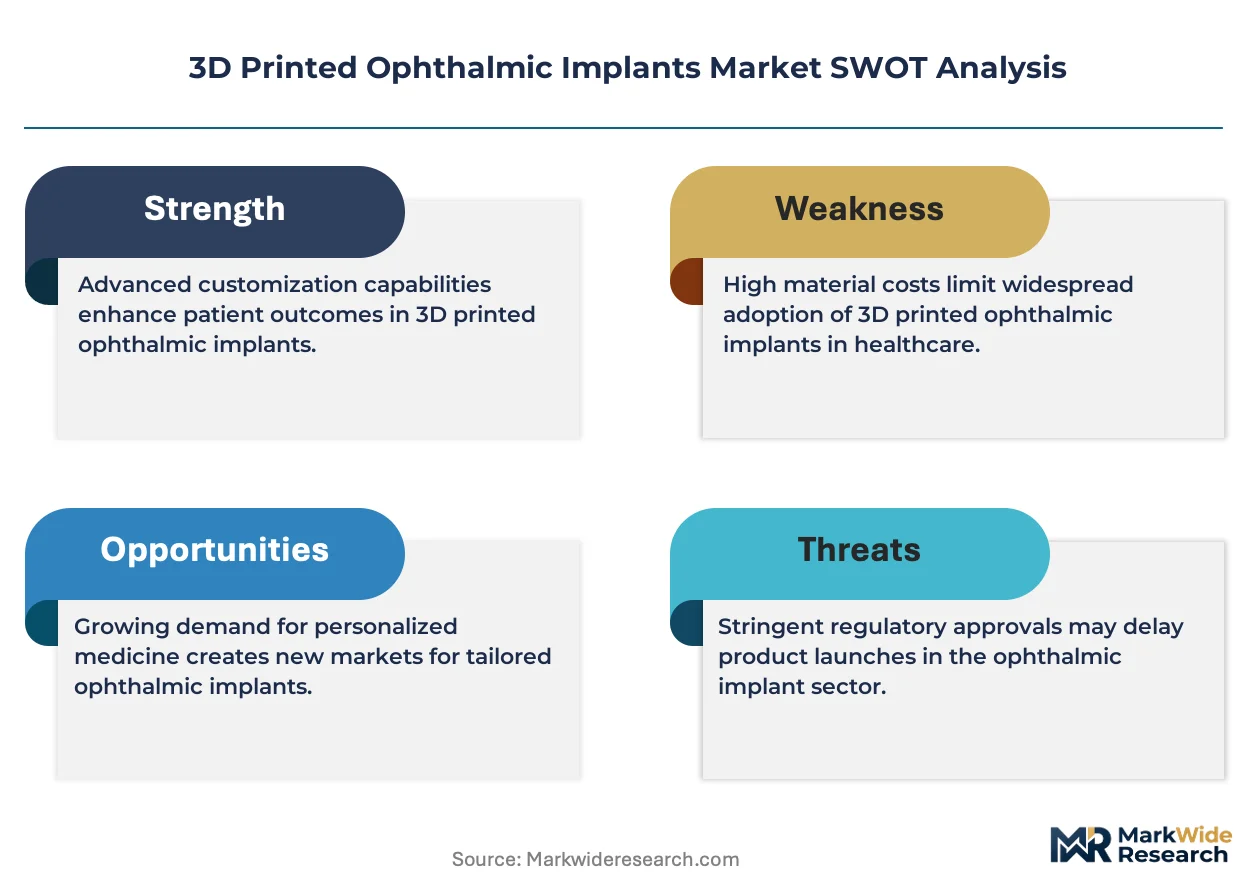
Buyer concentration among hospital networks and large ophthalmic clinic chains is repositioning procurement standards toward customized implant geometries and shorter lead times. Johnson & Johnson leverages its surgical device distribution infrastructure to reach high-volume cataract centers across North America. Luxexcel Group specializes in proprietary Digital Light Processing platforms for prescription-integrated intraocular lenses. EssilorLuxottica anchors European demand through its captive lens manufacturing and retail optometry channels.
3D printed ophthalmic implants comprise biocompatible ocular devices fabricated through additive manufacturing, typically achieving layer resolutions below 50 micrometers to match corneal topography or scleral curvature for functional optical performance. Their primary purpose is restoring vision or reinforcing ocular structure with geometries unattainable through conventional lathe-cutting or molding. Intraocular lenses dominate current revenue given the volume of cataract procedures, while corneal implants represent the fastest-growing category as bioprinting advances enable stromal layer replication. Hydrogel materials command premium positioning due to oxygen permeability requirements, whereas PMMA remains the cost-optimized standard for posterior chamber lenses.
FDA breakthrough device pathways and EU MDR technical documentation requirements are compressing development timelines while raising clinical evidence bars for market authorization. ISO 10993 biocompatibility testing and FDA Quality System Regulation compliance now function as gatekeepers for contract manufacturing partnerships. Japan's PMDA ophthalmic device consultation system adds a third regulatory layer for firms targeting Asian reimbursement lists. Stakeholders must monitor evolving ASTM F42 additive manufacturing standards and predicate device strategies as regulatory convergence between FDA and EU notified bodies accelerates.
Market Dynamics
Patient-specific implant geometries are compressing traditional manufacturing lead times from weeks to days, forcing cataract centers and corneal clinics to restructure surgical scheduling workflows around additive production capacities.
Growth Catalysts
- FDA Breakthrough Device Pathway:Expedited review timelines for 3D printed intraocular lenses with novel optical designs accelerate commercialization for US-based manufacturers. Hospital networks prioritize suppliers with this designation in vendor qualification processes.
- Digital Light Processing Platforms:Layer resolutions below 50 micrometers enable prescription-integrated geometries impossible through conventional lathe-cutting. High-volume cataract centers adopt these platforms for same-week lens fabrication.
- Japan:PMDA ophthalmic device consultation system provides structured pre-submission feedback that reduces regulatory uncertainty for bioprinted corneal implants targeting Asian reimbursement lists.
Market Restraints
- Photoinitiator Cost Volatility:Hydrogel precursor chemicals face supply concentration among German and Japanese specialty chemical producers, squeezing margins for implant fabricators dependent on oxygen-permeable materials.
- EU MDR Technical Documentation:Enhanced clinical evidence requirements for Class III ophthalmic devices extend conformity assessment timelines by 12-18 months compared to previous Medical Device Directive standards.
- Laser-Sculpted PMMA Substitutes:Conventional posterior chamber lenses remain the cost-optimized standard for Medicare-reimbursed procedures, limiting premium pricing power for 3D printed alternatives in price-sensitive segments.
Strategic Opportunities
- Brazil:ANVISA regulatory harmonization efforts with FDA predicate device pathways create expedited market entry for US-validated 3D printed implants in Latin America's largest ophthalmic device market.
- Bioprinting-Stromal Layer Convergence:Integration of cell-laden bioinks with precision extrusion systems enables patient-matched corneal grafts that replicate native collagen lamellar structure.
- Direct-to-Clinic Distribution:Bypassing traditional device distributor markups through captive additive manufacturing installations at hospital networks captures margin previously allocated to wholesale channels.
Industry Challenges
- Biomedical Engineer Scarcity:Cross-functional expertise spanning ISO 10993 biocompatibility testing, additive process parameter optimization, and ophthalmic optical design remains concentrated among a handful of academic training programs.
- ASTM F42 Standardization Gaps:Incomplete consensus guidelines for layer-wise quality assurance of optical-grade implants force manufacturers to develop proprietary validation protocols that delay regulatory submissions.
- Legacy Practice Management Integration:Surgical scheduling software at established cataract centers lacks API connectivity to additive manufacturing job queuing systems, requiring manual coordination between clinical and production workflows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | 3D Printed Ophthalmic Implants Market |
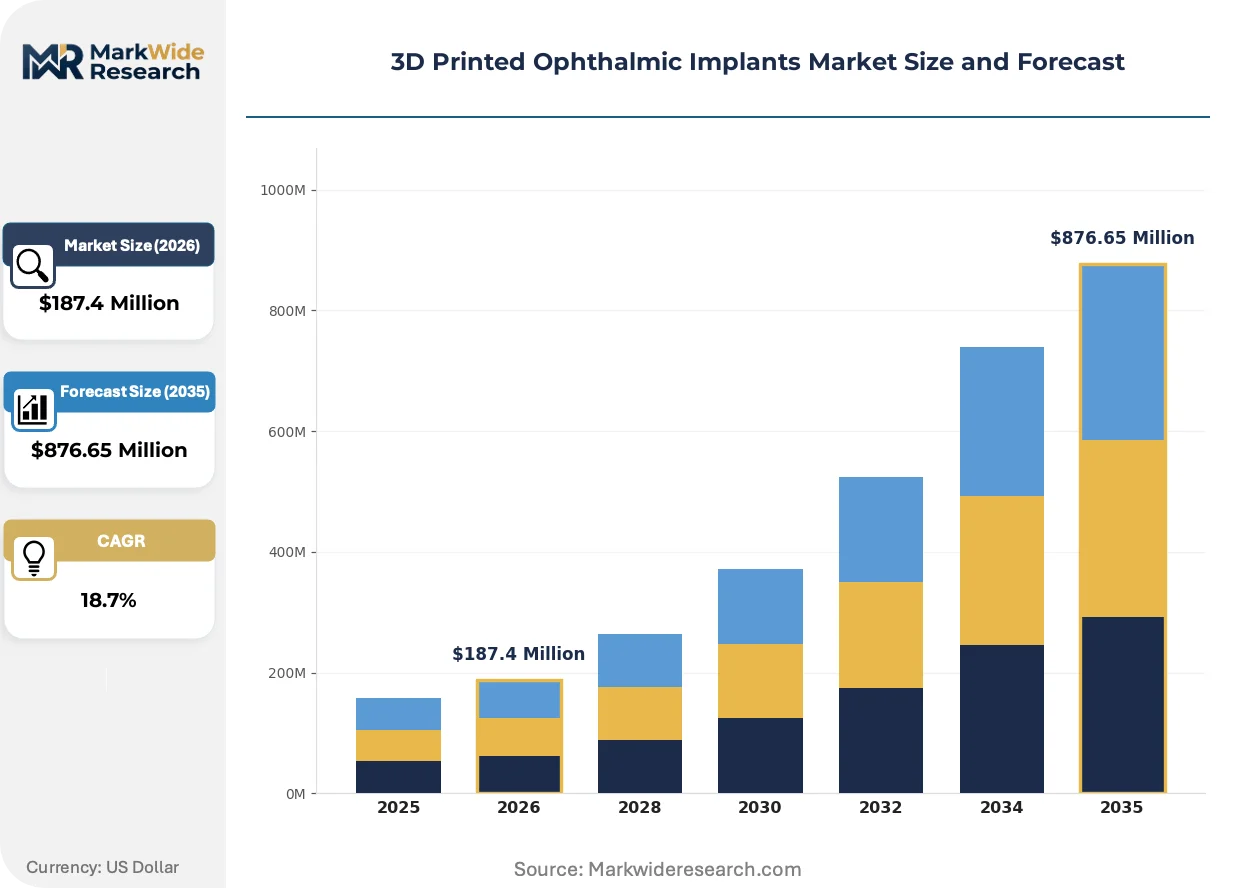
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $876.65 Million |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Corneal Implants, Scleral Fixation Devices, Intraocular Lenses, Retinal Implants Material: PMMA, Silicone, Thermoplastic Polyurethane, Hydrogel End User: Ophthalmic Clinics, Hospitals, Research Institutions, Surgical Centers Technology: Fused Deposition Modelling, Stereolithography, Selective Laser Sintering, Digital Light Processing |
| Companies Covered | Proto Labs, Retina Implant AG, Luxexcel Group, Renishaw, Bausch + Lomb, STAAR Surgical, EssilorLuxottica, Johnson & Johnson, Imaginarium, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
3D Printed Ophthalmic Implants Market Evolving Landscape
Computational topology optimization and real-time print monitoring are converging to produce implant geometries that adapt to individual ocular biomechanics rather than standardized population averages.
Multi-material extrusion systems with inline photopolymerization are automating the fabrication of gradient-refractive-index intraocular lenses that mimic the human crystalline lens. Academic medical centers in Germany and the United States are piloting these platforms for presbyopia-correcting implants. The technology is automating what previously required manual assembly of multiple optical elements, collapsing production costs for complex lens designs.
EU MDR Article 10 post-market surveillance requirements mandate systematic implant tracking through unique device identification. Notified bodies in Germany and the Netherlands are enforcing this through unannounced manufacturing site audits. Hydrogel-based corneal implants face the steepest compliance burden due to material degradation variability that complicates long-term clinical follow-up protocols.
Hospital procurement committees are consolidating vendor lists around suppliers offering both device fabrication and surgical planning software. Large ophthalmic clinic chains in the United States and Japan now require integrated digital workflows from preoperative biometry through postoperative monitoring. This bundling is displacing standalone device manufacturers who lack software development capabilities or partnerships with optical biometry equipment vendors.
3D Printed Ophthalmic Implants Market Segmentation
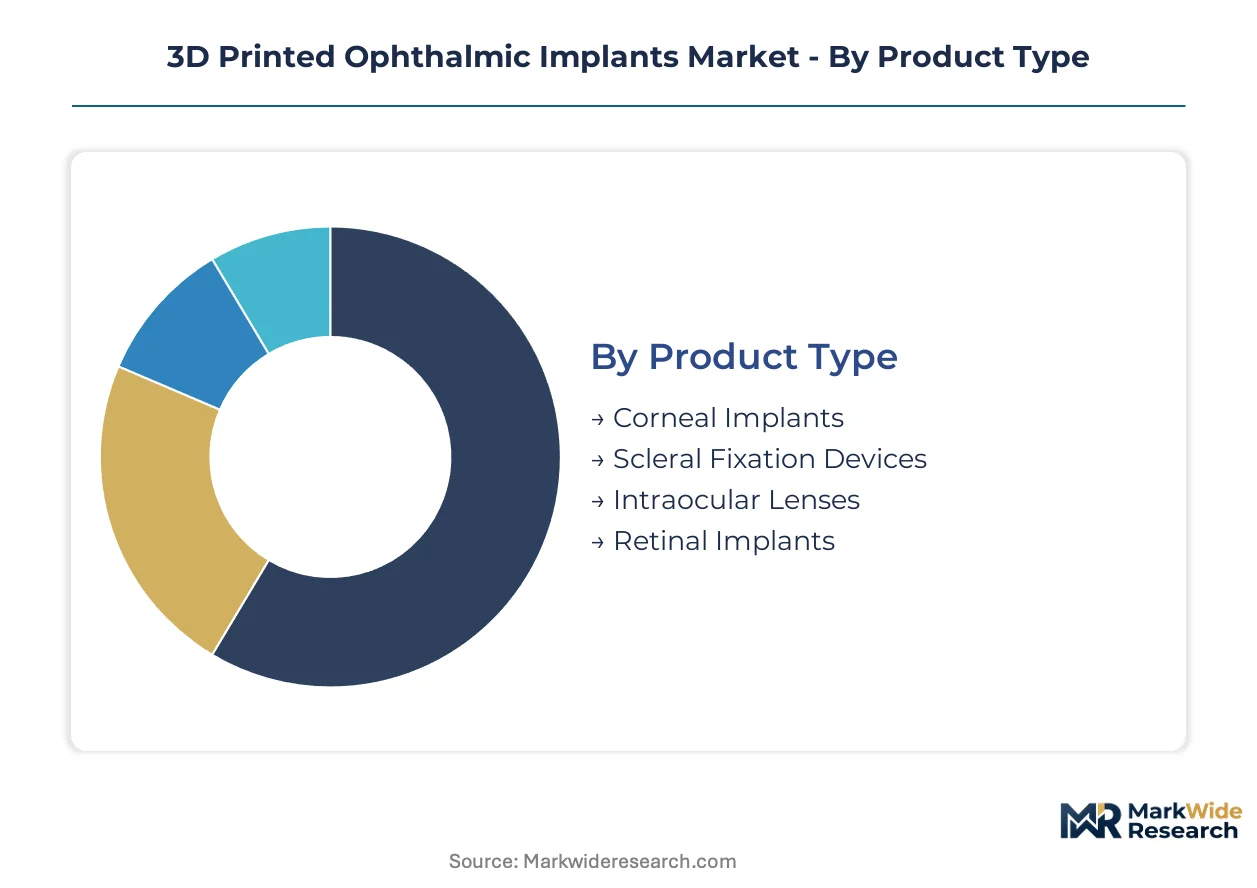
Segmentation in 3D printed ophthalmic implants reveals how additive manufacturing capabilities align with distinct clinical workflows. Product geometries, material properties, and production technologies each create separate procurement and regulatory pathways that reshape vendor positioning.
Product Type:
Standalone implantable devices dominate current surgical volumes, while embedded optical systems represent deeper integration with diagnostic platforms.
- Intraocular Lenses:Polymer optics fabricated through vat photopolymerization achieve dioptric power integration unattainable through conventional lathing. Cataract centers in the United States and Germany concentrate procurement around same-week fabrication capabilities enabled by hospital-installed additive platforms.
- Corneal Implants:Stromal layer replication through bioprinting enables patient-matched curvature restoration for keratoconus and post-refractive ectasia. Academic medical centers in Japan pilot these grafts under PMDA consultation pathways, with oxygen permeability requirements driving hydrogel material selection.
- Scleral Fixation Devices:Custom haptic geometries for complex cases lacking capsular support.
- Retinal Implants:Electrode array microfabrication for prosthetic vision applications in research settings.
Intraocular lenses lead volumes today; corneal implants are gaining share fastest.
Material:
Cost tiers separate commodity polymers from premium hydrogels with specialized optical and biological performance characteristics.
- Hydrogel:Cross-linked polymer networks achieve oxygen permeability exceeding 80 Dk/t for extended corneal epithelial health. Premium positioning in corneal implants reflects German and Japanese specialty chemical supply concentration for photoinitiator precursors.
- PMMA:Methyl methacrylate homopolymers remain the Medicare-reimbursed standard for posterior chamber lenses, constraining pricing power for 3D printed alternatives in US price-sensitive segments despite inferior optical quality.
- Silicone:Elastomeric flexibility for foldable intraocular lens delivery systems.
- Thermoplastic Polyurethane:Segmental mechanical compliance for scleral buckle and fixation applications.
PMMA commands the largest installed base; hydrogel exhibits the steepest expansion trajectory.
End User:
Customer type determines whether additive manufacturing occurs at centralized production facilities or point-of-care installations.
- Hospitals:Integrated health systems in the United States consolidate procurement around vendors offering both device fabrication and surgical planning software. Large networks now require digital workflows from preoperative biometry through postoperative monitoring, displacing standalone manufacturers.
- Surgical Centers:High-volume cataract facilities restructure scheduling around captive additive production capacities, compressing lens delivery from weeks to days.
- Ophthalmic Clinics:Outpatient settings dependent on distributor relationships for custom device ordering.
- Research Institutions:Academic medical centers piloting bioprinted corneal grafts and gradient-refractive-index lenses.
Hospitals absorb the majority of current procurement; surgical centers are expanding installed additive capacity most aggressively.
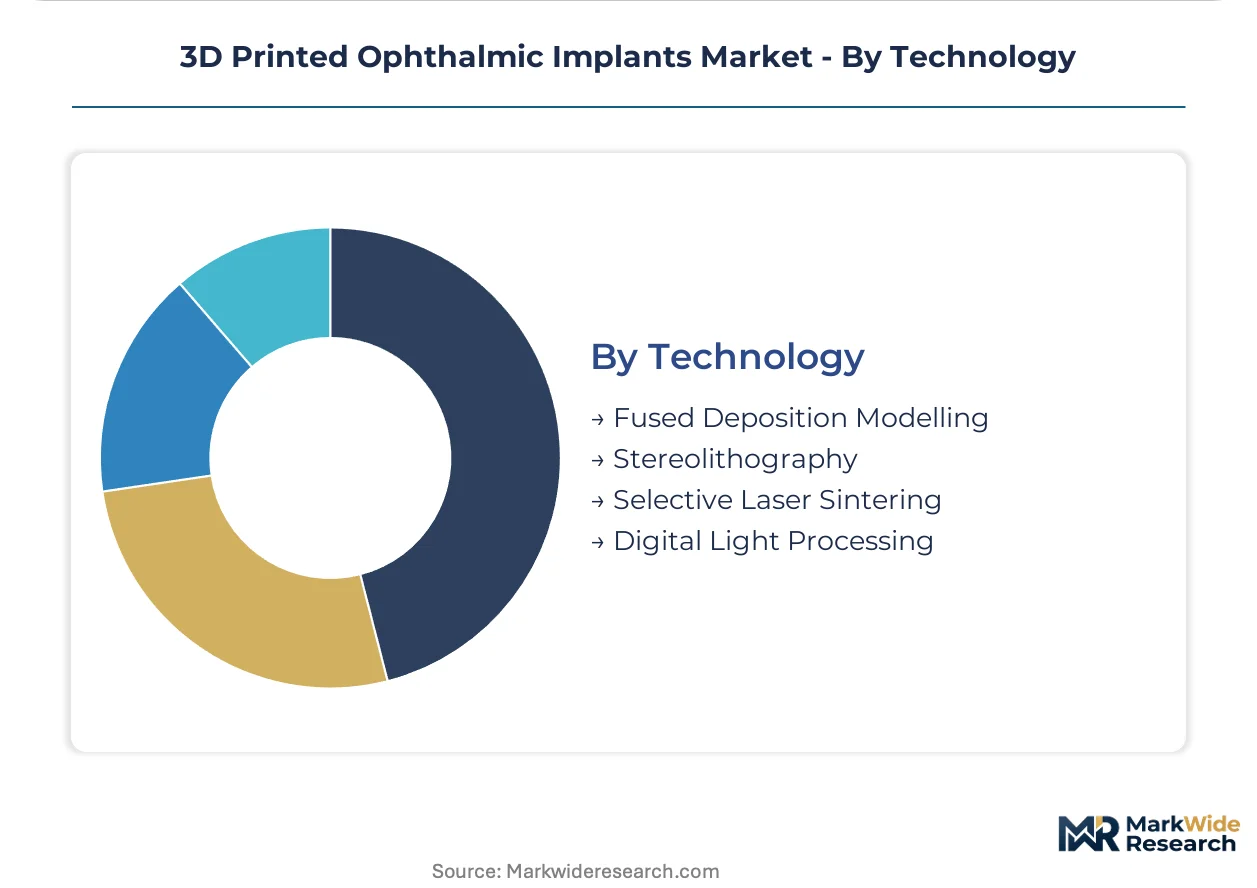
Technology:
Maturity curves separate decades-old stereolithography from emerging digital light processing platforms achieving sub-50-micrometer optical resolutions.
- Digital Light Processing:Maskless projection systems enable prescription-integrated geometries with layer resolutions below 50 micrometers. Luxexcel Group and competing platform vendors target high-volume cataract centers with same-week lens fabrication capabilities.
- Stereolithography:Laser-scanned vat polymerization remains the workhorse for hydrogel corneal implants, with established ISO 10993 biocompatibility validation pathways.
- Selective Laser Sintering:Powder-bed fusion for thermoplastic polyurethane structural components.
- Fused Deposition Modelling:Material extrusion limited to prototyping and surgical planning models due to optical surface quality constraints.
Stereolithography retains the broadest regulatory clearance; digital light processing is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany concentrates regulatory validation infrastructure while the United States dominates hospital procurement volumes for patient-specific ocular devices. Japan's PMDA consultation system accelerates bioprinted corneal implant development timelines. Brazil's ANVISA harmonization efforts create expedited pathways for US-validated predicate devices.
United States
FDA breakthrough device designations compress commercialization timelines for 3D printed intraocular lenses with novel optical geometries. Hospital networks in California and Texas consolidate procurement around vendors offering integrated surgical planning software. The Cleveland Clinic and Massachusetts Eye and Ear pilot gradient-refractive-index lens fabrication through academic-industry partnerships.
Germany
EU MDR notified bodies in Berlin and Munich enforce enhanced clinical evidence requirements for Class III ophthalmic devices. German specialty chemical producers concentrate photoinitiator supply for oxygen-permeable hydrogel formulations. The Stuttgart-Tübingen corridor anchors precision optics manufacturing clusters serving cataract centers across Western Europe.
Japan
PMDA ophthalmic device consultation pathways reduce regulatory uncertainty for bioprinted corneal grafts targeting Asian reimbursement lists. Tokyo and Osaka academic medical centers pilot stromal layer replication under structured pre-submission feedback protocols. Japanese demand concentrates on premium hydrogel materials exceeding 80 Dk/t oxygen permeability thresholds.
Brazil
ANVISA regulatory harmonization with FDA predicate device pathways expedites market entry for US-validated 3D printed implants. São Paulo and Rio de Janeiro ophthalmic clinic chains restructure procurement toward customized implant geometries. Latin America's largest ophthalmic device market absorbs cost-optimized PMMA alternatives alongside premium additive-manufactured options.
United Kingdom
MHRA post-Brexit conformity assessment procedures align with EU MDR technical documentation standards for ophthalmic device authorization. London and Manchester hospital networks prioritize suppliers with captive additive manufacturing installations. UK research institutions collaborate with German platform vendors on digital light processing resolution optimization.
3D Printed Ophthalmic Implants Market Competitive Landscape
United States producers anchor one tier; European specialists hold premium positioning through proprietary fabrication platforms. The vendor base stratifies across diversified medical device conglomerates, pure-play additive manufacturing service providers, and captive ophthalmic technology developers. Three archetypes dominate: hospital-integrated platform vendors, contract manufacturing specialists, and legacy lens manufacturers extending into additive production. Competitive moves concentrate on strategic partnerships with optical biometry equipment vendors and backward integration into photoinitiator precursor supply.
Within the diversified medical device tier, Johnson & Johnson and EssilorLuxottica exemplify scale-driven positioning through captive distribution infrastructure and retail optometry channel control. Among pure-play additive specialists, Luxexcel Group occupies a position representing prescription-integrated intraocular lens platform development. Retina Implant AG sits within the research-intensive archetype focused on prosthetic vision applications. These three entities collectively illustrate how competitive positioning fragments across integrated health system procurement, standalone technology licensing, and academic medical center collaboration models.
| Leading Market Players |
|---|
| Proto Labs |
| Retina Implant AG |
| Luxexcel Group |
| Renishaw |
| Bausch + Lomb |
| STAAR Surgical |
| EssilorLuxottica |
| Johnson & Johnson |
| Imaginarium |
| Others |
Value Network & Pricing Analysis
Hospital procurement committees demanding integrated surgical planning software are forcing standalone implant manufacturers to absorb software development costs or surrender pricing power to bundled-service competitors. This specification shift elevates vendors with captive digital workflows while squeezing margins for pure-play device fabricators dependent on distributor markups.
Pricing Analysis
Capacity additions in Germany and the United States are reshaping price floors for prescription-integrated intraocular lenses. Three-tier pricing structure across premium hydrogel, standard silicone, and economy PMMA levels separates optical performance tiers. Price differentiation rests on FDA breakthrough designation status and ISO 10993 biocompatibility certification grade. Margins are tightening due to photoinitiator cost volatility concentrated among Japanese and German specialty chemical producers. Medicare-reimbursed cataract centers exhibit highest price sensitivity; academic medical centers piloting bioprinted corneal grafts show lowest.
Supply Chain Analysis
Regional distribution centers in Stuttgart-Tübingen and Osaka operate hub-and-spoke patterns for photoinitiator precursors and precision optics components. Manufacturing concentrates in Germany, the United States, and Japan for platform hardware; hydrogel precursor chemicals draw from German and Japanese specialty producers. Raw material dependencies include photoinitiator chemicals, optical-grade PMMA resin, and silicone elastomers. Single-source vulnerability for photoinitiator supply creates structural risk exposure. Distribution runs through hospital-integrated captive installations and traditional device distributors serving outpatient ophthalmic clinics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market offers margin expansion through same-week fabrication capabilities that collapse inventory carrying costs and command premium positioning against conventional lathe-cut lenses.
For Market Incumbents: Deepen backward integration into photoinitiator precursor supply to defend against German and Japanese chemical producer pricing power. Consolidate procurement relationships with high-volume cataract centers by embedding additive manufacturing platforms directly within hospital networks. Lock in ISO 10993 certification investment as a barrier against emerging bioprinting specialists lacking established validation pathways. For New Entrants and Emerging Players: Direct-to-clinic software partnerships offer white-space entry around legacy practice management integration gaps. Target Brazil's ANVISA-harmonized regulatory pathway for expedited predicate device commercialization. Pursue bioprinted corneal implant development under Japan's PMDA consultation system to capture fastest-growing segment share. For Investors and Strategic Acquirers: Asymmetric upside sits with hospital-integrated platform vendors possessing captive surgical planning software and installed additive production capacity. Five-to-ten year viability favors firms bridging bioprinting research with EU MDR conformity assessment completion. Watch FDA breakthrough device designation velocity as inflection signal for premium pricing tier access.| Strategic Initiative | Industry Significance |
|---|---|
| Hospital System Partnership | Cleveland Clinic and Massachusetts Eye and Ear validate gradient-refractive-index lens platforms through academic-industry collaboration. |
| FDA Submission | Breakthrough device designation compresses review timelines for novel optical geometries in cataract centers. |
| CE Marking Pathway | EU MDR technical documentation requirements elevate clinical evidence bars for German notified body clearance. |
| Software Companion Development | API connectivity between surgical scheduling and additive manufacturing job queuing displaces manual coordination workflows. |
| Reimbursement Strategy | Medicare coverage determinations for patient-specific implants determine addressable market scale in United States cataract procedures. |
Research Methodology
Multiple input streams — primary interviews with biomedical engineers and hospital purchasing committees, secondary validation against FDA 510(k) filings and EU MDR technical documentation — were reconciled through bottom-up and top-down triangulation. Stakeholder roles engaged included GPO contracts managers, ophthalmic surgeons, additive manufacturing platform engineers, and regulatory affairs specialists. Secondary sources encompassed hospital procurement databases, CMS Medicare reimbursement data, PMDA consultation pathway records, and ASTM F42 additive manufacturing standards documentation.
Historical shipment data was cross-referenced against expert panel inputs across product type, material grade, end-user facility type, and fabrication technology dimensions. CAGRs were derived from segment-level growth trajectory modeling. Forecast inputs included FDA breakthrough designation approval velocity, EU MDR notified body capacity constraints, and hospital network consolidation patterns affecting procurement centralization.
The model assumes a particular technology adoption path; alternative pathways for bioprinted stromal layer replication would alter the outlook if clinical validation timelines compress or extend. Forecasts reflect documented assumptions around regulatory convergence and reimbursement policy stability. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ophthalmology
Global Therapeutic Lenses Market
Ophthalmology
Ophthalmic Clinical Trials Market
Ophthalmology
Global Aphakia Market
Ophthalmology
Global Tonometer Market
Ophthalmology
Global Ophthalmology PACS Market
Ophthalmology
Retinal Detachment Market
Ophthalmology
Neovascular Age-Related Macular Degeneration Treatment Market
Ophthalmology
Lazy Eye Market
Ophthalmology
UAE Ophthalmic Devices Market
Ophthalmology
Global Vitreous Tamponades Market
Ophthalmology
Ophthalmic Devices Market
Ophthalmology
South Africa Ophthalmic Devices Market
Ophthalmology
Coloured Contact Lenses Market
Ophthalmology
Light Therapy Glasses Market
Ophthalmology
Pseudotumor Cerebri Market
Ophthalmology
Herpes Zoster Ophthalmicus Market