
 MR-Linac and Image-Guided Radiotherapy QA Measurement Systems Market | 2026-2036
MR-Linac and Image-Guided Radiotherapy QA Measurement Systems Market Size, Share, and Industry Trends Forecast 2026-2036
MR-Linac and Image-Guided Radiotherapy QA Measurement Systems Market Insights
Software-defined service layers is repositioning how vendors monetize QA measurement systems, shifting capital sales toward recurring calibration subscriptions and remote monitoring contracts. PTW Freiburg leverages its European installed base to sustain long-term service agreements. IBA Dosimetry anchors its competitive stance through detector array specialization. Standard Imaging competes aggressively on phantom device customization for institutional research protocols.
MR-Linac and image-guided radiotherapy QA measurement systems comprise phantom devices, detector arrays, dosimetry systems, and imaging QA tools engineered to verify geometric accuracy, dose delivery precision, and image fidelity in hybrid magnetic resonance-linear accelerator environments. These systems employ water-equivalent phantoms, diode or ionization chamber arrays, and film-based or electronic portal imaging devices to measure beam profiles, output constancy, and registration accuracy between imaging and treatment isocenters. Phantom devices command the deepest margin pools due to material customization requirements and replacement cycles tied to accelerator upgrade schedules. Cloud-based analytics deployment is gaining fastest as clinics seek centralized multi-site QA management and predictive maintenance capabilities.
The FDA's 21 CFR Part 820 quality system regulation and the European Medical Device Regulation (MDR) impose stringent design controls and post-market surveillance obligations on QA system manufacturers, elevating barriers for new entrants while rewarding established players with robust technical documentation. The EU AI Act introduces additional conformity assessment layers for machine-learning-enabled image analysis modules within integrated QA platforms. Stakeholders must monitor how regulatory divergence between FDA's software pre-certification pilot and MDR's notified body recertification timelines reshapes product development roadmaps and geographic launch sequencing.
Market Dynamics
The MR-Linac QA measurement systems market is pivoting toward software-centric revenue architectures, with cloud-based analytics platforms displacing standalone hardware sales as the primary value capture mechanism for vendors serving cancer treatment networks.
Growth Catalysts
- FDA 510(k) software-as-medical-device pathway:The FDA's streamlined clearance framework for cloud-based QA analytics is compressing time-to-market for integrated monitoring platforms, accelerating vendor investment in remote calibration services.
- Multi-site health system consolidation:Large integrated delivery networks in the United States are mandating centralized QA data lakes across their radiation oncology footprints, creating pull-through demand for compatible phantom devices and detector arrays.
- Hybrid imaging-dose verification protocols:MR-Linac installations in Germany and Japan are requiring simultaneous geometric and dosimetric validation workflows that legacy LINAC QA systems cannot execute, forcing equipment refresh cycles.
Market Restraints
- Scandium-doped phantom material cost volatility:Specialized water-equivalent polymer formulations essential for MR-compatible phantoms face supply concentration among three European chemical processors, exposing margins to raw material price swings.
- EU MDR notified body capacity constraints:Extended recertification timelines for Class IIa medical device software are delaying product launches by 14-22 months, freezing R&D amortization schedules for mid-tier vendors.
- Film dosimetry substitution pressure:Radiochromic film manufacturers face displacement from diode array systems offering real-time feedback, collapsing a traditional QA consumables revenue stream.
Strategic Opportunities
- Underpenetrated Japanese proton center segment:Japan's expanding proton therapy infrastructure lacks MR-Linac QA protocols adapted to magnetic field effects on beam delivery, creating first-mover whitespace for specialized phantom developers.
- EU AI Act conformity assessment services:Machine-learning-enabled image registration modules within QA platforms require new certification pathways, opening recurring revenue streams for compliance consulting and automated documentation tools.
- Subscription-based remote monitoring:Predictive maintenance algorithms applied to accelerator performance data are enabling vendor transitions from capital sales to annual calibration contracts with 85-90% renewal visibility.
Industry Challenges
- Cross-disciplinary physics-engineering talent scarcity:MR-Linac QA system development demands simultaneous expertise in magnetic resonance physics, radiation dosimetry, and software architecture, with fewer than 200 qualified specialists graduating annually from combined medical physics and biomedical engineering programs.
- Legacy LINAC integration complexity:Cancer clinics operating mixed fleets of conventional linear accelerators and MR-Linac systems must maintain dual QA workflows, fragmenting training budgets and inflating total cost of ownership.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | MR-Linac and Image-Guided Radiotherapy QA Measurement Systems Market |
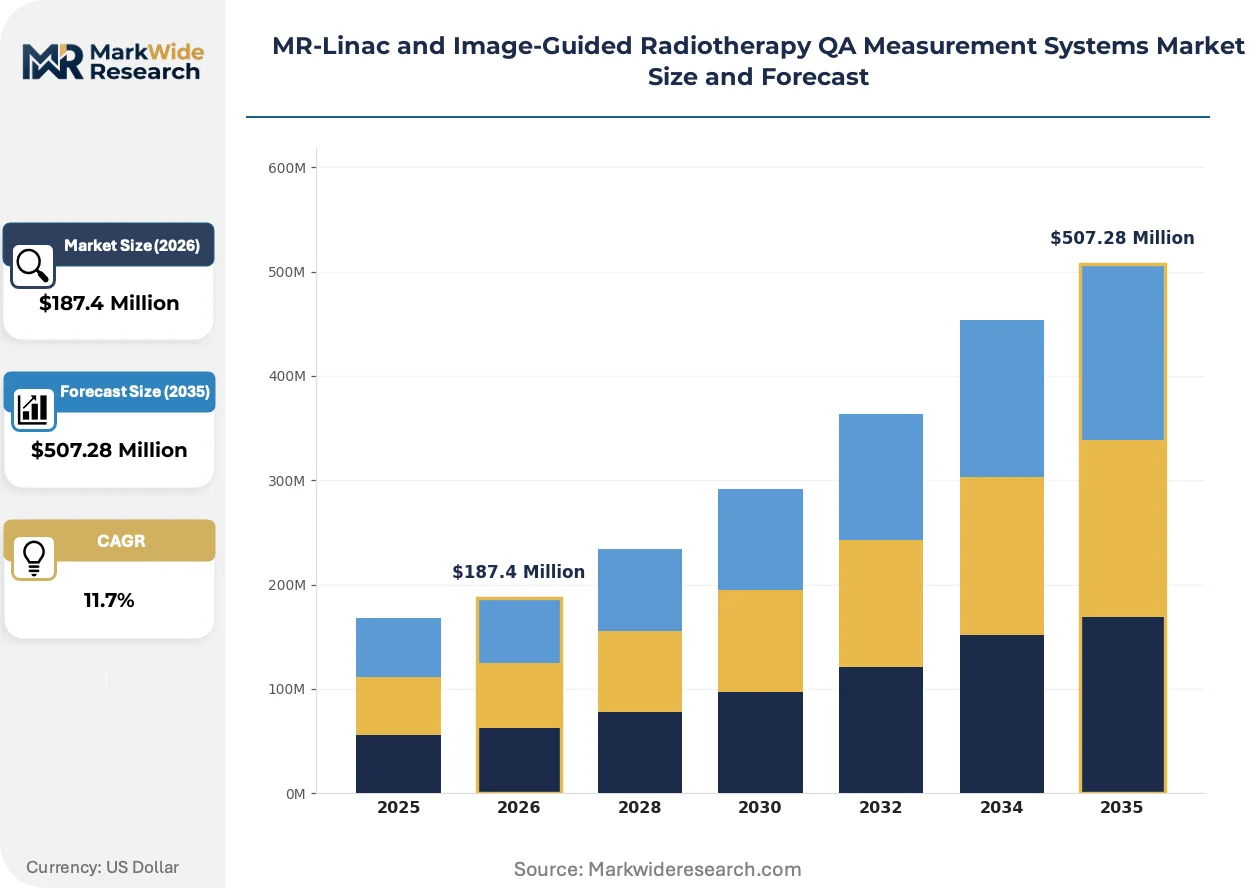
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $507.28 Million |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Phantom Devices, Detector Arrays, Dosimetry Systems, Imaging QA Tools Application: Quality Assurance, Treatment Planning Verification, Beam Performance Testing, Image Quality Assessment End User: Radiotherapy Centers, Research Institutions, Cancer Treatment Clinics, Diagnostic Imaging Facilities Deployment: On-Premise, Cloud-Based Analytics, Integrated Systems, Standalone Devices |
| Companies Covered | PTW Freiburg, IBA Dosimetry, Standard Imaging, Mirion Medical, ScandiDos, The Phantom Laboratory, CIRS, RaySafe, Vision RT, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
MR-Linac and Image-Guided Radiotherapy QA Measurement Systems Market Trends and Innovations
Artificial intelligence and cloud infrastructure are converging to restructure how radiation oncology departments validate treatment delivery, compressing QA cycle times while expanding the data granularity available for clinical decision support.
Electronic portal imaging devices with embedded machine learning inference engines are integrating real-time isocenter verification into treatment beams, eliminating separate QA sessions. Major academic medical centers in the United States and Germany are deploying these systems during patient treatment slots, recovering 15-20 minutes of daily beam time previously allocated to standalone phantom measurements. This integration is compressing the addressable market for conventional film-based verification systems while expanding service contract values for vendors managing algorithm updates.
The EU AI Act's risk classification framework for medical device software is forcing QA platform developers to segregate machine learning modules from core dosimetry functions, creating dual regulatory pathways. Manufacturers must now maintain separate technical documentation for image analysis algorithms versus hardware calibration protocols, inflating quality management system costs by an estimated 25-35%. German notified bodies are experiencing 8-month backlogs for these assessments, pushing vendors to sequence European launches after FDA clearances.
Hospital procurement departments are unbundling QA equipment purchases from vendor service agreements, treating calibration subscriptions as separate competitive bids. This pattern is most pronounced in United States integrated delivery networks with centralized radiation oncology oversight, where supply chain teams leverage multi-site volume to compress annual service pricing by 12-18%. Vendors responding with outcome-based performance guarantees tied to accelerator uptime metrics are capturing preferred provider status in these RFP processes.
MR-Linac and Image-Guided Radiotherapy QA Measurement Systems Market Segmentation
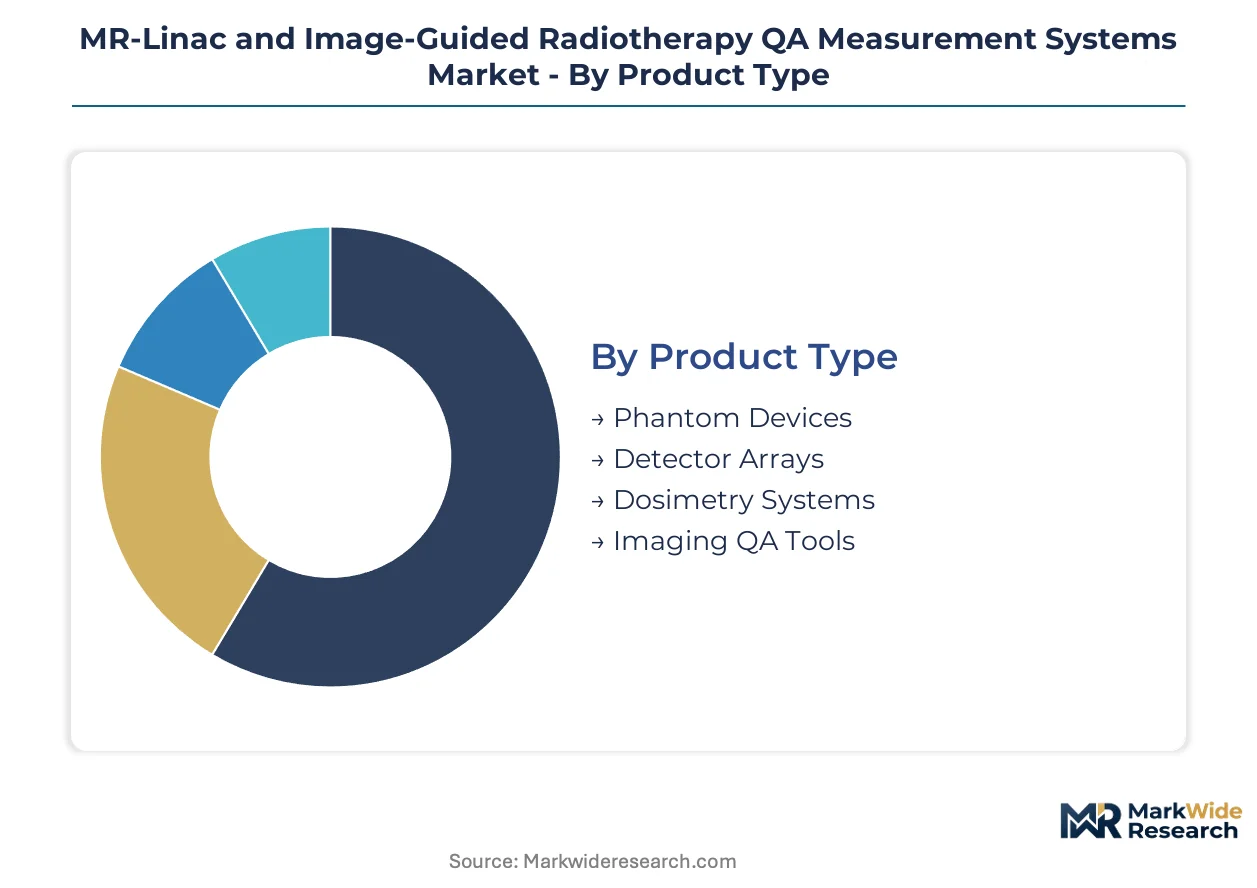
Segmentation in the MR-Linac QA measurement systems market reveals distinct procurement patterns across hardware categories and service delivery models. Each segment carries unique margin profiles and replacement cycles that shape vendor portfolio strategies.
Product Type:
Supply concentration in specialized polymer formulations and detector manufacturing creates divergent competitive dynamics across hardware categories.
- Phantom Devices:Water-equivalent polymer phantoms with scandium-doped formulations enable MR-compatible beam profiling. Cancer treatment clinics in the United States and Germany drive replacement demand tied to accelerator upgrade schedules. Phantom devices command the deepest margin pools due to material customization requirements and institutional research protocol specifications.
- Detector Arrays:Diode and ionization chamber arrays deliver real-time dosimetric feedback during QA workflows. Japan's proton therapy centers are adopting specialized arrays adapted to magnetic field effects on beam delivery, creating first-mover whitespace for manufacturers with magnetic resonance physics expertise.
- Dosimetry Systems:Integrated electrometers and reference chambers calibrate absolute dose output for hybrid MR-Linac environments.
- Imaging QA Tools:Electronic portal imaging devices and film-based verification systems assess geometric accuracy between imaging and treatment isocenters.
Phantom devices absorb the bulk of installed capacity; cloud-enabled detector arrays are expanding most quickly.
Application:
Workflow integration requirements determine technology selection, with simultaneous geometric and dosimetric validation protocols forcing equipment refresh cycles in advanced installations.
- Quality Assurance:Daily, monthly, and annual QA protocols verify output constancy, beam symmetry, and mechanical isocenter stability. Large integrated delivery networks in the United States mandate centralized QA data lakes across radiation oncology footprints, creating pull-through demand for compatible measurement systems.
- Treatment Planning Verification:End-to-end testing validates dose calculation algorithms against measured data in anthropomorphic phantoms. German academic medical centers are deploying machine-learning-enabled image registration modules that require new EU AI Act conformity assessment pathways.
- Beam Performance Testing:Depth-dose and profile measurements characterize beam quality across clinical energy ranges.
- Image Quality Assessment:Spatial resolution, contrast, and geometric distortion tests validate MR imaging fidelity for treatment guidance.
Quality Assurance commands the largest share of recurring revenue; Treatment Planning Verification is climbing the fastest as adaptive therapy protocols proliferate.
End User:
Procurement authority and budget structures vary sharply across institutional types, with research institutions commanding premium pricing for customized phantom configurations.
- Radiotherapy Centers:High-volume treatment facilities require robust QA programs supporting multiple accelerator platforms. These centers face dual workflow complexity when operating mixed fleets of conventional linear accelerators and MR-Linac systems, fragmenting training budgets and inflating total cost of ownership.
- Cancer Treatment Clinics:Community-based oncology practices prioritize streamlined QA workflows with minimal physics staffing. The FDA's 510(k) software-as-medical-device pathway is accelerating adoption of cloud-based analytics platforms among these clinics seeking to compress time-to-market for remote monitoring capabilities.
- Research Institutions:Academic medical centers drive innovation in novel QA methodologies and phantom device customization.
- Diagnostic Imaging Facilities:Standalone imaging centers require QA tools focused on MR geometric accuracy rather than dosimetric validation.
Radiotherapy Centers account for the majority of hardware placements; Cancer Treatment Clinics are gaining share fastest as community MR-Linac installations expand.
Deployment:
Revenue model architecture is pivoting from capital sales toward recurring calibration subscriptions as cloud infrastructure matures.
- Cloud-Based Analytics:Centralized multi-site QA management platforms enable predictive maintenance algorithms applied to accelerator performance data. Vendors are transitioning from capital sales to annual calibration contracts with high renewal visibility, capturing preferred provider status in United States integrated delivery network RFP processes.
- Integrated Systems:Hardware-software bundles with embedded machine learning inference engines compress QA cycle times by integrating real-time isocenter verification into treatment beams. Major academic medical centers in Germany and the United States are recovering 15-20 minutes of daily beam time previously allocated to standalone phantom measurements.
- On-Premise:Traditional locally-hosted software deployments persist in facilities with stringent data sovereignty requirements.
- Standalone Devices:Non-networked hardware systems serve low-volume sites with limited IT infrastructure.
Integrated Systems dominate current installed base; Cloud-Based Analytics is expanding most quickly as health system consolidation accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production of MR-Linac QA measurement systems concentrates among specialized polymer processors in Germany and detector manufacturers in Japan, while consumption clusters in the United States, Germany, and Japan where MR-Linac installations are most densely clustered.
United States
Integrated delivery networks mandate centralized QA data lakes across radiation oncology footprints, creating pull-through demand for compatible phantom devices and detector arrays. The FDA's 510(k) software-as-medical-device pathway compresses time-to-market for cloud-based analytics platforms. Major academic medical centers in Boston and Houston deploy machine-learning-enabled image registration modules during patient treatment slots.
Germany
Hybrid imaging-dose verification protocols require simultaneous geometric and dosimetric validation workflows that force equipment refresh cycles. The EU MDR imposes stringent design controls and post-market surveillance obligations on QA system manufacturers. Notified bodies in Munich and Berlin experience eight-month backlogs for machine-learning module assessments, delaying product launches.
Japan
Expanding proton therapy infrastructure lacks MR-Linac QA protocols adapted to magnetic field effects on beam delivery. METI coordinates national research programs advancing adaptive radiation therapy technologies. Osaka and Nagoya academic medical centers pioneer specialized detector arrays for magnetic field environments.
United Kingdom
NHS England's specialized commissioning frameworks concentrate MR-Linac procurement in designated cancer centers, streamlining QA equipment standardization. The Medicines and Healthcare products Regulatory Agency enforces UKCA marking requirements post-Brexit. London and Manchester radiotherapy networks pilot centralized multi-site QA management platforms.
France
ANSM regulates medical device software through notified body pathways parallel to EU MDR implementation. National cancer plans prioritize MR-guided radiotherapy expansion in university hospital centers. The Paris-Saclay cluster anchors research collaborations between physics laboratories and clinical radiation oncology departments.
MR-Linac and Image-Guided Radiotherapy QA Measurement Systems Market Competitive Landscape
Top-tier vendors anchor the premium instrumentation tier, while mid-scale specialists occupy phantom customization and regional service niches. The vendor base spans three strategic archetypes: detector array specialists leveraging magnetic resonance physics expertise, phantom device fabricators commanding material customization premiums, and software analytics platforms capturing recurring calibration subscriptions. Consolidation pressure intensifies as cloud-based service contracts displace standalone hardware sales, while cross-disciplinary talent scarcity elevates acquisition premiums for physics-engineering teams.
Within the detector array specialization tier, PTW Freiburg and IBA Dosimetry exemplify contrasting geographic anchoring strategies—Freiburg leveraging European installed base density for long-term service agreements, Dosimetry concentrating on magnetic field-adapted measurement protocols. Standard Imaging occupies a position emphasizing phantom device customization for institutional research specifications. These three entities represent the dominant competitive archetypes: service-anchored incumbents, technology-adapted specialists, and research-customization providers.
| Leading Market Players |
|---|
| PTW Freiburg |
| IBA Dosimetry |
| Standard Imaging |
| Mirion Medical |
| ScandiDos |
| The Phantom Laboratory |
| CIRS |
| RaySafe |
| Vision RT |
| Others |
Pricing and Supply Chain Analysis
United States integrated delivery networks with centralized radiation oncology procurement command substantial leverage over vendor pricing, compressing annual service contracts through multi-site volume aggregation while elevating outcome-based performance guarantees as the dominant pricing model. Their procurement authority reshapes how phantom device manufacturers and detector array specialists structure recurring revenue architectures.
Pricing Analysis
Cost-down pressure on calibration subscriptions accelerates as hospital supply chain teams unbundle hardware purchases from service agreements and treat annual contracts as separate competitive bids. Three-tier pricing structure across premium, standard, and economy levels separates research-grade phantom customization from routine QA protocols and entry-level detector arrays. Price differentiation rests on ISO 13485 certification tier and after-sales service bundling, with community cancer clinics exhibiting highest price sensitivity and academic medical centers least sensitive due to research protocol requirements.
Supply Chain Analysis
Refurbishment flows for scandium-doped polymer phantoms and ionization chamber arrays remain underdeveloped, creating aftermarket service gaps that specialized vendors exploit for recurring calibration revenue. Manufacturing concentrates in Germany for water-equivalent polymer formulations, Japan for detector array fabrication, and the United States for cloud analytics platform development. Raw material dependencies span European chemical processors for scandium-doped compounds, Japanese semiconductor foundries for diode sensors, and domestic cloud infrastructure providers. Single-source vulnerability in European polymer supply exposes margins to raw material price swings. Distribution runs through direct vendor relationships with hospital procurement committees and group purchasing organizations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The MR-Linac QA measurement systems market operates as a vertical-integration race where control over scandium-doped polymer supply and captive cloud analytics development determines margin sustainability. Players are pursuing backward integration into specialized chemical processing to secure phantom material supply.
For Market Incumbents: Anticipate displacement pressure from machine-learning-enabled image registration modules by securing EU AI Act conformity assessment capabilities ahead of notified body backlogs. Anchor defensive positioning through long-term service agreements with United States integrated delivery networks and in-house production of scandium-doped polymer formulations to neutralize raw material cost volatility. Priority investments should target magnetic field-adapted detector arrays for Japan's proton therapy expansion. For New Entrants and Emerging Players: Cloud-native analytics platforms with predictive maintenance algorithms offer the most penetrable wedge against established hardware vendors, particularly among community cancer treatment clinics seeking compressed QA workflows without dedicated physics staffing. Target Japan's proton center segment where MR-Linac QA protocols remain underdeveloped for magnetic field environments. Go-to-market positioning should emphasize FDA 510(k) software-as-medical-device pathway acceleration and subscription-based remote monitoring contracts with high renewal visibility. For Investors and Strategic Acquirers: The window for entry favors mid-scale phantom device fabricators with material customization expertise and established European notified body relationships. Long-term viability hinges on capturing recurring calibration subscription revenue rather than capital hardware sales. Acquisition targets should demonstrate cross-disciplinary physics-engineering talent density. Monitor FDA software pre-certification pilot program expansion and EU MDR notified body capacity additions as inflection indicators for product launch velocity.| Strategic Initiative | Industry Significance |
|---|---|
| EU AI Act Conformity Assessment | Machine-learning module segregation inflates quality management costs for German notified body submissions. |
| Backward Integration into Polymer Processing | In-house scandium-doped formulation production neutralizes European chemical processor supply concentration. |
| Cloud Analytics Platform Development | FDA 510(k) software pathway compresses time-to-market for remote calibration subscription models. |
| Magnetic Field-Adapted Detector Arrays | Japan's proton therapy infrastructure lacks QA protocols addressing magnetic field effects on beam delivery. |
| Multi-Site Health System Partnership | United States integrated delivery networks mandate centralized QA data lakes across radiation oncology footprints. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, supplemented by primary interviews with radiation oncology physicists, hospital procurement managers, biomedical engineers, and GPO contracts specialists. FDA 510(k) clearances, EU MDR technical documentation, and METI research program disclosures provided regulatory trajectory validation. Bottom-up installed base estimates for MR-Linac systems across the United States, Germany, and Japan were cross-referenced against top-down vendor revenue segmentation to triangulate market sizing.
Granularity-level modeling addressed product type segmentation across phantom devices, detector arrays, dosimetry systems, and imaging QA tools; deployment models spanning cloud-based analytics, integrated systems, on-premise, and standalone devices; and end-user categories including radiotherapy centers, cancer treatment clinics, research institutions, and diagnostic imaging facilities. CAGRs were derived from accelerator upgrade cycle analysis, health system consolidation patterns, and regulatory pathway velocity assumptions. Forecast inputs incorporated scandium-doped polymer replacement schedules and cloud analytics adoption curves among community oncology practices.
Several conditions sit outside the modeled scope, including potential EU MDR notified body capacity expansion, raw material substitution breakthroughs for water-equivalent phantoms, and disruptive LINAC technology architectures that could obsolete current QA protocols. Forecasts reflect assumptions regarding sustained health system consolidation momentum and stable regulatory divergence between FDA and EU pathways. Practitioners should monitor FDA software pre-certification program maturation, EU AI Act implementation timelines, and Japanese proton center MR-Linac installation rates for early signals of forecast revision triggers.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Imaging
Echocardiography Market
Medical Imaging
Japan Magnetic Resonance Imaging Market
Medical Imaging
Teleradiology Services Market
Medical Imaging
Germany Nuclear Imaging Market
Medical Imaging
Argentina Diagnostic Imaging Equipment Market
Medical Imaging
Breast MRI Screening Market
Medical Imaging
Nuclear Medicine Software Market
Medical Imaging
Forensic Imaging Market
Medical Imaging
Ultrasound-Based Imaging Market
Medical Imaging
South Korea Magnetic Resonance Imaging Market
Medical Imaging
Global Cardiac Imaging Software Market
Medical Imaging
Global Vendor-Neutral Archive (VNA) and PACS Market
Medical Imaging
Global 3D Ultrasound Market
Medical Imaging
France Diagnostic Imaging Equipment Market
Medical Imaging
North America Computed Tomography (CT) Market
Medical Imaging
South Korea Diagnostic Imaging Equipment Market