
 Skin Moisture Detectors Market | 2026-2036
Skin Moisture Detectors Market Size, Share, and Industry Trends Forecast 2026-2036
Skin Moisture Detectors Market Analytics
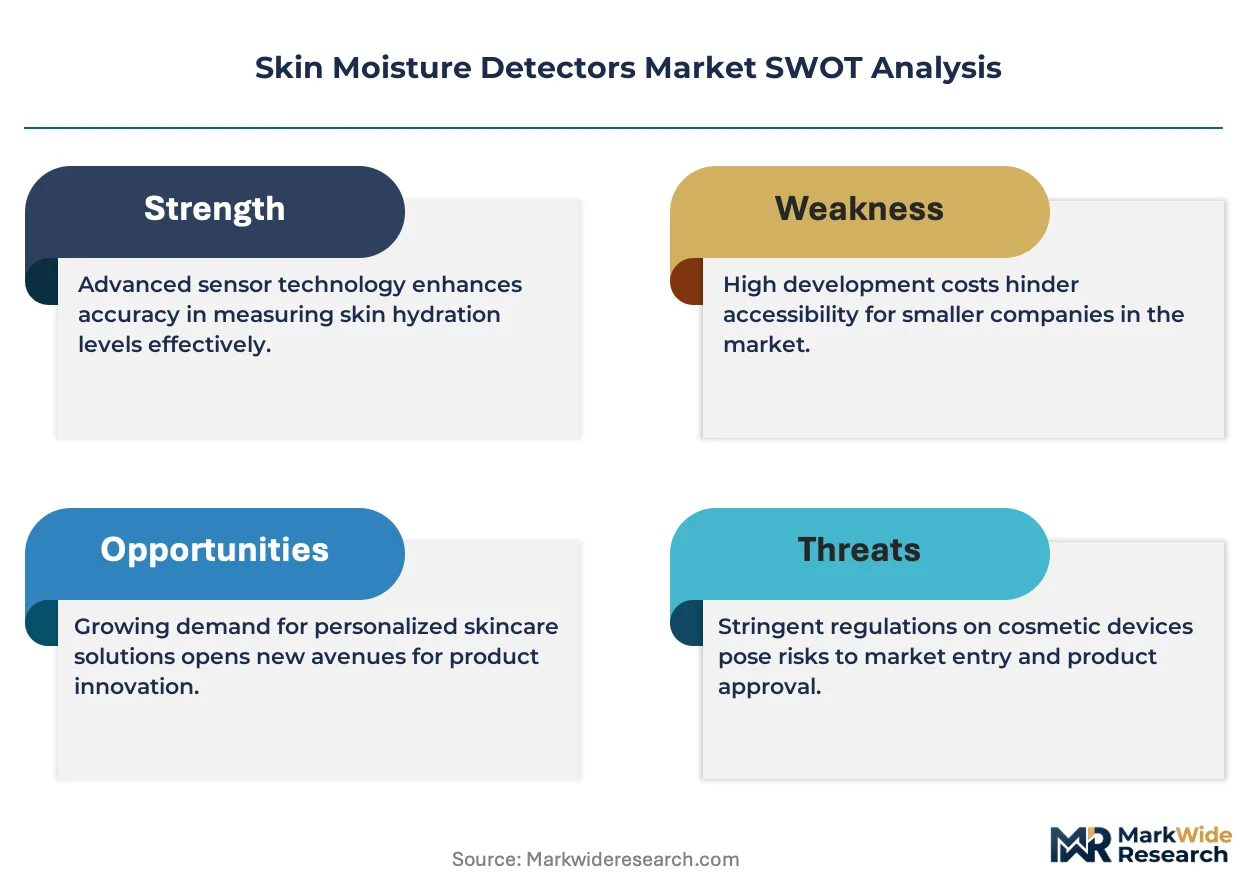
EU MDR is rebalancing procurement criteria toward clinically validated skin moisture detectors over unregulated consumer gadgets. Delfin Technologies leverages its Scandinavian R&D base to sustain medical-grade certification pipelines. Panasonic anchors East Asian manufacturing scale for capacitive sensor modules. Bio-Therapeutic differentiates through channel control in professional aesthetic equipment distribution.
Skin moisture detectors are electrochemical or electromagnetic instruments that quantify stratum corneum hydration via impedance, capacitance, or near-infrared reflectance, typically resolving moisture content within 0.1% precision for clinical reproducibility. Their primary commercial purpose spans cosmetic efficacy validation, eczema monitoring, and personalized skincare regimen calibration. Optical sensors command premium positioning in dermatology clinics where non-contact measurement reduces cross-contamination risk. Portable technology variants are expanding fastest among cosmetic manufacturers seeking in-store consumer diagnostics. Wearable formats remain nascent but concentrate margin pools in premium consumer research panels.
FDA 510(k) clearance pathways shape US market access for devices claiming diagnostic utility, while EU MDR and CE marking enforce biocompatibility and electromagnetic compatibility standards across European commercialization. Japan's PMDA maintains distinct hydration measurement accuracy thresholds that fragment technical specifications for Asia-Pacific registration. China's NMPA recently tightened clinical evidence requirements for dermal analysis devices under revised Class II medical device rules. Stakeholders must monitor regulatory divergence between cosmetic-grade and medical-grade classification thresholds to avoid portfolio stranding.
Market Dynamics
EU MDR clinical validation requirements are compressing the addressable market for unregulated consumer-grade skin moisture detectors while elevating certified medical-grade equipment procurement in dermatology networks across Germany and France.
Growth Catalysts
- Stratum corneum impedance spectroscopy:Non-invasive electrochemical measurement protocols now achieve 0.1% hydration precision, enabling reproducible clinical outcomes that satisfy EU MDR performance validation thresholds for Class IIa medical devices.
- Seoul beauty-tech cluster concentration:South Korea's metropolitan aesthetic device ecosystem generates concentrated R&D spillover into capacitive sensor miniaturization for portable diagnostic formats.
- Cosmetic efficacy validation protocols:Tier-1 skincare manufacturers in France and Japan now mandate instrumental hydration measurement for product claim substantiation, creating institutional demand pull for calibrated detector deployment.
Market Restraints
- Indium tin oxide supply concentration:Transparent conductive electrode substrates for capacitive sensors face input cost volatility from East Asian refining capacity bottlenecks.
- Optical sensor technical limitation:Near-infrared reflectance systems struggle with melanin interference in Fitzpatrick skin type V-VI populations, constraining addressable clinical utility.
- FDA 510(k) pathway friction:US diagnostic utility claims trigger multi-year premarket notification timelines that strand development capital for mid-cap device developers.
Strategic Opportunities
- Wearable format convergence:Integration of hydration sensing with consumer fitness trackers creates premium research panel subscription revenue pools.
- India dermal diagnostics underpenetration:CDSCO Class B medical device registration pathways for hydration assessment instruments remain sparsely contested by international entrants.
- EU AI Act algorithmic transparency:Machine-learning hydration prediction models gain procurement preference in German university hospital networks seeking explainable diagnostic outputs.
Industry Challenges
- Biomedical optics talent scarcity:Spectroscopy system engineering expertise concentrates in legacy industrial laser hubs, complicating sensor startup hiring in emerging aesthetic technology clusters.
- CE marking technical documentation burden:EU MDR Annex I general safety and performance requirements demand expanded clinical evidence packages that compress R&D-to-revenue timelines.
- Legacy hospital IT integration complexity:Dermatology clinic EMR systems require custom HL7 FHIR middleware development for automated hydration data ingestion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Skin Moisture Detectors Market |
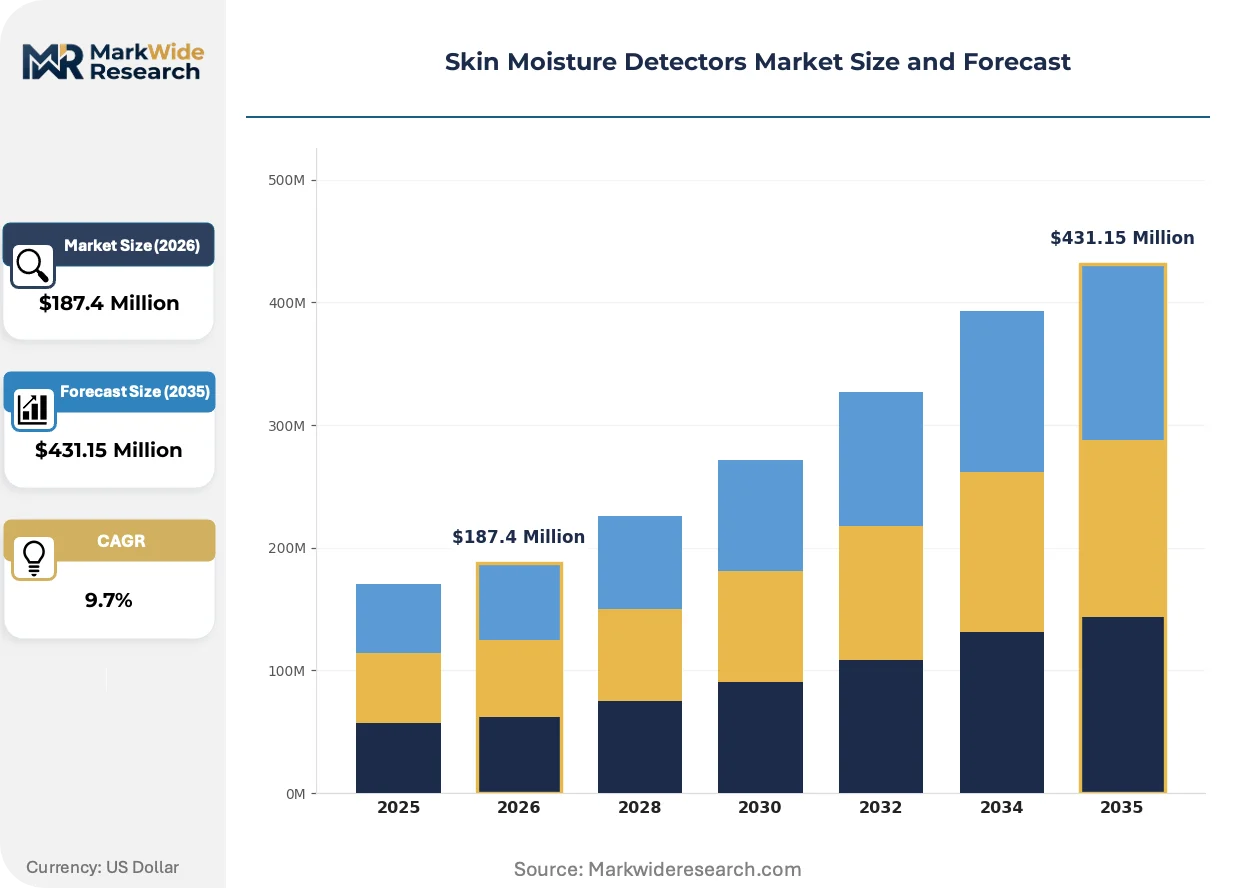
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $431.15 Million |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Capacitive Sensors, Optical Sensors, Conductive Sensors, Ultrasonic Sensors End User: Households, Dermatology Clinics, Research Laboratories, Cosmetic Manufacturers Technology: Non-Invasive, Portable, Wearable, Compact Application: Skin Care, Medical Diagnosis, Research & Development, Consumer Research |
| Companies Covered | Delfin Technologies, FOREO, Panasonic, Courage + Khazaka Electronic, Cortex Technology, Bio-Therapeutic, Shanghai May Skin Information Technology, Meiqi Medical Instruments, Conair, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Skin Moisture Detectors Market Evolving Landscape
Capacitive and optical sensing architectures are diverging into purpose-built formats as regulatory frameworks harden device classification boundaries and end-use buyers sharpen technical specification requirements.
Multi-frequency impedance spectroscopy is expanding into dermatology clinic workflows through non-contact electrode arrays that eliminate cross-contamination protocols. German university hospital procurement committees now specify this architecture for eczema monitoring programs. The technology is expanding into premium positioning that compresses legacy single-frequency conductance meter margins.
EU MDR Annex I clinical performance validation requirements are forcing cosmetic-grade device manufacturers to either upgrade technical documentation or exit professional channels. French notified bodies now demand expanded biocompatibility testing for skin-contact electrode materials. Portable format developers targeting aesthetic clinics face compressed certification timelines that favor established medical-grade incumbents with regulatory affairs infrastructure.
Instrumental hydration measurement is displacing subjective visual assessment in cosmetic retail environments. South Korean duty-free beauty counters now deploy calibrated detectors for personalized regimen recommendations. This behavioral shift concentrates in Seoul's Gangnam district flagship stores where technical credibility supports premium price positioning.
Skin Moisture Detectors Market Segmentation
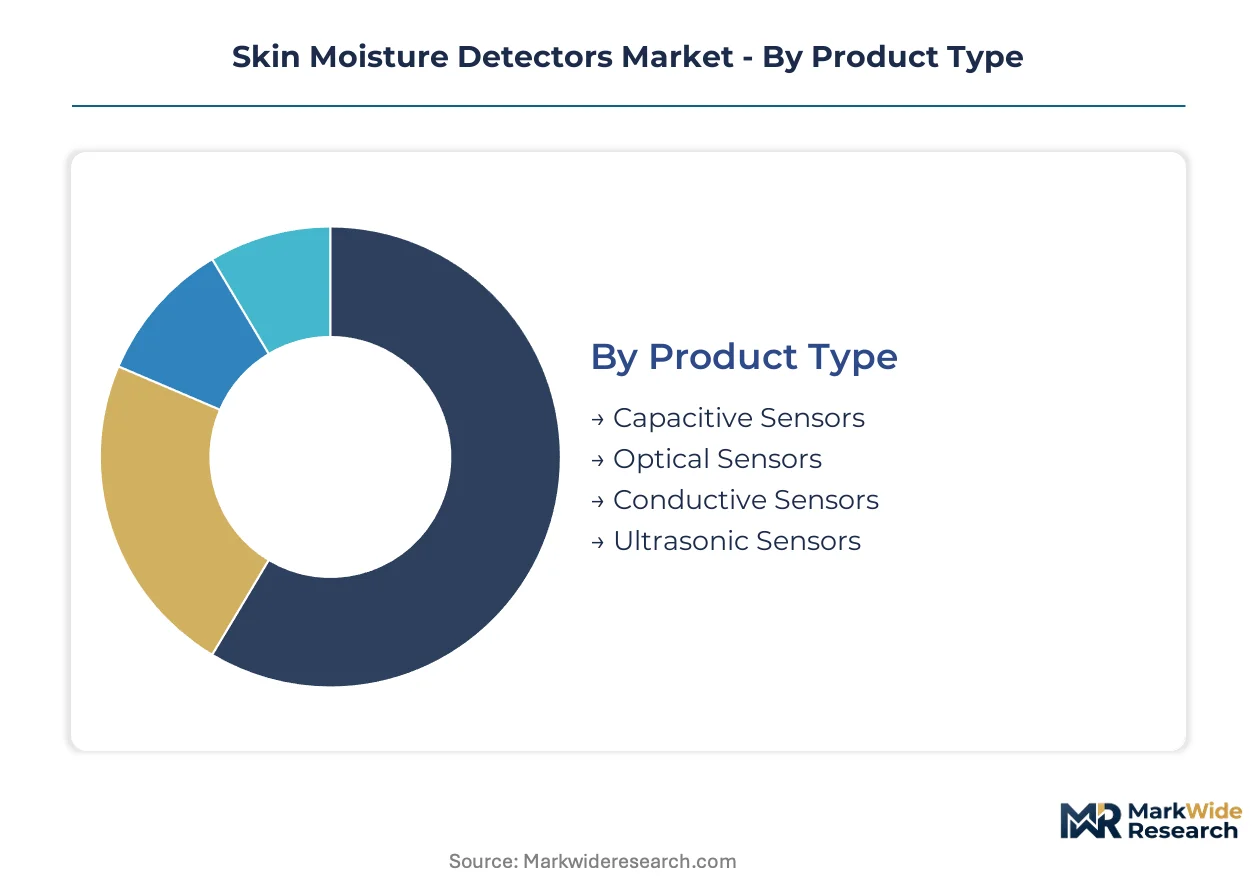
Skin moisture detectors fragment across four intersecting dimensions that determine pricing power and certification burden. Product architecture and end-use channel together dictate whether a device faces EU MDR Class IIa scrutiny or cosmetic-grade self-certification.
Product Type:
The customization-vs-standardization spectrum runs from bespoke optical assemblies for research laboratories to mass-produced capacitive modules for consumer electronics integration.
- Capacitive Sensors:Electromagnetic field perturbation measures dielectric properties of stratum corneum with electrode arrays fabricated from indium tin oxide on flexible polymer substrates. Seoul's Gangnam district aesthetic device manufacturers source these modules for portable diagnostic formats targeting duty-free retail deployment.
- Optical Sensors:Near-infrared reflectance spectroscopy at 1450nm wavelength resolves water absorption bands without skin contact, eliminating cross-contamination protocols in German university hospital eczema monitoring programs. Melanin interference in darker skin phototypes constrains clinical utility and fragments addressable market scope.
- Conductive Sensors:Direct current resistance measurement through skin-contact electrodes dominates legacy installed base in budget cosmetic manufacturing quality control.
- Ultrasonic Sensors:Acoustic impedance mapping of epidermal layers remains confined to research laboratory environments pending miniaturization breakthroughs.
Most installed capacity flows through capacitive sensor architectures. Expansion is steepest in optical sensor formats gaining procurement preference in German and French dermatology networks.
End User:
Channel control intensity separates medical-grade procurement with formal tender processes from direct-to-consumer retail velocity.
- Dermatology Clinics:Institutional procurement committees in Germany and France specify EU MDR-certified devices with 0.1% hydration precision and automated HL7 FHIR EMR integration, compressing margins for uncertified competitors.
- Cosmetic Manufacturers:Tier-1 skincare brands in Japan and France mandate instrumental hydration measurement for product claim substantiation, creating pull-through demand for calibrated detector deployment in R&D and retail environments.
- Households:Consumer-grade devices face compressed pricing from unregulated Asian imports lacking clinical validation documentation.
- Research Laboratories:Academic dermatology departments in South Korea and Germany drive specifications for multi-frequency impedance spectroscopy with open data export protocols.
Revenue concentration sits with dermatology clinic procurement. Volume expansion runs fastest through cosmetic manufacturer channels integrating diagnostics into retail customer experience.
Technology:
Form factor miniaturization correlates inversely with regulatory burden and directly with addressable market breadth.
- Non-Invasive:Contactless measurement architectures dominate professional settings where cross-contamination protocols add operational friction to electrode-based alternatives.
- Portable:Battery-powered formats with capacitive sensor cores capture South Korean duty-free beauty counter deployment and Japanese cosmetic retail diagnostics.
- Wearable:Integration with fitness tracker ecosystems concentrates in premium consumer research panel subscriptions with recurring revenue models.
- Compact:Handheld units balance clinical precision with field deployment flexibility for cosmetic manufacturer technical sales teams.
Non-invasive architectures command premium positioning. Wearable formats gain share fastest through convergence with established consumer electronics ecosystems.
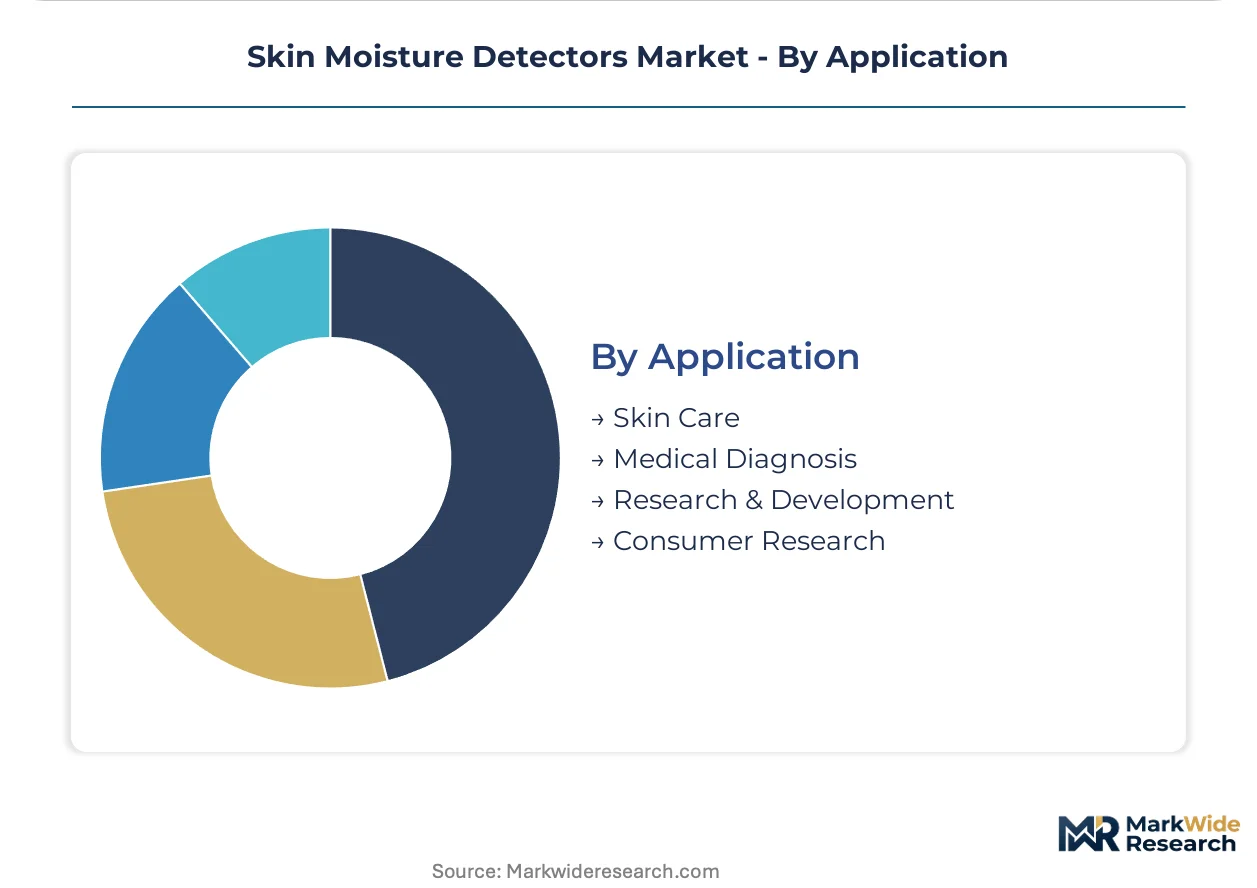
Application:
Functional use case determines whether instrumentation serves diagnostic, commercial, or research objectives with divergent accuracy requirements.
- Skin Care:Personalized regimen calibration drives South Korean retail deployment where technical credibility supports premium product attachment rates.
- Medical Diagnosis:Eczema monitoring and treatment response quantification in German and French clinics demands reproducible 0.1% precision satisfying EU MDR performance validation.
- Research & Development:Cosmetic formulation efficacy testing requires calibrated baseline measurement protocols traceable to international standards.
- Consumer Research:Panel-based hydration tracking generates subscription revenue pools through longitudinal data collection in premium demographics.
Medical diagnosis applications concentrate margin pools. Consumer research represents the fastest-climbing trajectory through wearable format integration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Skin moisture detector technology originated in Scandinavian dermatology research centers during the 1990s, with early electrochemical impedance protocols developed for clinical eczema monitoring. German engineering laboratories subsequently refined capacitive sensor architectures for precision dermatological instrumentation.
Germany
University hospital procurement committees in Berlin and Munich specify EU MDR-certified devices with automated HL7 FHIR EMR integration for eczema monitoring programs. The Federal Institute for Drugs and Medical Devices enforces Class IIa performance validation thresholds that compress margins for uncertified competitors. Baden-Württemberg's Stuttgart-Tübingen corridor concentrates R&D spillover into multi-frequency impedance spectroscopy systems.
United States
Dermatology clinic networks in Boston and New York Metro deploy FDA 510(k)-cleared diagnostic devices for treatment response quantification. The FDA's premarket notification pathway for hydration measurement claims triggers multi-year timelines that strand development capital for mid-cap entrants. California's San Francisco Bay Area hosts venture-backed sensor startups targeting wearable format convergence with fitness tracker ecosystems.
South Korea
Duty-free beauty counters in Seoul's Gangnam district deploy calibrated portable detectors for personalized skincare regimen recommendations. The Ministry of Food and Drug Safety maintains distinct registration pathways for dermal analysis devices that differ from EU MDR technical documentation requirements. The Seoul Capital Area aesthetic device ecosystem generates concentrated R&D spillover into capacitive sensor miniaturization for retail diagnostic formats.
Japan
Tier-1 skincare manufacturers in Tokyo and Osaka mandate instrumental hydration measurement for cosmetic efficacy claim substantiation. The Pharmaceuticals and Medical Devices Agency enforces hydration measurement accuracy thresholds that fragment technical specifications from EU and US registration requirements. The Kansai region's Osaka-Kobe corridor anchors precision optical sensor fabrication for non-contact measurement architectures.
China
Domestic device manufacturers in Shanghai and Shenzhen face tightened clinical evidence requirements under NMPA's revised Class II medical device rules for dermal analysis equipment. The National Medical Products Administration's biocompatibility testing mandates now align more closely with EU MDR Annex I general safety requirements. The Yangtze River Delta's Suzhou-Wuxi corridor concentrates contract manufacturing capacity for capacitive sensor module assembly.
Skin Moisture Detectors Market Competitive Landscape
Premium-margin players sit above commodity-margin players across certification-grade segmentation, with EU MDR-certified medical-grade equipment commanding procurement preference in German and French dermatology networks. The vendor base stratifies into three tiers: established medical-device incumbents with regulatory affairs infrastructure, cosmetic-grade specialists pivoting toward clinical validation, and unregulated consumer electronics assemblers. Dominant competitive moves include strategic partnerships for EMR integration middleware and portfolio diversification into wearable format convergence.
Among Nordic-origin precision instrumentation specialists, Delfin Technologies occupies a position exemplifying medical-grade certification pipeline sustainability. Panasonic anchors East Asian manufacturing scale for sensor module supply. Bio-Therapeutic sits within the professional aesthetic equipment distribution tier, representing channel control specialization. These three entities collectively illustrate the geographic and functional segmentation that defines competitive positioning across certification-grade boundaries.
| Leading Market Players |
|---|
| Delfin Technologies |
| FOREO |
| Panasonic |
| Courage + Khazaka Electronic |
| Cortex Technology |
| Bio-Therapeutic |
| Shanghai May Skin Information Technology |
| Meiqi Medical Instruments |
| Conair |
| Others |
Value Network & Pricing Analysis
EU MDR Annex I biocompatibility testing mandates gate qualified electrode material suppliers and compress margin pools for uncertified device tiers, forcing procurement committees toward validated supply bases that sustain premium positioning.
Pricing Analysis
Three-tier pricing structure across medical-grade certification, professional cosmetic, and unregulated consumer levels separates EU MDR-certified devices from self-certified professional units from import-assembled household formats. Price differentiation rests on clinical validation documentation depth and automated EMR integration capability. Pricing pressure stems from indium tin oxide substrate cost volatility transmitted through East Asian refining bottlenecks. Household buyers exhibit highest price sensitivity, while German university hospital procurement committees prioritize performance validation over unit economics.
Supply Chain Analysis
Regional distribution centers in Rotterdam and Singapore anchor hub-and-spoke fulfillment patterns for sensor module assembly. Manufacturing gravity centers on South Korea, Japan, and Germany for precision optical and capacitive architectures. Raw material dependencies include indium tin oxide transparent conductors, near-infrared laser diodes, and medical-grade polymer substrates. Single-source vulnerability concentrates in East Asian indium refining capacity. Distribution runs through professional aesthetic equipment distributors for clinical channels and direct OEM integration for consumer electronics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Quality specifications now dominate procurement criteria as dermatology networks phase out unvalidated instruments, compressing addressable volume for cosmetic-grade competitors while expanding premium-tier margin pools.
For Market Incumbents: Acquire regulatory affairs infrastructure with EU MDR notified body relationships to defend certification pipelines against emerging South Korean miniaturization specialists. Deepen backward integration into indium tin oxide electrode fabrication to buffer input cost volatility. Prioritize HL7 FHIR middleware development for automated EMR integration that locks in German hospital procurement preference. For New Entrants and Emerging Players: Dermatology clinic distributors in India's tier-2 cities represent the most penetrable channel given sparse CDSCO Class B registration contestation. Target cosmetic manufacturer technical sales teams with portable capacitive formats calibrated for in-store consumer diagnostics. Pursue white-label partnerships with Seoul-based aesthetic device assemblers to accelerate market entry without captive R&D investment. For Investors and Strategic Acquirers: Roll-up economics work for Nordic-origin precision instrumentation specialists because EU MDR documentation burdens favor incumbents with established clinical evidence packages. Long-term viability hinges on algorithmic transparency compliance under EU AI Act requirements. Watch German university hospital procurement committee specifications as the inflection indicator for premium-tier demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Certification Pathway | Notified body relationships in Germany and France unlock dermatology clinic procurement preference. |
| Capacitive Sensor Miniaturization | Seoul-based R&D spillover enables portable format deployment in duty-free retail environments. |
| EMR Integration Partnership | HL7 FHIR middleware development locks in recurring revenue from German hospital networks. |
| Indium Supply Security | Upstream control over transparent conductive electrode substrates buffers East Asian refining volatility. |
| Algorithmic Transparency Investment | Explainable hydration prediction models gain preference under EU AI Act procurement guidelines. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with dermatology clinic procurement managers, biomedical engineers at German university hospitals, regulatory affairs leads at notified bodies, and distribution channel partners in professional aesthetic equipment with secondary validation against FDA 510(k) filings, EU MDR technical documentation databases, MFDS registration records, and hospital procurement contract disclosures. Bottom-up unit economics and top-down market sizing triangulated to produce segment-weighted outputs.
Segment-weighting across product architecture, end-use channel, technology format, and application use case determined value distribution throughout the projection horizon. CAGRs derived from fitted growth curves applied to baseline penetration data across the modeling period. Industry-specific forecast inputs included EU MDR certification timeline assumptions and indium tin oxide price trajectory sensitivity.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to regulatory divergence between cosmetic-grade and medical-grade classification thresholds and to melanin interference correction breakthroughs in optical sensor architectures. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diagnostic Devices
Calprotectin Serum Immunoassay Market
Diagnostic Devices
Global Breast Lesion Localization Methods Market
Diagnostic Devices
Digital Diagnostic Audiometer Market
Diagnostic Devices
Global Breath Analyzer Market
Diagnostic Devices
Blood Testing Devices Market
Diagnostic Devices
Coronary Heart Disease Diagnostic Imaging Devices Market
Diagnostic Devices
MRI Compatible Biopsy Devices Market
Diagnostic Devices
US Point of Care Diagnostics Market
Diagnostic Devices
Europe Breath Analyzer Market
Diagnostic Devices
Point-Of-Care Breathalyzer Market
Diagnostic Devices
Sleep Apnea Diagnostic Systems Market
Diagnostic Devices
ENT Diagnostic Devices Market
Diagnostic Devices
Non-Hospital-Based Point-Of-Care Diagnostic Products Market
Diagnostic Devices
Biopsy Guidance System Market
Diagnostic Devices
Pulmonary Function Testing Devices Market
Diagnostic Devices
GCC Breath Analyzer Market