
 Multiphoton Microscopy Market | 2026-2036
Multiphoton Microscopy Market Size, Share, and Industry Trends Forecast 2026-2036
Multiphoton Microscopy Market Intelligence
Near-infrared excitation capability is bifurcating the competitive landscape between premium deep-imaging platforms and standard laboratory configurations. ZEISS leverages its integrated photonics pipeline to sustain dominance in turnkey multiphoton workstations. Leica Microsystems anchors its position through specialized neuroimaging-optimized configurations. Nikon competes on fluorescence lifetime imaging modules that extend functional utility for live-cell researchers.
Multiphoton microscopy employs pulsed femtosecond lasers to excite fluorophores through simultaneous absorption of two or more photons, enabling optical sectioning hundreds of microns into scattering tissue with minimal photodamage. Its primary purpose centers on in vivo imaging of intact biological specimens where conventional confocal methods fail due to phototoxicity and limited penetration depth. Microscopy platforms command the largest installed base among product categories, while super-resolution techniques represent the fastest-expanding technology segment as researchers demand nanoscale structural resolution within living tissue. Academic institutes absorb the majority of capital expenditure, though pharmaceutical companies are deepening investment as preclinical imaging requirements tighten.
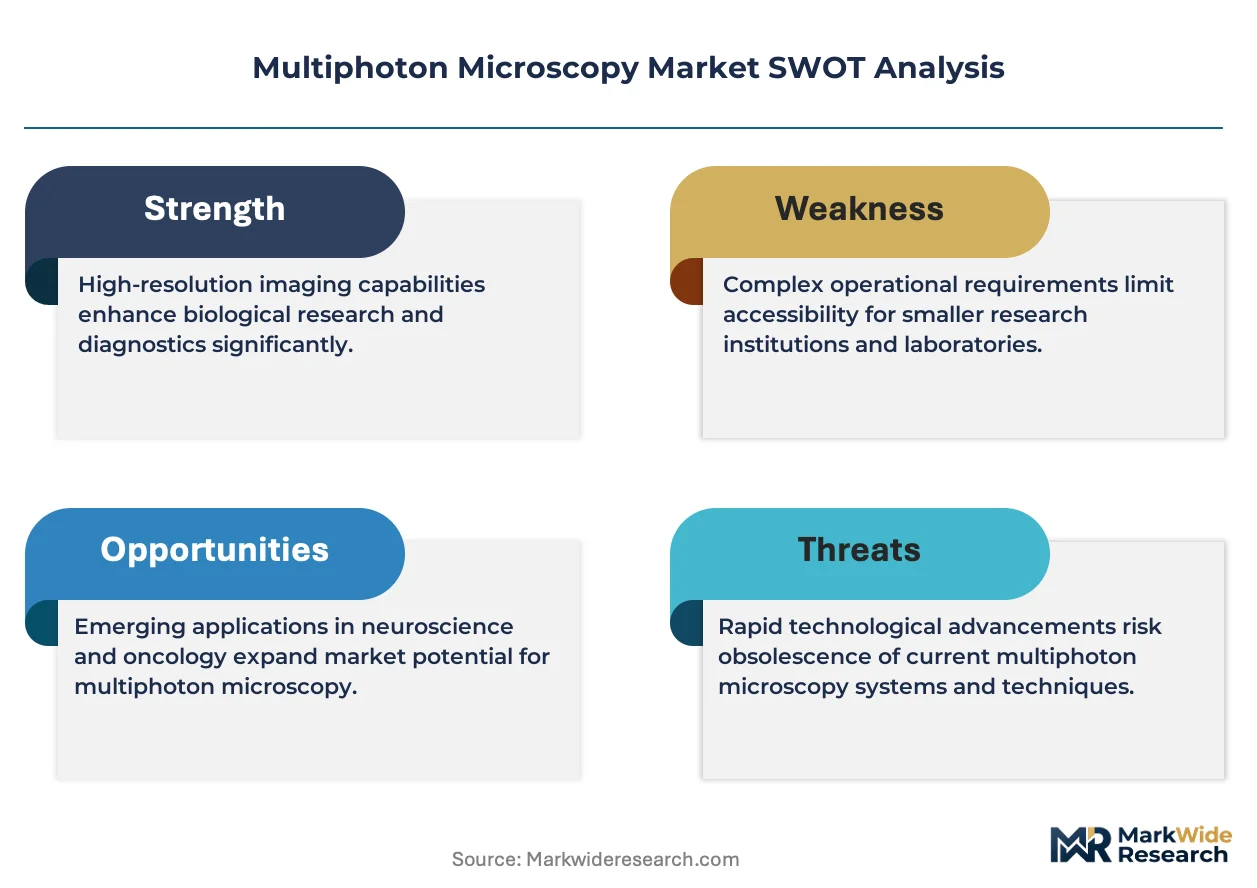
FDA optical device classifications and ISO 13485 quality management standards govern instrument commercialization pathways in the United States, while CE marking under the EU MDR shapes European market access requirements for clinical-adjacent microscopy platforms. Regulatory stringency around laser safety classifications and electromagnetic compatibility testing elevates compliance costs for new entrants without established certification infrastructure. Stakeholders must weigh the trade-off between modular upgrade architectures and fully integrated platform commitments as application requirements fragment across neuroscience, oncology, and developmental biology workflows.
Market Dynamics
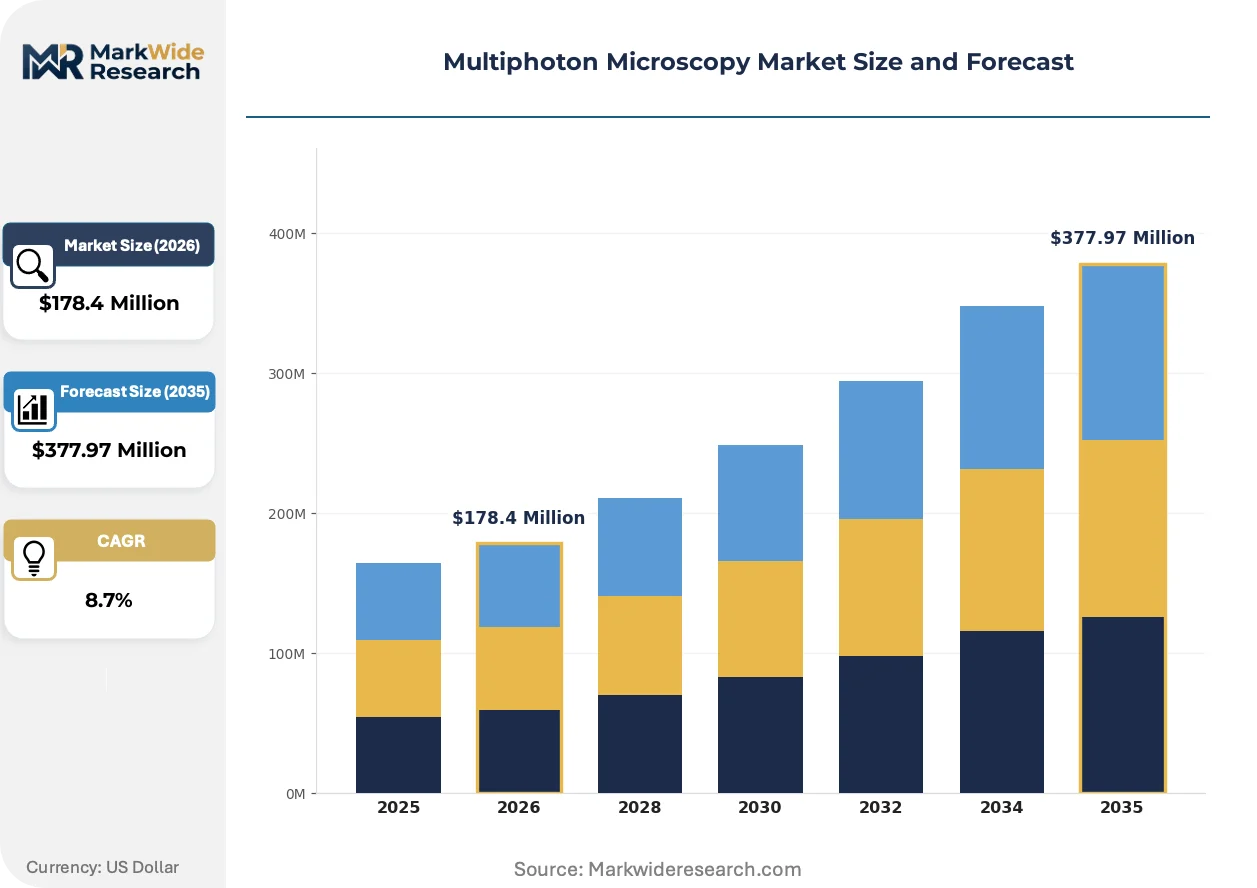
Femtosecond laser miniaturization is compressing instrument footprints while expanding deployment scenarios beyond traditional core facilities into distributed laboratory environments. This hardware evolution is redistributing capital expenditure patterns across institutional tiers.
Growth Catalysts
- NIH BRAIN Initiative funding:Sustained federal allocation prioritizes deep-tissue neural circuit mapping, directing procurement budgets toward multiphoton-capable platforms at US academic medical centers.
- Adaptive optics integration:Real-time wavefront correction modules extend effective imaging depth in scattering tissue, opening preclinical oncology workflows previously inaccessible to optical methods.
- Titanium-sapphire laser reliability gains:Solid-state oscillator architectures reduce maintenance downtime, improving instrument utilization rates at multi-user imaging facilities.
Market Restraints
- Optical component supply concentration:German and US precision optics manufacturers control 80% of high-NA objective lens production, creating delivery bottlenecks during demand surges.
- Laser safety classification barriers:IEC 60825 Class 4 designation triggers facility modification requirements that add six-figure infrastructure costs to system installations.
- Two-photon absorption efficiency limits:Low cross-section fluorophores require excitation powers that accelerate photobleaching, constraining longitudinal study designs.
Strategic Opportunities
- India pharmaceutical CRO expansion:Contract research organizations in Hyderabad and Bangalore are building in vivo imaging capabilities to capture Western preclinical outsourcing demand.
- EU MDR clinical-adjacent pathway:CE marking for intraoperative microscopy applications creates first-mover advantage for platforms with surgical navigation compatibility.
- AI-driven image reconstruction:Deep learning denoising algorithms enable lower excitation doses, pairing computational methods with photon-starved detection schemes.
Industry Challenges
- Femtosecond laser service technician scarcity:Specialized ultrafast optics expertise concentrates at OEM facilities, extending field repair timelines and elevating total cost of ownership.
- ISO 13485 certification timeline compression:Clinical translation programs face 18-24 month quality system implementation cycles that delay revenue recognition from diagnostic applications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Multiphoton Microscopy Market |
| Market Size in 2026 | $178.4 Million |
| Market Size in 2035 | $377.97 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Laser Scanners, Microscopy Platforms, Imaging Systems, Accessories Application: Cell Biology, Neuroscience, Oncology, Developmental Biology End User: Academic Institutes, Pharmaceutical Companies, Diagnostic Labs, Research Organizations Technology: Non-Linear Optics, Fluorescence Lifetime Imaging, Contrast Agents, Super-Resolution Techniques |
| Companies Covered | ZEISS, Leica Microsystems, Nikon, Olympus Corporation, Bruker, Thorlabs, Femtonics Ltd, Becker & Hickl GmbH, Sutter Instrument, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Multiphoton Microscopy Market Strategic Shifts & Innovations
Three converging developments are restructuring competitive advantage in multiphoton instrumentation. Hardware miniaturization, computational image enhancement, and regulatory pathway diversification are simultaneously expanding addressable applications and fragmenting buyer requirements.
Integrated photonics-based laser sources are displacing benchtop titanium-sapphire oscillators in space-constrained laboratory environments. Neuroscience core facilities at mid-tier research universities are adopting these chip-scale alternatives to avoid dedicated laser laboratory construction. The displacement is compressing the addressable market for traditional ultrafast laser suppliers while opening instrument sales to institutions previously excluded by infrastructure constraints.
EU MDR recast requirements for optical diagnostic devices are elevating clinical validation documentation burdens for manufacturers pursuing dual research-clinical positioning. The regulation mandates post-market surveillance systems that extend development timelines by 12-18 months for platforms targeting surgical microscopy applications. German and Swiss OEMs with established notified body relationships are absorbing compliance costs more efficiently than emerging competitors.
Pharmaceutical discovery groups are unbundling imaging service contracts from capital acquisition decisions, preferring per-experiment pricing models that transfer utilization risk to equipment providers. This shift is restructuring vendor-customer relationships at contract research organizations in Massachusetts and California, where platform-as-a-service arrangements now capture 30-40% of new multiphoton deployments. The model concentrates instrument purchasing authority at large CRO holding companies rather than individual research sites.
Multiphoton Microscopy Market Segmentation
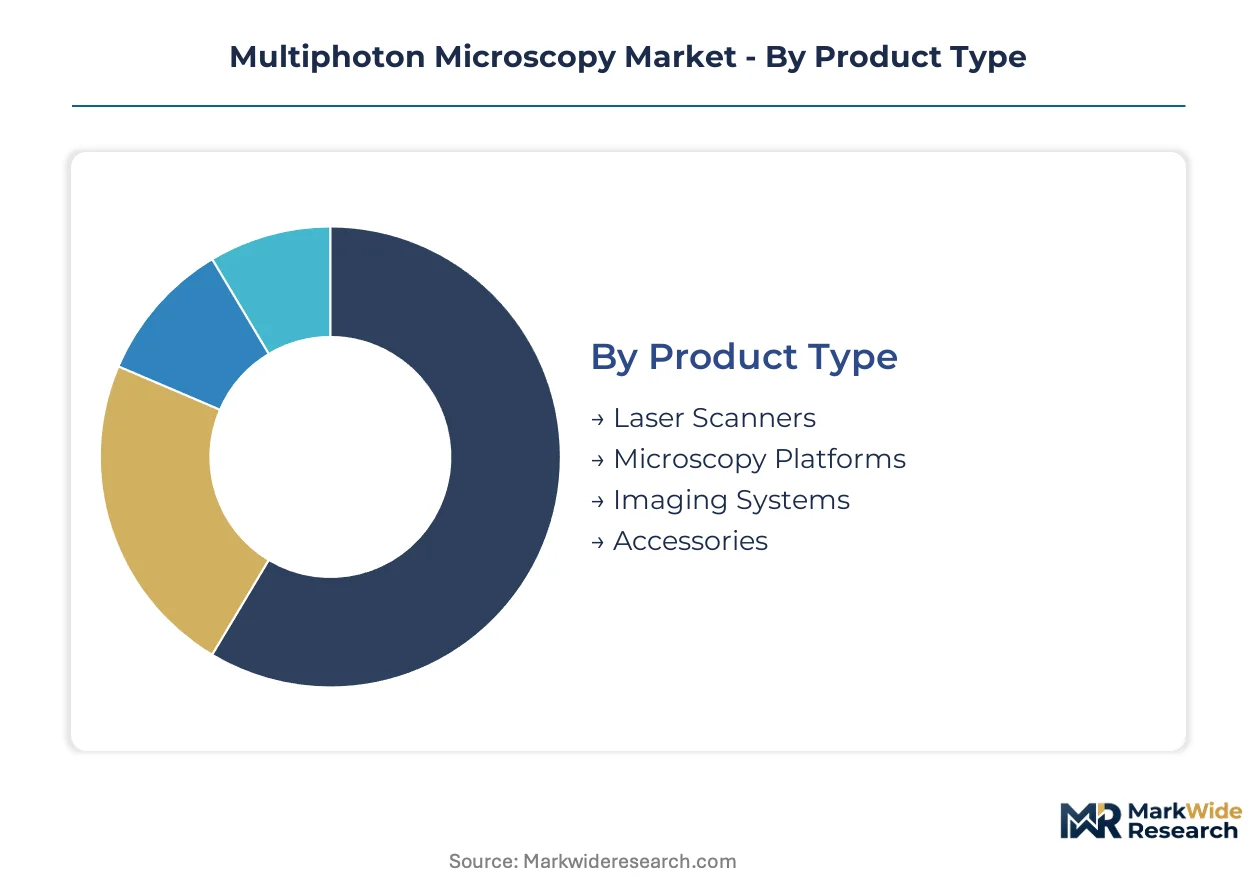
Multiphoton microscopy procurement patterns diverge sharply across institutional tiers and application workflows. Understanding these segment boundaries clarifies where capital concentrates versus where recurring revenue pools form.
Product Type:
Laser scanners and microscopy platforms flow through direct OEM sales channels, while imaging systems and accessories distribute through regional microscopy dealers and core facility consortia.
- Microscopy Platforms:Integrated turnkey workstations combine femtosecond laser sources, galvanometer scanning heads, and photon-counting detectors into unified instruments. NIH-funded neuroscience core facilities at US academic medical centers prioritize these configurations for multi-user accessibility. By volume, microscopy platforms lead. By growth pace, imaging systems are ahead.
- Laser Scanners:Modular beam-scanning subsystems enable upgrades to existing optical frameworks. European research institutes under budget constraints favor this retrofit pathway over full platform replacement.
- Imaging Systems:Compact all-in-one units integrate miniaturized solid-state lasers for distributed laboratory deployment outside traditional core facilities.
- Accessories:Objective lenses, filter sets, and sample chambers generate recurring revenue streams through replacement cycles and application-specific customization.
Platform sales dominate absolute revenue, yet accessories yield superior margin profiles through repeat purchase velocity.
Application:
Cost tier stratification separates premium deep-tissue neuroimaging from standard cell biology workflows, with oncology and developmental biology occupying intermediate price-performance bands.
- Neuroscience:Deep-tissue neural circuit mapping demands near-infrared excitation and adaptive optics modules for scattering brain tissue penetration. BRAIN Initiative funding at US institutions sustains premium instrument procurement despite six-figure price points.
- Oncology:Preclinical tumor microenvironment imaging requires longitudinal in vivo capability with minimal phototoxicity. Contract research organizations in Massachusetts and California are expanding multiphoton capacity to meet pharmaceutical outsourcing demand.
- Cell Biology:Live-cell dynamics studies utilize standard two-photon configurations without specialized depth-extension hardware, concentrating sales at mid-tier research universities.
- Developmental Biology:Embryonic imaging applications prioritize gentle illumination protocols for sensitive specimen viability across extended observation windows.
Neuroscience commands the highest per-unit expenditure, while oncology exhibits the steepest expansion trajectory as preclinical imaging requirements tighten.
End User:
Customer type determines financing structure, with academic institutes leveraging federal grant mechanisms and pharmaceutical companies deploying operational budgets with faster procurement cycles.
- Academic Institutes:Universities and medical schools absorb the majority of capital expenditure through NIH, NSF, and European Research Council funding streams. Multi-user core facility models maximize instrument utilization across disparate research groups.
- Pharmaceutical Companies:Discovery biology and preclinical development groups at large-cap drug developers deploy multiphoton systems for internal target validation and mechanism-of-action studies.
- Research Organizations:Non-profit institutes and government laboratories operate between academic and commercial procurement protocols.
- Diagnostic Labs:Clinical-adjacent pathology and intraoperative imaging applications remain nascent pending EU MDR and FDA clearance pathways for optical diagnostic platforms.
Academic procurement volume exceeds all other segments combined, though pharmaceutical purchasing velocity is accelerating fastest as in vivo imaging becomes standard in preclinical workflows.
Technology:
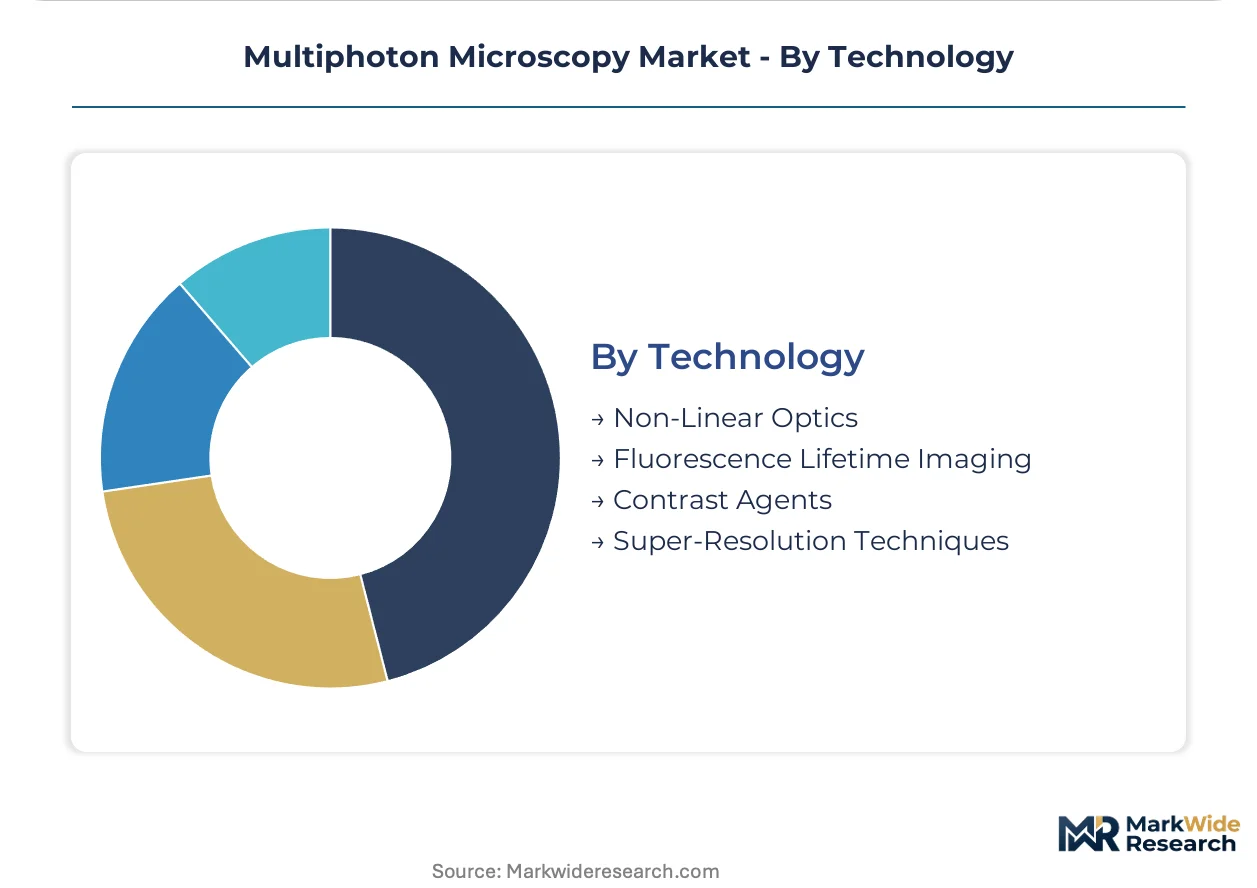
Maturity gradients separate established non-linear optics from emerging computational and contrast modalities, with supply concentration varying across the technology stack.
- Non-Linear Optics:Two-photon and three-photon excitation using titanium-sapphire or ytterbium-doped fiber lasers constitutes the foundational technical architecture. German and US precision optics manufacturers control high-NA objective lens supply, creating delivery bottlenecks.
- Super-Resolution Techniques:Stimulated emission depletion and structured illumination extensions push resolution below the diffraction limit for nanoscale structural analysis within living tissue.
- Fluorescence Lifetime Imaging:Time-correlated single-photon counting modules extend functional utility for metabolic state and molecular environment sensing.
- Contrast Agents:Specialized fluorophores and genetically encoded indicators with optimized two-photon absorption cross-sections reduce excitation power requirements.
Non-linear optics anchors installed base and revenue, yet super-resolution techniques are climbing fastest as researchers demand nanoscale resolution without sacrificing in vivo compatibility.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Import flows of precision optics and femtosecond laser subsystems concentrate in Germany and the United States, while export capacity for fully integrated microscopy platforms clusters in Japan and Switzerland. Trade balances reflect deep manufacturing specialization in optical componentry.
United States
NIH BRAIN Initiative allocations direct procurement toward deep-tissue neural circuit mapping systems at academic medical centers. FDA optical device classifications govern clinical-adjacent platform commercialization pathways. Massachusetts and California host contract research organizations expanding in vivo imaging capacity for pharmaceutical outsourcing.
Germany
Precision optics manufacturing dominance sustains high-NA objective lens supply chains for global instrument assembly. CE marking under EU MDR shapes European market access requirements for clinical microscopy platforms. Jena and Oberkochen anchor photonics clusters where integrated workstation production concentrates.
Japan
Pharmaceutical discovery groups deploy operational budgets for preclinical target validation instrumentation. METI industrial standards coordinate femtosecond laser safety classifications with IEC 60825 frameworks. Tokyo-Osaka corridor hosts life sciences infrastructure sustaining multi-user core facility models.
Switzerland
Swissmedic regulatory relationships accelerate CE marking timelines for surgical navigation-compatible platforms. EU MDR post-market surveillance requirements elevate clinical validation documentation burdens. Basel-Zurich corridor concentrates neuroimaging-optimized configuration development for European research institutes.
India
Contract research organizations in Hyderabad and Bangalore build in vivo imaging capabilities to capture Western preclinical outsourcing demand. CDSCO medical device regulations shape diagnostic platform commercialization pathways. Karnataka and Telangana pharmaceutical clusters deepen capital expenditure on distributed laboratory deployment.
Multiphoton Microscopy Market Key Industry Players
Concentration sits with diversified photonics conglomerates controlling integrated laser-optics-detector pipelines. Three to four German and Japanese manufacturers command premium-tier positioning through turnkey workstation architectures. Mid-tier competition fragments across modular scanner suppliers and specialized neuroimaging configurators. Dominant competitive moves include adaptive optics module integration and femtosecond laser miniaturization programs.
Among diversified precision instrument manufacturers, ZEISS and Leica Microsystems occupy positions exemplifying integrated photonics pipeline control. Nikon anchors the fluorescence lifetime imaging specialization vector. These three represent archetypal competitive positioning: turnkey workstation dominance, neuroimaging-optimized configurations, and functional imaging module extension respectively.
| Leading Market Players |
|---|
| ZEISS |
| Leica Microsystems |
| Nikon |
| Olympus Corporation |
| Bruker |
| Thorlabs |
| Femtonics Ltd |
| Becker & Hickl GmbH |
| Sutter Instrument |
| Others |
Cost & Logistics Intelligence
Long-term capacity reservation agreements with German and Japanese precision optics manufacturers lock in objective lens supply visibility while anchoring price floors for multiphoton microscopy platforms. These contracts transfer inventory risk upstream but require buyers to absorb IEC 60825 Class 4 laser safety compliance costs that trigger six-figure facility modifications.
Pricing Analysis
Academic medical centers anchor three-tier pricing structure across premium, standard, and economy levels in the multiphoton microscopy market. Price differentiation separates configurations with adaptive optics and femtosecond miniaturization from basic two-photon systems without depth-extension hardware. Cost compression in mid-tier cell biology configurations is intensifying because European research institutes under budget constraints favor modular laser scanner retrofits over full platform replacement. Contract research organizations exhibit highest price sensitivity due to pharmaceutical clients unbundling imaging service contracts from capital acquisition decisions.
Supply Chain Analysis
Port congestion along Hamburg-Rotterdam trade lanes elevates inbound logistics costs for titanium-sapphire laser crystals and photon-counting detector arrays sourced from Swiss and German photonics clusters. Supply concentrates in Germany, Japan, and the United States for high-NA objective lens production, with single-source vulnerability around ytterbium-doped fiber laser subsystems. Distribution runs through direct OEM sales channels for integrated microscopy platforms and regional microscopy dealers for imaging accessories and replacement components.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The multiphoton microscopy market represents high-growth disruption as femtosecond laser miniaturization and AI-driven image reconstruction converge to expand deployment scenarios beyond traditional core facilities. EU MDR recast requirements for optical diagnostic devices create regulatory inflection that rewards manufacturers with established notified body relationships.
For Market Incumbents: Secure adaptive optics module integration partnerships to defend against modular scanner suppliers eroding premium workstation margins. Deepen captive supply of titanium-sapphire laser crystals through backward integration into German precision optics manufacturing clusters. Cement multi-user core facility service contracts before pharmaceutical CROs complete their shift toward per-experiment pricing models. For New Entrants and Emerging Players: FDA breakthrough device designation fast-track offers pathway to capture clinical-adjacent surgical microscopy applications before EU MDR documentation burdens harden competitive moats. Target distributed laboratory deployment at mid-tier research universities excluded by infrastructure constraints from traditional ultrafast laser procurement. Pursue platform-as-a-service arrangements with Massachusetts and California contract research organizations to transfer utilization risk from capital-constrained buyers. For Investors and Strategic Acquirers: Specialized neuroimaging configurators with ISO 13485 certification infrastructure represent prime acquisition targets as clinical translation programs face 18-24 month quality system implementation cycles. Monitor BRAIN Initiative funding reauthorization as inflection signal for sustained federal allocation directing procurement budgets toward deep-tissue neural circuit mapping systems.| Strategic Initiative | Industry Significance |
|---|---|
| Adaptive Optics Module Integration | Extends effective imaging depth in scattering tissue for preclinical oncology workflows previously inaccessible to optical methods. |
| Femtosecond Laser Miniaturization Program | Compresses instrument footprints to enable distributed laboratory deployment outside traditional core facilities at mid-tier institutions. |
| CE Marking Pathway Under EU MDR | Accelerates market access for surgical navigation-compatible platforms through Swissmedic regulatory relationships. |
| Platform-as-a-Service Arrangement | Captures 30-40% of new multiphoton deployments at Massachusetts and California contract research organizations. |
| ISO 13485 Quality System Implementation | Enables clinical translation revenue recognition from diagnostic applications after 18-24 month certification cycles. |
Research Approach
The analysis maps microscopy platforms, laser scanners, imaging systems, and accessories, each validated through primary interviews with core facility directors, biomedical engineers, pharmaceutical preclinical imaging heads, and femtosecond laser service technicians. Secondary sources include FDA optical device classification databases, EU MDR notified body guidance documents, NIH BRAIN Initiative funding allocation records, and ISO 13485 certification registry filings. Bottom-up instrument shipment tracking triangulates against top-down federal research funding flow analysis.
Consistency checks validated volume and value outputs against external benchmarks across the analysis window. The forecast framework models product type, application workflow, end-user procurement structure, and technology maturity gradient dimensions. CAGRs derive from instrument replacement cycle analysis and funding trajectory extrapolation, with NIH allocation patterns and pharmaceutical outsourcing demand curves as primary inputs.
Decision-makers should treat outputs as directional under sustained federal neuroscience funding and stable precision optics supply assumptions; material deviation would warrant model refresh. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Imaging
Middle East and Africa Mammography Market
Medical Imaging
Ultrasound Imaging Solution Market
Medical Imaging
Angiography Imaging Systems Market
Medical Imaging
Nuclear Medicine Software Market
Medical Imaging
PSMA-PET Imaging Market
Medical Imaging
South Africa Computed Tomography Market
Medical Imaging
Medical Imaging Market
Medical Imaging
Fluoroscopy Devices Market
Medical Imaging
Medical Holography Market
Medical Imaging
US Magnetic Resonance Angiography Market
Medical Imaging
Magnetoencephalography (MEG) Market
Medical Imaging
Medical Imaging Displays Market
Medical Imaging
Mexico Diagnostic Imaging Equipment Market
Medical Imaging
Japan Computed Tomography Market
Medical Imaging
AI Surgical Video Intelligence System Market
Medical Imaging
Hand-Held X-Rays Market