
 South Korea Diagnostic Imaging Equipment Market | 2026-2036
South Korea Diagnostic Imaging Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
South Korea Diagnostic Imaging Equipment Market Analytics
The South Korean diagnostic imaging equipment landscape is restructuring around a widening capability gap between premium systems with AI-integrated diagnostics and commodity hardware serving price-sensitive clinics. Samsung Healthcare leverages its semiconductor heritage to anchor domestic CT and ultrasound production. Siemens Healthineers differentiates through advanced MRI platforms with embedded clinical decision support. GE Healthcare sustains its installed base via long-term service contracts and refurbished equipment programs.
South Korea diagnostic imaging equipment encompasses ionizing and non-ionizing modalities that generate anatomical and functional visualizations for clinical diagnosis, with CT scanners typically employing X-ray tubes rotating at 0.25-0.35 seconds per revolution and field strengths for MRI ranging from 1.5 to 3.0 Tesla. The equipment serves oncology staging, interventional cardiology guidance, and orthopedic surgical planning across hospital networks. X-ray systems occupy the largest installed base but face margin compression from digital retrofit kits and extended replacement intervals. Ultrasound segments show structural momentum in point-of-care settings where portable digital platforms displace cart-based analog units. MRI commands premium positioning in neurology and cardiac applications where advanced imaging protocols justify higher capital outlays.
MFDS enforces Good Manufacturing Practice standards and post-market surveillance requirements that shape product registration timelines and clinical evidence obligations for new modality introductions. The Ministry of Health and Welfare governs national health insurance reimbursement rates that directly influence hospital capital expenditure cycles and technology upgrade decisions. Stakeholders must monitor pending reimbursement category expansions for AI-assisted diagnostic reads and hybrid imaging procedures.
Market Dynamics
AI-integrated diagnostic protocols are compressing scanner replacement cycles across South Korean tertiary hospitals, forcing equipment vendors to restructure service contracts around algorithm performance guarantees rather than hardware uptime alone.
Growth Catalysts
- Aging Demographics:South Korea's super-aged society status by 2025 drives demand for oncology and cardiovascular imaging. Tertiary hospitals in Seoul expand MRI fleets to manage rising cancer caseloads.
- MFDS Accelerated Pathways:The Ministry of Food and Drug Safety streamlines registration for AI-assisted diagnostic devices. Reduced clinical evidence timelines compress product launch windows for software-embedded scanners.
- Digital Retrofit Kits:Analog X-ray systems across provincial clinics upgrade via detector replacement modules. Lower capital barriers extend equipment lifespans while preserving imaging workflow continuity.
Market Restraints
- Helium Supply Concentration:MRI magnet cooling depends on helium imports from Qatar and the United States. Price volatility and export quota restrictions constrain 3.0 Tesla scanner deployment timelines.
- Reimbursement Compression:National Health Insurance Service rate freezes on standard CT and MRI reads limit hospital capital recovery periods. Equipment ROI calculations extend beyond typical depreciation schedules.
- Technical Obsolescence Risk:Rapid AI algorithm iteration threatens hardware-locked diagnostic platforms. Purchasers delay commitments pending clarity on cloud-based versus edge-computing architectures.
Strategic Opportunities
- Gwangju-Daejeon Corridor:Secondary cities outside Seoul's saturated cluster show underpenetrated point-of-care ultrasound demand. Portable digital platforms target emergency medicine networks in these regions.
- Hybrid Imaging Reimbursement:Pending NHIS category expansions for PET-CT and PET-MRI fusion procedures create first-mover advantages. Early adopters secure preferred provider status for oncology staging protocols.
- 5G-Enabled Teleradiology:Convergence of low-latency networks and edge AI processing enables rural hospital access to Seoul-based specialist reads. Equipment vendors bundle connectivity infrastructure with scanner sales.
Industry Challenges
- Radiologist Workforce Constraints:Training pipeline bottlenecks limit specialist availability for AI validation and oversight. Hospitals compete for board-certified professionals capable of supervising automated diagnostic outputs.
- Legacy PACS Integration:New scanner installations require middleware adaptation to decade-old picture archiving systems. DICOM compatibility gaps delay go-live dates and inflate implementation costs.
- Cybersecurity Certification Burden:MFDS medical device software security guidelines demand extensive penetration testing. Smaller manufacturers lack in-house capabilities to navigate documentation requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South Korea Diagnostic Imaging Equipment Market |
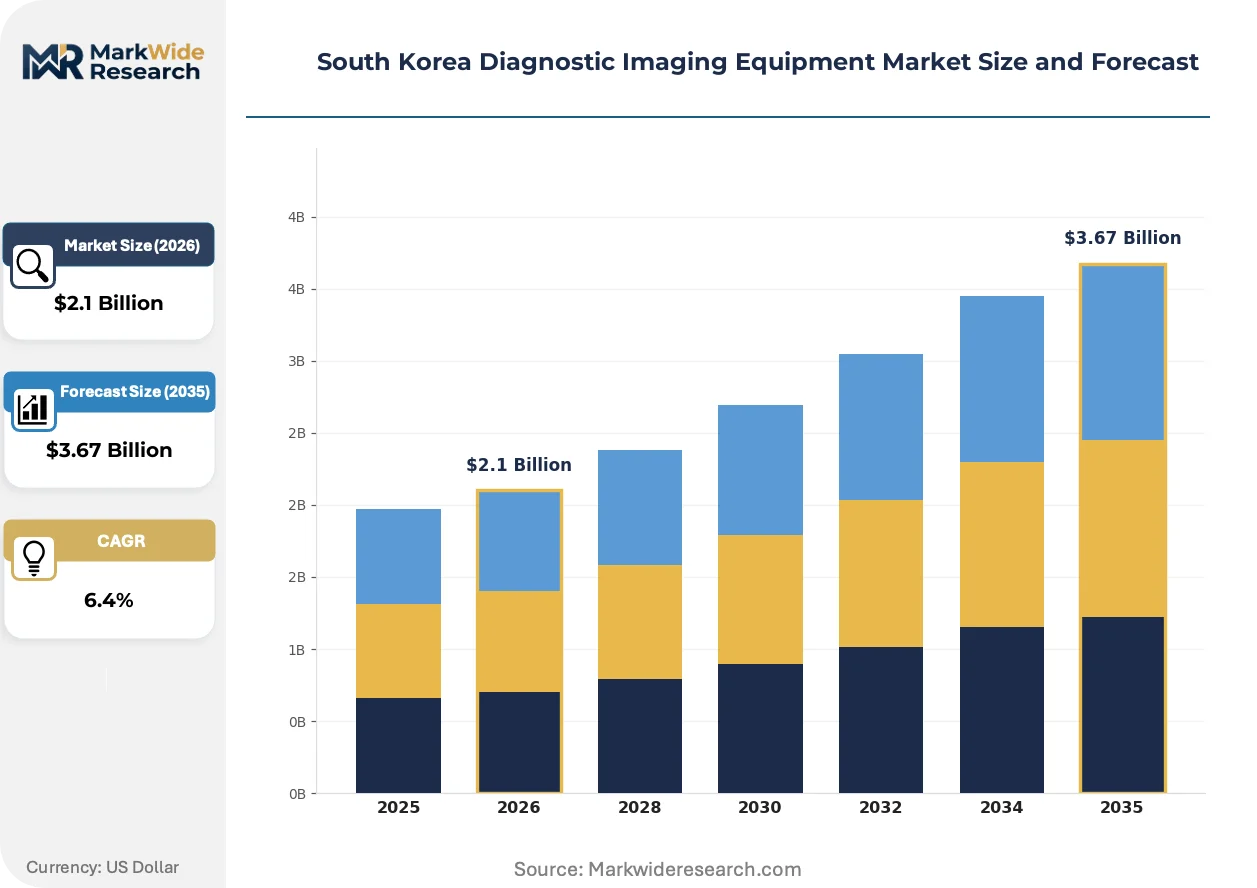
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $3.67 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: X-ray, MRI, CT Scanner, Ultrasound Technology: Digital, Analog, Hybrid, Advanced Imaging End User: Hospitals, Clinics, Diagnostic Centers, Research Labs Application: Oncology, Cardiology, Neurology, Orthopedics |
| Companies Covered | GE Healthcare, Siemens Healthineers, Koninklijke Philips, Canon, FUJIFILM, Samsung Healthcare, Shimadzu Medical, Esaote SpA, SG HealthCare, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South Korea Diagnostic Imaging Equipment Market Evolving Landscape
Photon-counting CT detector technology is absorbing development resources across major modality suppliers, restructuring competitive positioning around spectral imaging capabilities rather than rotational speed alone.
Semiconductor-based photon-counting detectors are absorbing the functional role of conventional energy-integrating scintillators in premium CT installations. Samsung Healthcare and Siemens Healthineers deploy these systems in cardiac and perfusion imaging suites at Seoul National University Hospital and Asan Medical Center. The technology is absorbing margin from conventional scanner lines as purchasers prioritize material decomposition accuracy for coronary plaque characterization.
MFDS post-market surveillance requirements for AI-embedded diagnostic software mandate real-world performance reporting every two years. Device manufacturers must establish domestic adverse event monitoring infrastructure or contract with authorized Korean representatives. Radiology departments at Severance Hospital and Samsung Medical Center face documentation burdens for algorithm-assisted reads, slowing procurement of non-validated platforms.
Consolidated purchasing through hospital group procurement organizations concentrates scanner acquisition decisions. The Catholic Medical Center and Ajou University Hospital networks centralize modality selection authority, displacing individual department preferences with enterprise-wide standardization mandates. Gyeonggi province teaching hospitals exhibit the strongest GPO leverage, extracting extended warranty terms and training commitments from vendors.
South Korea Diagnostic Imaging Equipment Market Segmentation
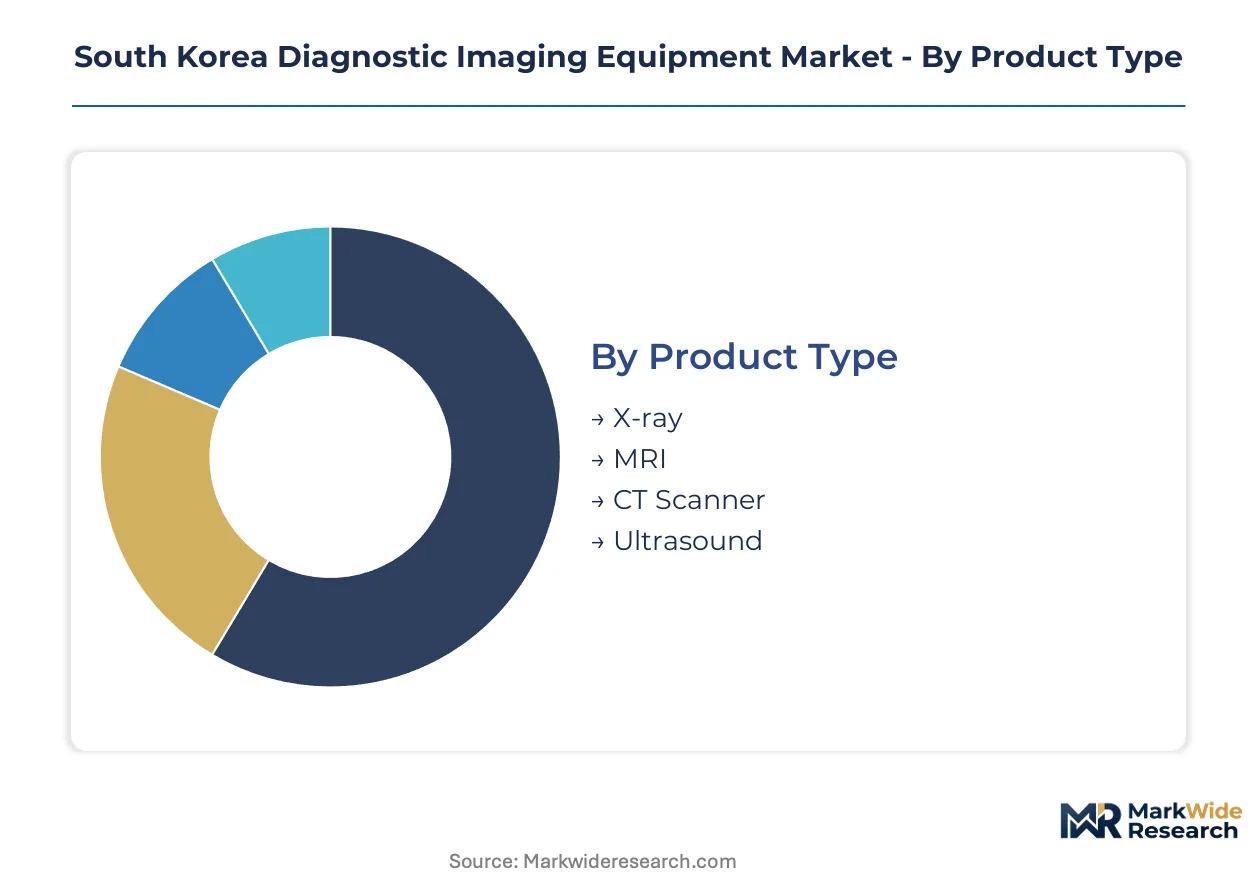
Diagnostic imaging equipment in South Korea fragments across four distinct dimensions that govern procurement patterns and vendor positioning. Product type and technology tiers determine capital intensity and replacement cycles, while end-user scale and clinical application shape feature requirements and reimbursement pathways.
Product Type:
Supply concentration for finished systems clusters around Seoul-Gyeonggi corridor manufacturing facilities and import distribution hubs.
- CT Scanner:Rotating X-ray tube assemblies with 0.25-0.35 second revolution speeds generate cross-sectional anatomical datasets. Tertiary hospitals in Seoul prioritize photon-counting detector configurations for cardiac perfusion protocols despite helium supply constraints on 3.0 Tesla companion installations.
- MRI:Superconducting magnet systems operating at 1.5 to 3.0 Tesla field strengths produce high-contrast soft tissue visualizations. Asan Medical Center and Samsung Medical Center anchor national demand for advanced neurovascular and cardiac imaging platforms.
- X-ray:Fixed and mobile radiography systems retain the largest installed base across South Korean healthcare networks.
- Ultrasound:Cart-based and portable platforms serve point-of-care emergency medicine and obstetric applications.
CT scanner and MRI systems absorb the bulk of installed capacity; ultrasound is expanding most quickly through portable digital platforms.
Technology:
Cost tier stratification separates premium installations at national university hospitals from economy configurations serving provincial clinics.
- Digital:Solid-state detector arrays and software-reconstructible raw data formats enable dose reduction and workflow automation. Seoul National University Hospital and Severance Hospital drive specification requirements for fully digital acquisition chains.
- Advanced Imaging:AI-embedded reconstruction algorithms and spectral decomposition capabilities command capital premiums. MFDS accelerated registration pathways compress launch timelines for software-integrated modalities at leading tertiary centers.
- Hybrid:Dual-modality fusion systems combining functional and anatomical imaging.
- Analog:Legacy film-based and CR cassette systems persist in cost-constrained rural facilities.
Digital platforms absorb the bulk of installed capacity; advanced imaging configurations are gaining share fastest through replacement cycles at major hospitals.
End User:
Customer type determines service contract structures and training commitment intensity from equipment vendors.
- Hospitals:Multi-modality imaging departments with 24-hour operational requirements and dedicated radiology residency programs. Catholic Medical Center and Ajou University Hospital networks leverage consolidated purchasing to extract extended warranty terms.
- Diagnostic Centers:Specialized outpatient facilities focused on high-volume screening and elective procedures.
- Clinics:Primary care and specialty practices with limited capital budgets and space constraints.
- Research Labs:Academic and pharmaceutical imaging facilities requiring preclinical and experimental protocol support.
Hospitals absorb the bulk of installed capacity; diagnostic centers are climbing the fastest as outpatient imaging migrates from inpatient settings.
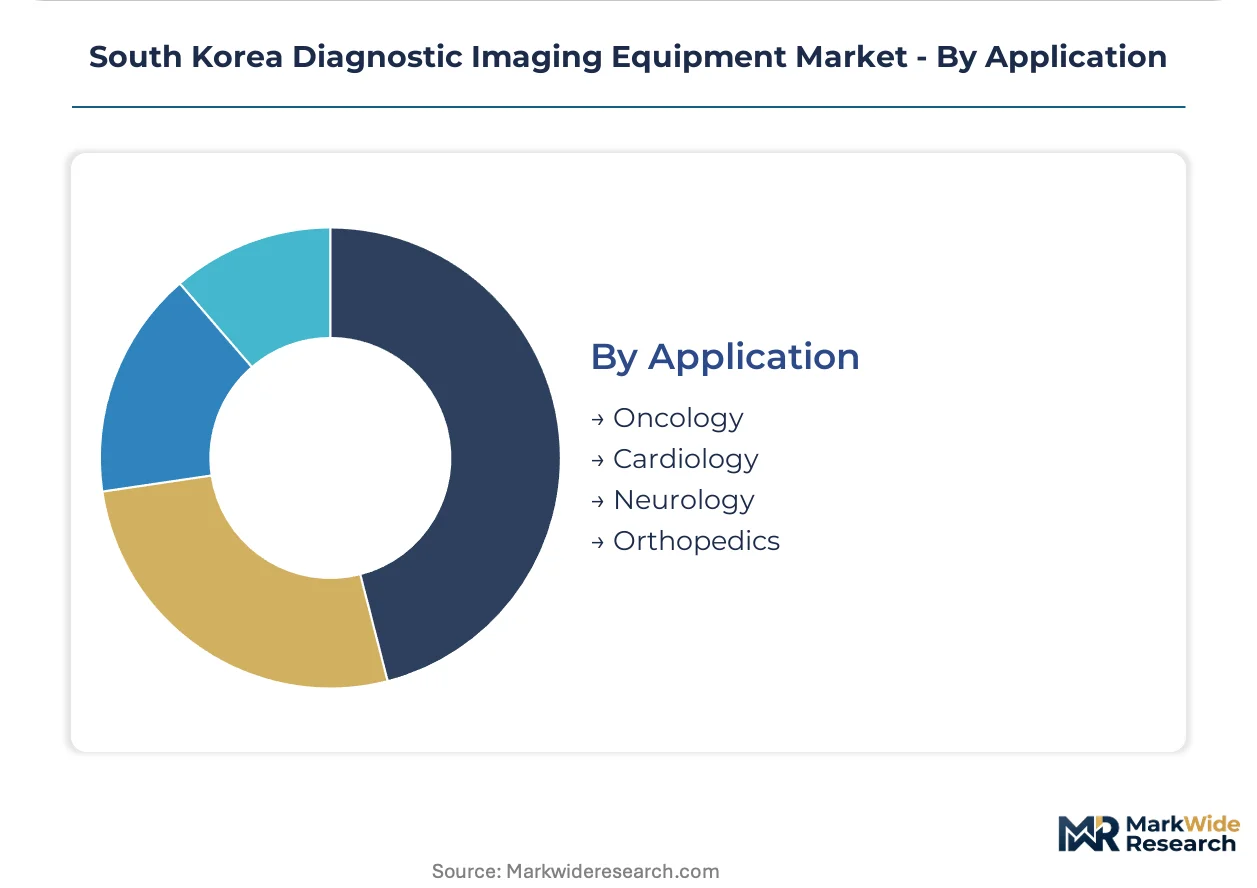
Application:
Clinical use case drives specification requirements and determines reimbursement category eligibility under National Health Insurance Service schedules.
- Oncology:Staging and treatment response monitoring protocols demand multi-parametric MRI and PET-CT fusion capabilities. Major hospitals expand scanner fleets specifically to manage rising cancer caseloads in South Korea's super-aged demographic profile.
- Cardiology:Coronary CT angiography and cardiac MRI applications require sub-millisecond temporal resolution and advanced gating technologies.
- Neurology:Functional MRI and diffusion tensor imaging for stroke and neurodegenerative disease assessment.
- Orthopedics:Musculoskeletal MRI and weight-bearing CT for surgical planning and post-operative evaluation.
Oncology applications absorb the bulk of installed capacity; cardiology is expanding most quickly through photon-counting CT deployments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Seoul Capital Area concentrates diagnostic imaging procurement authority through tertiary hospital networks and consolidated purchasing organizations. This metropolitan cluster shapes national equipment specifications and reimbursement benchmarks that cascade to provincial facilities.
Seoul Capital Area
Asan Medical Center and Samsung Medical Center anchor demand for 3.0 Tesla MRI and photon-counting CT platforms. MFDS accelerated registration pathways for AI-embedded devices compress procurement cycles at these flagship institutions. Gyeonggi province teaching hospitals extract extended warranty terms through group purchasing organization leverage.
Busan-Ulsan
Port-city logistics infrastructure supports import distribution for CT detector assemblies and MRI magnet components. Regional cancer centers expand PET-CT fleets to manage oncology caseloads from surrounding Gyeongsang provinces. Ulsan University Hospital anchors specialized cardiac imaging capacity for the southeastern industrial corridor.
Daegu-Gyeongbuk
Secondary-city hospitals face radiologist workforce constraints that accelerate teleradiology partnerships with Seoul-based specialists. Provincial clinics deploy portable ultrasound platforms for emergency medicine networks. Kyungpook National University Hospital maintains the region's only advanced neurovascular MRI suite.
Daejeon-Sejong
Government research complexes drive preclinical imaging demand for pharmaceutical development protocols. Korea Institute of Science and Technology facilities anchor experimental MRI and hybrid imaging research. Sejong administrative city hospitals serve as pilot sites for NHIS reimbursement category expansions.
Gwangju-Honam
Underpenetrated point-of-care ultrasound demand creates opportunities for portable digital platform vendors. Chonnam National University Hospital anchors the southwestern region's oncology imaging capacity. Rural clinic networks seek 5G-enabled connectivity bundles for remote specialist consultation access.
South Korea Diagnostic Imaging Equipment Market Competitive Landscape
Premium-margin players sit above commodity-margin players across the technology-integration spectrum, with AI-embedded systems commanding capital premiums over conventional hardware configurations. The vendor base stratifies between full-modality conglomerates, regional specialists, and semiconductor-heritage integrators. Two dominant competitive moves reshape positioning: service contract restructuring around algorithm performance guarantees, and consolidated purchasing organization engagement to secure multi-hospital network agreements.
Among diversified healthcare conglomerates, GE Healthcare, Siemens Healthineers, and Samsung Healthcare occupy positions across the premium-tier vector. GE Healthcare exemplifies the installed-base defense archetype through long-term service contract structures. Siemens Healthineers represents the advanced imaging specialization pattern with embedded clinical decision support platforms. Samsung Healthcare anchors the semiconductor-heritage integration model, leveraging domestic component supply chains for CT and ultrasound production.
| Leading Market Players |
|---|
| GE Healthcare |
| Siemens Healthineers |
| Koninklijke Philips |
| Canon |
| FUJIFILM |
| Samsung Healthcare |
| Shimadzu Medical |
| Esaote SpA |
| SG HealthCare |
| Others |
Value Network & Pricing Analysis
Captive helium supply contracts and in-house magnet production at Siemens Healthineers and GE Healthcare anchor premium-tier pricing power while insulating against Qatar export quota volatility. This vertical integration pattern concentrates margin defense among full-modality conglomerates and forces mid-tier vendors toward detector outsourcing partnerships.
Pricing Analysis
Throughput-guaranteed service contracts anchor pricing for AI-embedded CT and MRI platforms at Seoul National University Hospital and Asan Medical Center. Three-tier pricing structure across premium, standard, and economy levels separates photon-counting configurations from digital retrofit kits and legacy analog systems. Cost compression in economy-tier X-ray segments is intensifying because provincial clinics extend replacement intervals via detector upgrade modules. Diagnostic centers show highest price sensitivity due to NHIS reimbursement rate freezes, while tertiary hospitals absorb premium premiums for algorithm-validated platforms.
Supply Chain Analysis
Specialized cryogenic engineering talent shortages in South Korea and Germany constrain superconducting magnet production timelines for 3.0 Tesla MRI systems. Component sourcing draws from Japan for gradient coil assemblies, the United States for helium recovery systems, and domestic Samsung semiconductor foundries for detector substrates. Single-source vulnerability sits with Qatar helium exports feeding magnet cooling requirements. Distribution runs through Seoul-Gyeonggi corridor warehousing with direct-to-hospital installation teams.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is a vertical-integration race. Players are pursuing upstream control over photon-counting detector semiconductor fabrication to escape margin compression in conventional scanner lines.
For Market Incumbents: Lock in radiologist workforce pipelines through endowed chair partnerships at Korea University and Yonsei University to defend against AI validation bottlenecks. Secure captive helium supply contracts or invest in closed-loop magnet cooling systems to neutralize Qatar export quota exposure. Consolidate GPO relationships with Catholic Medical Center and Ajou University Hospital networks through algorithm performance guarantees embedded in long-term service agreements. For New Entrants and Emerging Players: Capture point-of-care ultrasound demand in the Gwangju-Daejeon corridor where portable digital platforms displace aging cart-based units. Target 5G-enabled teleradiology infrastructure bundles for rural Honam region clinics seeking Seoul-based specialist connectivity. Pursue MFDS accelerated registration pathways for AI-assisted diagnostic software to compress launch timelines against hardware-locked competitors. For Investors and Strategic Acquirers: Exit pathways concentrate in semiconductor-heritage integrators with captive detector production and established MFDS compliance infrastructure. Long-term viability favors vendors with backward integration into photon-counting sensor fabrication rather than software-only AI plays. Watch for NHIS reimbursement category expansions for PET-CT and PET-MRI fusion procedures as inflection signal for hybrid imaging platform demand.| Strategic Initiative | Industry Significance |
|---|---|
| MFDS Accelerated Registration Pathway | Compresses product launch timelines for AI-embedded scanners at Seoul tertiary hospitals. |
| Helium Supply Contract Securement | Insulates 3.0 Tesla MRI production against Qatar export quota volatility. |
| GPO Network Partnership | Catholic Medical Center leverage extracts extended warranty terms from equipment vendors. |
| Photon-Counting Detector Integration | Samsung semiconductor heritage enables domestic production of premium CT configurations. |
| 5G Teleradiology Infrastructure Bundle | Rural Gwangju-Honam clinics gain Seoul specialist access via connectivity-embedded scanner sales. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this study. Primary interviews with hospital purchasing committee members, biomedical engineers, GPO contracts managers, and MFDS regulatory affairs specialists combined with MFDS device registration databases, NHIS reimbursement schedules, and Korea Medical Device Industry Association reports. Bottom-up installation base modeling and top-down healthcare expenditure triangulation validated market sizing across the analysis window.
Product-type granularity modeled CT scanner, MRI, X-ray, and ultrasound segments separately with technology-tier splits across digital, advanced imaging, hybrid, and analog configurations. End-user segmentation distinguished hospitals, diagnostic centers, clinics, and research labs with application-specific modeling for oncology, cardiology, neurology, and orthopedics. CAGRs derived from replacement cycle analysis, reimbursement trajectory assessment, and AI adoption curve modeling. Forecast inputs incorporated helium supply elasticity, radiologist workforce pipeline constraints, and 5G infrastructure rollout timelines.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to NHIS reimbursement category decisions and MFDS AI software security guideline evolution. Forecasts reflect documented assumptions around tertiary hospital capital expenditure continuity and semiconductor supply chain stability. Material deviation in helium export quota policy or MFDS post-market surveillance enforcement intensity warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Imaging
US Medical Imaging Market
Medical Imaging
Panoramic and Cephalometric Radiography Systems Market
Medical Imaging
Mexico Mammography Market
Medical Imaging
Argentina Nuclear Imaging Market
Medical Imaging
Cranial Doppler Market
Medical Imaging
Mexico Digital X-Ray Devices Market
Medical Imaging
Point-Of-Care Medical Imaging Market
Medical Imaging
Meningitis Imaging Market
Medical Imaging
Global Single-Photon Emission Computed Tomography (SPECT) Market
Medical Imaging
Brazil Magnetic Resonance Imaging (MRI) Market
Medical Imaging
Saudi Arabia Digital Radiology Market
Medical Imaging
Global Contrast-Enhanced Ultrasound Market
Medical Imaging
Europe Diagnostic Imaging Equipment Market
Medical Imaging
Digital Radiology Market
Medical Imaging
Echocardiography Market
Medical Imaging
Global Colposcopy Market