
 Medical Radiation Detection Market | 2026-2036
Medical Radiation Detection Market Size, Share, and Industry Trends Forecast 2026-2036
Medical Radiation Detection Market Analysis
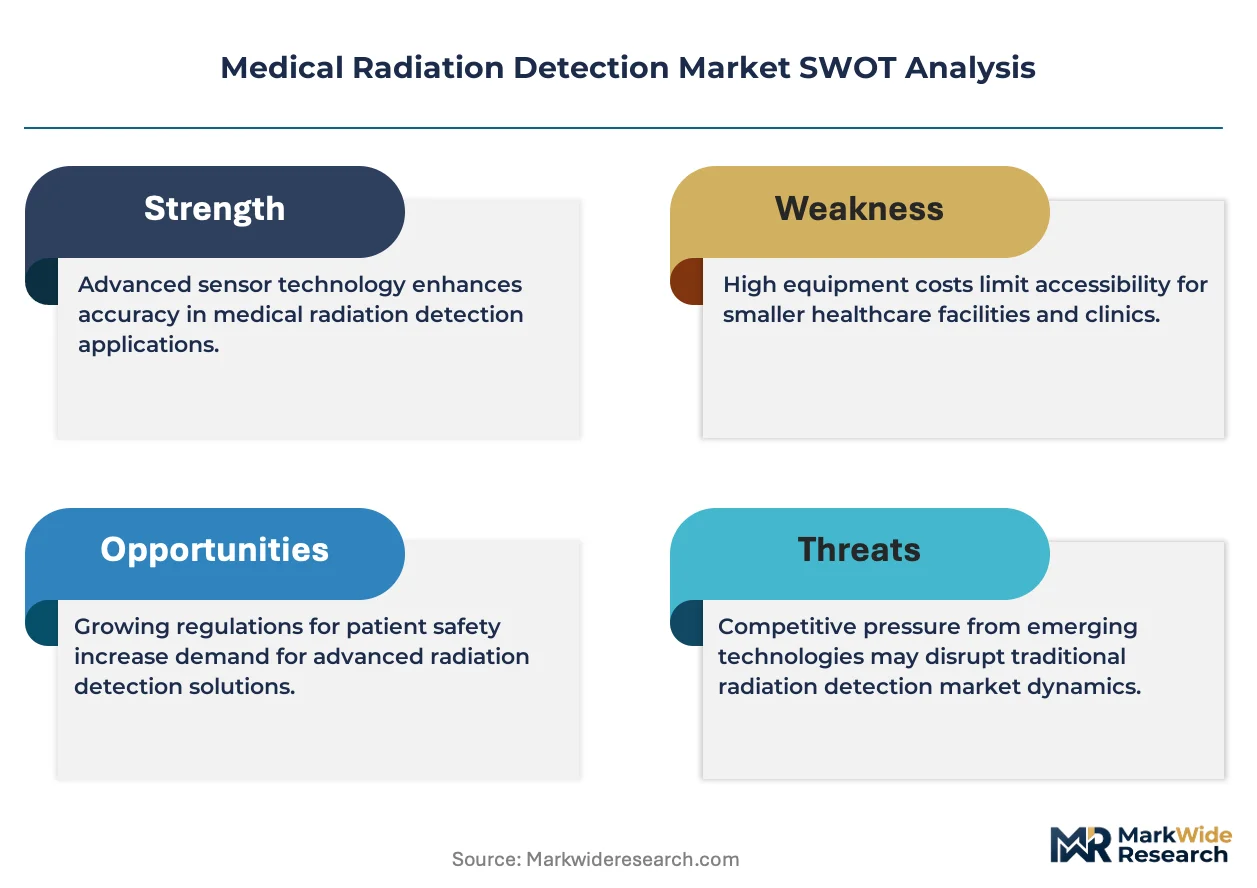
Certified health physicist shortages across developed markets is reorganizing how hospitals and clinics procure radiation monitoring services. Thermo Fisher Scientific leverages its diagnostic equipment distribution network to bundle detection hardware with service contracts. Mirion Technologies sustains dominance in nuclear medicine through captive manufacturing of scintillation crystals. PTW Freiburg GmbH specializes in ionization chamber calibration protocols that anchor its position in European radiotherapy centers.
Medical radiation detection encompasses instruments that quantify ionizing radiation exposure in clinical settings, typically employing gas-filled, scintillating, or solid-state sensors capable of resolving dose rates from microsieverts to grays for patient and personnel safety. Semiconductor detectors now capture the fastest expansion as silicon photomultipliers and cadmium zinc telluride crystals displace legacy analog systems in precision radiotherapy. Scintillation detectors retain the largest installed base across diagnostic imaging suites where cost sensitivity favors sodium iodide and plastic phosphor technologies. Digital detection architectures are displacing analog platforms in new hospital construction, creating margin concentration for vendors with integrated software-hardware offerings.
The FDA enforces 21 CFR Subpart K personnel monitoring requirements while the EMA coordinates with national regulators to implement the EU Medical Device Regulation dosimetry standards, collectively elevating product certification barriers for market entry. ISO 4037 calibration protocols and IEC 60846 performance specifications further constrain supplier qualification timelines. Stakeholders must monitor how AI-integrated spectral analysis reshapes procurement criteria for next-generation detection platforms.
Market Dynamics
The transition from analog to digital detection architectures is compressing vendor margins while elevating certification barriers, forcing established suppliers to restructure service offerings around integrated software-hardware bundles.
Growth Catalysts
- EU Medical Device Regulation dosimetry standards:The EMA-coordinated framework mandates continuous personnel monitoring in radiotherapy suites, expanding replacement cycles for legacy equipment across European hospital networks.
- Silicon photomultiplier arrays:These solid-state sensors enable sub-millimeter spatial resolution in proton therapy beam profiling, driving semiconductor detector procurement in precision radiotherapy centers.
- Hospital network consolidation:Multi-site health systems in the United States are centralizing radiation safety programs, creating volume procurement contracts that favor vendors with national service infrastructure.
Market Restraints
- Scintillation crystal supply concentration:Sodium iodide and lutetium oxyorthosilicate production clusters in Japan and China, exposing detector manufacturers to single-source fragility and shipping cost volatility.
- IEC 60846 compliance timelines:Performance verification protocols for active personal dosimeters extend product launch schedules by 14-18 months, delaying revenue recognition for new entrants.
- Certified health physicist scarcity:The pipeline of qualified radiation safety officers cannot match hospital expansion rates, forcing clinics to outsource monitoring services at premium rates.
Strategic Opportunities
- AI-integrated spectral analysis:Machine learning algorithms for real-time isotope identification in nuclear medicine departments create differentiation for vendors with embedded software capabilities.
- India's diagnostic imaging expansion:Government-funded cancer hospital construction under the National Health Mission generates first-time demand for portal monitors and area dosimeters in tier-2 cities.
- Subscription-based calibration services:Remote ionization chamber verification via cloud-connected reference sources locks in recurring revenue and reduces customer switching.
Industry Challenges
- Legacy analog system integration:Hybrid environments in renovated European radiotherapy centers require custom firmware bridges, inflating deployment costs and technical support burdens.
- ISO 4037 calibration capacity:Reference laboratory bottlenecks in secondary standard dosimetry extend lead times for detector commissioning, frustrating hospital construction schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Medical Radiation Detection Market |
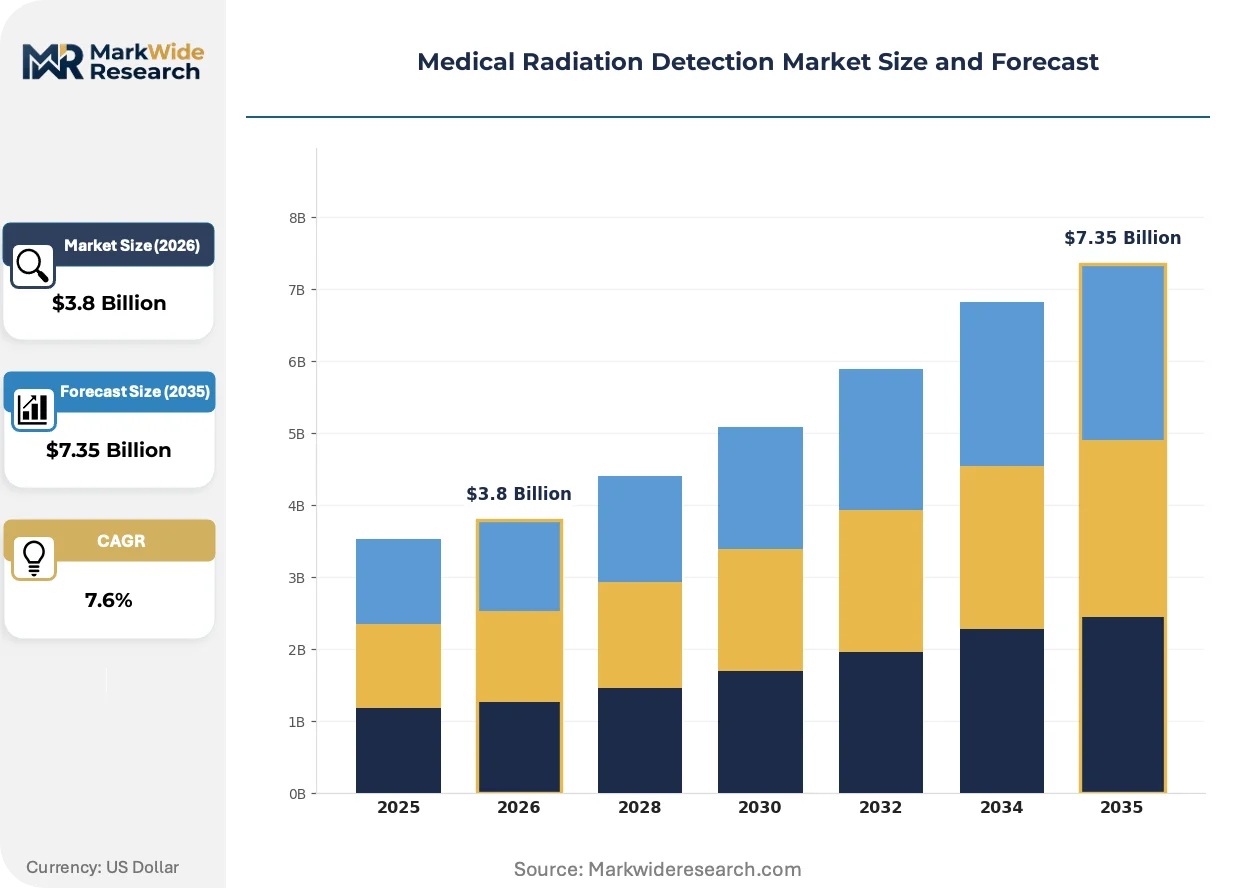
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $7.35 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Geiger-Muller Counters, Ionization Chambers, Scintillation Detectors, Semiconductor Detectors Application: Radiotherapy, Diagnostic Imaging, Nuclear Medicine, Radiation Safety End User: Hospitals, Clinics, Research Laboratories, Nuclear Facilities Technology: Analog Detection, Digital Detection, Spectroscopic Detection, Mobile Detection |
| Companies Covered | Thermo Fisher Scientific, Inc., Mirion Technologies, Inc., Fortive Corporation, IBA Dosimetry GmbH, LANDAUER, UAB Polimaster Europe, PTW Freiburg GmbH, ATOMTEX, Radiation Detection Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Medical Radiation Detection Market Emerging Trajectories
Detection technology is bifurcating between high-precision semiconductor platforms for radiotherapy and cost-optimized scintillation systems for diagnostic imaging, with software integration becoming the primary vendor battleground.
Cadmium zinc telluride direct-conversion detectors are displacing legacy analog pulse-height analyzers in stereotactic radiosurgery applications. Academic medical centers in Germany and the United States are adopting these crystals for real-time beam monitoring. The shift is compressing demand for traditional photomultiplier tubes while elevating software requirements for spectral deconvolution.
The FDA's 21 CFR Subpart K enforcement emphasis on electronic personnel monitoring is accelerating digital dosimeter deployment in interventional cardiology suites. Compliance officers now require automated dose registry integration, forcing vendors to develop HL7-compatible data architectures. Cardiac catheterization labs in the United States face the steepest adaptation curves.
Equipment procurement through consolidated group purchasing organizations is displacing direct manufacturer relationships at independent imaging centers. Hospital networks now negotiate enterprise-wide radiation safety contracts spanning detection hardware, calibration services, and physicist staffing. This concentration is most pronounced in the United States, where three purchasing alliances control majority outpatient imaging volume.
Medical Radiation Detection Market Segmentation
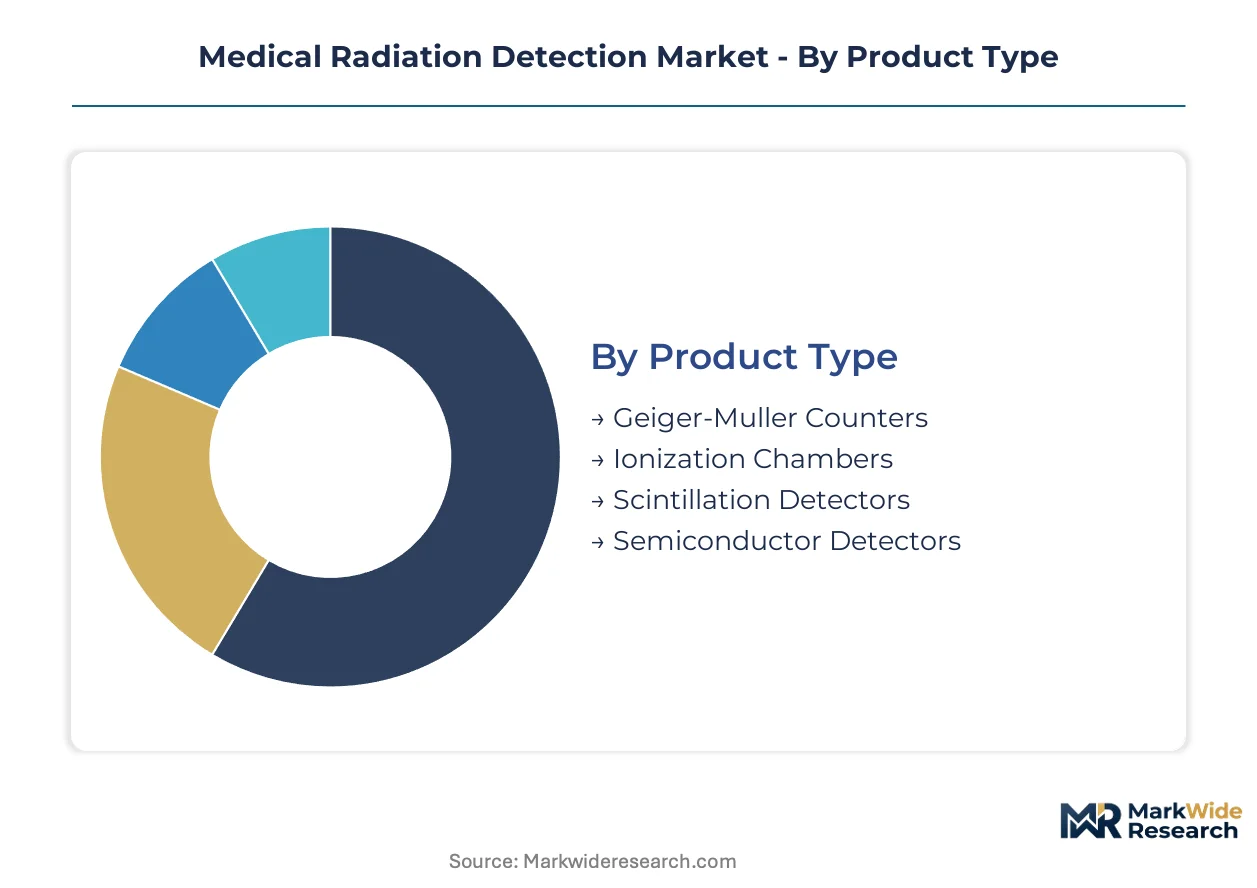
Technology heterogeneity across medical radiation detection creates distinct margin architectures. Product categories, application settings, and end-user procurement patterns each impose unique certification burdens and service requirements that reshape vendor profitability.
Product Type:
Margin concentration pools in semiconductor and scintillation platforms where calibration complexity and crystal sourcing create defendable positions.
- Semiconductor Detectors:Cadmium zinc telluride and silicon photomultiplier arrays enable direct-conversion dosimetry with sub-millimeter spatial resolution. German radiotherapy centers and United States academic medical centers drive procurement for real-time beam monitoring in proton therapy suites.
- Scintillation Detectors:Sodium iodide and plastic phosphor technologies dominate diagnostic imaging installations where cost sensitivity constrains capital budgets. Sodium iodide crystal supply clusters in Japan and China, exposing manufacturers to shipping cost volatility and single-source fragility.
- Ionization Chambers:PTW Freiburg GmbH anchors European market share through captive calibration protocol expertise, with Freiburg reference laboratories setting secondary standard dosimetry benchmarks.
- Geiger-Muller Counters:Legacy gas-filled tubes retain presence in personnel portal monitoring and routine contamination surveys where durability outweighs precision requirements.
Scintillation detectors hold installed capacity. Semiconductor detectors are rotating up the share rankings.
Application:
Procurement intensity varies sharply across clinical settings, with radiotherapy commanding premium pricing for beam profiling precision and nuclear medicine requiring isotope-specific spectral resolution.
- Radiotherapy:Stereotactic radiosurgery and proton therapy demand real-time dose verification with microgray sensitivity. United States hospital networks centralize procurement through enterprise contracts spanning hardware, software, and physicist staffing.
- Nuclear Medicine:Gamma camera calibration and radiopharmaceutical dose preparation require multi-isotope identification capabilities. AI-integrated spectral analysis is displacing legacy pulse-height analyzers in departments handling technetium-99m and fluorine-18 tracers.
- Diagnostic Imaging:CT dose index monitoring and fluoroscopy tracking drive volume demand for area dosimeters. Interventional cardiology suites in the United States face steep FDA 21 CFR Subpart K compliance curves for electronic personnel monitoring.
- Radiation Safety:Personnel dosimetry and environmental monitoring programs span hospital networks, with certified health physicist scarcity forcing clinics toward outsourced service models at premium rates.
Radiotherapy commands pricing premiums. Nuclear medicine is climbing fastest on AI-integrated platform demand.
End User:
Customer concentration patterns concentrate procurement leverage in hospital networks while fragmenting demand across independent clinics and research sites.
- Hospitals:Multi-site health systems in the United States negotiate consolidated radiation safety contracts through group purchasing organizations, displacing direct manufacturer relationships.
- Clinics:Independent imaging centers face capital constraints favoring scintillation-based systems over semiconductor platforms, with equipment procurement increasingly channeled through purchasing alliances.
- Research Laboratories:Academic medical centers in Germany and the United States drive early adoption of cadmium zinc telluride direct-conversion detectors for experimental beam profiling.
- Nuclear Facilities:Cyclotron installations and radiopharmaceutical production sites require specialized area monitoring with isotope-specific alarm thresholds.
Hospitals concentrate procurement volume. Research laboratories are rotating up the share rankings on precision radiotherapy investment.
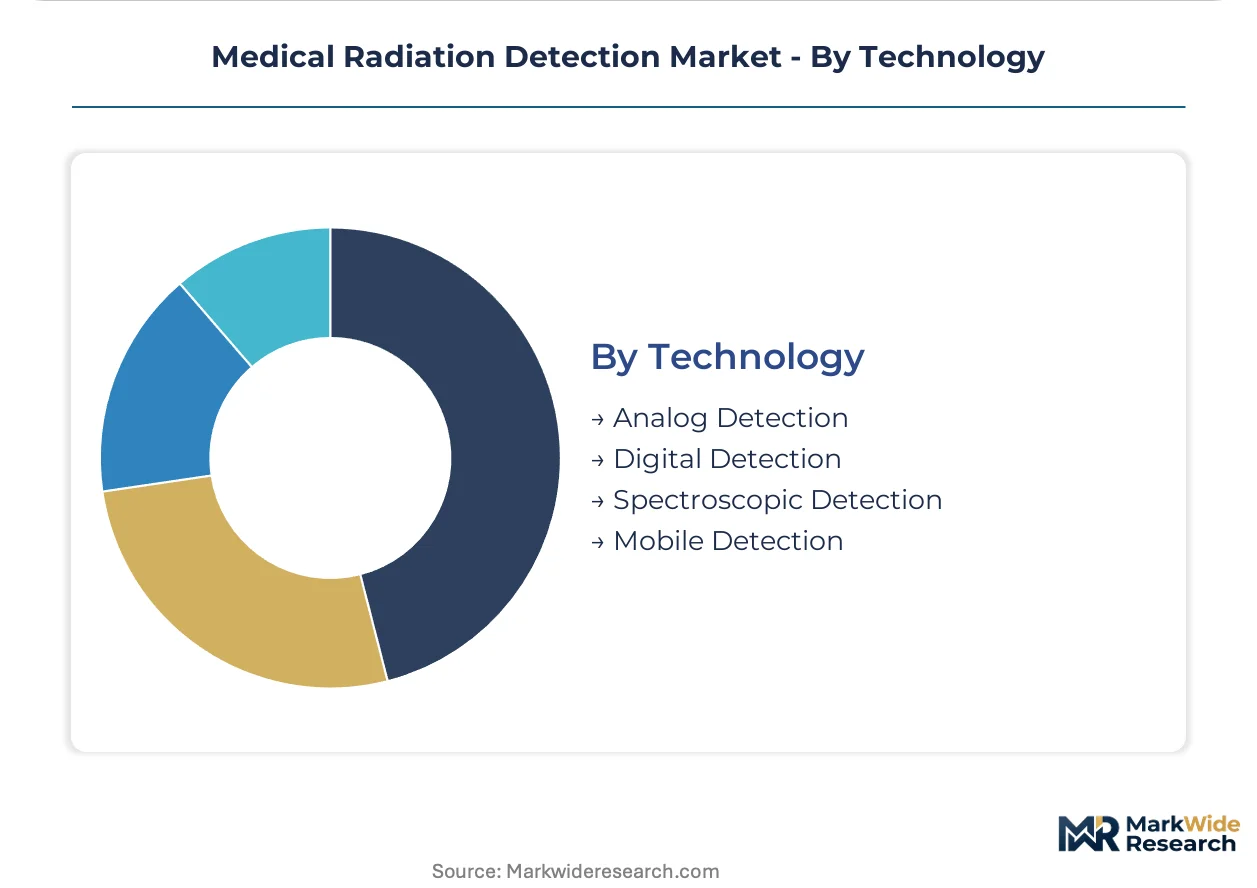
Technology:
Architecture transitions from analog to digital platforms are compressing legacy margins while elevating software integration requirements as the primary vendor battleground.
- Digital Detection:Solid-state sensors with embedded microprocessors enable automated dose registry integration and HL7-compatible data architectures. New hospital construction in North America and Europe specifies digital-native platforms exclusively.
- Spectroscopic Detection:Multi-channel analyzers with machine learning isotope identification create differentiation for vendors serving nuclear medicine departments with mixed-radionuclide environments.
- Mobile Detection:Wearable personal dosimeters and wireless area monitors support flexible deployment in hybrid clinical environments, though IEC 60846 compliance timelines extend product launch schedules.
- Analog Detection:Legacy pulse-height analyzers and gas-filled systems retain presence in renovated European radiotherapy centers requiring custom firmware bridges for hybrid installations.
Digital detection holds installed capacity. Spectroscopic detection is gaining share fastest on AI-embedded platform demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospital networks in the United States and Germany deploy precision semiconductor arrays for proton therapy beam profiling, while diagnostic imaging centers in India and Brazil prioritize cost-optimized scintillation systems for gamma camera calibration.
United States
FDA enforcement of 21 CFR Subpart K personnel monitoring requirements accelerates digital dosimeter deployment in interventional cardiology suites. Hospital network consolidation through group purchasing organizations concentrates procurement leverage for enterprise-wide radiation safety contracts. Academic medical centers in Boston and Houston drive early adoption of cadmium zinc telluride direct-conversion detectors for stereotactic radiosurgery applications.
Germany
EMA-coordinated EU Medical Device Regulation dosimetry standards mandate continuous personnel monitoring in radiotherapy suites, expanding replacement cycles for legacy equipment. PTW Freiburg GmbH anchors European market position through captive calibration protocol expertise at Freiburg reference laboratories. Precision radiotherapy investment concentrates in Bavaria and Baden-Württemberg, where university hospitals adopt silicon photomultiplier arrays for real-time beam monitoring.
India
Government-funded cancer hospital construction under the National Health Mission generates first-time demand for portal monitors and area dosimeters in tier-2 cities. CDSCO medical device registration requirements extend product qualification timelines for foreign detector manufacturers. Diagnostic imaging expansion concentrates in Maharashtra and Karnataka, where private hospital chains install scintillation-based gamma cameras for nuclear medicine departments.
Japan
PMDA quality management system inspections for active personal dosimeters elevate certification barriers for market entry. Sodium iodide crystal production clusters expose detector manufacturers to single-source fragility and shipping cost volatility. Radiopharmaceutical production sites in Osaka and Tokyo require specialized area monitoring with isotope-specific alarm thresholds for fluorine-18 and technetium-99m tracers.
Brazil
ANVISA medical device registration pathways for radiation detection equipment create extended approval timelines for international suppliers. Independent imaging centers face capital constraints favoring scintillation-based systems over semiconductor platforms for gamma camera installations. Diagnostic imaging demand concentrates in São Paulo and Rio de Janeiro, where private clinic networks expand nuclear medicine capabilities for oncology diagnostics.
Medical Radiation Detection Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier, with diagnostic equipment distributors leveraging service infrastructure to bundle hardware contracts. The market structure concentrates around vendors with captive calibration expertise and crystal sourcing control. Three archetypes dominate: integrated diagnostics conglomerates with distribution networks, specialist dosimetry houses with reference laboratory assets, and regional fabricators with cost-optimized scintillation platforms. Competitive moves center on strategic partnerships for software integration and geographic expansion through local calibration service partnerships.
Among integrated diagnostics conglomerates, Thermo Fisher Scientific leverages its distribution network to bundle detection hardware with service contracts. Mirion Technologies occupies a position within the specialist tier, sustaining presence in nuclear medicine through captive manufacturing capabilities. PTW Freiburg GmbH anchors the European reference laboratory segment, with its Freiburg facilities setting secondary standard dosimetry benchmarks for ionization chamber calibration protocols.
| Leading Market Players |
|---|
| Thermo Fisher Scientific, Inc. |
| Mirion Technologies, Inc. |
| Fortive Corporation |
| IBA Dosimetry GmbH |
| LANDAUER |
| UAB Polimaster Europe |
| PTW Freiburg GmbH |
| ATOMTEX |
| Radiation Detection Company |
| Others |
Supply Flow & Price Mechanics
Capacity utilization at sodium iodide crystal foundries in Japan and China governs price floors for scintillation detector manufacturers, with idle capacity triggering aggressive spot pricing that cascades through diagnostic imaging procurement cycles. This scale-driven volatility concentrates margin pressure on vendors lacking captive crystal supply or long-term offtake agreements with Japanese refiners.
Pricing Analysis
Long-term service contracts with embedded hardware refresh cycles dominate hospital network procurement, displacing spot-market transactions. Price differentiation separates FDA 21 CFR Subpart K-certified digital dosimeters from uncertified analog alternatives, with certification tier and after-sales physicist staffing as primary drivers. Cost compression in scintillation-based systems is intensifying because group purchasing organizations consolidate volume across multi-site health systems. Independent imaging centers exhibit highest price sensitivity, while academic medical centers in Germany and the United States prioritize performance specifications over unit cost.
Supply Chain Analysis
Inventory buffers for cadmium zinc telluride crystals and silicon photomultiplier arrays stretch 14-18 months due to IEC 60846 compliance verification timelines, constraining just-in-time procurement. Production concentrates in Japan, China, and Germany, with sodium iodide crystal growth and semiconductor wafer fabrication as critical inputs. Single-source fragility in Japanese crystal supply exposes detector manufacturers to shipping cost volatility and geopolitical disruption. Distribution runs through diagnostic equipment distributors with captive service infrastructure, bundling hardware with calibration and physicist staffing contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Procurement leverage has shifted decisively toward hospital networks and group purchasing organizations, with three United States purchasing alliances now controlling majority outpatient imaging volume and dictating enterprise-wide radiation safety contract terms.
For Market Incumbents: Compound calibration protocol expertise into subscription-based revenue streams, locking hospital networks into recurring ionization chamber verification via cloud-connected reference sources. Deepen backward integration into scintillation crystal supply through long-term offtake agreements with Japanese refiners, defending against single-source fragility. Prioritize AI-embedded spectral analysis R&D to differentiate against emerging software-native entrants threatening nuclear medicine margins. For New Entrants and Emerging Players: Lead with software-first platforms targeting India's tier-2 city cancer hospitals under the National Health Mission, where first-time portal monitor demand outpaces established vendor service capacity. Capture white-space in subscription-based calibration services for clinics forced toward outsourced radiation safety officer models due to certified health physicist scarcity. Deploy direct sales teams to Maharashtra and Karnataka private hospital chains, bypassing distributor markups that inflate scintillation system landed costs. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among specialist dosimetry houses with captive reference laboratory assets, where calibration service contracts generate 60-70% lifetime value capture versus hardware-only vendors. Target acquisition archetypes combining semiconductor detector IP with embedded software capabilities for proton therapy beam profiling. Watch FDA enforcement intensity for 21 CFR Subpart K compliance as inflection indicator for digital dosimeter replacement cycle acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EMA-coordinated EU MDR dosimetry standards mandate continuous personnel monitoring, expanding replacement demand. |
| Hospital System Partnership | Enterprise-wide radiation safety contracts through GPOs displace direct manufacturer relationships at independent centers. |
| Software Companion Development | HL7-compatible data architectures enable automated dose registry integration for interventional cardiology compliance. |
| Backward Integration into Crystal Supply | Captive sodium iodide sourcing insulates against Japanese production cluster shipping cost volatility. |
| Reimbursement Strategy | CMS coding alignment for AI-integrated spectral analysis accelerates nuclear medicine department procurement cycles. |
Methodological Framework
The analysis maps semiconductor, scintillation, ionization chamber, and Geiger-Muller detector sub-sectors, each validated through health physicists, hospital purchasing committee members, biomedical engineers, and GPO contracts managers. Primary interview findings triangulate against FDA 21 CFR filings, EMA MDR guidance documents, ISO 4037 calibration records, and hospital procurement database extracts. Bottom-up unit economics for detector categories reconcile with top-down market sizing across the analysis window.
Consistency checks validate volume and value outputs against IEC 60846 performance specification adoption curves and proton therapy installation databases. Segmentation dimensions span product type, application setting, end-user archetype, and technology architecture, with CAGRs derived from replacement cycle analysis and regulatory mandate implementation timelines. Forecast inputs incorporate certified health physicist pipeline data and group purchasing organization contract renewal schedules.
The analysis sits within stated boundaries; outcomes outside sustained FDA and EMA enforcement intensity or stable Japanese crystal supply conditions would require recalibration. Forecasts reflect documented assumptions regarding hospital network consolidation velocity and semiconductor detector cost curves. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Imaging
Netherlands Diagnostic Imaging Equipment Market
Medical Imaging
US Magnetic Resonance Imaging Market
Medical Imaging
Global Magnetic Resonance Imaging System Market
Medical Imaging
Ultrasound Elastography Systems Market
Medical Imaging
Mexico Digital Radiology Market
Medical Imaging
Medical Imaging Outsourcing Market
Medical Imaging
Fluoroscopy Devices Market
Medical Imaging
Global Contrast Enhanced Digital Mammography (CEDM) Market
Medical Imaging
Spain Digital X-Ray Market
Medical Imaging
Medical Digital Imaging Systems Market
Medical Imaging
Medical Digital Imaging Devices Market
Medical Imaging
Fluorescein Angiography Market
Medical Imaging
Echocardiography Market
Medical Imaging
Radiography-Fluoroscopy Combo System Market
Medical Imaging
Orthopedic Imaging Market
Medical Imaging
Germany Digital Radiology Market