
 Face Smart Lockers Market | 2026-2036
Face Smart Lockers Market Size, Share, and Industry Trends Forecast 2026-2036
Face Smart Lockers Market Insights
China is tilting toward large-scale smart locker deployment across its logistics corridors and transit hubs. Quadient leverages its European manufacturing footprint to sustain automated parcel terminal leadership. Cleveron anchors Nordic markets with specialized grocery and pharmacy locker systems. Ricoh competes through integrated cloud-based management platforms that extend its office automation heritage into locker infrastructure.
Face smart lockers are electromechanical storage units that authenticate users through facial recognition algorithms, typically incorporating infrared cameras, 3D depth sensors, and edge-processing chipsets to verify identity against encrypted biometric templates in under two seconds. These systems serve commercial and institutional environments by eliminating credential sharing, reducing physical contact points, and enabling centralized audit trails for asset tracking. Modular lockers capture the fastest expansion as retailers and logistics operators demand scalable configurations that adapt to seasonal volume swings. Facial recognition technology leads technology adoption where security sensitivity runs highest, while RFID persists in cost-sensitive deployments. Cloud-based management concentrates margin pools through recurring software subscriptions and remote diagnostics capabilities.
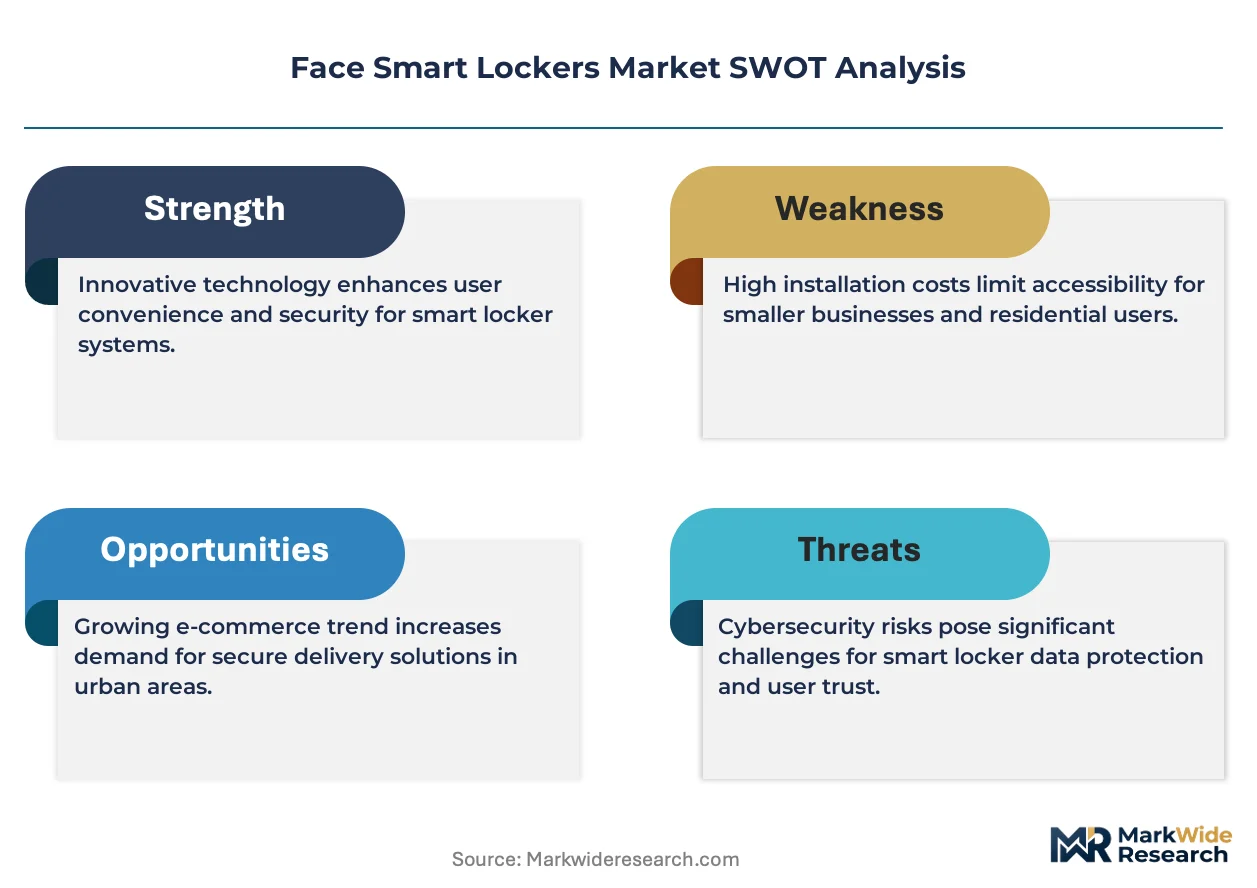
FCC certification governs wireless communication modules in US-deployed units, while GDPR and the EU AI Act constrain biometric data processing and algorithmic transparency across European installations. China's GB standards and MIIT cybersecurity rules mandate local data residency for facial templates, creating divergent product variants by geography. Stakeholders must weigh compliance fragmentation against platform standardization when selecting biometric engine partners and cloud architecture.
Market Dynamics
Cloud-based management systems and biometric authentication protocols are compressing deployment timelines across logistics corridors and transit hubs. Parcel delivery networks now demand centralized audit trails and remote diagnostics capabilities that legacy credential-based systems cannot deliver.
Growth Catalysts
- China's Smart City Mandates:GB standards and MIIT cybersecurity rules mandate local data residency for facial templates, accelerating locker deployment across logistics corridors and transit hubs.
- EU AI Act Compliance:Algorithmic transparency requirements for biometric data processing are forcing vendors to upgrade encryption standards, creating replacement demand across European installations.
- Edge-Processing Chipsets:Sub-two-second authentication speeds enabled by on-device neural processing are eliminating queue friction in high-throughput parcel terminals.
Market Restraints
- GDPR Biometric Friction:Explicit consent requirements and data retention limits constrain facial template storage duration across European deployments.
- Infrared Sensor Supply Concentration:Three suppliers dominate 3D depth sensor manufacturing, creating input volatility for locker OEMs.
- RFID Substitution Threat:Cost-sensitive retail deployments continue selecting radio-frequency credentials over biometric authentication for low-security use cases.
Strategic Opportunities
- Japan's Automated Retail Corridors:Convenience store chains and pharmacy networks are piloting grocery-specific locker configurations with temperature-controlled compartments.
- Modular Scalability:Seasonal volume swings in e-commerce logistics are driving demand for reconfigurable locker banks that expand without infrastructure overhaul.
- India's Logistics Modernization:BIS certification pathways for biometric hardware are opening procurement channels for last-mile delivery networks in tier-2 cities.
Industry Challenges
- FCC Certification Timelines:Wireless communication module approval for US-deployed units extends product launch cycles by four to six months.
- Legacy System Integration:ERP and warehouse management system connectivity requires custom API development for each enterprise deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Face Smart Lockers Market |
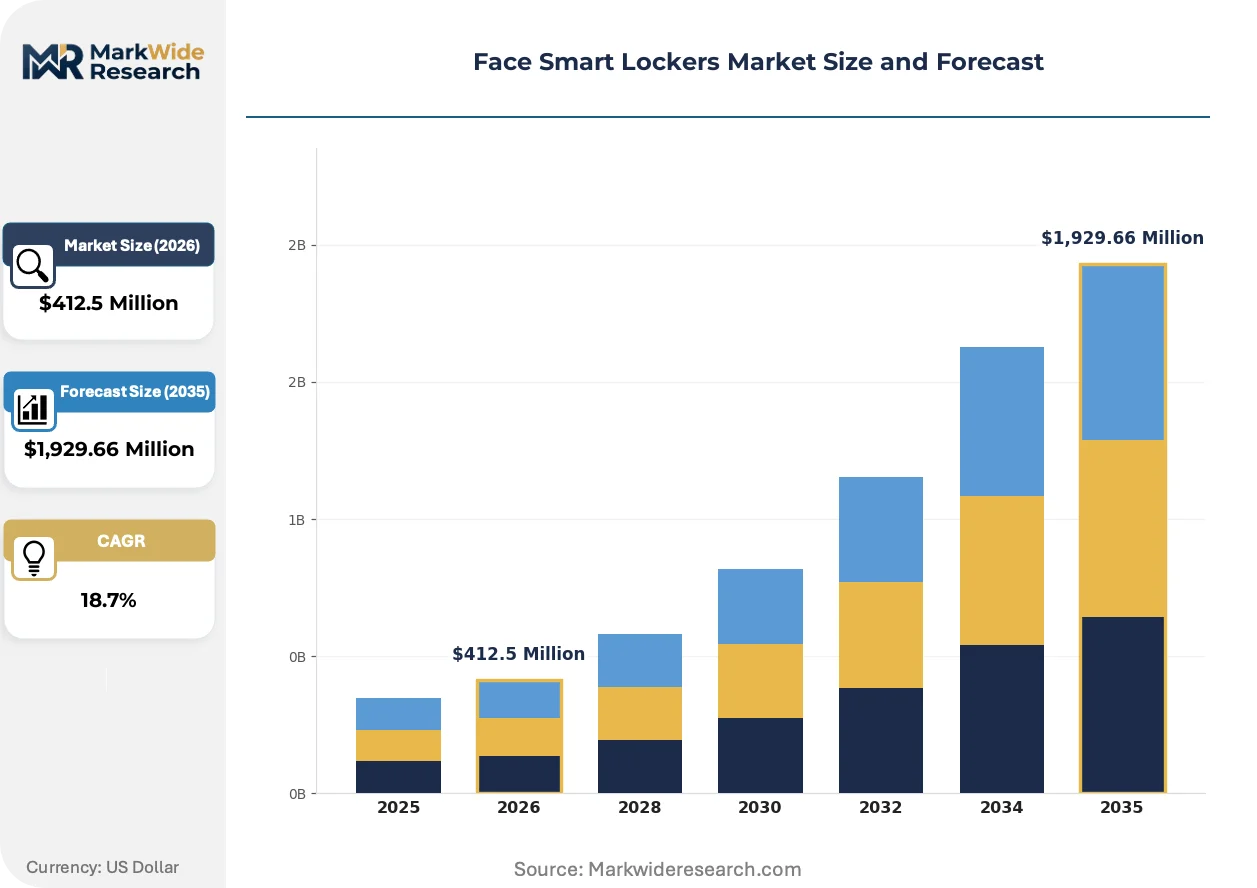
| Market Size in 2026 | $412.5 Million |
| Market Size in 2035 | $1,929.66 Million |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Lockers, Modular Lockers, Custom Lockers, Smart Lockers End User: Retail Stores, Offices, Educational Institutions, Gyms Technology: Facial Recognition, RFID, Biometric Access, Cloud-Based Management Installation: Standalone Units, Integrated Systems, Retrofit Solutions, Custom Configurations |
| Companies Covered | Quadient, Ricoh, Cleveron, Luxer One, Smartbox, TZ Limited, Parcel Pending, InPost, KEBA AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Face Smart Lockers Market Trends and Innovations
Biometric authentication architectures are fragmenting into geography-specific variants as data residency mandates harden. Vendors must now engineer parallel product lines rather than unified global platforms.
Edge-processing chipsets with dedicated neural accelerators are rendering obsolete cloud-dependent facial recognition pipelines that introduce latency and privacy vulnerabilities. Logistics operators in China's smart city corridors are deploying these systems at scale. The shift compresses authentication to sub-second speeds while eliminating round-trip data transmission.
The EU AI Act's algorithmic transparency requirements are forcing biometric engine providers to disclose training data composition and decision logic. European locker deployments now require audit-ready documentation for facial recognition accuracy rates across demographic groups. Vendors are responding by segregating EU product variants with localized model training.
Outcome-based service contracts are displacing capital purchase models for enterprise locker deployments. Logistics operators in Japan now prefer per-transaction pricing bundled with remote diagnostics and predictive maintenance. The shift transfers hardware obsolescence risk to vendors while locking in recurring revenue streams.
Face Smart Lockers Market Segmentation
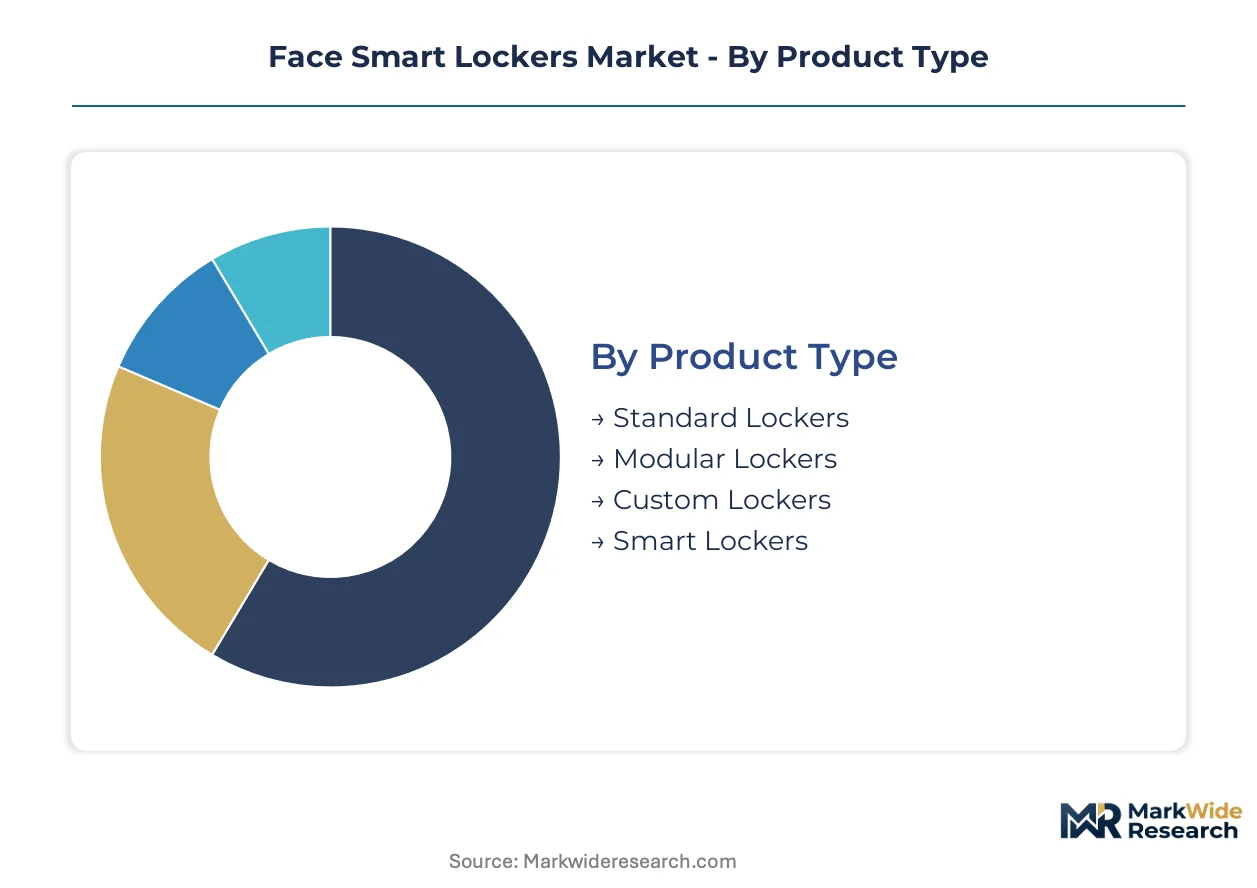
Face smart locker configurations diverge sharply across deployment environments, with product architecture, authentication protocols, and installation methods each commanding distinct procurement criteria. Logistics operators prioritize modular scalability, while retail and institutional buyers weigh biometric precision against integration complexity.
Product Type:
Use-case spectrum spans fixed-capacity installations to reconfigurable systems that adapt to seasonal volume swings in parcel terminals and transit hubs.
- Modular Lockers:Electromechanical units with interchangeable compartment sizes and expandable bank configurations. Parcel delivery networks in China's logistics corridors deploy these for peak-season capacity scaling without infrastructure overhaul.
- Standard Lockers:Fixed-dimension units with predetermined compartment counts and uniform sizing. Offices and educational institutions select these for predictable occupancy patterns where reconfiguration frequency remains low.
- Custom Lockers:Purpose-built dimensions and compartment layouts engineered for specific facility constraints. Temperature-controlled variants serve Japan's automated retail corridors for grocery and pharmacy applications.
- Smart Lockers:Integrated sensor arrays and connectivity modules enabling remote monitoring and predictive maintenance. Cloud-native architectures support centralized fleet management across distributed deployments.
The dominant share belongs to Standard Lockers, while Modular Lockers are closing the gap fastest.
End User:
Customer-type concentration reflects divergent security sensitivities and throughput requirements across commercial and institutional environments.
- Retail Stores:High-frequency parcel pickup points requiring sub-two-second authentication to minimize queue friction. Convenience store chains in Japan pilot temperature-controlled configurations for grocery fulfillment.
- Offices:Corporate campuses and co-working facilities prioritizing audit trails and credential elimination. GDPR compliance constraints shape European deployment specifications for facial template retention.
- Educational Institutions:Campus-wide locker networks serving student populations with seasonal usage patterns. Cost pressures sustain RFID persistence alongside biometric pilots in North American installations.
- Gyms:High-humidity environments demanding corrosion-resistant enclosures and rapid user turnover. Membership-based access models favor cloud-connected management for real-time occupancy visibility.
Retail Stores command the largest installed base, though Offices are expanding most quickly as hybrid work patterns stabilize.
Technology:
Authentication architectures fragment between biometric precision and cost-engineered credential systems across security-tiered deployments.
- Facial Recognition:Infrared camera arrays with 3D depth sensing and edge-processing neural accelerators. China's smart city mandates under MIIT cybersecurity rules accelerate adoption where data residency requirements permit local template storage.
- Cloud-Based Management:Centralized software platforms delivering remote diagnostics, predictive maintenance, and per-transaction pricing models. Japanese logistics operators prefer outcome-based contracts bundling hardware and software subscriptions.
- RFID:Radio-frequency credential systems with lower per-unit cost and reduced deployment complexity. Cost-sensitive retail deployments in India select these for low-security use cases where biometric investment cannot be justified.
- Biometric Access:Multi-modal authentication combining facial recognition with fingerprint or palm-vein verification. High-security installations in European financial services demand algorithmic transparency documentation under EU AI Act provisions.
Facial Recognition leads technology deployment, while Cloud-Based Management is gaining share fastest through recurring revenue migration.
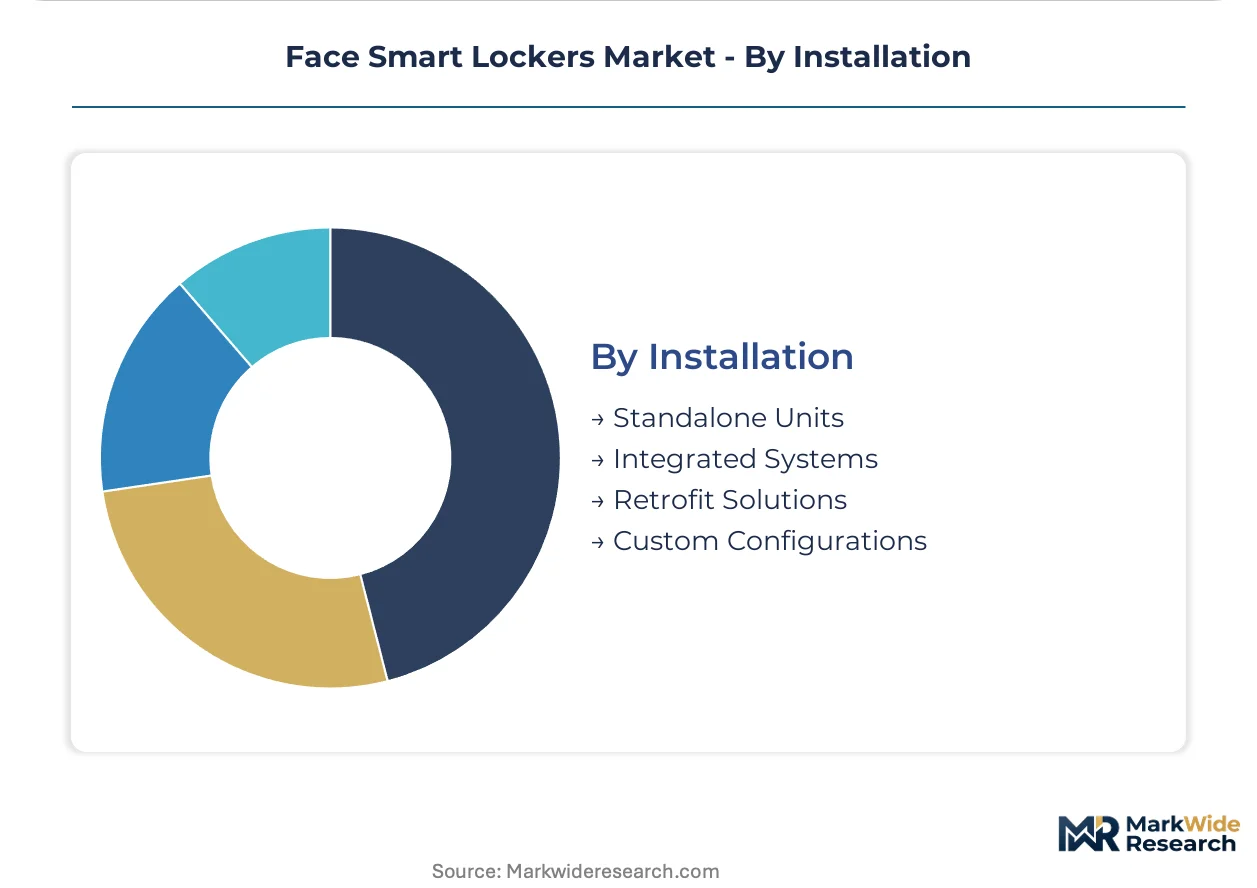
Installation:
Deployment method selection hinges on facility lifecycle stage and integration depth with existing infrastructure management systems.
- Integrated Systems:Hardwired installations with native connectivity to building management and security networks. New construction in China's transit hubs specifies these for unified control plane architecture.
- Standalone Units:Self-contained systems with independent power and network connectivity requiring minimal facility modification. Retrofit-friendly specifications dominate India's tier-2 city logistics modernization.
- Retrofit Solutions:Conversion kits upgrading legacy locker banks with biometric authentication modules. European replacement demand accelerates as GDPR and EU AI Act compliance deadlines force hardware refresh cycles.
- Custom Configurations:Bespoke mechanical and electrical engineering for irregular spatial constraints or specialized environmental requirements. Pharmaceutical cold-chain applications in Japan drive specification complexity.
Standalone Units hold the dominant position, though Integrated Systems are climbing the fastest as new-build smart city corridors multiply.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
MIIT cybersecurity rules and GB standards anchor deployment velocity in China, while GDPR constraints and EU AI Act provisions reshape European product architectures. Japan's automated retail corridors and India's logistics modernization create secondary growth poles.
China
Smart city mandates accelerate locker deployment across logistics corridors and transit hubs. MIIT cybersecurity rules mandate local data residency for facial templates, forcing domestic cloud architecture. Yangtze River Delta clusters host manufacturing scale for edge-processing chipsets.
Japan
Convenience store chains pilot temperature-controlled configurations for grocery and pharmacy fulfillment. METI guidelines on biometric data handling shape vendor compliance specifications. Kansai corridor operators prefer outcome-based service contracts bundling hardware and predictive maintenance.
United States
FCC certification timelines extend product launch cycles for wireless communication modules. Logistics operators demand centralized audit trails that legacy credential systems cannot deliver. California transit hubs specify integrated building management connectivity for new construction.
Germany
EU AI Act algorithmic transparency requirements force biometric engine upgrades across existing installations. KBA transport safety standards influence parcel terminal specifications in urban logistics. Bavarian industrial zones concentrate retrofit demand as GDPR compliance deadlines approach.
India
BIS certification pathways for biometric hardware open procurement channels for last-mile networks in tier-2 cities. Logistics modernization programs prioritize standalone units requiring minimal facility modification. Maharashtra and Gujarat host pilot deployments for cost-sensitive retail applications.
Face Smart Lockers Market Competitive Landscape
Industrial conglomerates and specialized locker fabricators split the market across divergent customer acquisition models. The vendor base concentrates around three strategic archetypes: European manufacturing specialists with parcel terminal heritage, Asian electronics conglomerates leveraging cloud infrastructure scale, and Nordic automation purists focused on grocery and pharmacy verticals. Competitive moves center on geographic licensing partnerships and modular product platform expansion rather than direct capacity competition.
Within the European manufacturing tier, Quadient and Cleveron occupy distinct positioning. Quadient exemplifies the parcel terminal heritage archetype through its sustained automated logistics infrastructure presence. Cleveron anchors Nordic market specialization with grocery and pharmacy locker configurations. Ricoh represents the Asian electronics conglomerate vector, extending office automation heritage into cloud-connected locker management platforms.
| Leading Market Players |
|---|
| Quadient |
| Ricoh |
| Cleveron |
| Luxer One |
| Smartbox |
| TZ Limited |
| Parcel Pending |
| InPost |
| KEBA AG |
| Others |
Pricing and Supply Chain Analysis
Three suppliers dominate 3D depth sensor manufacturing for infrared camera arrays, concentrating margin capture upstream while locker OEMs face input volatility. This sensor oligopoly compresses hardware margins downstream, pushing vendors toward cloud-based software subscriptions and outcome-based service contracts to recover profitability.
Pricing Analysis
Chinese-manufactured units undercut European and North American pricing by substantial spreads, reflecting divergent labor costs and GB standards compliance overhead. The dominant pricing structure is a hybrid model combining hardware lease with per-transaction SaaS tiers. Price differentiation rests on certification grade (FCC versus CE marking tiers) and volume scale for fleet deployments. Pricing pressure stems from RFID substitution in cost-sensitive retail segments, where biometric investment cannot be justified. Educational institutions exhibit highest price sensitivity due to budget constraints, while Japan's convenience store chains show lowest sensitivity given temperature-controlled configuration requirements.
Supply Chain Analysis
Export-control regimes on advanced neural processing units constrain chipset flows from US and Taiwanese foundries to Chinese locker OEMs. Hardware assembly concentrates in China, South Korea, and Taiwan, drawing from specialized inputs including 3D depth sensors, edge-processing chipsets, and corrosion-resistant enclosures. Supply chain risk centers on single-source vulnerability for infrared sensor arrays. Distribution runs through logistics operator procurement departments and smart city infrastructure contractors, with cloud management platforms delivered via direct vendor relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Face smart lockers are recovering from a cyclical trough driven by pandemic-era contactless automation mandates, with replacement demand now accelerating as EU AI Act compliance deadlines force hardware refresh cycles.
For Market Incumbents: Insulate European installed bases against GDPR biometric friction by segregating EU product variants with localized model training and algorithmic transparency documentation. Deepen backward integration into edge-processing chipset supply through strategic partnerships with Taiwanese foundries, reducing exposure to sensor oligopoly pricing power.
For New Entrants and Emerging Players: India's tier-2 city logistics modernization represents substantial white-space opportunity, with BIS certification pathways opening procurement channels for standalone units requiring minimal facility modification. Target cost-sensitive retail deployments with RFID-biometric hybrid configurations that justify premium over pure credential systems. Pursue channel partnerships with last-mile delivery networks rather than direct enterprise sales.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed European parcel terminal specialists seeking cloud-platform capabilities to complete their technology stack. Long-term viability hinges on recurring software revenue migration displacing capital purchase models. Watch Japan's outcome-based contract penetration rates as the inflection indicator for service-model adoption velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| Cloud-Native Platform Migration | Enables per-transaction pricing and predictive maintenance for Japanese logistics operators. |
| EU AI Act Compliance Certification | Creates replacement demand across European installations requiring algorithmic transparency documentation. |
| Modular Scalability Expansion | Captures seasonal volume swings in China's e-commerce logistics corridors without infrastructure overhaul. |
| Edge-Processing Chipset Integration | Eliminates cloud-dependent latency while satisfying MIIT data residency mandates for facial templates. |
| Temperature-Controlled Configuration Development | Opens grocery and pharmacy verticals in Japan's automated retail corridors. |
Research Methodology
The analysis maps modular locker configurations, cloud-based management platforms, and biometric authentication protocols, each validated through logistics procurement directors, smart city infrastructure planners, and biometric engine providers. Primary fieldwork combined interviews with locker OEM product managers, parcel terminal operators, and facility management executives. Secondary sources encompassed MIIT cybersecurity filings, EU AI Act implementation guidance, BIS certification registries, and customs data on electromechanical storage unit trade flows. Bottom-up unit economics triangulated against top-down smart city investment commitments.
Assumptions held fixed include GB standards and MIIT data residency mandates persisting across the projection horizon, while RFID substitution rates and edge-processing cost curves were varied in sensitivity scenarios. The analytical framework modeled segmentation across product architecture, end-user environment, authentication technology, and installation method, with regional regulatory clusters treated as distinct demand pools. CAGRs were derived from installed base expansion rates and replacement cycle compression. Industry-specific inputs included parcel volume growth trajectories and biometric algorithm accuracy improvement curves.
Practitioners should monitor EU AI Act enforcement intensity and MIIT cybersecurity rule revisions for early signals of compliance cost escalation. Forecasts reflect assumptions of continued sensor supply concentration and sustained cloud-subscription pricing migration. Material shifts in export-control regime stringency or breakthroughs in multi-modal biometric fusion would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Security and Surveillance
Global Bot Security Market
Security and Surveillance
Home Security Sensors Market
Security and Surveillance
Global Security and Vulnerability Management Market
Security and Surveillance
5G-Enhanced Surveillance Market
Security and Surveillance
Riot Control System Market
Security and Surveillance
Global Physical Security Software Market
Security and Surveillance
Proactive Security Market
Security and Surveillance
Explosive Detection Technology Market
Security and Surveillance
Global X-Ray Security Scanner Market
Security and Surveillance
Global Threat Intelligence Management Market
Security and Surveillance
North America Security Services Market
Security and Surveillance
Swimming Pool Alarm Market
Security and Surveillance
Global Alarm Monitoring Market
Security and Surveillance
Security Inspection Market
Security and Surveillance
Europe Security Services Market
Security and Surveillance
X-Ray Security Screening System Market